
 South Africa General Surgical Devices Market | 2026-2036
South Africa General Surgical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa General Surgical Devices Market Analytics
Buyer consolidation among public hospital groups is realigning procurement patterns across South Africa's general surgical devices sector. Medtronic leverages its broad instrument portfolio to sustain long-term supply agreements with provincial health departments. Johnson & Johnson Medical Devices anchors its position through extensive distribution networks reaching secondary and tertiary facilities nationwide. Stryker Corporation differentiates via specialized orthopedic surgical instruments that dominate elective procedure volumes in private hospital chains.
General surgical devices encompass hand-held instruments, powered equipment, and disposable consumables manufactured from medical-grade stainless steel, titanium alloys, and polymer composites, designed to cut, coagulate, grasp, or approximate tissue during operative procedures. Electrosurgical devices and minimally invasive instrument sets represent the fastest-expanding product categories as laparoscopic procedure volumes rise in both public and private settings. Open surgery instruments retain substantial share in emergency and trauma applications where access speed outweighs precision advantages, while robotic-assisted platforms occupy a narrow but high-margin niche concentrated in metropolitan private hospitals.
The South African Health Products Regulatory Authority enforces medical device registration and quality management system compliance that shapes market access timelines for imported products. BIS-equivalent conformity assessment and ISO 13485 certification requirements filter out smaller offshore suppliers unable to maintain documented traceability. Stakeholders must monitor evolving preferential procurement regulations and local manufacturing incentives that could reshape competitive dynamics between established multinationals and emerging domestic producers.
Market Dynamics
Public hospital procurement consolidation under South Africa's National Health Insurance framework is compressing supplier margins and privileging framework-contract vendors with documented traceability systems.
Growth Catalysts
- Electrosurgical device adoption:Laparoscopic procedure volumes in Gauteng Province's tertiary hospitals are pulling advanced coagulation instruments into standard surgical kits.
- SAHPRA registration pathways:Streamlined quality management system compliance is accelerating market access for ISO 13485-certified manufacturers.
- Private hospital expansion:Netcare and Life Healthcare are adding theater capacity in metropolitan nodes, expanding the addressable base for powered surgical equipment.
Market Restraints
- Import dependency:Medical-grade stainless steel and titanium alloy supply chains concentrate in German and Chinese specialty mills, exposing rand-denominated procurement to currency volatility.
- Biocompatibility testing costs:SAHPRA-mandated cytotoxicity and sensitization studies add eighteen-to-twenty-four month pre-market timelines for polymer-composite instruments.
- Reusable instrument sterilization infrastructure:Public sector autoclave maintenance backlogs in Eastern Cape and Limpopo provinces limit deployment of higher-margin instrument sets.
Strategic Opportunities
- KwaZulu-Natal underpenetration:Durban's private hospital cluster carries lower surgical device inventory depth than Gauteng, creating whitespace for distributor partnerships.
- Local manufacturing incentives:Department of Trade and Industry production tax credits could offset SAHPRA compliance costs for domestic stainless steel instrument fabrication.
- Robotic-assisted surgery convergence:Integration of haptic feedback systems with existing laparoscopic towers offers upgrade pathways for metropolitan private theaters.
Industry Challenges
- Sterile processing technician scarcity:Public hospital staffing gaps in decontamination and sterilization departments delay instrument turnaround times.
- Legacy equipment interoperability:Integration of new electrosurgical generators with existing patient monitoring systems requires costly adapter development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa General Surgical Devices Market |
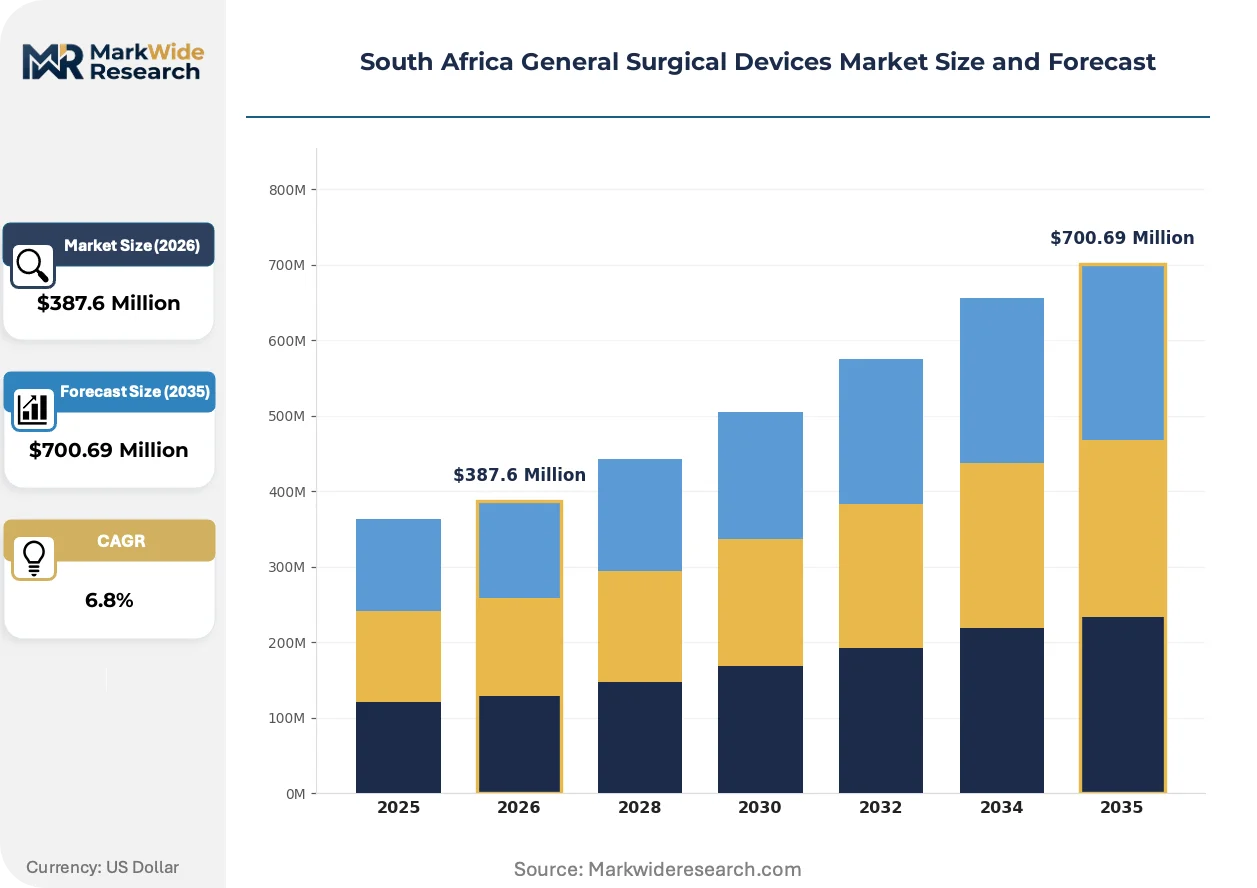
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Instruments, Electrosurgical Devices, Staplers, Sutures End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Laboratories Technology: Minimally Invasive, Open Surgery, Robotic-Assisted, Laparoscopic Application: Orthopedics, Cardiovascular, Gastrointestinal, Neurological |
| Companies Covered | Boston Scientific, Zimmer Biomet, Medtronic, Smith & Nephew, Conmed Corporation, Johnson & Johnson Medical Devices, B. Braun Melsungen AG, Olympus Corporation, Stryker Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa General Surgical Devices Market Evolving Landscape
Minimally invasive surgical platforms are compressing the traditional boundary between open and laparoscopic instrument portfolios, forcing suppliers to bundle disposable and reusable components.
Single-use polymer-composite trocars and retrieval bags are integrating into standardized laparotomy sets, reducing cross-contamination risk in high-volume public hospitals. Procurement managers in Johannesburg academic centers are specifying these configurations in framework tenders. The shift is integrating disposable economics into capital equipment planning cycles, compressing total cost-of-ownership calculations.
SAHPRA's alignment with MDR-equivalent post-market surveillance requirements is extending adverse event reporting obligations to private hospital chains. Device history record retention mandates are forcing distributors to upgrade inventory management systems. Electrosurgical device manufacturers with existing EU MDR technical documentation are transferring compliance packages to accelerate South African registration.
Provincial treasury centralized purchasing is displacing hospital-level procurement autonomy, consolidating vendor selection at framework-contract level. National Treasury's transversal procurement framework is replacing individual hospital tender processes. Gauteng and Western Cape health departments are piloting this model, compressing supplier access points from hundreds to dozens.
South Africa General Surgical Devices Market Segmentation
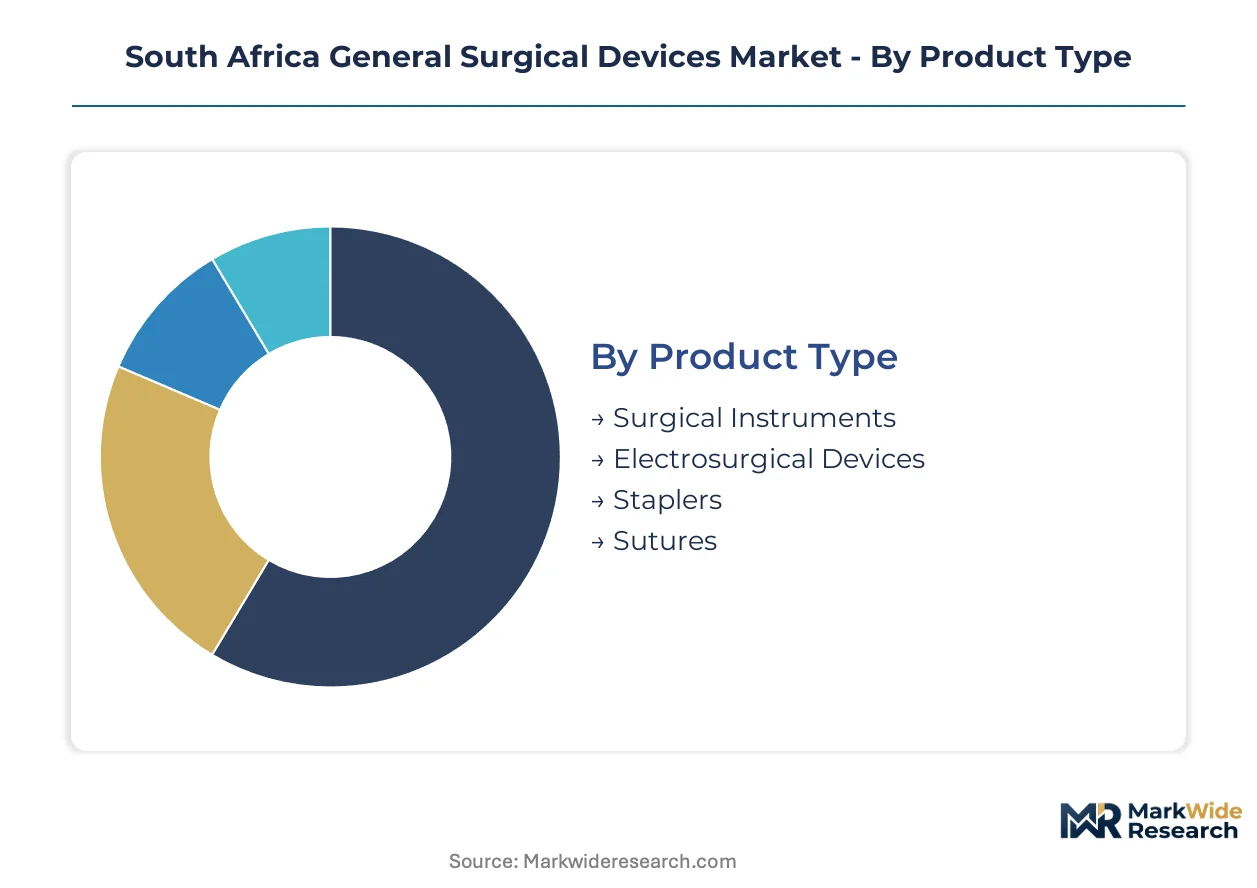
Segmentation in South Africa's general surgical devices market reveals how procurement consolidation and clinical specialization reshape supplier priorities. Understanding these divides exposes where framework-contract vendors concentrate resources versus where distributor partnerships unlock access.
Product Type:
Material composition and power source differentiate procurement tiers across public and private channels.
- Surgical Instruments:Hand-held scalpels, forceps, and retractors manufactured from medical-grade stainless steel dominate emergency theater inventories. Gauteng Province's tertiary hospitals maintain the deepest reusable instrument sets, though Eastern Cape autoclave backlogs constrain deployment.
- Electrosurgical Devices:Advanced coagulation generators and vessel sealing systems command premium positioning in metropolitan private hospitals. Life Healthcare and Netcare theater expansions in Johannesburg are pulling these into standardized laparoscopic kits.
- Staplers:Linear and circular stapling devices manufactured from titanium alloys serve gastrointestinal and thoracic procedures.
- Sutures:Absorbable and non-absorbable wound closure products span mass-market public hospital procurement.
Surgical Instruments lead on scale; Electrosurgical Devices lead on momentum.
End User:
Facility type determines sterilization infrastructure depth and capital equipment refresh cycles.
- Hospitals:Public sector consolidation under National Treasury's transversal framework compresses supplier margins while privileging ISO 13485-certified vendors with documented traceability. Private hospital chains in Pretoria and Cape Town sustain higher-margin powered equipment procurement.
- Ambulatory Surgical Centers:Day-procedure facilities concentrate on disposable instrument economics to minimize sterilization overhead. KwaZulu-Natal's underpenetrated Durban cluster presents partnership whitespace.
- Specialty Clinics:Ophthalmology and dermatology-focused facilities require procedure-specific instrument portfolios.
- Research Laboratories:Academic medical centers in Johannesburg anchor preclinical device validation and training.
Hospitals dominate procurement volume; Ambulatory Surgical Centers are climbing the fastest.
Technology:
Access methodology shapes capital intensity and training requirements for surgical staff.
- Minimally Invasive:Laparoscopic towers and instrument sets reduce recovery times and expand day-surgery eligibility. SAHPRA's streamlined quality pathways are accelerating registration for EU MDR-documented device families.
- Open Surgery:Traditional incision-based instruments retain dominance in trauma and emergency applications where speed outweighs precision. Public hospital procurement prioritizes these for reliability under infrastructure constraints.
- Robotic-Assisted:Haptic feedback platforms occupy a narrow high-margin niche concentrated in metropolitan private theaters.
- Laparoscopic:Dedicated camera and insufflation systems integrate into standardized minimally invasive configurations.
Open Surgery retains installed base dominance; Minimally Invasive gains share fastest.
Application:
Clinical specialty drives specification requirements and reimbursement dynamics.
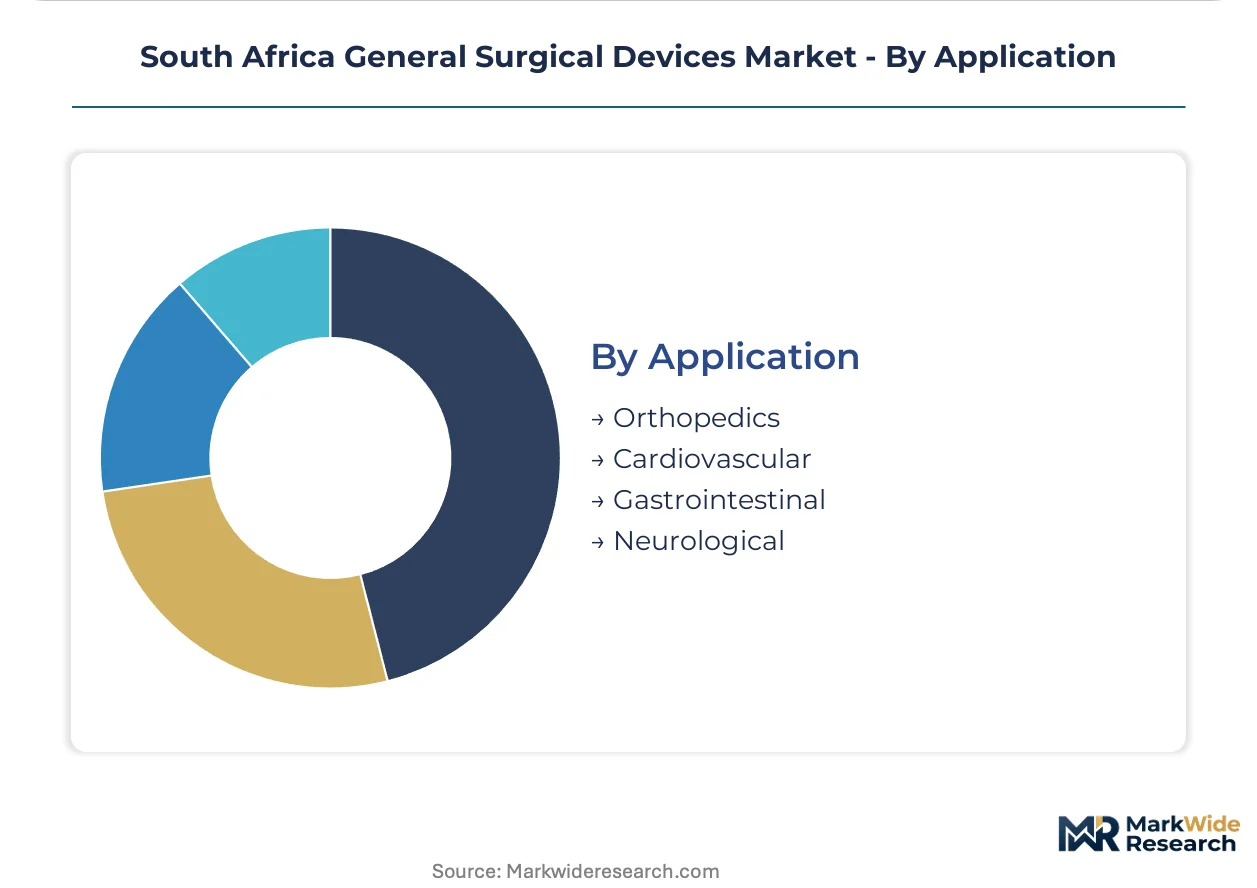
- Orthopedics:Joint replacement and trauma fixation instruments command substantial elective procedure volumes in private hospital chains. Stryker's specialized portfolio anchors this segment through distributor networks reaching secondary facilities.
- Cardiovascular:Sternum saws, vessel cannulation sets, and bypass instrumentation require highest-grade biocompatibility certification. SAHPRA-mandated cytotoxicity testing extends pre-market timelines for polymer-composite entrants.
- Gastrointestinal:Resection and anastomosis instruments serve high-volume public hospital caseloads.
- Neurological:Micro-instrumentation and cranial access systems concentrate in academic medical centers.
Orthopedics leads procedure volume; Cardiovascular shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled surgical device technicians and sterile processing specialists cluster in Gauteng and Western Cape provinces, anchoring procurement sophistication and maintenance capacity that smaller provinces struggle to replicate.
Gauteng Province
Johannesburg and Pretoria host the deepest surgical caseloads in South Africa, with academic medical centers driving demand for advanced electrosurgical platforms. The National Treasury's transversal procurement framework pilots here, consolidating hospital-level purchasing into provincial framework contracts. Private hospital chains in Sandton and Pretoria East are expanding theater capacity for powered surgical equipment.
Western Cape
Cape Town's private hospital cluster sustains premium-tier instrument procurement, while public facilities face sterilization infrastructure constraints. The provincial health department is implementing centralized purchasing aligned with National Health Insurance preparatory work. Stellenbosch and Tygerberg academic complexes anchor training and preclinical validation activity.
KwaZulu-Natal
Durban's private hospital sector carries lower surgical device inventory depth than Gauteng, creating whitespace for distributor partnerships targeting ambulatory surgical centers. The provincial health department lags in framework-contract adoption, preserving some hospital-level procurement autonomy. Richards Bay industrial zones offer potential for stainless steel instrument fabrication under Department of Trade and Industry incentives.
Eastern Cape
Public sector autoclave maintenance backlogs constrain deployment of reusable instrument sets in Port Elizabeth and Mthatha facilities. The province relies on Gauteng-based sterilization services for complex instrument processing. Bhisho provincial administration is negotiating framework-contract participation with delayed implementation timelines.
Limpopo
Rural hospital networks in Polokwane and Tzaneen prioritize basic open-surgery instruments over minimally invasive platforms due to infrastructure limitations. The provincial health department depends on national tender processes rather than autonomous procurement frameworks. Musina border proximity creates informal instrument sourcing channels from Zimbabwe that SAHPRA is working to regulate.
South Africa General Surgical Devices Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across South Africa's procurement tiers. The market structure concentrates around framework-contract vendors with ISO 13485 certification and documented traceability systems that public hospital consolidations now require. Three archetypes dominate: multinational portfolio suppliers with broad instrument ranges, specialized orthopedic and minimally invasive device manufacturers, and regional distributors bridging import logistics to secondary facilities. Competitive moves center on securing provincial health department framework agreements and upgrading distributor inventory management systems to meet SAHPRA device history record retention mandates.
Among multinational portfolio suppliers, Medtronic, Johnson & Johnson Medical Devices, and Stryker Corporation occupy positions reflecting their global scale and established South African distribution infrastructure. Medtronic exemplifies the broad-instrument-portfolio archetype suited to consolidated procurement frameworks. Johnson & Johnson Medical Devices represents extensive distribution network reach into secondary and tertiary facilities nationwide. Stryker Corporation sits within the specialized orthopedic surgical instrument tier that dominates elective procedure volumes in private hospital chains. These three anchors illustrate how global manufacturers are adapting to National Health Insurance procurement consolidation while defending positions in higher-margin private theater segments.
| Leading Market Players |
|---|
| Boston Scientific |
| Zimmer Biomet |
| Medtronic |
| Smith & Nephew |
| Conmed Corporation |
| Johnson & Johnson Medical Devices |
| B. Braun Melsungen AG |
| Olympus Corporation |
| Stryker Corporation |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between ISO 13485-certified framework vendors and uncertified offshore suppliers manifests in pricing power concentration and supply chain exclusion dynamics across South Africa's surgical device procurement tiers. Public hospital consolidation under National Treasury's transversal framework privileges documented traceability, compressing margins for non-compliant entrants while premium-tier private hospital chains sustain pricing differentiation through specialized electrosurgical platforms.
Pricing Analysis
Capacity additions in Gauteng's private hospital chains are reshaping price floors for powered surgical equipment as Life Healthcare and Netcare theater expansions absorb premium-tier inventory. Three-tier pricing structure across premium, standard, and economy levels separates robotic-assisted platforms from laparoscopic towers and basic open-surgery instrument sets. Cost compression in public sector framework contracts is intensifying because provincial treasury centralized purchasing eliminates hospital-level negotiation leverage. Ambulatory surgical centers in KwaZulu-Natal exhibit highest price sensitivity due to disposable instrument economics, while Johannesburg academic medical centers show least sensitivity for advanced coagulation systems.
Supply Chain Analysis
Instrument refurbishment flows from public hospital autoclave backlogs in Eastern Cape and Limpopo create reverse-logistics demand toward Gauteng-based sterilization services, extending turnaround cycles and inventory holding costs. Medical-grade stainless steel and titanium alloy supply chains concentrate in German and Chinese specialty mills, exposing rand-denominated procurement to currency volatility. Polymer-composite trocars and retrieval bags draw from Malaysian and Indian injection-molding facilities. Single-source vulnerability concentrates in electrosurgical generator component sourcing. Distribution runs through Johannesburg-based medical device distributors reaching secondary and tertiary facilities nationwide.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SAHPRA's alignment with MDR-equivalent post-market surveillance requirements compounds procurement barriers, transforming regulatory compliance into a demand catalyst as hospital systems prioritize registered device families with adverse event documentation.
For Market Incumbents: Deepen framework-contract penetration by upgrading distributor inventory management systems to meet SAHPRA device history record retention mandates. Secure long-term supply agreements with provincial health departments before National Health Insurance procurement consolidation accelerates. Vertical integration into local stainless steel instrument fabrication under Department of Trade and Industry tax credits offsets compliance cost pressure from emerging domestic producers. For New Entrants and Emerging Players: The premium-to-economy price-point gap in KwaZulu-Natal's underpenetrated Durban cluster offers whitespace for distributor partnerships targeting ambulatory surgical centers with disposable instrument economics. Focus initial penetration on day-procedure facilities minimizing sterilization overhead rather than competing for Gauteng framework contracts. Partner with existing Johannesburg-based medical device distributors to bypass capital-intensive logistics infrastructure buildout. For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 13485 certification requirements filter out smaller offshore suppliers unable to maintain documented traceability for public hospital procurement. Long-term viability favors acquisition targets with established SAHPRA registration pathways and existing provincial health department relationships. Monitor National Health Insurance implementation timelines as inflection indicator for framework-contract vendor concentration acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| SAHPRA Registration Pathway | Accelerates market access for EU MDR-documented electrosurgical device families. |
| Hospital System Partnership | Secures provincial framework contracts with National Treasury transversal procurement pilots. |
| Backward Integration into Local Manufacturing | Offsets compliance costs through Department of Trade and Industry production tax credits. |
| Software Companion Development | Enables interoperability between new electrosurgical generators and existing patient monitoring systems. |
| Reimbursement Strategy | Aligns minimally invasive platform positioning with National Health Insurance procedure coverage expansion. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down import tracking forms the analytical core of this study. Primary interviews with hospital purchasing committees, biomedical engineers, GPO contracts managers, and provincial health department procurement officers combined with secondary validation from SAHPRA registration databases, National Treasury tender records, and hospital procurement databases. Trade data from South African Revenue Service customs records and industry association shipment reports provided supply-side triangulation against demand-side facility surveys.
Input-output matrices map surgical procedure volumes to instrument consumption rates across open, laparoscopic, and robotic-assisted access methodologies over the projection horizon. Segmentation dimensions modeled include product type, end-user facility tier, technology platform, and clinical application specialty. CAGRs derive from regression analysis against historical procurement patterns adjusted for National Health Insurance policy implementation trajectories. Forecast inputs incorporate provincial health department budget allocations and private hospital chain capital expenditure disclosures for theater capacity expansion.
Caveats apply where rand volatility against euro and yuan denominations could materially shift import cost structures and procurement timelines. Practitioners should monitor SAHPRA regulatory guidance updates and National Treasury transversal framework rollout pace for early signals of competitive access point compression.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asia-Pacific Wearable Medical Devices Market
Medical Devices
Augmented Bone Graft Market
Medical Devices
Transradial Access Devices Market
Medical Devices
Europe Sternal Closure Systems Market
Medical Devices
Global Medical Device Cleaning Market
Medical Devices
Europe Ablation Technologies Market
Medical Devices
France Ophthalmic Devices Market
Medical Devices
Global Disability Devices Market
Medical Devices
North America Portable Medical and Healthcare Devices Market
Medical Devices
Medical Laser Cutting Device Market
Medical Devices
Endoluminal Device Systems Market
Medical Devices
EMG Biosensors Market
Medical Devices
Capsulorhexis Forceps Market
Medical Devices
China Anesthesia Devices Market
Medical Devices
Global Anesthesia Video Laryngoscope Market
Medical Devices
Middle East and Africa Electroencephalography Devices Market