
 Asia-Pacific Card-Based Access Control Market | 2026-2036
Asia-Pacific Card-Based Access Control Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Card-Based Access Control Market Insights
China's Guangdong-Shenzhen manufacturing corridor is tilting toward higher-volume card reader module production. ASSA ABLOY leverages its regional distribution network to sustain premium positioning across Southeast Asian commercial developments. Honeywell International Inc. anchors large-scale enterprise deployments through integrated building management platforms. Siemens AG competes on protocol interoperability, extending its Desigo ecosystem into hospital and airport verticals across Japan and South Korea.
Card-based access control systems authenticate identity through encoded credentials read by electromagnetic or radio-frequency sensors, typically operating at 125 kHz low-frequency or 13.56 MHz high-frequency bands for secure facility entry management. The primary commercial purpose centers on physical security layering, combining credential validation with audit trail logging for regulatory compliance and liability reduction. Contactless cards lead product type revenue pools due to transit authority standardization, while biometric cards represent the fastest-growing credential format as multi-factor authentication requirements harden in financial services and defense applications. Corporate offices dominate end-user demand by installed base, though healthcare facilities command higher per-door system values through integration with patient privacy frameworks and pharmaceutical storage protocols.
India's BIS certification mandates for electronic security products shape import compliance costs and local assembly incentives. China's GB standards for information security and MIIT radio equipment approvals filter market access for foreign reader manufacturers. Japan's METI energy efficiency guidelines influence standby power specifications for networked controllers. Stakeholders must weigh credential migration timelines against legacy infrastructure amortization as mobile-enabled access competes with physical card deployments.
Market Dynamics
Smart city infrastructure rollouts across India are compressing deployment timelines for credential systems in government facilities, while China's MIIT radio equipment approvals filter foreign reader access and reshape competitive positioning around domestic manufacturing clusters.
Growth Catalysts
- India's PLI scheme for electronics:Local assembly incentives for card readers and credential components are reducing import dependency and shortening procurement cycles for security integrators.
- Transit authority standardization:Contactless card protocols adopted by metropolitan rail operators in Guangzhou and Tokyo are creating interoperable credential ecosystems that spill into adjacent commercial real estate.
- Biometric card convergence:Fingerprint-embedded credentials are penetrating financial services and defense verticals as multi-factor authentication requirements harden.
Market Restraints
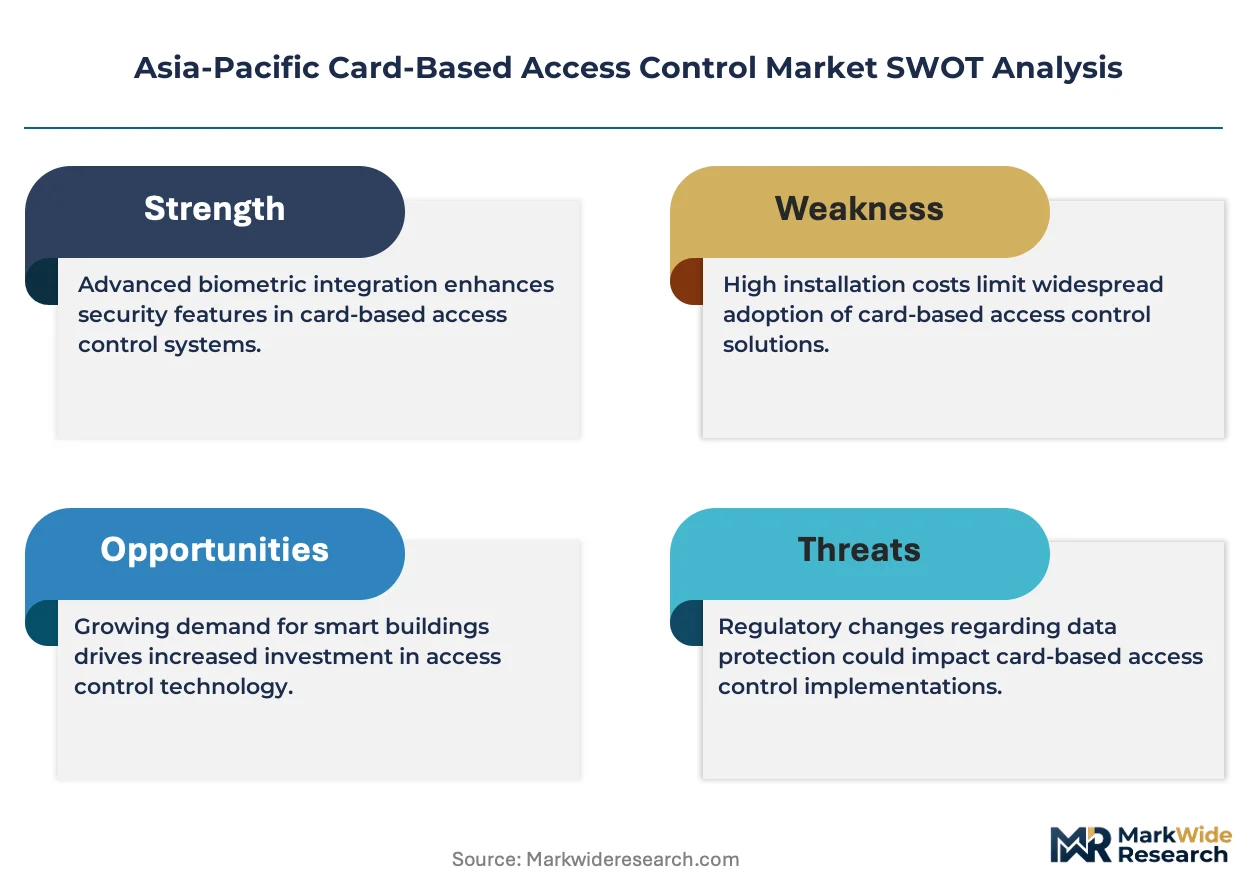
- Semiconductor supply concentration:Reader module production depends on wafer fabrication concentrated in Taiwan and South Korea, exposing lead time volatility.
- Legacy system lock-in:125 kHz low-frequency installations across aging commercial stock in Australia constrain upgrade budgets and credential migration paths.
- BIS certification timelines:India's mandatory testing for electronic security products extends import compliance cycles by four to six months.
Strategic Opportunities
- Vietnam's industrial zone expansion:Foreign manufacturing facility construction is generating greenfield demand for integrated access and workforce management systems.
- Mobile-to-card bridging:Hybrid readers accepting both physical credentials and smartphone tokens are capturing early replacement cycles in Singapore's financial district.
- Japan's hospital digitization:METI-backed smart building incentives are accelerating Desigo-compatible deployments in patient privacy frameworks.
Industry Challenges
- RF engineering talent scarcity:13.56 MHz antenna design expertise concentrates in Shenzhen and Seoul, constraining regional system integrator capabilities.
- Protocol fragmentation:Proprietary controller languages from incumbent building automation vendors complicate multi-site enterprise standardization.
- Cyber-physical certification overlap:Networked controllers must satisfy both information security GB standards and physical security product testing, doubling compliance documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Card-Based Access Control Market |
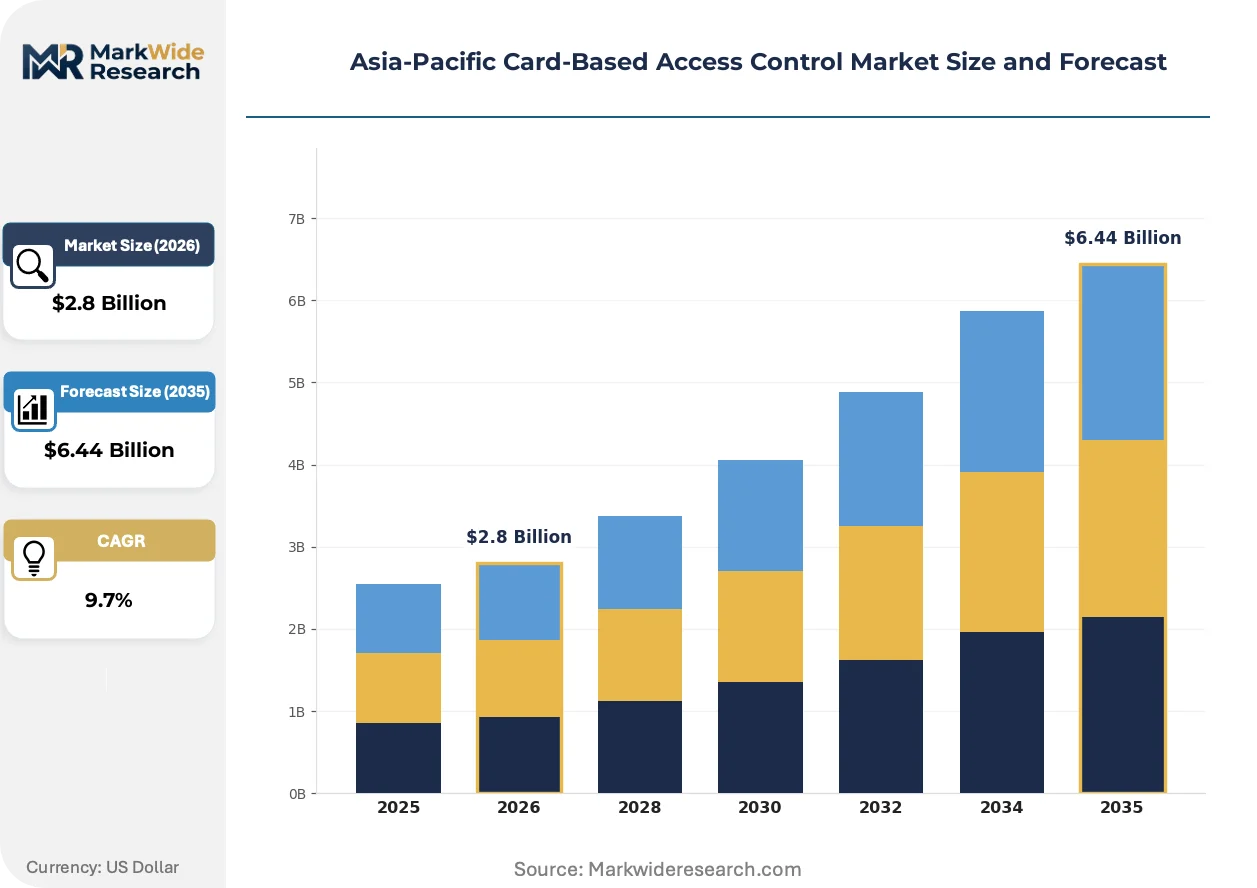
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.44 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contactless Cards, Magnetic Stripe Cards, Smart Cards, Biometric Cards End User: Corporate Offices, Government Buildings, Educational Institutions, Healthcare Facilities Technology: RFID, NFC, Biometrics, Optical Recognition Application: Identity Verification, Secure Access, Time Tracking, Attendance Management |
| Companies Covered | Siemens AG, ASSA ABLOY, Honeywell International Inc., Suprema Inc., dormakaba Group, Robert Bosch GmbH, Tyco Security Products, NEC Corporation, Johnson Controls, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Card-Based Access Control Market Trends and Innovations
Credential technology is migrating from physical token dominance toward multi-modal authentication, while regulatory pressure on data localization and energy efficiency is rewriting hardware specifications across the region.
Biometric card technology is migrating from pilot deployments to scaled enterprise rollouts. Fingerprint sensors embedded in ISO 7810-compliant credentials enable two-factor authentication without separate readers. Japanese banks and Australian defense contractors are adopting these cards fastest. The technology is migrating from high-security niches toward mainstream commercial offices, compressing pricing premiums for traditional contactless products.
China's GB standards for information security and radio equipment are tightening market access requirements. MIIT approval processes now mandate domestic encryption modules for networked controllers. Foreign reader manufacturers face extended testing cycles and joint venture pressures. Hospital and airport verticals in Japan and South Korea are responding by prioritizing Siemens AG protocol interoperability to future-proof against credential format shifts.
Facility managers are unbundling hardware procurement from long-term service contracts. Large commercial developers in Shanghai and Bengaluru now separate reader purchases from installation and maintenance, forcing vendors to compete on module pricing alone. System integrators are absorbing commissioning risk to win multi-site enterprise accounts. This pattern is most visible in China's tier-one metropolitan clusters where commercial real estate investment cycles are shortening.
Asia-Pacific Card-Based Access Control Market Segmentation
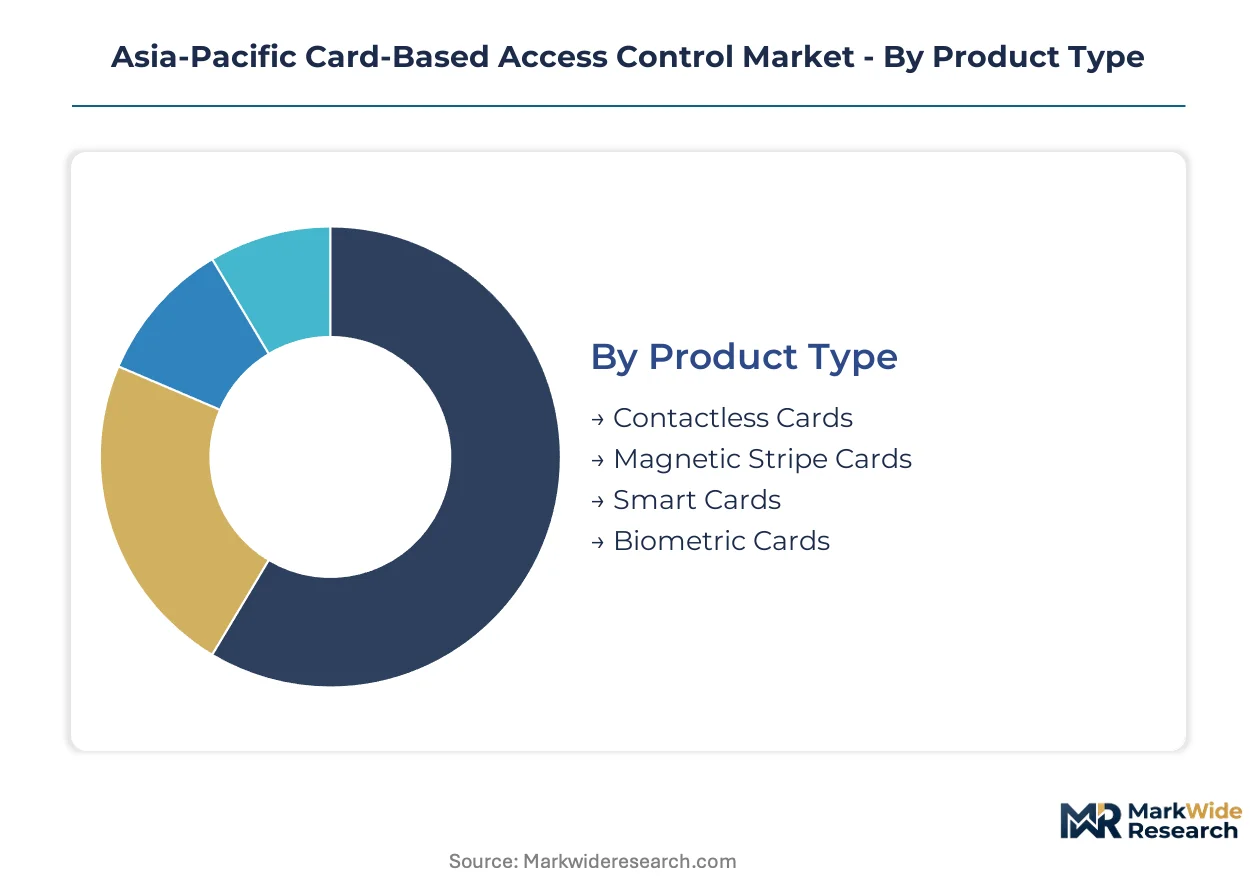
Segmentation in the Asia-Pacific card-based access control market reveals divergent replacement cycles across credential formats and end-use verticals. Procurement patterns vary sharply between transit-integrated contactless deployments and specialized biometric rollouts in regulated environments.
Product Type:
Contactless cards turn over fastest due to wear from daily transit use, while biometric cards cycle slowest given extended pilot-to-production timelines and certification requirements.
- Contactless Cards:ISO 14443-compliant credentials operating at 13.56 MHz dominate transit authority procurements in Guangzhou and Tokyo. Rail operator standardization creates spillover demand into adjacent commercial developments, compressing replacement intervals to three-to-four years.
- Biometric Cards:Fingerprint-embedded ISO 7810 credentials enable two-factor authentication without dedicated biometric readers. Japanese banks and Australian defense contractors are adopting these fastest as multi-factor requirements harden in financial services and classified facilities.
- Smart Cards:Microprocessor-based credentials with encrypted memory segments serve high-assurance government applications across India and South Korea.
- Magnetic Stripe Cards:Legacy 1970s-era technology persists in aging Australian commercial stock and budget-conscious educational deployments.
Contactless cards anchor the volume base while biometric cards gain share at the steepest rate.
End User:
Cost tiers separate high-assurance healthcare and government installations from commoditized educational procurements.
- Corporate Offices:Multi-tenant commercial developments in Shanghai and Bengaluru drive installed base volume. Facility managers unbundle hardware from service contracts, forcing pure module pricing competition.
- Healthcare Facilities:Patient privacy frameworks and pharmaceutical storage protocols command premium per-door system values. Japan's METI-backed hospital digitization accelerates Desigo-compatible deployments.
- Government Buildings:India's smart city infrastructure rollouts compress deployment timelines for credential systems in municipal and federal facilities.
- Educational Institutions:Budget-constrained universities and K-12 systems prioritize low-cost magnetic stripe and basic contactless solutions.
Corporate offices generate the highest door count while healthcare facilities capture the steepest per-unit pricing premiums.
Technology:
Supply concentration for 13.56 MHz antenna design expertise in Shenzhen and Seoul shapes regional integrator capabilities.
- RFID:125 kHz low-frequency and 13.56 MHz high-frequency electromagnetic coupling dominates physical access applications. China's MIIT radio equipment approvals filter foreign reader access and reshape competitive positioning around domestic manufacturing clusters.
- NFC:Smartphone-compatible protocols enable mobile-to-card bridging in Singapore's financial district. Hybrid readers accepting both physical credentials and smartphone tokens capture early replacement cycles.
- Biometrics:Fingerprint, iris, and facial recognition modules integrate with card-based systems for stepped-up authentication in defense and financial verticals.
- Optical Recognition:Barcode and QR-based credentials serve temporary visitor management and low-security time-tracking applications.
RFID technology anchors installed base volume while NFC adoption climbs the fastest among new deployments.
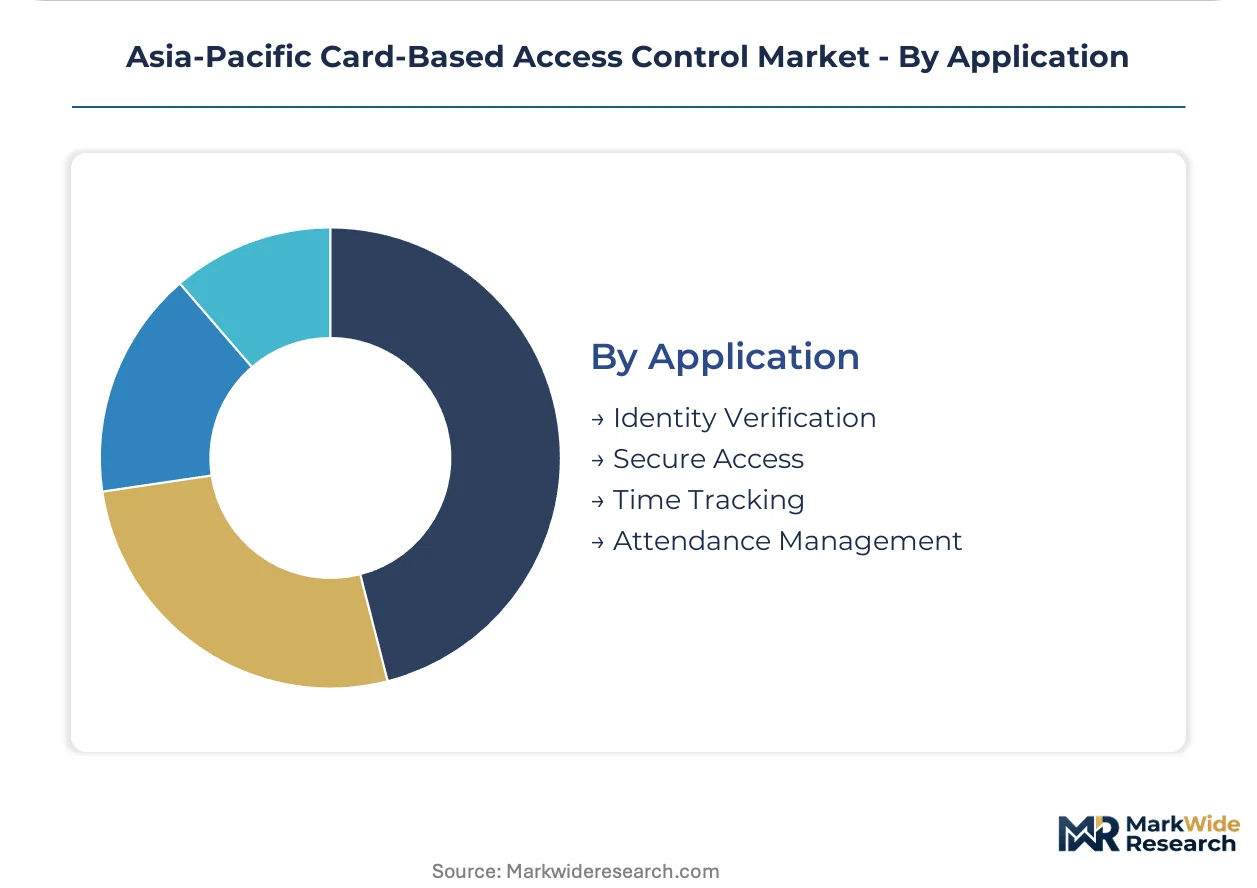
Application:
Margin structures vary from commoditized attendance tracking to high-value secure access with audit compliance requirements.
- Secure Access:Physical entry control with credential validation and audit trail logging for regulatory compliance and liability reduction. China's GB standards for information security mandate domestic encryption modules for networked controllers.
- Identity Verification:Multi-factor authentication combining card possession with biometric or PIN verification in high-assurance environments.
- Time Tracking:Workforce management integration captures clock-in/clock-out events for payroll and labor compliance.
- Attendance Management:Educational and corporate campus monitoring for presence verification and space utilization analytics.
Secure access applications dominate revenue contribution while identity verification expands most quickly under hardening authentication requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wafer fabrication for reader modules clusters in Taiwan and South Korea, exposing procurement cycles to lead time volatility. Domestic assembly incentives in India and China's MIIT radio equipment approvals are redrawing competitive boundaries across the region.
China
Guangdong-Shenzhen manufacturing corridors are tilting toward higher-volume card reader module production. MIIT radio equipment approvals mandate domestic encryption modules for networked controllers, filtering foreign reader access. Tier-one metropolitan clusters in Shanghai and Beijing drive commercial real estate and transit integration projects.
India
Smart city infrastructure rollouts compress deployment timelines for credential systems in government buildings. BIS certification mandates for electronic security products extend import compliance cycles by four to six months. The PLI scheme for electronics manufacturing is reshaping local supply chains for card readers and credential components.
Japan
METI energy efficiency guidelines influence standby power specifications for networked controllers in hospital and airport verticals. METI-backed smart building incentives accelerate Desigo-compatible deployments in patient privacy frameworks. Kanto and Kansai regions concentrate demand for protocol-interoperable systems.
South Korea
13.56 MHz antenna design expertise concentrates in Seoul, constraining regional system integrator capabilities. MFDS-equivalent standards for information security shape networked controller specifications. The Seoul Capital Area drives enterprise deployments with hardened multi-factor authentication requirements.
Vietnam
Industrial zone expansion generates greenfield demand for integrated access and workforce management systems. Foreign manufacturing facility construction is accelerating credential system procurement. Northern industrial provinces around Hanoi and Hai Phong concentrate new facility development.
Asia-Pacific Card-Based Access Control Market Competitive Landscape
Integrated building automation conglomerates and specialized security hardware fabricators split the market along enterprise-scale versus vertical-specialist lines. The vendor base organizes into three strategic archetypes: full-stack building management platforms, credential-hardware pure-plays, and regional system integrators with captive installation networks. Consolidation pressures favor acquisition of antenna design boutiques and encryption module specialists. Geographic expansion through joint ventures dominates competitive moves as MIIT and BIS compliance requirements harden.
Within the full-stack platform tier, Siemens AG and Honeywell International Inc. exemplify protocol-interoperability positioning across hospital and airport verticals. ASSA ABLOY occupies a position representing premium hardware distribution leverage across Southeast Asian commercial developments. These three anchors sit within contrasting geographic footprints—German, American, and Swedish-Danish origins respectively—reflecting the market's dependence on multinational building automation heritage.
| Leading Market Players |
|---|
| Siemens AG |
| ASSA ABLOY |
| Honeywell International Inc. |
| Suprema Inc. |
| dormakaba Group |
| Robert Bosch GmbH |
| Tyco Security Products |
| NEC Corporation |
| Johnson Controls |
| Others |
Pricing and Supply Chain Analysis
Wafer fabrication concentration in Taiwan and South Korea anchors reader module costs, pushing margin pools toward system integrators who control antenna design expertise and encryption certification pathways.
Pricing Analysis
MIIT radio equipment approvals dictate the pricing tier structure across networked controller categories. Three-tier pricing structure across premium, standard, and economy levels separates Siemens AG protocol-interoperable hospital systems from domestic Chinese encryption-compliant mid-tier products and unbundled reader modules for commercial developers. Cost compression in economy-tier hardware is intensifying because facility managers in Shanghai and Bengaluru now separate reader purchases from installation contracts. Educational institutions exhibit highest price sensitivity, while healthcare facilities accepting METI-backed smart building incentives show lowest sensitivity due to bundled digitization budgets.
Supply Chain Analysis
Silicon wafer feedstock draws from Taiwan Semiconductor Manufacturing clusters and South Korean foundry networks, with assembly tilting toward Guangdong-Shenzhen corridors under China's domestic encryption mandates. Critical inputs include 13.56 MHz RF antenna substrates, EMV-compliant microcontroller units, and ISO 7810-compliant biometric sensor laminates. Single-source vulnerability concentrates in Taiwan wafer supply for high-frequency reader chipsets. Distribution runs through ASSA ABLOY's Southeast Asian commercial development networks and Honeywell's enterprise building management channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biometric card convergence is disrupting credential economics, with fingerprint-embedded ISO 7810 formats compressing traditional contactless premiums and forcing repositioning across hardware tiers.
For Market Incumbents: Entrench protocol interoperability advantages by extending Desigo-compatible ecosystems into Japan's hospital digitization wave and securing BIS pre-certification for Indian smart city tenders. Deepen backward integration into 13.56 MHz antenna design boutiques in Shenzhen to offset RF engineering talent scarcity threatening system integrator margins.
For New Entrants and Emerging Players: Establish a beachhead in Vietnam's northern industrial provinces around Hanoi and Hai Phong, where foreign manufacturing facility construction generates greenfield demand for integrated access and workforce management systems. Capture early replacement cycles in Singapore's financial district by specializing in hybrid readers bridging physical credentials with smartphone tokens.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed credential-hardware pure-plays holding captive installation networks across Southeast Asian commercial developments. Five-to-ten year viability hinges on encryption module localization capabilities under hardening MIIT and BIS compliance requirements. Watch for inflection when Indian PLI scheme recipients achieve scale sufficient to displace Taiwanese reader module imports.
| Strategic Initiative | Industry Significance |
|---|---|
| Encryption Module Localization | MIIT domestic encryption mandates filter foreign controller access and reshape competitive boundaries around joint ventures. |
| Antenna Design Boutique Acquisition | 13.56 MHz RF engineering talent scarcity in Shenzhen and Seoul constrains regional integrator capabilities. |
| Hospital System Partnership | METI-backed smart building incentives accelerate Desigo-compatible deployments in Japan's patient privacy frameworks. |
| Industrial Zone Greenfield Entry | Foreign manufacturing facility construction in Vietnam's northern provinces drives integrated access system procurement. |
| Mobile-to-Card Bridging Platform | Hybrid readers accepting both physical credentials and smartphone tokens capture Singapore financial district replacement cycles. |
Research Methodology
Cross-validation between security integrator procurement data and semiconductor trade flow records anchors the qualitative findings. Primary interviews with facility managers at multi-tenant commercial developments, hospital biomedical engineers, transit authority technology officers, and BIS certification laboratory directors combined with secondary validation from MIIT equipment approval databases, Japan's METI smart building incentive disclosures, and Indian PLI scheme beneficiary lists. Bottom-up credential shipment analysis and top-down building automation spend estimates complete the triangulation.
Calibration against historical CAGRs from adjacent physical security verticals shapes the projection framework across the analysis window. Segmentation dimensions modeled include credential format, end-use vertical, technology protocol, and application type, with regional regulatory cluster as an additional industry-specific dimension. CAGRs derive from installed base turnover rates, replacement cycle compression from transit authority standardization, and biometric card pilot-to-production timeline acceleration. Forecast inputs incorporate semiconductor lead time volatility from Taiwan and South Korea wafer concentration, plus BIS certification timeline extensions for electronic security products.
Sensitivities concentrate around MIIT encryption module mandate enforcement intensity, Taiwanese wafer fabrication capacity allocation shifts, and Indian PLI scheme localization achievement timelines. Cross-checking against IHS Markit building automation equipment shipment data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Parking Access Control Market
Access Control Systems
Perimeter Intrusion Detection Systems Market
Access Control Systems
Global Commercial Security System Market
Access Control Systems
Middle East and Africa Proximity Access Control Market
Access Control Systems
Latin America Smart Lock Market
Access Control Systems
Global Home Security Systems Market
Access Control Systems
Card-Based Electronic Access Control Systems Market
Access Control Systems
Border Security System Market
Access Control Systems
Residential Smart Lock Market
Access Control Systems
France Access Control Market
Access Control Systems
Latin America Proximity Access Control Market
Access Control Systems
Restricted Access Barrier System (RABS) Market
Access Control Systems
Europe Access Control Software Market
Access Control Systems
Locks Market
Access Control Systems
Latin America Card-Based Access Control Market
Access Control Systems
Digital Security Control Market