
 North America Smart Locks Market | 2026-2036
North America Smart Locks Market Size, Share, and Industry Trends Forecast 2026-2036
North America Smart Locks Market Analytics
The EPA's ENERGY STAR certification expansion into connected home devices is recalibrating procurement criteria for smart lock manufacturers. Assa Abloy AB leverages its Yale Home and August Home Inc. brand portfolio to dominate residential retrofit channels across the United States. Allegion Plc anchors commercial specification business through its Schlage brand's presence in hospitality and multi-tenant buildings. Kwikset competes aggressively on price in mass retail while sustaining brand recognition through builder program partnerships.
North America smart locks are electromechanical locking devices that authenticate users through wireless protocols, biometric sensors, or keypad credentials, typically operating on battery power with ANSI/BHMA Grade 2 or Grade 3 security ratings for residential and light commercial duty cycles. These systems replace or augment traditional mechanical cylinders to enable remote access management, audit logging, and integration with home automation platforms. Deadbolt locks occupy the largest product segment due to consumer familiarity and straightforward installation compatibility with standard door prep. Wi-Fi technology leads connectivity preferences for standalone consumer purchases, while Z-Wave and Zigbee concentrate in professionally monitored smart home ecosystems where mesh networking reliability supports whole-property automation. The hospitality end user segment generates premium margin pools through cloud-based property management system integration and mobile key credentialing.
The FCC regulates radio frequency emissions for Bluetooth, Wi-Fi, Z-Wave, and Zigbee modules under Part 15 rules, requiring device certification before market entry and influencing hardware design choices for antenna configuration and power output. The NHTSA maintains indirect influence through connected vehicle-to-home access research, while state-level data privacy statutes in California and Illinois shape how smart lock vendors handle biometric data and access logs. Stakeholders must monitor evolving patchwork compliance obligations as municipal building codes in major metropolitan areas begin incorporating smart device cybersecurity provisions into permit requirements.
Market Dynamics
Multi-family developers in Texas and Florida now mandate connected access systems as baseline amenities, compressing decision cycles and forcing hardware vendors to pre-certify for property management platform integration.
Growth Catalysts
- FCC Part 15 certification streamlines:Unlicensed radio frequency rules accelerate Bluetooth and Wi-Fi module approvals, reducing hardware vendors' time-to-market for new lock iterations.
- ANSI/BHMA Grade 2 specification pull:Builder programs in Sun Belt states increasingly require Grade 2 deadbolts with smart capability, creating specification lock-in for certified suppliers.
- Cloud-based property management convergence:Hospitality operators demand mobile key credentialing and audit logging, driving premium module attach rates in hotel retrofit and new construction.
Market Restraints
- Lithium battery supply concentration:Cell production for lock power systems concentrates in East Asian manufacturing clusters, exposing vendors to input cost volatility and logistics friction.
- Z-Wave chipset allocation constraints:Mesh networking module availability tightens during semiconductor fab capacity cycles, delaying professional installation channel fulfillment.
- Biometric data liability exposure:Illinois Biometric Information Privacy Act and California Consumer Privacy Act impose statutory damages frameworks that elevate vendor insurance costs and legal reserve requirements.
Strategic Opportunities
- Arizona and Nevada greenfield construction corridors:Pre-wiring rates for smart home infrastructure in these states exceed national baselines, creating first-mover specification advantages for integrated access providers.
- EPA ENERGY STAR connected device expansion:Emerging certification criteria for standby power and wireless efficiency create procurement preference tailwinds for compliant hardware in utility rebate programs.
- Matter protocol convergence:Thread and Wi-Fi interoperability standardization reduces ecosystem fragmentation, enabling cross-platform lock sales to previously siloed home automation buyers.
Industry Challenges
- Cybersecurity firmware audit capacity:Municipal building codes in Chicago and New York City now incorporate connected device security provisions into permit reviews, stretching vendor engineering resources for documentation and third-party validation.
- Mesh network commissioning expertise:Z-Wave and Zigbee installation complexity exceeds consumer DIY capability, forcing manufacturers to subsidize dealer training programs or absorb higher support call center costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Smart Locks Market |
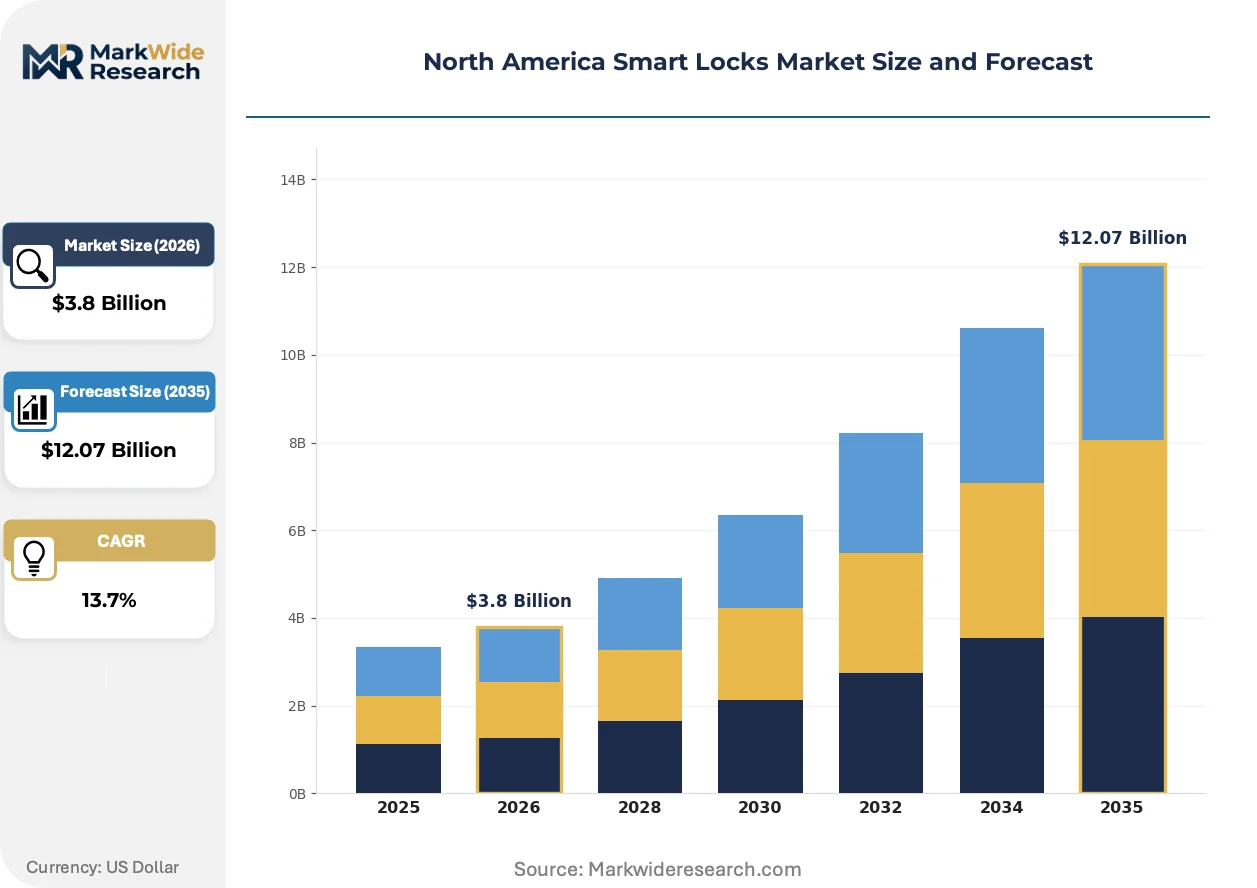
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.07 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Deadbolt Locks, Knob Locks, Lever Handles, Padlocks Technology: Bluetooth, Wi-Fi, Z-Wave, Zigbee End User: Residential, Commercial, Industrial, Hospitality Installation Type: Retrofit, New Construction, Wireless, Wired |
| Companies Covered | Assa Abloy AB, Allegion Plc, Honeywell International, Inc., Schlage, Kwikset, August Home Inc., Yale Home, Vivint Smart Home, Inc., Salto Systems, S.L., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Smart Locks Market Evolving Landscape
Hardware architecture is pivoting from standalone battery-powered units toward edge-compute capable platforms that process biometric templates locally while maintaining cloud audit trails, compressing the functional gap between residential and light commercial duty cycles.
Ultrasonic presence sensing is integrating into deadbolt form factors to enable hands-free unlocking sequences while preserving battery life through intermittent activation patterns. Hospitality operators in Florida and Texas are piloting these modules for VIP guest experience differentiation. The technology is integrating access events with HVAC and lighting triggers, creating whole-room automation bundles that lift hardware margin structures.
The FCC's Part 15 rules for unlicensed devices are tightening enforcement around harmonized frequency bands, particularly for 2.4 GHz Wi-Fi coexistence in dense multi-dwelling environments. Hardware vendors must now submit more granular antenna pattern documentation and power spectral density measurements. Smaller module suppliers without in-house RF engineering are exiting the North American certification pathway, consolidating component sourcing around established radio platform vendors.
Builder procurement has compressed from multi-year master agreements to annual specification reviews tied to project-level amenity budgeting. National multi-family developers now rotate preferred vendor lists every 12-18 months based on total installed cost and platform integration scores. This rotation is most visible in Texas and Arizona markets where construction velocity and competitive leasing dynamics amplify procurement team negotiating leverage.
North America Smart Locks Market Segmentation
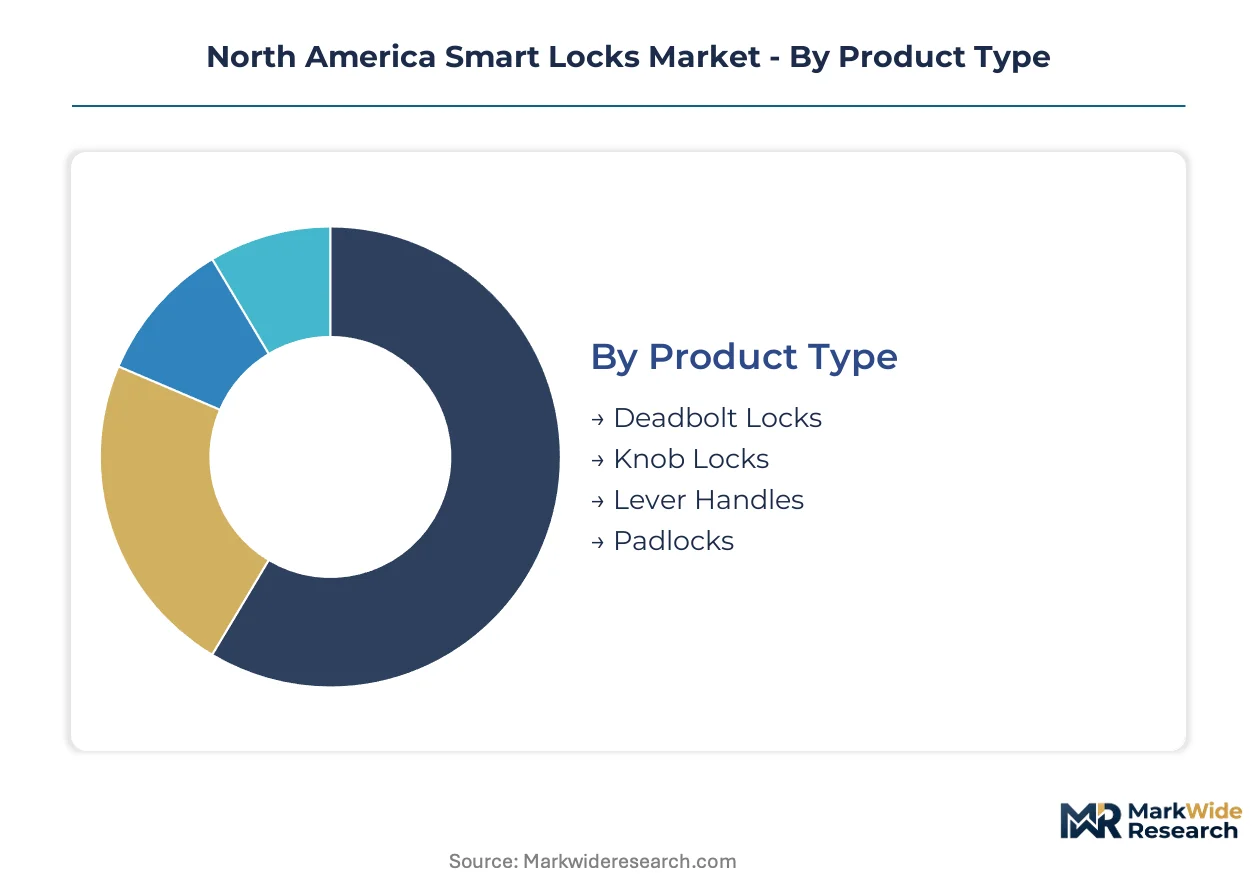
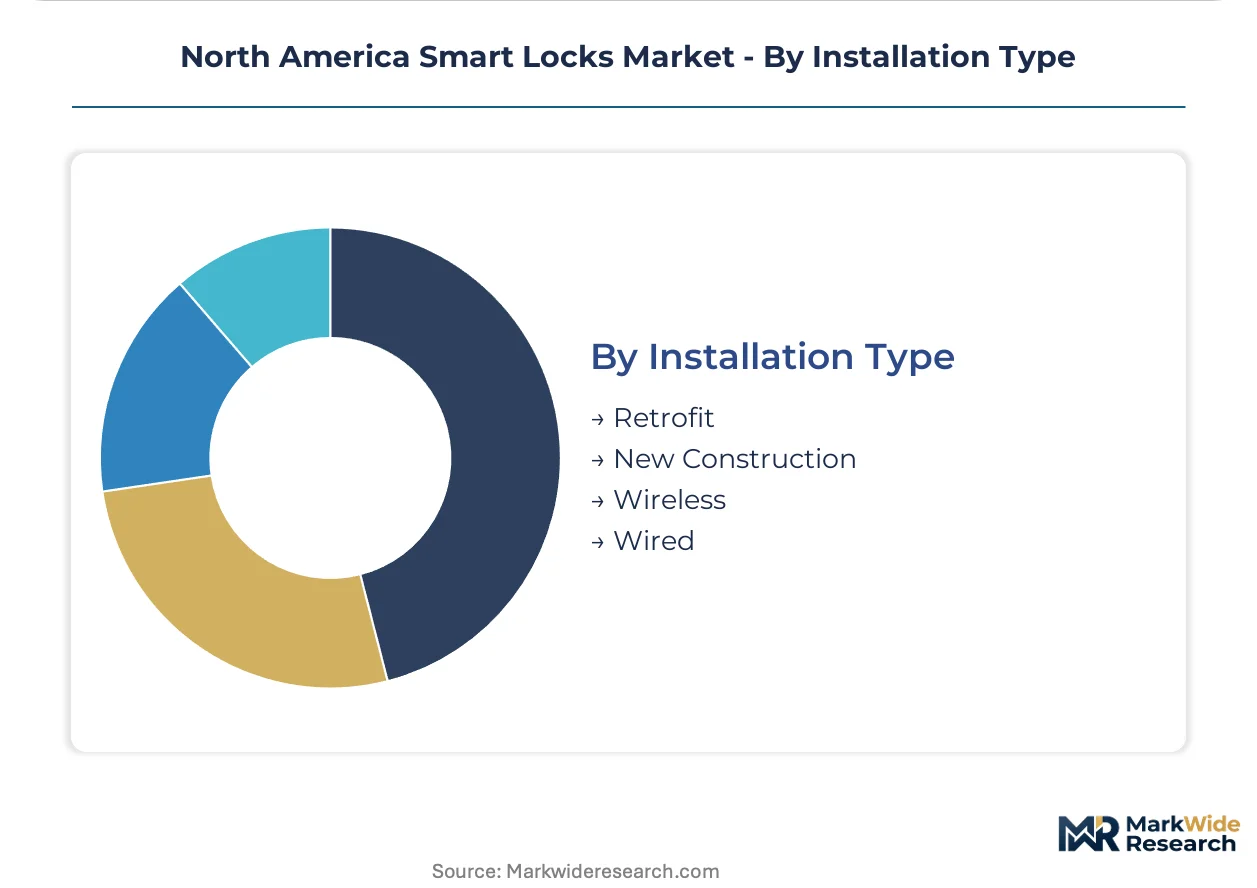
Smart lock purchasing decisions diverge sharply across installation contexts and connectivity requirements. Upgrade cycles for existing mechanical hardware differ fundamentally from new construction specification timelines, with each pathway demanding distinct certification, pricing, and channel strategies.
Product Type:
Replacement cycles for mechanical locks vary by form factor, with deadbolt upgrades outpacing other categories in residential retrofit channels.
- Deadbolt Locks:ANSI/BHMA Grade 2 and Grade 3 cylindrical deadbolts dominate residential retrofit demand due to standardized door prep compatibility. Sun Belt builder programs in Texas and Florida specify these units as baseline amenities, compressing procurement cycles for certified suppliers.
- Knob Locks:Entry knob assemblies with integrated smart functionality address rental property and light commercial applications where tenant turnover drives frequent credential reprogramming. Demand concentrates in multi-family corridors where property managers prioritize low-cost rekeying alternatives.
- Lever Handles:ADA-compliant lever configurations serve hospitality and assisted living facilities requiring accessibility accommodation alongside electronic access control.
- Padlocks:Battery-powered hasp and shackle designs target gate, storage, and equipment shed applications with weatherized IP ratings for outdoor deployment.
Deadbolt Locks sits at the top of the volume ranking, with Lever Handles climbing the fastest.
Technology:
Connectivity protocol selection determines hardware cost structures and ecosystem compatibility, with trade-offs between standalone operation and integrated automation.
- Bluetooth:Low-energy modules enable smartphone proximity unlocking without home network dependency. Consumer DIY purchases favor this technology for simplified installation without router configuration.
- Wi-Fi:Direct IP connectivity supports remote access management and real-time status monitoring without hub requirements. FCC Part 15 certification for 2.4 GHz coexistence shapes antenna design and power output specifications for dense multi-dwelling deployments.
- Z-Wave:Sub-GHz mesh networking delivers whole-property coverage for professionally monitored smart home systems. Chipset allocation constraints during semiconductor fab capacity cycles delay fulfillment in dealer installation channels.
- Zigbee:IEEE 802.15.4-based mesh protocols integrate with Thread border routers and Matter controllers, enabling cross-platform interoperability for ecosystem-agnostic buyers.
Wi-Fi captures the largest addressable base, while Z-Wave maintains the steepest expansion trajectory in professionally monitored segments.
End User:
Vertical-specific access management requirements create divergent margin profiles, with hospitality and commercial segments commanding premium pricing for audit and integration capabilities.
- Residential:Single-family and multi-family homeowners prioritize smartphone convenience and temporary guest credentialing. Retrofit demand concentrates in owner-occupied suburban markets where DIY installation rates exceed national baselines.
- Commercial:Office and retail tenants require centralized credential management with time-based access restrictions. Integration with existing badge systems and property management platforms drives specification decisions.
- Industrial:Manufacturing and warehouse facilities demand ruggedized hardware with environmental sealing and battery life optimization for infrequently serviced remote entry points.
- Hospitality:Hotel operators deploy mobile key credentialing and cloud-based property management system integration. Florida and Texas hospitality corridors generate premium margin pools through VIP experience differentiation and whole-room automation bundles.
Residential commands absolute volume leadership, with Hospitality gaining share fastest on cloud convergence and mobile credential adoption.
Installation Type:
Deployment methodology determines channel economics and customer acquisition costs, with new construction offering specification lock-in advantages absent from aftermarket replacement.
- Retrofit:Battery-powered designs replace existing mechanical cylinders without wiring modifications. Mass retail and e-commerce channels serve consumer self-installation with online configuration support.
- New Construction:Pre-wiring for smart home infrastructure in Arizona and Nevada greenfield corridors enables hardwired power and network backbones. Builder program partnerships secure multi-year specification commitments before tenant occupancy.
- Wireless:Radio-frequency modules eliminate conduit and cable requirements, reducing labor costs for professional installers in existing building stock.
- Wired:Ethernet or PoE connectivity serves commercial and hospitality deployments requiring continuous power and guaranteed network availability for audit logging compliance.
New Construction dominates forward-looking revenue pipelines, with Wireless expanding most quickly on installation labor savings and mesh network reliability improvements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas and Florida construction labor pools anchor North American smart lock demand, with installer certification programs concentrating in Dallas-Fort Worth and Miami-Dade metro corridors. Pre-wiring contractor networks in these states exceed national density baselines for connected home infrastructure deployment.
United States
Sun Belt builder programs in Texas, Florida, and Arizona specify Grade 2 smart deadbolts as standard amenities, compressing annual procurement cycles. The FCC's Part 15 rules govern Bluetooth, Wi-Fi, Z-Wave, and Zigbee module certification, mandating granular antenna documentation for dense multi-dwelling deployments. Dallas-Fort Worth and Austin construction corridors generate specification lock-in for certified suppliers through multi-family developer preferred vendor rotations.
Canada
Toronto and Vancouver multi-family developers integrate connected access into green building certification pathways, with property management platform convergence driving hardware selection. Health Canada maintains indirect influence through electromagnetic exposure guidelines for wireless devices, while municipal energy efficiency programs in Ontario shape procurement criteria for low-power lock modules. The Greater Toronto Area concentrates hospitality retrofit demand for mobile key credentialing systems.
Mexico
Monterrey and Mexico City manufacturing facilities supply battery housings and injection-molded lock chassis to North American assembly operations, with cross-border logistics integration tightening component lead times. The country's federal telecommunications regulator oversees radio frequency equipment type approval, harmonizing with FCC Part 15 frameworks for streamlined export certification. Baja California assembly plants increasingly handle final lock module integration for US retail channels.
California
The California Consumer Privacy Act imposes statutory damages frameworks on biometric data handling, elevating vendor insurance costs and legal reserve requirements for fingerprint-enabled locks. Silicon Valley smart home platform providers drive Wi-Fi and Thread protocol integration demands, with Matter interoperability certification becoming a procurement filter. Los Angeles and San Francisco municipal building codes incorporate connected device cybersecurity provisions into permit reviews.
Illinois
The Biometric Information Privacy Act creates liability exposure for fingerprint and facial recognition lock deployments, forcing vendors to implement local template processing and strict data retention limits. Chicago's municipal cybersecurity ordinance requires third-party firmware validation for connected locks in commercial and multi-family permits. The Chicagoland corridor concentrates commercial office retrofit demand for centralized credential management systems.
North America Smart Locks Market Competitive Landscape
Capital-heavy hardware manufacturers compete with asset-light platform integrators for margin capture in North American smart lock channels. The market structures around three tiers: multinational security conglomerates with builder program scale, specialized connected home brands with direct-to-consumer reach, and professional installation ecosystem providers with dealer network density. Strategic moves concentrate on property management platform pre-certification partnerships and Matter protocol interoperability certification to reduce ecosystem fragmentation barriers.
Within the multinational security conglomerate tier, Assa Abloy AB and Allegion Plc anchor residential and commercial specification channels through brand portfolio breadth. August Home Inc. occupies a position exemplifying platform-native connected home specialists that prioritize mobile app experience and cloud service integration over traditional mechanical lock heritage. These three entities represent divergent archetypes—integrated hardware-service platforms, legacy security hardware scale players, and digital-native access control innovators—competing for specification influence across retrofit and new construction deployment modes.
| Leading Market Players |
|---|
| Assa Abloy AB |
| Allegion Plc |
| Honeywell International, Inc. |
| Schlage |
| Kwikset |
| August Home Inc. |
| Yale Home |
| Vivint Smart Home, Inc. |
| Salto Systems, S.L. |
| Others |
Value Network & Pricing Analysis
Lithium carbonate price volatility cascades through smart lock manufacturing tiers, compressing margins on battery-powered units while amplifying cost advantages for hardwired new construction specifications. Input cost fluctuations reshape procurement negotiations between East Asian cell suppliers and North American assembly operations, forcing vendors to tier pricing around power architecture choices.
Pricing Analysis
Bundled installation services versus unbundled hardware-only transactions split the market into divergent margin structures. Three-tier pricing structure across premium, standard, and economy levels separates hospitality-grade cloud-integrated systems from mass retail Bluetooth units and builder-program deadbolts. Price differentiation hinges on ANSI/BHMA certification grade and property management platform pre-certification status. Cost compression in the economy tier is intensifying because lithium battery sourcing concentrates in constrained East Asian manufacturing clusters. Mass retail consumers exhibit highest price sensitivity, while hospitality operators prioritize total installed cost including platform integration fees.
Supply Chain Analysis
Trans-Pacific freight cost fluctuations reshape inventory positioning strategies for North American distribution hubs serving Texas and Florida construction corridors. Component sourcing draws from China for lithium cells and RF modules, Mexico for injection-molded chassis and battery housings, and Taiwan for Z-Wave and Zigbee chipsets. Raw material dependencies include lithium carbonate for power systems, ABS and zinc alloys for mechanical hardware, and FR4 substrates for PCB assemblies. Single-source vulnerability concentrates in sub-GHz mesh networking chipsets during semiconductor fab capacity cycles. Distribution runs through big-box retail chains for consumer DIY segments and direct-to-builder programs for new construction specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Smart Locks Market represents a late-cycle quality story as multi-family developers in Sun Belt states shift procurement criteria toward Grade 2 certified deadbolts with integrated platform compatibility. This specification elevation favors vendors with pre-certified property management system partnerships over pure hardware competitors.
For Market Incumbents: Lock in specification advantages through exclusive builder program partnerships in Arizona and Nevada greenfield corridors before preferred vendor list rotations compress margins. Deepen backward integration into lithium battery pack assembly to offset East Asian cell supplier pricing power. Prioritize FCC Part 15 certification pipeline investments to accelerate time-to-market against emerging Matter protocol specialists. For New Entrants and Emerging Players: The mid-market price-point gap between premium hospitality systems and economy mass retail units offers white-space entry for Thread-enabled locks with local biometric processing. Target wireless retrofit installations in Chicago and New York City where municipal cybersecurity ordinances create compliance barriers for incumbent firmware architectures. Pursue dealer certification subsidies as the primary go-to-market angle to overcome Z-Wave commissioning complexity. For Investors and Strategic Acquirers: Consolidation pressure builds where property management platform integration capabilities concentrate among fewer certified hardware vendors. Long-term viability favors platform-native specialists with recurring cloud service revenue over pure hardware manufacturers exposed to lithium cost volatility. Acquisition target archetype: mid-tier connected home brands with Matter interoperability certification and established installer training infrastructure. Monitor Matter protocol adoption rates in professionally monitored smart home ecosystems as the critical inflection signal for ecosystem consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Property Management Platform Pre-Certification | Secures specification lock-in with Texas and Florida multi-family developers rotating vendor lists annually. |
| Matter Protocol Interoperability Certification | Enables cross-platform sales to previously siloed Apple, Google, and Amazon home automation buyers. |
| Local Biometric Template Processing | Reduces Illinois BIPA and California CCPA liability exposure for fingerprint-enabled lock deployments. |
| Dealer Training Program Expansion | Addresses Z-Wave and Zigbee commissioning complexity exceeding consumer DIY installation capability. |
| EPA ENERGY STAR Connected Device Certification | Unlocks utility rebate program eligibility for low-power standby consumption lock modules. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with smart lock product managers, multi-family developer procurement directors, hospitality technology officers, professional installer network heads, and FCC certification consultants with secondary validation. Primary inputs drew from property management platform integration documentation, ANSI/BHMA certification databases, and municipal building code amendment records. Secondary sources included FCC equipment authorization filings, EPA ENERGY STAR program specifications, SEC 10-K disclosures from publicly traded security hardware manufacturers, and construction permit data from Sun Belt metropolitan statistical areas. Bottom-up unit shipment estimates triangulated against top-down construction spending allocations for connected home infrastructure.
Comparable historical reference periods anchored the projection framework, with growth trajectories derived from segment-specific adoption curves across the analysis window. The analytical framework modeled volume and value outputs across product type, connectivity protocol, end-user vertical, and installation methodology dimensions. CAGRs were computed from fitted trend lines applied to annualized shipment data. Industry-specific forecast inputs included pre-wiring penetration rates in greenfield construction corridors and lithium battery cost curve assumptions.
The model assumes a particular technology adoption path; alternative pathways for Thread and Matter protocol convergence would alter the outlook for Z-Wave and Zigbee ecosystem lock-in. Forecasts reflect assumptions about semiconductor fab capacity normalization, municipal cybersecurity ordinance diffusion, and property management platform consolidation velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
North America Pin-Based Access Control Market
Access Control Systems
Global Barrier Systems Market
Access Control Systems
North America Home Security System Market
Access Control Systems
Access Control and Authentication Market
Access Control Systems
Latin America Pin-Based Access Control Market
Access Control Systems
North America Proximity Access Control Market
Access Control Systems
Global Smart Lock Market
Access Control Systems
GCC Home Security Systems Market
Access Control Systems
Global Keyless Vehicle Access Control Systems Market
Access Control Systems
Network Access Control Market
Access Control Systems
Digital Security Control Market
Access Control Systems
Restricted Access Barrier System (RABS) Market
Access Control Systems
Smart Door Lock Market
Access Control Systems
Parking Access Control Market
Access Control Systems
Global Commercial Security System Market
Access Control Systems
Europe Access Control Software Market