
 India Access Control Hardware Market | 2026-2036
India Access Control Hardware Market Size, Share, and Industry Trends Forecast 2026-2036
India Access Control Hardware Market Foresight
Bureau of Indian Standards certification for electronic security equipment is realigning the cost-of-entry calculus for domestic and import-dependent vendors alike. Godrej and Boyce Manufacturing Company Limited leverages its established manufacturing footprint in India to sustain price competitiveness against multinational entrants. Honeywell International Inc. anchors its position through integrated building management systems that bundle access control with fire safety and HVAC. IDEMIA Identity and Security India Private Limited specializes in biometric credential technologies that differentiate its portfolio from conventional card-reader suppliers.
Access control hardware comprises electromechanical and electronic devices—card readers, biometric scanners, keypads, and controllers—engineered to authenticate credentials and regulate physical entry points through standardized communication protocols such as Wiegand and OSDP. These systems serve the primary commercial purpose of protecting personnel, assets, and data across facilities where unauthorized access creates operational or liability risk. Biometric scanners command expanding share as facial recognition and fingerprint recognition technologies mature in accuracy and cost efficiency, while RFID-based card readers retain dominance in high-volume commercial deployments where low per-unit cost and minimal user training outweigh security premium. Integrated systems and cloud-based solutions are capturing disproportionate growth as facility managers prioritize centralized monitoring and remote administration over standalone installations.
The Bureau of Indian Standards, the Central Electricity Authority, and state-level police licensing authorities collectively shape product standards, installation compliance, and market access for security hardware vendors operating across Indian jurisdictions. BIS certification mandates electromagnetic compatibility and environmental durability testing that filter out uncertified imports and informal assemblers. Stakeholders must monitor evolving state police NOC requirements and smart city tender specifications, as these procurement frameworks increasingly embed biometric interoperability and data localization clauses that determine vendor eligibility.
Market Dynamics
Bureau of Indian Standards certification mandates are compressing the vendor landscape, forcing domestic assemblers and import-dependent distributors to absorb compliance costs or exit. This regulatory filter is accelerating consolidation around certified manufacturers with captive testing infrastructure.
Growth Catalysts
- Smart city infrastructure mandates:Municipal corporations in Delhi NCR, Mumbai, and Bengaluru are embedding biometric interoperability requirements into security tenders, creating replacement demand across IT parks and government facilities.
- CEA electrical safety protocols:The Central Electricity Authority's electromagnetic compatibility standards for building automation systems are legitimizing professional installation channels over informal contractors.
- Facial recognition maturation:Algorithm accuracy improvements and cost reductions in 3D camera modules are displacing fingerprint-only systems in premium commercial deployments.
Market Restraints
- Semiconductor input volatility:Controller chip and RFID component supply concentrates in East Asian foundries, exposing Indian integrators to currency fluctuation and logistics disruption.
- BIS testing backlog:Certification queue lengths at Bureau of Indian Standards laboratories extend product launch timelines for new entrants lacking established lab relationships.
- Mobile credential substitution:Smartphone-based access applications are capturing low-security commercial segments where hardware authentication previously dominated.
Strategic Opportunities
- Tier-2 city penetration:Hyderabad, Pune, and Chennai commercial real estate is underpenetrated relative to Mumbai and Delhi NCR, offering first-mover positioning for certified vendors.
- Cloud-native architecture convergence:Integration of access control with building management and video analytics platforms is enabling subscription revenue models for hardware suppliers.
- PLI scheme localization:Production-linked incentive schemes for electronics manufacturing are reducing landed cost disadvantages for domestic assembly operations.
Industry Challenges
- OSDP protocol migration complexity:Legacy Wiegand installations require controller replacement or bridge hardware, complicating upgrade paths for facility managers with constrained capital cycles.
- Biometric data localization compliance:State police NOC requirements and draft data protection frameworks impose storage architecture constraints that fragment product development roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Access Control Hardware Market |
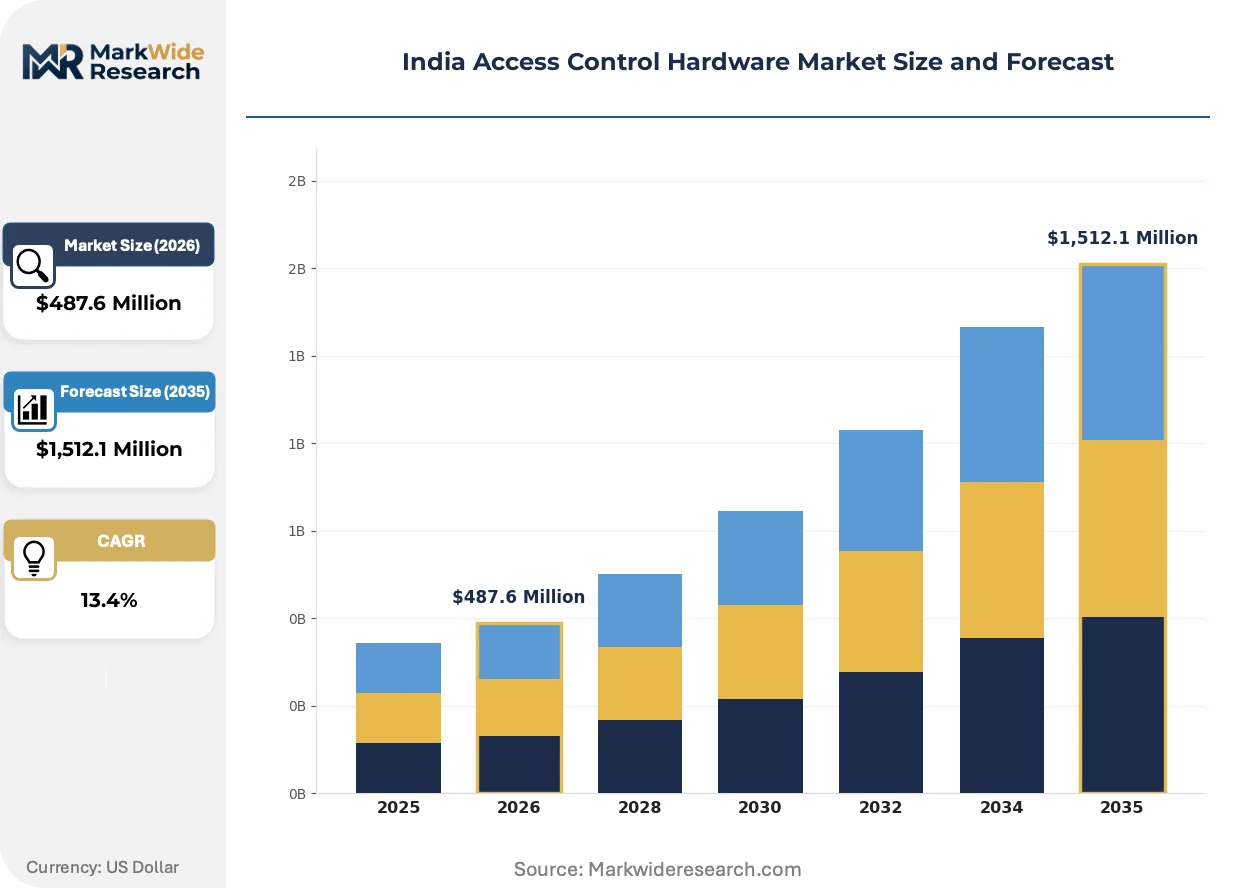
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,512.1 Million |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Card Readers, Biometric Scanners, Keypads, Controllers End User: Commercial Buildings, Residential Complexes, Industrial Facilities, Government Offices Technology: RFID, Fingerprint Recognition, Facial Recognition, PIN-Based Systems Installation: Standalone Systems, Integrated Systems, Wireless Solutions, Cloud-Based Solutions |
| Companies Covered | ASSA ABLOY AB, HID Global Corporation, Honeywell International Inc., Hangzhou Hikvision Digital Technology Co. Ltd., Dahua Technology Co. Ltd., Johnson Controls International plc, IDEMIA Identity and Security India Private Limited, Godrej and Boyce Manufacturing Company Limited, Robert Bosch GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Access Control Hardware Market Shifts & Advancements
Deep learning inference at the edge is redistributing processing architecture across access control deployments, compressing latency requirements while elevating hardware specification floors. This shift is forcing component suppliers to recalibrate power-performance tradeoffs.
Facial recognition with liveness detection is automating credential verification workflows in high-throughput commercial environments. Large IT parks in Bengaluru and Hyderabad are deploying these systems at main entry points to reduce guard staffing ratios. The technology is automating identity confirmation that previously required manual secondary checks, compressing operational expenditure structures for facility operators.
BIS electromagnetic compatibility certification is filtering out uncertified imports from Southeast Asian trading partners. The mandate requires third-party testing at accredited laboratories, adding six to twelve weeks to product introduction timelines. Domestic manufacturers with captive testing relationships are capturing share from distributors dependent on imported controllers.
Enterprise buyers are consolidating vendor relationships around integrated building technology suppliers. Facility managers in Mumbai commercial towers are bundling access control procurement with fire safety and HVAC maintenance contracts, displacing standalone security integrators. This concentration is most visible in Grade-A office stock where single-point accountability reduces operational coordination overhead.
India Access Control Hardware Market Segmentation
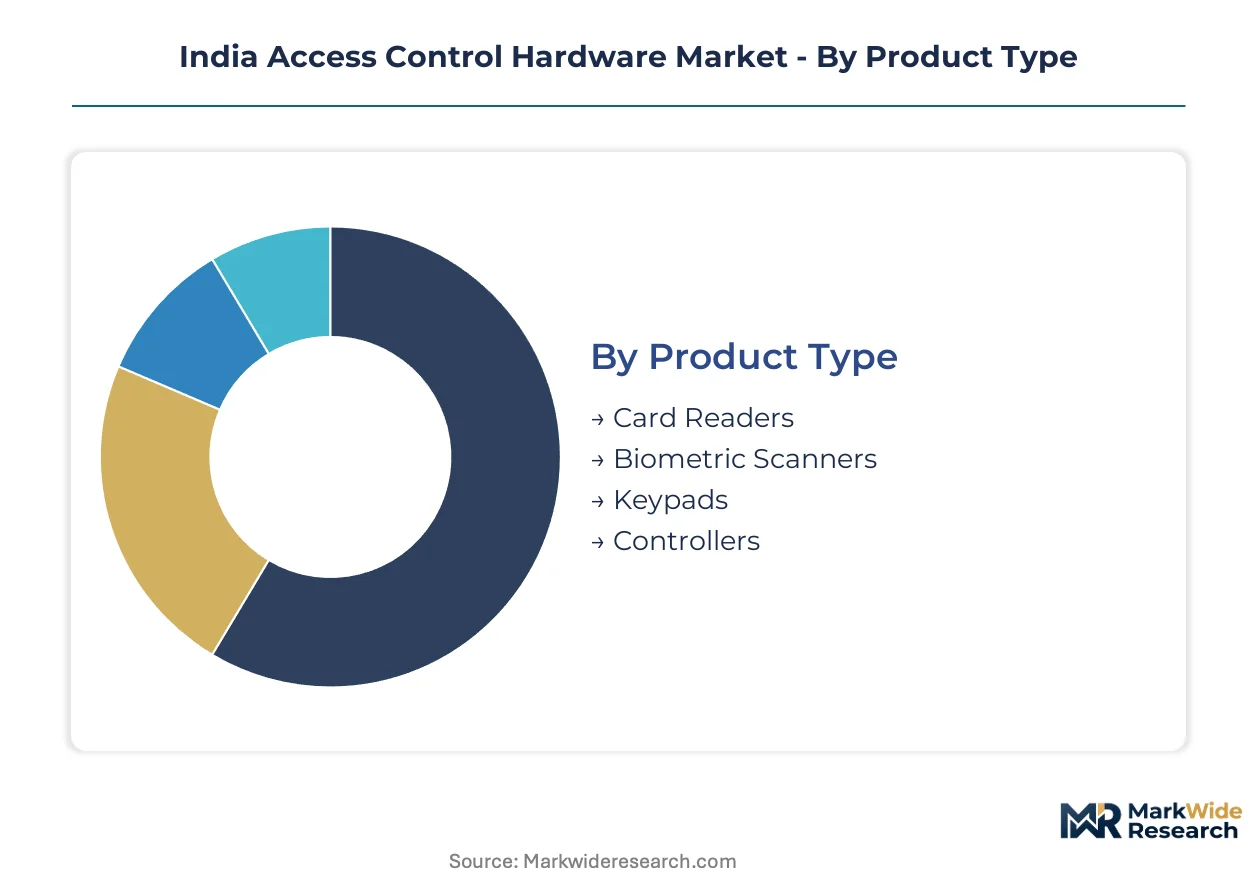
India's access control hardware market fragments across four critical dimensions that determine procurement priorities and vendor selection criteria. Product type and technology choices reflect security-versus-convenience tradeoffs, while end-user verticals and installation architectures shape deployment economics and replacement cycles.
Product Type:
Cost tier separates buyers seeking basic credential verification from those demanding multi-factor authentication infrastructure.
- Biometric Scanners:Fingerprint and facial recognition modules with liveness detection algorithms process credentials at the edge, reducing network dependency. Demand clusters in Bengaluru and Hyderabad IT parks where high-throughput employee screening compresses guard staffing costs. BIS electromagnetic compatibility certification filters out uncertified imports from Southeast Asian trading partners.
- Card Readers:RFID and proximity-based devices using Wiegand or OSDP protocols dominate high-volume commercial deployments. Mumbai commercial towers specify these for tenant access management where per-unit cost and minimal user training outweigh biometric premiums. The Central Electricity Authority's building automation standards are legitimizing professional installation channels over informal contractors.
- Keypads:PIN-entry devices with vandal-resistant enclosures serve cost-sensitive applications in industrial perimeter security.
- Controllers:Centralized processing units manage multiple entry points through standardized communication protocols.
Volume sits with Card Readers; growth tilts toward Biometric Scanners.
End User:
Application context determines security protocol stringency and integration complexity with existing building systems.
- Commercial Buildings:Grade-A office stock in Delhi NCR and Mumbai bundles access control with fire safety and HVAC maintenance contracts. Facility managers prioritize single-point accountability over standalone security integrators. Smart city tenders embed biometric interoperability requirements that filter vendor eligibility.
- Government Offices:State police NOC requirements and draft data protection frameworks impose biometric data localization constraints. Central government facilities in New Delhi specify domestic assembly to comply with public procurement preferences. PLI scheme localization is reducing landed cost disadvantages for certified domestic manufacturers.
- Industrial Facilities:Manufacturing plants and logistics hubs deploy ruggedized hardware for perimeter access and hazardous zone control.
- Residential Complexes:Gated communities in Pune and Chennai adopt smartphone-integrated systems for visitor management and amenity access.
Commercial Buildings anchor current procurement volumes; Government Offices are climbing the fastest as security tender specifications tighten.
Technology:
Maturity curves separate established credential formats from emerging authentication modalities reshaping competitive positioning.
- Facial Recognition:3D camera modules with deep learning inference at the edge automate identity confirmation in high-throughput environments. Large IT parks deploy these at main entry points to eliminate manual secondary checks. Algorithm accuracy improvements and cost reductions are displacing fingerprint-only systems in premium deployments.
- RFID:Proximity and smart card technologies retain dominance where low per-unit cost and minimal user friction outweigh security premiums. High-volume commercial deployments across Mumbai and Bengaluru specify RFID for tenant and visitor credentialing. Semiconductor input volatility in East Asian foundries exposes Indian integrators to currency fluctuation and logistics disruption.
- Fingerprint Recognition:Capacitive and optical sensors serve mid-tier security requirements with established reliability profiles.
- PIN-Based Systems:Numeric entry credentials persist in cost-constrained applications and as backup authentication layers.
RFID commands installed base; Facial Recognition gains share fastest as hardware specifications elevate.
Installation:
Architecture choice reflects capital cycle constraints versus operational expenditure preferences for remote administration capabilities.
- Cloud-Based Solutions:Subscription revenue models enable centralized monitoring and remote administration across distributed facility portfolios. Enterprise buyers in Bengaluru and Hyderabad consolidate vendor relationships around integrated building technology suppliers. BIS testing backlog at certification laboratories extends product launch timelines for new entrants lacking established lab relationships.
- Integrated Systems:Bundled access control with video analytics and building management platforms captures disproportionate growth in Grade-A commercial stock. Mumbai facility managers prioritize operational coordination overhead reduction through single-source procurement. OSDP protocol migration complexity complicates upgrade paths for legacy Wiegand installations.
- Standalone Systems:Single-point deployments serve small commercial tenants and residential applications with limited integration requirements.
- Wireless Solutions:Battery-powered and PoE-minimized installations reduce cabling infrastructure costs in retrofit scenarios.
Integrated Systems dominate new construction; Cloud-Based Solutions show steepest expansion trajectory as facility managers prioritize subscription over capital expenditure models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software Technology Parks of India (STPI) and Special Economic Zones anchor access control hardware procurement clusters across the country. State-level industrial policies amplify this concentration through infrastructure subsidies and preferential procurement frameworks.
Maharashtra
Mumbai's Grade-A commercial towers bundle access control with integrated building management systems. The state's urban development department mandates biometric interoperability in smart city tenders for Thane and Navi Mumbai. Pune's manufacturing corridors and IT parks drive replacement cycles for legacy Wiegand installations.
Karnataka
Bengaluru's IT parks deploy facial recognition systems at main entry points to compress guard staffing ratios. The Karnataka government's Electronics System Design and Manufacturing policy incentivizes domestic assembly operations. Whitefield and Electronic City clusters concentrate demand for cloud-native access architecture.
Delhi-NCR
Central government facilities in New Delhi specify domestic assembly to comply with public procurement preferences. The Delhi Development Authority embeds biometric data localization clauses in security infrastructure tenders. Gurugram's commercial real estate expansion outpaces certified vendor capacity.
Telangana
Hyderabad's HITEC City corridor generates underpenetrated demand relative to Mumbai and Bengaluru benchmarks. The Telangana State Industrial Infrastructure Corporation accelerates SEZ clearances for electronics manufacturing. Gachibowli and Madhapur IT clusters prioritize subscription-based access management over capital expenditure models.
Tamil Nadu
Chennai's automotive and electronics manufacturing facilities deploy ruggedized perimeter access hardware. The Tamil Nadu Industrial Development Corporation channels PLI scheme benefits toward security electronics localization. Sriperumbudur and Oragadam industrial belts specify electromagnetic compatibility-certified controllers.
India Access Control Hardware Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across certification tiers. The vendor landscape compresses around Bureau of Indian Standards compliance, filtering uncertified imports and informal assemblers. Three archetypes dominate: integrated building technology suppliers, biometric credential specialists, and domestic manufacturing conglomerates with captive testing infrastructure. Consolidation accelerates through strategic partnerships with system integrators and backward integration into controller chip sourcing.
Among diversified industrial conglomerates, Godrej and Boyce Manufacturing Company Limited anchors domestic manufacturing capacity with established BIS laboratory relationships. Honeywell International Inc. exemplifies the integrated building technology archetype through bundled fire safety and HVAC procurement channels. IDEMIA Identity and Security India Private Limited occupies the biometric specialist tier with facial recognition and fingerprint module differentiation. These three represent distinct competitive vectors: price competitiveness through localization, operational coordination reduction through integration, and security premium capture through biometric interoperability.
| Leading Market Players |
|---|
| ASSA ABLOY AB |
| HID Global Corporation |
| Honeywell International Inc. |
| Hangzhou Hikvision Digital Technology Co. Ltd. |
| Dahua Technology Co. Ltd. |
| Johnson Controls International plc |
| IDEMIA Identity and Security India Private Limited |
| Godrej and Boyce Manufacturing Company Limited |
| Robert Bosch GmbH |
| Others |
Supply & Pricing Matrix
Captive testing infrastructure anchors supply positioning and pricing power for Bureau of Indian Standards-certified manufacturers. Domestic assemblers with established laboratory relationships compress certification timelines while import-dependent distributors absorb six-to-twelve-week queue delays that erode margin structures.
Pricing Analysis
Short lead-time premiums separate certified domestic manufacturers from import-dependent competitors facing extended BIS laboratory queues. Three-tier pricing structure across certified-premium, standard-compliant, and economy-uncertified levels tracks electromagnetic compatibility testing completion status. Cost compression in economy tiers intensifies as smartphone-based mobile credentials capture low-security commercial segments. Government facilities and Grade-A commercial towers exhibit least price sensitivity due to tender mandates embedding biometric interoperability requirements.
Supply Chain Analysis
Refurbishment flows for legacy Wiegand controllers sustain aftermarket revenue streams while OSDP protocol migration accelerates replacement demand. Controller chip and RFID component sourcing concentrates in Taiwan, South Korea, and China, exposing Indian integrators to currency fluctuation and logistics disruption. Semiconductor input volatility from East Asian foundries creates single-source vulnerability for biometric scanner camera modules. Distribution runs through professional installation channels legitimized by Central Electricity Authority building automation standards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bureau of Indian Standards certification mandates construct a cost-of-compliance moat that filters uncertified imports and informal assemblers from vendor eligibility. This regulatory barrier consolidates procurement share around manufacturers with captive testing infrastructure and established laboratory relationships.
For Market Incumbents: Extend certification coverage into emerging biometric interoperability specifications before state police NOC requirements harden. Capture cloud-native architecture convergence through subscription revenue models that displace standalone hardware competitors. Mobile credential substitution threatens low-security segment share; defend through integrated building management bundling with fire safety and HVAC maintenance contracts. For New Entrants and Emerging Players: Begin with Hyderabad and Pune commercial real estate corridors where certified vendor capacity lags Mumbai and Bengaluru benchmarks. Target tier-2 city IT parks seeking facial recognition systems with liveness detection for high-throughput employee screening. Establish go-to-market positioning through system integrator partnerships rather than direct facility manager sales. For Investors and Strategic Acquirers: Exit pathways concentrate in integrated building technology suppliers with bundled procurement channel control. Long-term viability hinges on domestic assembly localization capturing Production-Linked Incentive scheme benefits for electronics manufacturing. Monitor state police NOC requirement expansion as inflection indicator for biometric data localization compliance investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| BIS Certification Acceleration | Established laboratory relationships compress product launch timelines against import-dependent competitors. |
| Cloud-Native Architecture Development | Subscription revenue models align facility manager preferences for operational expenditure over capital deployment. |
| Tier-2 City Distribution Expansion | Hyderabad and Pune commercial corridors offer first-mover positioning ahead of certified vendor saturation. |
| Biometric Interoperability Investment | Smart city tender specifications increasingly embed facial recognition and fingerprint module compatibility requirements. |
| Controller Chip Backward Integration | In-house sourcing of RFID and processing components reduces East Asian foundry dependency exposure. |
Research Methodology
Independent corroboration across facility manager interviews, system integrator assessments, and regulatory filing analysis underwrites the qualitative findings. Primary fieldwork engaged security procurement leads at IT parks, commercial tower operators, state police licensing authorities, and BIS certification specialists. Secondary validation drew from Bureau of Indian Standards electromagnetic compatibility test records, Central Electricity Authority building automation advisories, smart city tender documentation, and state-level SEZ procurement databases. Bottom-up demand aggregation across product types and end-user verticals triangulates against top-down market sizing from certified manufacturer capacity estimates.
Rate-of-change decomposition separates volume expansion from value migration across the projection horizon. Segmentation modeling incorporates product type, technology maturity, end-user vertical, and installation architecture dimensions. CAGRs derive from replacement cycle analysis of legacy Wiegand installations, smart city infrastructure deployment schedules, and cloud-native solution adoption curves. Forecast inputs include BIS certification queue length projections and PLI scheme localization incentive trajectories for electronics manufacturing.
Underlying measurement precision varies by segment; biometric scanner and cloud-based solution categories carry tighter precision than standalone keypad and controller estimates due to concentrated vendor disclosure. Forecasts reflect assumptions regarding state police NOC requirement harmonization and semiconductor supply normalization. Practitioners should monitor BIS testing backlog expansion and draft data protection framework finalization for early signals of certification timeline compression or biometric data localization architecture mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Port Security Systems Market
Access Control Systems
Automated Smart Locker System Market
Access Control Systems
APAC Home Security System Market
Access Control Systems
Japan Access Control Market
Access Control Systems
China Access Control Market
Access Control Systems
Electronic Access Control Systems Market
Access Control Systems
Acousto-Magnetic (AM) Security Systems Market
Access Control Systems
Restricted Access Barrier System (RABS) Market
Access Control Systems
Global Digital Door Lock Systems Market
Access Control Systems
Door Controller Systems Market
Access Control Systems
Europe Access Control Hardware Market
Access Control Systems
Physical Access Control Market
Access Control Systems
Bluetooth Smart Lock Market
Access Control Systems
Facial Recognition Access Control Solution Market
Access Control Systems
Turnstiles Access Control Systems Market
Access Control Systems
Mode Locking Device Market