
 United States Polyols Market | 2026-2036
United States Polyols Market Size, Share, and Industry Trends Forecast 2026-2036
United States Polyols Market Intelligence
Asset-light toll manufacturing and third-party reactor leasing is rewriting competitive entry dynamics for mid-scale polyol producers. Huntsman Corporation leverages its integrated propylene oxide-polyether chain to sustain margin capture across flexible foam formulations. Dow Inc. anchors its position through backward integration into chlorine and propylene feedstocks, while Covestro AG differentiates via specialized copolymer polyols for high-resilience automotive seating.
Polyols are multifunctional alcohols containing two or more hydroxyl groups, typically synthesized via alkoxylation of starter molecules with ethylene oxide or propylene oxide to achieve molecular weights ranging from hundreds to over ten thousand Daltons, serving primarily as backbone reactants in polyurethane polymerization. Polyether polyols dominate volume demand through their cost efficiency in flexible slabstock and molded foam applications, while bio-based polyols represent the fastest-expanding category as furniture brands and automotive OEMs impose renewable content mandates on tier-one suppliers. Polyester polyols command premium positioning in coatings and adhesives where hydrolytic stability and abrasion resistance justify higher raw material costs.
The EPA administers hydrofluorocarbon phasedown timelines under the AIM Act that constrain blowing agent choices in rigid foam insulation, while OSHA enforces diisocyanate exposure limits that affect downstream polyurethane processing economics and equipment investment. State-level building energy codes in California and New York progressively tighten thermal performance requirements, amplifying demand for high-efficiency rigid foam systems. Stakeholders must monitor how forthcoming EPA rulemakings on per- and polyfluoroalkyl substances intersect with polyol catalyst packages and surfactant systems.
Market Dynamics
The EPA's phasedown of hydrofluorocarbon blowing agents under the AIM Act is compressing formulation timelines and forcing rigid foam producers to requalify entire product portfolios with lower-GWP alternatives. This regulatory compression is reshaping capital allocation across the value chain.
Growth Catalysts
- Automotive Lightweighting Mandates:OEMs specify polyol-based seating foams to meet Corporate Average Fuel Economy standards, with flexible foam content per vehicle rising steadily.
- REACH-equivalent State Building Codes:California's Title 24 and New York's stretch codes tighten thermal performance requirements, amplifying demand for high-efficiency rigid insulation systems.
- Gulf Coast Petrochemical Integration:Concentrated propylene oxide supply chains along the Texas-Louisiana corridor sustain cost-competitive polyether production for domestic consumption.
Market Restraints
- Propylene Oxide Supply Concentration:Three integrated producers control the majority of domestic PO capacity, creating feedstock availability risk during turnarounds or weather events.
- OSHA Diisocyanate Exposure Limits:Downstream polyurethane processors face elevated compliance costs and equipment investment requirements to meet permissible exposure thresholds.
- Bio-based Feedstock Cost Premium:Soy oil and castor oil-derived polyols trade at sustained premiums versus petroleum-based equivalents, limiting penetration in price-sensitive construction applications.
Strategic Opportunities
- Mid-Atlantic Manufacturing Reshoring:Automotive seating suppliers in Michigan and Ohio seek localized polyol sourcing to reduce inbound freight exposure from Gulf Coast producers.
- Recycled Content Mandates:California's SB 54 and emerging extended producer responsibility frameworks create pull for circular polyol formulations incorporating chemically recycled content.
- Copolymer Polyol Specialization:High-resilience automotive seating specifications favor graft polyol technology, commanding margin premiums over conventional flexible foam grades.
Industry Challenges
- Alkoxylation Reactor Capacity Scarcity:Toll manufacturing availability constrains mid-scale entrants seeking to commercialize novel bio-based formulations without capital-intensive asset builds.
- AIM Act Compliance Timeline Compression:EPA-mandated HFC phasedown schedules require simultaneous reformulation of blowing agent packages, catalyst systems, and surfactant compatibilization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Polyols Market |
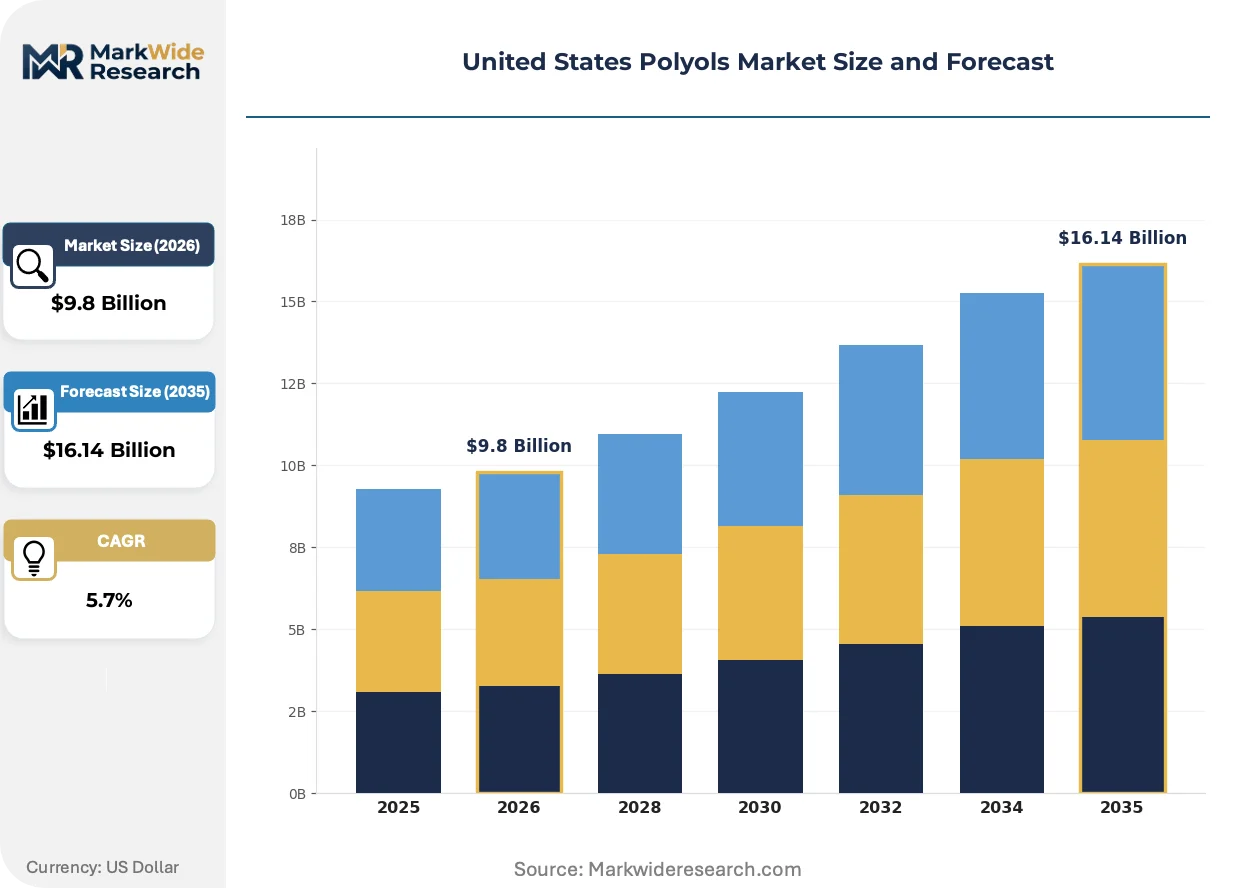
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $16.14 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyether Polyols, Polyester Polyols, Sugar Alcohols, Bio-based Polyols Application: Flexible Foam, Rigid Foam, Coatings, Adhesives End User: Furniture, Automotive, Construction, Consumer Goods Technology: Batch Production, Continuous Production, Green Chemistry, Polymer Modification |
| Companies Covered | Huntsman Corporation, Cargill, Incorporated, Dow Inc., Carpenter Co., Ashland Global Holdings Inc., BASF SE, Stepan Company, Shell plc, Covestro AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Polyols Market Strategic Shifts & Innovations
Formulation intelligence platforms and predictive property modeling are compressing development cycles for next-generation polyol systems. These capabilities are redistributing competitive advantage toward data-integrated producers.
Digital twin technology for alkoxylation reactor optimization is digitizing yield prediction and energy consumption forecasting across continuous production trains. Flexible foam compounders in the automotive supply chain are adopting these platforms to reduce batch-to-batch variability. This digitization is compressing the traditional empirical testing burden that historically dominated new grade qualification.
The EPA's enforcement of HFC phasedown milestones under the AIM Act is constraining blowing agent selections in rigid boardstock and spray foam applications. Formulators must requalify thermal performance ratings with hydrofluoroolefin or hydrocarbon alternatives. Construction insulation producers in climate zones 5-7 face the steepest reformulation requirements to maintain R-value specifications.
Automotive OEMs are consolidating supplier panels and imposing renewable content thresholds on tier-one seating manufacturers. Procurement teams now specify minimum bio-based polyol percentages in Request for Quote documentation. This specification-driven sourcing rotation is most visible in Detroit Three light truck platforms and Southeast Asian transplant operations serving the US market.
United States Polyols Market Segmentation
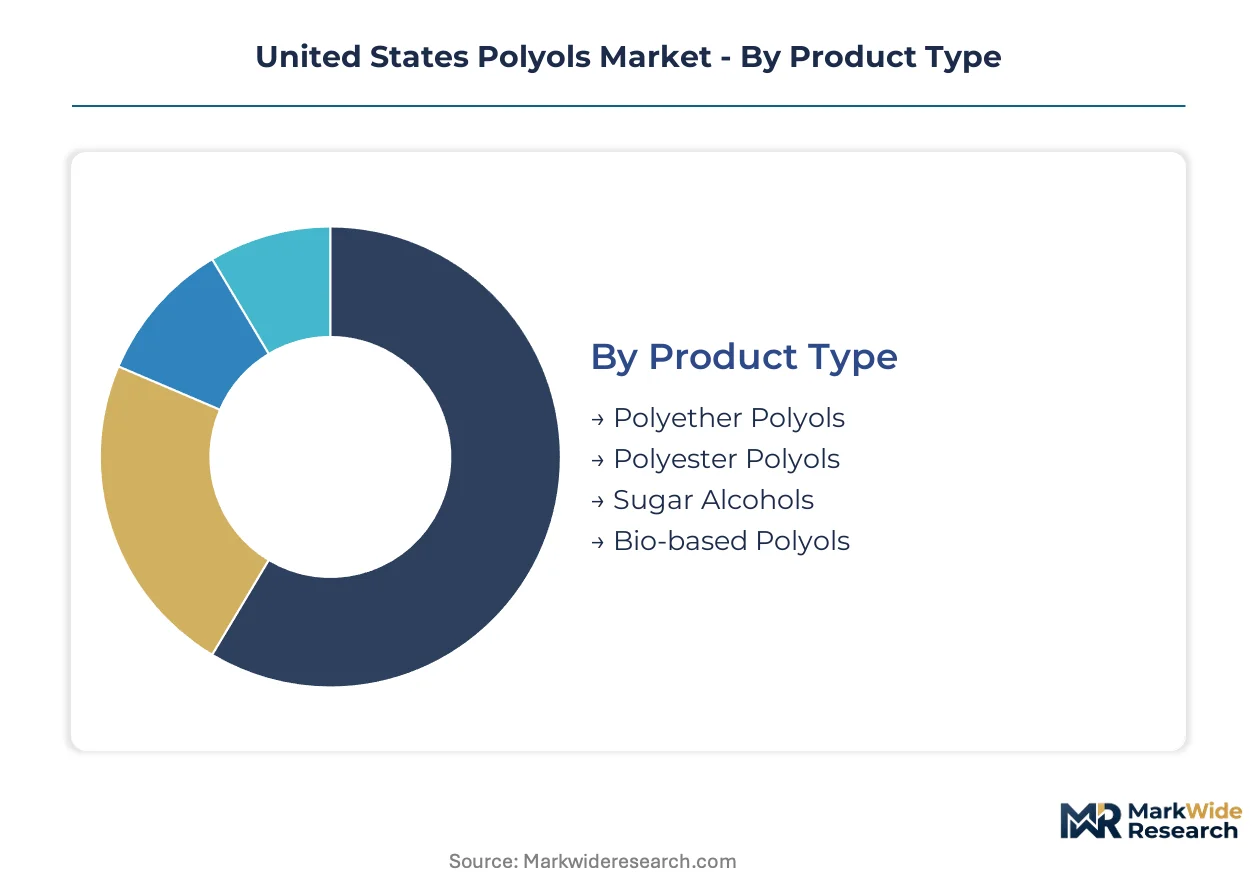
Polyol market segmentation reveals how formulation chemistry, application requirements, and manufacturing technology intersect to create distinct competitive arenas. Understanding these boundaries helps stakeholders identify where margin pools concentrate and where technical differentiation commands pricing power.
Product Type:
Mature commodity grades dominate volume throughput while specialty and sustainable variants represent the emerging frontier for value capture.
- Polyether Polyols:Synthesized via alkoxylation of starter molecules with propylene oxide or ethylene oxide, these materials achieve molecular weights from hundreds to over ten thousand Daltons. Flexible slabstock and molded foam applications in automotive seating across Michigan and Ohio absorb the majority of domestic consumption, with Gulf Coast propylene oxide supply chains sustaining cost-competitive production.
- Polyester Polyols:Built from dicarboxylic acids and diols, these materials deliver superior hydrolytic stability and abrasion resistance compared to polyether alternatives. Premium coatings and adhesive formulations in industrial maintenance applications justify higher raw material costs, though moisture sensitivity constrains use in open-cell foam systems.
- Sugar Alcohols:Sorbitol and mannitol derivatives serve as starter molecules for specialized polyether synthesis in rigid foam insulation.
- Bio-based Polyols:Soy oil and castor oil feedstocks supply renewable content for furniture brands meeting procurement mandates.
Polyether polyols handle the majority of throughput; bio-based polyols are expanding most quickly on share as sustainability specifications harden.
Application:
Volume concentrates in cushioning and insulation, with protective coatings representing the premium tier where formulation complexity commands margin.
- Flexible Foam:Open-cell polyurethane systems derived from polyether polyols absorb impact and distribute pressure in seating and bedding applications. Automotive OEMs in Detroit and transplant operations across the Southeast specify these materials for light truck platforms, with Corporate Average Fuel Economy standards driving lighter foam densities.
- Rigid Foam:Closed-cell structures deliver thermal insulation performance in building envelopes and appliance manufacturing. California's Title 24 and New York stretch codes amplify demand for high-efficiency boardstock and spray foam systems, though EPA AIM Act HFC phasedown timelines compress reformulation schedules.
- Coatings:Polyol-isocyanate crosslinking creates abrasion-resistant protective films for industrial substrates.
- Adhesives:Structural bonding applications leverage polyester polyol hydrolytic stability in moisture-exposed environments.
Flexible foam commands the largest volume position; rigid foam is gaining share fastest as building envelope standards tighten across climate zones 5-7.
End User:
Customer concentration patterns split between specification-driven automotive procurement and price-sensitive construction distribution channels.
- Furniture:Mattress and upholstered seating manufacturers specify slabstock grades for cutting and fabrication, with emerging renewable content thresholds in retailer sustainability programs. Bio-based polyol penetration is highest here due to consumer-facing brand positioning and lower performance sensitivity versus automotive applications.
- Automotive:Tier-one seating suppliers face consolidated supplier panels and technical qualification requirements for molded foam systems. OEM procurement teams now embed minimum bio-based percentages in Request for Quote documentation, reshaping sourcing rotation for Detroit Three platforms.
- Construction:Insulation contractors and panel manufacturers purchase rigid foam systems through distribution, with cost efficiency dominating specification decisions.
- Consumer Goods:Appliance insulation and packaging applications absorb commodity-grade production.
Automotive commands premium formulation margins; furniture is climbing the fastest on bio-based specification adoption.
Technology:
Manufacturing scale and process intensification separate mass-market producers from specialty compounders serving niche performance requirements.
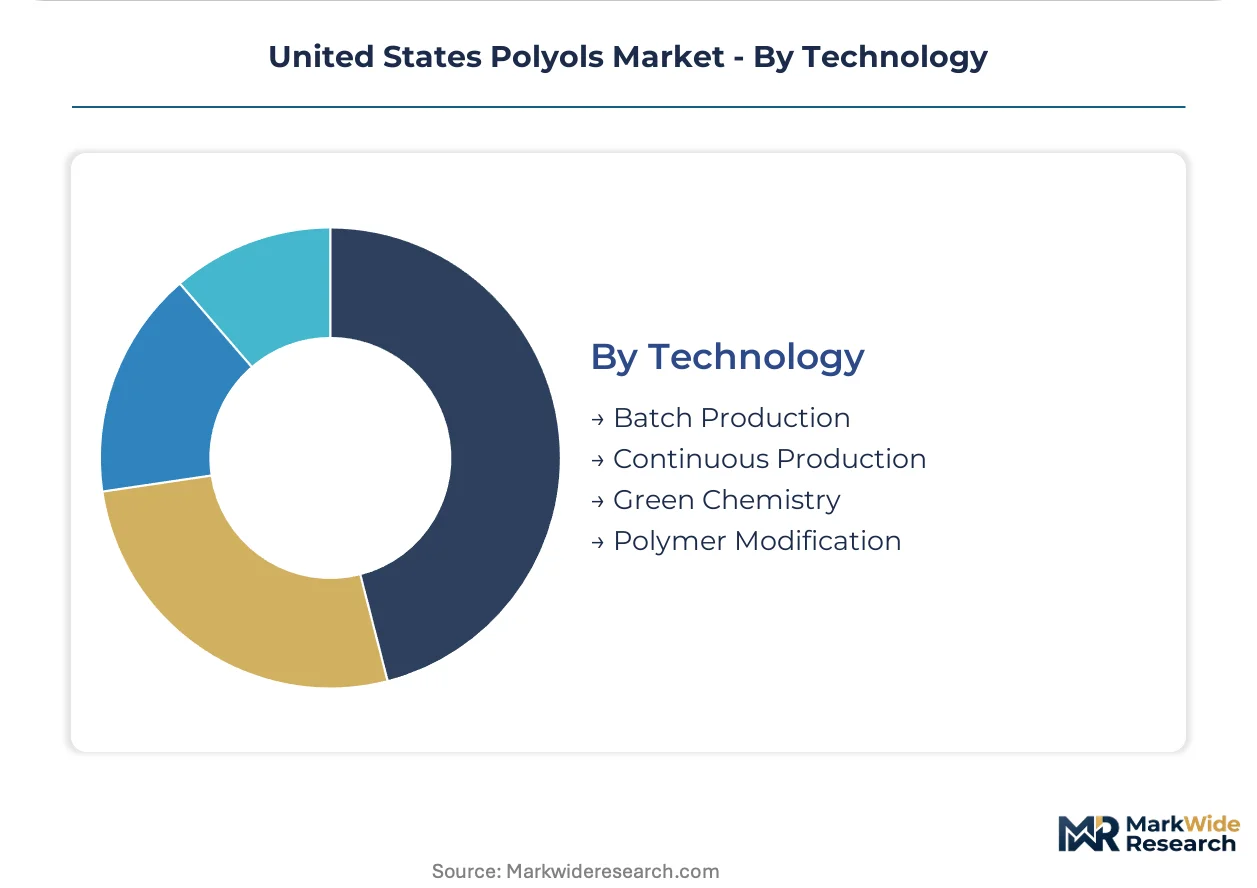
- Batch Production:Discontinuous alkoxylation in stirred-tank reactors enables rapid grade changeovers and small-lot customization for specialty copolymer formulations. Mid-scale producers leverage toll manufacturing arrangements to commercialize novel bio-based grades without capital-intensive asset builds.
- Continuous Production:Tubular reactor systems achieve superior energy efficiency and yield consistency for high-volume polyether grades. Integrated Gulf Coast producers exploit this technology to supply cost-competitive material for flexible foam slabstock.
- Green Chemistry:Catalytic innovations and renewable feedstock processing reduce environmental footprint in bio-based polyol manufacturing.
- Polymer Modification:Graft and copolymer technologies create high-resilience automotive seating grades commanding margin premiums.
Continuous production handles the majority of throughput; green chemistry is advancing fastest on regulatory and procurement pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal incentives under the Inflation Reduction Act and state-level building performance standards are redistributing polyol demand across domestic manufacturing clusters. Regional specialization reflects feedstock access, automotive OEM concentration, and construction code stringency.
Gulf Coast
Integrated propylene oxide production along the Texas-Louisiana corridor sustains cost-competitive polyether manufacturing for flexible foam slabstock. EPA AIM Act enforcement compresses HFC blowing agent reformulation timelines for rigid insulation producers. Houston and Lake Charles anchor the nation's largest continuous alkoxylation capacity, supplying molded foam systems to automotive seating fabricators.
Midwest
Detroit Three light truck platforms specify high-resilience seating foams from tier-one suppliers concentrated in Michigan and Ohio. OSHA diisocyanate exposure limits elevate compliance costs for polyurethane processors in the automotive supply chain. The Toledo-Cleveland corridor hosts specialty compounders serving seating manufacturers with localized just-in-time delivery.
Southeast
Transplant automotive operations in Tennessee, South Carolina, and Alabama absorb flexible foam systems for light truck and SUV production. State economic development authorities offer tax abatements for chemical manufacturing investments. The I-85 corridor between Atlanta and Charlotte attracts mid-scale polyol distributors seeking reduced freight exposure from Gulf Coast supply bases.
California
Title 24 building energy codes mandate high-efficiency rigid foam insulation in climate zones 8-16, amplifying demand for low-GWP spray foam systems. SB 54 extended producer responsibility frameworks create pull for circular polyol formulations with recycled content. The Central Valley and Inland Empire construction markets absorb premium rigid boardstock despite higher delivered costs from out-of-state producers.
Northeast
New York stretch codes and Massachusetts building performance standards tighten thermal envelope requirements for multifamily and commercial construction. Cold climate zones 5-7 drive specification of high-R-value rigid foam systems. The New Jersey-Philadelphia chemical corridor hosts legacy polyester polyol capacity serving coatings and adhesives manufacturers.
United States Polyols Market Key Industry Players
Channel-controlling players compete with product-specialist players across formulation tiers, with integrated propylene oxide producers capturing margin in commodity flexible foam grades while specialty compounders command premiums in automotive seating and rigid insulation. The market structure concentrates around three strategic archetypes: Gulf Coast-integrated mass producers, regional toll manufacturers, and copolymer polyol specialists. Dominant competitive moves include backward integration into chlorine and propylene feedstocks, and strategic partnerships with automotive tier-one seating suppliers.
Within the integrated producer tier, Dow Inc. and Huntsman Corporation exemplify scale-driven positioning anchored to captive propylene oxide supply. Covestro AG occupies a specialization position representing the copolymer polyol archetype for high-resilience automotive applications. These three entities collectively illustrate how feedstock control, formulation technology, and end-use specification depth determine competitive positioning.
| Leading Market Players |
|---|
| Huntsman Corporation |
| Cargill, Incorporated |
| Dow Inc. |
| Carpenter Co. |
| Ashland Global Holdings Inc. |
| BASF SE |
| Stepan Company |
| Shell plc |
| Covestro AG |
| Others |
Cost & Logistics Intelligence
Tight alkoxylation reactor utilization along the Gulf Coast petrochemical corridor is compressing spot availability and amplifying contract pricing power for integrated propylene oxide producers serving flexible foam compounders. This capacity constraint simultaneously elevates toll manufacturing rates and reinforces backward integration incentives among mid-scale automotive seating suppliers seeking supply security.
Pricing Analysis
Performance tier (automotive-specification versus construction-grade) creates the primary spread across polyol quotations, with high-resilience copolymer grades commanding substantial premiums over commodity slabstock equivalents. Contract-based long-term offtake dominates procurement patterns, though spot transactions persist for specialty bio-based formulations where supply fragmentation enables price discovery. Cost compression in rigid foam insulation is intensifying because EPA AIM Act compliance timelines force simultaneous reformulation of blowing agent packages, catalyst systems, and surfactant compatibilization. Construction distributors exhibit the highest price sensitivity, while automotive tier-one seating manufacturers prioritize specification compliance and just-in-time reliability over unit cost minimization.
Supply Chain Analysis
Toll manufacturing concentration among Gulf Coast alkoxylation specialists and regional batch reactor operators in the Midwest constrains mid-scale entrants seeking commercial-scale production without capital-intensive asset builds. Domestic supply draws from integrated propylene oxide production in Texas and Louisiana, supplemented by polyester polyol capacity in the New Jersey-Philadelphia chemical corridor. Feedstock exposure centers on propylene oxide supply concentration among three integrated producers, creating single-source vulnerability during planned turnarounds or unplanned weather disruptions. Distribution runs through direct rail and tank truck delivery to automotive seating fabricators, with construction insulation systems flowing via chemical distributors serving regional contractor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation services and technical qualification support represent the fastest-expanding revenue layer, outpacing base polyol volume growth as automotive OEMs consolidate supplier panels and impose renewable content mandates. This service-attach opportunity rewards producers capable of embedding predictive property modeling and digital twin optimization into customer relationships.
For Market Incumbents: Entrench position through captive propylene oxide supply expansion and strategic toll manufacturing partnerships that foreclose mid-scale competitor access to alkoxylation capacity. Accelerate copolymer polyol R&D investment to defend margin capture against bio-based substitute formulations penetrating furniture applications. Prioritize Gulf Coast reactor debottlenecking to maintain cost position in flexible foam slabstock grades serving price-sensitive construction channels.
For New Entrants and Emerging Players: Pursue white-space opportunity in Mid-Atlantic regional manufacturing reshoring, where automotive seating suppliers in Michigan and Ohio seek localized polyol sourcing to reduce inbound freight exposure. Target bio-based formulation partnerships with furniture brands facing retailer renewable content mandates, leveraging toll manufacturing arrangements to circumvent capital barriers. Lead with green chemistry certification and circular content verification to differentiate against incumbent commodity positioning.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across continuous alkoxylation capacity expansions, favoring asset-light toll manufacturing platforms and specialty copolymer formulation specialists over commodity polyether producers. Acquisition targets should demonstrate differentiated graft polyol technology or established automotive seating qualification relationships. Monitor EPA rulemaking timelines on per- and polyfluoroalkyl substances as an inflection indicator for catalyst package and surfactant system reformulation requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Oxide | Captive feedstock supply secures margin capture against PO supply concentration risk. |
| Green Chemistry Certification Program | Bio-based polyol positioning aligns with automotive OEM renewable content mandates. |
| Toll Manufacturing Partnership | Asset-light reactor access enables mid-scale entrants to commercialize novel formulations. |
| Long-term Supply Agreement | Contractual volume commitments reduce spot price exposure for construction insulation producers. |
| Joint Venture for Regional Manufacturing | Localized production in the Midwest reduces freight costs for automotive seating fabricators. |
Research Approach
Cross-validation between primary interviews with alkoxylation plant managers, automotive tier-one procurement leads, and construction distribution channel partners anchors the qualitative findings against secondary validation from customs trade data, ACC industry reports, and SEC 10-K filings. The research combines bottom-up production capacity surveys with top-down demand modeling across flexible foam, rigid insulation, and coatings applications. Triangulation between stakeholder interview insights and quantitative trade flow analysis ensures consistency in supply chain concentration and pricing power assessments.
Calibration against historical propylene oxide price volatility and automotive production cycles informs the analytical framework across the projection horizon. Segmentation dimensions modeled include polyol chemistry type, application end-use, manufacturing technology, and regional production hub. CAGRs were derived through regression analysis of demand drivers correlated with building code stringency, automotive lightweighting mandates, and bio-based procurement thresholds. Industry-specific forecast inputs incorporate EPA AIM Act compliance timelines and OSHA diisocyanate exposure limit enforcement patterns.
Sensitivities concentrate around propylene oxide supply disruptions, HFC phasedown acceleration, and bio-based feedstock cost volatility. Forecasts reflect assumptions regarding regulatory enforcement consistency and automotive OEM specification stability. Quarterly review of propylene oxide inventory levels, EPA rulemaking dockets, and automotive platform engineering changes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Global Polycarbonate Market
Polymers & Resins
Styrene Acrylonitrile (SAN) Market
Polymers & Resins
ASEAN Ethylene Vinyl Acetate (EVA) Resins Market
Polymers & Resins
Global Polyoxymethylene (POM) Market
Polymers & Resins
Polyisobutene Market
Polymers & Resins
Global Polyolefin Powders Market
Polymers & Resins
Expanded Thermoplastic Polyurethane Market
Polymers & Resins
Global Bio Polyamide Market
Polymers & Resins
Fluorine Polymer Films Market
Polymers & Resins
High-Purity Epoxy Resin Market
Polymers & Resins
Polypropylene Filler Sheet Market
Polymers & Resins
Global One Component Polyurethane Foam Market
Polymers & Resins
Polyethylene Furanoate Market
Polymers & Resins
Global Thermally Conductive Plastics Market
Polymers & Resins
Poly Alpha Olefin (PAO) Market