
 Polyethylene Terephthalate (PET) Resin Market | 2026-2036
Polyethylene Terephthalate (PET) Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Polyethylene Terephthalate (PET) Resin Market Analytics
Recycled-content certification and toll-processing services is hardening as a distinct revenue layer in PET resin commercialization. Indorama Ventures leverages its integrated bottle-to-bottle recycling infrastructure across multiple continents to sustain supply security for brand-owner contracts. Alpek anchors North American PET production through DAK Americas, its wholly owned subsidiary, while competing on purified terephthalic acid backward integration. Jiangsu Sanfangxiang Group dominates Asian filament-grade PET supply, extending its reach into differentiated industrial yarn segments.
Polyethylene terephthalate resin is a thermoplastic polyester polymerized from ethylene glycol and terephthalic acid, with intrinsic viscosity typically ranging from 0.70 to 0.84 dL/g depending on end-use performance requirements; it functions primarily as a lightweight, barrier-capable material for packaging and synthetic fiber applications. Recycled PET commands expanding volume pools as food-contact approvals broaden under EFSA and FDA frameworks, though clear PET retains the dominant share of virgin resin offtake for optical-grade bottle production. Bio-based PET, utilizing monoethylene glycol from sugarcane ethanol, occupies a premium niche where brand sustainability commitments justify cost differentials against conventional grades.
The EPA regulates PET manufacturing emissions under Clean Air Act provisions, while REACH and the EU Single-Use Plastics Directive constrain virgin polymer deployment in European packaging markets. China's MEE enforces wastewater and air quality standards that elevate compliance costs for PTA-PET integrated producers. India's BIS certification mandates for food-contact plastics create market access thresholds that favor scaled manufacturers with testing infrastructure. Stakeholders must weigh recycling technology commitments against virgin capacity timing as regulatory trajectories diverge across major demand centers.
Market Dynamics
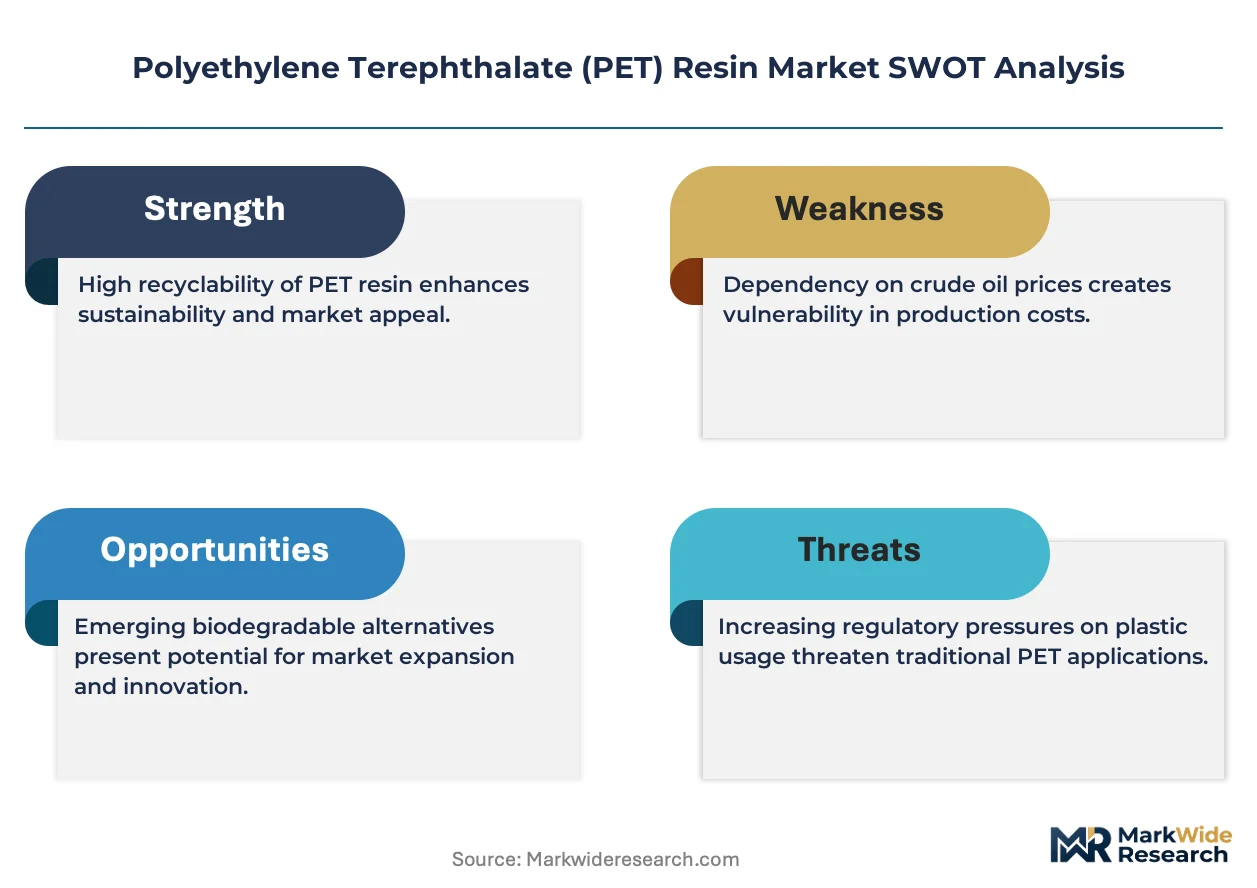
The EU Single-Use Plastics Directive and China's dual carbon goals are forcing virgin PET capacity toward bottle-to-bottle recycling retrofits, tightening feedstock availability for conventional resin grades.
Growth Catalysts
- Beverage packaging volume:Bottled water and carbonated soft drink consumption sustains resin offtake across emerging and developed economies alike.
- REACH-compliant recycling pathways:EFSA food-contact approvals for rPET expand addressable supply pools for brand-owner sustainability commitments.
- Textile fiber substitution:Polyester filament displaces cotton and nylon in apparel and industrial yarn applications, anchoring non-packaging demand.
Market Restraints
- PTA-MEG input volatility:Purified terephthalic acid and monoethylene glycol prices track naphtha and paraxylene feedstock swings, compressing integrated producer margins.
- Asian supply concentration:China, India, and Thailand host over sixty percent of global PET resin capacity, creating geographic risk for distant buyers.
- Mechanical recycling limits:Thermal degradation during reprocessing restricts rPET to lower-intrinsic-viscosity applications, capping food-grade circularity.
Strategic Opportunities
- India domestic demand:Per-capita PET consumption remains below regional benchmarks, offering runway for local capacity absorption as beverage and textile sectors expand.
- Chemical recycling scale-up:Depolymerization technologies promise food-grade monomer recovery from colored and contaminated feedstocks currently rejected by mechanical routes.
- EPR mandate alignment:Extended producer responsibility frameworks in the EU and India create contracted offtake structures for integrated recyclers.
Industry Challenges
- Food-contact certification timelines:FDA and EFSA novel food approvals for advanced recycling outputs require multi-year toxicology studies, delaying revenue recognition.
- Legacy equipment retrofit costs:Converting solid-state polymerization lines to handle high-rPET blends demands capital outlays that strain mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyethylene Terephthalate (PET) Resin Market |
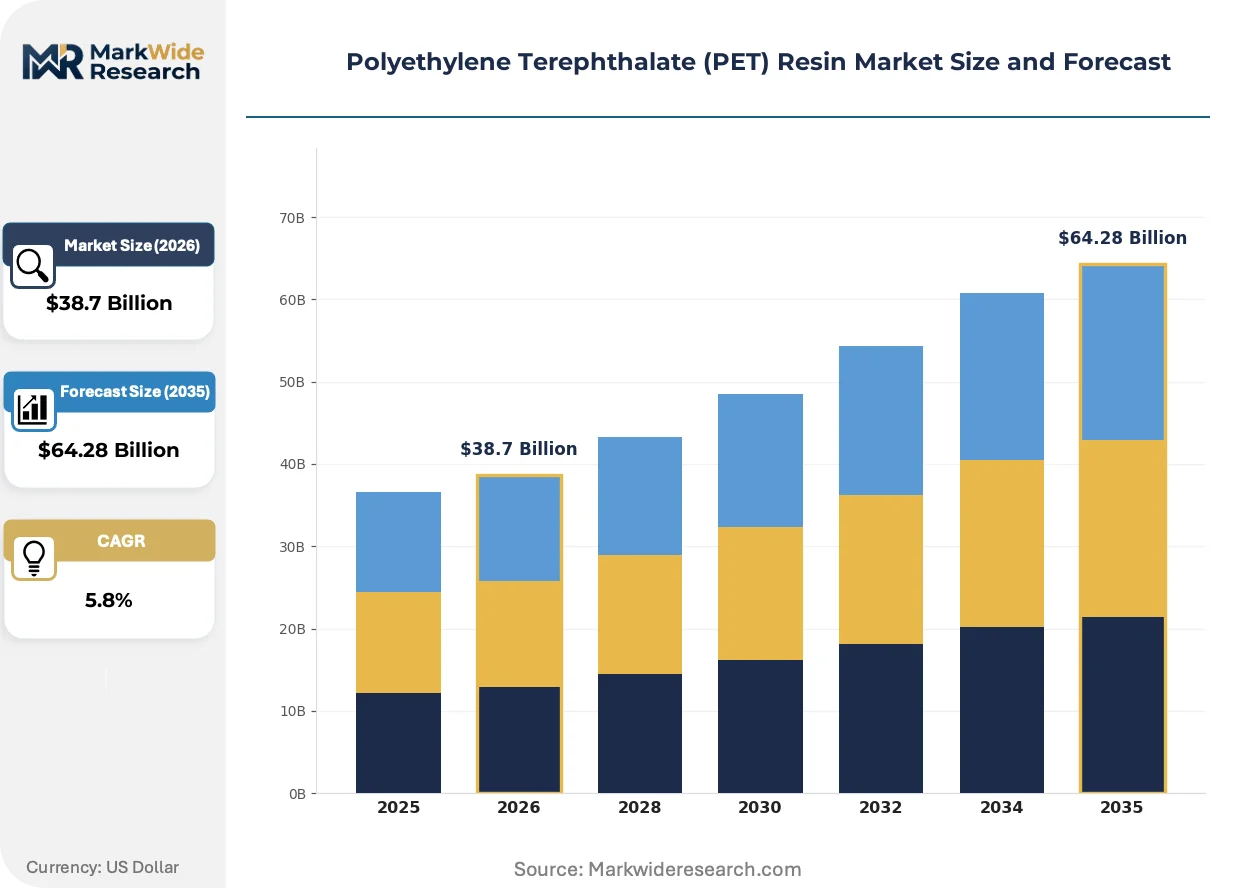
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clear PET, Colored PET, Recycled PET, Bio-based PET Application: Bottles, Films, Fibers, Containers End User: Food & Beverage, Automotive, Consumer Goods, Electronics Grade: Food Grade, Industrial Grade, Medical Grade, Engineering Grade |
| Companies Covered | Indorama Ventures Public Company Limited, Alpek, Jiangsu Sanfangxiang Group, SABIC, Sinopec, Far Eastern New Century Corporation, Nan Ya Plastics Corporation, DAK Americas, Yisheng Petrochemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyethylene Terephthalate (PET) Resin Market Evolving Landscape
Advanced recycling infrastructure and bio-based feedstock integration are reconfiguring how PET resin producers secure brand-owner contracts and regulatory compliance.
Enzymatic depolymerization is modularizing at pilot scale, breaking PET into terephthalic acid and ethylene glycol under mild temperature conditions. Beverage brand owners with net-zero commitments are offtaking volumes from these facilities ahead of cost parity with mechanical recycling. This technology is modularizing distributed recycling nodes that bypass centralized collection infrastructure.
REACH substance restrictions and the EU Packaging and Packaging Waste Regulation are tightening virgin polymer quotas for single-use applications. Producers with integrated mechanical and chemical recycling assets gain preferential access to regulated European markets. Food-grade rPET now commands premium positioning over virgin resin in German and French bottling contracts.
Buyers are consolidating procurement around recyclability certification tiers rather than commodity resin grades. Large beverage bottlers now specify third-party-audited recycled content percentages in master supply agreements, displacing spot-market purchasing. This pattern concentrates most visibly in North American and Western European contract structures where EPR compliance costs are internalized.
Polyethylene Terephthalate (PET) Resin Market Segmentation
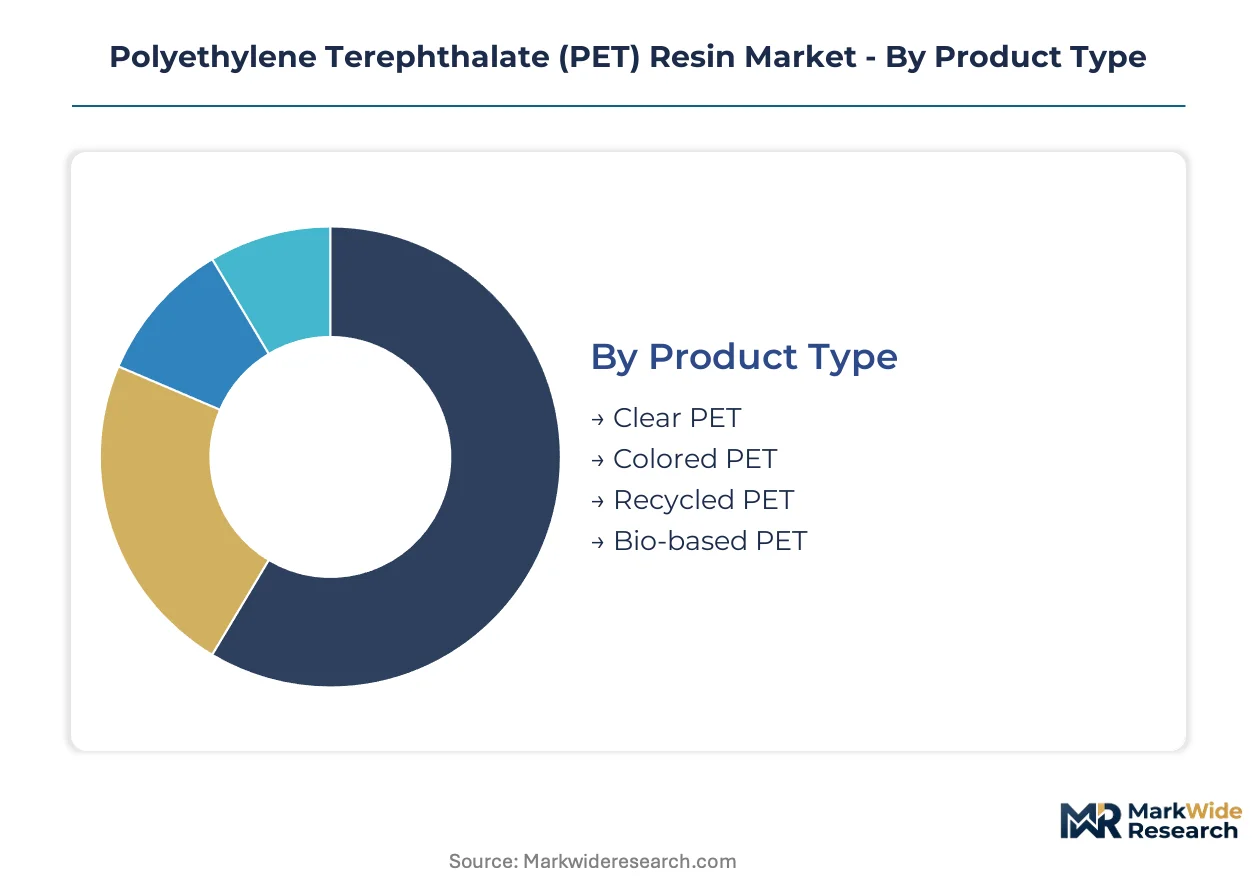
PET resin segmentation reflects divergent capital requirements across purification technologies and end-use specifications. Producers allocate capacity based on margin profiles tied to food-contact certification tiers and regional regulatory stringency.
Product Type:
Clear PET demands the heaviest upfront investment in optical-grade polymerization lines and contamination control systems. Bio-based PET requires dedicated fermentation-capable monoethylene glycol supply chains.
- Clear PET:Virgin resin with optical clarity specifications below 5 hazen units serves premium beverage bottling where brand visibility drives procurement. Demand concentrates in Germany and France under EU Packaging and Packaging Waste Regulation quotas for recycled content integration.
- Recycled PET:Post-consumer flake and pellet grades achieve food-contact status through EFSA and FDA novel food approvals, expanding supply pools for bottler sustainability contracts. India and Thailand are scaling mechanical recycling infrastructure to serve domestic beverage growth.
- Colored PET:Pigmented grades for non-beverage packaging applications where optical clarity is non-essential.
- Bio-based PET:Sugar-derived monoethylene glycol blends command premium positioning where brand net-zero commitments justify cost differentials against conventional feedstocks.
Clear PET absorbs the bulk of installed capacity; Recycled PET is expanding most quickly.
Application:
Volume concentration follows packaging demand patterns, with fiber applications anchoring non-packaging offtake through textile sector procurement.
- Bottles:Carbonated soft drink and bottled water packaging sustain the largest resin volume pools, with lightweighting trends reducing unit material intensity. China's beverage sector and India's emerging per-capita consumption drive capacity placement decisions.
- Films:Biaxially oriented PET films for flexible food packaging and industrial laminations require specialized extrusion lines with thickness control systems. Japanese electronics and automotive component demand shapes technical specifications.
- Fibers:Polyester filament and staple grades displace cotton in apparel and industrial yarn applications, with Jiangsu province hosting concentrated spinning capacity.
- Containers:Non-beverage rigid packaging for personal care and household products, where color and barrier specifications vary by end-use.
Bottles command the dominant share of resin throughput; Films are climbing the fastest on electronics and premium food packaging demand.
End User:
Customer procurement patterns diverge between spot-market commodity purchasing and long-term contracted offtake tied to EPR compliance frameworks.
- Food & Beverage:Brand-owner sustainability commitments drive rPET specification in master supply agreements, with third-party certification tiers displacing commodity grade purchasing. German and French bottlers lead recycled content integration under EU directive timelines.
- Automotive:Underhood components and interior trim applications demand heat-stabilized grades with dimensional stability specifications. US and German OEMs specify recycled content percentages in supplier scorecards.
- Consumer Goods:Personal care and household product packaging with moderate barrier requirements and broader color tolerance.
- Electronics:Film substrates and connector housings requiring electrical insulation properties and flame-retardant formulations.
Food & Beverage anchors volume commitments; Automotive is gaining share fastest on lightweighting and circular material mandates.
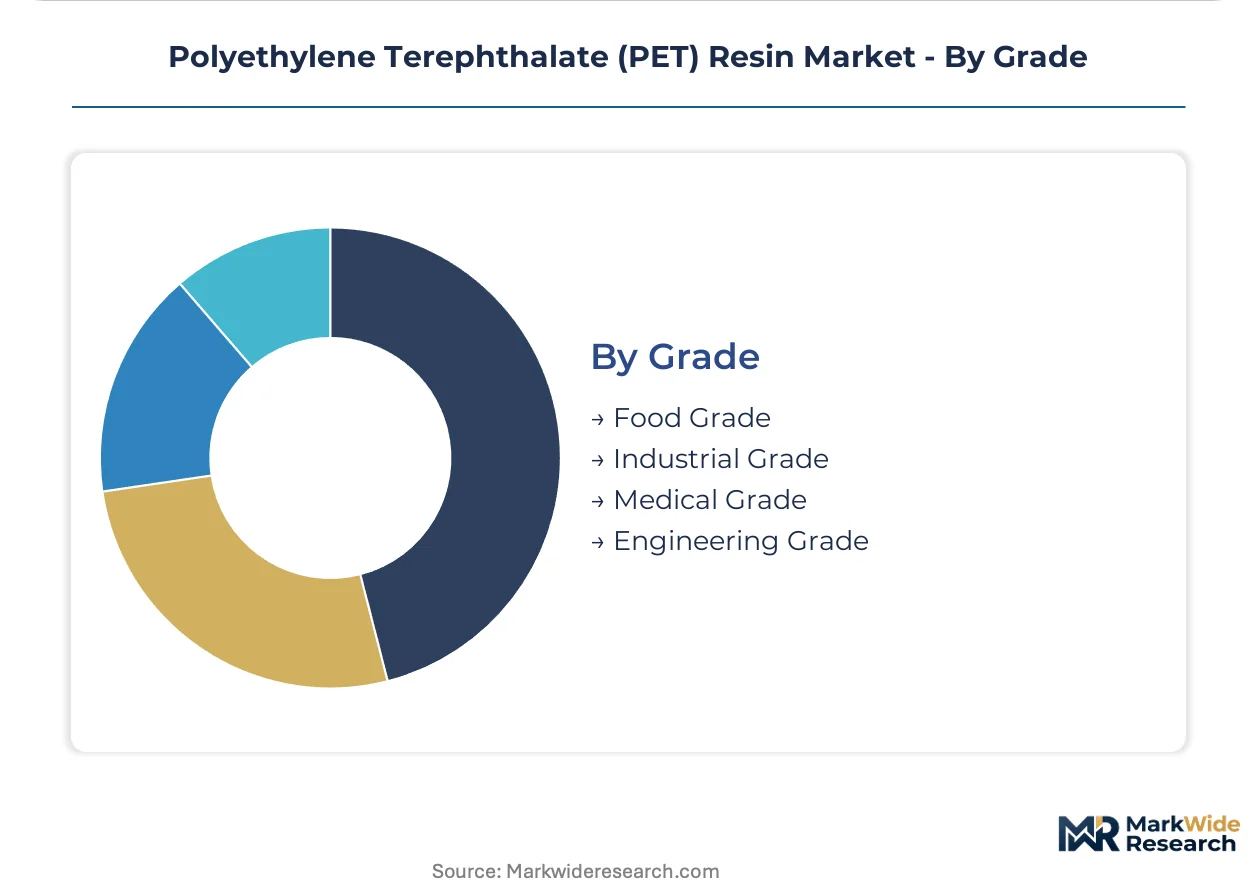
Grade:
Certification intensity and testing infrastructure requirements create tiered market access thresholds favoring scaled producers.
- Food Grade:Stringent migration limits and BIS certification in India, FDA food-contact notification in the US, and EFSA positive opinions in Europe create multi-jurisdictional compliance burdens. Indorama Ventures and Alpek maintain dedicated testing laboratories to accelerate approval timelines.
- Industrial Grade:Lower intrinsic viscosity specifications for non-food applications with reduced regulatory scrutiny and faster qualification cycles.
- Medical Grade:USP Class VI and ISO 10993 biocompatibility testing for device and pharmaceutical packaging applications with extended validation protocols.
- Engineering Grade:Glass-filled and modified formulations for structural applications requiring elevated mechanical properties.
Food Grade captures the majority of value-added resin production; Engineering Grade is expanding most quickly on automotive and electronics substitution trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotterdam's port complex anchors European PET resin logistics, handling PTA feedstock imports and rPET flake exports for German and French bottlers. The city's integrated chemical cluster supports backward integration into purified terephthalic acid production.
United States
Gulf Coast petrochemical corridors supply monoethylene glycol for domestic bottle-grade resin production. EPA Clean Air Act provisions regulate emissions from PTA-PET integrated facilities. Corpus Christi hosts concentrated polymerization capacity serving Coca-Cola and PepsiCo bottling networks.
China
Yangtze River Delta polyester filament demand from Jiangsu textile mills absorbs substantial resin volumes. MEE wastewater standards elevate compliance costs for PTA producers in Ningbo and Shanghai. Zhejiang province hosts integrated petrochemical zones combining paraxylene refining with PET polymerization.
India
Per-capita bottled water consumption in Maharashtra and Gujarat drives domestic resin absorption. BIS food-contact certification mandates create market access thresholds favoring scaled manufacturers. Dahej and Hazira industrial corridors host Reliance and Indorama Ventures expansions targeting beverage and textile fiber markets.
Germany
EU Packaging and Packaging Waste Regulation quotas accelerate rPET integration in carbonated soft drink bottling. REACH substance restrictions constrain virgin polymer deployment in single-use applications. Hamburg's port infrastructure handles post-consumer flake imports for food-grade recycling operations.
Thailand
Indorama Ventures' integrated bottle-to-bottle recycling complex in Rayong Province serves ASEAN beverage export markets. The country's Board of Investment incentives attract chemical recycling technology pilots. Map Ta Phut's petrochemical zone combines ethylene production with downstream PET resin manufacturing.
Polyethylene Terephthalate (PET) Resin Market Competitive Landscape
Capital-heavy producers compete with asset-light recyclers for brand-owner contracts. The market structures around three tiers: integrated petrochemical giants with captive PTA supply, specialized recyclers with EFSA/FDA food-contact approvals, and regional converters serving textile fiber markets. Strategic moves concentrate on chemical recycling scale-up and mechanical recycling retrofit commitments.
Within the integrated producer tier, Indorama Ventures and Alpek occupy positions defined by backward integration depth. Jiangsu Sanfangxiang Group exemplifies the Asia-centric filament-grade specialist archetype. These three entities represent divergent geographic and vertical positioning strategies across virgin resin, recycled flake, and specialty fiber segments.
| Leading Market Players |
|---|
| Indorama Ventures Public Company Limited |
| Alpek |
| Jiangsu Sanfangxiang Group |
| SABIC |
| Sinopec |
| Far Eastern New Century Corporation |
| Nan Ya Plastics Corporation |
| DAK Americas |
| Yisheng Petrochemical |
| Others |
Value Network & Pricing Analysis
Polymerization specialist labor pools in the Yangtze River Delta and Gulf Coast petrochemical corridors create tiered labor-cost differentials that widen pricing spreads between food-grade certification tiers and industrial-grade commodity resin. These workforce concentrations anchor margin structures for integrated producers competing on EFSA and FDA food-contact approval timelines.
Pricing Analysis
Food-contact certification value anchors PET resin pricing tiers, with EFSA-positive and FDA-notified grades commanding substantial premiums over industrial specifications. Price differentiation rests on contamination control infrastructure and migration testing capabilities that scaled producers maintain in-house. Pricing pressure intensifies in virgin clear PET as mechanical recycling capacity expands and rPET achieves cost parity in German and French bottling contracts. Mid-scale converters exhibit highest price sensitivity due to legacy solid-state polymerization equipment that cannot accommodate high-rPET blend ratios without capital retrofit.
Supply Chain Analysis
Specialized chemical engineering talent availability in China, India, and Thailand concentrates integrated PTA-PET manufacturing capacity and shapes regional cost competitiveness. Feedstock supply draws from purified terephthalic acid and monoethylene glycol production tethered to naphtha and paraxylene refining economics. Single-source vulnerability runs through concentrated paraxylene supply from regional aromatics complexes. Distribution runs through Rotterdam, Corpus Christi, and Singapore port hubs serving brand-owner bottling networks with contracted offtake structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PET resin commercialization sits in a technology-transition phase as enzymatic depolymerization and chemical recycling displace mechanical reprocessing limits for food-grade circularity.
For Market Incumbents: Deploy integrated recycling asset footprints to secure brand-owner sustainability contracts ahead of EPR mandate deadlines. Chemical recycling capacity additions in European port zones capture premium rPET positioning under EU Packaging and Packaging Waste Regulation quotas. Backward integration into PTA production defends margin compression from paraxylene feedstock volatility. For New Entrants and Emerging Players: Capture toll-processing service contracts from mid-scale beverage bottlers lacking in-house recycling infrastructure. India's domestic demand expansion offers white-space absorption for filament-grade specialists with BIS certification capabilities. Partner with enzymatic technology licensors to bypass mechanical recycling's intrinsic viscosity degradation limits. For Investors and Strategic Acquirers: Re-rating potential sits with chemical recycling technology developers given FDA and EFSA novel food approval momentum for depolymerization outputs. Five-to-ten-year viability favors assets with dual mechanical-chemical processing flexibility across multiple feedstock contamination tiers. Monitor EFSA positive opinion issuance velocity as inflection signal for food-grade rPET premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PTA Production | Captive purified terephthalic acid supply insulates Alpek and Indorama Ventures from paraxylene price swings. |
| Chemical Recycling Scale-Up | Enzymatic depolymerization pilots in Thailand and Europe unlock food-grade monomer recovery from colored feedstocks. |
| Food-Contact Certification Investment | Dedicated EFSA and FDA testing laboratories accelerate approval timelines for brand-owner sustainability contracts. |
| India Capacity Expansion | Reliance and Indorama Ventures expansions in Dahej and Hazira target domestic beverage and textile fiber absorption. |
| Long-Term Supply Agreement | Coca-Cola and PepsiCo bottling networks in Corpus Christi anchor contracted offtake for Gulf Coast polymerization assets. |
Research Methodology
Trade databases, customs records, and SEC 10-K filings formed the secondary backbone, supplemented by EFSA novel food approval registers and FDA food-contact notification databases. Primary interviews with PET plant managers, beverage procurement leads, and textile spinning technical directors validated capacity utilization assumptions and recycling technology adoption timelines. Bottom-up and top-down triangulation reconciled polymerization line counts with end-use demand segmentation across packaging and fiber applications.
Bottom-up modeling built from named production facility capacities and operating rates, while top-down verification cross-checked against regional beverage consumption and textile fiber substitution trends. Segmentation dimensions spanned product type, application, end user, and grade tier with regulatory certification intensity as an additional industry-specific layer. CAGRs were derived from regression analysis of historical resin pricing and volume correlations with feedstock cost indices and sustainability mandate implementation schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA and FDA approval timelines for advanced recycling outputs and EU Packaging and Packaging Waste Regulation quota enforcement stringency. Assumptions regarding chemical recycling cost parity and mechanical recycling feedstock availability shape projection validity. Material deviation in regulatory approval velocity or EPR mandate acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyglycerol Market
Polymers & Resins
Metallocene Polyethylene Market
Polymers & Resins
US Polymethyl Methacrylate Market
Polymers & Resins
Semi-Rigid Spray Polyurethane Foam Market
Polymers & Resins
Methyl Silicone Resins Market
Polymers & Resins
Global Polymer Market
Polymers & Resins
GCC Polyethylene Terephthalate (PET) Market
Polymers & Resins
Cross-Linked Polyethylene (XLPE) Market
Polymers & Resins
Polytetramethylene Ether Glycol (PTMEG) Market
Polymers & Resins
Global Injection Molding Plastic Market
Polymers & Resins
Phthalonitrile Resin Market
Polymers & Resins
Indonesia Polypropylene Market
Polymers & Resins
Nylon 66 Market
Polymers & Resins
Fluorinated Polyimide Market
Polymers & Resins
Glutathione Resin Market
Polymers & Resins
Polystyrene Market