
 United States Pharmaceutical Logistics Market | 2026-2036
United States Pharmaceutical Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
United States Pharmaceutical Logistics Market Analytics
Specialty pharmacy buyers is reorganizing fulfillment requirements around cell and gene therapies requiring cryogenic transport. FedEx Corporation leverages its SenseAware monitoring platform to compete on visibility for high-value shipments. United Parcel Service Inc. anchors temperature-controlled capacity through its UPS Healthcare division across the Southeast and Midwest distribution corridors.
United States Pharmaceutical Logistics encompasses the specialized movement, storage, and handling of pharmaceutical products under validated temperature conditions ranging from controlled room temperature to cryogenic states below minus 150 degrees Celsius, ensuring product integrity from manufacturer to patient. Cold chain logistics commands premium pricing due to qualification complexity and regulatory burden, while biologics within product type represents the fastest-expanding category driven by monoclonal antibody and mRNA therapeutic volumes. Last-mile delivery to hospitals and retail pharmacies faces margin compression from labor-intensive handling requirements and same-day service expectations.
FDA enforces Current Good Manufacturing Practice and Good Distribution Practice standards that mandate continuous temperature monitoring and documentation across pharmaceutical supply chains. The Drug Supply Chain Security Act and HIPAA privacy requirements shape serialization protocols and data handling practices for logistics providers. Stakeholders must monitor evolving guidance from the Department of Health and Human Services on domestic API manufacturing reshoring and its freight volume implications.
Market Dynamics
FDA serialization mandates under the Drug Supply Chain Security Act are forcing wholesale infrastructure replacement across domestic pharmaceutical distribution networks. Temperature-sensitive biologics now command dedicated cold chain capacity, reshaping facility investment priorities and lane configurations nationwide.
Growth Catalysts
- Biologics Volume Surge:Monoclonal antibody and mRNA therapeutic production is expanding validated cold storage requirements across Midwest and Southeast distribution hubs.
- Drug Supply Chain Security Act:Federal track-and-trace mandates are accelerating serialization hardware deployment and data infrastructure investment through 2035 compliance deadlines.
- Reshoring Policy Momentum:Department of Health and Human Services incentives for domestic API manufacturing are generating inbound freight volume to New Jersey and Pennsylvania pharmaceutical clusters.
Market Restraints
- Refrigerant Input Volatility:Liquid nitrogen and specialized coolant supply constraints are compressing margins for cryogenic transport operators serving cell therapy networks.
- Facility Concentration Risk:Over half of validated cold storage capacity sits within hurricane-exposed Gulf Coast and Southeast Atlantic zones, elevating business continuity exposure.
- HIPAA Data Friction:Privacy requirements create compliance overhead for real-time shipment visibility platforms integrating with hospital pharmacy systems.
Strategic Opportunities
- Home Infusion Channel Expansion:Direct-to-patient delivery models for specialty biologics are opening last-mile service contracts outside traditional hospital-centric networks.
- AI-Enabled Predictive Routing:Machine learning convergence with IoT temperature monitoring is enabling dynamic lane optimization for time-critical gene therapy shipments.
- IRA Domestic Manufacturing Credits:Inflation Reduction Act production incentives are attracting greenfield pharmaceutical logistics investment to Texas and North Carolina.
Industry Challenges
- Cryogenic Technician Scarcity:Qualified handlers for minus 150 degrees Celsius logistics operations remain concentrated in legacy biotech hubs, constraining network expansion.
- Validation Timeline Compression:FDA qualification protocols for new temperature-controlled lanes extend 18-24 months, delaying revenue realization on facility investments.
- Legacy WMS Integration:Enterprise warehouse management systems at established distributors require costly retrofitting to support serialized unit-level tracking mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Pharmaceutical Logistics Market |
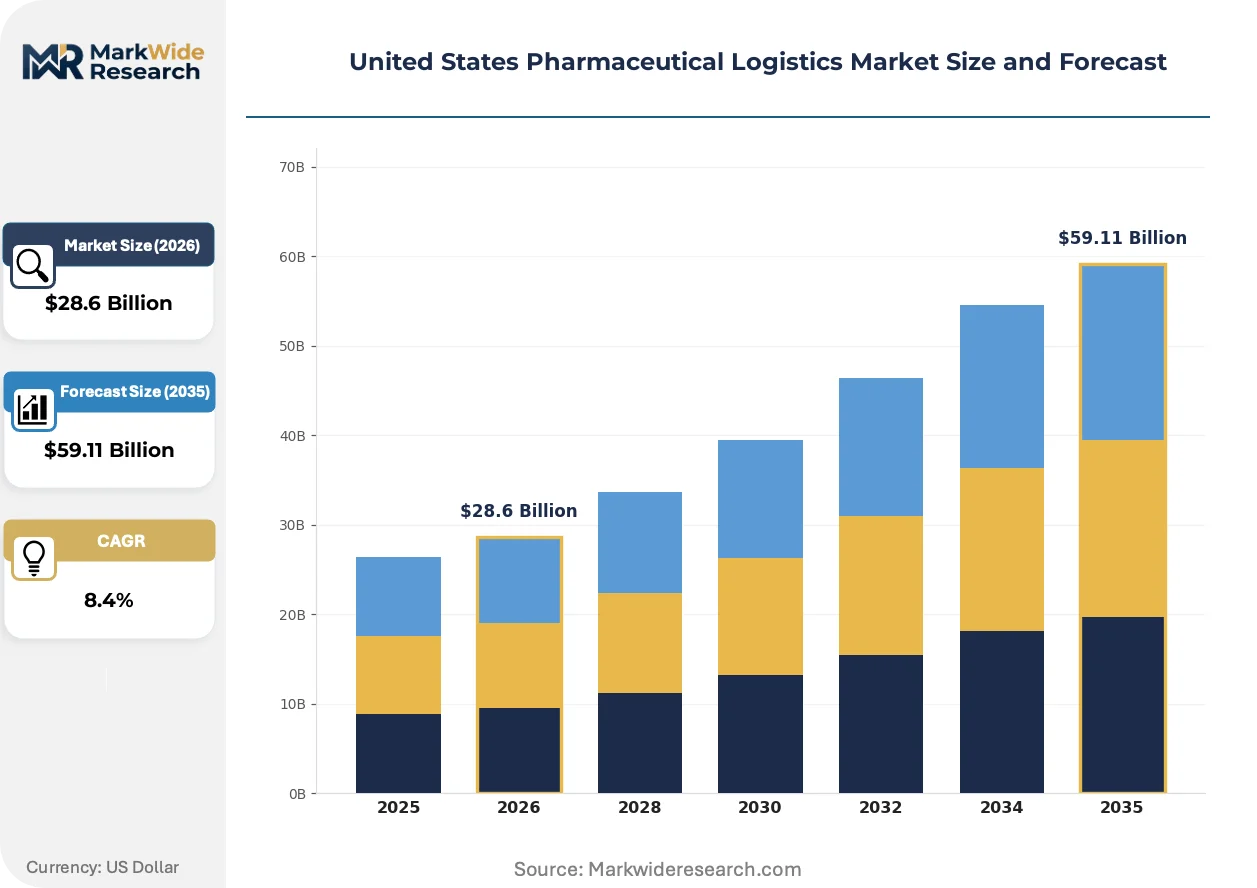
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $59.11 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Cold Chain Logistics Product Type: Prescription Drugs, Over-The-Counter Medications, Biologics, Vaccines Delivery Mode: Air Freight, Ground Freight, Last-Mile Delivery, Ocean Freight End User: Pharmaceutical Companies, Distributors, Retail Pharmacies, Hospitals |
| Companies Covered | United Parcel Service Inc., FedEx Corporation, Lineage Logistics Holdings LLC, Americold Realty Trust Inc., DHL Supply Chain & Global Forwarding, C.H. Robinson Worldwide Inc., Expeditors International of Washington Inc., XPO Inc., SEKO Logistics Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Pharmaceutical Logistics Market Evolving Landscape
Real-time visibility platforms are displacing passive temperature loggers as the default monitoring standard for high-value pharmaceutical shipments. Logistics providers now compete on data granularity rather than asset ownership alone.
Distributed ledger technology is fragmenting custody verification across pharmaceutical supply chains. Blockchain-enabled provenance tracking allows manufacturers to audit handoff integrity without centralized intermediary control. Specialty pharmacy buyers are piloting these systems for gene therapy shipments where chain-of-identity documentation carries liability implications. The technology is fragmenting traditional quality assurance roles between logistics providers and pharmaceutical sponsors.
FDA guidance on advanced manufacturing technologies is tightening validation requirements for continuous processing equipment shipped between contract development sites. The agency's evolving interpretation of Current Good Manufacturing Practice standards now extends to transport conditions for in-process biological materials. Biologics manufacturers with distributed production networks face heightened documentation burdens for inter-facility transfers.
Hospital pharmacy consolidation is compressing supplier relationship cycles across integrated delivery networks. Large health systems are unbundling logistics services from product procurement, awarding separate contracts to specialized cold chain operators. This purchasing behavior shift is most visible in the Northeast corridor where IDN concentration enables volume-based service tiering.
United States Pharmaceutical Logistics Market Segmentation
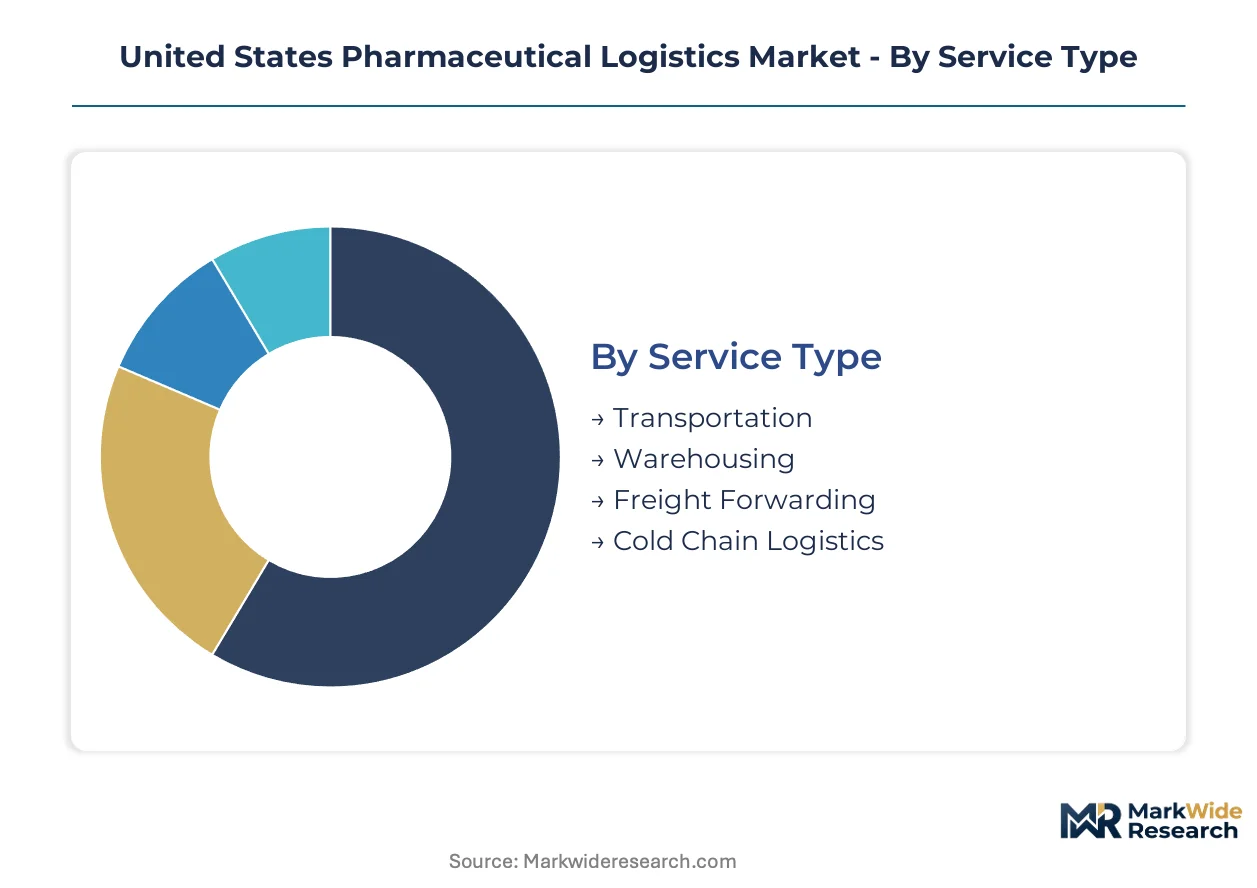
Segmentation in United States pharmaceutical logistics reveals how service specialization, product sensitivity, and delivery urgency create distinct operational and investment profiles across the value chain. Each dimension carries unique regulatory burdens, margin structures, and capacity constraints that shape provider competitiveness.
Service Type:
Cold chain logistics and transportation segments concentrate on domestic biologics distribution, while freight forwarding handles more export-oriented API movements.
- Cold Chain Logistics:Validated temperature-controlled infrastructure spans controlled room temperature through cryogenic minus 150 degrees Celsius states. Northeast corridor facilities in New Jersey and Pennsylvania anchor domestic biologics storage demand driven by FDA Current Good Manufacturing Practice compliance timelines.
- Transportation:Dedicated pharmaceutical fleets with real-time temperature monitoring and GPS tracking ensure chain-of-custody documentation across interstate lanes. Southeast and Midwest distribution corridors show strongest capacity expansion as monoclonal antibody production volumes climb.
- Warehousing:GMP-qualified facilities with serialized inventory management support Drug Supply Chain Security Act track-and-trace mandates.
- Freight Forwarding:Cross-border coordination for active pharmaceutical ingredients faces customs documentation complexity and temperature excursion risk at ports of entry.
Cold chain logistics holds the largest share; momentum sits with transportation as gene therapy volumes expand.
Product Type:
Margin structures stratify sharply across this category, with biologics and vaccines commanding premium handling fees versus commoditized small-molecule flows.
- Biologics:Monoclonal antibodies, cell therapies, and gene therapies require continuous cold chain integrity with specialized packaging and monitoring. Midwest manufacturing hubs in Indiana and Illinois are driving fastest capacity absorption for mRNA therapeutic distribution networks.
- Vaccines:Ultra-cold storage requirements for mRNA platforms have permanently expanded domestic cryogenic infrastructure. Federal stockpiling programs and seasonal immunization campaigns create demand spikes that stress regional distribution capacity.
- Prescription Drugs:Oral solid dosage forms move through less stringent controlled room temperature channels with higher volume density per shipment.
- Over-The-Counter Medications:Consumer-packaged health products utilize standard parcel networks with minimal regulatory overlay compared to prescription channels.
Prescription drugs maintains volume dominance; biologics shows the steepest expansion trajectory as therapeutic pipelines mature.
Delivery Mode:
Speed requirements and shipment value density determine modal selection, with air freight reserved for time-critical therapies and ocean freight for stable bulk APIs.
- Air Freight:Temperature-controlled cargo compartments and expedited customs clearance support high-value biologics with short shelf lives. Memphis and Louisville hub airports anchor domestic pharmaceutical air cargo networks.
- Last-Mile Delivery:Direct-to-patient and direct-to-pharmacy models are expanding fastest as specialty pharmacy networks bypass traditional wholesale distribution. Same-day service expectations in major metropolitan areas compress route economics.
- Ground Freight:Refrigerated trucking dominates interstate lane volume for regional distribution center replenishment.
- Ocean Freight:Containerized temperature-controlled shipping serves inbound API movements from Asian manufacturing sources.
Ground freight carries the highest shipment count; last-mile delivery is gaining share fastest as home infusion models proliferate.
End User:
Procurement sophistication varies dramatically, with hospital systems unbundling logistics from drug purchasing while retail pharmacies accept bundled distribution services.
- Hospitals:Integrated delivery networks in the Northeast corridor are awarding separate cold chain logistics contracts distinct from pharmaceutical procurement. IDN consolidation enables volume-based service tiering and performance benchmarking across member facilities.
- Pharmaceutical Companies:Sponsor organizations demand end-to-end visibility platforms with serialized unit-level tracking for regulatory submission support. In-house logistics teams at large manufacturers are outsourcing specialized cold chain lanes to qualified third-party providers.
- Distributors:Wholesale operations face infrastructure replacement pressure from FDA serialization mandates with compressed compliance timelines.
- Retail Pharmacies:Chain and independent pharmacies rely on consolidated delivery schedules with limited flexibility for urgent specialty medication requests.
Hospitals represent the most demanding customer segment; pharmaceutical companies are driving fastest platform investment as pipeline complexity increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of New York and New Jersey anchors North American pharmaceutical import volume, handling temperature-controlled containers from European API manufacturers and Asian biologics suppliers through dedicated cold chain terminals.
Northeast Corridor
Specialty pharmacy networks and integrated delivery systems drive concentrated demand for validated cold storage in New Jersey and Pennsylvania. FDA Current Good Manufacturing Practice enforcement timelines compress facility qualification schedules across pharmaceutical distribution clusters. Philadelphia and northern New Jersey host the densest concentration of GMP-qualified warehousing serving monoclonal antibody distribution.
Southeast Atlantic
Gene therapy manufacturing expansion in North Carolina and Georgia absorbs cryogenic logistics capacity for cell therapy clinical trials. Hurricane exposure elevates business continuity planning for Gulf Coast and Florida cold storage operators. Miami and Atlanta distribution hubs specialize in temperature-controlled freight forwarding for Latin American pharmaceutical exports.
Midwest Manufacturing Belt
mRNA therapeutic production facilities in Indiana and Illinois generate interstate lane demand for validated refrigerated trucking. Department of Health and Human Services reshoring incentives attract API manufacturing investment to Ohio and Michigan pharmaceutical zones. Chicago anchors regional distribution networks with multi-temperature consolidation capabilities.
Pacific Coast
Biologics manufacturing in South San Francisco and San Diego drives specialized air freight demand through Los Angeles International Airport. California environmental regulations accelerate electric refrigerated fleet adoption among last-mile delivery operators. Seattle and Portland distribution centers serve Pacific Northwest home infusion therapy networks.
Southwest
Texas medical center complexes in Houston and Dallas generate high-value pharmaceutical shipments requiring real-time temperature monitoring. Inflation Reduction Act domestic manufacturing credits attract greenfield pharmaceutical logistics investment to Austin and San Antonio. El Paso and Laredo border crossings handle temperature-controlled cross-border API movements with Mexican maquiladora operations.
United States Pharmaceutical Logistics Market Competitive Landscape
Listed leaders compete with private specialists across temperature-controlled infrastructure ownership, creating a tiered structure where asset-heavy operators command premium pricing for validated cold chain services. Consolidation pressure intensifies as FDA serialization mandates force wholesale infrastructure replacement with compressed compliance timelines. Three archetypes dominate: integrated parcel carriers with healthcare divisions, dedicated cold storage real estate investment trusts, and freight forwarders with pharmaceutical certification. Dominant competitive moves include strategic partnerships with biologics manufacturers and geographic expansion into gene therapy production clusters.
Within the integrated carrier tier, United Parcel Service Inc. and FedEx Corporation exemplify scale-driven operators leveraging established air cargo networks for time-critical pharmaceutical movements. Among specialized cold storage providers, Lineage Logistics Holdings LLC and Americold Realty Trust Inc. anchor temperature-controlled warehousing capacity expansion. These four entities represent contrasting strategic positions: parcel carriers compete on visibility platform investment while REITs compete on facility qualification speed and geographic density near biopharmaceutical manufacturing zones.
| Leading Market Players |
|---|
| United Parcel Service Inc. |
| FedEx Corporation |
| Lineage Logistics Holdings LLC |
| Americold Realty Trust Inc. |
| DHL Supply Chain & Global Forwarding |
| C.H. Robinson Worldwide Inc. |
| Expeditors International of Washington Inc. |
| XPO Inc. |
| SEKO Logistics Inc. |
| Others |
Value Network & Pricing Analysis
Cryogenic capacity utilization above 85 percent across New Jersey and Pennsylvania distribution clusters creates pricing power for validated cold storage operators while compressing margins for transport-only providers lacking facility assets. This scale concentration elevates price floors for gene therapy logistics as biologics manufacturers absorb premium rates to secure qualified capacity ahead of FDA compliance deadlines.
Pricing Analysis
Volume-discount tiering structures separate enterprise pharmaceutical sponsors from mid-size biotech firms and emerging cell therapy developers across contract minimums. Price differentiation hinges on FDA Current Good Manufacturing Practice certification tier and real-time visibility platform integration depth. Pricing pressure stems from liquid nitrogen supply constraints elevating cryogenic transport costs. Hospital integrated delivery networks exhibit highest price sensitivity due to unbundled procurement models, while gene therapy sponsors show lowest sensitivity given product value density and patient access imperatives.
Supply Chain Analysis
The United States anchors domestic biologics distribution infrastructure while India and China supply active pharmaceutical ingredients through temperature-controlled ocean freight corridors. Specialized refrigerants, serialized packaging components, and qualified handling labor constitute critical input dependencies. Single-source vulnerability concentrates in Gulf Coast cryogenic storage exposed to hurricane disruption. Distribution runs through wholesale distributors facing Drug Supply Chain Security Act infrastructure replacement mandates, with direct-to-patient channels gaining share in specialty pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States pharmaceutical logistics market sits in early-cycle recovery as biologics pipeline maturation and reshoring policy momentum rebuild freight volumes from pandemic-era disruptions.
For Market Incumbents: Shield core cold chain margins by accelerating backward integration into cryogenic refrigerant supply through long-term offtake agreements with industrial gas producers. Consolidate facility footprints in hurricane-exposed Southeast zones through redundant Midwest capacity additions to mitigate business continuity risk from climate-driven disruption.
For New Entrants and Emerging Players: Home infusion therapy logistics represents the most penetrable service layer where incumbent wholesale distributors lack direct-to-patient operational expertise. Target Texas and North Carolina gene therapy manufacturing clusters with specialized cryogenic courier services bypassing traditional distribution networks. Pursue FDA qualification partnerships with emerging cell therapy sponsors seeking dedicated lane validation.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized cold storage real estate investment trusts with GMP-qualified facility pipelines over asset-light freight forwarders lacking temperature-controlled infrastructure ownership. Five-to-ten year viability hinges on serialization compliance execution and biologics volume trajectories. Monitor Inflation Reduction Act domestic manufacturing credit utilization rates as inflection indicator for inbound API freight volume recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Capacity Expansion | Qualification speed determines capture of gene therapy clinical trial logistics contracts from FDA-registered biologics sponsors. |
| Serialization Infrastructure Deployment | Drug Supply Chain Security Act compliance deadlines force wholesale distributor warehouse management system replacement investments. |
| AI-Enabled Predictive Routing | Machine learning integration with IoT temperature monitoring reduces excursion risk for time-critical monoclonal antibody shipments. |
| Home Infusion Channel Development | Direct-to-patient delivery models bypass traditional hospital-centric networks for specialty biologics with complex administration requirements. |
| Refrigerant Supply Backward Integration | Long-term liquid nitrogen offtake agreements secure input cost stability for cryogenic transport operators serving cell therapy networks. |
Research Methodology
Desk research of FDA guidance documents, Drug Supply Chain Security Act implementation records, and pharmaceutical trade flow databases preceded structured interviews with cold chain logistics directors, biologics supply chain executives, hospital pharmacy procurement managers, and regulatory affairs specialists. Primary fieldwork combined with secondary validation through SEC filings of publicly traded logistics providers and pharmaceutical distribution company disclosures. Bottom-up capacity modeling triangulated against top-down biologics production volume estimates across the analysis window.
Variance decomposition across service type, product sensitivity tier, delivery mode, and end-user procurement sophistication shaped analytical framework construction throughout the projection horizon. Modeled dimensions encompassed temperature range requirements, serialization compliance status, regional regulatory cluster, and therapeutic category. CAGRs derived from segment-level volume trajectories and pricing elasticity assumptions. Forecast inputs incorporated monoclonal antibody pipeline advancement rates and Inflation Reduction Act manufacturing incentive utilization patterns.
Forecasts assume regulatory continuity in FDA Current Good Manufacturing Practice enforcement and Drug Supply Chain Security Act implementation timelines; material policy shifts affecting domestic API manufacturing incentives or temperature-controlled logistics qualification protocols would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Japan Generic Drug Market
Pharmaceuticals
Iodine Deficiency Drug Market
Pharmaceuticals
Candidiasis Drug Market
Pharmaceuticals
Long-Acting Monoclonal Antibodies Market
Pharmaceuticals
Fibromyalgia Antidepressant Market
Pharmaceuticals
Alkaptonuria Drugs Market
Pharmaceuticals
Metformin Hydrochloride Market
Pharmaceuticals
Global Non-Small Cell Lung Cancer Drugs Market
Pharmaceuticals
Preeclampsia Therapeutics Market
Pharmaceuticals
Indonesia Oral Anti-Diabetic Drug Market
Pharmaceuticals
Oxycodone Market
Pharmaceuticals
Global Human Vaccines Market
Pharmaceuticals
Global Azithromycin Market
Pharmaceuticals
Blood Clotting Accelerant Market
Pharmaceuticals
Global Plasma Derived Therapy Market
Pharmaceuticals
Asia Pacific SGLT2 Inhibitors Market