
 Global Human Vaccines Market | 2026-2036
Global Human Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Human Vaccines Market Foresight
Biologics manufacturing clusters in Belgium and Switzerland are recalibrating fill-finish capacity to accommodate mRNA and viral vector platforms. GSK plc leverages its adjuvant technology leadership to sustain differentiated positions in pandemic preparedness contracts. Pfizer Inc. anchors its portfolio through integrated lipid nanoparticle supply chains. Serum Institute of India Pvt. Ltd. dominates dose-volume economics for UNICEF and Gavi procurement channels.
Human vaccines comprise antigenic preparations derived from live attenuated, inactivated, subunit, conjugate, mRNA, or viral vector platforms, formulated to elicit protective immune responses through controlled antigen presentation. Manufacturing requires cold-chain integrity, sterile fermentation or cell culture propagation, and rigorous potency testing per pharmacopeial standards. The disease target segmentation shows influenza and pneumococcal categories commanding mature, high-volume procurement pools, while mRNA platforms represent the fastest-expanding technology segment driven by platform adaptability. Distribution through hospitals and immunization centers captures the majority of institutional procurement volume, though outreach programs are gaining share in low-access geographies.
The FDA, EMA, and WHO prequalification standards collectively determine market access timelines, with WHO PQ status serving as the gatekeeper for Gavi-eligible country procurement. The EU AI Act and FDA's evolving guidance on computational vaccine design are introducing new compliance layers for in-silico development workflows. Stakeholders must monitor regulatory divergence between accelerated emergency pathways and traditional licensure routes to optimize portfolio registration sequencing.
Market Dynamics
mRNA platform standardization is compressing development timelines while concentrating manufacturing capacity in specialized biologics clusters across Belgium, Switzerland, and India. This structural shift is reconfiguring competitive moats around lipid nanoparticle supply chains and cold-chain distribution networks rather than traditional antigen production expertise.
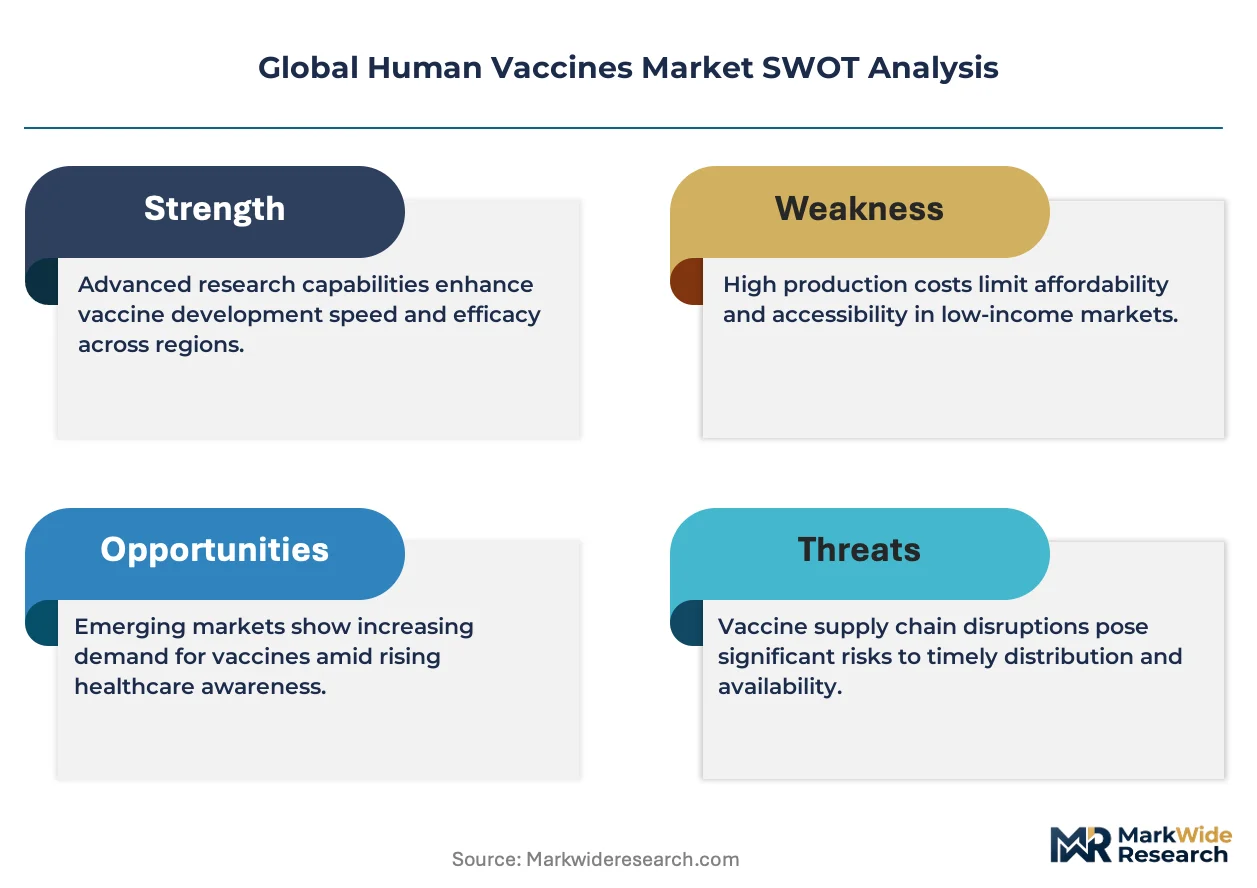
Growth Catalysts
- WHO prequalification acceleration:Streamlined PQ pathways for COVID-19 adapted platforms are unlocking Gavi-eligible country procurement at volumes previously inaccessible to novel technologies.
- India's Universal Immunization Programme:Government procurement commitments are anchoring dose-volume economics for pentavalent and rotavirus categories, pulling supplier investment toward high-throughput fill-finish capacity.
- Self-amplifying mRNA:Next-generation platform designs are reducing antigen dose requirements by 50-80%, enabling multi-valent formulations within existing manufacturing footprints.
Market Restraints
- Lipid input concentration:Ionizable lipid supply chains concentrate among three specialized chemical manufacturers, creating single-source vulnerability for mRNA platform scale-up.
- EMA/FDA divergence on viral vector release:Inconsistent potency assay validation requirements are forcing parallel development tracks, duplicating analytical development costs.
- Ultra-cold infrastructure gaps:Last-mile distribution in Sub-Saharan Africa and South Asia lacks verified -70°C chain integrity, excluding mRNA products from national program tenders regardless of efficacy profiles.
Strategic Opportunities
- Therapeutic vaccine expansion:Oncology neoantigen programs are migrating mRNA platforms from prophylactic to treatment modalities, opening reimbursement pathways at price points 10-20x above infectious disease categories.
- Combination respiratory vaccines:COVID-19/influenza/RSV trivalent formulations are capturing adult immunization preference in the United States and Germany, consolidating annual revaccination into single encounters.
- EU Health Emergency Preparedness and Response Authority:HERA's advance purchase commitments for variant-adapted vaccines are de-risking pandemic platform maintenance during inter-pandemic periods.
Industry Challenges
- Lipid nanoparticle formulation science talent:The intersection of colloid chemistry, pharmaceutical manufacturing, and regulatory science draws from a global pool estimated below 500 qualified specialists.
- Legacy inactivated vaccine asset stranding:Egg-based influenza production facilities face accelerated obsolescence as cell culture and recombinant platforms capture premium tender segments.
- Computational vaccine design validation:FDA and EMA guidance gaps on AI-generated antigen selection are extending IND review timelines for in-silico optimized candidates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Human Vaccines Market |
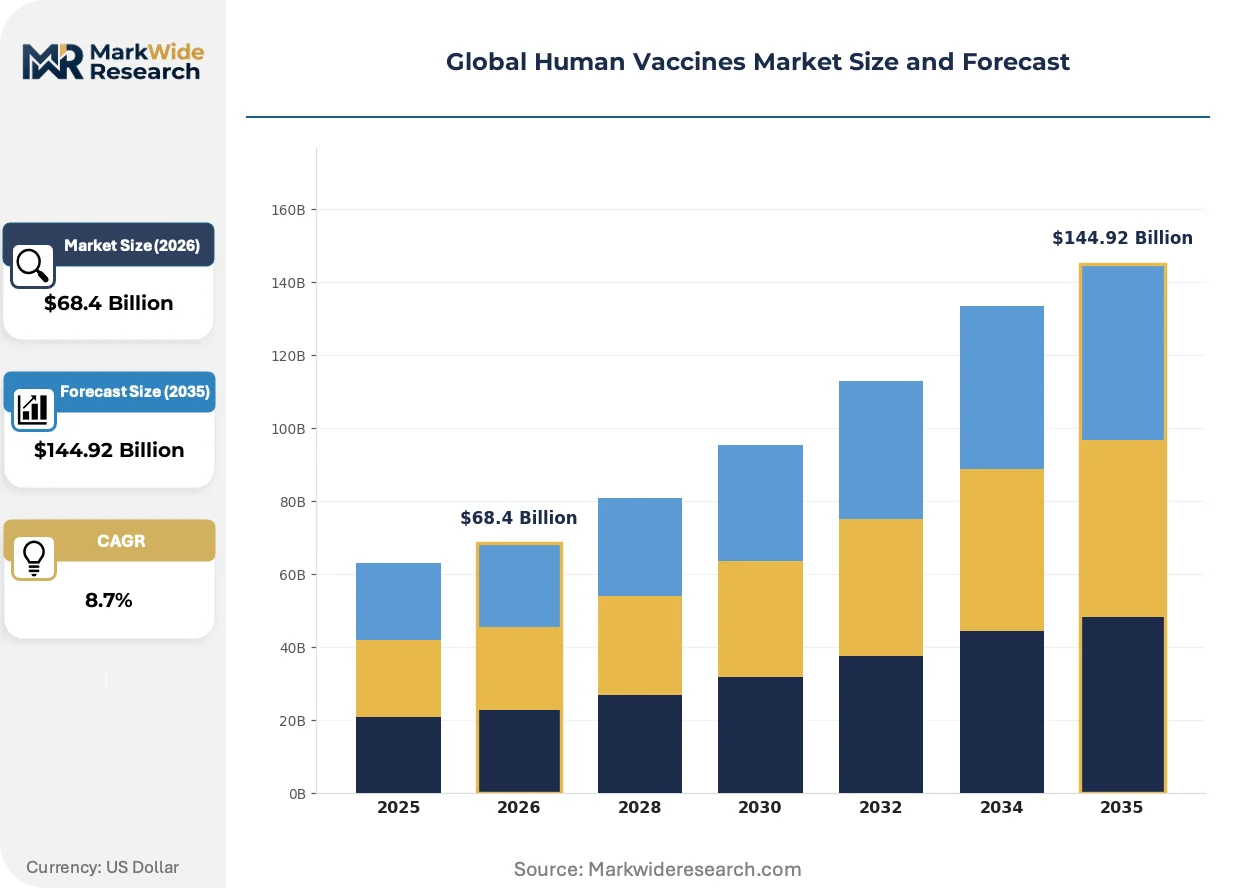
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vaccine Type: Live Attenuated, Inactivated, Subunit, Conjugate, mRNA, Viral Vector Age Group: Infants, Children, Adolescents, Adults, Elderly Disease Target: Influenza, Pneumococcal, HPV, Hepatitis B, Measles, Meningococcal Distribution Channel: Hospitals, Immunization Centers, Clinics, Pharmacies, Outreach Programs |
| Companies Covered | GSK plc, Merck & Co., Inc., Pfizer Inc., Sanofi, CSL Limited, Johnson & Johnson Services, Inc., AstraZeneca, Serum Institute of India Pvt. Ltd., Bavarian Nordic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Human Vaccines Market Shifts & Advancements
Platform convergence between mRNA and viral vector technologies is dissolving traditional category boundaries, while regulatory frameworks race to accommodate iterative antigen updates without full licensure pathways. Manufacturing automation and continuous processing are simultaneously reducing batch-to-batch variability and capital intensity.
Self-amplifying mRNA (sa-mRNA) is electrifying the platform landscape by encoding replicase enzymes that amplify antigen expression in vivo. Pediatric and adolescent immunization programs in the United Kingdom and Australia are piloting sa-mRNA formulations for combination respiratory indications. This amplification mechanism is enabling multi-valent products within existing lipid supply constraints, compressing the cost-per-dose floor previously established by conventional mRNA.
The EU AI Act's risk classification system is mandating algorithmic transparency for computational vaccine design tools deployed in European development workflows. Contract research organizations are restructuring validation protocols to document training data provenance and model drift monitoring. Early-phase developers targeting EMA licensure are most affected, with several candidates delayed for additional algorithmic audit submissions.
Subscription-based procurement models are displacing per-dose tendering in high-income national immunization programs. The United States and Japan are piloting multi-year guaranteed purchase commitments that amortize pandemic platform readiness across annual volumes. This shift transfers demand risk from manufacturers to public payers, concentrating contract awards on suppliers with demonstrated surge capacity.
Global Human Vaccines Market Segmentation
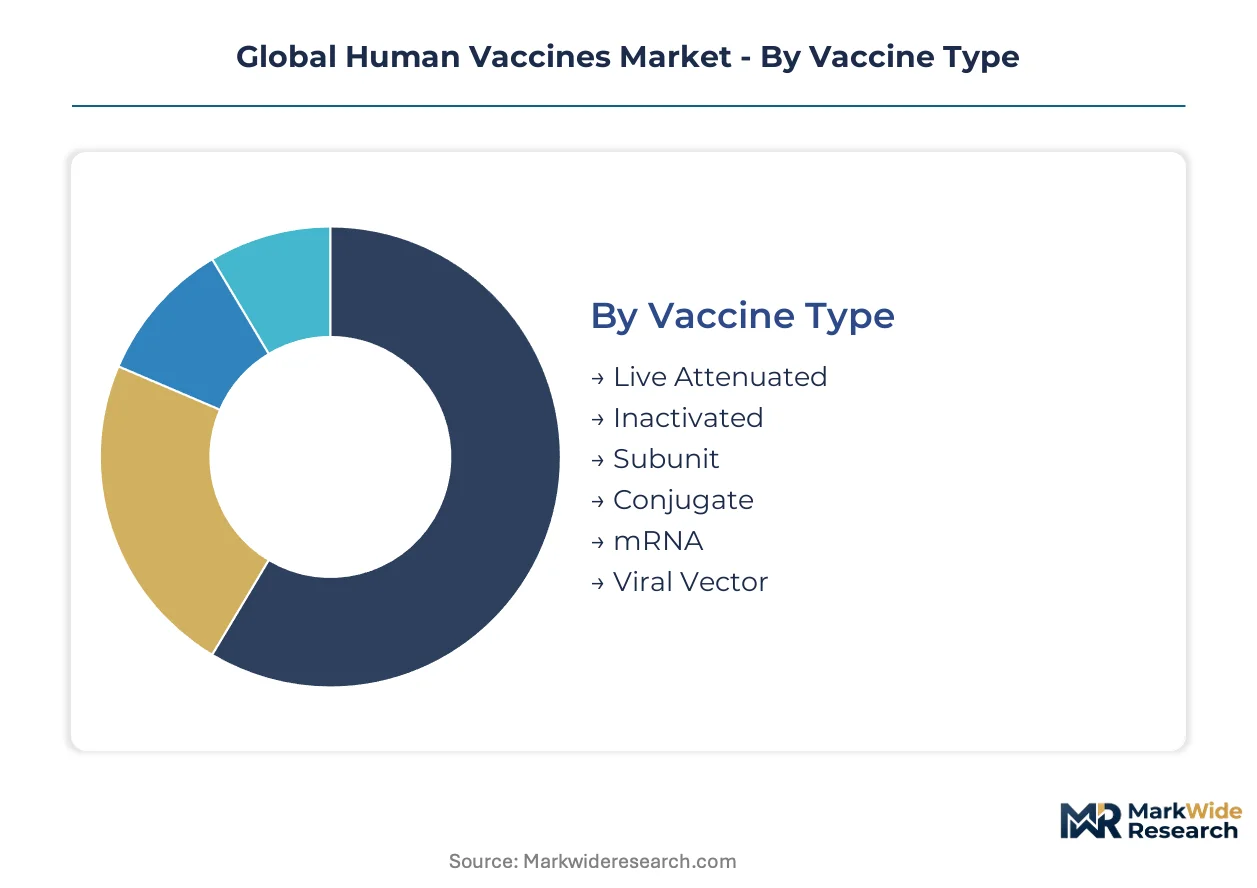
Platform heterogeneity in the Global Human Vaccines Market demands granular segmentation to map procurement pathways, cold-chain requirements, and regulatory submission strategies. Each dimension reveals distinct margin structures and access barriers that determine commercial viability across income tiers.
Vaccine Type:
Volume economics concentrate in established platforms with depreciated manufacturing infrastructure, while premium pricing attaches to novel modalities with concentrated supply chains.
- mRNA:Synthetic nucleic acid sequences encapsulated in lipid nanoparticles enable rapid antigen redesign without cell culture propagation. Demand concentrates in the United States and Germany for COVID-19 and combination respiratory indications, constrained by ionizable lipid supply bottlenecks and ultra-cold distribution requirements.
- Viral Vector:Recombinant adenovirus or vesicular stomatitis virus backbones deliver antigen-encoding genes with potent immunogenicity. Procurement is accelerating in Belgium and Switzerland for outbreak response stockpiles, driven by single-dose regimen advantages in logistically challenging settings.
- Live Attenuated:Weakened pathogen strains replicate transiently to elicit durable cellular and humoral immunity. Measles and yellow fever programs in India and Nigeria anchor dose-volume procurement through UNICEF channels.
- Inactivated:Whole pathogens chemically or thermally killed retain immunogenicity without replication competence. Influenza and polio manufacturing in multi-dose vial formats dominates emerging market tenders.
- Subunit:Purified protein or polysaccharide antigens combined with adjuvants minimize reactogenicity. Hepatitis B surface antigen production in yeast systems supplies institutional procurement in Japan and South Korea.
- Conjugate:Polysaccharide antigens covalently linked to carrier proteins generate T-cell dependent responses in infants. Pentavalent formulations for India's Universal Immunization Programme represent the largest procurement volume globally.
Mature deployment sits with inactivated and live attenuated platforms. Newer deployment is concentrated in mRNA and viral vector categories.
Age Group:
Procurement concentration follows immunization schedule density, with pediatric programs commanding multi-year tenders and adult segments showing episodic campaign-based purchasing.
- Infants:Birth-dose hepatitis B and BCG administration within 24 hours requires heat-stable formulations and community health worker deployment. India's 26 million annual births drive the largest single-nation procurement pool.
- Children:Expanded program on immunization schedules spanning 12-18 months concentrate pentavalent, rotavirus, and pneumococcal doses. Gavi-eligible countries in Sub-Saharan Africa are transitioning from donor-funded to co-financed procurement.
- Adolescents:HPV catch-up campaigns and meningococcal conjugate boosters target school-based delivery infrastructure. Australia's national HPV program and the United Kingdom's MenACWY school-based rollout represent mature implementation models.
- Adults:Occupational hepatitis B, influenza, and travel vaccines generate pharmacy-channel revenue in Germany and the United States. Employer-sponsored coverage creates reimbursement fragmentation.
- Elderly:Pneumococcal polysaccharide and high-dose influenza formulations target waning immunocompetence. Japan's super-aged demographic sustains premium pricing for adjuvanted products.
Procurement scale peaks in infant and children segments. Margin expansion is steepest in elderly and adolescent categories.
Disease Target:
Market maturity diverges sharply between endemic diseases with commoditized supply and emerging targets with concentrated developer pipelines.
- Influenza:Seasonal strain selection by the WHO Global Influenza Surveillance and Response Network dictates annual manufacturing campaigns. Egg-based production in the United States and cell culture platforms in Germany compete for northern hemisphere tenders.
- Pneumococcal:Increasing valency in conjugate formulations (13-valent to 20-valent) extends serotype coverage against invasive disease. South Africa's phased introduction and India's national program expansion are pulling volume growth.
- HPV:Bivalent, quadrivalent, and nonavalent formulations target cervical cancer prevention with adolescent female focus. Australia's transition to gender-neutral coverage and Rwanda's national program demonstrate implementation spectrum.
- Hepatitis B:Recombinant surface antigen production in yeast achieves lowest cost-per-dose among subunit vaccines. China's domestic manufacturers supply the national program with surplus export capacity.
- Measles:Live attenuated combined measles-rubella or measles-mumps-rubella formulations anchor second-dose coverage campaigns. Nigeria and Ethiopia represent the largest residual unvaccinated populations.
- Meningococcal:Serogroup A conjugate elimination in the African meningitis belt and quadrivalent ACWY adoption in Saudi Arabia's Hajj pilgrimage requirements sustain dual market structures.
Commoditized supply dominates influenza and hepatitis B procurement. Pipeline innovation concentrates in pneumococcal valency expansion and HPV indication broadening.
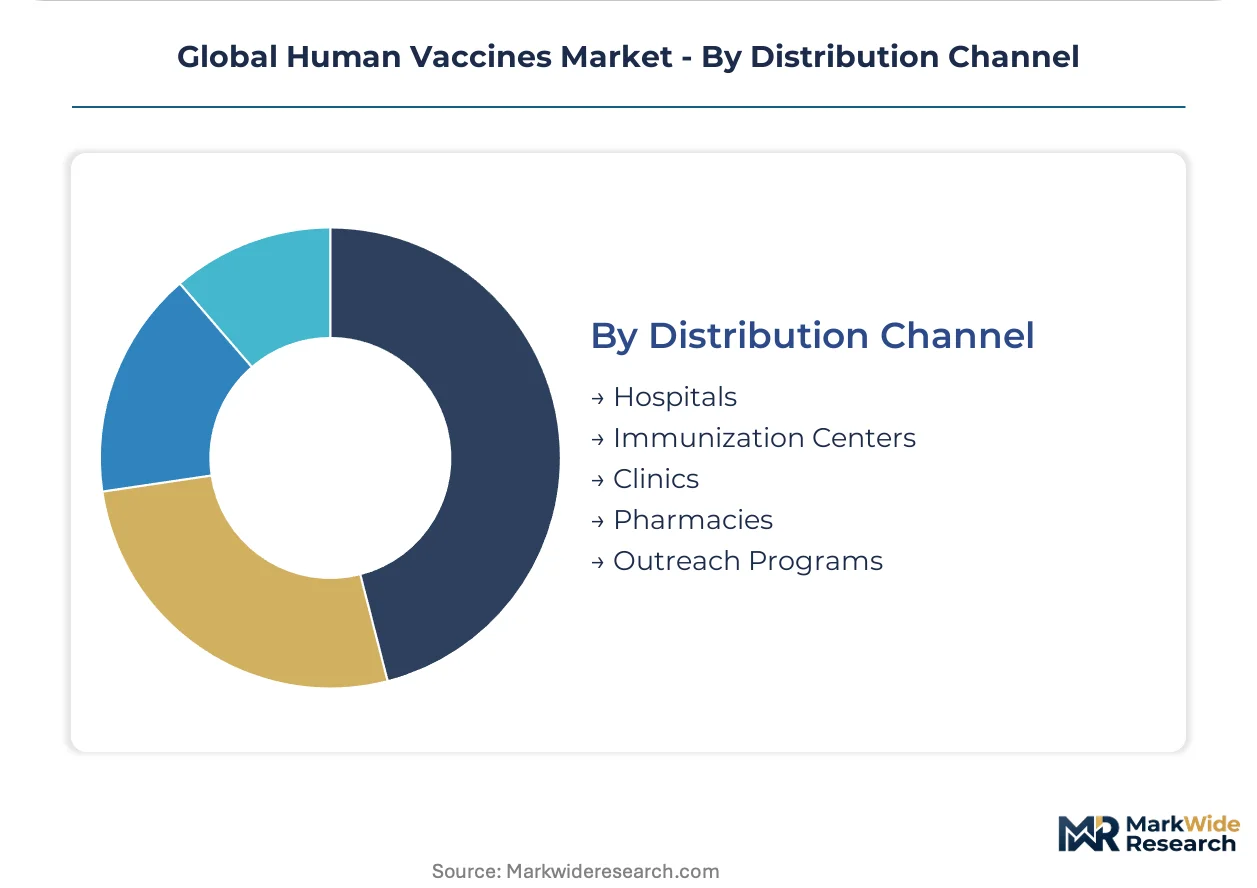
Distribution Channel:
Cold-chain integrity requirements and patient access barriers determine channel selection, with institutional procurement favoring centralized delivery and retail channels capturing discretionary adult demand.
- Hospitals:Inpatient birth-dose administration and post-exposure prophylaxis for rabies and tetanus require 24-hour availability and emergency department integration. Brazil's Sistema Único de Saúde hospital network anchors public procurement.
- Immunization Centers:Dedicated cold-chain infrastructure and trained vaccinator pools support campaign-style delivery for polio and measles supplementary immunization activities. India's sub-health centers reach approximately 150,000 rural locations.
- Clinics:Private pediatric practice in the United States and corporate occupational health in South Korea generate fee-for-service revenue outside national program tenders.
- Pharmacies:Community-based influenza and COVID-19 administration expanded during pandemic response, with Germany's Apotheken and the United States' retail pharmacy chains now embedded in adult immunization pathways.
- Outreach Programs:Mobile teams and community health worker deployment overcome last-mile gaps in Afghanistan, Pakistan, and conflict-affected regions of Sub-Saharan Africa, requiring thermostable formulations and compact cold boxes.
Institutional volume concentrates in hospitals and immunization centers. Pharmacy and outreach channels are expanding fastest for adult campaigns and humanitarian access respectively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgium's ionizable lipid chemical manufacturers anchor mRNA platform supply chains. Switzerland's biologics clusters concentrate viral vector fill-finish capacity. India's government procurement programs drive dose-volume economics for pentavalent and rotavirus categories.
United States
FDA accelerated approval pathways compress mRNA development timelines for COVID-19 and combination respiratory indications. The Biomedical Advanced Research and Development Authority maintains pandemic platform readiness through advance purchase commitments. Boston and San Francisco biotech clusters concentrate lipid nanoparticle formulation science talent.
Germany
EMA centralized procedures enable rapid variant-adapted vaccine licensure across EU member states. The Paul-Ehrlich-Institut enforces potency assay validation standards for viral vector release. Marburg and Dresden manufacturing sites specialize in cell culture-based influenza production.
India
Universal Immunization Programme procurement commitments anchor pentavalent and rotavirus dose volumes. CDSCO streamlined pathways for WHO prequalification alignment accelerate market access timelines. Pune and Hyderabad clusters concentrate high-throughput fill-finish capacity for UNICEF and Gavi channels.
Belgium
Specialized chemical manufacturers concentrate ionizable lipid supply for mRNA platform scale-up. EMA regulatory science guides define lipid nanoparticle characterization standards. Flanders biologics clusters recalibrate capacity to accommodate self-amplifying mRNA manufacturing.
Switzerland
Swissmedic maintains stringent batch release requirements for viral vector potency consistency. Federal procurement programs support pandemic preparedness stockpile maintenance. Basel and Bern manufacturing sites integrate continuous processing automation for reduced batch-to-batch variability.
Global Human Vaccines Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue therapeutic oncology applications and self-amplifying mRNA platforms. The market structure concentrates around integrated biologics manufacturers with captive lipid supply chains and specialized fill-finish infrastructure. Three archetypes dominate: adjuvant technology leaders, mRNA platform specialists, and high-volume dose suppliers for emerging market procurement. Competitive moves center on lipid nanoparticle supply chain consolidation and continuous processing automation investments.
Within the integrated biologics tier, GSK plc and Pfizer Inc. exemplify platform diversification across mRNA, viral vector, and protein subunit modalities. Serum Institute of India Pvt. Ltd. occupies a distinctive position anchoring dose-volume economics for Gavi-eligible country procurement through high-throughput manufacturing scale.
| Leading Market Players |
|---|
| GSK plc |
| Merck & Co., Inc. |
| Pfizer Inc. |
| Sanofi |
| CSL Limited |
| Johnson & Johnson Services, Inc. |
| AstraZeneca |
| Serum Institute of India Pvt. Ltd. |
| Bavarian Nordic |
| Others |
Supply & Pricing Matrix
Captive integration into ionizable lipid manufacturing anchors both supply security and pricing power for mRNA platform developers, with Belgium's specialized chemical producers commanding premium positioning against downstream vaccine manufacturers locked into long-term offtake agreements. This structural arrangement concentrates margin capture upstream while forcing dose suppliers to absorb cold-chain logistics costs that escalate with ultra-cold distribution requirements.
Pricing Analysis
Cold-chain service bundling separates premium mRNA doses with verified -70°C integrity guarantees from unbundled standard-tier inactivated vaccines where last-mile risk transfers to national procurement programs. Three-tier pricing structure across premium, standard, and economy levels reflects adjuvant sophistication, WHO prequalification status, and volume scale under Gavi co-financing arrangements. Cost compression in pediatric pentavalent categories intensifies because India's Universal Immunization Programme consolidates supplier awards among high-throughput fill-finish operators. Government tenders in Sub-Saharan Africa exhibit the highest price sensitivity, while Japan's super-aged demographic sustains premium tolerance for adjuvanted elderly formulations.
Supply Chain Analysis
Regional distribution centers in Belgium, Switzerland, and India configure hub-and-spoke patterns that concentrate mRNA lipid inputs and viral vector fill-finish capacity within specialized biologics clusters. Ionizable lipids, sterile fermentation media, and glass vial containment systems draw from concentrated chemical and packaging suppliers, creating single-source vulnerability for platform scale-up. Tariff exposure on Chinese-sourced adjuvant raw materials threatens margin stability for subunit vaccine producers. Distribution runs through UNICEF's Copenhagen stockpile for Gavi-eligible countries, while high-income markets rely on direct manufacturer-to-hospital contracts with integrated cold-chain monitoring.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a technology-transition phase where self-amplifying mRNA platforms displace legacy egg-based influenza manufacturing, compressing development timelines while concentrating competitive advantage around lipid nanoparticle formulation science.
For Market Incumbents: Lock in ionizable lipid supply through backward integration or exclusive offtake agreements with Belgium's specialized chemical manufacturers before capacity constraints harden. Accelerate continuous processing automation investments in Swiss and Indian fill-finish facilities to defend margin position against emerging sa-mRNA entrants with lower dose-requirement economics. The threat of therapeutic oncology mRNA platforms at 10-20x infectious disease price points demands selective pipeline prioritization to avoid asset stranding in commoditized pediatric categories. For New Entrants and Emerging Players: Contract research organizations with algorithmic transparency protocols offer the most penetrable partnership channel for EU AI Act compliance support, as EMA-bound developers face validation delays for computational vaccine design tools. White-space concentrates in thermostable formulation development for Sub-Saharan African last-mile distribution, where ultra-cold infrastructure gaps exclude mRNA products from national tenders regardless of efficacy. Gavi-eligible country procurement through UNICEF channels provides the clearest go-to-market anchor for high-volume, low-margin dose economics. For Investors and Strategic Acquirers: Exit pathways concentrate in platform-technology acquisitions by integrated biologics manufacturers seeking lipid nanoparticle capabilities, with therapeutic oncology applications commanding premium multiples over infectious disease franchises. Long-term viability favors developers with demonstrated WHO prequalification success and surge capacity under HERA-style advance purchase commitments. Watch FDA and EMA convergence on viral vector potency assay validation as the signal for regulatory arbitrage opportunities closing.| Strategic Initiative | Industry Significance |
|---|---|
| Lipid Supply Chain Consolidation | Captive ionizable lipid production secures mRNA platform scale-up against Belgium supplier bottlenecks. |
| Continuous Processing Automation | Swissmedic-aligned batch release standards in Basel facilities reduce variability for viral vector potency. |
| Self-Amplifying mRNA Pipeline Entry | sa-mRNA amplification mechanisms halve antigen dose requirements within existing manufacturing footprints. |
| Therapeutic Oncology Expansion | Neoantigen programs unlock reimbursement pathways at price premiums above infectious disease categories. |
| WHO Prequalification Acceleration | Streamlined PQ pathways unlock Gavi-eligible procurement volumes for COVID-19-adapted platforms. |
Research Methodology
Independent corroboration across CDSCO regulatory filings, UNICEF procurement databases, and EMA centralized procedure records underwrites the qualitative findings in this study. Primary interviews with vaccine development executives, regulatory affairs leads at EMA and FDA, formulary directors in Germany's statutory health insurance system, and Gavi procurement specialists combined with secondary validation from WHO prequalification listings, ClinicalTrials.gov records, and national immunization program tender documents. Bottom-up dose-volume modeling across platform types triangulates against top-down market sizing from biologics manufacturing capacity disclosures.
Historical reference periods spanning pre-pandemic, emergency authorization, and post-acceleration phases anchor the forecast window across the projection horizon. Segmentation dimensions modeled include vaccine platform type, age group immunization schedule density, disease target maturity, and regional regulatory cluster alignment. CAGRs derive from dose-demand projections weighted by procurement channel concentration and technology-transition adoption curves. Forecast inputs incorporate lipid nanoparticle supply constraints, WHO prequalification queue velocities, and self-amplifying mRNA clinical advancement rates.
Caveats apply where EMA-FDA divergence on viral vector release standards, ionizable lipid supply disruptions, or AI Act algorithmic audit delays could materially shift the outlook. Forecasts reflect documented assumptions on procurement commitment durability and pandemic platform maintenance funding. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global 3D Printed Drugs Market
Pharmaceuticals
Inhalation and Nasal Spray Generic Drugs Market
Pharmaceuticals
Global Antiemetics Market
Pharmaceuticals
Global Immuno Oncology Drugs Market
Pharmaceuticals
India Opioids Market
Pharmaceuticals
Global Osteoporosis Drugs Market
Pharmaceuticals
OTC Analgesic Market
Pharmaceuticals
Lithuania Pharmaceutical Market
Pharmaceuticals
Germany Pharmaceutical 3PL Market
Pharmaceuticals
Flavors Into Over-The-Counter (OTC) Pharmaceuticals Market
Pharmaceuticals
Global Pediatric Electrolyte Solutions Market
Pharmaceuticals
Global Online Pharmacy Market
Pharmaceuticals
Dermatitis Drugs Market
Pharmaceuticals
Peptide Therapeutics Market
Pharmaceuticals
Cannabinoid Drugs Market
Pharmaceuticals
Hydroxypropyl Methylcellulose (HPMC) Capsules Market