
 GCC Pallet Market | 2026-2036
GCC Pallet Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Pallet Market Intelligence
Third-party logistics channels across the GCC is reconfiguring around hub-and-spoke distribution models centered on Jeddah Islamic Port and Jebel Ali. CHEP (Brambles Limited) controls the pooled pallet rental infrastructure across Saudi Arabia and the UAE. Cabka Group GmbH specializes in injection-molded plastic pallets designed for pharmaceutical cold chains. LOSCAM International Holdings anchors returnable packaging programs for fast-moving consumer goods flowing through Dubai's free zones.
A pallet is a flat transport structure that supports goods in a stable fashion while being lifted by forklifts, pallet jacks, or other jacking devices, typically constructed from wood slats nailed to stringers or molded from high-density polyethylene with dynamic load ratings exceeding 1,500 kilograms. Wood pallets dominate GCC warehouse applications due to lower unit costs and repairability, though plastic pallets command margin pools in pharmaceutical and food export segments where hygiene standards and ISPM-15 exemption deliver operational savings. Stackable designs lead transportation applications across the region's long-haul trucking corridors, while collapsible formats grow fastest in last-mile delivery serving Saudi Arabia's expanding e-commerce fulfillment networks.
SFDA (Saudi Arabia) mandates traceable handling equipment for pharmaceutical distribution, pushing converters toward certified plastic pallet specifications. UAE's Ministry of Climate Change and Environment enforces waste reduction frameworks that incentivize returnable pallet pools over single-use wood alternatives. Saudi Standards, Metrology and Quality Organization (SASO) technical regulations for packaging materials shape import compliance for pallet suppliers entering the Kingdom. Stakeholders must monitor how Saudi Arabia's logistics privatization agenda and UAE's industrial decarbonization targets redirect procurement criteria toward circular material flows and asset-tracking integration.
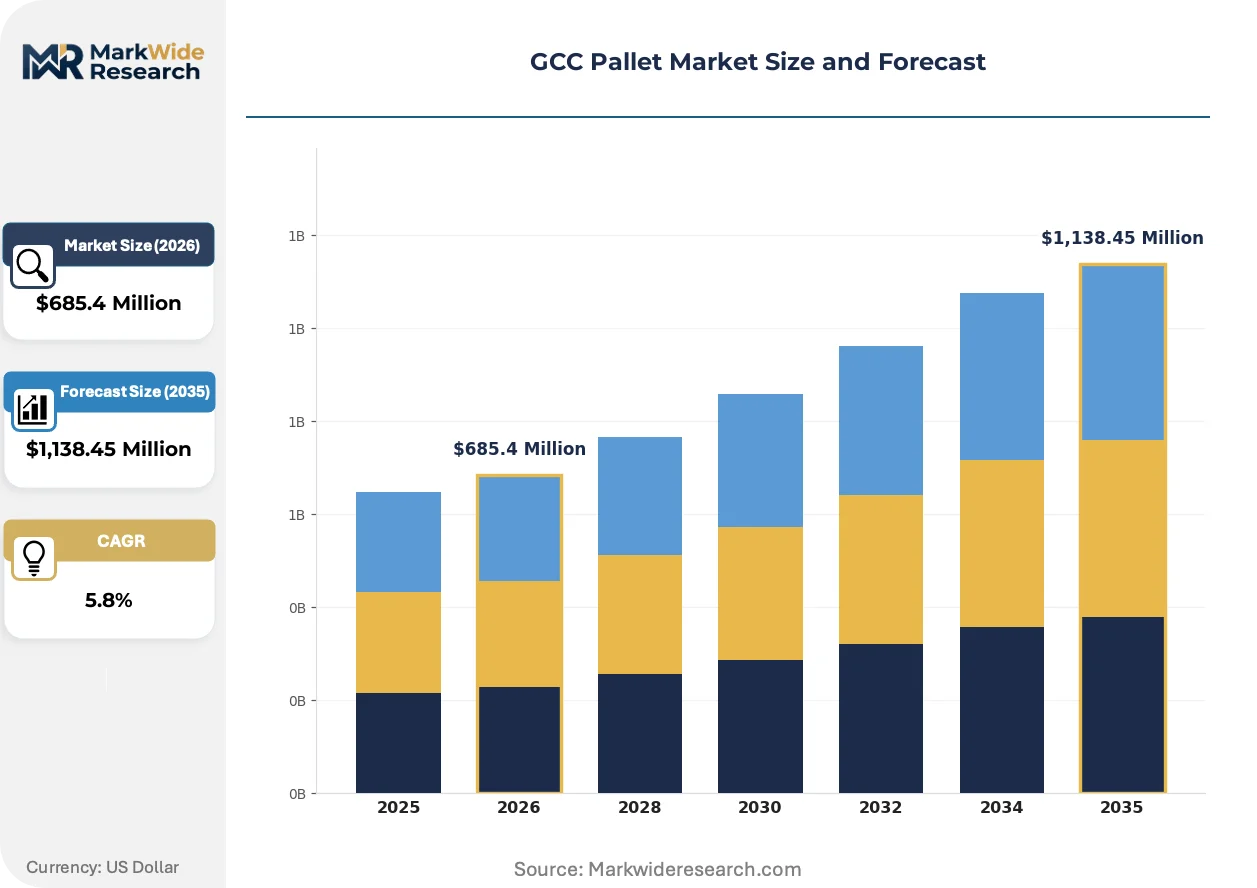
Market Dynamics
SFDA cold-chain mandates are compressing pallet specification windows across Saudi pharmaceutical distribution, forcing converters to certify plastic assets while logistics privatization accelerates asset-tracking integration.
Growth Catalysts
- SFDA pharmaceutical traceability mandates:Saudi Arabia's national pharmaceutical regulator now requires documented handling equipment chains, pulling certified plastic pallets into temperature-controlled distribution networks.
- UAE waste reduction frameworks:The Ministry of Climate Change and Environment incentivizes returnable pallet pools over single-use wood alternatives in Dubai's free zone logistics corridors.
- Composite materials:Injection-molded reinforced plastics designed for pharmaceutical cold chains are penetrating UAE re-export hubs serving East African and South Asian corridors.
Market Restraints
- Petrochemical input volatility:High-density polyethylene resin prices fluctuate with crude oil benchmarks, compressing margin pools for plastic pallet manufacturers serving the GCC.
- Wood pallet repairability gap:Lower unit costs and on-site repairability of timber alternatives anchor warehouse applications outside hygiene-critical segments.
- ISPM-15 certification friction:Heat-treatment requirements for wood pallets in cross-border agricultural trade create compliance overhead that slows substitution timelines.
Strategic Opportunities
- Kuwait and Bahrain underpenetration:Smaller GCC markets lack pooled pallet infrastructure, creating first-mover openings for rental operators with integrated asset-tracking systems.
- Collapsible format penetration:Saudi Arabia's e-commerce fulfillment networks are absorbing space-optimizing pallet designs for last-mile density in Riyadh and Jeddah corridors.
- SASO technical alignment:Saudi Standards, Metrology and Quality Organization packaging regulations create compliance pathways for certified suppliers entering the Kingdom's import channels.
Industry Challenges
- RFID integration complexity:Legacy warehouse management systems in Saudi distribution centers require costly middleware upgrades to capture pallet-level traceability data mandated by pharmaceutical regulators.
- Asset pool coordination:Returnable pallet programs across UAE-Saudi corridors face settlement friction from divergent depreciation schedules and damage liability frameworks between logistics operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Pallet Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Wood, Plastic, Metal, Composite End User: Retail, Pharmaceuticals, Food & Beverage, Logistics Design Type: Stackable, Non-stackable, Collapsible, Flat Application: Warehouse, Transportation, Storage, Export |
| Companies Covered | Falkenhahn AG, Mondi Plc, CHEP (Brambles Limited), PalletOne Inc., ORBIS Corporation, Cabka Group GmbH, LOSCAM International Holdings, Rehrig Pacific Company, Craemer GmbH, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Pallet Market Strategic Shifts & Innovations
Asset digitization and material substitution are compressing traditional pallet procurement cycles across GCC logistics networks. Cold-chain pharmaceutical requirements and circular economy mandates are accelerating specification divergence between hygiene-critical and commodity handling applications.
RFID-embedded plastic pallets are migrating from pilot pharmaceutical installations to mainstream adoption across Saudi distribution networks. SFDA-mandated traceability requirements are pulling tagged assets into temperature-controlled corridors serving Riyadh and Jeddah. This migration from passive identification to active tracking infrastructure is enabling real-time custody verification and compressing recall response timelines for vaccine and biologic shipments.
UAE's Ministry of Climate Change and Environment waste reduction frameworks are reshaping procurement criteria across Dubai's free zone logistics operators. Returnable pallet pool mandates now override single-use wood purchasing in government-contracted freight corridors. Pharmaceutical and food export segments are responding fastest, leveraging ISPM-15 exemption benefits of plastic alternatives to eliminate fumigation delays at Gulf port terminals.
Hub-and-spoke distribution consolidation around Jeddah Islamic Port and Jebel Ali is restructuring pallet velocity requirements across the GCC. Third-party logistics operators now specify dynamic load ratings exceeding 1,500 kilograms for long-haul trucking corridors while demanding collapsible formats for last-mile density. Saudi Arabia's e-commerce fulfillment networks are absorbing this specification divergence fastest, segmenting pallet fleets between bulk inbound and parcel outbound handling requirements.
GCC Pallet Market Segmentation
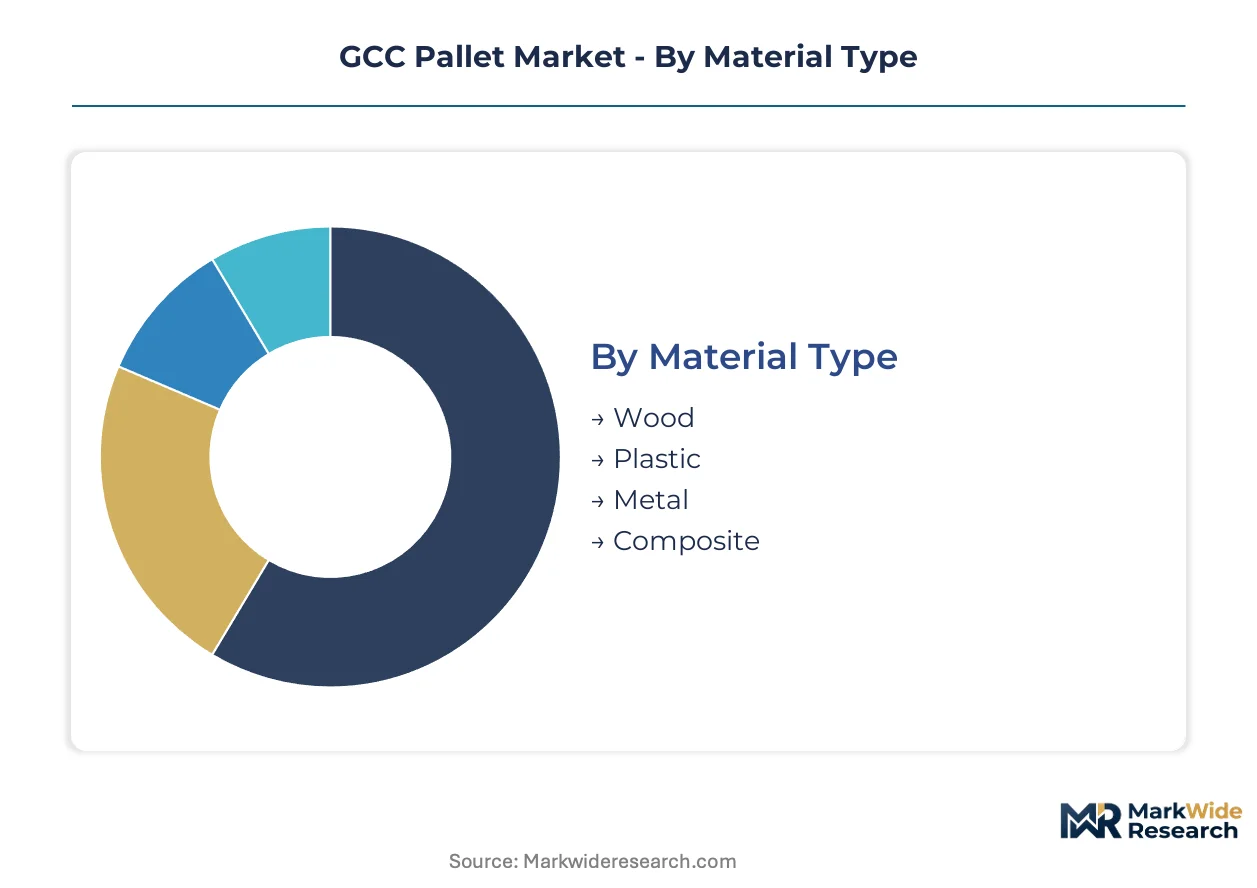
Pallet specification windows across the GCC diverge sharply between hygiene-critical pharmaceutical corridors and commodity warehouse operations. Material selection and design geometry now track regulatory mandates rather than unit cost alone.
Material Type:
Cost tier determines procurement patterns across Saudi and UAE logistics networks, with petrochemical input volatility compressing margin pools at the premium end.
- Wood:Lower unit costs and on-site repairability anchor warehouse applications across Saudi Arabia's bulk distribution centers. Timber stringer designs dominate Jeddah Islamic Port container freight despite ISPM-15 heat-treatment overhead for agricultural exports.
- Plastic:High-density polyethylene formulations with dynamic load ratings exceeding 1,500 kilograms command pharmaceutical and food export segments. SFDA cold-chain mandates pull certified assets into temperature-controlled Riyadh corridors where hygiene standards and ISPM-15 exemption eliminate fumigation delays.
- Metal:Steel and aluminum configurations serve heavy-industrial applications in UAE petrochemical zones requiring fire-resistant handling equipment.
- Composite:Injection-molded reinforced plastics penetrate Dubai's re-export hubs serving East African and South Asian trade lanes.
Wood holds installed capacity. Plastic is rotating up the share rankings.
End User:
Application-specific regulations fragment demand across customer types, with traceability mandates overriding cost optimization in controlled-temperature segments.
- Pharmaceuticals:SFDA mandates documented handling equipment chains, pulling RFID-embedded plastic pallets into vaccine and biologic distribution networks. Real-time custody verification compresses recall response timelines across Riyadh and Jeddah corridors.
- Logistics:Third-party operators across UAE-Saudi corridors specify divergent fleet geometries—bulk-rated designs for long-haul trucking, collapsible formats for last-mile density. Hub-and-spoke consolidation around Jebel Ali and Jeddah Islamic Port reconfigures velocity requirements.
- Food & Beverage:Export-oriented processors leverage plastic pallet ISPM-15 exemption to bypass Gulf port terminal delays.
- Retail:Saudi e-commerce fulfillment networks absorb space-optimizing designs for parcel outbound handling in Riyadh logistics clusters.
Logistics commands volume concentration. Pharmaceuticals is climbing the fastest.
Design Type:
Volume efficiency drives specification divergence between inbound bulk and outbound parcel operations across GCC distribution networks.
- Stackable:Block or stringer base configurations maximize cube utilization in Jeddah and Dubai container yards. Dynamic load ratings exceeding 1,500 kilograms suit long-haul Saudi trucking corridors where pallet stacking reduces freight cost per unit.
- Collapsible:Fold-down side walls and nesting geometry cut return-trip freight costs for Saudi last-mile operators serving Riyadh e-commerce fulfillment zones. Space-optimizing formats gain traction fastest where truck capacity constraints bite hardest.
- Non-stackable:Stringer designs with bottom deck boards suit floor-stacked warehouse storage in lower-velocity Saudi distribution centers.
- Flat:Skid configurations without bottom deck serve light-load retail display applications in UAE mall logistics.
Stackable holds installed capacity. Collapsible is rotating up the share rankings.
Application:
Geography shapes functional requirements, with port-centric export operations demanding distinct specifications from inland warehouse handling.
- Warehouse:Wood stringer pallets dominate Saudi bulk storage operations where repairability and lower capital outlay offset hygiene limitations. Jeddah distribution centers favor four-way entry designs for forklift maneuverability in narrow aisles.
- Export:Plastic alternatives displace heat-treated timber in UAE pharmaceutical and food corridors where ISPM-15 compliance friction slows cross-border clearance. Dubai free zone operators face Ministry of Climate Change and Environment waste reduction mandates favoring returnable pools.
- Transportation:Dynamic load ratings and nesting capability prioritize cube efficiency across UAE-Saudi long-haul trucking networks.
- Storage:Rackable designs with reinforced stringers serve high-bay Saudi distribution centers requiring pallet stacking above floor level.
Warehouse holds installed capacity. Export is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UAE logistics corridors command premium pricing for certified plastic pallets serving pharmaceutical re-exports, while Saudi bulk distribution centers absorb lower-cost wood alternatives under divergent regulatory pressure.
Saudi Arabia
Pharmaceutical cold-chain expansion and e-commerce fulfillment density drive specification divergence across Riyadh and Jeddah corridors. SFDA mandates documented handling equipment chains for vaccine distribution, pulling RFID-embedded assets into temperature-controlled networks. Jeddah Islamic Port anchors hub-and-spoke consolidation where third-party logistics operators specify dynamic load ratings exceeding 1,500 kilograms for long-haul trucking.
United Arab Emirates
Dubai's re-export hubs serving East African and South Asian trade lanes absorb composite material pallets designed for multi-modal transfer efficiency. The Ministry of Climate Change and Environment enforces waste reduction frameworks that incentivize returnable pallet pools over single-use wood alternatives in government-contracted freight corridors. Jebel Ali free zone operators face procurement mandates favoring circular material flows and asset-tracking integration.
Kuwait
Underdeveloped pooled pallet infrastructure creates first-mover openings for rental operators with integrated tracking systems serving food import and construction material distribution. The national environmental authority applies selective pressure on single-use packaging waste without comprehensive mandate coverage. Shuwaikh Port logistics clusters concentrate demand for stackable designs handling containerized freight from Asian manufacturing sources.
Qatar
Pharmaceutical distribution networks expand under healthcare infrastructure investment programs, pulling certified plastic specifications into Doha cold-chain corridors. The national standardization body aligns import compliance frameworks with Gulf technical regulations for packaging materials. Hamad Port container terminals concentrate demand for ISPM-15 exempt plastic alternatives eliminating cross-border agricultural clearance friction.
Bahrain
Smaller-scale logistics operations and limited domestic manufacturing base sustain reliance on imported wood pallet supply serving retail and food service distribution. The national environmental regulator maintains voluntary waste reduction guidelines without binding pallet pool mandates. Khalifa Bin Salman Port handles transshipment volume where nesting and collapsible formats optimize cube utilization on feeder vessel routes.
GCC Pallet Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying injection-molded assets and timber fabrication. The GCC pallet market structures around three distinct tiers: pooled rental operators controlling asset circulation across Saudi-UAE corridors, material-specific manufacturers serving hygiene-critical pharmaceutical segments, and regional fabricators supplying commodity wood alternatives for bulk warehouse applications. Strategic moves concentrate on RFID integration partnerships and collapsible format development for last-mile density optimization.
Within the pooled rental tier, CHEP anchors returnable packaging programs across Saudi Arabia and the UAE, while LOSCAM International Holdings exemplifies FMCG-focused asset pool coordination through Dubai free zone logistics corridors. Cabka Group GmbH represents the pharmaceutical-specialist archetype, with injection-molded plastic pallet specifications designed for cold-chain compliance under SFDA guidelines.
| Leading Market Players |
|---|
| Falkenhahn AG |
| Mondi Plc |
| CHEP (Brambles Limited) |
| PalletOne Inc. |
| ORBIS Corporation |
| Cabka Group GmbH |
| LOSCAM International Holdings |
| Rehrig Pacific Company |
| Craemer GmbH |
| Others |
Cost & Logistics Intelligence
Petrochemical feedstock concentration in Saudi Arabia and the UAE tethers pallet margin pools to resin price volatility, compressing plastic pallet converters while wood fabricators capture cost-advantaged warehouse segments. This upstream concentration funnels pricing power toward integrated resin producers and pooled rental operators with asset-tracking infrastructure.
Pricing Analysis
Configured-to-order pricing for RFID-embedded pharmaceutical pallets commands spreads exceeding standard block-pallet rates by certification tier and tracking integration depth. Pricing stratifies across premium certified-plastic tiers for SFDA-compliant cold chains, standard pooled-rental rates for FMCG corridors, and economy spot purchases for construction material handling. Cost compression in plastic tiers stems from polyethylene resin volatility tied to crude benchmarks. Warehouse operators in Saudi bulk distribution exhibit highest price sensitivity; pharmaceutical 3PLs in UAE free zones show lowest sensitivity due to regulatory compliance premiums.
Supply Chain Analysis
Contract manufacturing for injection-molded pallets concentrates in UAE industrial zones serving Dubai re-export hubs and Saudi pharmaceutical corridors. Raw material flows draw from Saudi petrochemical complexes for polyethylene resin, Chinese mold-fabrication for tooling, and Southeast Asian timber for wood pallet stringers. Single-source vulnerability sits with HDPE resin supply exposed to OPEC+ production decisions. Distribution runs through Jebel Ali and Jeddah Islamic Port container terminals where pallet pooling operators coordinate reverse logistics for returnable assets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GCC pallet demand is inflecting toward platform economics as RFID-enabled asset pools replace spot procurement, driven by SFDA traceability mandates and UAE circular-economy frameworks requiring interoperability between logistics operators.
For Market Incumbents: Build data-network moats through API integration with warehouse management systems serving Saudi pharmaceutical 3PLs. Incumbents must consolidate regional fabricator networks to capture wood pallet repair capacity before resin volatility pushes commodity buyers toward alternative materials. Certification investment in SASO-compliant tracking infrastructure defends against emerging pooled-rental entrants from European markets. For New Entrants and Emerging Players: Kuwait and Bahrain's absence of integrated pallet pooling presents first-mover openings for rental operators with collapsible-format assets and embedded tracking. New entrants should target food import corridors in Shuwaikh Port where stackable plastic specifications displace heat-treated wood under selective environmental pressure. A go-to-market angle anchored to pay-per-use financing models bypasses capital-constrained logistics operators in smaller GCC markets. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across RFID-integrated pallet manufacturing as sensor costs decline and software development scales. Long-term viability favors asset-light platform operators over injection-molding capacity owners exposed to resin volatility. Investors should monitor pharmaceutical 3PL contract renewal cycles as the signal for pooled-pallet adoption inflection across Saudi Arabia.| Strategic Initiative | Industry Significance |
|---|---|
| RFID Integration Partnership | SFDA traceability mandates pull tagged assets into Riyadh vaccine distribution networks. |
| Collapsible Format Development | Saudi e-commerce fulfillment density drives space-optimizing pallet absorption in last-mile corridors. |
| Pooled Asset Platform Expansion | UAE waste reduction frameworks override single-use wood purchasing in government-contracted freight lanes. |
| Backward Integration into Resin Supply | Petrochemical input volatility compresses margin pools for non-integrated plastic pallet converters. |
| Certification Investment in SASO Standards | Saudi import compliance pathways favor certified suppliers entering Kingdom distribution channels. |
Research Approach
Cross-validation between primary interviews with logistics procurement directors and secondary trade-flow data anchors the qualitative findings in this study. Conversations with pharmaceutical supply chain managers, 3PL operations heads, pallet pool coordinators, and SASO compliance officers combined with customs records, SFDA regulatory filings, and GCC petrochemical production statistics. Bottom-up shipment data triangulates against top-down resin consumption estimates across the analysis window.
Calibration against historical adoption curves for returnable packaging in comparable regulatory environments shaped the projection framework. Segmentation dimensions span material type, design geometry, end-use industry, and application corridor across the modeling period. CAGRs derive from elasticity-adjusted demand curves incorporating pharmaceutical cold-chain expansion rates and e-commerce fulfillment density metrics.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese molded-plastic exporters or European pooled-rental operators would shift outcomes beyond modeled ranges. Quarterly review of SFDA enforcement intensity and UAE free zone procurement mandate updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Latin America Pallet Market
Pallets Packaging
Pallet Banding Machine Market
Pallets Packaging
Paper Pallet Market
Pallets Packaging
Pallets Market
Pallets Packaging
Single Use Pallet Market
Pallets Packaging
Europe Lumber Pallet Market
Pallets Packaging
Italy Pallets Market
Pallets Packaging
Pallet Labelling System Market
Pallets Packaging
Molded Wood Pallets Market
Pallets Packaging
Pallet Jacks Market
Pallets Packaging
Middle East and Africa Lumber Pallet Market
Pallets Packaging
Block Pallets Market
Pallets Packaging
Spill Pallets Market
Pallets Packaging
Pallet Collar Market
Pallets Packaging
Foldable Plastic Pallet Boxes Market
Pallets Packaging
Pallet Tines Market