
 Algeria Oil and Gas Downstream Market | 2026-2036
Algeria Oil and Gas Downstream Market Size, Share, and Industry Trends Forecast 2026-2036
Algeria Oil and Gas Downstream Market Outlook
Specialized refinery engineering talent is redrawing competitive boundaries in Algeria's downstream expansion. Sonatrach SA leverages its state-operator status to dominate domestic refining capacity and control upstream feedstock allocation. TotalEnergies anchors its position through integrated petrochemical joint ventures that tie European technology transfer to local content requirements. Samsung Engineering Co Ltd competes on large-scale EPC execution, exporting Asian construction efficiency to Algerian greenfield sites.
Algeria oil and gas downstream encompasses crude oil refining, natural gas processing, and the manufacture of petroleum derivatives including gasoline, diesel, jet fuel, asphalt, and chemical feedstocks, typically operating through atmospheric and vacuum distillation units with cracking and reforming units to upgrade heavier fractions into higher-value products. Refined Oil output sustains the largest revenue share given Algeria's state-mandated fuel subsidy regime and transport sector dependence. Petrochemicals represents the fastest-expanding segment as Sonatrach pursues import substitution for plastics and fertilizers. LPG distribution through B2B Sales channels captures concentrated margin pools tied to industrial and residential bulk offtake contracts.
Algeria's national hydrocarbon regulator shapes downstream investment timelines through production-sharing contract terms and local content mandates. The country's environmental authority enforces refinery emissions standards that push operators toward sulfur recovery and flaring reduction investments. Stakeholders must weigh the pace of subsidy reform against petrochemical diversification returns when committing capital to Algerian downstream assets.
Market Dynamics
Sonatrach's feedstock allocation authority under Algeria's revised hydrocarbon law is redirecting private investment toward integrated petrochemical complexes, compressing standalone refining project timelines.
Growth Catalysts
- LPG bulk offtake contracts:Industrial and residential distributors are locking in multi-year supply agreements with Sonatrach's Hassi Messaoud processing facilities, anchoring predictable revenue streams.
- Algerian hydrocarbon law revisions:Production-sharing contract terms now permit foreign operators to book reserves, accelerating European engineering contractor mobilization to greenfield sites.
- Sulfur recovery mandates:The country's environmental authority is enforcing flaring reduction protocols, forcing refinery upgrades that create specialized EPC demand.
Market Restraints
- European engineering labor scarcity:Specialized refinery construction expertise concentrates in Italian and Spanish contractor pools, creating bidding bottlenecks for simultaneous Algerian projects.
- Imported catalyst dependency:Hydrocracking and reforming unit operations require specialty catalysts sourced from German and US suppliers, exposing margins to euro-dollar volatility.
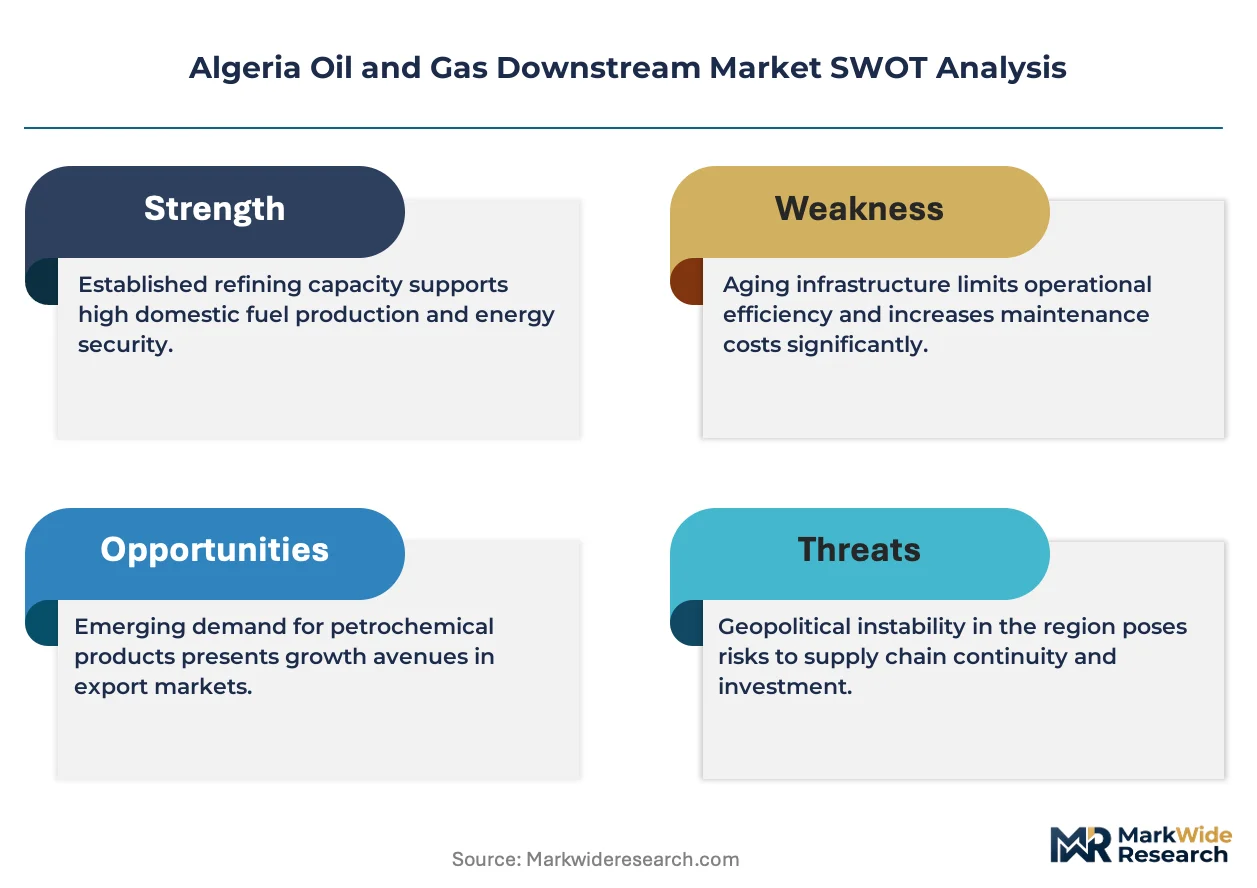
- State-mandated fuel subsidies:Refined product pricing caps suppress downstream returns, diverting capital toward export-oriented petrochemical derivatives.
Strategic Opportunities
- Oran industrial corridor expansion:Mediterranean port infrastructure upgrades enable direct refined product export to Southern European markets, bypassing congested eastern terminals.
- Fertilizer feedstock integration:Ammonia and urea production complexes at Arzew are capturing natural gas liquids that previously flared, converting waste streams into agricultural export revenue.
- Digital twin deployment:Advanced process simulation is reducing refinery commissioning timelines for Asian EPC contractors executing Hassi Messaoud greenfield builds.
Industry Challenges
- Commissioning engineer shortages:Complex hydrocracker and delayed coker startups require experienced startup teams that Algerian technical universities cannot supply at scale.
- Legacy pipeline integration:New refinery complexes must interface with Sonatrach's existing Trans-Algerian crude and product pipeline network, forcing bespoke metallurgy and pressure-rating compromises.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Algeria Oil and Gas Downstream Market |
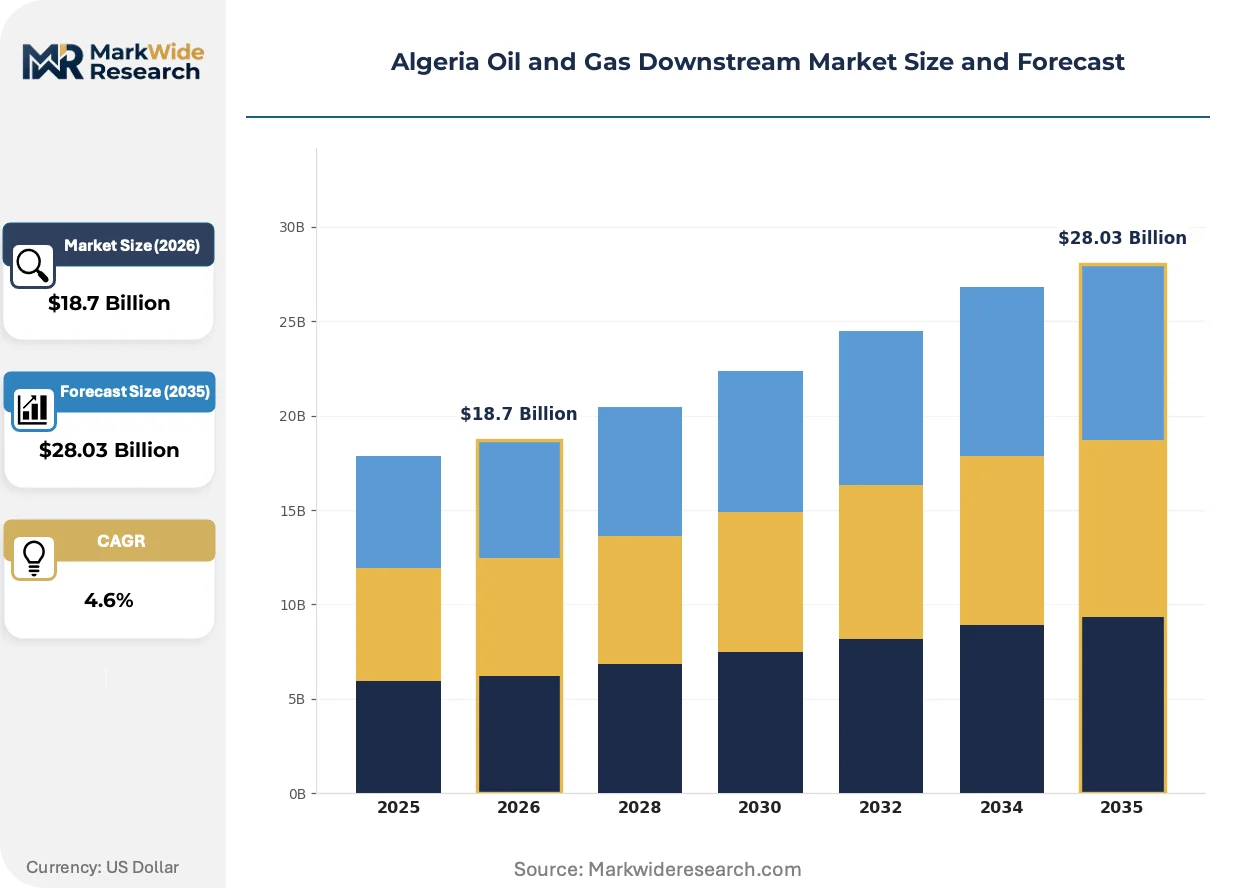
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Oil, Petrochemicals, Lubricants, LPG End User: Power Plants, Automotive Industry, Manufacturing Sector, Residential Consumers Distribution Channel: Retail Outlets, B2B Sales, Online Platforms, Direct Sales Service Type: Transportation, Storage, Refining, Maintenance |
| Companies Covered | Sonatrach SA, TotalEnergies, China National Petroleum Corporation, Tecnicas Reunidas SA, Samsung Engineering Co Ltd, Eni, BP, ExxonMobil, Chevron, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Algeria Oil and Gas Downstream Market Strategic Shifts
Digital process control and modular construction methods are compressing project delivery timelines across Algeria's downstream expansion wave, while regulatory pressure on emissions intensifies technology substitution.
Residue upgrading technologies including ebullated-bed hydrocracking are displacing conventional coking units in new Algerian refinery designs. Sonatrach's engineering teams are specifying these systems for heavy crude processing at Hassi Messaoud, converting vacuum residue directly into diesel and naphtha pools rather than producing petroleum coke. This configuration is displacing merchant coke export revenue with higher-value liquid product yields.
Algeria's environmental authority has tightened refinery emissions standards to align with Mediterranean environmental protocols, forcing sulfur recovery unit investments that capture acid gas streams. Operators now face mandatory continuous emissions monitoring and quarterly reporting thresholds that previous grandfathered facilities avoided. The Hassi Messaoud industrial corridor is responding with combined Claus and tail-gas treatment installations that push sulfur recovery above 99.8 percent.
Refinery procurement teams are consolidating maintenance, repair, and operations contracts under multi-year integrated service agreements that bundle catalyst supply, technical services, and unit turnaround management. This model is replacing fragmented spot purchasing of individual consumables and specialty labor. European technology licensors are deploying this structure most aggressively at Sonatrach's newest complexes, embedding their personnel within operating units.
Algeria Oil and Gas Downstream Market Segmentation
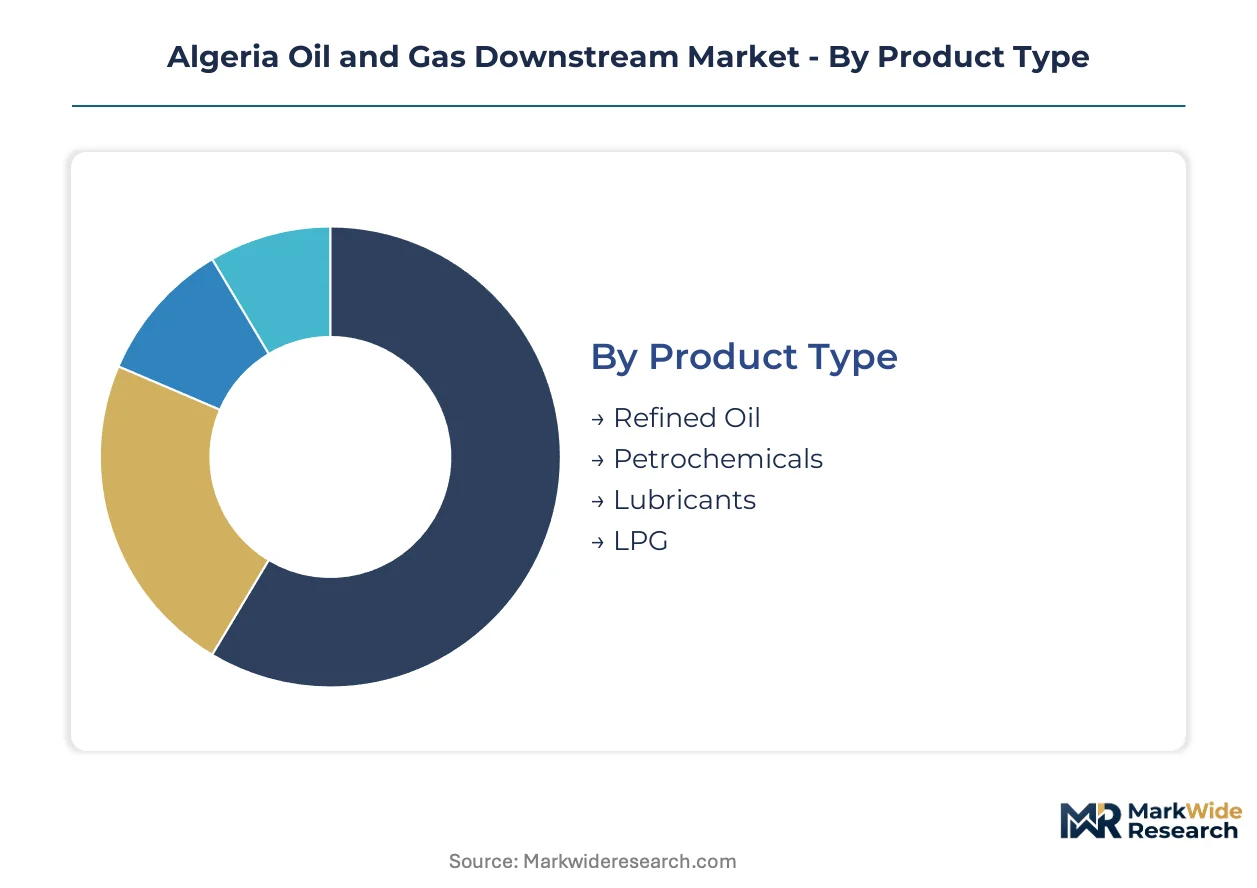
Segmentation in Algeria's downstream market reveals how state policy and infrastructure geography allocate value across product flows. Distinct channel strategies and service configurations emerge from Sonatrach's centralized control over feedstock and pipeline networks.
Product Type:
Domestic consumption anchors refined oil and LPG volumes, while petrochemicals target Mediterranean export markets through upgraded port infrastructure.
- Refined Oil:Gasoline, diesel, and jet fuel produced through atmospheric distillation and catalytic reforming units supply Algeria's transport sector under subsidized pricing regimes. Demand concentrates in coastal urban corridors from Algiers to Oran, where vehicle density and industrial activity outpace interior regions.
- Petrochemicals:Ethylene, propylene, and aromatics derived from naphtha cracking and natural gas liquids processing feed plastics and fertilizer manufacturing. Expansion runs fastest at Arzew and Skikda complexes, where Sonatrach's integration with European technology partners enables derivative exports to Southern Europe.
- Lubricants:Base oils blended with additive packages serve industrial machinery and automotive fleets across Algerian manufacturing zones.
- LPG:Propane and butane fractions from gas processing plants supply residential cooking and heating through bulk distribution networks concentrated in northern population centers.
Refined oil commands the established base. The steepest expansion runs through petrochemicals.
End User:
Industrial offtake scales with manufacturing investment cycles, while residential demand tracks household energy access programs in Algeria's northern tier.
- Power Plants:Fuel oil and natural gas derivatives fire thermal generation capacity serving Algeria's national grid. Demand clusters at coastal facilities near Skikda and Annaba, where combined-cycle plants anchor baseload supply to eastern industrial zones.
- Automotive Industry:Gasoline and diesel formulations meeting Euro-equivalent specifications supply a vehicle fleet exceeding four million units. Consumption concentrates in Algiers and Oran metropolitan areas, where traffic congestion and commercial transport density drive per-capita fuel intensity.
- Manufacturing Sector:Process heat and feedstock requirements from cement, steel, and food processing industries absorb middle distillates and natural gas liquids.
- Residential Consumers:LPG cylinders and kerosene serve cooking and heating needs in urban apartments and rural settlements lacking pipeline gas connections.
Automotive offtake dominates volume flows. Manufacturing sector consumption is climbing fastest as industrial diversification accelerates.
Distribution Channel:
Channel structure reflects the split between state-controlled retail fuel networks and negotiated bulk contracts for industrial buyers.
- B2B Sales:Long-term supply agreements with manufacturing enterprises, power generators, and agricultural cooperatives lock in predictable volumes at formula pricing tied to international benchmarks. These contracts concentrate margin capture with Sonatrach's trading arm, bypassing retail infrastructure costs.
- Retail Outlets:Branded and independent service stations distribute gasoline and diesel to vehicle owners across Algeria's national road network. Site density correlates with population corridors, with highest throughput on the Algiers-Oran and Algiers-Constantine axes.
- Direct Sales:Large industrial consumers receive pipeline or dedicated truck deliveries from refinery gate, minimizing intermediate handling.
- Online Platforms:Emerging digital ordering systems for LPG cylinder delivery and lubricant procurement serve urban households and small workshops.
B2B sales anchor revenue stability. Digital platform penetration is expanding most quickly in Algiers and Oran metro zones.
Service Type:
Service segmentation tracks capital intensity, with refining and storage commanding fixed asset deployment against operational maintenance spend.
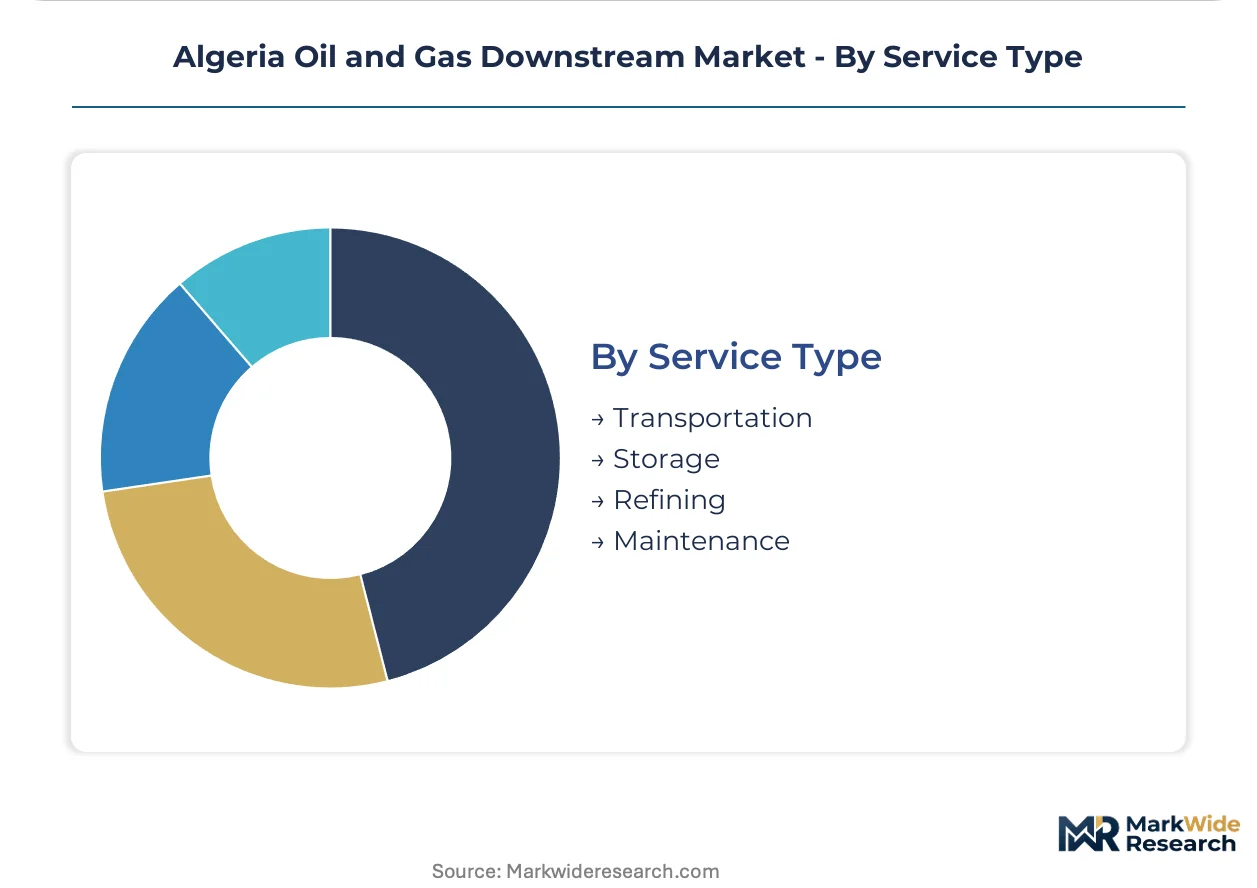
- Refining:Crude distillation, conversion, and treating operations at Hassi Messaoud, Skikda, and Arzew complexes transform upstream feedstock into specification products. Capacity utilization rates determine national product balance and import dependency for middle distillates.
- Transportation:Pipeline, rail, and coastal tanker movements connect production sites with consumption centers and export terminals. The Trans-Algerian pipeline network moves crude south-to-north, while product pipelines serve coastal demand clusters.
- Storage:Strategic and commercial tankage at ports and inland depots buffers supply disruptions and seasonal demand swings.
- Maintenance:Turnaround services, catalyst replacement, and integrity management sustain unit reliability and emissions compliance.
Refining operations absorb the dominant capital share. Maintenance services are gaining priority as environmental enforcement tightens and unit ages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Algeria's national hydrocarbon regulator anchors downstream investment decisions across North Africa's largest refining economy. Sonatrach's feedstock allocation authority under revised hydrocarbon law shapes where capacity expansion concentrates. Mediterranean port infrastructure upgrades at Arzew and Skikda determine export competitiveness for refined products and petrochemical derivatives.
Hassi Messaoud Industrial Corridor
Crude distillation and conversion units anchor Algeria's refining capacity in this central desert zone. The national hydrocarbon regulator's production-sharing contract terms direct European engineering contractor mobilization to greenfield sites. Sonatrach's newest refinery complexes here deploy residue upgrading technologies that displace conventional coking units.
Arzew Petrochemical Complex
Ammonia and urea production facilities capture natural gas liquids previously flared at this western coastal hub. Algeria's environmental authority enforces sulfur recovery mandates that push operators toward tail-gas treatment investments. Mediterranean export terminals here enable direct fertilizer shipments to Southern European agricultural markets.
Skikda Refining and Power Generation Zone
Combined-cycle thermal plants and coastal refineries cluster at this eastern port city serving national grid baseload. State-mandated fuel subsidies sustain refined product demand from automotive and industrial offtakers across the coastal corridor. Pipeline connections to the Trans-Algerian network integrate Skikda with southern crude production fields.
Oran Industrial Corridor
Port infrastructure upgrades at this northwestern hub enable refined product exports bypassing congested eastern terminals. Bulk LPG distribution networks concentrate here to serve residential cooking demand in surrounding urban settlements. Manufacturing sector process heat requirements absorb middle distillates delivered through dedicated pipeline connections.
Algiers Metropolitan Demand Center
Vehicle fleet density exceeding four million units concentrates gasoline and diesel consumption in this northern coastal capital. Retail outlet networks along the Algiers-Oran and Algiers-Constantine axes record highest throughput volumes nationally. Digital platform penetration for LPG cylinder delivery is expanding most quickly in this metro zone.
Algeria Oil and Gas Downstream Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across Algeria's downstream expansion wave. State-operator dominance through feedstock control creates a consolidated upstream-refining nexus, while international EPC contractors compete on execution efficiency for greenfield construction. Two strategic archetypes define competitive positioning: integrated state enterprises leveraging captive crude allocation, and specialized engineering contractors exporting construction methodologies from European and Asian home markets. Dominant competitive moves center on strategic partnerships for technology transfer and capacity expansion through large-scale EPC contracts.
Among state-backed integrated operators, Sonatrach SA occupies the anchor position through its control of domestic refining capacity and upstream feedstock allocation. European technology partners exemplified by TotalEnergies sit within the joint-venture tier that ties European process licensing to local content compliance. At the execution-focused end, Samsung Engineering Co Ltd represents Asian EPC contractors competing on modular construction efficiency and compressed project delivery timelines for Hassi Messaoud greenfield builds.
| Leading Market Players |
|---|
| Sonatrach SA |
| TotalEnergies |
| China National Petroleum Corporation |
| Tecnicas Reunidas SA |
| Samsung Engineering Co Ltd |
| Eni |
| BP |
| ExxonMobil |
| Chevron |
| Others |
Value Chain & Pricing Dynamics
Refinery capacity utilization rates above 85 percent at Hassi Messaoud complexes concentrate supply-side leverage with Sonatrach's trading arm, compressing price floors for middle distillates while elevating margin capture on petrochemical derivatives exported through Mediterranean terminals.
Pricing Analysis
Coastal-to-interior price spreads of 8-12 percent reflect transport cost differentials on the Trans-Algerian pipeline network, with Algiers and Oran metropolitan zones commanding premium throughput volumes. Pricing stratifies across export-grade petrochemicals, subsidized domestic transport fuels, and bulk industrial LPG contracts tied to international benchmark formulas. Cost compression in refined product tiers is intensifying because state-mandated subsidy caps suppress recovery rates, while industrial buyers under long-term offtake agreements exhibit lowest price sensitivity due to formula-linked pass-through mechanisms.
Supply Chain Analysis
Mediterranean port congestion at Arzew and Skikda terminals elevates inbound logistics costs for hydrocracking catalysts sourced from German and US specialty chemical suppliers, with container availability tightening on Asia-Europe trade lanes. Manufacturing concentration rests on Italy and Spain for engineering contractor labor pools, Germany and the US for process catalysts, and South Korea for modular construction components. Single-source vulnerability permeates the catalyst supply tier, where proprietary formulations from two dominant licensors create bottleneck exposure. Distribution runs through Sonatrach's pipeline network for crude feedstock and product movements, with coastal tanker exports handling petrochemical derivatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among state-linked industrial offtakers locking in decade-long petrochemical supply agreements, fragmenting negotiating leverage for smaller distributors dependent on spot market access.
For Market Incumbents: Fortify feedstock allocation authority through deeper integration with Hassi Messaoud upstream processing complexes, embedding proprietary sulfur recovery and residue upgrading technologies that emerging Asian EPC contractors cannot replicate. Prioritize multi-year integrated service contracts bundling catalyst supply with technical services to lock out European technology licensors seeking direct operator relationships. For New Entrants and Emerging Players: Differentiate on digital twin deployment and modular construction methodologies that compress commissioning timelines for greenfield refinery builds, targeting the Oran industrial corridor where port infrastructure upgrades outpace established eastern terminal capacity. Penetrate through specialized commissioning engineer staffing services, addressing the acute talent shortage that Algerian technical universities cannot supply at scale. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors engineering contractors with proven residue upgrading and emissions compliance capabilities rather than pure-play refining operators exposed to subsidy reform risk. Long-term viability hinges on petrochemical integration depth and European technology transfer relationships. The inflection signal to monitor is Sonatrach's feedstock allocation priority shifts between refined product export commitments and domestic fertilizer feedstock integration at Arzew.| Strategic Initiative | Industry Significance |
|---|---|
| Residue Upgrading Technology Deployment | Ebullated-bed hydrocracking configurations at Hassi Messaoud displace petroleum coke yields with higher-value diesel and naphtha pools. |
| Sulfur Recovery Unit Investment | Combined Claus and tail-gas treatment installations push recovery above 99.8 percent under tightened Algerian environmental authority mandates. |
| Integrated Service Agreement Consolidation | Multi-year contracts bundling catalyst supply and turnaround management replace fragmented spot purchasing at Sonatrach's newest complexes. |
| Digital Twin Process Simulation | Advanced modeling reduces commissioning timelines for Asian EPC contractors executing greenfield builds in the Hassi Messaoud corridor. |
| Mediterranean Port Infrastructure Expansion | Arzew and Skikda terminal upgrades enable direct refined product and fertilizer exports to Southern European agricultural markets. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, incorporating perspectives from Sonatrach engineering directors, European EPC contractor project managers, Algerian environmental authority compliance officers, and industrial offtake procurement leads at fertilizer and power generation complexes. Secondary validation drew from Algerian hydrocarbon regulator production-sharing contract disclosures, Sonatrach annual activity reports, Mediterranean port authority throughput statistics, and European engineering trade association capacity surveys. Bottom-up project pipeline assessments triangulated against top-down macroeconomic demand modeling.
Across the analysis window, forecasts deployed segmented growth accounting across product type tiers, end-user industry verticals, distribution channel structures, and service type categories. CAGRs were derived from capacity utilization trajectories, subsidy reform scenario weighting, and petrochemical integration investment cycles. Key inputs included crude slate quality assumptions for Hassi Messaoud heavy crude processing, European engineering labor availability curves, and sulfur recovery mandate compliance cost schedules.
Material uncertainties — subsidy reform timing, European contractor labor mobility restrictions, and catalyst supply chain disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding Sonatrach capital allocation priorities and Algerian hydrocarbon law enforcement consistency. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Brazil Wireline Logging Services Market
Oil & Gas
Oil and Gas Cloud Applications Market
Oil & Gas
Rig-Less Intervention Service Market
Oil & Gas
Polycrystalline Diamond Compact (PDC) Drill Bit Market
Oil & Gas
Frac Stack Market
Oil & Gas
Oil and Gas Pipeline Coatings Market
Oil & Gas
South America Oil and Gas Hoses and Coupling Market
Oil & Gas
Thermal Spray Coating for Oil and Gas Market
Oil & Gas
Global Floating LNG Terminal Market
Oil & Gas
Underwater Monitoring System for Oil and Gas Market
Oil & Gas
Oil and Gas Industry Turbomachinery Market
Oil & Gas
Coal Bed Methane Market
Oil & Gas
Oman Directional Drilling Market
Oil & Gas
Managed Pressure Drilling Services Market
Oil & Gas
Shale Shakers Market
Oil & Gas
Singapore LNG Storage Tank Market