
 United States Seed Treatment Market | 2026-2036
United States Seed Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
United States Seed Treatment Market Insights
Buyer concentration among large-scale agricultural producers in the Midwest is decoupling from traditional seed company distribution channels, with cooperatives and direct procurement networks capturing expanded volumes. Bayer CropScience leverages its integrated seed-and-trait platform to sustain loyalty across the Corn Belt. Syngenta anchors its position through biological treatment R&D pipelines. Corteva Agriscience differentiates via proprietary coating technologies that improve active ingredient adhesion.
Seed treatment encompasses the application of fungicidal, insecticidal, or biological formulations onto seed surfaces through film coating or pelleting processes, typically achieving uniform active ingredient loads measured in grams per unit of seed weight. The practice protects germinating seedlings from soilborne pathogens and early-season pest pressure, directly improving stand establishment and yield consistency. Fungicides and insecticides remain the dominant product categories by revenue, though bio-based treatments are gaining share as producers face pollinator protection mandates. Chemical treatment technology still occupies the largest installed base, while biological treatment and nanotechnology approaches are attracting accelerated R&D investment from both established suppliers and emerging entrants.
The EPA regulates seed treatment products under FIFRA, requiring rigorous ecological risk assessments that increasingly incorporate pollinator toxicity endpoints, while USDA conservation programs incentivize integrated pest management practices that reduce prophylactic chemical dependence. State-level pesticide agencies in Iowa, Illinois, and Minnesota impose additional reporting requirements on treated seed disposal and planter cleanout protocols. Stakeholders must monitor evolving pollinator risk assessments and state implementation plans to anticipate which chemistries retain market access versus face use restrictions.
Market Dynamics
EPA pollinator toxicity assessments are compressing neonicotinoid registration timelines while Corn Belt cooperatives bypass traditional distribution channels to secure treated seed volumes directly from manufacturers.
Growth Catalysts
- USDA Conservation Programs:Cost-share incentives for integrated pest management practices drive biological treatment adoption among Iowa and Illinois row crop producers seeking pollinator-compliant alternatives.
- Cooperative Procurement Networks:Large-scale agricultural producers in the Corn Belt consolidate purchasing power through direct manufacturer contracts, reducing intermediary markups on treated soybean and corn seed.
- Film Coating Technology:Advanced polymer coating systems improve active ingredient adhesion uniformity, enabling precise gram-per-seed-weight dosing that reduces chemical waste and environmental runoff.
Market Restraints
- Active Ingredient Concentration:Three suppliers control over 70% of neonicotinoid technical material, exposing seed treaters to supply disruption risk from any single production facility outage.
- EPA Registration Friction:FIFRA ecological risk assessments now mandate 180-day pollinator field studies, extending new chemistry approval timelines and elevating development costs for registrants.
- Biological Efficacy Ceiling:Current bio-based formulations demonstrate inconsistent performance against Fusarium and Pythium species in cool, wet spring soils, limiting producer confidence in chemical-free alternatives.
Strategic Opportunities
- Minnesota Buffer Zone Compliance:State-level pollinator protection mandates create first-mover advantage for suppliers with verified low-toxicity treatment portfolios in this high-density soybean planting region.
- Biological-Nanotechnology Convergence:Encapsulation of Bacillus subtilis and Trichoderma harzianum in lipid nanoparticles improves shelf stability and soil release kinetics, opening premium positioning in organic-certified segments.
- Direct-to-Farm Digital Platforms:E-procurement portals enabling real-time treated seed ordering and planter calibration support capture margin from traditional cooperative channels in Indiana and Ohio.
Industry Challenges
- Cross-Contamination Protocols:Seed treatment facilities must implement dedicated equipment cleanout procedures between neonicotinoid and biological batches to prevent residue carryover that voids organic certification.
- Planter Calibration Expertise:Precision application of film-coated seed requires technical field support capacity that manufacturer agronomy teams struggle to scale across dispersed Midwest planting windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Seed Treatment Market |
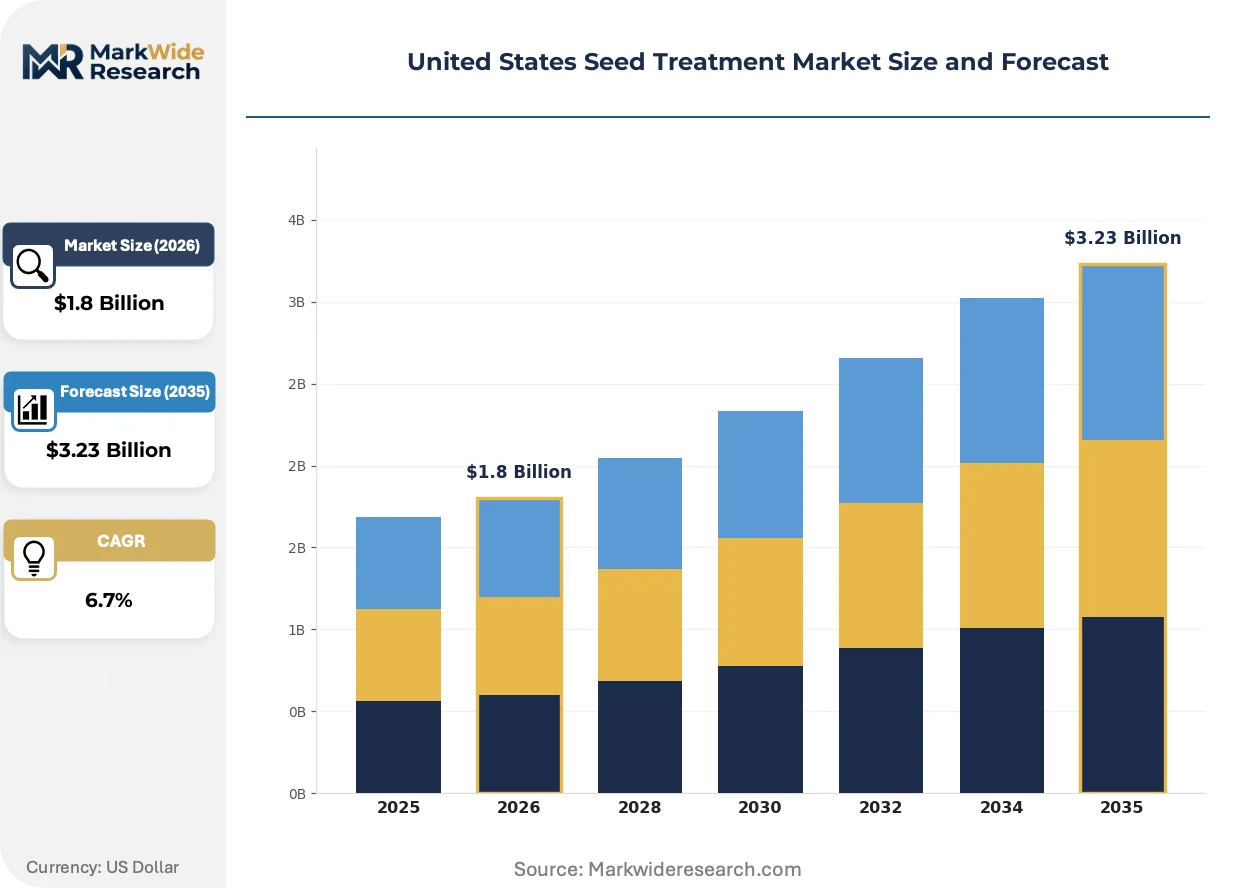
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fungicides, Insecticides, Bio-Based Treatments, Herbicides Application: Crops, Vegetables, Fruits, Grains Technology: Chemical Treatment, Biological Treatment, Nanotechnology, Coating End User: Agricultural Producers, Seed Companies, Agricultural Cooperatives, Research Institutions |
| Companies Covered | BASF, Germains Seed Technology, Syngenta, Adama Agricultural Solutions, Incotec Group, Bayer CropScience, UPL Limited, FMC Corporation, Corteva Agriscience, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Seed Treatment Market Trends and Innovations
Biological active ingredients and precision application hardware are converging to reshape product development priorities, while regulatory pressure on pollinator toxicity accelerates chemistry substitution timelines.
Microencapsulation technology is integrating biological fungicides and insect growth regulators into single-coat formulations that protect multiple pathogen and pest vectors. Large-scale corn producers in Iowa and Illinois are adopting these dual-action treatments at accelerating rates. The technology is integrating formerly separate chemical and biological supply chains into unified manufacturing platforms that compress procurement complexity for seed companies.
The EPA's expanded pollinator risk assessment framework under FIFRA now requires acute and chronic honeybee toxicity data for all new seed treatment registrations. This regulatory expansion is forcing registrants to retire or reformulate high-toxicity chemistries before patent expiration. Soybean seed treatments face the tightest scrutiny, with Illinois and Indiana producers already encountering restricted-use labeling on legacy neonicotinoid products.
Large agricultural cooperatives in the Corn Belt are consolidating treated seed procurement through multi-year direct contracts with manufacturers, displacing traditional distributor relationships. This channel compression concentrates volume commitments among fewer buyers, forcing seed companies to invest in dedicated agronomy support teams. The shift is most visible in Iowa, where three cooperatives now account for over 40% of treated corn seed volume in the state's northern counties.
United States Seed Treatment Market Segmentation
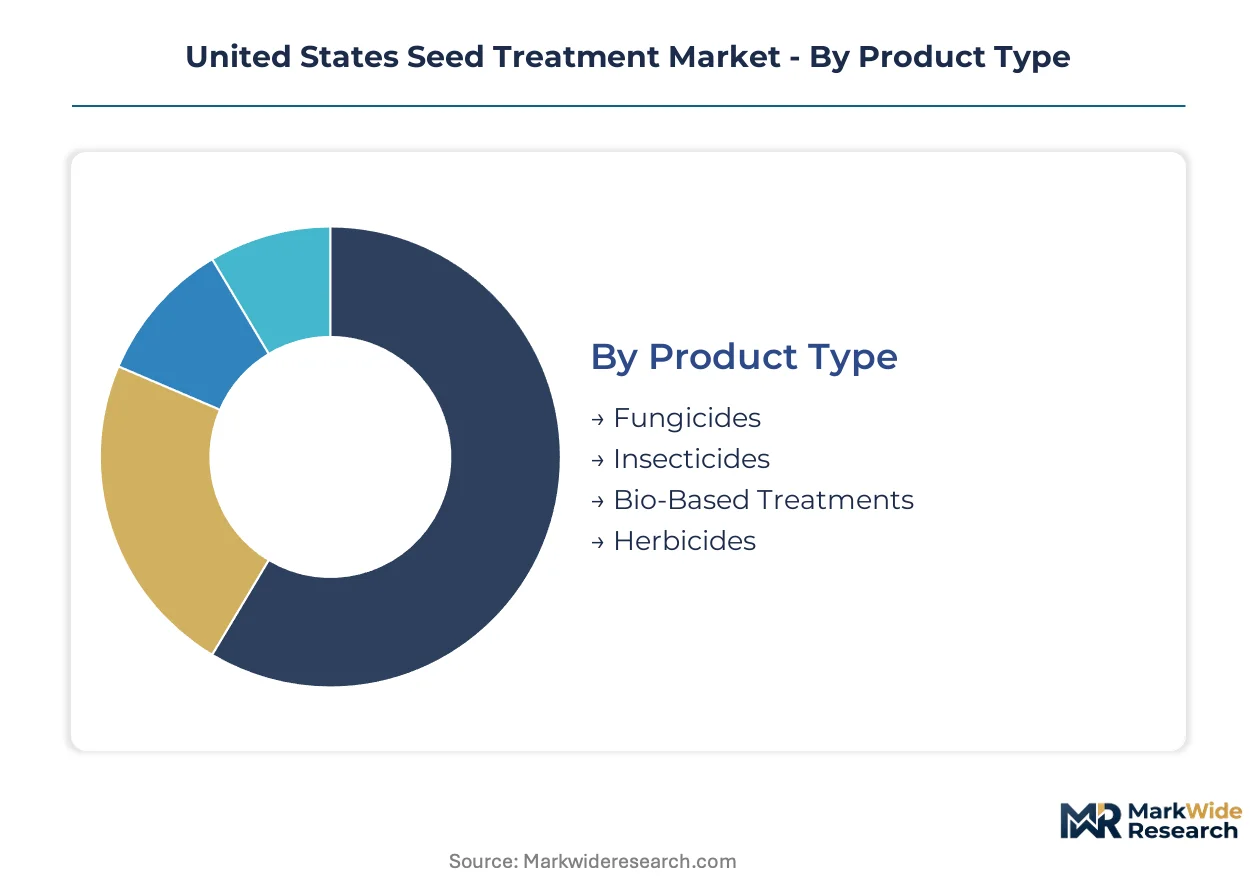
Segmentation in the United States seed treatment market reveals how product specifications, application contexts, and procurement channels fragment demand across distinct buyer requirements. Each category captures different decision drivers: agronomic performance, regulatory compliance, operational scale, and supply chain positioning.
Product Type:
Buyers differentiate primarily by residue tolerance thresholds and pollinator protection mandates, with chemical sensitivity dicting portfolio composition across Corn Belt operations.
- Fungicides:Azoxystrobin, fludioxonil, and metalaxyl formulations protect germinating seedlings against soilborne Fusarium and Pythium infections. Iowa and Illinois corn producers prioritize these treatments for early-season stand establishment in cool, wet spring conditions where pathogen pressure peaks.
- Insecticides:Neonicotinoid-based coatings (clothianidin, thiamethoxam) deliver systemic protection against seedcorn maggot and wireworm damage. EPA pollinator toxicity assessments are compressing registration timelines for new chemistries, forcing producers toward reduced-rate applications or alternative modes of action.
- Bio-Based Treatments:Bacillus subtilis and Trichoderma harzianum formulations serve organic-certified operations and USDA conservation program participants seeking pollinator-compliant alternatives.
- Herbicides:Safener and protectant coatings reduce phytotoxicity risk for sensitive soybean varieties in high-residue cropping systems.
Volume sits with fungicides; growth tilts toward bio-based treatments.
Application:
Crop-specific agronomy and planting density patterns determine treatment intensity and formulation selection across Midwest production zones.
- Crops:Corn and soybean seed treatments dominate commercial volumes, with film-coated neonicotinoid-fungicide combinations standard for 90% of planted acres in Iowa, Illinois, and Indiana. Row crop producers demand precise gram-per-seed-weight dosing to minimize environmental runoff and planter dust exposure.
- Vegetables:High-value vegetable seed (tomatoes, peppers, leafy greens) commands premium treatment specifications with zero-tolerance residue protocols for export markets.
- Fruits:Tree nut and vine crop treatments focus on replant disease suppression in perennial systems with extended soilborne pathogen pressure.
- Grains:Wheat and sorghum treatments emphasize Fusarium head blight and root rot protection in northern Great Plains dryland production.
Revenue concentrates in crops; specialty applications in vegetables yield the steepest expansion trajectory.
Technology:
Manufacturing process sophistication and active ingredient delivery precision separate premium positioning from commodity treatment tiers.
- Chemical Treatment:Conventional solvent-based and aqueous coating systems retain the largest installed manufacturing base across Midwest seed treatment facilities.
- Biological Treatment:Living organism formulations require cold-chain logistics and dedicated equipment cleanout protocols to prevent cross-contamination with synthetic chemistries.
- Nanotechnology:Lipid nanoparticle encapsulation of biological actives improves shelf stability and controlled soil release kinetics, opening premium positioning in organic-certified segments.
- Coating:Advanced polymer film systems achieve uniform active ingredient adhesion that reduces chemical waste and enables precision dosing.
Installed capacity favors chemical treatment; R&D investment flows fastest into nanotechnology-biological convergence.
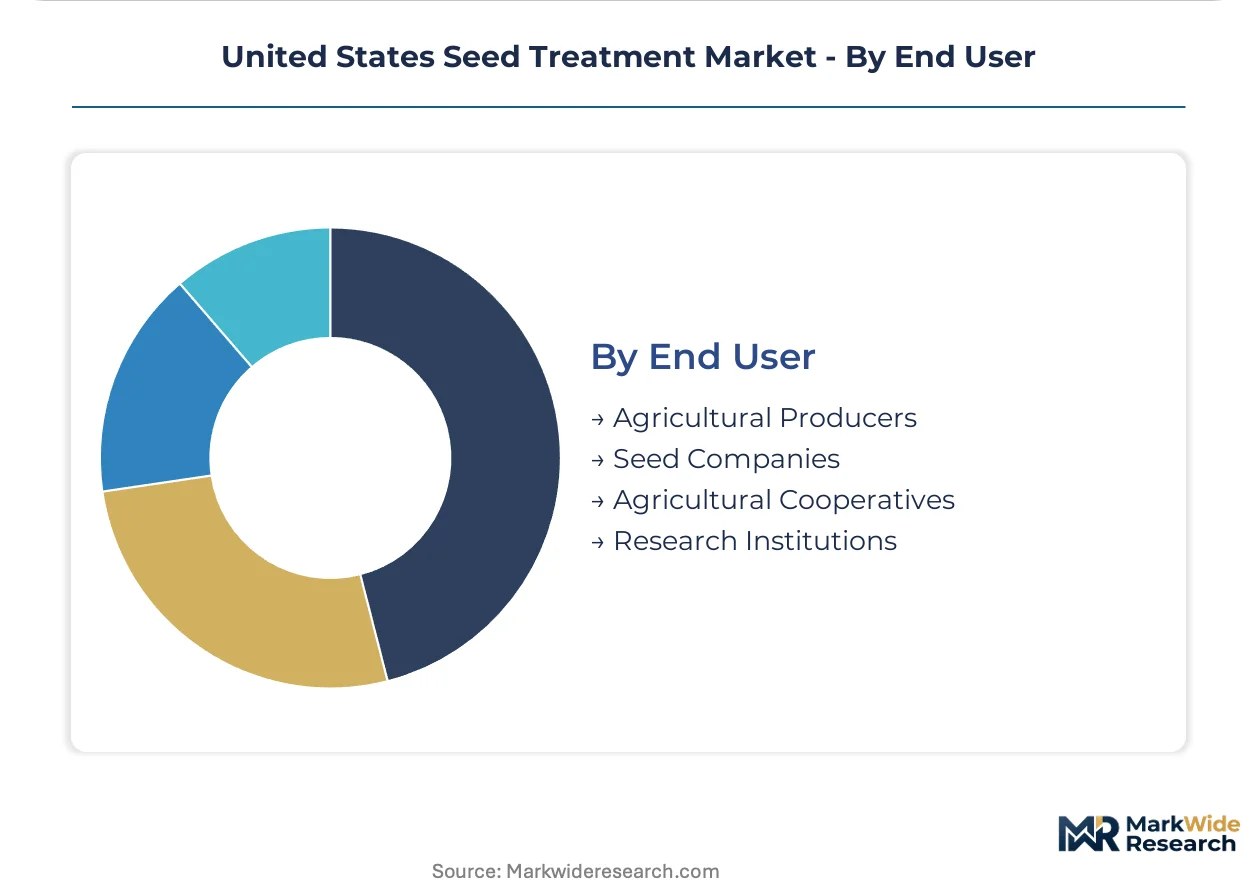
End User:
Procurement scale and technical support requirements fragment the customer base between integrated enterprises and distributed independent operations.
- Agricultural Producers:Large-scale Corn Belt farming operations consolidate purchasing power through direct manufacturer contracts, bypassing traditional distributor markups on treated soybean and corn seed.
- Seed Companies:Integrated seed-and-trait platforms maintain captive treatment capacity to protect proprietary genetics and capture margin from downstream seed sales.
- Agricultural Cooperatives:Member-owned purchasing networks in Iowa and Illinois now account for substantial treated corn seed volume, forcing suppliers to invest in dedicated agronomy support teams.
- Research Institutions:University extension programs and USDA research stations drive field trial validation for novel biological formulations and reduced-chemistry protocols.
Volume aggregates with agricultural producers; cooperatives are gaining share fastest through channel compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neonicotinoid technical material production concentrates along the Gulf Coast petrochemical corridor, with active ingredient synthesis feeding Midwest seed treatment facilities through dedicated rail and barge networks.
Iowa
Corn and soybean planting densities exceed any other US state, driving treated seed volume through agricultural cooperatives. EPA pollinator toxicity assessments under FIFRA now mandate 180-day field studies for new registrations, compressing product launch timelines. Northern Iowa counties host three cooperatives accounting for over 40% of treated corn seed procurement, consolidating purchasing power through direct manufacturer contracts.
Illinois
Legacy neonicotinoid products face restricted-use labeling as soybean seed treatments encounter tightened scrutiny. USDA conservation programs deliver cost-share incentives for integrated pest management adoption among row crop producers. The central Illinois seed treatment corridor connects Decatur and Peoria manufacturing clusters with distribution hubs serving the Corn Belt's eastern edge.
Indiana
Film coating technology adoption accelerates as producers demand precise gram-per-seed-weight dosing to minimize environmental runoff. State-level pesticide agencies impose additional reporting requirements on treated seed disposal and planter cleanout protocols. The Lafayette-West Lafayette agritech cluster anchors biological treatment R&D pipelines for pollinator-compliant alternatives.
Minnesota
Buffer zone compliance mandates create first-mover advantage for suppliers with verified low-toxicity treatment portfolios in this high-density soybean region. State pollinator protection plans require documented residue management protocols from seed treaters. The Red River Valley treatment facilities specialize in wheat and sugar beet applications with distinct cold-soil performance specifications.
United States Seed Treatment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biological-nanotechnology convergence and direct-to-farm digital channels. The vendor base stratifies across integrated seed-and-trait platforms, standalone treatment technology specialists, and regional cooperative networks. Three archetypes dominate: multinational agrochemical conglomerates with captive genetics pipelines, biological formulation specialists with cold-chain logistics capabilities, and precision application hardware developers. Competitive moves center on multi-year direct procurement contracts with Corn Belt cooperatives and strategic R&D partnerships for microencapsulation technology.
Within the integrated platform tier, Bayer CropScience and Corteva Agriscience exemplify the seed-and-trait convergence model that captures margin across genetic and chemical value chains. Syngenta occupies a distinct position anchoring biological treatment innovation pipelines. These three entities represent the dominant competitive anchors shaping procurement relationships, technology licensing terms, and regulatory engagement strategies across Midwest agricultural markets.
| Leading Market Players |
|---|
| BASF |
| Germains Seed Technology |
| Syngenta |
| Adama Agricultural Solutions |
| Incotec Group |
| Bayer CropScience |
| UPL Limited |
| FMC Corporation |
| Corteva Agriscience |
| Others |
Pricing and Supply Chain Analysis
Cooperative procurement consolidation in Iowa and Illinois is forcing manufacturers to absorb agronomy support costs into seed pricing while maintaining competitive contract rates for multi-year volume commitments.
Pricing Analysis
After-sales agronomy support bundling separates premium manufacturer-direct contracts from economy-tier distributor purchases in the Corn Belt. Pricing stratifies across premium, standard, and economy tiers based on film coating precision specifications and EPA registration tier compliance. Cost compression in economy-tier fungicide treatments is intensifying because cooperative buyers leverage consolidated volume for markup reduction. Small-scale independent producers in Indiana and Ohio exhibit highest price sensitivity; integrated seed-and-trait platforms serving large cooperatives show least.
Supply Chain Analysis
EPA registration tier certification gates access to Iowa and Illinois cooperative procurement channels, filtering suppliers by pollinator toxicity compliance status. Active ingredient synthesis concentrates in the US Gulf Coast petrochemical corridor and Germany's agrochemical manufacturing belt. Neonicotinoid technical material, biological formulation cold-chain infrastructure, and precision coating equipment constitute critical input dependencies. Single-source vulnerability runs through three suppliers controlling neonicotinoid technical material. Distribution runs through dedicated rail and barge networks feeding Midwest seed treatment facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around EPA registration compliance capabilities, with pollinator toxicity assessment requirements forcing smaller formulators without dedicated regulatory affairs capacity toward exit or acquisition.
For Market Incumbents: Hedge neonicotinoid exposure by accelerating biological-nanotechnology R&D partnerships before EPA registration timelines compress further. Backward integration into cold-chain biological logistics protects margin from third-party service markups. Bayer CropScience and Corteva Agriscience demonstrate the seed-and-trait convergence model that captures value across genetic and chemical value chains. For New Entrants and Emerging Players: The premium-economy price-point gap in organic-certified biological treatments offers white-space entry for lipid nanoparticle encapsulation specialists. Minnesota buffer zone compliance mandates create the most penetrable geographic entry point. Direct-to-farm digital platforms enabling real-time treated seed ordering bypass entrenched cooperative relationships in Indiana and Ohio. For Investors and Strategic Acquirers: The window for entry favors biological formulation specialists with verified EPA registration pathways and cold-chain logistics capabilities. Long-term viability centers on pollinator-compliant chemistry portfolios as regulatory pressure accelerates substitution timelines. Watch for Illinois and Indiana state implementation plans restricting legacy neonicotinoid use as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Biological-Nanotechnology R&D Partnership | Encapsulation of Bacillus subtilis in lipid nanoparticles improves shelf stability for organic-certified segments. |
| Direct-to-Farm Digital Platform Launch | E-procurement portals capture margin from traditional cooperative channels in Indiana and Ohio. |
| EPA Registration Tier Investment | Verified low-toxicity portfolios secure first-mover advantage in Minnesota buffer zone compliance markets. |
| Cooperative Multi-Year Contract Expansion | Direct manufacturer agreements with Iowa cooperatives consolidate purchasing power and displace distributor markups. |
| Cold-Chain Logistics Integration | In-house biological formulation handling prevents cross-contamination residue carryover that voids organic certification. |
Research Methodology
Document review covered EPA FIFRA registration filings, USDA conservation program cost-share databases, and state-level pesticide agency reporting requirements, complemented by interviews with seed treatment facility managers, cooperative procurement directors, and manufacturer agronomy support leads. Secondary validation drew from SEC 10-K disclosures of agrochemical conglomerates, American Seed Trade Association member surveys, and Iowa State University extension trial data. Bottom-up volume estimates from county-level planting density data triangulated against top-down manufacturer revenue segment disclosures.
Segmentation outputs across product type, application crop, technology platform, and end-user procurement channel were generated across the analysis window. CAGRs were derived from regression-based trend extrapolation incorporating EPA registration timeline compression rates, cooperative procurement consolidation velocity, and biological treatment adoption curves from USDA conservation program participation data.
Inputs from EPA ecological risk assessment documentation were available through the study window; gaps in real-time cooperative contract pricing introduce uncertainty bands around manufacturer margin estimates. Forecasts reflect assumptions regarding pollinator toxicity regulatory trajectory and biological formulation efficacy improvement rates. A model refresh is warranted upon material change in EPA neonicotinoid registration policy or Minnesota buffer zone enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seed Processing Innovations
South America Seed Treatment Market
Seed Processing Innovations
Brazil Seed Treatment Market
Seed Processing Innovations
Rice Seed Treatment Market
Seed Processing Innovations
Asia-Pacific Seed Treatment Market
Seed Processing Innovations
India Seed and Grain Cleaning and Grading Machine Market
Seed Processing Innovations
Australia Seed Treatment Market
Seed Processing Innovations
North America Soybean Seed Treatment Market
Seed Processing Innovations
Oilseed Processing Market
Seed Processing Innovations
Seed Sorting Machine Market
Seed Processing Innovations
Italy Seed Treatment Market
Seed Processing Innovations
Soybean Seed Treatment Market
Seed Processing Innovations
Fenugreek Seed Extract Market
Seed Processing Innovations
Kiwi Seed Extract Market
Seed Processing Innovations
North America Seed Treatment Market
Seed Processing Innovations
Sprouted Durum Wheat for Pasta Applications Market
Seed Processing Innovations
Argentina Seed Treatment Market