
 United States Luxury Goods Market | 2026-2036
United States Luxury Goods Market Size, Share, and Industry Trends Forecast 2026-2036
United States Luxury Goods Market Outlook
The gap between heritage craftsmanship and mass-market premium positioning is expanding across the United States luxury goods landscape. LVMH Moët Hennessy Louis Vuitton leverages its vertical control over leather goods and wine spirits to sustain pricing power in classic luxury segments. Hermès International SA anchors its exclusivity through deliberate scarcity and artisan labor models. Kering SA competes by accelerating digital integration across Gucci and Saint Laurent while navigating wholesale rationalization.
Luxury goods encompass tangible products commanding price premiums through perceived rarity, superior materials, and symbolic social value, typically utilizing full-grain leather, precious metals, hand-stitching, or mechanical horology with tolerances measured in microns. Their commercial purpose centers on status signaling and wealth preservation rather than purely functional utility. Accessories and watches capture concentrated margin pools due to material intensity and repair-service ecosystems. Apparel faces structural pressure from casualization trends, while online retail reshapes customer acquisition economics for affluent consumers and millennials.
The FTC monitors advertising claims and anti-counterfeiting standards, while customs enforcement through CBP inspects import documentation for genuine provenance. State-level sales tax variations across California, New York, and Texas create compliance complexity for omnichannel distribution. Stakeholders must weigh digital resale authentication investments against physical flagship expansion as generational wealth transfer redefines brand loyalty parameters.
Market Dynamics
Wealth concentration in coastal metropolitan corridors is compressing customer acquisition costs for heritage houses while simultaneously intensifying price transparency pressure through digital resale platforms. The FTC's sustained scrutiny of sustainability claims and provenance advertising is forcing operational recalibration across marketing and supply chain verification functions.
Growth Catalysts
- Generational wealth transfer:Millennial and Gen Z heirs in California and New York are redirecting discretionary spending toward experiential luxury and limited-edition collaborations, expanding addressable demand beyond traditional collector demographics.
- FTC Green Guides enforcement:Stricter substantiation requirements for environmental marketing claims are accelerating investment in blockchain-based supply chain documentation, creating competitive differentiation for early adopters.
- Digital authentication infrastructure:Entrupy and similar machine-learning verification tools are reducing friction in secondary market transactions, unlocking latent inventory circulation and repeat purchase velocity among circular economy participants.
Market Restraints
- Exotic leather input volatility:CITES permitting delays and farm-to-tannery traceability mandates in Italy and France are compressing margin predictability for accessories houses dependent on crocodile and python skins.
- Artisan labor scarcity:French compagnonnage training programs and Italian leatherworking conservatories are producing fewer qualified craftspeople than retirement rates demand, constraining production scalability for hand-finished goods.
- Counterfeit platform proliferation:Social commerce algorithms on TikTok and Instagram are amplifying superfake visibility, eroding brand equity insulation that historically protected heritage pricing power.
Strategic Opportunities
- Texas and Florida wealth migration:Dallas, Houston, and Miami are absorbing high-net-worth relocations from California and New York, creating greenfield flagship expansion potential with lower commercial rent intensity than legacy coastal corridors.
- Repair and restoration services:Hermès-style atelier models for leather conditioning, hardware replacement, and patina restoration are building recurring revenue streams and lifetime value metrics independent of new product cycles.
- IRA luxury goods excise considerations:Proposed federal tax code modifications targeting high-value consumption present structuring opportunities for art-adjacent collectibles and investment-grade horology categories.
Industry Challenges
- Digital-native creative talent acquisition:Luxury houses compete with technology and entertainment sectors for 3D designers, virtual environment architects, and NFT platform specialists, compressing compensation benchmarks and retention stability.
- Omnichannel inventory harmonization:Real-time visibility across flagship boutiques, outlet networks, and digital flagship platforms demands ERP modernization that many heritage IT infrastructures cannot support without multi-year capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Luxury Goods Market |
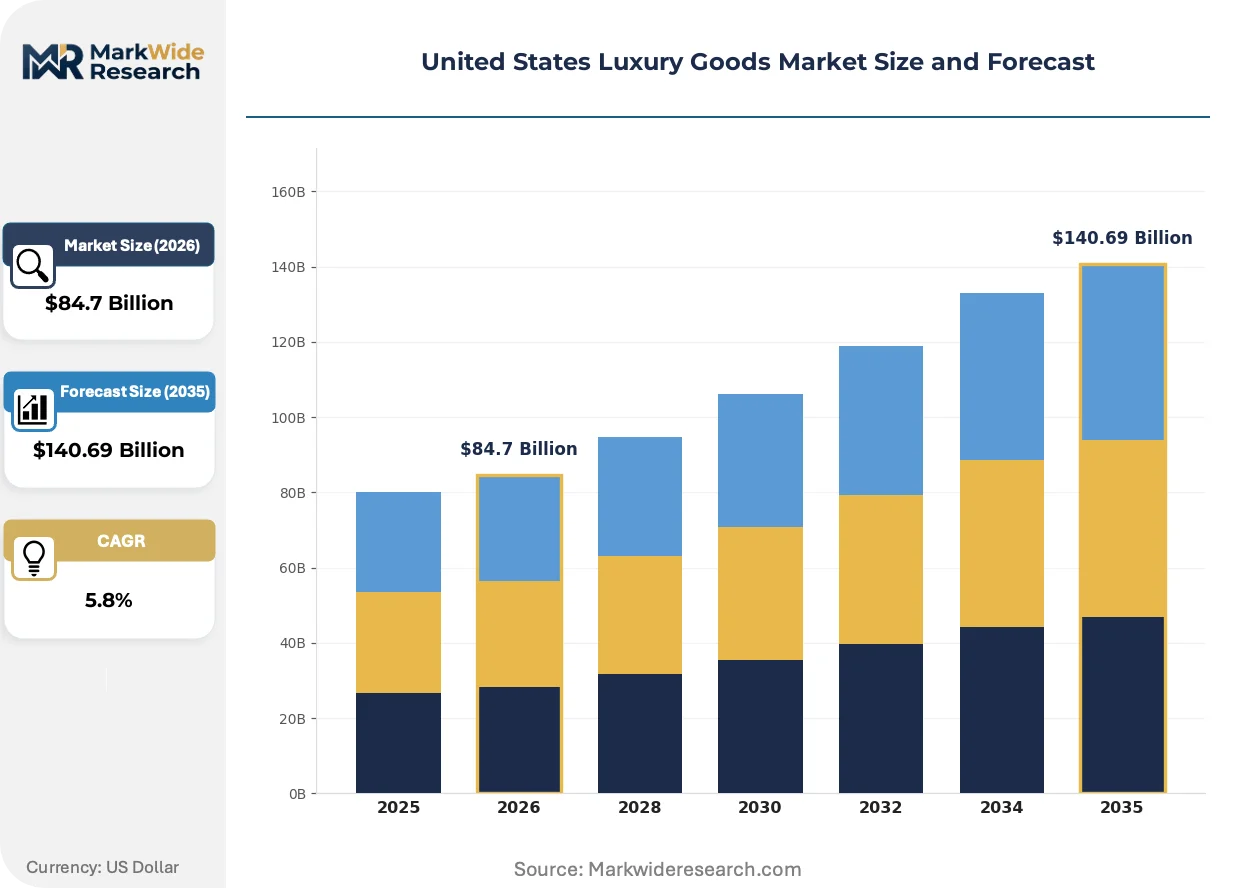
| Market Size in 2026 | $84.7 Billion |
| Market Size in 2035 | $140.69 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apparel, Footwear, Accessories, Watches Customer Type: Affluent Consumers, Millennials, High-Net-Worth Individuals, Celebrities Sales Channel: Online Retail, Department Stores, Exclusive Boutiques, Outlets Brand Positioning: Premium Brands, Designer Labels, Emerging Luxury, Classic Luxury |
| Companies Covered | Chanel Limited, Tapestry, Inc., LVMH Moët Hennessy Louis Vuitton, Fossil Group, Inc., Movado Group, Inc., Kering SA, Hermès International SA, Signet Jewelers, Compagnie Financière Richemont SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Luxury Goods Market Strategic Shifts
Digital authentication and virtual try-on capabilities are restructuring how affluent consumers evaluate provenance and fit before committing to high-value transactions. These technologies are compressing the traditional discovery-to-purchase funnel while simultaneously expanding addressable geography beyond flagship catchment areas.
Blockchain-based digital product passports are overtaking paper certificates of authenticity as the default provenance documentation standard. High-net-worth collectors in Miami and Los Angeles are demanding cryptographic ownership records transferable across secondary platforms. This shift is enabling fractional ownership models and collateralized lending against authenticated luxury assets, compressing traditional auction house intermediation.
FTC endorsement disclosure requirements under 16 CFR Part 255 are tightening compliance obligations for influencer partnerships and celebrity ambassador contracts. Marketing departments must now maintain granular documentation of material connections and performance claims substantiation. Accessories and beauty segments with heavy social media dependency are restructuring agency relationships and content approval workflows to preempt enforcement action.
Secondary market participation is shifting from stigma-driven concealment to status-affirming transparency among younger affluent buyers. The RealReal and Vestiaire Collective are displacing consignment anonymity with publicly visible seller ratings and authenticated purchase histories. This behavioral pivot is most pronounced in New York and San Francisco, where circular luxury consumption now signals environmental consciousness alongside purchasing power.
United States Luxury Goods Market Segmentation
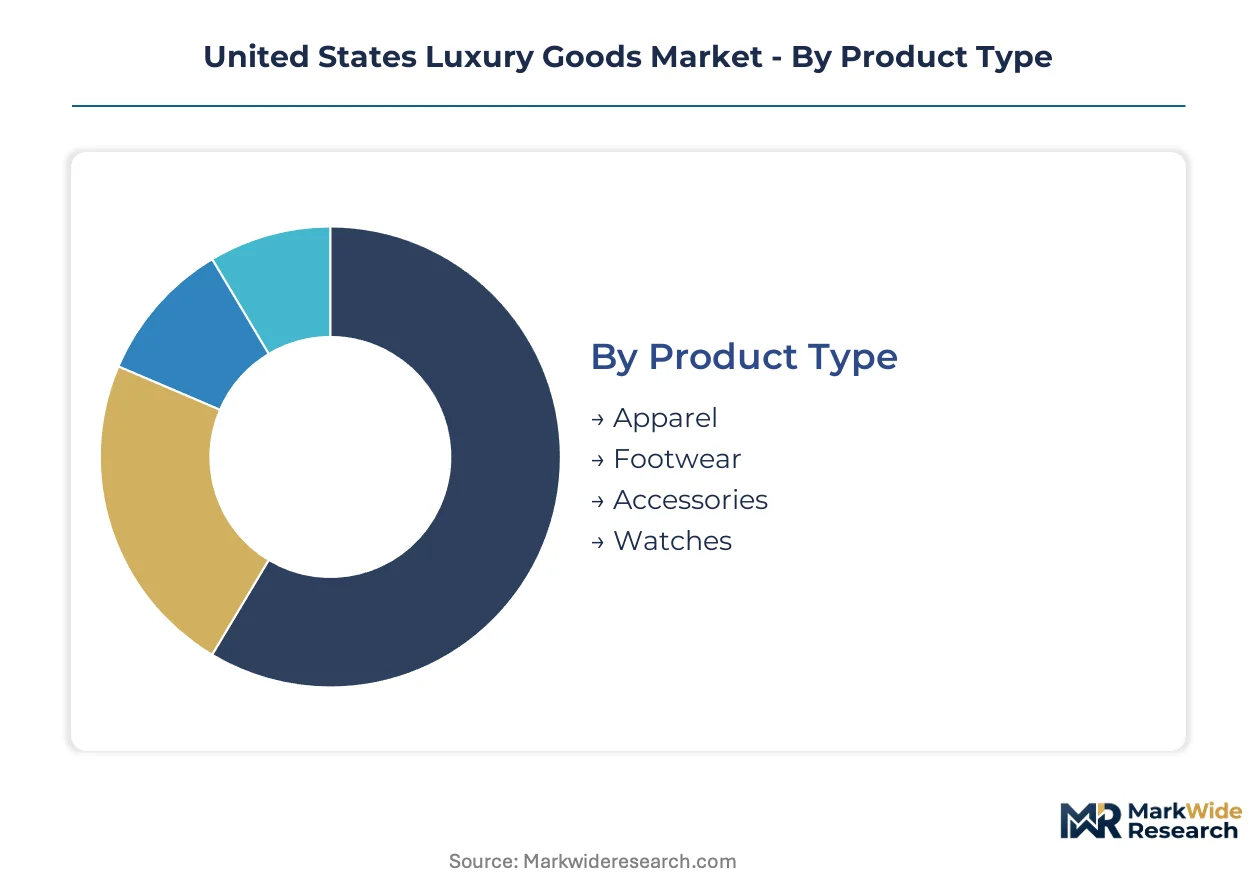
Segmentation in United States luxury goods reveals divergent margin architectures and customer lifetime value profiles. Heritage houses calibrate inventory allocation across channels and positioning tiers to protect exclusivity while capturing generational wealth transfer.
Product Type:
Material intensity and repair-service ecosystems drive buyer willingness to pay premiums across tangible luxury categories.
- Accessories:Leather goods, silk scarves, and small leather articles command concentrated margins through full-grain hides and hand-stitching tolerances measured in microns. Demand clusters in California and New York flagship corridors where wealth concentration supports experiential positioning and atelier services.
- Watches:Mechanical horology with precious metal casings and complications functions as portable wealth storage. Florida collectors and Texas energy sector executives anchor domestic demand for investment-grade timepieces with documented provenance.
- Apparel:Ready-to-wear faces structural pressure from casualization trends compressing formal occasion frequency.
- Footwear:Artisan construction methods in Italian and French manufacturing bases limit scalable production for hand-finished categories.
Accessories leads on scale; watches leads on momentum.
Customer Type:
Generational cohorts exhibit divergent channel preferences and status-signaling behaviors.
- High-Net-Worth Individuals:Ultra-affluent buyers with investable assets exceeding $30 million prioritize scarcity, bespoke services, and direct designer relationships over transactional convenience.
- Millennials:Heirs redirecting discretionary spending toward limited-edition collaborations and circular economy participation represent the steepest expansion trajectory among buyer cohorts.
- Affluent Consumers:Mass-affluent segment with household income above $250,000 sustains volume in accessible luxury tiers.
- Celebrities:Entertainment and athletic personalities function as demand amplifiers through red-carpet visibility and social media endorsement.
High-net-worth individuals anchor margin contribution; millennials drive volume acceleration.
Sales Channel:
Channel economics determine customer acquisition costs and brand control intensity.
- Exclusive Boutiques:Flagship retail in coastal metropolitan corridors enables immersive brand storytelling and atelier service integration. California, New York, and Florida wealth clustering supports flagship expansion with experiential luxury positioning.
- Online Retail:Digital flagship platforms compress discovery-to-purchase funnels while expanding geography beyond physical catchment areas. FTC endorsement disclosure requirements under 16 CFR Part 255 reshape influencer partnership compliance.
- Department Stores:Wholesale partnerships dilute margin capture but sustain brand visibility in secondary markets.
- Outlets:Off-price channels liquidate seasonal inventory while risking brand equity erosion through accessibility expansion.
Exclusive boutiques dominate margin extraction; online retail captures the fastest share gain.
Brand Positioning:
Positioning tier determines pricing power elasticity and resale market depth.
- Classic Luxury:Heritage houses with century-plus histories leverage vertical control over supply chains and deliberate scarcity models to sustain pricing power. Artisan labor scarcity in French compagnonnage programs constrains production scalability.
- Designer Labels:Contemporary fashion houses balance creative velocity with commercial accessibility through seasonal collection turnover.
- Premium Brands:Accessible luxury segments compete on material quality and craftsmanship signaling at lower entry price points.
- Emerging Luxury:New entrants and direct-to-consumer disruptors challenge incumbent positioning through digital-native customer acquisition and sustainability transparency.
Classic luxury commands pricing authority; emerging luxury expands addressable reach fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Artisan leatherworkers and horological craftspeople cluster in specific metropolitan corridors where wealth concentration supports atelier service models. The FTC's Green Guides enforcement and state-level tax variations reshape distribution economics across coastal and Sun Belt markets. Flagship expansion concentrates where high-net-worth migration patterns intersect with experiential retail infrastructure.
California
Silicon Valley technology executives and entertainment industry principals drive demand for limited-edition collaborations and bespoke accessories. California's Proposition 65 labeling requirements for chemical content in leather goods force supply chain documentation investments. Los Angeles and San Francisco anchor flagship density with experiential positioning and atelier services for patina restoration.
New York
Financial services wealth and generational heirs sustain concentrated spending on investment-grade timepieces and heritage leather goods. New York's Department of Financial Services monitors luxury lending practices and collateralized asset verification standards. Manhattan's Madison Avenue and SoHo districts host flagship corridors where circular economy platforms like The RealReal authenticate secondary market circulation.
Florida
Retired executives and Latin American wealth migration fuel demand for precious metal horology and yacht-adjacent accessories. Florida's lack of state income tax attracts high-net-worth relocations from Northeast corridors. Miami's Design District and Bal Harbour host experiential flagships targeting collectors from Mexico, Colombia, and Brazil.
Texas
Energy sector executives and technology relocations from California redirect discretionary spending toward classic luxury positioning. Texas's franchise tax structure and absence of personal income tax reduce operational costs for flagship expansion. Dallas's Highland Park Village and Houston's River Oaks concentrate boutique development with lower commercial rent intensity than coastal equivalents.
Illinois
Midwestern manufacturing wealth and professional services partnerships sustain demand for accessible luxury tiers and corporate gifting categories. Illinois's use tax enforcement on out-of-state digital purchases complicates omnichannel compliance for heritage houses. Chicago's Magnificent Mile retains flagship presence despite population outmigration to Sun Belt alternatives.
United States Luxury Goods Market Competitive Environment
Capital-heavy producers with captive tanneries and vineyard estates compete with asset-light designers licensing brand equity through manufacturing partnerships. The United States market structures around three tiers: heritage houses with century-plus vertical control, contemporary conglomerates managing portfolio diversification, and accessible luxury platforms scaling through wholesale rationalization. Dominant competitive moves include deliberate scarcity calibration to protect pricing power and digital authentication infrastructure investments to capture secondary market circulation velocity.
Within the heritage house tier, Hermès International SA and Chanel Limited exemplify artisan labor models and deliberate production constraints that sustain exclusivity. LVMH Moët Hennessy Louis Vuitton occupies a position spanning wine spirits, leather goods, and jewelry through vertical integration across multiple luxury categories. Kering SA and Tapestry, Inc. represent conglomerate structures balancing creative velocity with commercial accessibility across portfolio brands. These archetypes anchor competitive dynamics where pricing power derives from scarcity engineering rather than manufacturing scale alone.
| Leading Market Players |
|---|
| Chanel Limited |
| Tapestry, Inc. |
| LVMH Moët Hennessy Louis Vuitton |
| Fossil Group, Inc. |
| Movado Group, Inc. |
| Kering SA |
| Hermès International SA |
| Signet Jewelers |
| Compagnie Financière Richemont SA |
| Others |
Value Chain & Pricing Dynamics
Captive control over French and Italian tanneries anchors supply security for heritage houses while simultaneously underwriting pricing power through scarcity engineering and material provenance documentation. This integration choice insulates margin architecture from commodity volatility but concentrates geographic risk exposure in European artisan labor markets.
Pricing Analysis
Bundled atelier services and unbundled product-only transactions now split the United States luxury goods pricing architecture. Three-tier pricing structure across classic luxury, designer label, and accessible premium levels segments buyers by wealth tier and occasion frequency. Price differentiation rests on artisan labor intensity and blockchain-backed provenance certification. Pricing pressure stems from digital resale platform transparency compressing information asymmetry. Mass-affluent consumers exhibit highest price sensitivity, while ultra-high-net-worth collectors remain elasticity-insensitive to incremental premiums for bespoke services.
Supply Chain Analysis
Dual-sourcing mandates from corporate procurement departments and family office investment committees now require heritage houses to qualify backup tanneries in Italy and Spain alongside primary French suppliers. Raw material dependencies center on full-grain hides from French livestock farms, precious metals from Swiss refiners, and exotic skins subject to CITES permitting delays. Supply chain risk concentrates in single-source vulnerability for compagnonnage-trained artisans whose replacement training cycles span multiple years. Distribution runs through flagship boutiques in coastal metropolitan corridors, with digital flagship platforms capturing fastest downstream share expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in United States luxury goods rest on circular economy service revenue and generational wealth transfer capture, with repair-service ecosystems and secondary market authentication infrastructure compressing customer acquisition costs.
For Market Incumbents: Deepen captive control over artisan training pipelines through direct sponsorship of French compagnonnage programs and Italian leatherworking conservatories. Accelerate blockchain-based digital product passport deployment to preempt FTC Green Guides enforcement actions on sustainability claim substantiation. Fortify secondary market authentication partnerships with Entrupy and similar machine-learning verification platforms to capture circular economy velocity.
For New Entrants and Emerging Players: Direct-to-consumer digital flagships and social commerce-native brand building offer the most penetrable route into millennial and Gen Z buyer cohorts. Target Texas and Florida wealth migration corridors where commercial rent intensity trails California and New York equivalents. Deploy sustainability transparency and supply chain documentation as primary go-to-market differentiation against heritage house opacity.
For Investors and Strategic Acquirers: Roll-up economics work for regional boutique networks and authenticated resale platforms because customer lifetime value metrics in luxury goods span decades rather than quarters. Long-term viability favors asset-light digital authentication infrastructure over capital-heavy captive manufacturing. Watch secondary market transaction velocity as the signal to monitor for inflection in brand equity insulation.
| Strategic Initiative | Industry Significance |
|---|---|
| Atelier Service Expansion | Recurring revenue from Hermès-style repair and restoration builds lifetime value independent of product cycles. |
| Blockchain Provenance Deployment | Digital product passports preempt FTC enforcement while enabling fractional ownership and collateralized lending. |
| Texas and Florida Flagship Buildout | Lower commercial rent intensity in Dallas and Miami corridors captures wealth migration from coastal markets. |
| Artisan Training Pipeline Sponsorship | Direct investment in French compagnonnage programs addresses labor scarcity constraining production scalability. |
| Secondary Market Authentication Partnership | Machine-learning verification tools unlock circular economy participation among environmentally conscious affluent buyers. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with brand executives, atelier directors, luxury retail buyers, and high-net-worth collectors with secondary validation. Primary sources included heritage house supply chain managers, digital authentication platform engineers, and family office investment officers overseeing collectible asset allocation. Secondary data drew from FTC enforcement actions, CITES permitting databases, customs import documentation, and circular economy platform transaction records. Bottom-up demand modeling and top-down macroeconomic triangulation anchored market sizing.
Comparable-period anchoring tied projection frameworks to historical performance across pre-pandemic, pandemic-disrupted, and post-recovery reference windows. Segmentation dimensions modeled included product type, generational cohort, channel architecture, and regional wealth concentration patterns. CAGRs derived from trend extrapolation adjusted for structural shifts in digital adoption and regulatory enforcement intensity. Forecast inputs incorporated artisan labor supply constraints, exotic leather permitting delays, and generational wealth transfer velocity assumptions.
Regulatory enforcement intensity, exotic material permitting disruptions, and counterfeit platform proliferation are the dominant revision risks. Forecasts reflect documented assumptions on wealth migration patterns and digital authentication adoption curves. Deviation in FTC Green Guides enforcement severity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Goods
Accessible Luxury Goods Market
Luxury Goods
India Lab Grown Diamond Jewelry Market
Luxury Goods
Spain Luxury Jewelry Market
Luxury Goods
North America Luxury Goods Market
Luxury Goods
GCC Luxury Goods Market
Luxury Goods
Singapore Luxury Goods Market
Luxury Goods
Middle East and Africa Luxury Goods Market
Luxury Goods
GCC Secondhand Luxury Goods Market
Luxury Goods
France Luxury Goods Market
Luxury Goods
Brazil Luxury Goods Market
Luxury Goods
Luxury Products for Kids Market
Luxury Goods
China Luxury Goods Market
Luxury Goods
Qatar Luxury Good Market
Luxury Goods
UAE Luxury Jewelry Market
Luxury Goods
Thailand Luxury Goods Market
Luxury Goods
United Arab Emirates Luxury Goods Market