
 Accessible Luxury Goods Market | 2026-2036
Accessible Luxury Goods Market Size, Share, and Industry Trends Forecast 2026-2036
Accessible Luxury Goods Market Insights
Aftermarket authentication and resale platform revenue is reshaping how value circulates in accessible luxury. LVMH anchors its position through vertical control over tanneries and atelier networks. Sézane differentiates via direct-to-consumer digital channels that bypass traditional wholesale markups.
Accessible luxury goods occupy the price tier between mass-market and heritage couture, typically retailing from two hundred to fifteen hundred dollars and employing calibrated materials such as full-grain leather, organic cotton, and precision-milled hardware to signal quality without prohibitive cost. Apparel and handbags capture the largest margin pools due to higher perceived value and repeat purchase frequency, while footwear competes on technical construction and comfort engineering. Online retail leads volume growth among distribution channels, though showrooms sustain conversion rates through tactile experience.
REACH in Europe and EPA guidelines in the United States govern chemical disclosure and tanning effluent standards, pushing suppliers toward certified dye processes and traceable hide sourcing. China's SAMR enforces labeling accuracy and anti-counterfeiting protocols that affect market entry for foreign labels. Stakeholders must monitor regulatory divergence across these jurisdictions while calibrating sourcing strategies and consumer communication.
Market Dynamics
Digital-native resale infrastructure and REACH-mandated chemical disclosure are restructuring value capture and supplier accountability across the accessible luxury tier.
Growth Catalysts
- Gen Z channel migration:First-time luxury buyers born 1997-2012 conduct discovery and purchase through social commerce platforms, compressing traditional wholesale cycles.
- REACH compliance premiums:European brands command price authority by certifying chrome-free tanning and traceable hide sourcing under ECHA disclosure mandates.
- China middle-class expansion:Domestic label competition with Western entrants in tier-two cities drives innovation in localized design and payment integration.
Market Restraints
- Hide cost volatility:Brazilian and Argentinian cattle supply fluctuations transmit directly to full-grain leather input pricing, squeezing margin at the two-hundred-dollar entry tier.
- Tannery concentration:Italian and French vegetable-tanning capacity limits volume scaling for brands seeking EU-origin material credentials.
- Synthetic leather substitution:Polyurethane and bio-based alternatives threaten perceived value differentiation in handbag and footwear categories.
Strategic Opportunities
- India market entry:Underpenetrated metro markets present whitespace for direct-to-consumer digital launch with localized sizing and climate-adapted materials.
- Aftermarket authentication services:Blockchain-backed provenance verification creates recurring revenue streams detached from primary production cycles.
- EU Green Deal alignment:CSRD reporting requirements favor early movers with circular design and take-back program infrastructure.
Industry Challenges
- Artisan skill scarcity:Atelier-trained leatherworkers and precision hardware finishers command wage premiums that outpace productivity gains in Portugal and Romania.
- Dual certification timelines:Simultaneous REACH and SAMR compliance for China-Europe product launches extends time-to-market by eight to fourteen months.
- Legacy ERP integration:Real-time inventory visibility across direct-to-consumer and wholesale channels demands middleware investment that mid-tier brands struggle to resource.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Accessible Luxury Goods Market |
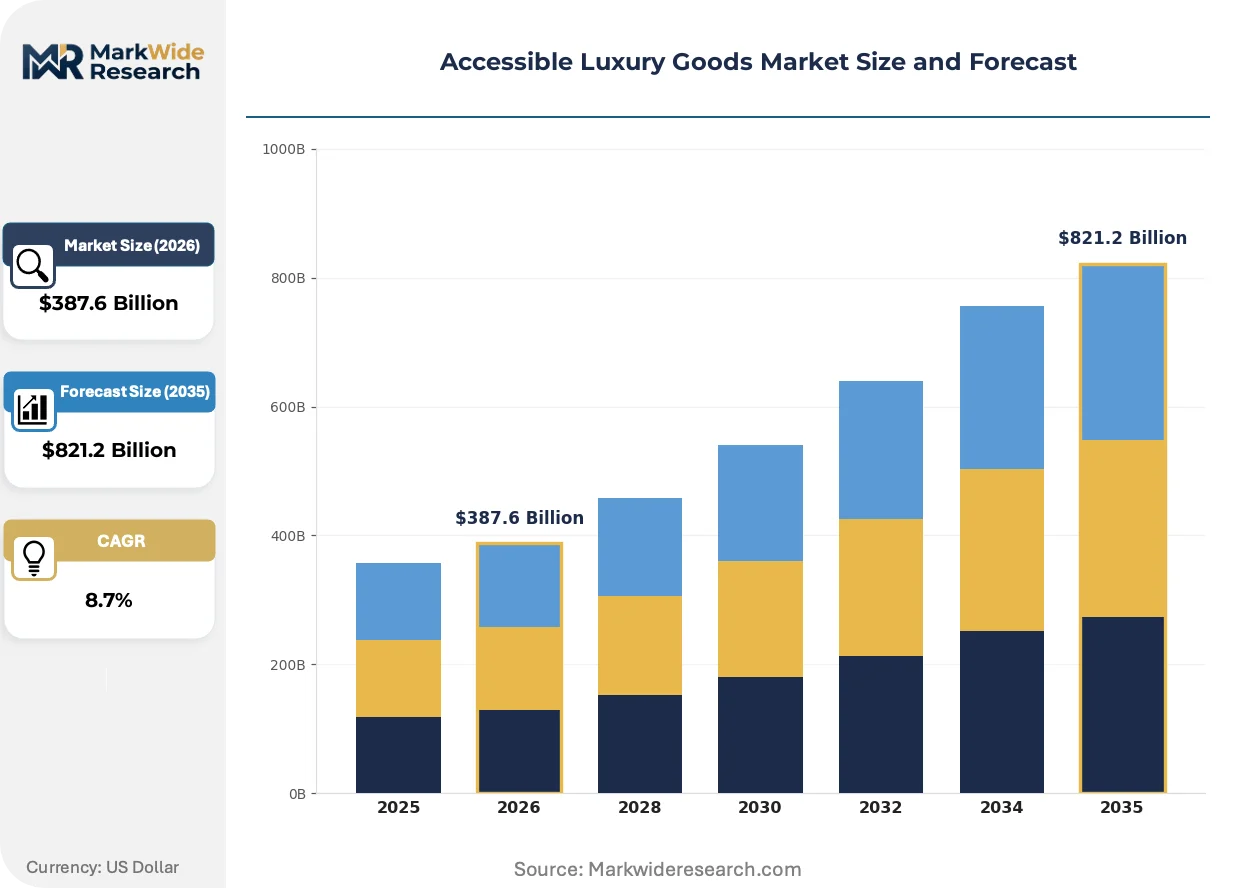
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $821.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Footwear, Handbags, Apparel, Accessories Customer Type: Millennials, Gen Z, Upper Middle Class, Professionals Distribution Channel: Online Retail, Outlets, Department Stores, Showrooms Marketing Strategy: Influencer Marketing, Social Media Campaigns, Collaboration, Limited Editions |
| Companies Covered | Sézane, Hermès, Coach, LVMH, Chanel, Marc Jacobs, Louis Vuitton, Porsche, Ralph Lauren, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Accessible Luxury Goods Market Trends and Innovations
Material science breakthroughs and regulatory transparency mandates are compressing traditional quality signaling mechanisms while opening new vectors for brand differentiation.
Mycelium-derived leather alternatives are migrating from experimental capsules to core collection staples. Kering and Stella McCartney have scaled production partnerships with Bolt Threads and Modern Meadow, while mid-tier labels adopt the material for entry-price accessories. This shift is migrating from niche sustainability marketing to mainstream cost parity, enabling brands to bypass volatile hide markets without sacrificing tactile credibility.
REACH Annex XVII restrictions on chromium VI compounds and formaldehyde-releasing agents tightened enforcement protocols in 2024. Tanneries in Veneto and Alsace invested in vegetable-tanning infrastructure to maintain EU market access. Small-batch handbag producers face disproportionate testing cost burdens, accelerating consolidation toward vertically integrated manufacturers with captive laboratory capacity.
Pre-owned platform integration now shapes primary purchase intent. Vestiaire Collective and The RealReal authentication standards influence new-buyer education, with Gen Z consumers treating resale value retention as a core selection criterion. This behavior concentrates in France and the United States, where platform density and postal infrastructure support seamless reverse logistics.
Accessible Luxury Goods Market Segmentation
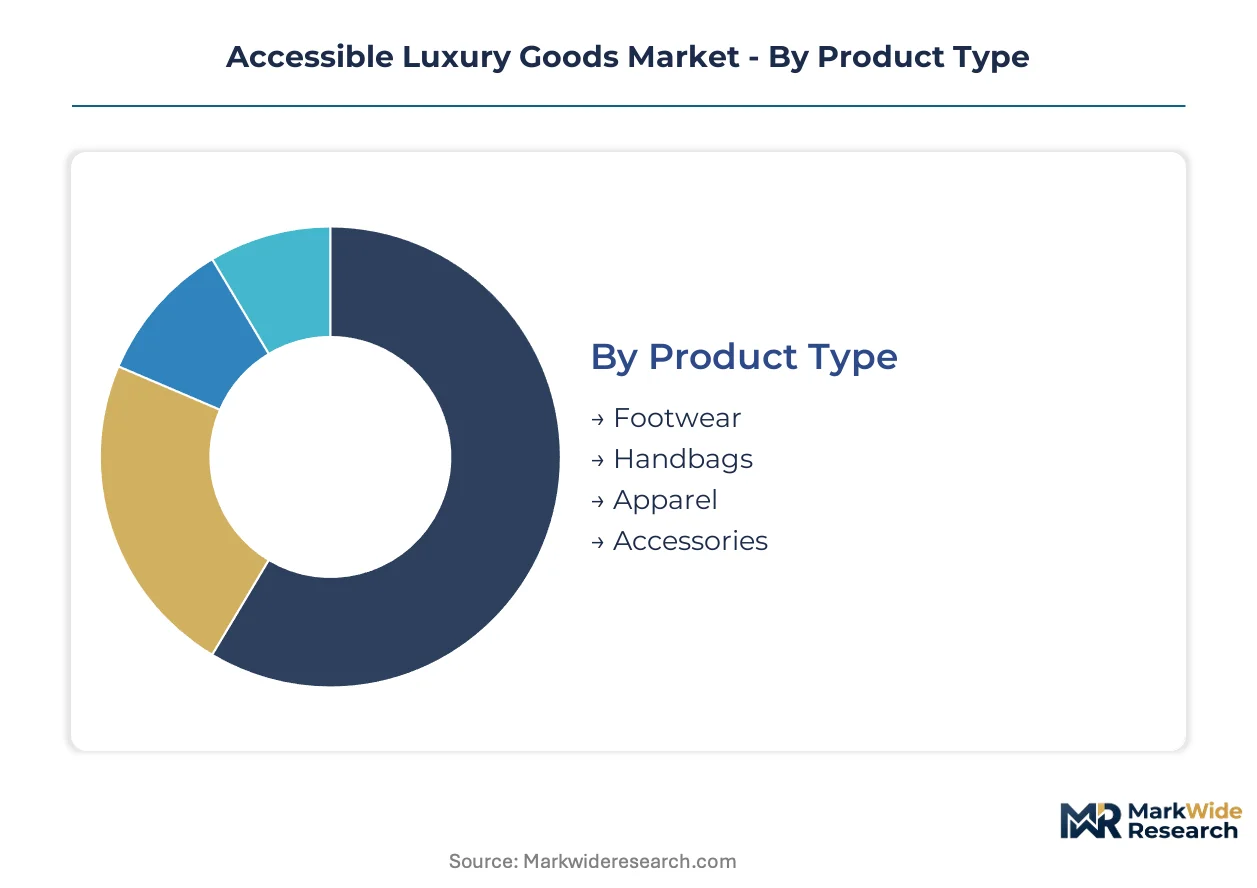
Price tier positioning and generational purchasing behavior define competitive boundaries in accessible luxury. Material calibration and channel strategy vary sharply across these divides, forcing brands to select segments rather than blanket the market.
Product Type:
Cost tier differentiation separates entry-level accessories from core collection anchors that absorb fixed atelier overhead.
- Handbags:Full-grain leather constructions with precision-milled hardware dominate margin capture. Demand concentrates in China among first-time luxury buyers who treat resale value retention as a purchase criterion.
- Apparel:Organic cotton and wool-blend tailoring signal quality without couture pricing. European consumers under REACH-mandated disclosure requirements pay premiums for certified dye processes and traceable fiber sourcing.
- Footwear:Technical construction and comfort engineering compete on specification sheets. Italian vegetable-tanned uppers face volume constraints from tannery concentration in Veneto.
- Accessories:Entry-price leather goods and small leather items complete purchase baskets. Mycelium alternatives from Bolt Threads partnerships migrate into this tier first.
Handbags command the established base. The steepest expansion runs through Apparel.
Customer Type:
Generational cohorts diverge in discovery channels, with digital-native buyers compressing traditional wholesale cycles.
- Gen Z:Born 1997-2012, this cohort conducts discovery through social commerce platforms and treats resale platform authentication standards as quality signals. Vestiaire Collective and The RealReal shape their primary purchase intent in France and the United States.
- Millennials:Established earners with repeat purchase frequency favor direct-to-consumer digital channels that bypass wholesale markups. Sézane's model captures this segment through localized sizing and climate-adapted materials.
- Upper Middle Class:Disposable income concentration in China's tier-two cities drives competition between domestic labels and Western entrants on payment integration and localized design.
- Professionals:Workplace-adjacent purchases prioritize durability credentials and repair service availability. CSRD reporting requirements from the EU Green Deal influence their preference for circular design and take-back programs.
Millennials anchor current revenue. Gen Z is gaining share fastest through channel migration velocity.
Distribution Channel:
Channel economics determine margin retention, with tactile experience sustaining conversion rates where digital volume accelerates.
- Online Retail:Volume growth leader with compressed discovery-to-purchase cycles. Real-time inventory visibility demands middleware investment that mid-tier brands struggle to resource.
- Showrooms:Tactile experience sustains conversion rates for leather goods where texture and hardware weight influence decisions. Urban concentration in Paris, Milan, and New York supports this model.
- Outlets:Off-price inventory clearance protects full-price positioning. Portuguese and Romanian production clusters feed this channel with parallel quality grades.
- Department Stores:Legacy wholesale relationships face margin pressure from direct-to-consumer migration. Remaining relevance concentrates in Japan's Isetan and China's SKP networks.
Department Stores hold the residual base. Online Retail climbs the fastest on Gen Z channel preference.
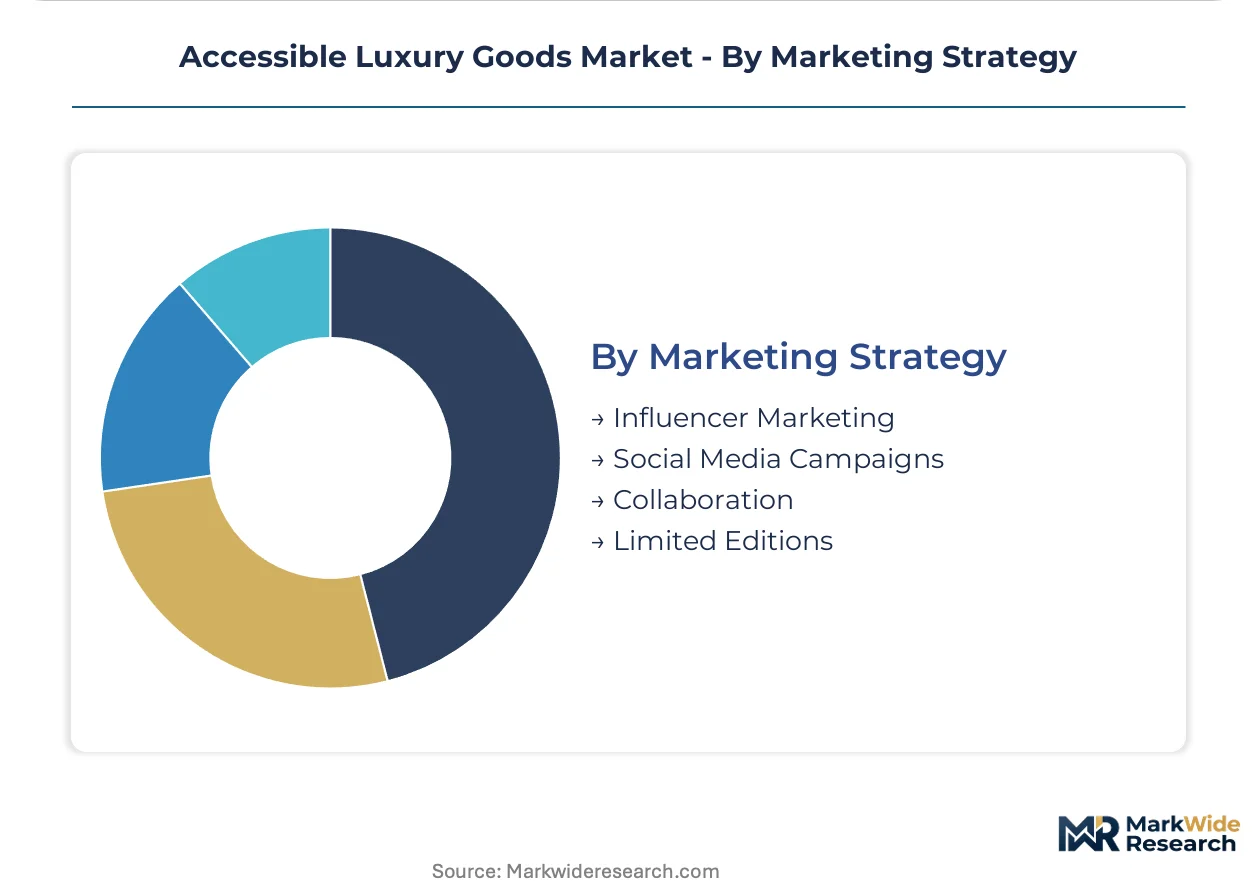
Marketing Strategy:
Engagement mechanics shift from broadcast advertising to peer-validated discovery and scarcity engineering.
- Influencer Marketing:Authenticated creator partnerships on Instagram and TikTok compress traditional campaign cycles. SAMR labeling accuracy enforcement in China affects disclosure requirements for sponsored content.
- Limited Editions:Scarcity engineering drives immediate purchase behavior and aftermarket premium. Blockchain-backed provenance verification creates recurring authentication revenue detached from production.
- Collaboration:Cross-brand capsules generate media density and access new customer files. Kering's production partnerships with Modern Meadow demonstrate material science co-branding potential.
- Social Media Campaigns:Platform-native content production costs favor vertically integrated brands with in-house creative teams. ESG messaging under CSRD requirements demands substantiation that small-batch producers struggle to document.
Social Media Campaigns retain the broadest reach. Limited Editions expand most quickly on resale platform integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese buyers demonstrate the lowest price elasticity for accessible luxury, accepting premium markups for resale value assurance, while Brazilian consumers remain highly sensitive to leather input cost fluctuations. European markets split between disclosure-driven premiums in France and Germany versus discount-seeking behavior in Southern Europe.
China
SAMR labeling accuracy enforcement and anti-counterfeiting protocols reshape competitive entry for Western labels against domestic upstarts like Songmont. Tier-two cities including Chengdu and Hangzhou concentrate middle-class expansion where payment integration and localized design determine market share. The Yangtze River Delta manufacturing cluster feeds both domestic brands and contract production for foreign entrants.
United States
Gen Z channel migration through TikTok Shop and Instagram Checkout compresses traditional wholesale cycles for handbag and apparel discovery. EPA guidelines on tanning effluent standards push California-based brands toward certified dye process documentation. New York Metro and Los Angeles sustain showroom conversion rates where tactile hardware evaluation influences purchase decisions.
France
REACH Annex XVII restrictions on chromium VI compounds accelerate vegetable-tanning infrastructure investment in Alsace and Limousin tannery clusters. Paris anchors authentication service density where Vestiaire Collective standards reshape primary purchase intent. ECHA disclosure mandates command measurable price premiums for chrome-free certified leather goods.
Italy
Veneto tannery concentration limits volume scaling for brands seeking EU-origin material credentials, creating waitlist dynamics for full-grain leather allocation. Tuscany's artisan atelier networks face wage premium pressure from Romanian and Portuguese competitor clusters. Milan showroom density sustains conversion rates for entry-price accessories where mycelium alternatives first penetrate.
India
BIS quality certification requirements and DGFT import protocols govern market entry for foreign accessible luxury labels. Mumbai and Delhi-NCR present underpenetrated whitespace for direct-to-consumer digital launch with climate-adapted material portfolios. Domestic leatherworking clusters in Kanpur and Chennai supply both export contract manufacturing and emerging local brand ecosystems.
Accessible Luxury Goods Market Competitive Landscape
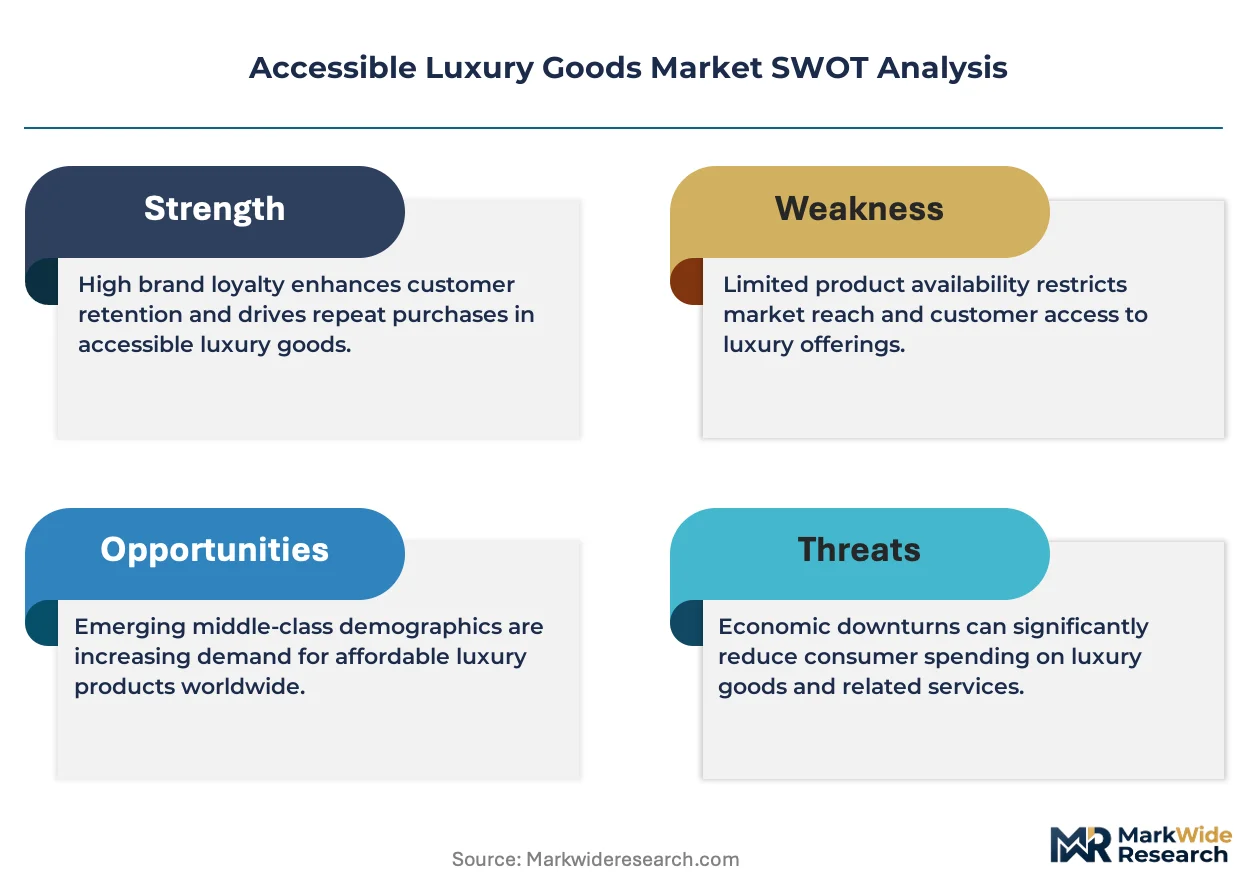
Capability concentration sits with heritage atelier networks; scale advantage sits with vertically integrated luxury conglomerates. The market structures around three tiers: captive tannery-and-retail ecosystems, direct-to-consumer digital natives, and wholesale-dependent mid-tier labels. Strategic archetypes include disclosure-premium harvesters, resale-platform orchestrators, and material-science early adopters. Dominant competitive moves encompass backward integration into hide sourcing and blockchain-backed provenance infrastructure deployment.
Within the heritage conglomerate tier, LVMH and Hermès exemplify vertical control over tannery networks and atelier capacity. Among digital-native specialists, Sézane occupies a position representing direct-to-consumer bypass of wholesale markups. These three entities anchor distinct competitive vectors: upstream supply capture, artisan scarcity preservation, and channel disintermediation.
| Leading Market Players |
|---|
| Sézane |
| Hermès |
| Coach |
| LVMH |
| Chanel |
| Marc Jacobs |
| Louis Vuitton |
| Porsche |
| Ralph Lauren |
| Others |
Pricing and Supply Chain Analysis
Italian and French vegetable-tanning capacity concentration in Veneto and Alsace tannery clusters feeds directly into margin capture at the entry-price handbag tier, where brands compete for EU-origin material credentials that command disclosure premiums under REACH mandates.
Pricing Analysis
Aftermarket authentication and resale platform revenue now drives lifetime value capture beyond the initial transaction. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and traceable hide sourcing, with chrome-free tanning commanding measurable markups in France and Germany. Cost compression in the two-hundred-dollar entry tier intensifies because Brazilian and Argentinian cattle supply fluctuations transmit directly to full-grain leather input pricing. Gen Z buyers demonstrate the lowest price elasticity when resale value retention is assured, while Brazilian consumers remain highly sensitive to leather input cost volatility.
Supply Chain Analysis
Extended payment terms from Italian tanneries to Portuguese and Romanian production clusters finance working capital across the mid-tier brand ecosystem. Geographic supply concentration centers on Italy for vegetable-tanned uppers, China for hardware and synthetic alternatives, and Brazil for raw hide sourcing. Raw material dependencies rest on full-grain leather, precision-milled hardware, and emerging mycelium-derived alternatives from Bolt Threads partnerships. Single-source vulnerability in Veneto tanning capacity creates allocation waitlists during demand spikes. Distribution runs through direct-to-consumer digital channels that bypass traditional wholesale markups, though showrooms sustain conversion rates in Paris, Milan, and New York.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Accessible luxury sits in early-cycle expansion as Gen Z channel migration through social commerce platforms compresses traditional wholesale discovery cycles and accelerates volume growth.
For Market Incumbents: Harden tannery network control through captive laboratory capacity for REACH and SAMR compliance testing, reducing dual certification timelines that currently extend time-to-market. Deepen artisan atelier relationships in Portugal and Romania before wage premiums for leatherworkers outpace productivity gains. Mycelium-derived alternatives from Modern Meadow partnerships threaten perceived value differentiation and demand rapid response through material science co-branding. For New Entrants and Emerging Players: Build out direct-to-consumer digital infrastructure targeting India's underpenetrated Mumbai and Delhi-NCR metro markets, where BIS quality certification requirements create barrier advantages for early movers with climate-adapted material portfolios. Localized sizing and payment integration capture whitespace that domestic brands currently serve. Blockchain-backed provenance verification offers a defensible go-to-market angle that resonates with resale-platform-educated buyers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across atelier-trained leatherworker networks and precision hardware finishing capacity. Long-term viability favors vertically integrated specialists with captive tannery access and circular design infrastructure aligned to CSRD reporting requirements. Acquisition targets should demonstrate EU Green Deal readiness through take-back program deployment. The signal to watch is consolidation velocity among small-batch handbag producers facing disproportionate REACH testing cost burdens.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tannery Networks | Captive hide sourcing and chrome-free certification capacity secures REACH-compliant material allocation priority. |
| Blockchain Provenance Infrastructure Deployment | Vestiaire Collective and The RealReal authentication standards reshape Gen Z primary purchase intent and aftermarket revenue. |
| Mycelium Material Science Partnership | Bolt Threads and Modern Meadow production scaling enables cost parity with volatile hide markets without tactile credibility loss. |
| Direct-to-Consumer Digital Channel Expansion | Sézane's bypass of wholesale markups captures Millennial repeat purchase frequency through localized sizing. |
| Circular Design and Take-Back Program Launch | CSRD reporting requirements from the EU Green Deal favor early movers with substantiated ESG documentation. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with brand managers, category buyers at retailers, channel sales heads, and supply planners; and secondary validation through customs records, SEC filings, ECHA disclosure databases, and retail audit data. Bottom-up demand modeling across product type, customer cohort, and distribution channel combined with top-down macroeconomic triangulation anchored volume and value estimates.
Forecast inputs considered generational purchasing behavior shifts, regulatory disclosure mandate timelines, and material substitution curves across the projection horizon. Segmentation dimensions modeled include price tier positioning, generational cohort, channel economics, and geographic regulatory cluster. CAGRs were derived through trend extrapolation adjusted for penetration ceiling effects and adoption S-curve positioning. Hide cost volatility indices and tannery capacity utilization rates fed industry-specific forecast sensitivity.
Practitioners should monitor REACH enforcement intensity, SAMR labeling protocol updates, and mycelium production scale-up milestones for early signals of forecast revision. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Goods
United States Luxury Goods Market
Luxury Goods
GCC Secondhand Luxury Goods Market
Luxury Goods
Luxury Piano Market
Luxury Goods
Mens Watch Market
Luxury Goods
Europe Secondhand Luxury Goods Market
Luxury Goods
Italy Luxury Goods Market
Luxury Goods
Luxury Pen Market
Luxury Goods
Germany Luxury Goods Market
Luxury Goods
India Watch Market
Luxury Goods
Thailand Luxury Goods Market
Luxury Goods
Luxury Goods Market
Luxury Goods
Used Luxury Bags Trading Service Market
Luxury Goods
Brazil Luxury Goods Market
Luxury Goods
Europe Handbags Market
Luxury Goods
Secondhand Luxury Goods Market
Luxury Goods
United Kingdom Luxury Goods Market