
 Middle East and Africa Luxury Goods Market | 2026-2036
Middle East and Africa Luxury Goods Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Luxury Goods Market Outlook
EU Green Deal compliance requirements for imported finished goods is rebalancing procurement priorities among Middle East and Africa luxury distributors. LVMH Moet Hennessy Louis Vuitton leverages its vertically controlled leather goods supply chain to preempt carbon disclosure mandates. Kering anchors its regional competitiveness through audited sustainability reporting that satisfies European parent-company standards. Cartier specializes in gemstone traceability protocols that exceed baseline regulatory thresholds.
Luxury goods comprise meticulously crafted apparel, accessories, footwear, and jewelry characterized by superior materials, artisanal construction, and price premiums anchored to scarcity and heritage value. These products serve commercial purposes centered on status signaling, wealth preservation, and experiential consumption across ultra-high-net-worth and aspirational buyer segments. Jewelry commands the deepest margin pools due to raw material appreciation and bespoke commission structures, while online distribution channels represent the fastest-growing access vector as Gulf retailers digitize clienteling and virtual try-on capabilities. The accessible luxury tier attracts middle-class shoppers seeking entry-point brand affiliation, though super-premium lines retain the strongest pricing power among collectors and tourists.
Saudi Arabia's SFDA oversees cosmetic and fragrance safety standards that affect product registration timelines for European imports entering Gulf markets. The UAE's MOHAP enforces labeling and consumer protection rules that shape how luxury houses structure regional packaging and warranty terms. Stakeholders must monitor how Gulf regulatory harmonization and evolving EU due diligence directives will reshape cross-border sourcing obligations and local compliance investments.
Market Dynamics
The EU Green Deal's Carbon Border Adjustment Mechanism is forcing Middle East and Africa luxury distributors to restructure sourcing networks and certify supply chain emissions ahead of European import deadlines.
Growth Catalysts
- Gulf tourist spending concentration:Dubai's retail infrastructure and megaproject developments channel regional ultra-high-net-worth demand into concentrated luxury corridors.
- EU Green Deal compliance requirements:European carbon disclosure mandates for imported finished goods create competitive differentiation for early-adopting distributors with audited sustainability protocols.
- Digital clienteling platforms:Gulf retailers deploying virtual try-on capabilities and personalized online services capture aspirational buyer segments previously inaccessible through physical channels.
Market Restraints
- Gemstone supply concentration:Rough diamond and colored gemstone sourcing depends on a limited network of certified mines and cutting centers, exposing margins to extraction bottlenecks.
- SFDA registration timelines:Saudi Arabia's cosmetic and fragrance safety standards extend product approval cycles for European imports entering Gulf markets.
- Artisan labor scarcity:Master craftsperson availability constrains expansion of bespoke jewelry and leather goods production capacity.
Strategic Opportunities
- Saudi Vision 2030 retail expansion:Riyadh and Jeddah luxury precinct development opens underpenetrated domestic demand beyond traditional Dubai-centric spending.
- Blockchain-enabled provenance tracking:Convergence of distributed ledger technology with gemological certification creates new premium tiers for traceable raw materials.
- Secondhand authentication services:Pre-owned luxury platforms addressing wealth preservation motives among collector segments represent emerging channel innovation.
Industry Challenges
- Cross-border compliance harmonization:Divergent labeling requirements between UAE MOHAP and Saudi SFDA force redundant packaging reconfiguration for multi-territory distributors.
- Legacy inventory systems integration:Real-time carbon footprint tracking demands substantial capex in enterprise resource planning upgrades across family-owned retail networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Luxury Goods Market |
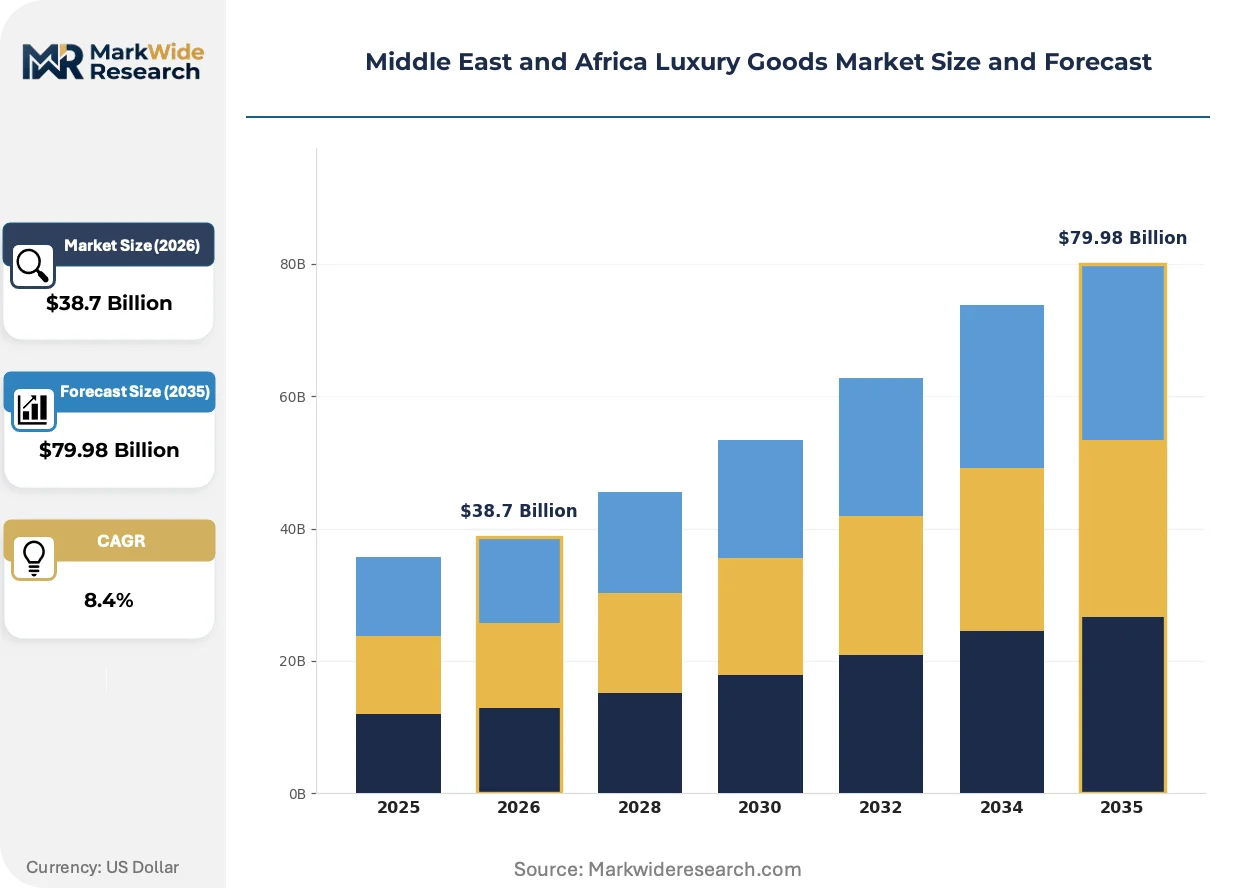
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apparel, Accessories, Footwear, Jewelry Distribution Channel: Online, Specialty Stores, Department Stores, Direct Selling End User: Affluent Consumers, Middle-Class Shoppers, Tourists, Collectors Price Tier: Premium, Super-Premium, Accessible Luxury, Others |
| Companies Covered | LVMH Moet Hennessy Louis Vuitton, Kering, Cartier, Chanel, Hermes International, Compagnie Financiere Richemont, Prada, Gucci, Louis Vuitton, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Luxury Goods Market Strategic Shifts
Digital transformation and sustainability verification are converging to reshape how luxury houses engage Gulf consumers and satisfy European regulatory requirements simultaneously.
Artificial intelligence-powered personalization engines is expanding into high-end retail operations across Dubai and Abu Dhabi. Ultra-high-net-worth collectors now expect algorithmic curation of limited-edition releases matched to purchase history. This technology is compressing traditional clienteling cycles while deepening wallet share among repeat buyers.
EU Green Deal carbon border adjustments are restructuring procurement priorities for Middle East distributors importing European finished goods. Compliance documentation requirements now precede shipment logistics in vendor selection criteria. Jewelry and timepiece categories face the steepest certification burdens due to multi-source raw material complexity.
Experiential retail formats are displacing conventional boutique layouts in Gulf luxury corridors. Saudi Arabia's Riyadh Season and Dubai's immersive retail concepts integrate hospitality, cultural programming, and private shopping suites. This format concentrates tourist spending and extends dwell time among visiting ultra-high-net-worth buyers from South Asia and Sub-Saharan Africa.
Middle East and Africa Luxury Goods Market Segmentation
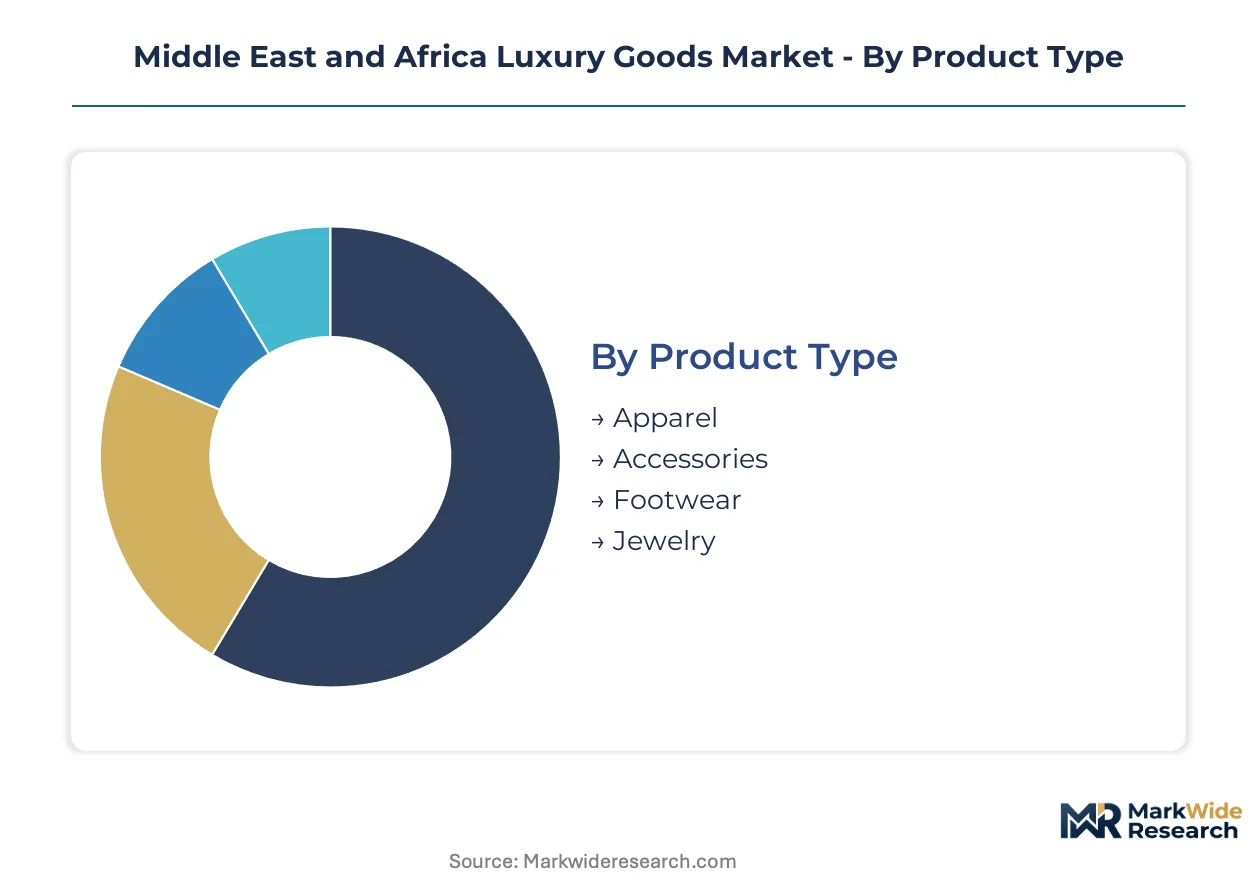
Luxury houses operating across Gulf Cooperation Council markets deploy precise segmentation strategies to capture divergent spending patterns among ultra-high-net-worth residents, visiting tourists, and emerging aspirational buyers. Category-specific positioning determines margin architecture, with jewelry commanding the deepest pools while accessible luxury expands volume reach.
Product Type:
Material composition and artisanal intensity distinguish competitive positioning across the four product categories, with raw material traceability protocols increasingly shaping procurement hierarchies.
- Jewelry:Gemstone-intensive categories incorporating certified diamonds, colored stones, and precious metals with bespoke commission structures. Demand concentrates among Gulf-based collectors and visiting ultra-high-net-worth tourists from South Asia, driven by wealth preservation motives and Dubai's tax-advantaged trading environment.
- Accessories:Leather goods, silk goods, and small leather articles characterized by vertically controlled supply chains and heritage craftsmanship. Saudi Arabia's Vision 2030 retail precinct developments channel domestic demand away from traditional Dubai-centric spending patterns.
- Apparel:Ready-to-wear and couture garments utilizing superior fabrics and atelier construction methods.
- Footwear:Artisanal leather construction with limited production runs and heritage manufacturing techniques.
Jewelry leads on scale; accessories leads on momentum.
Distribution Channel:
Channel selection determines customer acquisition economics and regulatory compliance burdens, with digital infrastructure investments reshaping traditional Gulf retail hierarchies.
- Specialty Stores:Brand-controlled boutiques delivering immersive clienteling experiences and private shopping suites. Dubai's mall corridors and Riyadh's emerging luxury districts anchor regional flagship deployment, though SFDA registration timelines for Saudi cosmetic and fragrance imports extend operational complexity.
- Online:E-commerce platforms integrating virtual try-on capabilities, AI-powered personalization engines, and digital clienteling services. UAE-based retailers deploying these technologies capture aspirational segments previously inaccessible through physical channels alone.
- Department Stores:Multi-brand retail environments with established tourist foot traffic and consolidated logistics.
- Direct Selling:Invitation-only trunk shows and private client appointments for ultra-high-net-worth collectors.
Specialty stores dominate current revenue; online channels are expanding most quickly.
End User:
Buyer archetype segmentation governs product mix, pricing architecture, and service intensity across Gulf retail operations.
- Affluent Consumers:Resident ultra-high-net-worth individuals with sustained purchasing power and established brand relationships. Dubai's retail infrastructure and megaproject developments concentrate this segment's spending into dedicated luxury corridors with integrated hospitality programming.
- Tourists:Visiting buyers from South Asia, Sub-Saharan Africa, and emerging markets seeking tax-advantaged purchases and experiential retail formats. Riyadh Season and Dubai's immersive concepts specifically target this segment's extended dwell time expectations.
- Collectors:Connoisseur buyers focused on limited editions, provenance documentation, and investment-grade acquisitions.
- Middle-Class Shoppers:Aspirational buyers seeking entry-point brand affiliation through accessible luxury tier products.
Affluent consumers anchor volume; tourists drive steepest expansion trajectory.
Price Tier:
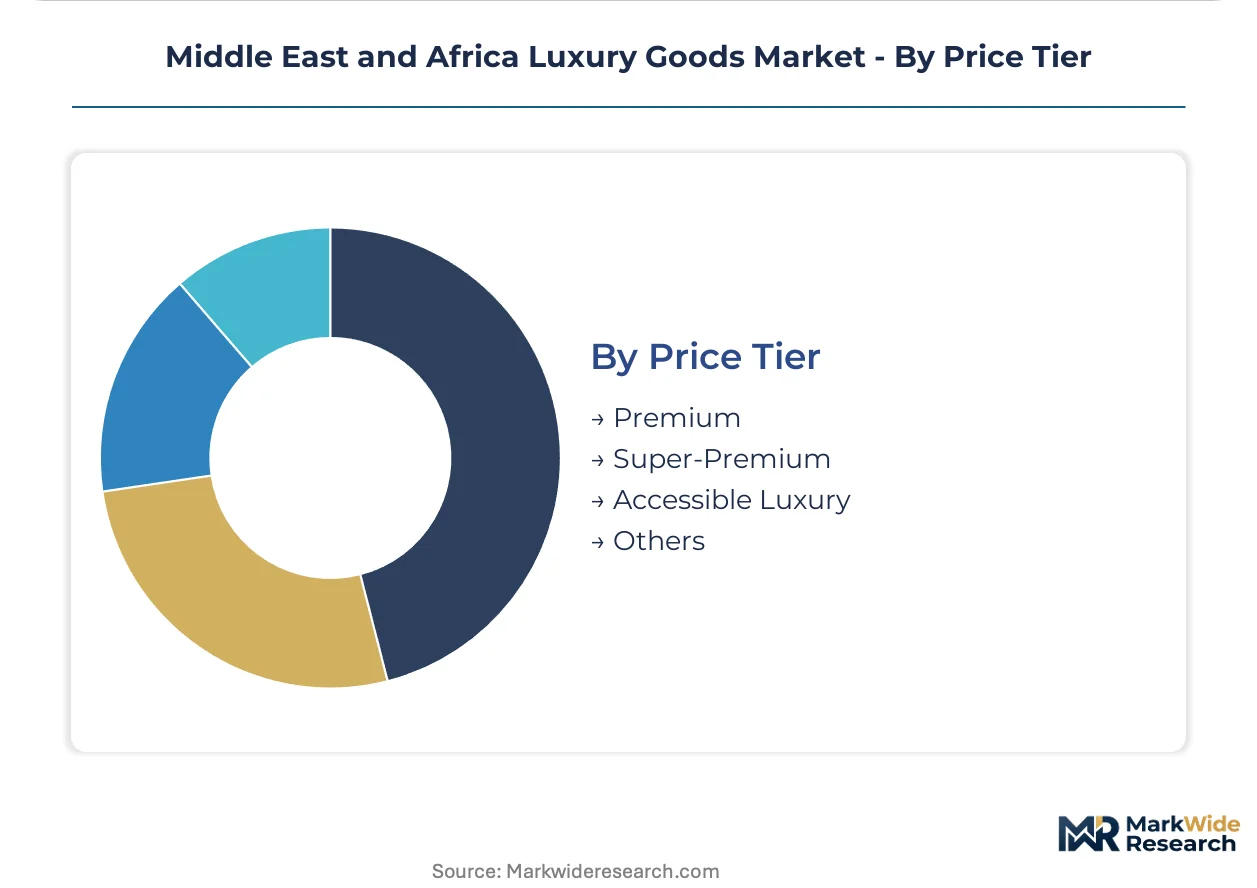
Premium stratification aligns production scale, material intensity, and exclusivity guarantees with distinct buyer willingness-to-pay thresholds.
- Super-Premium:Bespoke and limited-edition offerings with documented provenance, master artisan involvement, and scarcity-engineered release schedules. Collectors and visiting ultra-high-net-worth tourists from South Asia sustain demand for this tier's strongest pricing power.
- Premium:Core luxury lines with established heritage positioning and consistent quality benchmarks. UAE MOHAP labeling requirements and warranty term regulations shape how houses structure regional packaging for this volume-critical segment.
- Accessible Luxury:Entry-point price positioning targeting middle-class aspirational buyers with brand affiliation motives.
- Others:Niche and experimental pricing structures outside standard tier architecture.
Premium commands volume share; super-premium delivers margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Master craftspeople and retail specialists concentrate in Dubai and Riyadh, anchoring Gulf luxury corridors with expertise in gemology, leatherwork, and experiential clienteling. This talent concentration channels regional ultra-high-net-worth spending into concentrated retail infrastructure.
United Arab Emirates
Dubai Mall and Mall of the Emirates anchor tourist-facing luxury spending from South Asian and Sub-Saharan African visitors. MOHAP enforces labeling and consumer protection rules that shape warranty terms and packaging structures for European imports. Downtown Dubai's immersive retail concepts integrate hospitality programming that extends dwell time among visiting collectors.
Saudi Arabia
Vision 2030 retail precinct developments in Riyadh and Jeddah redirect domestic demand away from traditional Dubai-centric patterns. SFDA oversees cosmetic and fragrance safety standards that extend product registration timelines for European luxury houses. Riyadh Season's experiential formats concentrate tourist spending through integrated cultural programming and private shopping suites.
South Africa
Cape Town and Johannesburg host established collector communities focused on investment-grade jewelry and timepiece acquisitions. The country's national consumer protection regulator enforces warranty and labeling standards that affect how European houses structure regional distribution. Sandton City's luxury corridor attracts Sub-Saharan African ultra-high-net-worth buyers seeking provenance-documented pieces.
Qatar
Doha's Pearl-Qatar and Place Vendôme developments channel concentrated spending from resident and visiting Gulf nationals. The country's national standards body aligns product safety requirements with broader Gulf harmonization initiatives. Lusail's emerging retail infrastructure targets FIFA World Cup visitor legacy conversion into sustained luxury demand.
Kuwait
The Avenues Mall anchors domestic ultra-high-net-worth spending with limited leakage to Dubai or European capitals. Kuwait's national consumer protection authority enforces warranty term regulations that shape how houses structure regional service commitments. Salmiya's luxury retail cluster concentrates collector demand for limited-edition releases and bespoke commissions.
Middle East and Africa Luxury Goods Market Competitive Environment
Capital-heavy producers with captive manufacturing assets compete with asset-light designers licensing production to certified ateliers. The vendor base concentrates among ten to fifteen houses controlling the majority of regional revenue, with tiered differentiation between conglomerate-backed portfolios and independent maisons. Strategic archetypes include vertically integrated leather goods specialists, gemstone-traceability-focused jewelers, and multi-brand luxury groups. Dominant competitive moves encompass sustainability certification investments ahead of EU Green Deal deadlines and experiential retail format deployment across Gulf megaprojects.
Within the conglomerate tier, LVMH Moet Hennessy Louis Vuitton and Kering represent asset-heavy positioning with controlled supply chains. Cartier exemplifies the specialist archetype through gemstone-intensive focus. These three anchors illustrate how European parent-company sustainability mandates translate into regional competitive differentiation.
| Leading Market Players |
|---|
| LVMH Moet Hennessy Louis Vuitton |
| Kering |
| Cartier |
| Chanel |
| Hermes International |
| Compagnie Financiere Richemont |
| Prada |
| Gucci |
| Louis Vuitton |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal carbon disclosure mandates now gate both qualified supplier access and premium-tier pricing power for Middle East and Africa luxury distributors importing European finished goods. Houses lacking audited emissions documentation face exclusion from super-premium positioning, while early adopters capture margin expansion through scarcity-engineered release schedules.
Pricing Analysis
Bundled experiential services versus unbundled product-only transactions now define pricing architecture across Gulf luxury corridors. Three-tier pricing structure across super-premium, premium, and accessible luxury levels reflects after-sales service intensity and provenance documentation depth. Price differentiation stems from gemological certification grade and heritage brand equity. Cost compression in accessible luxury tiers is intensifying because middle-class aspirational buyers multiply faster than master craftsperson supply. Tourists from South Asia exhibit lowest price sensitivity; domestic middle-class shoppers in Saudi Arabia show highest.
Supply Chain Analysis
Rough diamond and colored gemstone supply rests on certified mines in Botswana, Russia, and Canada, with cutting concentrated in India and Belgium. Raw material dependencies include platinum group metals from South Africa, silk from Italy and China, and exotic leathers from France and Italy. Single-source vulnerability runs through De Beers-sightholder relationships for large-stone rough. Distribution runs through Dubai's Jebel Ali free zone for regional hub-and-spoke logistics into Riyadh, Jeddah, and Doha.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through carbon-compliant supply chain restructuring and super-premium tier elevation. EU import documentation requirements favor houses with backward-integrated raw material control.
For Market Incumbents: Hedge against EU Green Deal enforcement gaps by dual-sourcing critical inputs from certified and transitional suppliers simultaneously. Preempt SFDA registration bottlenecks through dedicated Saudi compliance teams. Lock in master craftsperson capacity via atelier acquisition in Dubai and Riyadh before artisan labor scarcity worsens. For New Entrants and Emerging Players: The price-point gap between super-premium collector pieces and accessible luxury entry points offers white-space capture in authenticated pre-owned platforms. Saudi Arabia's Vision 2030 retail precincts represent the most penetrable geography given domestic demand redirection from Dubai. Launch through digital clienteling with virtual try-on capabilities to bypass flagship real estate costs. For Investors and Strategic Acquirers: Roll-up economics work for regional multi-brand distributors because Gulf regulatory harmonization creates scale advantages in compliance overhead absorption. Target family-owned retail networks with legacy inventory systems requiring ERP modernization. Watch blockchain-enabled provenance adoption rates as inflection indicator for which houses can sustain super-premium pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Certification Investment | EU Green Deal compliance documentation now precedes shipment logistics in vendor selection criteria. |
| Experiential Retail Format Deployment | Riyadh Season and Dubai immersive concepts extend dwell time among visiting ultra-high-net-worth collectors. |
| Blockchain Provenance Integration | Distributed ledger convergence with gemological certification creates new premium tiers for traceable materials. |
| Digital Clienteling Platform Buildout | AI-powered personalization engines capture aspirational segments previously inaccessible through physical channels. |
| Master Craftspeople Atelier Acquisition | Artisan labor scarcity constrains bespoke jewelry expansion; captive capacity secures production pipelines. |
Study Parameters
Coverage spans Gulf Cooperation Council states and South Africa, with primary inputs from each territory's luxury retail corridors. Primary interviews with brand general managers, regional distribution heads, gemological certification officers, and hospitality-integrated retail designers combined with secondary validation from customs records, tourism authority visitor spending data, and EU regulatory filings. Bottom-up store-level revenue estimates triangulated against top-down national luxury consumption benchmarks.
Rate-of-change decomposition across product type, distribution channel, end user archetype, and price tier informed the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated SFDA registration timeline impacts on cosmetic and fragrance category velocity, plus carbon border adjustment compliance cost pass-through assumptions.
Caveats apply where Gulf regulatory harmonization delays or EU due diligence directive scope expansion could materially shift the outlook. Forecasts assume sustained tourist spending concentration in Dubai and Riyadh retail infrastructure. A small set of named triggers—EU carbon tariff rate finalization, Saudi Vision 2030 project acceleration, and blockchain certification standard adoption—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Goods
Europe Secondhand Luxury Goods Market
Luxury Goods
Luxury Resale Platform Market
Luxury Goods
Spain Luxury Jewelry Market
Luxury Goods
Pre-Owned Luxury Watches Market
Luxury Goods
Singapore Luxury Goods Market
Luxury Goods
GCC Luxury Goods Market
Luxury Goods
Personal Luxury Goods Market
Luxury Goods
Brazil Luxury Goods Market
Luxury Goods
Thailand Luxury Goods Market
Luxury Goods
GCC Personal Luxury Goods Market
Luxury Goods
Asia-Pacific Luxury Goods Market
Luxury Goods
Luxury Watches Market
Luxury Goods
Used Luxury Bags Trading Service Market
Luxury Goods
Mens Watch Market
Luxury Goods
China Luxury Goods Market
Luxury Goods
Global Gold and Diamond Jewellery Market