
 Luxury Products for Kids Market | 2026-2036
Luxury Products for Kids Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury Products for Kids Market Foresight
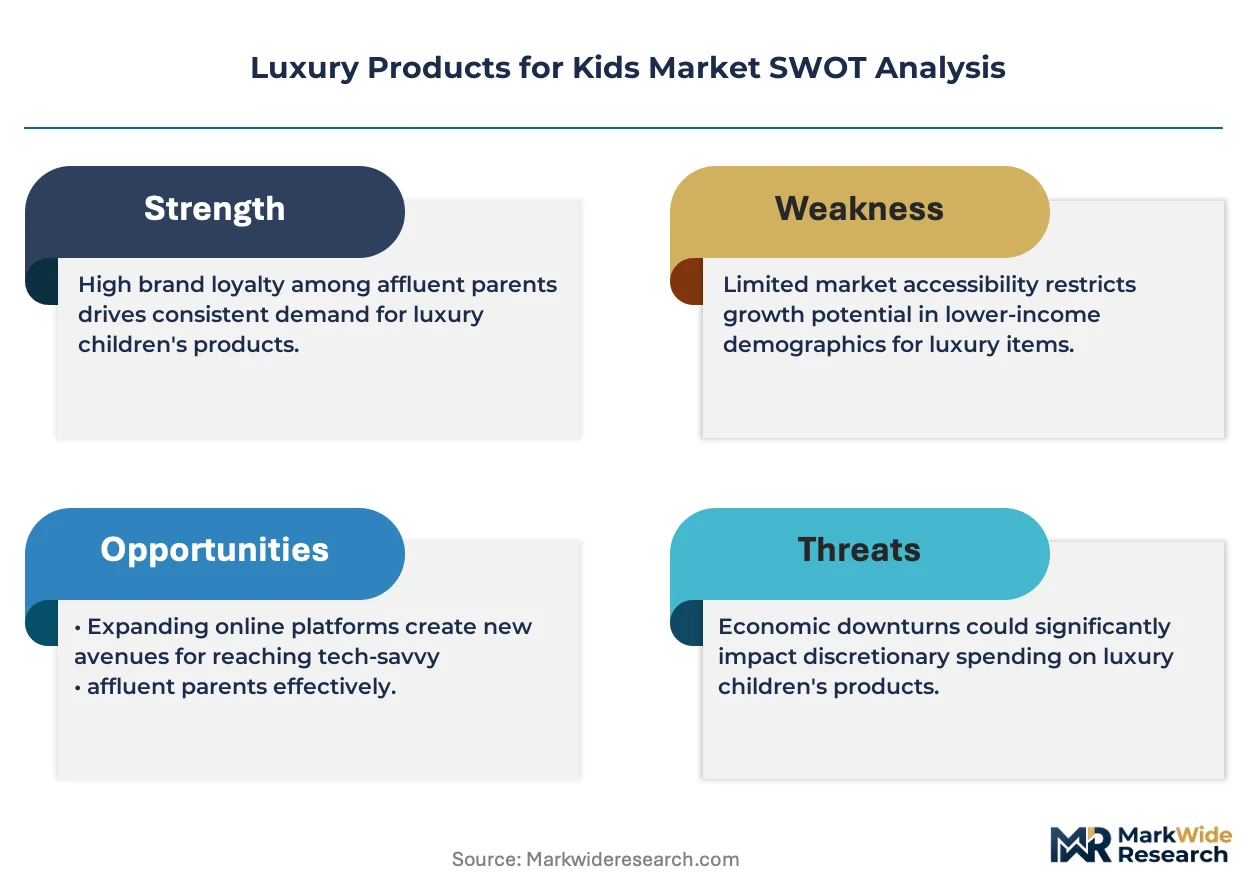
Asset-light licensing and royalty-based partnerships are reshaping competitive entry in luxury children's goods. Gucci leverages its parent company's global manufacturing infrastructure to sustain rapid product turnover across seasonal collections. Burberry anchors its kids' line through controlled distribution in flagship stores and select luxury department stores. Stella McCartney differentiates through certified organic material sourcing and transparent supply chain positioning.
Luxury products for kids encompass premium apparel, accessories, footwear, and play items manufactured to adult luxury standards with child-specific sizing, safety adaptations, and durability requirements. These goods typically employ natural fibers such as organic cotton, silk, and cashmere alongside non-toxic finishes that meet stringent skin-contact regulations for juvenile consumers. Luxury apparel occupies the largest value share within product type segmentation, driven by recurring seasonal purchasing cycles and gift-giving occasions. Premium toys represent the fastest-expanding category, particularly in educational and collectible sub-segments where parents justify expenditure through developmental value claims. Distribution through exclusive brands and high-end retailers captures the highest margin pools, as controlled scarcity supports price integrity and brand prestige.
REACH regulations administered by ECHA restrict hazardous substances in textiles sold across European Union member states, directly affecting dye selection and finishing processes for luxury children's apparel. The U.S. Consumer Product Safety Commission enforces flammability standards and lead-content limits that dictate material compliance costs for brands operating in North America. China's SAMR oversees product quality labeling and advertising claims targeting juvenile consumers, creating additional certification layers for market entry. Stakeholders must monitor evolving chemical restriction schedules and traceability mandates across these jurisdictions to anticipate compliance cost shifts and sourcing restructuring requirements.
Market Dynamics
REACH compliance administered by ECHA is forcing luxury children's apparel manufacturers to reformulate dyes and finishing agents, compressing supplier timelines and elevating certification costs across European supply chains.
Growth Catalysts
- Affluent millennial parenting cohorts:High-net-worth families in China and the United States are normalizing designer children's apparel as routine expenditure rather than occasional gifting.
- REACH chemical safety mandates:ECHA's evolving substance restriction schedules are accelerating material innovation investments among premium textile suppliers seeking competitive differentiation.
- Educational toy premiumization:STEM-certified play products with collectible attributes are capturing parental willingness to pay for developmental value claims.
Market Restraints
- Organic fiber input volatility:Certified organic cotton and cashmere supply concentrates in limited geographies, exposing margins to climate-induced yield fluctuations.
- Multi-jurisdiction compliance stacking:Brands must simultaneously satisfy REACH, CPSC flammability standards, and SAMR labeling requirements, multiplying testing overhead.
- Secondhand luxury circulation:Peer-to-peer resale platforms for outgrown children's apparel are eroding full-price replacement frequency among cost-conscious affluent households.
Strategic Opportunities
- India's emerging HNWI base:Mumbai and Delhi luxury retail expansion targets first-generation wealthy families with limited established brand loyalties in children's goods.
- Rental and subscription models:Rotating wardrobe services for rapidly outgrown sizes address sustainability concerns while capturing recurring revenue streams.
- EU Green Deal alignment:Brands achieving CSRD-compliant supply chain transparency can access preferential placement in European department store sustainability edit.
Industry Challenges
- Specialized material sourcing expertise:Procurement teams lack technical depth to evaluate non-toxic finish alternatives against evolving ECHA candidate lists.
- Traceability system integration:Legacy ERP platforms require costly customization to capture batch-level chemical certification data demanded by EU regulators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxury Products for Kids Market |
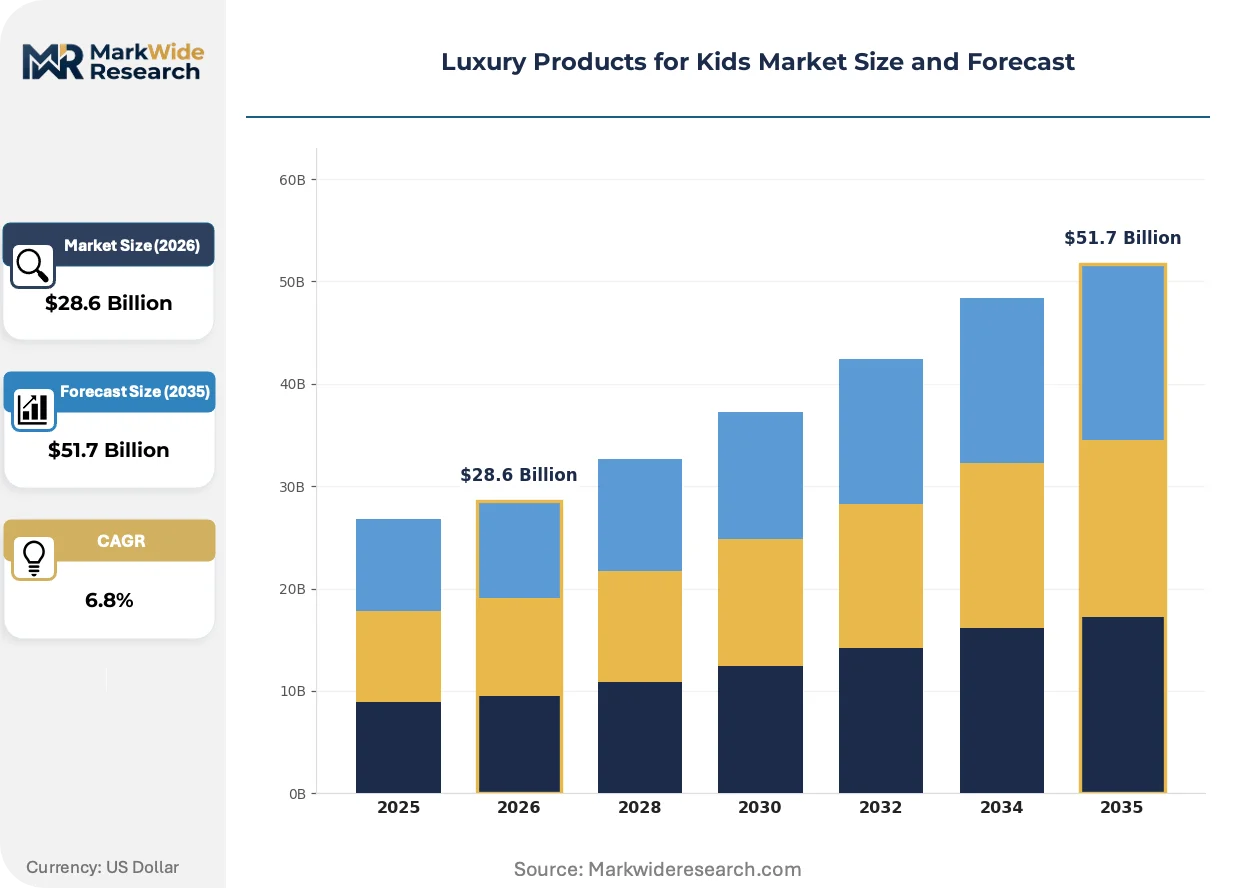
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Luxury Apparel, Premium Toys, Designer Accessories, Upscale Footwear Age Group: Toddlers, Preschoolers, School Age, Teens Material: Organic Cotton, Silk, Cashmere, Leather Distribution Channel: High-End Retailers, Online Boutiques, Luxury Department Stores, Exclusive Brands |
| Companies Covered | Gucci, Burberry, Dolce & Gabbana, Fendi, Ralph Lauren, Armani Junior, Stella McCartney, Moncler, Bonpoint, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury Products for Kids Market Shifts & Advancements
Digital product passports and on-demand manufacturing are compressing traditional seasonal collection cycles, enabling responsiveness to regulatory shifts and micro-trend adoption among affluent parent cohorts.
Blockchain-based provenance tracking is collapsing information asymmetries between manufacturers and end consumers regarding organic fiber origins and chemical treatment histories. Premium children's brands in Germany and France are adopting these systems ahead of anticipated EU Digital Product Passport mandates. The technology is collapsing the traditional audit gap that previously allowed certification gaps to persist undetected through multi-tier supply chains.
REACH authorization requirements for skin-sensitizing dyes are tightening formulation constraints on luxury children's apparel sold across EU member states. ECHA's 2024-2025 restriction roadmap specifically targets disperse dyes and formaldehyde-releasing finishes common in silk and wool processing. Italian and Portuguese textile finishers are accelerating water-based alternative R&D to maintain access to European luxury brand accounts.
Parental purchasing for children's luxury goods is fragmenting across direct-to-brand digital channels, bypassing traditional department store intermediaries. Flagship e-commerce and social commerce livestreaming in China now capture substantial volume previously routed through multi-brand retailers. This channel rotation is most pronounced among millennial parents in Shanghai and Shenzhen, where convenience and exclusive digital drops outweigh tactile pre-purchase evaluation.
Luxury Products for Kids Market Segmentation
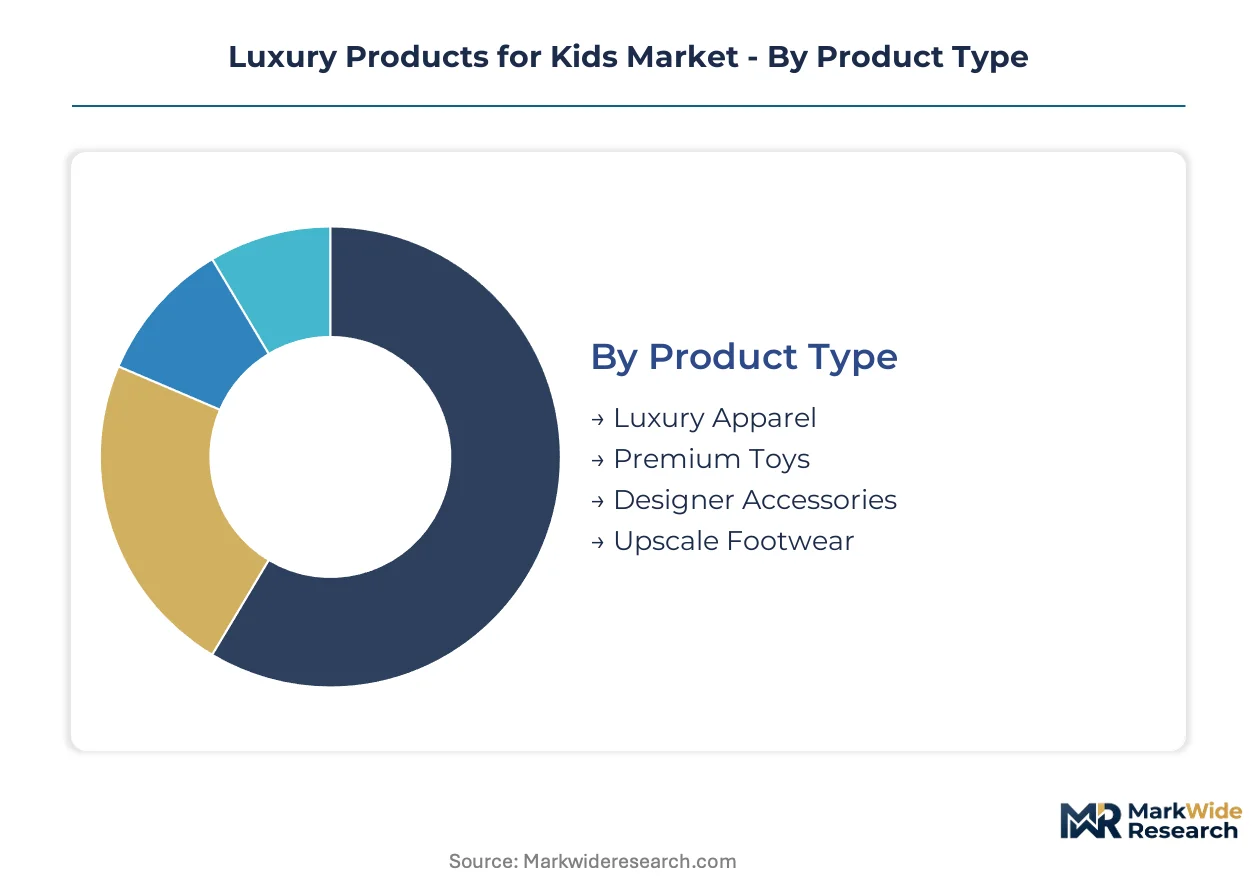
Segmentation in luxury children's goods reveals distinct purchasing cadences across product categories. Rapid size turnover in apparel creates fundamentally different inventory dynamics versus collectible toys with extended shelf lives.
Product Type:
Seasonal collection cycles vary dramatically across product categories, with apparel demanding quarterly replenishment while toys sustain annual release schedules.
- Luxury Apparel:Organic cotton, silk, and cashmere garments sized for child-specific proportions with REACH-compliant dye formulations. Demand clusters among affluent millennial parents in China and the United States who treat designer children's clothing as routine expenditure rather than occasional gifting. ECHA chemical restrictions are compressing supplier timelines for European market access.
- Premium Toys:STEM-certified educational products and collectible play items manufactured to adult luxury finish standards with child safety adaptations. Parents in Shanghai and Shenzhen justify expenditure through developmental value claims, with social commerce livestreaming capturing volume previously routed through multi-brand retailers.
- Designer Accessories:Premium bags, jewelry, and small leather goods scaled for juvenile use.
- Upscale Footwear:Natural fiber and leather constructions with orthopedic considerations for growing feet.
Luxury apparel dominates installed base. Premium toys are where expansion concentrates.
Age Group:
Size turnover velocity determines repurchase frequency, with rapid growth phases in early childhood creating compressed replacement cycles versus extended wear periods in later years.
- Toddlers:Highest replacement frequency due to rapid physical development, driving subscription and rental model viability.
- Preschoolers:Gift-giving occasions concentrate heavily in this bracket, with grandparents and extended family contributing substantial purchase volume.
- School Age:Peer influence begins shaping brand preferences, with children developing awareness of luxury signifiers worn by classmates.
- Teens:Convergence with adult luxury sizing creates bridge to mainline collections, though distinct juvenile positioning persists for this cohort.
School age captures peak household spend per child. Toddlers represent the steepest expansion trajectory for alternative ownership models.
Material:
Certification requirements and supply concentration create tiered cost structures across fiber categories, with climate vulnerability introducing margin volatility.
- Organic Cotton:Certified fiber with restricted pesticide use, concentrated in Turkish and Indian growing regions. Yield fluctuations from climate stress expose finished goods pricing to agricultural commodity swings.
- Silk:Protein fiber requiring specialized finishing to meet ECHA skin-contact standards for juvenile consumers. Italian and Portuguese textile finishers are accelerating water-based alternative R&D to maintain European market access.
- Cashmere:Fine undercoat fiber with supply concentrating in Mongolian and Chinese herding regions.
- Leather:Tanned hides with chromium-free processing requirements for REACH compliance in children's goods.
Organic cotton commands the broadest supplier base. Silk is climbing the fastest as parents prioritize natural fiber content.
Distribution Channel:
Margin capture and brand control trade off against reach and customer acquisition efficiency across channel configurations.
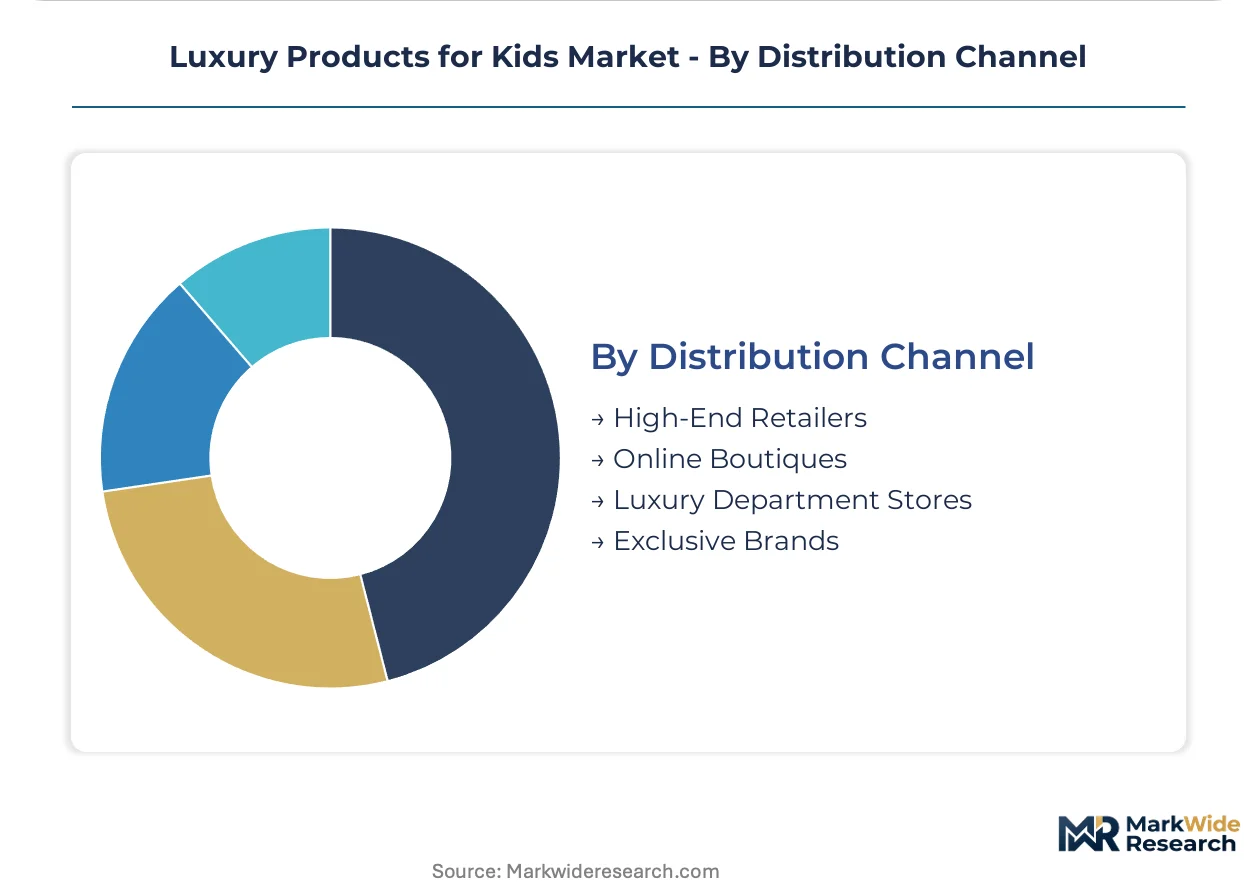
- High-End Retailers:Curated multi-brand environments with trained sales staff and tactile pre-purchase evaluation. Controlled scarcity supports price integrity, though peer-to-peer resale platforms are eroding full-price replacement frequency.
- Online Boutiques:Direct-to-brand digital channels with flagship e-commerce and exclusive digital drops. Millennial parents in China's tier-one cities favor convenience over in-person evaluation, fragmenting volume away from traditional intermediaries.
- Luxury Department Stores:Established traffic with sustainability edit placement for CSRD-compliant brands.
- Exclusive Brands:Captive retail with maximum margin extraction and controlled brand environment.
Exclusive brands dominate margin pools. Online boutiques are gaining share fastest among digitally native parent cohorts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH authorization schedules and China's dual carbon goals are redirecting capital toward compliant manufacturing bases. Affluent millennial parenting cohorts in Shanghai, New York, and Milan are normalizing designer children's apparel as routine expenditure rather than occasional gifting.
China
High-net-worth families in Shanghai and Shenzhen are deepening luxury consumption through social commerce livestreaming channels. SAMR oversees product quality labeling and advertising claims targeting juvenile consumers, creating additional certification layers for market entry. The Pearl River Delta manufacturing cluster is accelerating water-based finishing R&D to maintain European brand account access.
United States
Affluent millennial parents treat designer children's clothing as routine expenditure across New York, Los Angeles, and Chicago metropolitan areas. The CPSC enforces flammability standards and lead-content limits that dictate material compliance costs for domestic and imported goods. Pacific Northwest retail expansion targets first-generation wealthy families with limited established brand loyalties in children's goods.
Italy
Milan anchors European luxury children's apparel design and finishing expertise. REACH restrictions on disperse dyes and formaldehyde-releasing finishes are compressing supplier timelines for silk and wool processing. Italian textile finishers in Como and Biella are accelerating water-based alternative R&D to maintain market access.
France
Paris-based heritage houses control distribution through flagship stores and select luxury department stores. ECHA's evolving substance restriction schedules are accelerating material innovation investments among premium textile suppliers. The Île-de-France region concentrates design talent and atelier infrastructure for small-batch children's collections.
India
Mumbai and Delhi luxury retail expansion targets first-generation wealthy families with limited established brand loyalties. BIS certification requirements for imported textiles create additional testing overhead for European and American brands. Maharashtra and Karnataka are emerging as domestic manufacturing alternatives for organic cotton children's apparel.
Luxury Products for Kids Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. The vendor base organizes around heritage luxury houses with parent-company manufacturing infrastructure, mid-tier fashion brands extending adult lines downward, and independent children's specialists with certified organic positioning. Dominant competitive moves include asset-light licensing partnerships and controlled distribution scarcity to support price integrity.
Within the heritage house tier, Gucci, Burberry, and Stella McCartney occupy positions that exemplify divergent strategic archetypes. Gucci leverages its parent company's global manufacturing infrastructure to sustain rapid product turnover across seasonal collections. Burberry anchors its kids' line through controlled distribution in flagship stores and select luxury department stores. Stella McCartney represents the certified organic material sourcing and transparent supply chain positioning archetype, differentiating through ECHA-compliant formulation constraints and batch-level traceability systems ahead of anticipated EU Digital Product Passport mandates.
| Leading Market Players |
|---|
| Gucci |
| Burberry |
| Dolce & Gabbana |
| Fendi |
| Ralph Lauren |
| Armani Junior |
| Stella McCartney |
| Moncler |
| Bonpoint |
| Others |
Supply & Pricing Matrix
Mongolian and Chinese herding regions supply the cashmere fiber that anchors margin pools in European luxury children's apparel. REACH-compliant dye formulations and ECHA skin-contact certifications create tiered value capture that separates premium positioning from mass-market alternatives.
Pricing Analysis
Certification level creates the primary spread across the market, with ECHA-compliant organic material sourcing commanding substantial premiums over conventional alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects material grade, brand heritage, and distribution channel exclusivity. Cost compression in mid-tier segments is intensifying because secondhand luxury resale platforms are eroding full-price replacement frequency. Digitally native millennial parents in China's tier-one cities show the lowest price sensitivity, while cost-conscious affluent households in Western Europe demonstrate the highest.
Supply Chain Analysis
Export-control regimes on specialized dye technologies limit flows of disperse dye alternatives from Italian and Portuguese finishers to Asian manufacturing bases. Organic cotton concentrates in Turkish and Indian growing regions, silk processing anchors in Como and Biella, and cashmere sourcing feeds from Mongolian herding cooperatives. Climate-induced yield fluctuations in certified organic fiber regions create persistent margin volatility. Distribution runs through exclusive brand flagship stores, high-end retailers, and direct-to-consumer digital channels with controlled scarcity protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward digitally native millennial parents whose channel fragmentation and sustainability demands are consolidating influence over brand positioning and pricing integrity.
For Market Incumbents: Entrench ECHA-compliant supply chain positioning through accelerated water-based finishing R&D investments at Italian and Portuguese textile partners. Deepen batch-level traceability systems ahead of EU Digital Product Passport mandates to defend against certified-organic specialist challengers. Channel control through flagship retail expansion in Mumbai and Delhi protects margin pools from secondhand platform erosion. For New Entrants and Emerging Players: India's emerging HNWI base in Maharashtra and Karnataka offers underpenetrated white-space with limited established brand loyalties among first-generation wealthy families. Rental and subscription models for toddler-size rapid turnover address sustainability concerns while capturing recurring revenue streams. Social commerce livestreaming in China's Pearl River Delta manufacturing cluster provides the most penetrable go-to-market angle for direct audience building. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier fashion brands with adult line extension potential into certified-organic children's positioning and transparent supply chain infrastructure. Long-term viability hinges on regulatory anticipation capability rather than scale economies. Watch for ECHA substance restriction schedule acceleration as the inflection indicator forcing wholesale supplier restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Finishing R&D Investment | Italian and Portuguese textile finishers accelerate alternatives to maintain ECHA-compliant European market access. |
| Batch-Level Traceability System Deployment | Blockchain-based provenance tracking collapses audit gaps ahead of EU Digital Product Passport mandates. |
| Rental and Subscription Model Launch | Rotating wardrobe services capture recurring revenue from toddler-size rapid replacement cycles. |
| Social Commerce Livestreaming Expansion | Direct-to-consumer channels in Shanghai and Shenzhen fragment volume away from traditional department store intermediaries. |
| Flagship Retail Expansion in India | Mumbai and Delhi luxury retail targets first-generation wealthy families with limited established brand loyalties. |
Research Methodology
A spread of perspectives from brand procurement directors, textile finishing specialists, luxury retail buyers, and regulatory compliance officers converged on the working assumptions. Primary interviews combined with secondary validation from ECHA restriction roadmaps, SAMR labeling guidelines, CPSC flammability standards, and customs trade data. Bottom-up and top-down triangulation cross-checked supplier capacity claims against end-market demand signals.
Demand-supply balance across the projection horizon anchored volume and value outputs. Segmentation dimensions modeled include product type, age group, material certification tier, and distribution channel configuration. CAGRs were derived from growth rate convergence analysis across the modeling period. Industry-specific forecast inputs incorporated REACH compliance cost trajectories and organic fiber yield volatility patterns.
Practitioners should monitor ECHA substance restriction schedule acceleration and climate-induced organic cotton yield fluctuations for early signals. Forecasts reflect assumptions about regulatory enforcement continuity and affluent millennial parenting cohort expenditure normalization. Material shifts in EU Digital Product Passport implementation timelines or SAMR advertising claim enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Goods
GCC Secondhand Luxury Goods Market
Luxury Goods
India Lab Grown Diamond Jewelry Market
Luxury Goods
Europe Handbags Market
Luxury Goods
Singapore Luxury Goods Market
Luxury Goods
Spain Luxury Goods Market
Luxury Goods
China Luxury Goods Market
Luxury Goods
GCC Luxury Goods Market
Luxury Goods
China Luxury Market
Luxury Goods
United Kingdom Luxury Goods Market
Luxury Goods
Europe Secondhand Luxury Goods Market
Luxury Goods
GCC Personal Luxury Goods Market
Luxury Goods
Luxury Apparels Market
Luxury Goods
Luxury Handbag Market
Luxury Goods
Luxury Resale Platform Market
Luxury Goods
Italy Luxury Goods Market
Luxury Goods
Luxury Mechanical Watches Market