
 Brazil Luxury Goods Market | 2026-2036
Brazil Luxury Goods Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Luxury Goods Market Outlook
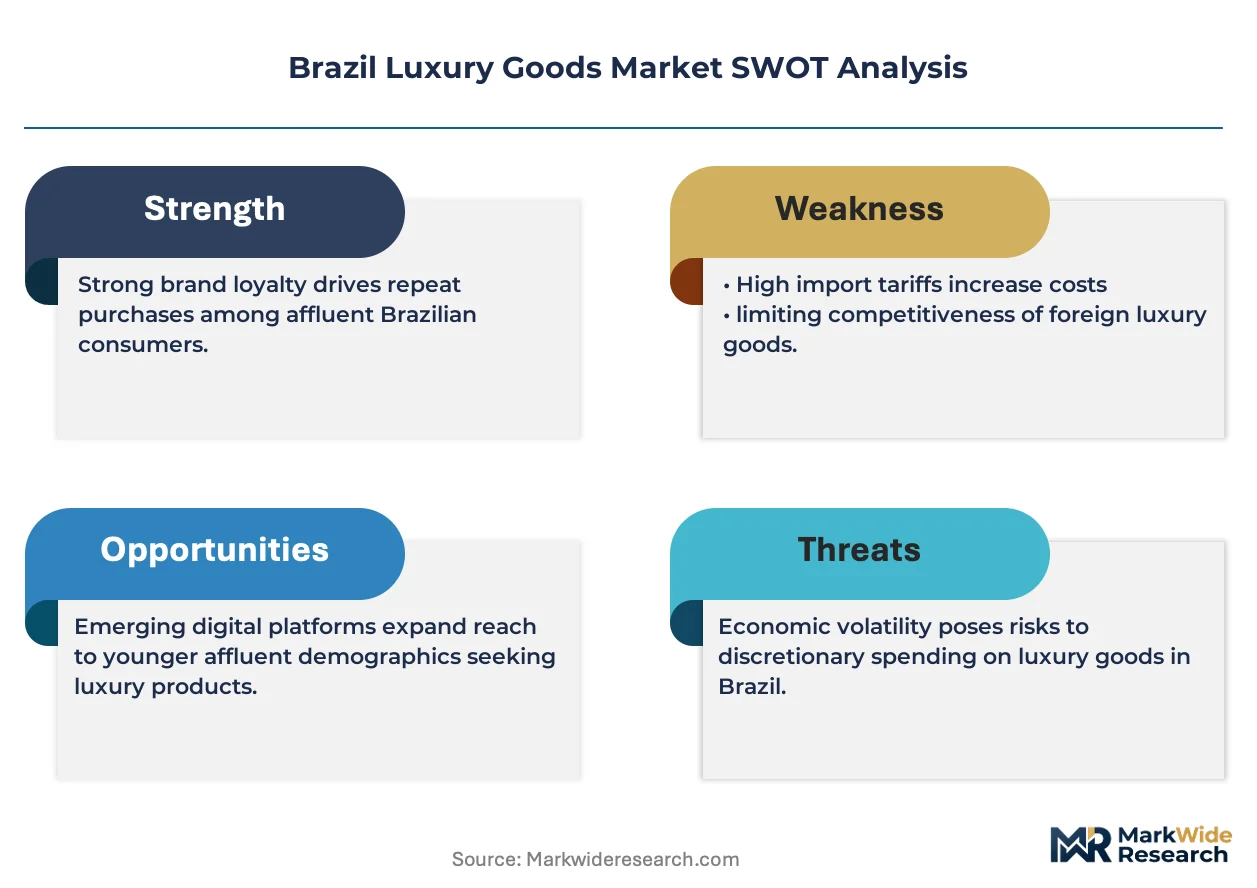
Skilled artisan labor scarcity in Brazilian jewelry manufacturing is redrawing competitive boundaries for domestic producers. Arezzo leverages its vertically integrated leather goods production to sustain margin control across footwear and accessories. H.Stern anchors its position through proprietary gemstone sourcing and certified master craftsmanship in Rio de Janeiro. Vivara Participações S.A. competes by dominating the mid-luxury bridal and gift jewelry segment through controlled retail distribution.
Brazil luxury goods encompass high-value fashion apparel, leather accessories, fine jewelry, and precision timepieces distinguished by superior materials, artisan construction, and brand heritage pricing. These products serve status signaling, wealth preservation, and experiential consumption purposes for Brazil's upper-income strata. Fashion and jewelry command the dominant revenue share, while e-commerce distribution represents the fastest structural expansion as digital authentication tools reduce counterfeit risk. The super premium price tier captures concentrated margin pools, whereas aspirational segments face volume pressure from informal parallel imports.
ANVISA governs cosmetic and fragrance product registration, while the Brazilian Institute of Metrology (INMETRO) enforces jewelry precious metal certification standards, collectively elevating compliance costs for imported goods. The Central Bank's foreign exchange monitoring affects luxury import financing and pricing transparency for international brands. Stakeholders must monitor regulatory enforcement intensity and digital tax compliance requirements as Brazil modernizes its cross-border e-commerce framework.
Market Dynamics
ANVISA's updated cosmetic and fragrance labeling standards are compressing product launch timelines while São Paulo's affluent consumer corridor pulls international brand investment toward controlled retail formats.
Growth Catalysts
- Southeast Regional Demand Concentration:São Paulo and Rio de Janeiro metropolitan luxury districts are absorbing disproportionate investment in flagship retail infrastructure.
- E-commerce Authentication Technologies:Digital verification tools are reducing counterfeit penetration, enabling brand-controlled direct-to-consumer channels for timepieces and leather goods.
- INMETRO Precious Metal Certification:Standardized gold and platinum assay protocols are elevating consumer trust in domestically certified jewelry, supporting domestic manufacturer premium positioning.
Market Restraints
- Artisan Labor Scarcity:Certified master craftspeople in Rio de Janeiro's jewelry manufacturing cluster command wage premiums that compress domestic producer margins.
- Foreign Exchange Volatility:Central Bank monitoring of luxury import financing creates pricing opacity for international brands sourcing inventory in dollars or euros.
- Parallel Import Penetration:Informal gray-market channels for fragrances and accessories undercut authorized distributor pricing in aspirational consumer segments.
Strategic Opportunities
- Cross-border E-commerce Modernization:Brazil's evolving digital tax compliance framework creates first-mover advantage for brands establishing localized fulfillment infrastructure.
- Bridal Jewelry Segment Expansion:Mid-luxury gift and ceremonial categories remain underpenetrated outside Southeast metropolitan cores, particularly in Northeast urban centers.
- Vertically Integrated Leather Production:Captive tannery and manufacturing operations enable margin defense against import-dependent competitors facing currency exposure.
Industry Challenges
- Regulatory Compliance Timeline Compression:ANVISA product registration protocols for new fragrance formulations extend go-to-market cycles beyond competitive windows in adjacent Latin American markets.
- Legacy Retail Footprint Reconfiguration:High-street flagship investments in São Paulo's fashion corridor require recalibration as digital authentication shifts purchase completion online.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Luxury Goods Market |
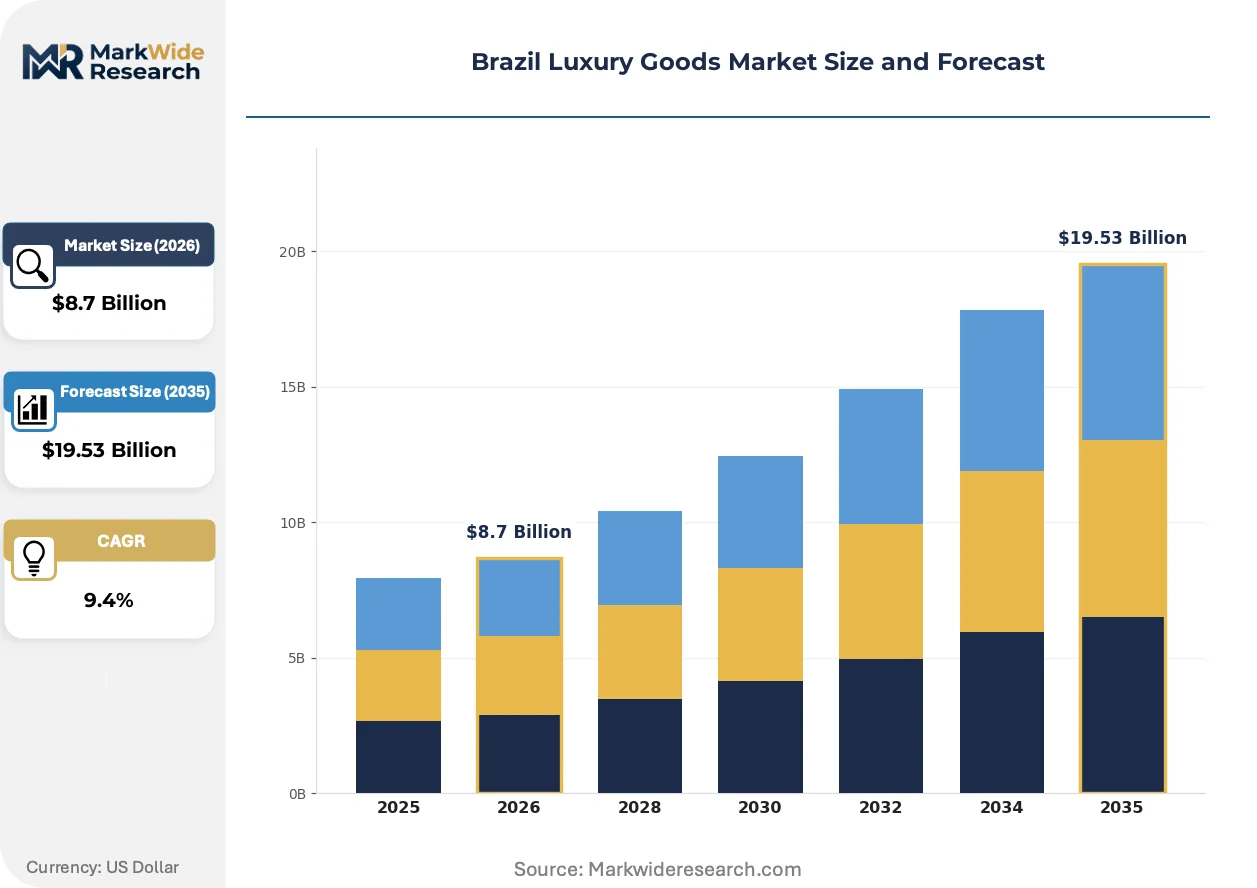
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fashion, Accessories, Jewelry, Watches End User: Affluent Consumers, High-Net-Worth Individuals, Tourists, Celebrities Distribution Channel: Department Stores, E-commerce, Specialty Stores, Direct Sales Price Tier: Premium, Super Premium, Ultra Luxury, Aspirational |
| Companies Covered | LVMH Moët Hennessy Louis Vuitton, Kering Group, Compagnie Financière Richemont SA, PUIG, Prada Holding S.p.A., Arezzo, H.Stern, Vivara Participações S.A., Chanel Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Luxury Goods Market Strategic Shifts
Digital authentication infrastructure is redrawing competitive boundaries between authorized distribution and gray-market alternatives. Three developments are compressing legacy operating models.
Blockchain-based provenance verification is miniaturizing trust infrastructure for high-value timepieces and gemstone jewelry. São Paulo's ultra-high-net-worth collectors are adopting smartphone-integrated authentication apps at accelerating rates. This capability is miniaturizing the role of physical certificates and dealer intermediaries in secondary market transactions.
ANVISA's fragrance allergen disclosure mandates are forcing reformulation cycles for imported prestige cosmetics. Compliance costs are concentrating among smaller international houses lacking localized regulatory affairs capacity. The super-premium fragrance tier is absorbing these costs through packaging redesign while mass prestige lines delay launches.
Experiential retail formats are displacing transactional flagship models in Rio de Janeiro's luxury corridor. Brand-controlled salons offering bespoke customization and master craftsman demonstrations are capturing extended dwell time from heritage-seeking consumers. This pattern is most visible in Leblon and Ipanema districts where experiential density correlates with repeat purchase rates.
Brazil Luxury Goods Market Segmentation
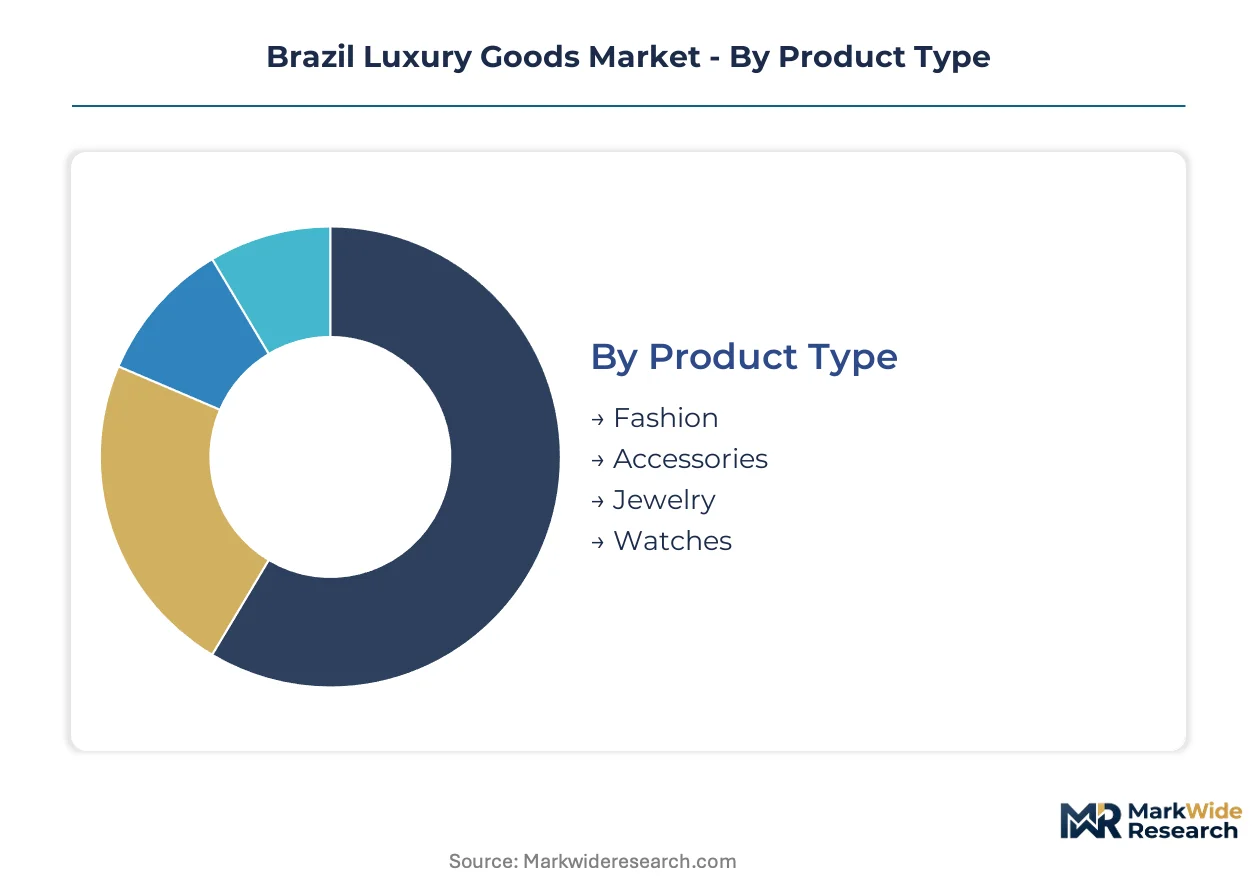
Segmentation in Brazil's luxury goods market reveals how demand concentrates geographically and demographically. Understanding these divides helps stakeholders allocate capital between São Paulo's established corridors and emerging Northeast urban centers.
Product Type:
Domestic manufacturing anchors jewelry and leather accessories, while fashion apparel and precision timepieces rely heavily on imported inventory subject to Central Bank exchange monitoring.
- Fashion:High-value apparel from European and American houses dominates São Paulo's luxury retail corridors. Demand clusters in the Jardins district, where flagship investments from international maisons absorb disproportionate marketing spend.
- Accessories:Leather goods and small leather articles benefit from Arezzo's vertically integrated domestic production. Captive tannery operations insulate margins against currency volatility that pressures import-dependent competitors.
- Jewelry:H.Stern's Rio de Janeiro master craftsmanship and Vivara's controlled retail distribution define competitive positioning. INMETRO precious metal certification elevates consumer trust in domestically certified pieces.
- Watches:Swiss and German precision timepieces circulate through authorized dealers facing gray-market price undercutting. Digital authentication tools are compressing unauthorized channel penetration.
Fashion holds the largest share; momentum sits with accessories as domestic production advantages deepen.
End User:
Customer stratification runs from established wealth preserving capital in tangible goods to aspirational buyers seeking entry-point status signals.
- Affluent Consumers:Upper-middle professionals in São Paulo and Rio de Janeiro metropolitan areas drive volume in accessible luxury tiers. This segment responds to experiential retail formats and bridal jewelry occasions.
- High-Net-Worth Individuals:Ultra-wealthy collectors concentrate in Leblon, Ipanema, and Jardins districts. Blockchain-based provenance verification is miniaturizing their reliance on dealer intermediaries for secondary market transactions.
- Tourists:International visitors contribute seasonal demand spikes, particularly during Rio's summer calendar and São Paulo fashion events. Tax reimbursement infrastructure affects purchase completion rates.
- Celebrities:Entertainment and sports figures generate amplification effects for domestic brands seeking international visibility. H.Stern leverages this channel for gemstone narrative marketing.
Affluent consumers anchor volume; high-net-worth individuals are gaining share fastest as wealth concentration intensifies in Southeast Brazil.
Distribution Channel:
Channel strategy must reconcile legacy retail footprint investments with accelerating digital authentication capabilities.
- Department Stores:Multi-brand luxury floors in São Paulo's Iguatemi and Cidade Jardim complexes maintain relevance through curated editorship. Foot traffic depends on experiential programming beyond transactional display.
- E-commerce:Brand-controlled direct-to-consumer platforms are expanding most quickly as digital verification tools reduce counterfeit risk. Cross-border e-commerce modernization creates first-mover advantage for localized fulfillment infrastructure.
- Specialty Stores:Mono-brand boutiques in Rio's luxury corridor emphasize master craftsman demonstrations and bespoke customization. Extended dwell time correlates with repeat purchase rates in Leblon and Ipanema.
- Direct Sales:Private clienteling and appointment-only showrooms serve ultra-high-net-worth collectors seeking discretion. This channel captures concentrated margin pools through personalized service intensity.
Specialty stores retain the largest share; e-commerce climbs the fastest as authentication infrastructure matures.
Price Tier:
Pricing stratification reflects regulatory compliance cost absorption capacity and parallel import vulnerability.
- Premium:Entry-luxury positioning faces sustained pressure from informal gray-market channels for fragrances and accessories. ANVISA allergen disclosure mandates compress launch timelines for this tier.
- Super Premium:Established houses absorb reformulation and packaging redesign costs through pricing power. This tier concentrates among players with localized regulatory affairs capacity.
- Ultra Luxury:Bespoke and limited-production pieces command artisan scarcity premiums. Certified master craftspeople in Rio's jewelry cluster command wage premiums that validate exclusivity positioning.
- Aspirational:Mass prestige lines delay launches as compliance costs concentrate disproportionately. Volume pressure from parallel imports undercuts authorized distributor pricing.
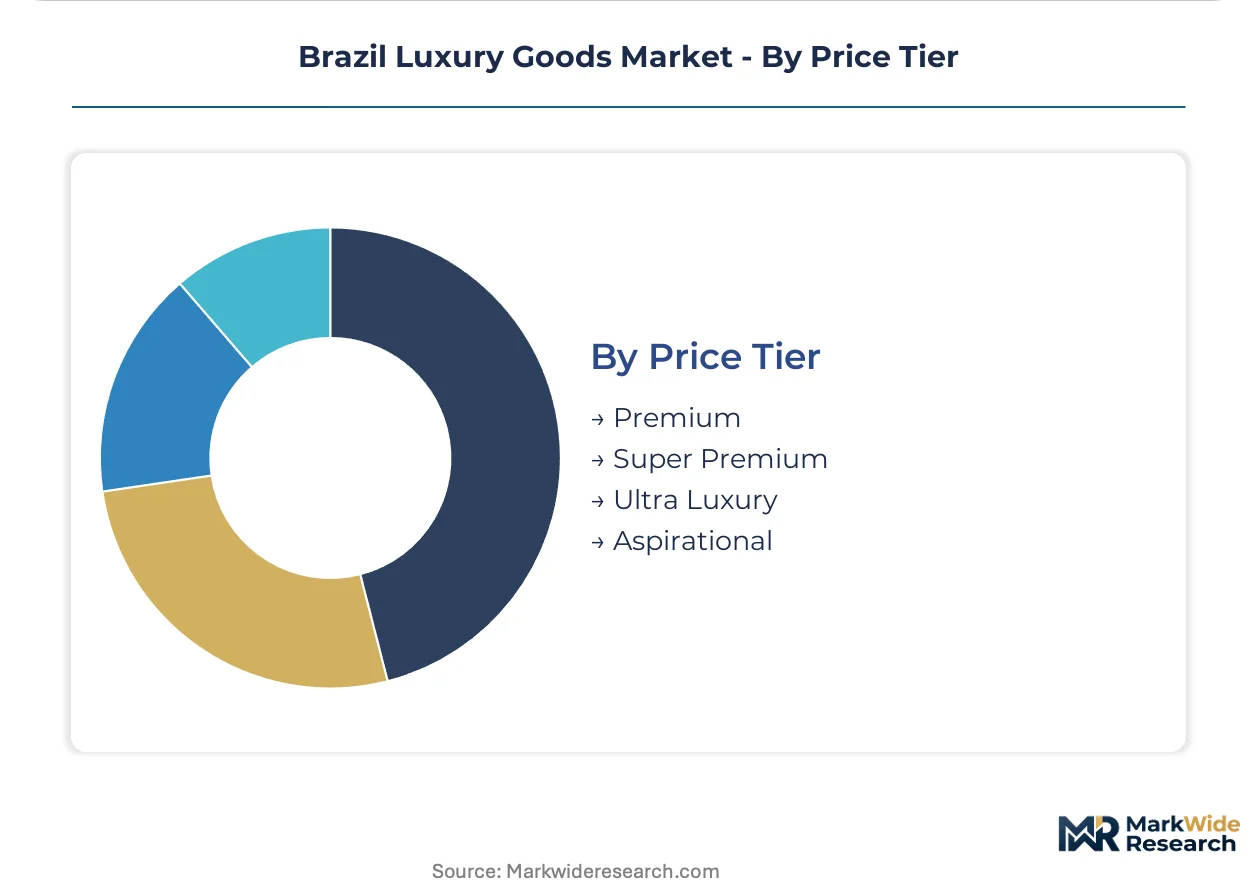
Super premium captures the largest share; ultra luxury shows steepest expansion trajectory as wealth preservation demand intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo commands pricing premiums that exceed Rio de Janeiro's luxury corridors by double-digit margins, reflecting concentrated wealth and infrastructure investment asymmetries across Brazil's Southeast region.
São Paulo
Jardins and Iguatemi districts absorb disproportionate flagship investments from European fashion maisons. ANVISA's cosmetic registration protocols compress launch timelines for fragrance houses establishing Brazilian subsidiaries. The metropolitan corridor's experiential retail density correlates with repeat purchase rates among affluent professionals.
Rio de Janeiro
Leblon and Ipanema districts concentrate ultra-high-net-worth collectors seeking bespoke jewelry and master craftsman demonstrations. INMETRO precious metal certification elevates consumer trust in domestically certified pieces from Rio's jewelry manufacturing cluster. H.Stern anchors proprietary gemstone sourcing through certified craftsmanship operations.
Minas Gerais
Belo Horizonte's emerging luxury retail footprint targets underpenetrated bridal jewelry demand outside Southeast metropolitan cores. The state's gemstone trading infrastructure supports upstream supply relationships for domestic manufacturers. Controlled retail distribution networks are expanding into this corridor to capture ceremonial purchase occasions.
Rio Grande do Sul
Porto Alegre's affluent consumer base drives accessible luxury tier volume for leather goods and accessories. The Central Bank's foreign exchange monitoring affects import financing transparency for distributors serving this southern market. Regional shopping complexes are recruiting mono-brand boutiques to diversify beyond traditional department store anchors.
Bahia
Salvador's tourism-dependent luxury demand spikes during seasonal calendar events. Tax reimbursement infrastructure affects purchase completion rates among international visitors. Northeast urban centers remain underpenetrated for mid-luxury gift categories, creating expansion opportunities for controlled retail distribution.
Brazil Luxury Goods Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across Brazil's luxury goods sector. The market structure concentrates around vertically integrated domestic manufacturers and import-dependent international houses with localized regulatory affairs capacity. Three archetypes dominate: European heritage maisons with brand equity pricing power, Brazilian leather and jewelry specialists with captive production advantages, and fragrance houses navigating ANVISA compliance requirements. Competitive moves center on experiential retail format investments and cross-border e-commerce infrastructure localization.
Among European luxury conglomerates, LVMH Moët Hennessy Louis Vuitton, Kering Group, and Compagnie Financière Richemont SA exemplify the heritage maison archetype, occupying positions defined by brand equity pricing and controlled distribution investments in São Paulo's flagship corridors. These entities represent the import-dependent international house segment facing Central Bank exchange monitoring and ANVISA registration protocol compliance costs.
| Leading Market Players |
|---|
| LVMH Moët Hennessy Louis Vuitton |
| Kering Group |
| Compagnie Financière Richemont SA |
| PUIG |
| Prada Holding S.p.A. |
| Arezzo |
| H.Stern |
| Vivara Participações S.A. |
| Chanel Limited |
| Others |
Value Chain & Pricing Dynamics
Ninety-day fragrance registration cycles at ANVISA compress inventory turns for import-dependent houses while concentrating pricing power with vertically integrated domestic producers who bypass foreign exchange exposure. This lead-time asymmetry between regulatory clearance and captive production capacity shapes margin structures across Brazil's luxury corridors.
Pricing Analysis
São Paulo's Jardins district commands price premiums that exceed Rio de Janeiro's Leblon corridor by substantial margins, reflecting infrastructure investment asymmetries and wealth concentration. Three-tier pricing structure across super-premium, premium, and aspirational levels stratifies by INMETRO certification status and brand heritage depth. Cost compression in the aspirational tier intensifies because parallel import channels undercut authorized distributor margins. Aspirational buyers exhibit highest price sensitivity while ultra-high-net-worth collectors demonstrate inelastic demand for certified master craftsmanship.
Supply Chain Analysis
Inventory cycles for Swiss precision timepieces extend well beyond domestic leather goods due to Central Bank foreign exchange monitoring and multi-layered import financing. Geographic supply concentration centers on Italy and France for fashion apparel, Switzerland for timepiece movements, and domestic Rio de Janeiro clusters for certified jewelry manufacturing. Raw material dependencies include Argentine leather hides, African gemstone rough, and European fragrance compounds. Single-source vulnerability concentrates in master artisan labor pools. Distribution runs through controlled mono-brand boutiques and department store luxury floors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Experiential service layers including bespoke customization and master craftsman demonstrations expand faster than transactional product sales, creating recurring engagement revenue that outpaces hardware margins. This service-attach dynamic redefines value capture in Brazil's luxury corridors.
For Market Incumbents: Fortify margin control through captive tannery operations and certified jewelry manufacturing clusters that insulate against currency volatility. Deepen regulatory affairs capacity to compress ANVISA registration timelines for fragrance launches. Prioritize experiential retail format investments in São Paulo's Iguatemi complex to extend client dwell time and repeat purchase rates.
For New Entrants and Emerging Players: Anchor in underpenetrated Northeast urban centers where bridal jewelry demand exceeds controlled retail distribution coverage. Target Salvador and Belo Horizonte ceremonial purchase occasions with localized fulfillment infrastructure. Establish digital authentication capabilities early to bypass legacy dealer intermediaries in secondary timepiece markets.
For Investors and Strategic Acquirers: Long-term, this sits as a scarcity-premium play because certified master craftsmanship pools in Rio de Janeiro concentrate irreplaceable human capital. Acquisition targets should display backward integration into raw material sourcing and established ANVISA compliance protocols. Monitor Central Bank foreign exchange policy shifts as inflection indicators for import-dependent house profitability.
| Strategic Initiative | Industry Significance |
|---|---|
| Experiential Retail Format Investment | Master craftsman demonstrations in Leblon and Ipanema extend dwell time and validate premium positioning. |
| Cross-Border E-Commerce Localization | Brazil's evolving digital tax compliance framework rewards first-movers with brand-controlled direct-to-consumer channels. |
| Regulatory Affairs Capacity Expansion | Localized ANVISA expertise compresses fragrance launch timelines versus competitors relying on distant headquarters. |
| Backward Integration into Tannery Operations | Captive leather production insulates Arezzo and domestic peers from Argentine hide price volatility and currency exposure. |
| Blockchain Authentication Infrastructure | Provenance verification tools reduce gray-market penetration and enable secondary market revenue capture for timepieces. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs records, Central Bank foreign exchange disclosures, and ANVISA registration databases to establish baseline market sizing. Primary interviews engaged brand managers at European heritage maisons, category buyers at São Paulo's Iguatemi and Cidade Jardim complexes, and regulatory affairs leads navigating fragrance compliance protocols. Secondary validation drew from INMETRO certification registries, Brazilian Institute of Geography and Statistics consumer expenditure surveys, and trade flow documentation. Bottom-up product category builds triangulate against top-down wealth distribution and luxury expenditure elasticity estimates.
Segmentation dimensions modeled include product type across fashion, accessories, jewelry, and watches; end-user stratification from affluent professionals to ultra-high-net-worth collectors; distribution channel evolution across e-commerce, specialty stores, and department store luxury floors; and price tier differentiation. CAGRs derive from regression analysis against macroeconomic drivers including exchange rate volatility, wealth concentration indices, and regulatory enforcement intensity. Forecast inputs incorporate bridal jewelry occasion frequency and digital authentication adoption curves.
Material uncertainties — foreign exchange regime shifts, ANVISA enforcement intensity changes, and artisan labor pool contraction — sit outside the modeled envelope and could revise trajectory materially. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Goods
Accessible Luxury Goods Market
Luxury Goods
United Arab Emirates Luxury Goods Market
Luxury Goods
Middle East and Africa Luxury Goods Market
Luxury Goods
Europe Secondhand Luxury Goods Market
Luxury Goods
Pre-Owned Luxury Watches Market
Luxury Goods
Germany Luxury Goods Market
Luxury Goods
South Korea Luxury Goods Market
Luxury Goods
Personal Luxury Goods Market
Luxury Goods
Brazil Luxury Jewelry Market
Luxury Goods
China Luxury Goods Market
Luxury Goods
Luxury Mechanical Watches Market
Luxury Goods
Malaysia Luxury Goods Market
Luxury Goods
Italy Luxury Goods Market
Luxury Goods
UAE Luxury Jewelry Market
Luxury Goods
Luxury Piano Market
Luxury Goods
Hard Luxury Goods Market