
 Qatar Luxury Good Market | 2026-2036
Qatar Luxury Good Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Luxury Good Market Analytics
Aftermarket authentication and resale certification is narrowing the traditional margin advantage of primary retail channels in Qatar's luxury ecosystem. LVMH Moët Hennessy Louis Vuitton SE leverages its vertically integrated atelier network to sustain exclusivity in Doha's premium corridors. Chalhoub Group anchors regional distribution through long-standing partnerships with European maisons. Al Fardan Group competes in fine jewelry through deep relationships with Swiss watchmakers and Gulf-based collectors.
Qatar luxury goods encompass high-value personal items including haute couture garments, precious metal jewelry, mechanical timepieces, and artisanal fragrances, typically produced through limited-batch manufacturing with heritage craftsmanship techniques and authenticated provenance documentation. These products serve status signaling, wealth preservation, and cultural celebration functions among ultra-affluent consumers. Fashion and jewelry segments dominate transaction volume in Doha's retail landscape, while super premium price tier offerings capture disproportionate margin pools through scarcity-driven allocation. Tourist client flows through Hamad International Airport channel represent the fastest-growing demand vector, though high-net-worth individuals remain the structural profit center.
Qatar's national tourism regulator and the Qatar Financial Centre shape market access through investor visa frameworks and commercial licensing requirements that privilege established luxury houses over unverified entrants. The Qatar Central Bank's anti-money laundering protocols enforce stringent provenance documentation for high-value jewelry and watch transactions exceeding specified thresholds. Stakeholders must monitor evolving customs valuation methodologies and digital authentication mandates that will determine competitive positioning in the emirate's next development phase.
Market Dynamics
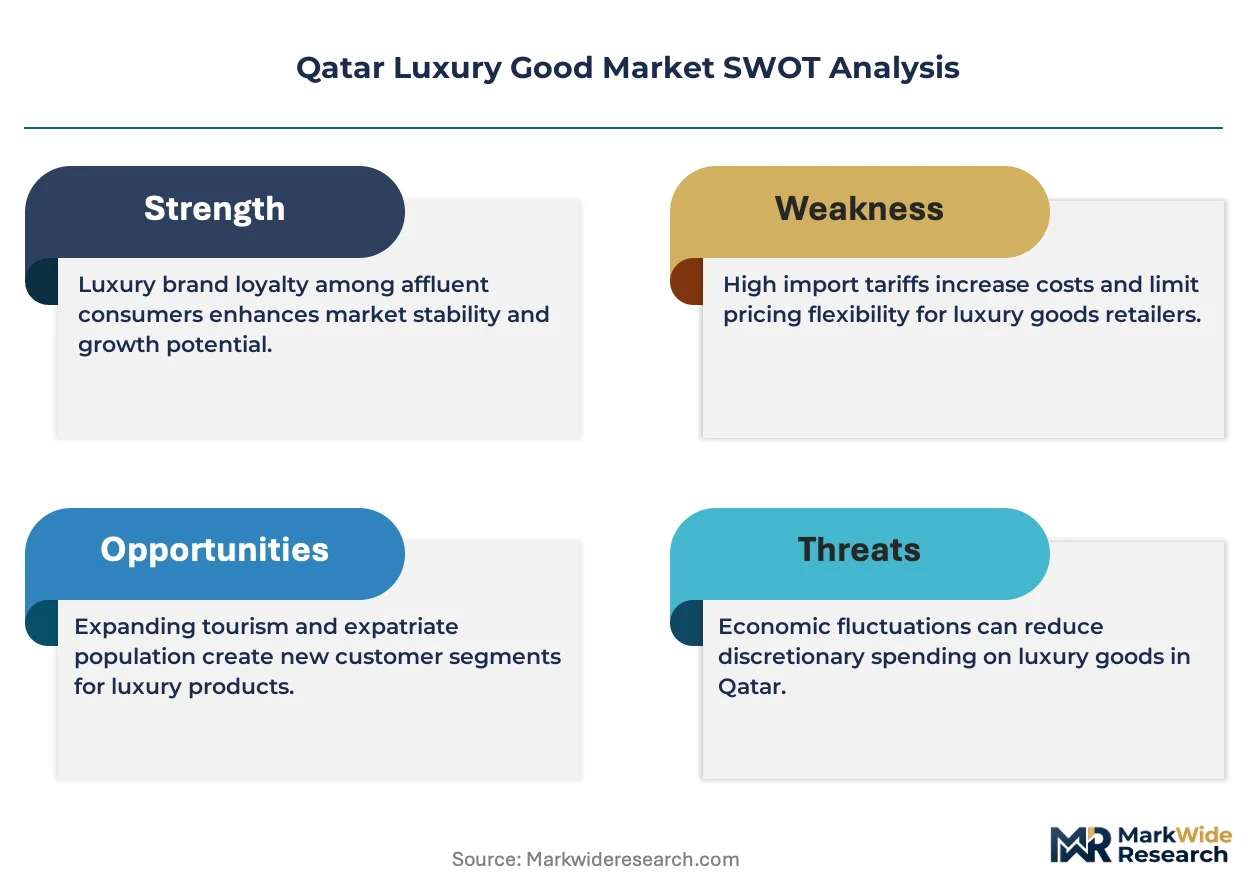
Qatar's luxury goods sector is being restructured by the Qatar Central Bank's anti-money laundering protocols, which now mandate blockchain-verified provenance documentation for high-value jewelry and watch transactions above specified thresholds.
Growth Catalysts
- Visa facilitation frameworks:The national tourism regulator's streamlined entry programs for ultra-high-net-worth visitors from Asia-Pacific and Gulf Cooperation Council jurisdictions expand the tourist client base.
- Heritage craftsmanship techniques:Limited-batch manufacturing methods using artisanal metalworking and hand-finishing processes sustain scarcity premiums in mechanical timepieces and precious metal jewelry.
- West Bay and Pearl-Qatar clustering:Flagship boutique concentration in Doha's premium districts creates destination shopping gravity that draws collectors from across the Arabian Peninsula.
Market Restraints
- Swiss watchmaker supply concentration:Dependency on a narrow base of Geneva and Vallée de Joux ateliers for mechanical movements creates allocation bottlenecks during demand surges.
- Customs valuation methodology friction:Evolving import duty calculations for consignment-based inventory transfers complicate working capital planning for regional distributors.
- Aftermarket authentication encroachment:Resale certification platforms are compressing margin pools traditionally captured by primary retail channels in fine jewelry and timepieces.
Strategic Opportunities
- Lusail development corridor:The emerging city's retail infrastructure expansion offers first-mover positioning for experiential flagship concepts beyond saturated Doha districts.
- Digital authentication mandates:Regulatory requirements for provenance documentation create competitive advantage for houses with captive blockchain verification capabilities.
- Hamad International Airport channel:Transit passenger volumes through the hub facility represent underexploited capture potential for impulse luxury purchases.
Industry Challenges
- Artisanal skill scarcity:Master watchmakers and haute couture atelier specialists command premium compensation that strains fixed cost structures.
- Legacy inventory systems:Integration complexity with digital authentication platforms requires capital deployment that mid-tier distributors struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Luxury Good Market |
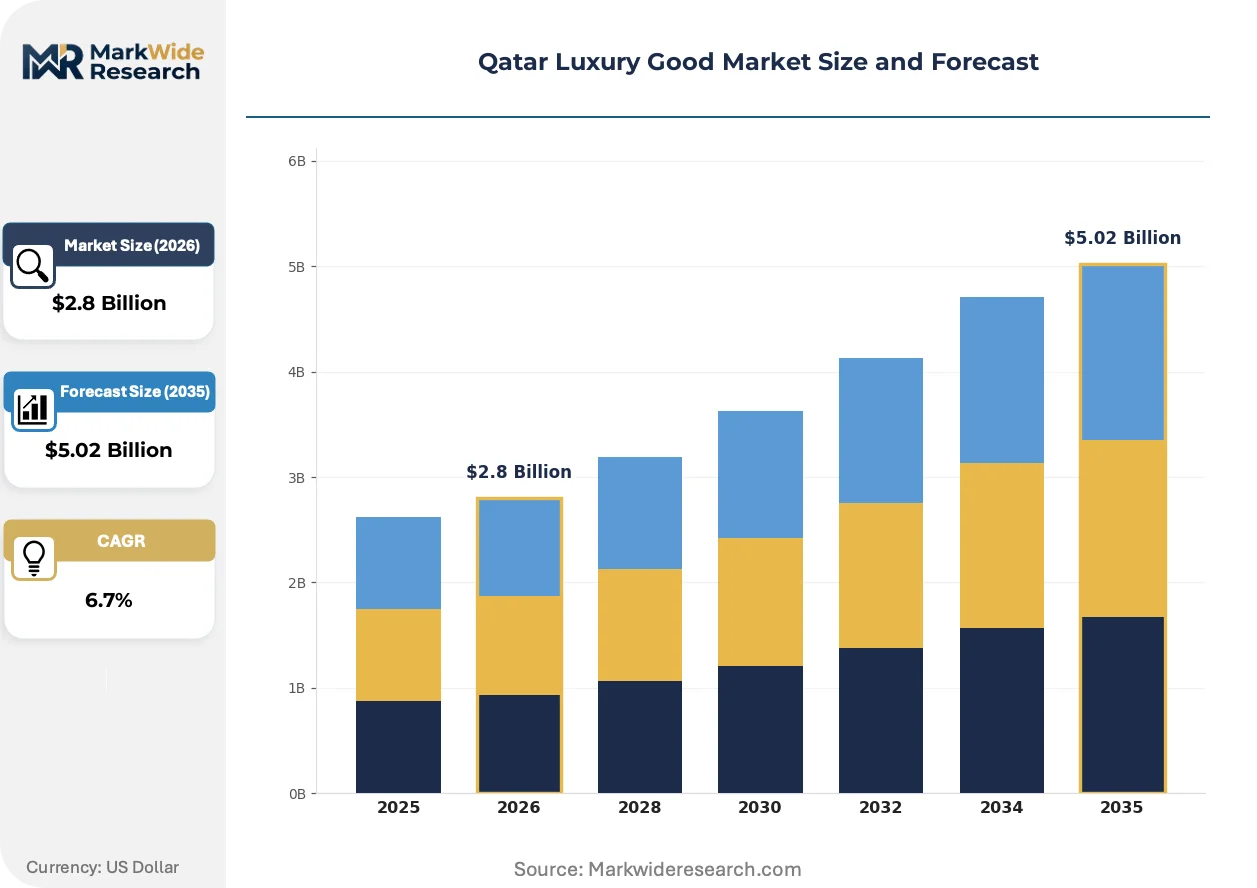
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fashion, Jewelry, Watches, Perfumes Price Tier: Premium, Super Premium, Affordable Luxury, Mass Market Client Type: High-net-worth Individuals, Retail Consumers, Corporate Clients, Tourists Distribution Channel: Online, Department Stores, Boutiques, Event Pop-ups |
| Companies Covered | LVMH Moët Hennessy Louis Vuitton SE, Kering SA, Richemont SA, Chanel SA, Rolex SA, Al Fardan Group, Chalhoub Group, Joyalukkas Group, The Estée Lauder Companies Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Luxury Good Market Evolving Landscape
Three forces are actively restructuring Qatar's luxury landscape: blockchain-based provenance verification, regulatory documentation mandates, and the unbundling of after-sales authentication from primary retail.
Blockchain ledger technology is hybridizing provenance tracking across high-value jewelry and mechanical timepiece categories. Qatari collectors and institutional buyers now demand immutable ownership records that span manufacturing origin through secondary market transfers. This capability compression is forcing traditional retailers to either develop captive verification infrastructure or cede margin to specialized authentication platforms.
The Qatar Central Bank's anti-money laundering protocols now require documented chain-of-custody for transactions exceeding specified jewelry and watch thresholds. This regulatory pressure is redirecting procurement patterns toward houses with vertically controlled supply chains. Fine jewelry segments with complex multi-source gem provenance face the steepest compliance adaptation costs.
Collector purchasing patterns are fragmenting across primary boutique, airport duty-free, and certified resale channels. Younger ultra-affluent buyers in Doha and Lusail increasingly initiate discovery through digital platforms before executing transactions in physical flagships. This channel hybridization is most pronounced among mechanical timepiece collectors seeking discontinued reference availability.
Qatar Luxury Good Market Segmentation
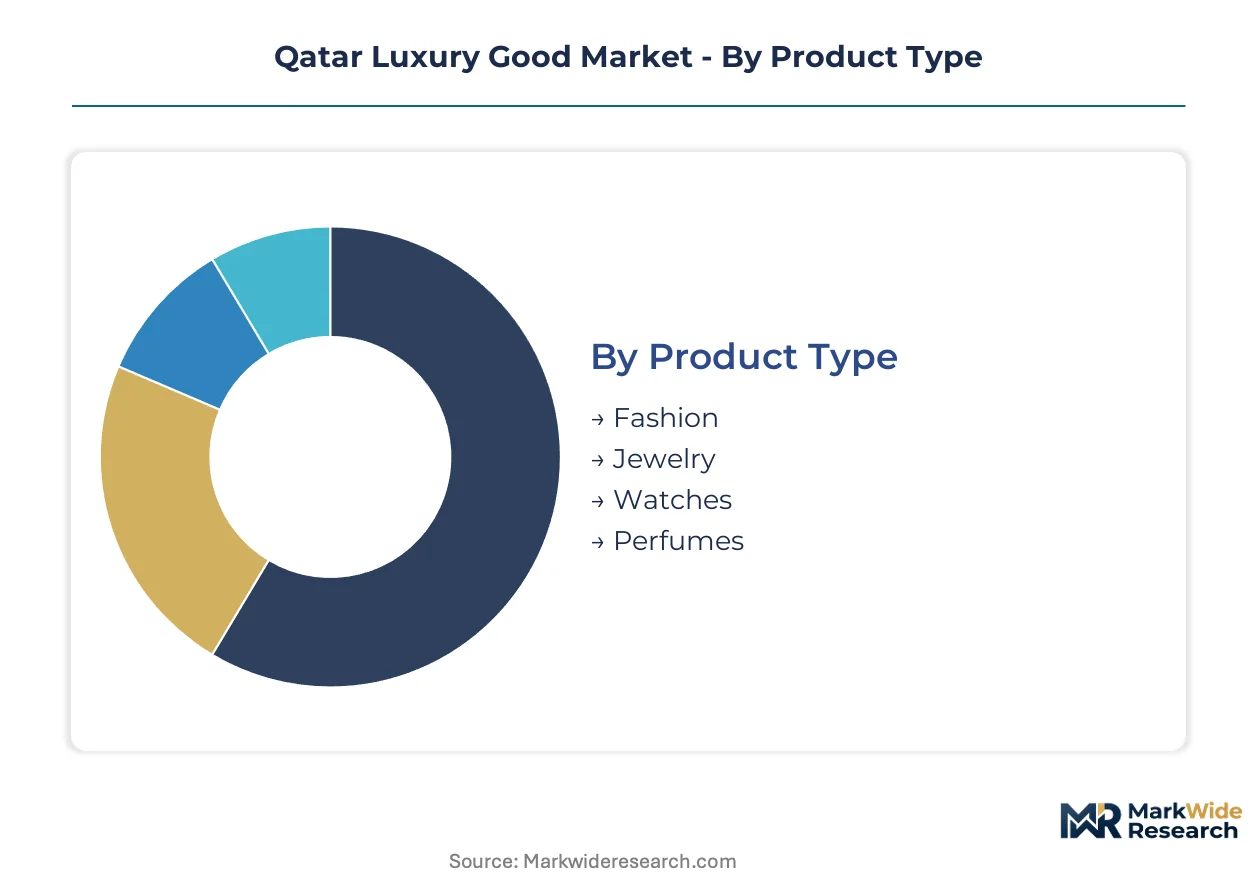
Segmentation in Qatar's luxury market reveals distinct velocity profiles across product categories, with fashion and fragrances turning inventory rapidly while jewelry and mechanical timepieces appreciate through extended holding periods. Understanding these differential cycles informs working capital deployment and boutique merchandising strategies for regional distributors.
Product Type:
Cycle times vary dramatically across this category, with seasonal fashion collections refreshing quarterly while heritage timepieces remain in collector portfolios for decades.
- Fashion:Haute couture and ready-to-wear garments from European maisons rotate through Doha's West Bay flagships on seasonal schedules. Qatari ultra-affluent consumers drive pre-order allocation battles for limited runway pieces, with Pearl-Qatar boutiques capturing the highest transaction frequency in this segment.
- Jewelry:Precious metal and gemstone pieces incorporating artisanal metalworking techniques carry the longest inventory cycles in luxury retail. The Qatar Central Bank's anti-money laundering documentation requirements for high-value transactions above specified thresholds add procedural friction to already deliberate purchase decisions.
- Watches:Mechanical timepieces from Swiss ateliers concentrate collector demand through scarcity-driven allocation systems.
- Perfumes:Artisanal fragrances with heritage composition formulas turn inventory fastest among personal luxury categories.
Fashion dominates installed base by transaction volume. Watches are where expansion concentrates among ultra-affluent collectors seeking alternative store-of-value instruments.
Price Tier:
Margin structures stratify sharply across this dimension, with super premium offerings capturing disproportionate profit pools despite lower unit velocity than accessible tiers.
- Super Premium:One-of-a-kind haute joaillerie pieces and complication timepieces priced above accessible thresholds serve wealth preservation functions for Gulf-based collectors. These transactions require bespoke consultation spaces and extended relationship cultivation through Al Fardan Group and Chalhoub Group client advisory networks.
- Premium:Established luxury house collections with recognized heritage positioning anchor revenue stability for Doha flagships. High-net-worth individuals in Lusail's emerging districts increasingly initiate relationships through this tier before graduating to bespoke commissioning.
- Affordable Luxury:Diffusion lines and accessible leather goods expand client acquisition funnels for younger ultra-affluent buyers.
- Mass Market:Licensed fragrances and entry accessories complete the accessibility pyramid for tourist impulse purchases through Hamad International Airport.
Super Premium dominates installed base by value concentration. Affordable Luxury is where expansion concentrates as generational wealth transfer accelerates in Qatari family offices.
Client Type:
Procurement authority and decision timelines diverge substantially across this dimension, from institutional corporate gifting to individual collector passion.
- High-net-worth Individuals:Ultra-affluent Qataris and resident expatriates with investable assets above specified thresholds drive bespoke commissioning for haute couture and one-of-one jewelry pieces. West Bay and Pearl-Qatar private client salons dedicate dedicated advisory teams to this segment's relationship-intensive purchase patterns.
- Tourists:Transit passengers through Hamad International Airport represent the most rapidly expanding demand vector for impulse-accessible categories. Visa facilitation frameworks from the national tourism regulator specifically target ultra-high-net-worth visitors from Asia-Pacific jurisdictions.
- Corporate Clients:Institutional procurement for diplomatic and executive gifting sustains predictable demand for recognized heritage brands.
- Retail Consumers:Self-purchase occasions among affluent professionals concentrate in fashion and fragrance categories.
High-net-worth Individuals dominate installed base by margin contribution. Tourists are climbing the fastest as visa facilitation frameworks expand eligible visitor pools.
Distribution Channel:
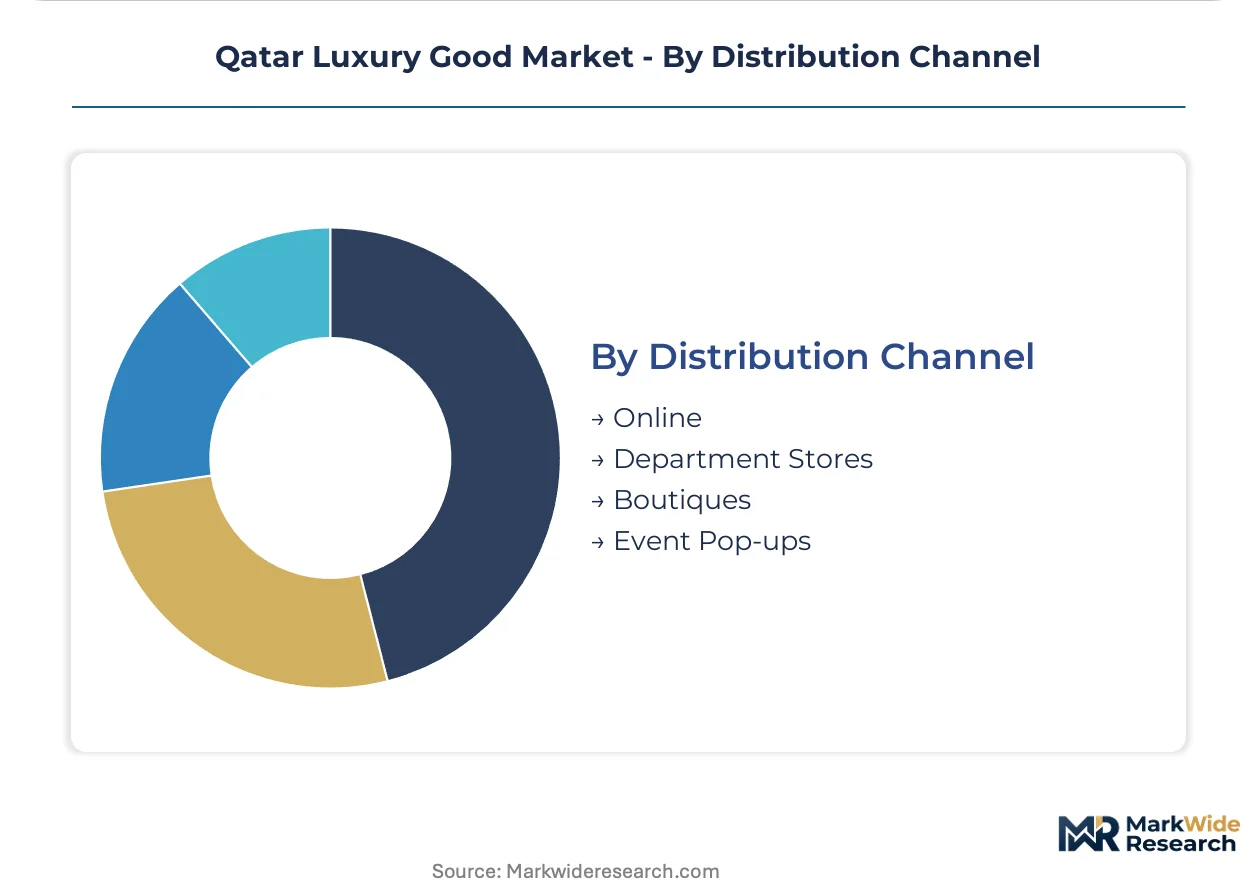
Channel economics reflect diverging cost structures and authentication requirements, with physical flagships carrying premium positioning that digital platforms struggle to replicate.
- Boutiques:Flagship locations in Doha's West Bay and Pearl-Qatar districts concentrate the highest-value transactions and relationship-based selling for mechanical timepieces and fine jewelry. LVMH Moët Hennessy Louis Vuitton SE and partner distributors invest experiential concepts in these locations to sustain exclusivity perception.
- Online:Digital discovery platforms increasingly initiate purchase journeys among younger ultra-affluent collectors, though high-value jewelry and watch transactions still close in physical environments. Blockchain-verified provenance documentation requirements from the Qatar Central Bank create infrastructure advantages for houses with captive digital authentication capabilities.
- Department Stores:Multi-brand environments in luxury retail complexes capture tourist footfall and accessible-tier browsing.
- Event Pop-ups:Temporary installations aligned with cultural and sporting calendar moments generate scarcity-driven purchase urgency.
Boutiques dominate installed base by revenue concentration. Online is gaining share fastest as digital-native collectors enter the ultra-affluent demographic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Geneva and Paris ateliers supply the mechanical movements and haute couture that anchor Qatar's luxury retail corridors. Swiss watchmaking clusters and Italian leather goods districts shape inventory composition across Doha flagships.
France
French heritage maisons dominate haute couture and leather goods allocation to Qatari distributors. The French national anti-money laundering authority enforces stringent provenance documentation that aligns with Qatar Central Bank protocols. Parisian ateliers in the Marais and Faubourg Saint-Honoré districts concentrate artisanal capacity for limited-batch production destined for Gulf markets.
Switzerland
Swiss mechanical movement manufacturers control scarcity-driven allocation systems for complication timepieces. Swissmedic and the State Secretariat for Economic Affairs administer export licensing frameworks that govern high-value watch transfers to Middle Eastern distributors. The Vallée de Joux and Geneva cantons host vertically integrated ateliers supplying Chalhoub Group and Al Fardan Group procurement networks.
Italy
Italian leather goods and fine jewelry manufacturers sustain artisanal craftsmanship premiums in Qatar's super premium tier. The Italian Ministry of Economic Development oversees Made in Italy certification protocols that verify manufacturing origin for import documentation. Tuscan tanneries and Milanese design studios cluster production capacity for seasonal collections rotating through Pearl-Qatar boutiques.
United Kingdom
British heritage brands anchor corporate gifting demand from Qatari institutional clients. The UK Financial Conduct Authority's anti-money laundering guidance influences documentation standards adopted by Qatar Financial Centre-licensed distributors. London's Mayfair district concentrates private client advisory capacity serving ultra-high-net-worth collectors from the Arabian Peninsula.
United Arab Emirates
UAE-based regional distributors operate parallel procurement channels that compete with direct Qatar flagships. The UAE's Ministry of Economy administers commercial agency laws that structure partnership terms between European maisons and Gulf distributors. Dubai's Mall of the Emirates and City Walk clusters draw cross-border shopping traffic from Doha residents seeking allocation advantages.
Qatar Luxury Good Market Competitive Landscape
Vertically integrated European maisons and regional distribution specialists split the market into distinct competitive spheres. Consolidation around heritage atelier networks limits entry for unverified challengers. Two strategic archetypes dominate: captive supply chain operators with in-house manufacturing capacity, and relationship-based distributors leveraging long-standing Gulf collector networks. Competitive moves concentrate on exclusive retail licensing agreements and experiential flagship concept deployment.
Within the captive supply chain tier, LVMH Moët Hennessy Louis Vuitton SE and Richemont SA exemplify vertically integrated control over manufacturing and distribution. Among regional specialists, Chalhoub Group and Al Fardan Group occupy positions anchored by multi-decade relationships with European maisons and Gulf-based collector communities. These four entities represent the structural poles around which Qatar's luxury retail configuration organizes.
| Leading Market Players |
|---|
| LVMH Moët Hennessy Louis Vuitton SE |
| Kering SA |
| Richemont SA |
| Chanel SA |
| Rolex SA |
| Al Fardan Group |
| Chalhoub Group |
| Joyalukkas Group |
| The Estée Lauder Companies Inc. |
| Others |
Value Network & Pricing Analysis
Atelier undercapacity in Geneva and the Vallée de Joux drives allocation rigidity for mechanical movements, forcing Qatari distributors to accept stringent pre-order terms while Swiss houses capture pricing power through scarcity-driven release schedules.
Pricing Analysis
After-sales service revenue from authentication, restoration, and extended warranty programs sustains lifetime value for mechanical timepieces and fine jewelry. Three-tier pricing structure across super premium, premium, and accessible luxury levels stratifies by craftsmanship intensity and provenance documentation depth. Pricing pressure stems from aftermarket authentication platforms compressing traditional retail margins. Tourist buyers at Hamad International Airport exhibit highest price sensitivity, while ultra-high-net-worth collectors in West Bay private salons demonstrate minimal elasticity for one-of-one commissions.
Supply Chain Analysis
Swissmedic export licensing frameworks restrict mechanical movement flows to Middle Eastern distributors, creating procedural friction for high-value watch transfers. Supply concentrates in Switzerland for complications, France for haute couture and leather goods, and Italy for artisanal jewelry and fragrances. Raw material dependencies span precious metals from Swiss refiners, gemstones from Antwerp and Mumbai cutting centers, and exotic leather from Tuscan tanneries. Single-source vulnerability runs through Geneva atelier networks for tourbillon and perpetual calendar movements. Distribution runs through Chalhoub Group and Al Fardan Group procurement networks serving Doha and Lusail flagships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Master watchmaker scarcity and captive atelier capacity constraints define competitive advantage in this market, with artisanal skill gaps widening between heritage houses and distributor-dependent challengers.
For Market Incumbents: Entrench exclusivity through backward integration into blockchain-verified provenance systems that satisfy Qatar Central Bank documentation mandates. Expand experiential flagship concepts in Lusail's emerging retail corridor before saturation. Defend against aftermarket authentication encroachment by capturing resale certification revenue through captive secondary market platforms. For New Entrants and Emerging Players: Build out digital-native discovery platforms targeting younger ultra-affluent collectors in Doha and Lusail who initiate purchase journeys online before physical transaction closure. Target the affordable luxury tier as generational wealth transfer accelerates in Qatari family offices. Pursue white-space positioning through Hamad International Airport duty-free concessions for impulse-accessible categories. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across blockchain authentication infrastructure and experiential retail buildouts. Long-term viability favors vertically integrated houses with captive atelier networks over distributor-dependent models. Monitor Qatar Central Bank digital documentation mandate enforcement as inflection indicator for compliance cost advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Provenance Integration | Captive verification capabilities satisfy Qatar Central Bank anti-money laundering protocols and capture resale authentication revenue. |
| Lusail Flagship Expansion | First-mover positioning in the emerging city's retail infrastructure escapes West Bay and Pearl-Qatar saturation. |
| Master Watchmaker Recruitment | Artisanal skill acquisition from Vallée de Joux ateliers secures allocation priority for scarce complication movements. |
| Airport Duty-Free Concession | Hamad International Airport transit volumes represent underexploited impulse purchase capture for accessible luxury tiers. |
| Private Client Advisory Network | Relationship-intensive selling through Al Fardan and Chalhoub advisory teams sustains super premium transaction margins. |
Research Methodology
Cross-validation between distributor procurement executives and European maison regional directors anchors the qualitative findings. Primary interviews with Qatar Financial Centre licensing officers, Qatar Central Bank compliance specialists, Swiss watchmaker atelier managers, and Pearl-Qatar boutique directors combined with secondary validation from customs documentation, SEC filings of listed luxury groups, and Swissmedic export licensing records. Bottom-up transaction analysis and top-down market sizing triangulate volume estimates.
Calibration against historical allocation patterns and visa facilitation framework expansion rates shapes the projection framework. Segmentation dimensions span product type, price tier, client archetype, and distribution channel across the analysis window. CAGRs derive from trend extrapolation moderated by supply concentration constraints and regulatory documentation adoption curves. Artisanal capacity utilization and blockchain verification infrastructure deployment serve as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by mid-tier distributors would shift outcomes. Material shifts in Qatar Central Bank digital authentication mandate timelines or Swiss export licensing restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Goods
Watch Winder Market
Luxury Goods
France Luxury Goods Market
Luxury Goods
Luxury Mechanical Watches Market
Luxury Goods
Spain Luxury Goods Market
Luxury Goods
Singapore Luxury Goods Market
Luxury Goods
Europe Handbags Market
Luxury Goods
Wooden Watch Market
Luxury Goods
South Korea Luxury Goods Market
Luxury Goods
Spain Luxury Jewelry Market
Luxury Goods
Thailand Luxury Goods Market
Luxury Goods
Pre-Owned Luxury Watches Market
Luxury Goods
Europe Secondhand Luxury Goods Market
Luxury Goods
Hard Luxury Goods Market
Luxury Goods
United Kingdom Luxury Goods Market
Luxury Goods
Mens Watch Market
Luxury Goods
Luxury Watches Market