
 Thailand Luxury Goods Market | 2026-2036
Thailand Luxury Goods Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Luxury Goods Market Analytics
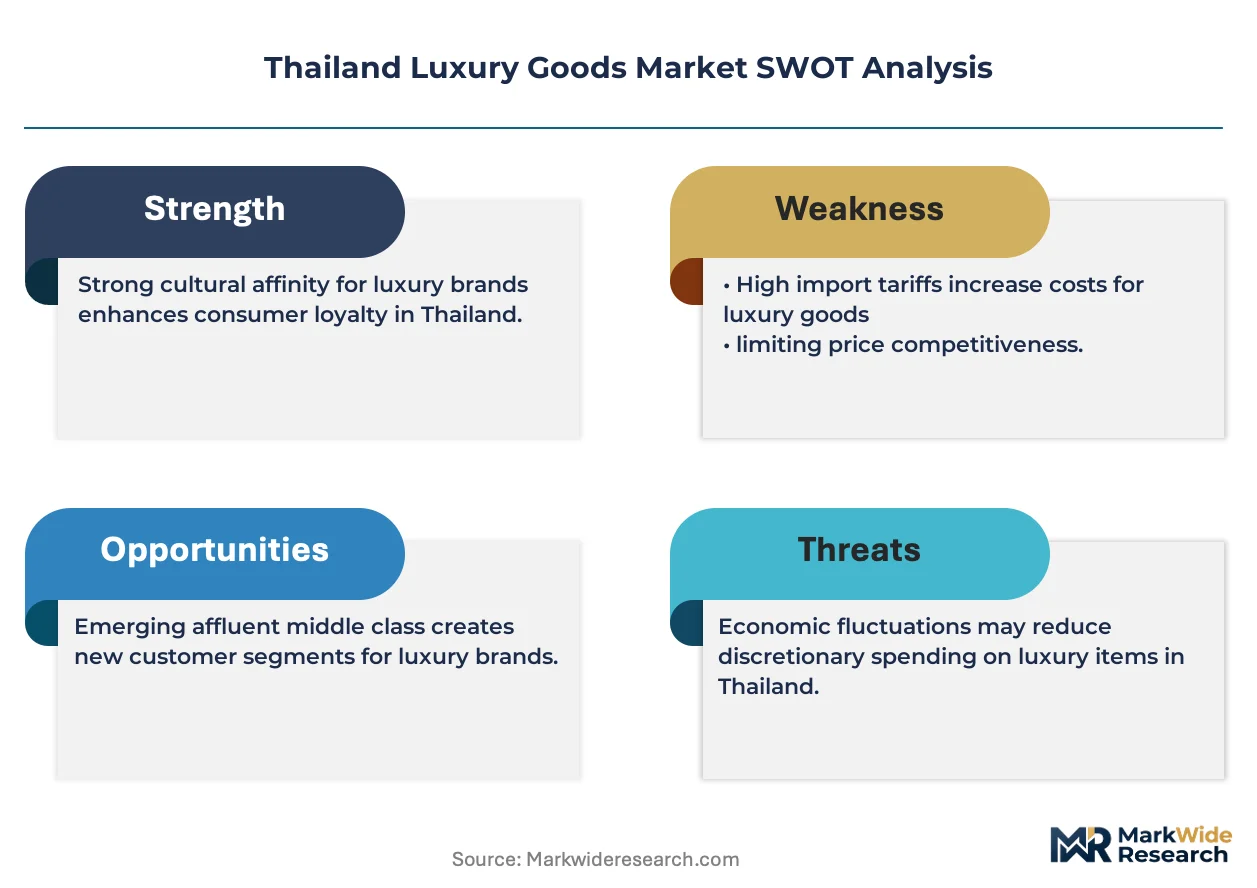
Thailand's evolving environmental compliance framework is restructuring how luxury houses source materials and certify supply chains. LVMH Moët Hennessy Louis Vuitton SE anchors its regional leather-goods production through controlled atelier networks. Kering SA differentiates via regenerative agriculture commitments across its Thai silk and cotton suppliers. Hermès International SA dominates the ultra-premium saddle-leather segment through captive tannery relationships.
Luxury goods encompass high-value, non-essential products characterized by superior craftsmanship, scarcity signaling, and price inelasticity, typically utilizing precious metals, exotic leathers, or hand-finished mechanical movements to denote status and durability. Fashion and jewelry together occupy the dominant value share, driven by Thai ceremonial gifting traditions and wedding expenditure patterns. Watches represent the fastest-growing category as Bangkok collectors deepen exposure to haute horlogerie auction circuits. Accessories sustain reliable margin pools through repeat-purchase leather goods and small leather items with lower entry price thresholds.
Thailand's Consumer Protection Board and Department of Intellectual Property enforce anti-counterfeiting protocols that shape brand protection investments and channel authorization requirements. The country's Revenue Department transfer-pricing audits and customs valuation rules directly influence how houses structure import markups and local entity profitability. Stakeholders must monitor evolving digital service tax proposals and cross-border e-commerce duty thresholds that could reroute tourist and resident purchasing behavior between domestic boutiques and offshore platforms.
Market Dynamics
Thailand's Board of Investment green manufacturing incentives are restructuring material sourcing mandates, forcing luxury houses to reconfigure atelier networks and captive tannery relationships to maintain domestic production eligibility.
Growth Catalysts
- Regenerative agriculture frameworks:Kering SA's soil-health commitments across Thai silk suppliers are creating certified fiber pipelines that attract EU import preferences under deforestation-free supply chain rules.
- Ultra-high-net-worth residential clustering:Bangkok's Sukhumvit corridor concentration of wealth is compressing customer acquisition costs for flagship boutiques through organic foot traffic density.
- Haute horlogerie auction circuits:Thai collector participation in regional watch auctions is deepening secondary market liquidity and primary-market brand equity simultaneously.
Market Restraints
- Exotic leather input volatility:CITES permitting delays for crocodile and python skins are extending raw material procurement cycles by 8-14 months for saddle-leather producers.
- Transfer-pricing audit exposure:Thailand's Revenue Department scrutiny of import markups is compressing profit repatriation flexibility for houses with regional headquarters structures.
- Digital service tax uncertainty:Pending cross-border e-commerce duty thresholds threaten to divert tourist spending toward offshore platforms with pricing arbitrage advantages.
Strategic Opportunities
- Chiang Mai artisan corridor development:Northern Thailand's untapped craft heritage offers lower-cost atelier expansion outside Bangkok's saturated real estate.
- Ceremonial gifting digitization:Blockchain-verified provenance certificates for wedding jewelry purchases are penetrating younger affluent demographics.
- BOI carbon-neutral production incentives:Renewable energy commitments in manufacturing are unlocking tax holidays that improve unit economics for export-oriented leather goods.
Industry Challenges
- Master craftsperson pipeline gaps:Saddle-stitch and hand-finishing skills require 5-7 year apprenticeships that outpace current training program throughput.
- Anti-counterfeiting enforcement fragmentation:Coordination gaps between Thailand's Consumer Protection Board and Department of Intellectual Property create jurisdictional delays in raid execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Luxury Goods Market |
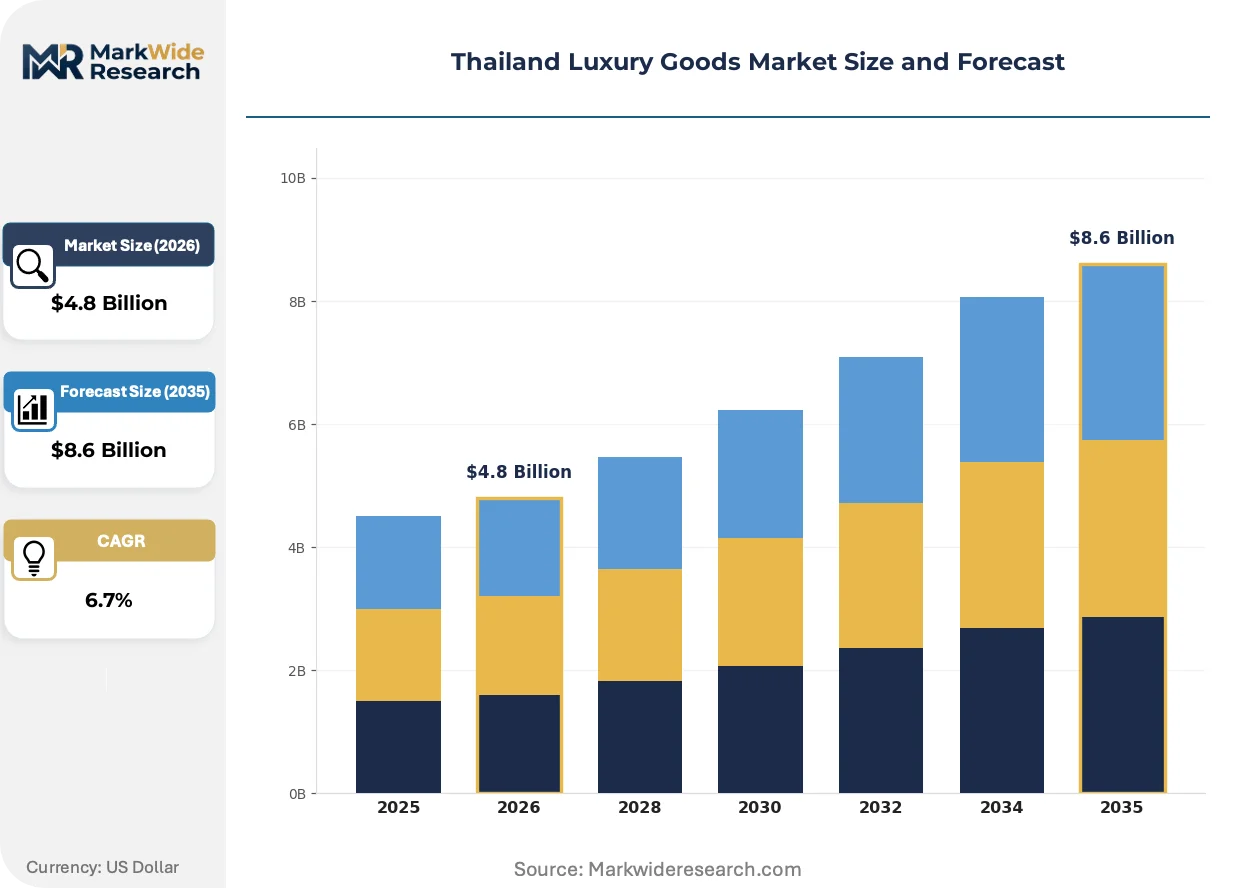
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Category: Fashion, Jewelry, Watches, Accessories Customer Type: Affluent Individuals, Tourists, Collectors, Celebrities Sales Channel: Online Retail, Brick-and-Mortar, Luxury Boutiques, Department Stores Service Type: Personal Shopping, Concierge Services, After-Sales Support, Customization |
| Companies Covered | Hermès International SA, Richemont SA, LVMH Moët Hennessy Louis Vuitton SE, Tiffany & Co., Cartier, Kering SA, Prada SpA, Bulgari, Chanel SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Luxury Goods Market Evolving Landscape
Material traceability technologies and circular service models are restructuring how Thai consumers authenticate value and extend product lifecycles, compressing traditional resale channel margins.
Blockchain-based supply chain verification is converging with physical RFID-NFC hybrid tags to create tamper-evident provenance records. Bangkok's ultra-premium jewelry houses are piloting these systems for wedding expenditure pieces where ceremonial gifting demands documentary certainty. This convergence is compressing authentication service margins and displacing third-party certifiers.
Thailand's evolving digital service tax proposals are forcing recalculation of cross-border e-commerce fulfillment economics. The Revenue Department's draft framework would capture offshore platform transactions previously exempt under tourist duty allowances. High-frequency purchasers in Bangkok's Silom corridor are responding by consolidating orders through domestic flagship channels to preserve after-sales service entitlements.
Collector behavior around haute horlogerie is rotating toward experiential ownership models. Thai auction participants now prioritize consignment relationships with authorized service centers over pure price optimization. This pivot is visible among Bangkok's Sukhumvit residential clusters where maintenance-access guarantees outweigh secondary-market premiums in purchase decisions.
Thailand Luxury Goods Market Segmentation
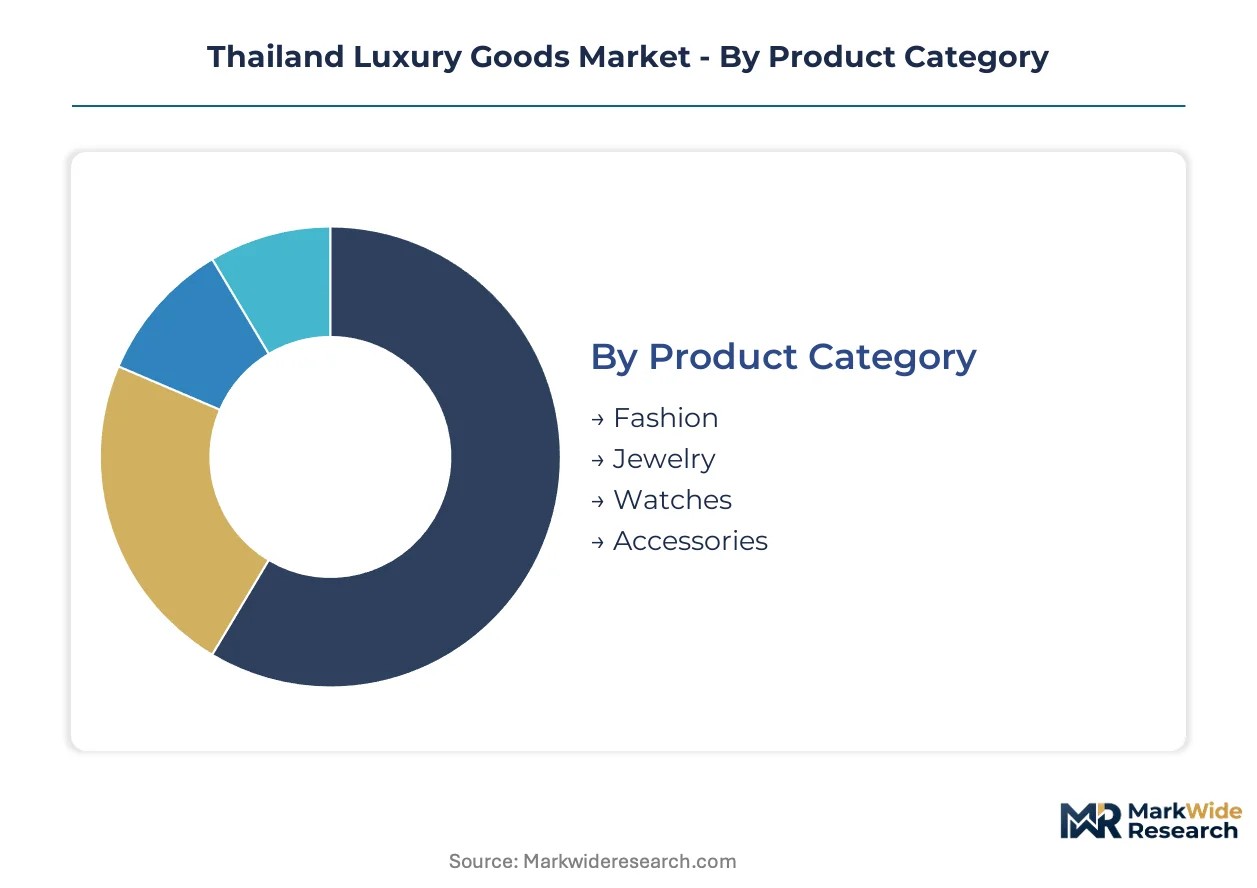
Thai luxury consumption fragments across ceremonial gifting traditions, collector investment behavior, and experiential service expectations. Understanding these segment boundaries clarifies how houses allocate capital between Bangkok flagship investments and emerging northern craft corridors.
Product Category:
Purchase motivation pivots on occasion specificity and asset-like durability expectations.
- Fashion:Ready-to-wear and couture collections utilizing Thai silk blends and regenerative cotton fibers. Bangkok's Sukhumvit corridor drives volume through affluent millennial wardrobe refresh cycles tied to social calendar density.
- Jewelry:High-carat gold, platinum, and gemstone pieces with blockchain-verified provenance for wedding expenditure. Ceremonial gifting in Bangkok's Silom district concentrates demand during Q4 wedding season peaks.
- Watches:Mechanical haute horlogerie with authorized service center access prioritized over secondary-market premiums. Thai collectors deepen auction circuit participation, expanding both primary and resale liquidity.
- Accessories:Leather goods and small leather items with controlled entry price thresholds and repeat-purchase economics.
Fashion leads on scale; watches lead on momentum.
Customer Type:
Spending concentration correlates with residential proximity to flagship clusters and cross-border mobility patterns.
- Affluent Individuals:Bangkok-based high-net-worth households with sustained domestic purchasing and BOI incentive-driven local production preference. Sukhumvit and Silom residential zones compress customer acquisition costs through organic foot traffic.
- Tourists:Cross-border visitors from ASEAN markets and China responding to duty differential arbitrage. Pending digital service tax proposals threaten to divert spending toward offshore platforms.
- Collectors:Auction-active participants prioritizing maintenance-access guarantees and experiential ownership models over pure price optimization.
- Celebrities:Brand ambassador relationships and seeding programs generating earned media amplification within Thai entertainment industry networks.
Affluent individuals anchor revenue stability; collectors drive margin expansion through consignment economics.
Sales Channel:
Channel selection reflects after-sales service entitlement valuation and authentication certainty requirements.
- Online Retail:Cross-border e-commerce platforms facing Revenue Department duty threshold recalibration. High-frequency purchasers consolidate orders through domestic channels to preserve service guarantees.
- Brick-and-Mortar:Concession formats within Thai department store networks with standardized fixture investments and shared foot traffic economics.
- Luxury Boutiques:Flagship-controlled environments in Bangkok's Sukhumvit corridor with dedicated clienteling staff and private appointment infrastructure.
- Department Stores:Central Group and The Mall Group anchor tenants with co-located beauty and jewelry adjacencies driving cross-category basket expansion.
Luxury boutiques capture premium pricing power; online retail faces regulatory compression.
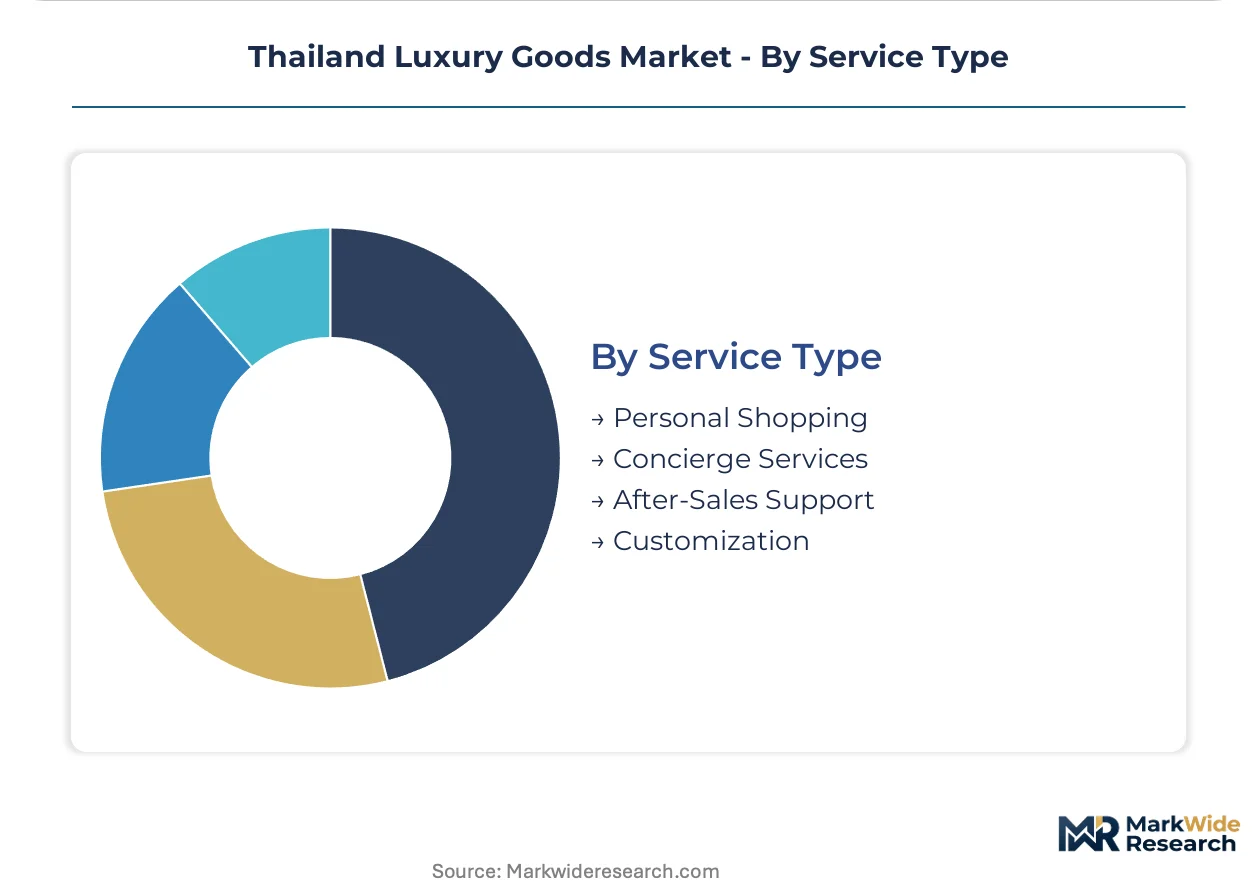
Service Type:
Service tier selection signals customer lifetime value segmentation and relationship depth.
- Personal Shopping:Dedicated stylist assignments with wardrobe auditing and occasion-specific curation. Bangkok's ultra-high-net-worth residential clusters sustain full-time staff-to-client ratios.
- Concierge Services:Event access, travel coordination, and lifestyle management extending brand relationship beyond product transactions.
- After-Sales Support:Authorized repair networks for mechanical watches and leather restoration, increasingly prioritized over independent service providers.
- Customization:Bespoke material selection, monogramming, and made-to-measure programs with 8-14 week fulfillment cycles tied to exotic leather procurement delays.
After-sales support secures retention; customization commands price premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thai luxury consumption traces its modern lineage to Bangkok's 1980s hospitality boom, when international hoteliers established the city's first high-end retail corridors. Sukhumvit and Silom districts subsequently anchored flagship clustering patterns that persist today.
Bangkok Metropolitan Region
Ultra-high-net-worth residential concentration in Sukhumvit and Silom corridors drives organic foot traffic density for flagship boutiques. Thailand's Board of Investment green manufacturing incentives are restructuring material sourcing mandates for atelier networks. The Ratchaprasong shopping district hosts Central Group anchor tenants where cross-category basket expansion sustains concession economics.
Chiang Mai and Northern Thailand
Untapped craft heritage in Chiang Mai offers lower-cost atelier expansion outside Bangkok's saturated real estate. The country's Revenue Department transfer-pricing scrutiny has less enforcement bandwidth in secondary cities. Artisan clusters in Lamphun and San Kamphaeng are developing silk and cotton processing capabilities for regenerative fiber pipelines.
Eastern Economic Corridor
Rayong and Chonburi provinces host BOI-promoted manufacturing zones with carbon-neutral production tax holidays. Renewable energy commitments in these industrial parks improve unit economics for export-oriented leather goods. Laem Chabang port proximity reduces logistics friction for regional distribution.
Phuket and Southern Tourism Corridors
Duty differential arbitrage attracts ASEAN and Chinese tourists to luxury retail in beach resort zones. Pending digital service tax proposals threaten to divert spending toward offshore platforms with pricing advantages. Central Phuket and Jungceylon malls concentrate brand presence where tourist footfall peaks during Q4 high season.
Thailand Luxury Goods Market Competitive Landscape
Capital-heavy producers with captive tannery and atelier networks compete with asset-light houses relying on outsourced craftsmanship and licensed distribution. Market structure tilts toward consolidated control among French and Swiss conglomerates with multi-brand portfolios. Three archetypes dominate: vertically integrated leather-goods specialists, diversified luxury conglomerates with hard-goods exposure, and jewelry-focused maisons with ceremonial gifting expertise. Dominant competitive moves include regenerative agriculture certification partnerships and authorized service center network expansion.
Within the vertically integrated tier, Hermès International SA exemplifies captive supply chain control through saddle-leather tannery relationships. LVMH Moët Hennessy Louis Vuitton SE and Kering SA occupy positions as diversified conglomerates restructuring Thai sourcing around BOI green manufacturing compliance. These three anchors represent distinct strategic postures: single-brand depth versus multi-brand breadth versus sustainability-first differentiation.
| Leading Market Players |
|---|
| Hermès International SA |
| Richemont SA |
| LVMH Moët Hennessy Louis Vuitton SE |
| Tiffany & Co. |
| Cartier |
| Kering SA |
| Prada SpA |
| Bulgari |
| Chanel SA |
| Others |
Value Network & Pricing Analysis
Captive tannery relationships anchor pricing power for ultra-premium leather goods houses while compressing margin exposure to CITES-regulated exotic skin volatility. Thailand's Board of Investment green manufacturing incentives reward backward integration into renewable energy-powered atelier networks, creating cost advantages that reinforce entry price thresholds for domestic production.
Pricing Analysis
Three-tier pricing structure across ultra-premium, premium, and accessible luxury levels dominates Thai market positioning. Price differentiation rests on craftsmanship certification tiers and authorized after-sales service bundling rather than material cost alone. Pricing pressure stems from Revenue Department transfer-pricing scrutiny compressing import markup flexibility for regional headquarters structures. Tourist segments exhibit highest price sensitivity due to pending digital service tax arbitrage opportunities, while Bangkok's Sukhumvit residential collectors prioritize maintenance-access guarantees over discount optimization.
Supply Chain Analysis
Regional distribution centers in Laem Chabang and Bangkok's free trade zones coordinate hub-and-spoke fulfillment to domestic flagship boutiques and department store concessions. Raw material procurement draws from Italian and French tanneries for saddle-leather, Thai silk suppliers in Lamphun for regenerative fiber pipelines, and CITES-permitted Southeast Asian farms for exotic skins. Single-source vulnerability concentrates in master craftsperson apprenticeship pipelines requiring 5-7 year training cycles. Distribution runs through controlled flagship channels where authorized service entitlements secure customer retention.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's luxury goods market functions as a geographic-arbitrage play between Bangkok's high-cost flagship real estate and Chiang Mai's lower-cost artisan corridor, with Revenue Department enforcement bandwidth thinning outside the capital.
For Market Incumbents: Deepen captive atelier control in Chiang Mai's emerging craft corridor to secure BOI carbon-neutral production tax holidays before real estate costs converge with Bangkok levels. Counter transfer-pricing audit exposure by restructuring import markups through documented local manufacturing value-add. Prioritize authorized service center network expansion as the defensive moat against secondary-market price transparency. For New Entrants and Emerging Players: Northern Thailand's ceremonial gifting digitization gap offers white-space entry through blockchain-verified provenance certificates targeting millennial wedding expenditure. Lamphun's untapped silk processing infrastructure provides lower-cost fiber sourcing outside Bangkok's saturated supplier base. Launch through domestic e-commerce consolidation plays that preserve after-sales service entitlements under pending Revenue Department duty threshold changes. For Investors and Strategic Acquirers: Roll-up economics work for vertically integrated leather-goods specialists with captive tannery relationships because master craftsperson pipeline gaps create irreplicable capability scarcity. Long-term viability hinges on BOI incentive renewal trajectories and deforestation-free supply chain certification durability. Monitor CITES permitting reform signals as inflection indicators for exotic leather input cost normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Chiang Mai Atelier Expansion | BOI tax holidays improve unit economics for carbon-neutral leather goods production. |
| Blockchain Provenance Integration | Thai wedding expenditure patterns demand documentary certainty for ceremonial gifting. |
| Authorized Service Center Network | Bangkok collectors prioritize maintenance-access guarantees over secondary-market premiums. |
| Regenerative Agriculture Certification | Kering's soil-health commitments attract EU import preferences under deforestation-free rules. |
| Digital Service Tax Compliance | Revenue Department scrutiny forces recalculation of cross-border e-commerce fulfillment economics. |
Research Methodology
Coverage spans Bangkok Metropolitan Region, Chiang Mai and Northern Thailand, Eastern Economic Corridor, and Phuket tourism corridors, with primary inputs from each. Interviews with brand country managers, atelier production heads, department store concession directors, and Revenue Department tax specialists combined with secondary validation from Thailand's Board of Investment filings, customs valuation records, and Central Group tenant disclosure patterns. Bottom-up demand modeling triangulated against top-down macroeconomic consumption indicators.
Granularity-level modeling tracked product category, customer type, sales channel, and service type dimensions at the sub-segment level across the projection horizon. CAGRs derived from trend extrapolation anchored in historical luxury consumption elasticity patterns and forward-looking regulatory assumption sets. Forecast inputs incorporated BOI incentive renewal probabilities and CITES permitting cycle normalization scenarios without year-specific triggers.
Underlying measurement precision varies by segment; Bangkok flagship channel data carries tighter precision than emerging Chiang Mai artisan corridor estimates. Forecasts reflect documented assumptions around transfer-pricing enforcement intensity and digital service tax implementation timing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Goods
Middle East and Africa Luxury Goods Market
Luxury Goods
Accessible Luxury Goods Market
Luxury Goods
Pre-Owned Luxury Watches Market
Luxury Goods
France Luxury Goods Market
Luxury Goods
Global Gold Jewelry Market
Luxury Goods
North America Luxury Goods Market
Luxury Goods
Spain Luxury Jewelry Market
Luxury Goods
Luxury Resale Platform Market
Luxury Goods
Spain Luxury Goods Market
Luxury Goods
United Kingdom Luxury Goods Market
Luxury Goods
Russia Luxury Goods Market
Luxury Goods
Europe Secondhand Luxury Goods Market
Luxury Goods
Designer Bags and Luxury Handbags Market
Luxury Goods
Watch Winder Market
Luxury Goods
GCC Secondhand Luxury Goods Market
Luxury Goods
Global Gold and Diamond Jewellery Market