
 GCC Luxury Goods Market | 2026-2036
GCC Luxury Goods Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Luxury Goods Market Insights
Buyer concentration among ultra-high-net-worth individuals in Riyadh and Dubai is recalibrating how brands allocate inventory and clienteling resources across the Gulf. LVMH Moët Hennessy Louis Vuitton leverages its multi-brand portfolio to capture spending from both established collectors and newly affluent entrants. Chalhoub Group anchors its regional dominance through controlled distribution networks spanning flagship boutiques and duty-free corridors. Kering SA differentiates via selective retail partnerships that limit geographic overlap between its maisons.
GCC luxury goods encompass premium apparel, leather goods, timepieces, jewelry, and cosmetics characterized by artisanal craftsmanship, scarce supply, and price positioning that absorbs substantial disposable income. These products serve as stores of value, social signaling instruments, and components of wealth-display rituals among Gulf elites. Accessories and watches represent the fastest-expanding product categories as male consumers deepen their participation in personal luxury. Affluent consumers and tourists drive volume, yet collectors command disproportionate margin pools through bespoke commissioning and wait-list access.
UAE's Department of Economy and Tourism enforces consumer protection standards affecting warranty terms and return policies for luxury retail, while Saudi Arabia's General Authority for Competition monitors pricing transparency in concentrated brand distributions. The EU's CSRD and deforestation regulations indirectly shape supply chain compliance for European houses operating in the Gulf. Stakeholders must track how Gulf sovereign wealth participation in luxury groups alters brand governance and regional market prioritization.
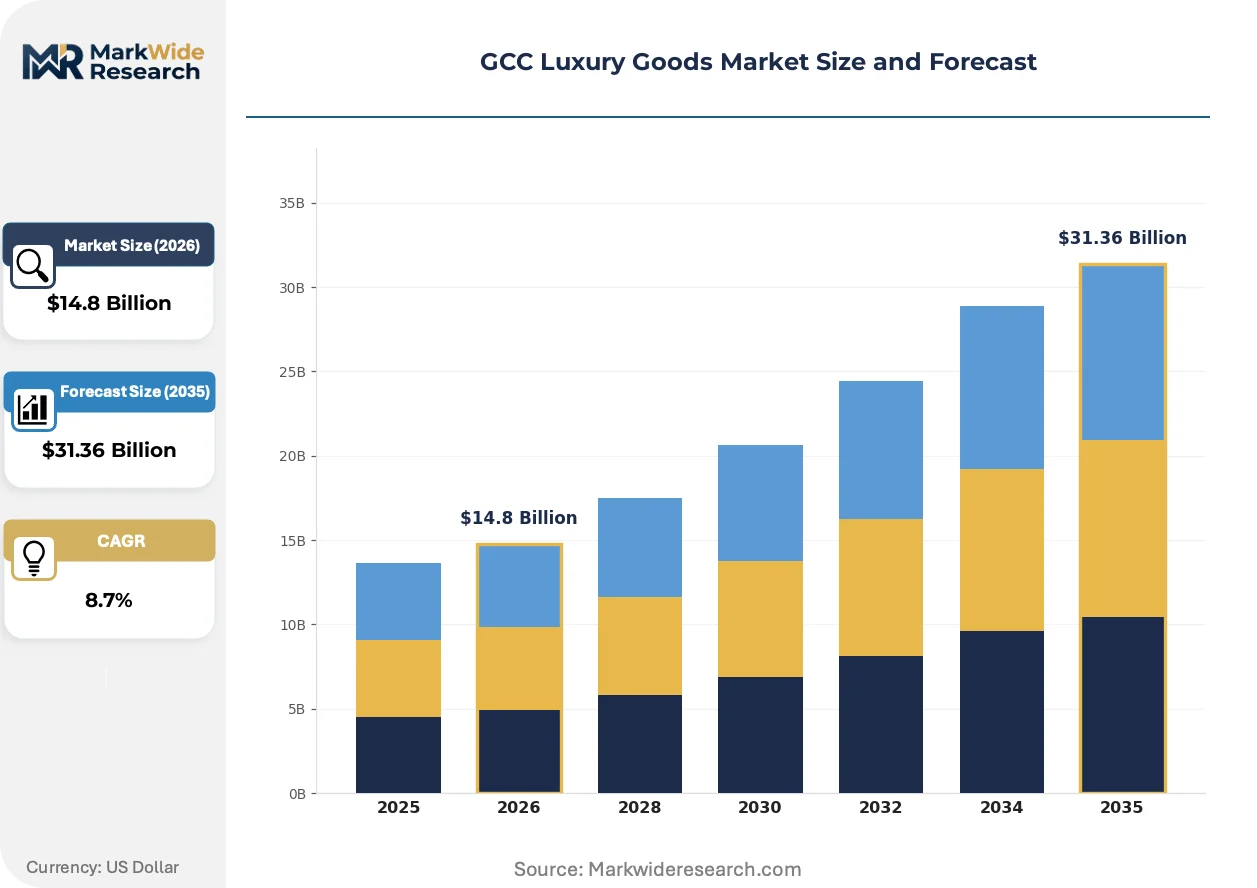
Market Dynamics
Ultra-high-net-worth individuals in Riyadh and Dubai are consolidating purchase power, forcing brands to reconfigure inventory allocation toward private clienteling and wait-list management rather than open retail.
Growth Catalysts
- Saudi Vision 2030 residency reforms:New eligibility frameworks expand the pool of qualified luxury consumers eligible for long-term settlement and discretionary spending authorization.
- Gold bullion:Timepieces and leather goods increasingly function as portable wealth stores amid regional currency volatility, deepening collector commitment to scarce artisanal production.
- Dubai's duty-free corridors:Concentrated tourist traffic through controlled retail environments captures transient high-value purchases with minimal brand distribution overhead.
Market Restraints
- Artisan labor scarcity:Master craftspeople for bespoke leather and horological finishing concentrate in Switzerland and Italy, creating supply bottlenecks for Gulf-commissioned pieces.
- EU CSRD compliance costs:Extended supply chain disclosure requirements raise administrative burdens for European houses serving GCC clients through direct retail.
- Secondary market displacement:Certified pre-owned timepieces from established collectors divert demand from primary retail channels, compressing margin capture for authorized dealers.
Strategic Opportunities
- Qatar hospitality integration:Museum-grade retail environments within luxury hotels create immersive brand experiences unavailable in conventional boutique formats.
- Blockchain authentication convergence:Distributed ledger technology paired with NFC-enabled product passports enables verifiable provenance for resale-dependent collector categories.
- Kuwait's underpenetrated male accessories segment:Limited local presence of dedicated men's leather goods specialists leaves white space for category-focused entrants.
Industry Challenges
- Clienteling talent acquisition:Fluency in Arabic dialects, horological expertise, and discretion protocols required for serving UHNW households exceeds regional training pipeline output.
- Legacy ERP integration:Gulf-based retail operators struggle to synchronize inventory visibility between flagship boutiques and duty-free concessions in real time.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Luxury Goods Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.36 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apparel, Footwear, Accessories, Watches Customer Type: Affluent Consumers, Tourists, Collectors, Institutions Distribution Channel: Online Retail, Department Stores, Boutiques, Duty-Free Price Tier: High-End, Mid-Range, Exclusive, Limited Edition |
| Companies Covered | LVMH Moët Hennessy Louis Vuitton, Kering SA, Compagnie Financière Richemont SA, Chanel SA, Chalhoub Group, Hermès International, Prada S.p.A., Al Tayer Group, Burberry Group plc, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Luxury Goods Market Trends and Innovations
Digital infrastructure and regulatory transparency mandates are reconfiguring how authenticity is verified and how brands maintain exclusivity in an era of resale platform proliferation.
Near-field communication chips embedded in watch cases and leather goods is modularizing the authentication stack, enabling instant provenance verification through smartphone interfaces. Collectors in Dubai and Riyadh are adopting this capability fastest, treating digital certificates as essential companion assets to physical pieces. The technology is modularizing trust infrastructure away from paper documentation and dealer reputation toward cryptographic certainty.
EU deforestation regulations now require leather traceability to ranch-level documentation for goods entering European distribution, indirectly pressuring Gulf retail supply chains. Brands must requalify tannery partners and maintain chain-of-custody records across multiple jurisdictions. Saudi Arabia's General Authority for Competition is monitoring whether these compliance costs translate into opaque pricing practices affecting local consumers.
Bespoke commissioning through direct architect relationships is displacing seasonal collection purchasing among Riyadh-based collectors. Male clients now initiate multi-year leather goods programs with single artisans rather than acquiring from retail inventory. This pattern concentrates most visibly in timepiece and luggage categories where personalization signals status differentiation.
GCC Luxury Goods Market Segmentation
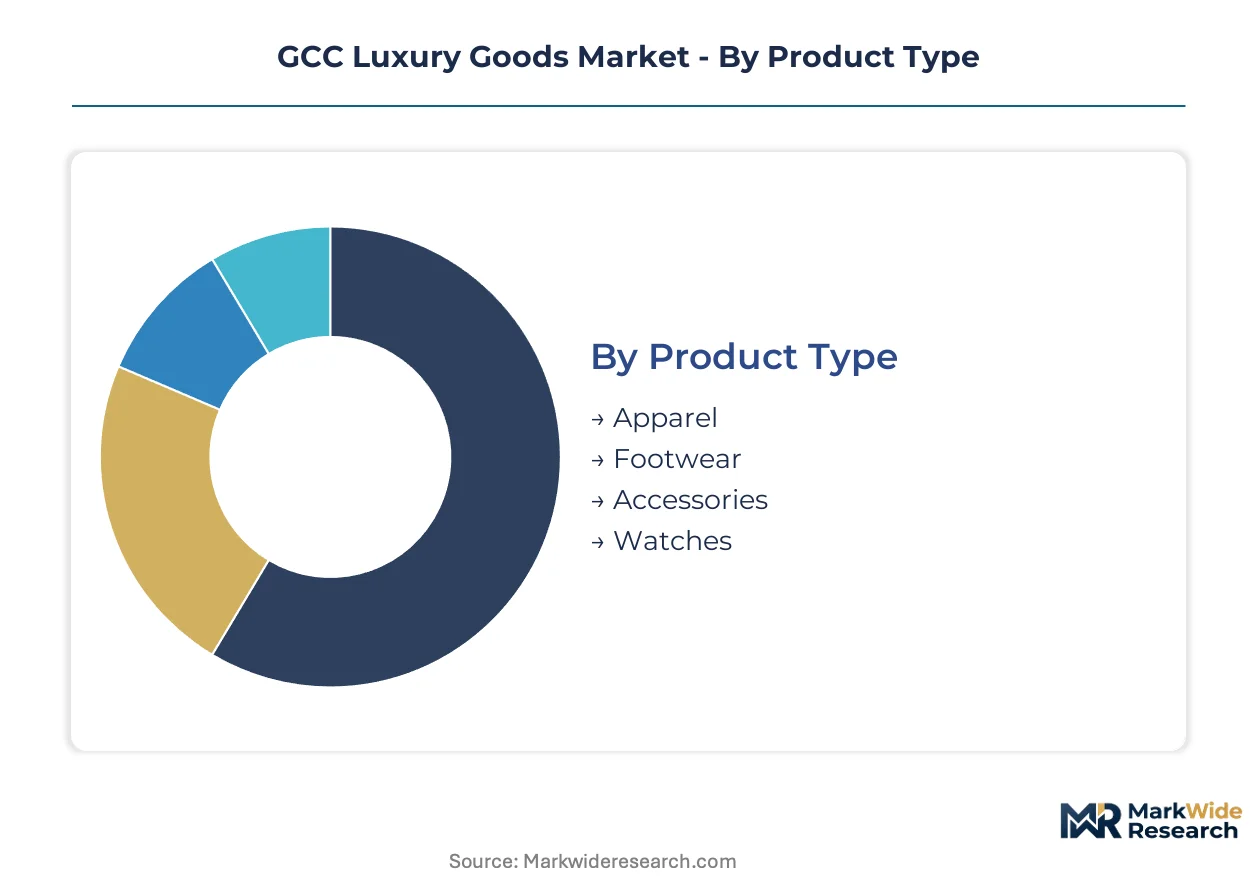
Segmentation in the GCC luxury goods market determines how brands allocate scarce artisan capacity and clienteling resources across divergent buyer profiles. Purchase patterns among Riyadh-based collectors differ fundamentally from Dubai tourist flows, requiring distinct inventory and service architectures.
Product Type:
EU deforestation regulations now mandate ranch-level traceability for leather goods entering European distribution, while Swiss horological certifications govern watch authenticity standards across Gulf retail channels.
- Apparel:Ready-to-wear collections from European maisons dominate flagship boutique floorspace in Dubai Mall and Riyadh Park. Saudi Vision 2030 entertainment sector expansion is driving womenswear demand among newly affluent professional households in Riyadh and Jeddah.
- Footwear:Artisanal construction with Italian or French provenance commands wait-list status among Dubai collectors. Limited production runs from single-factory specialists create allocation battles that brands resolve through clienteling priority scores.
- Accessories:Leather goods and small leather articles function as portable wealth stores amid regional currency volatility. Scarce exotic skins from CITES-compliant tanneries concentrate margin capture among top-tier GCC households.
- Watches:Horological complications with Geneva Seal or COSC certification anchor collector portfolios in Abu Dhabi and Doha. Secondary market premiums for discontinued references are diverting primary retail demand toward pre-owned platforms.
Accessories sits at the top of the volume ranking, with Watches climbing the fastest.
Customer Type:
Margin concentration follows buyer sophistication, with institutions and collectors commanding bespoke commissioning pipelines while tourists drive throughput in duty-free corridors.
- Affluent Consumers:Newly wealthy entrants from Saudi professional classes are acquiring entry-level leather goods and quartz timepieces as status signaling instruments. MOHAP consumer protection standards in the UAE govern warranty terms for this transaction-heavy segment.
- Tourists:Transient purchasers through Dubai International and Hamad International duty-free zones generate volume with minimal clienteling overhead. VAT refund mechanisms and concentrated retail footprints capture spending during layover windows.
- Collectors:Multi-generational Gulf families commission bespoke pieces through direct artisan relationships rather than seasonal retail acquisition. This segment absorbs disproportionate master craftsperson capacity from Swiss and Italian workshops.
- Institutions:Sovereign wealth-related entities and royal offices procure ceremonial gifts and diplomatic presentations through private treaty arrangements. Procurement patterns bypass standard retail markup structures entirely.
Collectors generate the highest margin per transaction, with Affluent Consumers expanding most quickly.
Distribution Channel:
Real-time inventory synchronization between flagships and concessions remains technically challenging, constraining how brands manage scarcity signaling across touchpoints.
- Online Retail:Digital flagship platforms with virtual try-on and concierge chat are capturing younger affluent entrants in Kuwait and Bahrain. Authentication infrastructure using NFC-enabled product passports addresses resale market trust deficits.
- Department Stores:Chalhoub Group's controlled concessions within Harvey Nichols and Galeries Lafayette anchor mall-based discovery for tourist and local hybrid audiences. Lease structures favor brand-controlled merchandising over retailer curation.
- Boutiques:Architect-designed flagships in Dubai Design District and Riyadh's Diriyah Gate deliver immersive brand narratives unavailable in multi-brand environments. These locations concentrate clienteling talent with Arabic fluency and horological expertise.
- Duty-Free:Dubai International's Concourse A and Hamad International's Al Mourjan Business Lounge host museum-grade retail environments capturing high-value transient purchases. Margin compression from concession fees is offset by volume throughput and zero inventory carry risk.
Boutiques command the highest revenue per square meter, with Online Retail gaining share fastest.
Price Tier:
Exclusivity engineering through deliberate scarcity and wait-list management separates price tiers more than manufacturing cost differentials.
- High-End:Core collection pieces with established brand codes and recognized silhouettes serve as entry points for newly affluent GCC consumers. Pricing transparency monitoring by Saudi Arabia's General Authority for Competition affects how brands communicate value propositions.
- Mid-Range:Diffusion lines and cosmetic categories capture frequency-driven purchasing from younger demographics in Abu Dhabi and Muscat. This tier faces pressure from certified pre-owned alternatives in watches and leather goods.
- Exclusive:Made-to-order programs with named artisan attribution require multi-year relationship cultivation with Riyadh and Dubai households. Production slots are allocated through clienteling priority systems rather than open availability.
- Limited Edition:Numbered releases with regional exclusivity clauses generate secondary market premiums that brands struggle to recapture. Blockchain-based provenance tracking is emerging to authenticate these high-velocity resale assets.
Exclusive commands the highest margin percentage, with Limited Edition showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
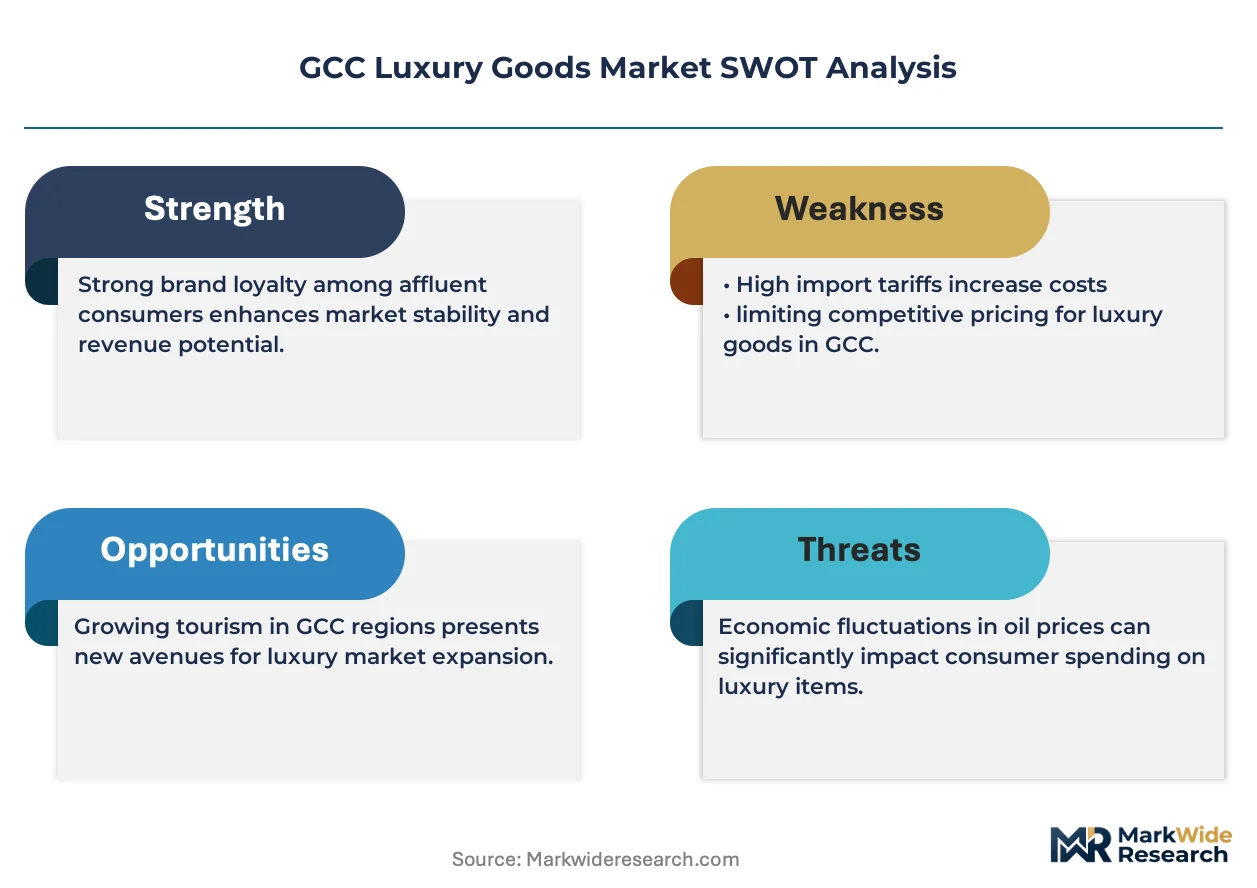
Saudi Arabia's Vision 2030 residency reforms are accelerating luxury consumption faster than the UAE's mature duty-free infrastructure can expand, creating divergent growth trajectories across the Gulf Cooperation Council.
United Arab Emirates
Dubai Mall and Abu Dhabi's Galleria Al Maryah Island concentrate flagship boutique investments from European maisons. MOHAP consumer protection standards govern warranty disclosures and return policies for high-value transactions. The Dubai International duty-free corridor captures transient ultra-high-net-worth purchases during layover windows with minimal inventory carry risk.
Saudi Arabia
Riyadh-based collectors are commissioning bespoke leather goods and timepieces through direct artisan relationships rather than seasonal retail acquisition. The General Authority for Competition monitors pricing transparency in concentrated brand distributions. Diriyah Gate and Jeddah's Red Sea Project are emerging as architect-designed retail destinations for immersive brand experiences.
Qatar
Museum-grade retail environments within luxury hotels at Lusail and West Bay are creating immersive brand experiences unavailable in conventional boutique formats. Hospitality-driven procurement from sovereign wealth-related entities bypasses standard retail markup structures. Hamad International's Al Mourjan Business Lounge hosts controlled retail environments capturing high-value transient purchases.
Kuwait
Limited local presence of dedicated men's leather goods specialists leaves white space for category-focused entrants targeting underpenetrated male accessories demand. Younger affluent entrants are adopting digital flagship platforms with virtual try-on capabilities. The Avenues Mall anchors mall-based discovery for hybrid local-tourist audiences through controlled concessions.
GCC Luxury Goods Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the GCC luxury goods sector, creating a tiered competitive structure where portfolio breadth clashes with artisan depth. The vendor base fragments across French and Italian heritage houses, Swiss horological specialists, and Gulf-based distribution operators controlling physical retail access. Two strategic archetypes dominate: multi-brand luxury groups leveraging cross-category synergies, and single-maison specialists preserving scarcity through controlled distribution. M&A activity concentrates on securing tannery and atelier capacity, while strategic partnerships with hospitality operators reshape experiential retail.
Within the multi-brand conglomerate tier, LVMH Moët Hennessy Louis Vuitton and Kering SA exemplify portfolio diversification strategies spanning leather goods, timepieces, and cosmetics. Compagnie Financière Richemont SA occupies a position anchoring the hard luxury segment through concentrated horological and jewelry assets. These three French and Swiss entities represent the dominant competitive anchors shaping brand governance and regional market prioritization across Gulf retail channels.
| Leading Market Players |
|---|
| LVMH Moët Hennessy Louis Vuitton |
| Kering SA |
| Compagnie Financière Richemont SA |
| Chanel SA |
| Chalhoub Group |
| Hermès International |
| Prada S.p.A. |
| Al Tayer Group |
| Burberry Group plc |
| Others |
Pricing and Supply Chain Analysis
Captive artisan capacity in Swiss ateliers and Italian tanneries anchors pricing power for GCC luxury houses, concentrating margin capture among brands with direct control over master craftsperson allocation and wait-list management systems.
Pricing Analysis
Capacity additions in Dubai's duty-free corridors are reshaping price floors for entry-level leather goods and quartz timepieces, compressing margins on standardized inventory while exclusive made-to-order programs with named artisan attribution sustain premium positioning. Three-tier pricing structure across exclusive, limited edition, and high-end levels stratifies according to clienteling priority scores and bespoke commissioning relationships rather than manufacturing cost differentials. Pricing pressure stems from certified pre-owned platforms diverting collector demand from primary retail channels, eroding authorized dealer margins. Tourists through Dubai International exhibit highest price sensitivity, while multi-generational Riyadh collectors demonstrate minimal elasticity for scarce artisan production.
Supply Chain Analysis
Freight costs for exotic leather shipments from CITES-compliant tanneries concentrate in air cargo corridors linking Milan, Geneva, and Dubai, with customs clearance protocols at Jebel Ali Free Zone adding procedural latency to high-value inventory movements. Geographic supply concentration centers on Switzerland for horological complications, Italy for artisanal leather finishing, and France for couture ateliers. Raw material dependencies include crocodile skins from certified farms, gold bullion for watch cases, and rare earth elements for movement components. Single-source vulnerability pervades master craftsperson allocation, where individual artisan capacity constraints bottleneck Gulf-commissioned bespoke production. Distribution runs through Chalhoub Group's controlled concessions and brand-direct flagships with real-time inventory synchronization challenges.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Vision 2030 residency reforms compound luxury demand by expanding qualified consumer pools eligible for long-term settlement and discretionary spending authorization across Riyadh and Jeddah.
For Market Incumbents: To counter secondary market displacement eroding primary retail margins, deepen direct artisan relationships through captive atelier investments in Florence and Geneva, while deploying blockchain-enabled product passports to recapture resale authentication revenue streams. For New Entrants and Emerging Players: Launch via digital flagship platforms with virtual try-on capabilities targeting Kuwait's underpenetrated male accessories segment, where limited local presence of dedicated leather goods specialists leaves white space for category-focused positioning with Arabic-language concierge services. For Investors and Strategic Acquirers: Consolidation pressure builds where artisan labor scarcity exceeds regional training pipeline output, favoring acquisition targets with established master craftsperson relationships and Gulf clienteling infrastructure. Long-term viability hinges on backward integration into tannery capacity and atelier networks. Watch for inflection signals in sovereign wealth participation patterns altering brand governance priorities.| Strategic Initiative | Industry Significance |
|---|---|
| Atelier Capacity Acquisition | Secures scarce master craftsperson allocation from Swiss and Italian workshops for GCC bespoke programs. |
| Blockchain Product Passport Launch | Enables cryptographic provenance verification addressing collector trust deficits in pre-owned timepiece markets. |
| Hospitality Retail Integration | Creates museum-grade brand experiences within Qatar's luxury hotel developments at Lusail and West Bay. |
| Digital Flagship Platform Expansion | Captures younger affluent entrants in Kuwait and Bahrain through virtual try-on and concierge chat interfaces. |
| Clienteling Talent Pipeline Investment | Addresses Arabic fluency and horological expertise gaps exceeding regional training output for UHNW service. |
Research Methodology
Coverage spans the UAE, Saudi Arabia, Qatar, and Kuwait, with primary inputs from each market combining structured interviews with brand clienteling directors, luxury retail operators, and hospitality procurement officers alongside secondary validation from customs records, Chalhoub Group distribution disclosures, and EU CSRD compliance filings. Bottom-up demand modeling triangulates against top-down macroeconomic indicators across the GCC.
Granularity-level framing applies product type, customer archetype, distribution channel, and price tier dimensions at the country level, with sovereign wealth participation patterns and residency reform eligibility criteria incorporated as GCC-specific forecast inputs. CAGRs derive from segmented volume projections reconciled against reported retail footprint expansions and duty-free corridor throughput data.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt regulatory shifts affecting golden visa eligibility or EU deforestation enforcement intensity. Forecasts reflect documented assumptions about artisan capacity expansion rates and collector demand persistence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Goods
United Kingdom Luxury Goods Market
Luxury Goods
China Luxury Goods Market
Luxury Goods
Qatar Luxury Good Market
Luxury Goods
China Luxury Market
Luxury Goods
GCC Secondhand Luxury Goods Market
Luxury Goods
Hard Luxury Goods Market
Luxury Goods
Brazil Luxury Jewelry Market
Luxury Goods
UAE Luxury Jewelry Market
Luxury Goods
Designer Bags and Luxury Handbags Market
Luxury Goods
Thailand Luxury Goods Market
Luxury Goods
France Luxury Goods Market
Luxury Goods
Luxury Mechanical Watches Market
Luxury Goods
Europe Handbags Market
Luxury Goods
GCC Personal Luxury Goods Market
Luxury Goods
Personal Luxury Goods Market
Luxury Goods
India Lab Grown Diamond Jewelry Market