
 UAE Luxury Jewelry Market | 2026-2036
UAE Luxury Jewelry Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Luxury Jewelry Market Insights
Market Dynamics
Multi-source gemstone procurement is expanding across UAE-based houses as geopolitical supply risks prompt diversification beyond traditional Belgian and Indian cutting centers. Cartier leverages its vertically integrated atelier network to sustain rare stone access across multiple continents. Damas anchors its domestic position through deep mall-based retail penetration and localized design collaborations. Graff differentiates via ultra-high-value single-stone pieces that occupy the auction-to-private-sale pipeline.
Product and Segment Landscape
UAE luxury jewelry denotes precious-metal and gemstone adornments crafted to exceptional workmanship standards, typically employing 18-karat gold or platinum settings with VS-clarity diamonds or certified colored stones, serving as wealth preservation instruments and ceremonial markers for affluent consumers. Diamond and gold product types dominate volume, though platinum is registering the fastest ascent among younger collectors seeking differentiation from conventional bridal portfolios. Specialty stores command the highest margin pools within distribution channels, while online retail is accelerating fastest among expatriate buyers seeking remote authentication services.
Regulatory Environment and Outlook
MOHAP enforces hallmarking and purity disclosure rules that shape retail compliance costs, while Dubai Multi Commodities Centre's Kimberley Process implementation and UAE-specific anti-money laundering protocols for precious metals dealers govern cross-border trade conduct. Stakeholders must monitor how evolving blockchain traceability mandates from the UAE's federal precious metals regulator reshape sourcing documentation requirements and consumer transparency expectations.
Market Dynamics
MOHAP's blockchain-based diamond traceability mandates are compressing sourcing documentation timelines while elevating authentication costs across Dubai's retail corridor. Heritage maisons and independent houses alike must reconfigure procurement systems to satisfy federal precious metals regulator requirements.
Growth Catalysts
- High-net-worth tourist inflows:Affluent visitors from Saudi Arabia and India sustain retail traffic density in Dubai's Gold Souk and Mall of the Emirates boutiques, anchoring volume for heritage maisons.
- Kimberley Process implementation:DMCC's enforcement of conflict-free diamond certification standards enhances UAE's legitimacy as a regional trading hub, attracting international auction houses and private dealers.
- Platinum adoption among younger collectors:Differentiation-seeking buyers under 35 are diversifying beyond conventional bridal portfolios, expanding addressable demand for white-metal specialists.
Market Restraints
- Geopolitical supply concentration:Traditional Belgian and Indian cutting centers dominate rough diamond access, exposing UAE houses to disruption risks from single-region dependencies.
- MOHAP compliance cost escalation:Precious metals certification requirements impose fixed operational burdens on smaller retailers, compressing margin pools for independent operators.
- Input price volatility:Gold and platinum spot fluctuations create inventory valuation uncertainty, complicating hedging strategies for houses with large finished-goods positions.
Strategic Opportunities
- Abu Dhabi retail corridor expansion:Underpenetrated luxury mall development on Saadiyat Island offers flagship positioning for maisons seeking to reduce Dubai concentration risk.
- Remote authentication services:Expatriate buyers in Europe and South Asia represent untapped demand for blockchain-verified digital purchasing channels with customs-cleared delivery.
- Colored stone certification convergence:Integration of GIA and SSEF grading standards with MOHAP hallmarks creates premium positioning for houses investing in multi-laboratory documentation.
Industry Challenges
- Master craftsperson scarcity:Specialized skills in hand-engraving and micro-pavé setting are concentrating among aging practitioners, constraining production scaling for bespoke orders.
- Blockchain integration complexity:Legacy inventory management systems require capital-intensive reconfiguration to interface with federal traceability platforms, delaying compliance timelines for mid-sized houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Luxury Jewelry Market |
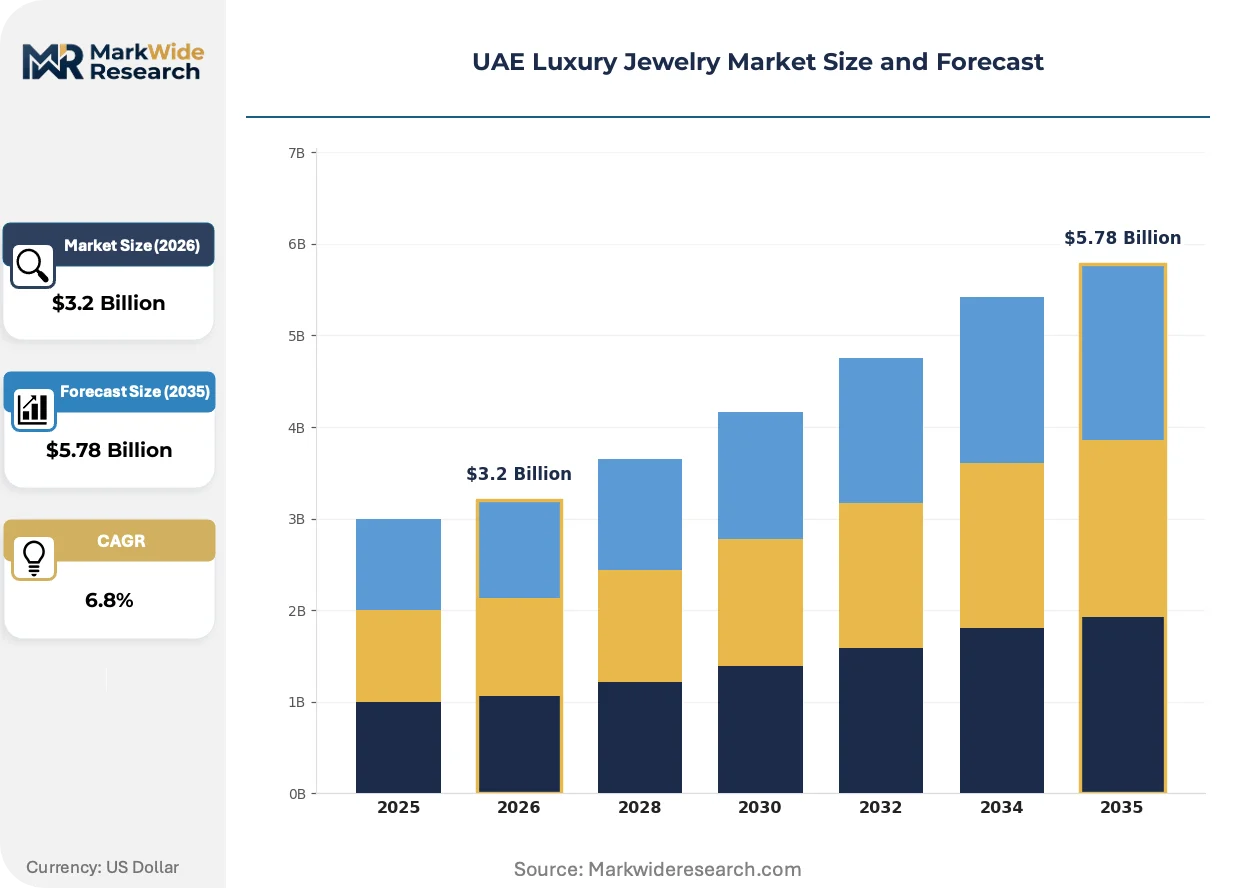
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diamond, Gold, Platinum, Silver End User: Consumers, Collectors, Gift Buyers, Wedding Planners Distribution Channel: Online Retail, Specialty Stores, Department Stores, Auction Houses Price Tier: Affordable, Mid-Range, Premium, High-End |
| Companies Covered | Van Cleef & Arpels, Graff, Cartier, Arqa Jewellery, MKS Jewellery, Tiffany & Co., Damas, Sana Al Maktoum Fine Jewellery, Bulgari, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Luxury Jewelry Market Trends and Innovations
Digital authentication infrastructure is reshaping how UAE houses verify provenance and transact with remote buyers. Three developments are compressing traditional verification cycles and opening new channel architectures.
AI-powered gemstone grading is electrifying quality assurance workflows across Dubai's cutting and polishing facilities. Laboratory-grown diamond detection algorithms now process stones in seconds rather than hours. Major retail groups are deploying these systems at point-of-sale to eliminate downstream disputes. The technology is compressing authentication bottlenecks that previously delayed cross-border shipments.
MOHAP's federal precious metals regulator is mandating blockchain-anchored custody documentation for all diamonds above 0.30 carats. Retailers must upload cutting-center certificates, import declarations, and retail invoices to a unified ledger. High-value single-stone specialists face the steepest adaptation costs due to fragmented upstream paperwork. Houses are responding by requiring cutting partners to pre-format documentation to UAE specifications.
Private sales channels are displacing traditional auction pipelines for ultra-high-value pieces. Collectors above $5 million net worth now expect direct atelier access with white-glove logistics. Heritage houses are recruiting former auction specialists to staff these relationships. This behavioral shift is most visible among Indian and Russian buyers seeking discretion and immediate possession.
UAE Luxury Jewelry Market Segmentation
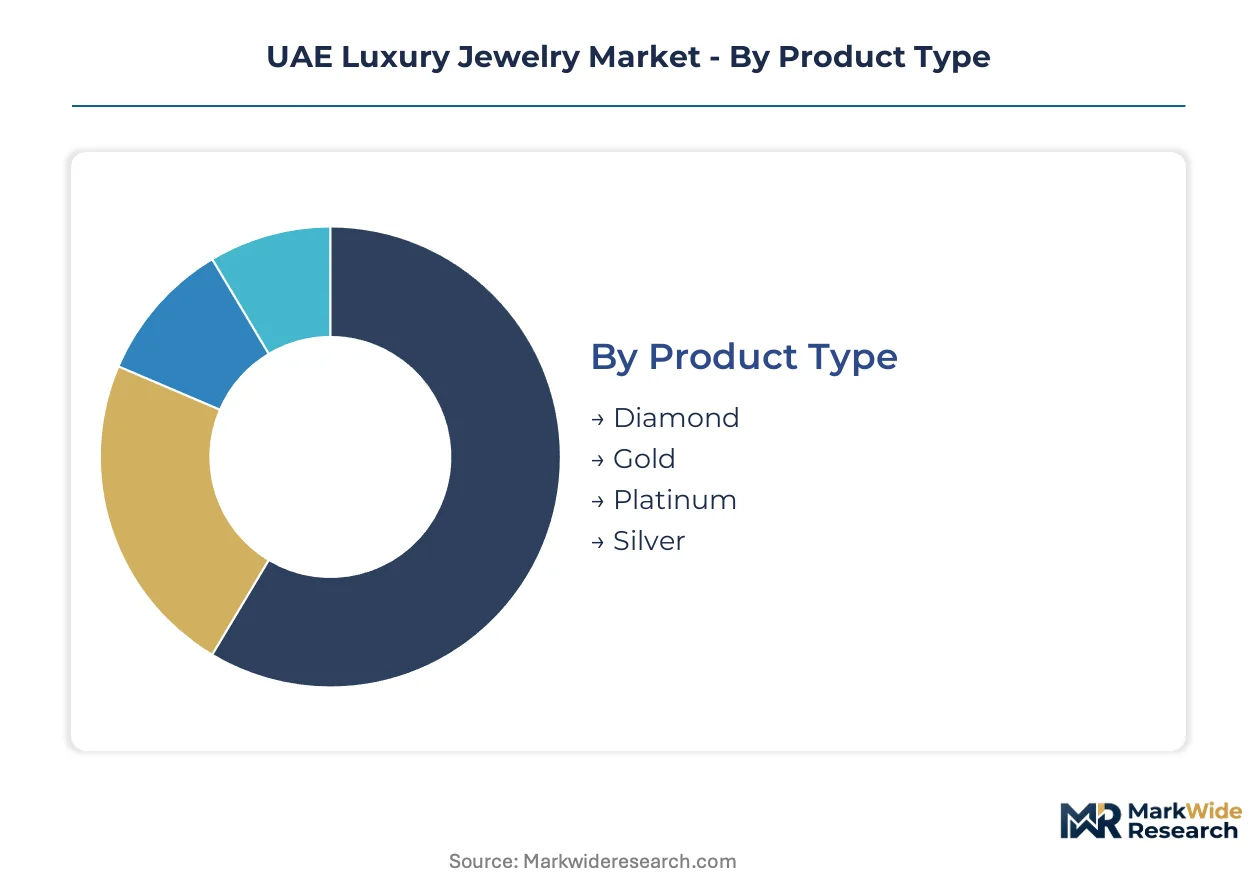
Segmentation in the UAE luxury jewelry market reveals how purchasing behavior fragments across ceremonial occasions, wealth preservation motives, and channel preferences. Understanding these divides allows houses to align inventory depth with the specific authentication and service expectations of each buyer cohort.
Product Type:
Diamond sourcing concentrates in Belgian and Indian cutting centers, exposing UAE houses to single-region disruption risks that are prompting diversification into secondary polishing hubs.
- Diamond:Certified stones above VS clarity dominate bridal and investment portfolios, with demand concentrating in Dubai's Gold Souk boutiques where Saudi tourists seek portable wealth instruments. MOHAP's blockchain traceability mandates are compressing documentation timelines for these high-value pieces.
- Gold:18-karat and 22-karat alloys anchor ceremonial purchases across South Asian expatriate communities, with fabrication concentrated in Sharjah's manufacturing district. Price volatility in spot markets complicates hedging for retailers holding large finished-goods positions.
- Platinum:White-metal differentiation attracts collectors under 35 seeking alternatives to conventional bridal portfolios.
- Silver:Entry-tier artisanal pieces serve tourist souvenir demand with lower authentication overhead.
Gold absorbs the bulk of installed manufacturing capacity; platinum is expanding most quickly among younger buyer cohorts.
End User:
Buyer motivation splits between transactional ceremonial purchasing and discretionary collecting, with each segment demanding distinct service architectures and authentication protocols.
- Consumers:Affluent residents and tourists making personal adornment purchases drive volume through mall-based flagship locations, with expectations of immediate MOHAP-certified documentation.
- Collectors:Ultra-high-net-worth individuals above $5 million net worth now expect direct atelier access with white-glove logistics and private sales channels displacing traditional auction pipelines.
- Gift Buyers:Expatriate professionals purchasing for family members in South Asia represent untapped demand for blockchain-verified digital purchasing with customs-cleared delivery.
- Wedding Planners:Bulk ceremonial procurement for multi-day South Asian weddings concentrates demand in Dubai's wholesale corridor.
Consumers absorb the bulk of transaction volume; collectors are climbing the fastest in average transaction value.
Distribution Channel:
Channel strategy determines margin capture and authentication burden, with digital infrastructure now enabling remote verification that was previously impossible.
- Online Retail:Expatriate buyers in Europe and South Asia accelerate fastest among channels, seeking remote authentication services with blockchain-verified provenance documentation.
- Specialty Stores:Heritage maisons command the highest margin pools through mall-based flagship penetration in Dubai Mall and Mall of the Emirates.
- Department Stores:Mid-range inventory placement serves convenience-oriented purchasers with standardized certification.
- Auction Houses:Ultra-high-value single-stone pieces occupy the pipeline-to-private-sale transition as direct atelier relationships displace traditional consignment.
Specialty stores absorb the bulk of premium revenue; online retail is gaining share fastest among geographically dispersed buyers.
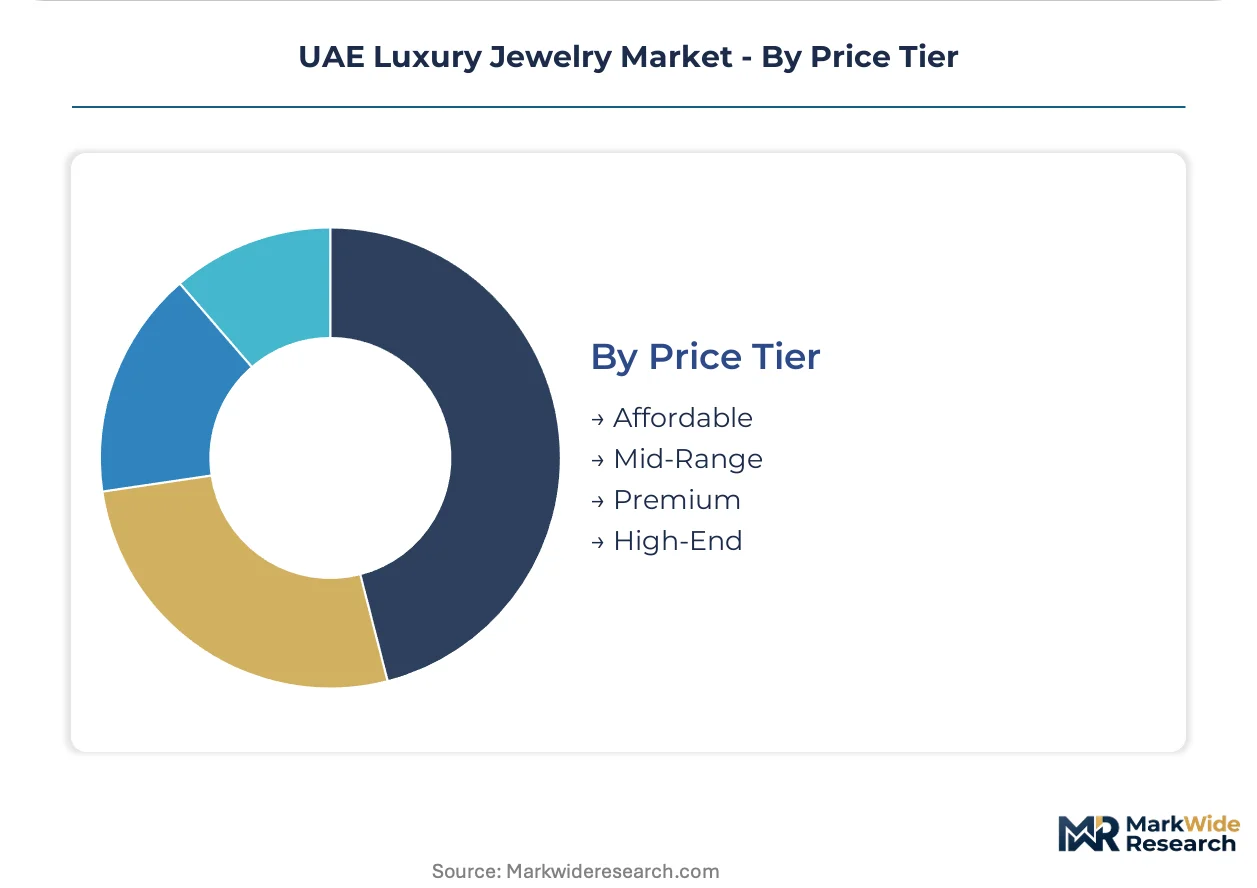
Price Tier:
Pricing stratification aligns with certification intensity and service depth, with federal hallmarks creating visible quality demarcation.
- Affordable:Entry-level silver and small-gold pieces serve tourist impulse purchasing with minimal documentation requirements.
- Mid-Range:Standard certified diamonds and gold bridal sets concentrate volume in Dubai's retail corridor.
- Premium:GIA-graded stones with MOHAP hallmarks attract wealth preservation buyers seeking resale liquidity.
- High-End:Multi-laboratory documentation from GIA, SSEF, and MOHAP creates positioning for rare colored stones and heritage provenance pieces.
Mid-range absorbs the bulk of unit volume; high-end is expanding most quickly in absolute revenue contribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's Gold Souk anchors precious metal trading across the Gulf, with Sharjah's manufacturing district supplying fabrication capacity for ceremonial gold demand. Abu Dhabi's Saadiyat Island corridor is attracting flagship expansions as maisons seek to reduce Dubai concentration risk.
Dubai
High-net-worth tourists from Saudi Arabia and India sustain retail traffic density in Mall of the Emirates boutiques. MOHAP's blockchain-based diamond traceability mandates compress sourcing documentation timelines for heritage maisons operating in the emirate. The Gold Souk and Dubai Mall corridor concentrate flagship positioning for international houses.
Abu Dhabi
Underpenetrated luxury mall development on Saadiyat Island offers expansion opportunities for white-metal specialists targeting younger collectors. The emirate's cultural district investments are creating new anchor points for private sales channels. Galleria Al Maryah Island is emerging as a secondary luxury retail node.
Sharjah
18-karat and 22-karat gold fabrication concentrates in the emirate's manufacturing district, serving South Asian expatriate ceremonial demand. Localized design collaborations between houses and regional artisans are deepening product differentiation. Industrial zones near the Dubai border optimize logistics for cross-emirate distribution.
Northern Emirates
Ras Al Khaimah and Fujairah are developing tourism infrastructure that could extend luxury retail reach beyond the Dubai-Abu Dhabi axis. Lower operational costs are attracting mid-range inventory positioning for standardized certification products. Port facilities in Fujairah offer alternative import channels for rough diamond consignments.
Saudi Arabia
Affluent Saudi tourists represent the largest cross-border buyer cohort in Dubai's retail corridor, driving volume for portable wealth instruments. The kingdom's national precious metals regulator is implementing parallel traceability standards that will create documentation convergence with UAE requirements. Riyadh's emerging luxury retail zone is beginning to retain domestic spending that previously flowed to Dubai.
UAE Luxury Jewelry Market Competitive Landscape
Global heritage maisons compete with Gulf-based regional champions across authentication standards and private client relationships. Market structure tilts toward consolidated premium positioning, with a fragmented mid-tier of independent houses serving ceremonial demand. Two strategic archetypes dominate: vertically integrated atelier networks securing rare stone access, and mall-anchored retail specialists optimizing foot traffic conversion. Competitive moves concentrate on blockchain compliance infrastructure and direct-to-collector channel development.
Among heritage French maisons, Cartier and Van Cleef & Arpels exemplify vertically integrated sourcing architectures that sustain multi-continent rare stone access. Graff occupies a position within the ultra-high-value single-stone segment, anchoring the auction-to-private-sale pipeline. Damas represents the regional champion archetype, with deep mall-based retail penetration across Dubai's luxury corridor. These three houses illustrate how global scale, white-glove service depth, and localized distribution density each command distinct margin pools.
| Leading Market Players |
|---|
| Van Cleef & Arpels |
| Graff |
| Cartier |
| Arqa Jewellery |
| MKS Jewellery |
| Tiffany & Co. |
| Damas |
| Sana Al Maktoum Fine Jewellery |
| Bulgari |
| Others |
Pricing and Supply Chain Analysis
MOHAP's blockchain traceability mandates for diamonds above 0.30 carats gate qualified supply access and premium-tier pricing eligibility, forcing houses to absorb authentication infrastructure costs or forfeit high-end positioning. Buyers now expect bundled documentation as standard, compressing margins for operators unable to pre-format cutting-center certificates to UAE specifications.
Pricing Analysis
Warranty and service bundling separates heritage maisons from independent operators, with white-glove logistics and lifetime maintenance included in premium tiers while mid-range players unbundle these to hit price points. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification intensity—GIA-graded stones with MOHAP hallmarks command resale liquidity premiums, entry-tier silver carries minimal documentation overhead. Cost compression in mid-range bridal portfolios intensifies as Sharjah fabrication capacity expands. Wedding planners and bulk ceremonial buyers exhibit highest price sensitivity; collectors above $5 million net worth demonstrate lowest sensitivity, prioritizing provenance verification over absolute cost.
Supply Chain Analysis
Direct-to-flagship retail channels handle ultra-high-value single-stone demand, while wholesale corridors feed mass ceremonial procurement. Rough diamond supply concentrates in Belgium, India, and Israel, with secondary polishing hubs emerging in Botswana and Vietnam to diversify geopolitical exposure. Finished-goods fabrication draws from Sharjah's manufacturing district for gold alloys and Dubai's atelier network for platinum settings. Single-source vulnerability in Belgian cutting centers exposes UAE houses to disruption from regional trade restrictions. Distribution runs through Dubai Mall and Mall of the Emirates flagships for premium positioning, with Gold Souk stalls handling tourist volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE luxury jewelry market sits in a technology-transition phase, with AI-powered gemstone grading and blockchain traceability infrastructure displacing legacy manual authentication workflows.
For Market Incumbents: Cement dominance by backward integration into cutting-center partnerships that pre-format documentation to MOHAP specifications, eliminating compliance bottlenecks that delay rivals. Expand captive atelier capacity in Sharjah to secure craftsperson talent before aging practitioner scarcity worsens. Blockchain integration complexity threatens mid-sized competitors; early compliance completion creates sustainable differentiation. For New Entrants and Emerging Players: Launch via remote authentication services targeting expatriate gift buyers in Europe and South Asia, where established houses underinvest in digital purchasing channels. Abu Dhabi's Saadiyat Island corridor offers white-space flagship positioning with lower rent structures than Dubai saturation. White-metal specialization for collectors under 35 represents the most penetrable segment, as heritage maisons retain conventional bridal portfolio focus. For Investors and Strategic Acquirers: DMCC's parallel Kimberley Process enforcement with Saudi Arabia's national precious metals regulator is the leading indicator that documentation convergence will consolidate regional trading legitimacy around UAE-compliant operators. Long-term viability favors houses with vertically integrated rare stone access across multiple continents. Acquisition targets should demonstrate pre-existing blockchain infrastructure or cutting-center partnerships. Watch for MOHAP compliance deadline enforcement as the signal for margin compression among laggards.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Infrastructure Deployment | MOHAP's federal ledger mandates create compliance moats for early adopters against mid-sized competitors. |
| Cutting-Center Partnership Restructuring | Pre-formatted documentation to UAE specifications compresses sourcing timelines for heritage houses. |
| Private Sales Channel Development | Direct atelier access with white-glove logistics captures ultra-high-value buyers displacing auction pipelines. |
| Abu Dhabi Flagship Expansion | Saadiyat Island mall development reduces Dubai concentration risk for white-metal specialists. |
| AI Grading Technology Integration | Laboratory-grown diamond detection algorithms at point-of-sale eliminate downstream authentication disputes. |
Research Methodology
Independent corroboration across heritage maison executives, DMCC compliance officers, Sharjah manufacturing district operators, and South Asian expatriate buyer panels underwrites the qualitative findings in this study. Primary fieldwork combined structured interviews with boutique managers, procurement leads at cutting centers, and wedding planner networks with secondary validation from MOHAP regulatory filings, DMCC trade statistics, and GIA certification databases. Bottom-up demand modeling across consumer, collector, and gift buyer segments triangulated against top-down precious metals import data.
Rate-of-change decomposition across product type, end user motivation, distribution channel, and price tier dimensions anchored the analytical framework over the projection horizon. CAGRs derived from historical trade flow patterns and forward-looking regulatory implementation timelines. Forecast inputs incorporated platinum adoption curves among younger collectors and blockchain compliance cost trajectories for mid-sized houses.
Geopolitical supply disruption, MOHAP enforcement intensity variation, and gold spot volatility are the dominant revision risks to modeled outputs. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Goods
Mexico Luxury Goods Market
Luxury Goods
Luxury Appraisal Service Market
Luxury Goods
Spain Luxury Goods Market
Luxury Goods
Luxury Resale Platform Market
Luxury Goods
GCC Luxury Goods Market
Luxury Goods
Thailand Luxury Goods Market
Luxury Goods
Accessible Luxury Goods Market
Luxury Goods
Middle East and Africa Luxury Goods Market
Luxury Goods
United States Luxury Goods Market
Luxury Goods
Qatar Luxury Good Market
Luxury Goods
Mens Watch Market
Luxury Goods
Secondhand Luxury Goods Market
Luxury Goods
United Arab Emirates Luxury Goods Market
Luxury Goods
Pre-Owned Luxury Watches Market
Luxury Goods
India Lab Grown Diamond Jewelry Market
Luxury Goods
Personal Luxury Goods Market