
 India Lab Grown Diamond Jewelry Market | 2026-2036
India Lab Grown Diamond Jewelry Market Size, Share, and Industry Trends Forecast 2026-2036
India Lab Grown Diamond Jewelry Market Foresight
Asset-light leasing models for CVD reactor equipment is narrowing the capital barrier for mid-tier entrants. Bhanderi Lab Grown Diamonds leverages captive rough supply to sustain margin control across the polishing pipeline. Limelight Diamonds anchors premium positioning through exclusive retail partnerships in metro malls. Fiona Diamonds differentiates via direct-to-consumer digital channels that bypass legacy bourse intermediaries.
Lab grown diamond jewelry comprises ornamental pieces set with diamonds synthesized through chemical vapor deposition or high-pressure high-temperature methods, typically achieving D-F color grades and VS+ clarity at carat weights from 0.30 to 3.00. These pieces serve consumers seeking ethical provenance and price accessibility without sacrificing optical performance. Rings dominates bridal and solitaire purchases where certification transparency commands premium positioning. Online Shoppers represents the fastest-expanding customer type as virtual try-on tools and EMI financing reduce purchase friction. Specialty Stores retains margin concentration through assisted selling and bespoke design services.
BIS disclosure mandates and CDSCO-adjacent import monitoring for synthetic rough shape product legitimacy and consumer trust thresholds. The PLI scheme for gem and jewelry manufacturing incentivizes domestic CVD seed production and downstream integration. Stakeholders must track how BIS enforcement intensity and state-level GST audit frequency alter working capital requirements for inventory-heavy retailers.
Market Dynamics
Surat's diamond processing cluster now integrates synthetic rough with traditional cutting infrastructure, compressing lead times from rough import to finished jewelry while reshaping margin distribution across the value chain.
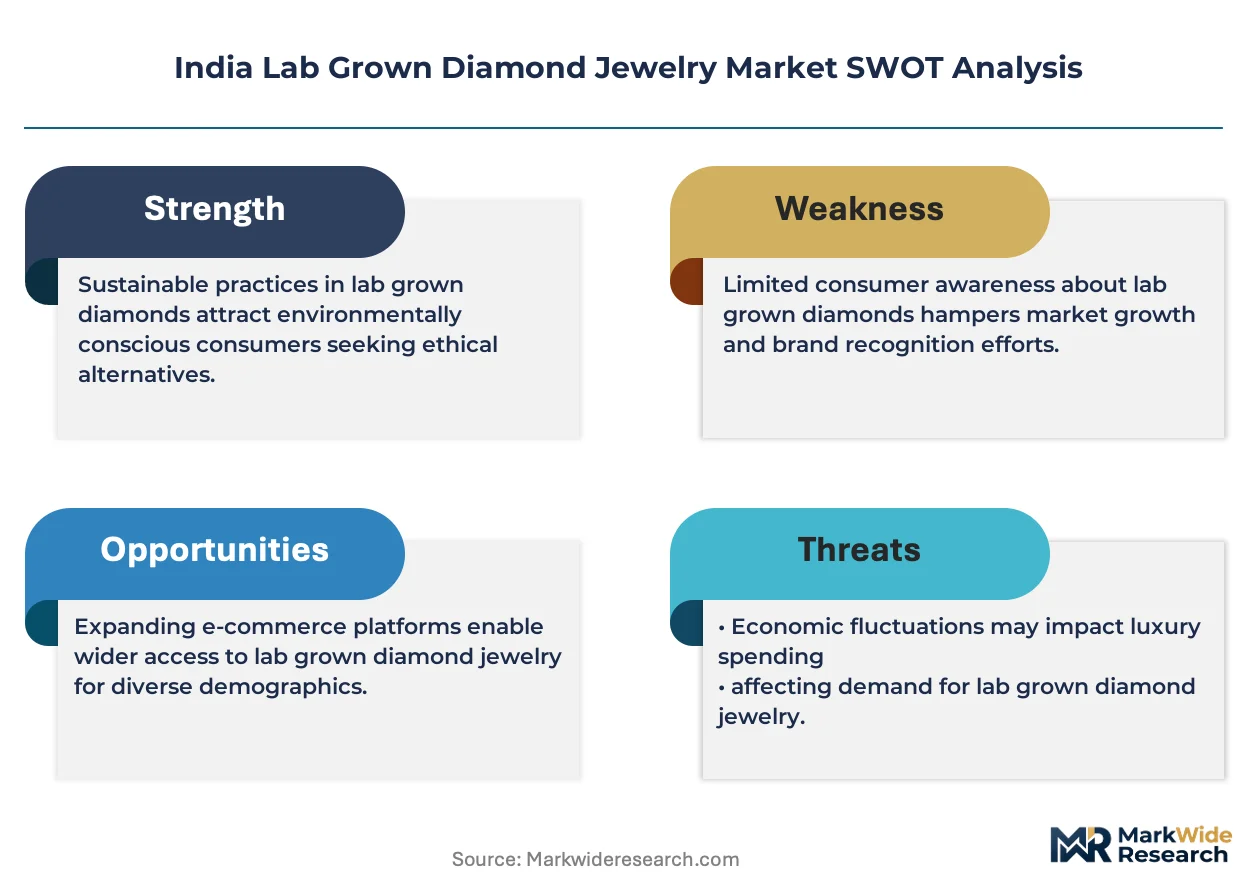
Growth Catalysts
- BIS Certification Mandate:The Bureau of Indian Standards disclosure requirement accelerates quality standardization and consumer trust thresholds across retail channels.
- PLI Scheme for Gem and Jewelry:Production-linked incentives for domestic CVD seed production reduce import dependency and incentivize downstream integration.
- Urban Millennial Demand:Mumbai and Delhi bridal-set purchasers now prioritize ethical provenance and price accessibility in solitaire purchases.
Market Restraints
- Power Cost Volatility:CVD reactor operations face margin pressure from Gujarat and Maharashtra industrial electricity tariff fluctuations.
- Import Concentration Risk:Synthetic rough supply chains remain concentrated through CDSCO-adjacent monitoring checkpoints, creating bottleneck exposure.
- Optical Detection Limitations:Distinguishing lab-grown from natural stones without spectroscopic equipment constrains secondary market liquidity.
Strategic Opportunities
- Tier-II City Penetration:Pune, Ahmedabad, and Hyderabad retail corridors remain underdeveloped for assisted-selling formats.
- Virtual Try-On Convergence:Augmented reality tools combined with EMI financing platforms reduce purchase friction for online shoppers.
- Export-Oriented Units:SEZ status under DGFT frameworks enables duty-free rough import for re-export of finished jewelry to Gulf markets.
Industry Challenges
- Skilled Cutter Shortage:Traditional Surat polishing artisans require retraining for synthetic rough handling and inclusion mapping.
- CVD Reactor Capex Burden:Mid-tier entrants face working capital strain from seed crystal procurement and reactor downtime risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Lab Grown Diamond Jewelry Market |
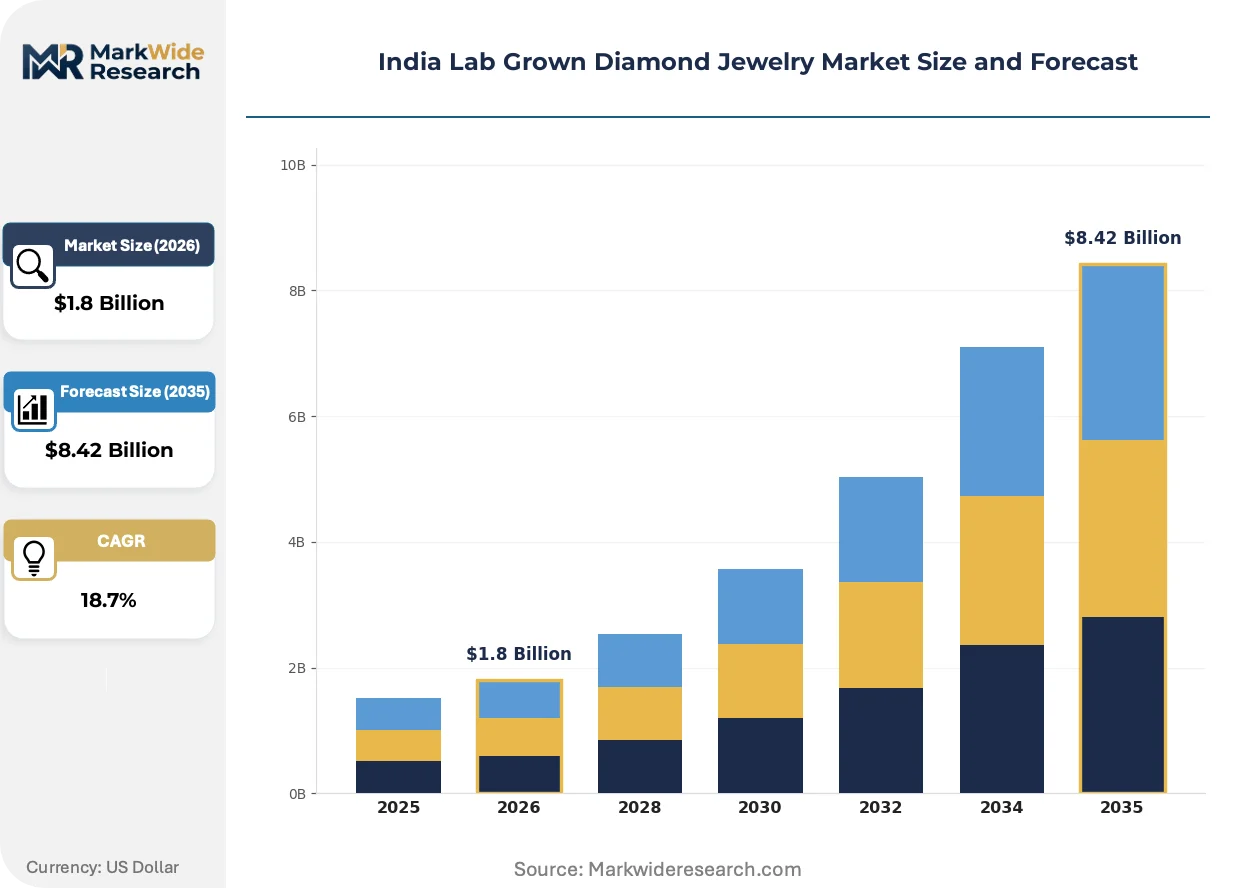
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rings, Necklaces, Earrings, Bracelets Customer Type: Retail Consumers, Wholesale Buyers, Online Shoppers, Luxury Brands Application: Weddings, Engagements, Gifts, Fashion Distribution Channel: Online Marketplaces, Specialty Stores, Department Stores, Direct Sales |
| Companies Covered | Ivana Jewels, Bhanderi Lab Grown Diamonds, Emori, Nuvo Diamonds, Fiona Diamonds, Limelight Diamonds, ABD Diamonds, Maitri Lab-grown Diamonds, Varniya, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Lab Grown Diamond Jewelry Market Shifts & Advancements
Digital infrastructure is compressing the traditional bourse-to-retail pipeline, enabling direct manufacturer-consumer relationships that bypass legacy intermediary layers and reshape pricing transparency.
AI-powered virtual try-on technology is virtualizing the bridal jewelry selection process. Metro mall retailers and direct-to-consumer platforms deploy smartphone-based rendering tools that simulate ring settings on live video feeds. This compression of the consideration phase reduces return rates and accelerates conversion timelines for high-consideration purchases.
BIS enforcement protocols now mandate laser inscription disclosure on all lab-grown diamond jewelry sold through Indian retail channels. The regulation requires traceability documentation from CVD or HPHT origin through polishing. Specialty stores in Maharashtra and Gujarat have responded by integrating spectroscopic verification equipment into assisted-selling workflows.
EMI financing integration is altering payment behavior among first-time diamond purchasers. Fintech partnerships embedded in e-commerce checkout flows now displace lump-sum payment expectations for sub-INR 2 lakh transactions. This shift is most visible among Delhi and Bangalore online shoppers purchasing solitaire rings through direct-to-consumer channels.
India Lab Grown Diamond Jewelry Market Segmentation
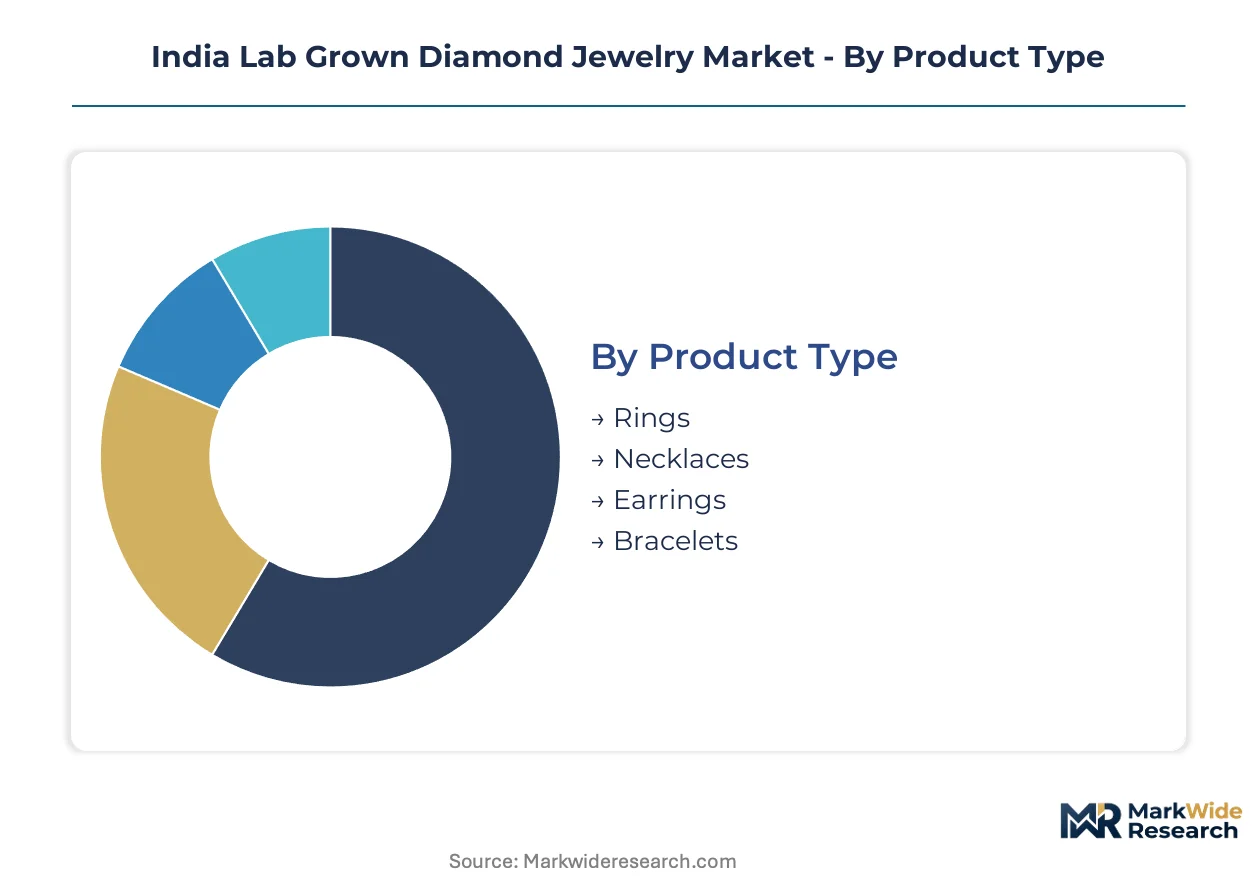
Segmentation in the India lab grown diamond jewelry market reveals distinct velocity profiles across product lines and purchase contexts. Understanding which segments compress decision cycles versus those requiring extended consideration periods enables inventory positioning and channel resource allocation.
Product Type:
Rings turn over fastest in bridal windows while bracelets and necklaces operate on slower gifting cycles tied to festival calendars.
- Rings:Solitaire and bridal band configurations dominate unit economics, with D-F color grades and VS+ clarity specifications standard. Maharashtra and Gujarat bridal purchasers drive replenishment frequency through compressed engagement-to-wedding timelines.
- Earrings:Stud and drop configurations achieve the shortest replacement cycles among fashion jewelry, with Mumbai metro consumers restyling quarterly. EMI financing integration has collapsed the traditional saving period for this category.
- Necklaces:Pendant and chain assemblies concentrate in Diwali and wedding season gifting windows across Delhi NCR corridors.
- Bracelets:Tennis and bangle styles retain the longest inventory turns, with Surat polishing clusters optimizing rough allocation for lower carat-weight throughput.
Rings anchors the volume base while earrings gains share at the steepest rate.
Customer Type:
Cost tier stratification separates lump-sum capable purchasers from EMI-dependent entrants across the financing spectrum.
- Online Shoppers:Virtual try-on tools and embedded fintech partnerships have collapsed purchase friction for this cohort. Bangalore and Hyderabad consumers lead adoption of augmented reality-enabled selection workflows.
- Retail Consumers:Assisted-selling formats in Mumbai and Delhi malls sustain premium positioning through spectroscopic verification demonstrations and bespoke design consultations.
- Wholesale Buyers:Surat-based jewelry manufacturers procure calibrated melee parcels for domestic setting operations, with BIS disclosure mandates now conditioning bulk procurement terms.
- Luxury Brands:Exclusive retail partnerships in metro malls anchor premium positioning through controlled distribution and certified provenance documentation.
Retail consumers provide the margin foundation even as online shoppers expand most quickly through digital infrastructure penetration.
Application:
Volume concentration maps directly to ceremonial calendar density across Indian metropolitan centers.
- Weddings:Bridal set configurations command the highest per-transaction values, with solitaire rings paired with matching band sets. Gujarat and Maharashtra families drive seasonal demand spikes aligned to auspicious date clustering.
- Engagements:Ring-focused purchases concentrate in Delhi and Mumbai urban millennial cohorts prioritizing ethical provenance signaling.
- Gifts:Earring and pendant selections spike during Diwali and Raksha Bandhan windows, with corporate gifting programs emerging through direct-to-consumer platforms.
- Fashion:Stackable rings and convertible earring designs target self-purchase behavior among Pune and Ahmedabad professional women.
Weddings anchors the value concentration while fashion climbs the fastest through self-purchase normalization.
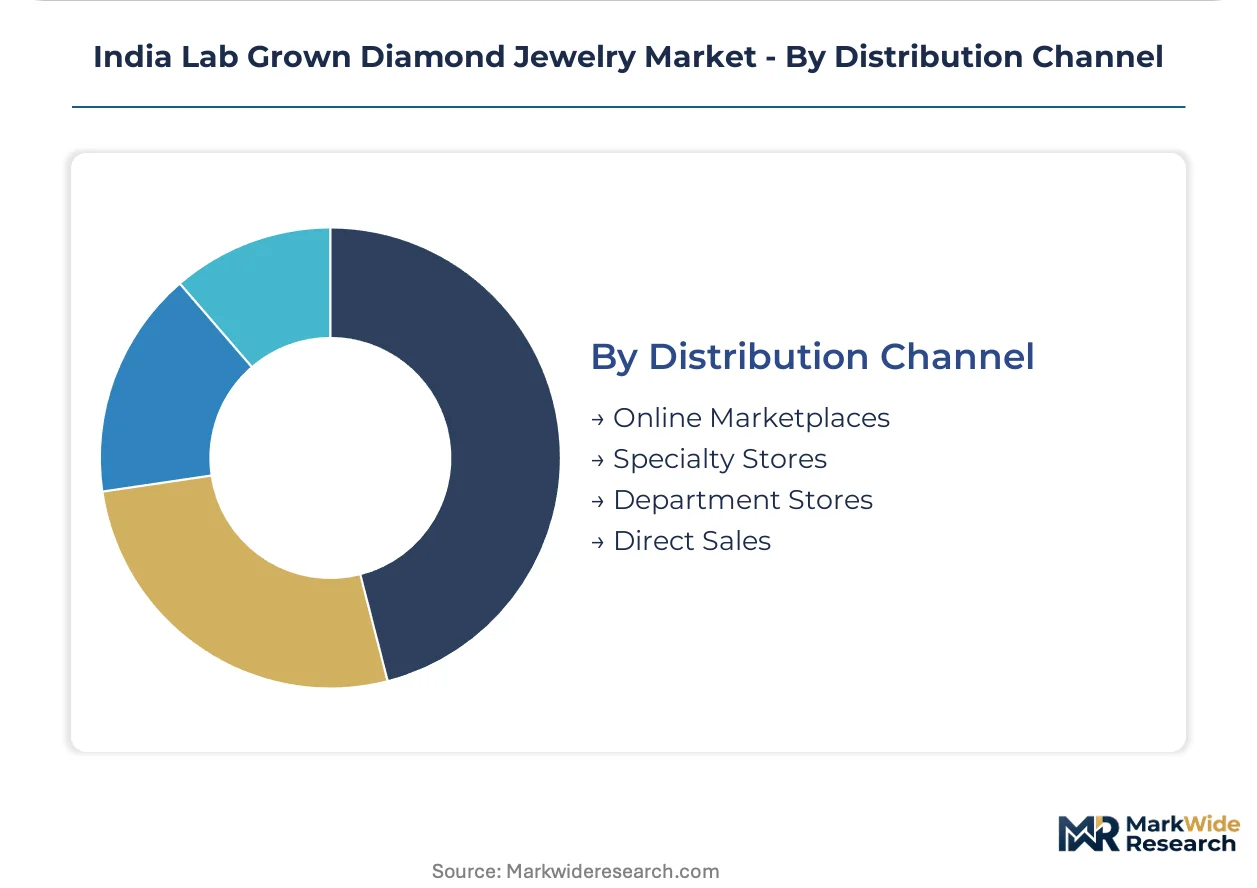
Distribution Channel:
Margin tiering separates assisted-selling formats from self-service digital endpoints across the customer journey.
- Specialty Stores:Metro mall locations in Mumbai, Delhi, and Bangalore integrate spectroscopic verification equipment and bespoke design services. BIS enforcement protocols have elevated compliance costs that favor scaled operators.
- Online Marketplaces:Direct-to-consumer platforms bypass legacy bourse intermediaries, with EMI financing embedded at checkout collapsing payment friction for sub-INR 2 lakh transactions.
- Department Stores:Multi-brand concessions in Hyderabad and Chennai malls extend reach to convenience-oriented purchasers seeking one-stop jewelry and apparel shopping.
- Direct Sales:Manufacturer-owned flagships and trunk show formats target high-net-worth collectors with exclusive cuts and custom setting services.
Specialty stores retain margin concentration while online marketplaces gain share fastest through infrastructure compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The PLI scheme for gem and jewelry manufacturing is redistributing production capacity across Indian states. Maharashtra and Gujarat retain polishing dominance while Karnataka and Telangana emerge as CVD seed production hubs.
Maharashtra
Mumbai's bridal-set purchasers drive solitaire ring demand through metro mall specialty stores. BIS disclosure mandates require laser inscription traceability from CVD origin through retail. The Mumbai-Pune corridor concentrates spectroscopic verification equipment deployment in assisted-selling formats.
Gujarat
Surat's diamond processing cluster integrates synthetic rough with traditional cutting infrastructure, compressing lead times from import to finished jewelry. CDSCO-adjacent import monitoring checkpoints shape synthetic rough supply chain configurations. The Surat polishing workforce requires retraining for synthetic rough handling and inclusion mapping.
Karnataka
Bangalore online shoppers lead adoption of augmented reality-enabled selection workflows for virtual try-on tools. EMI financing embedded in e-commerce checkout flows collapses payment friction for sub-INR 2 lakh transactions. The city anchors direct-to-consumer platform development that bypasses legacy bourse intermediaries.
Delhi-NCR
Urban millennial engagement ring purchasers in Delhi prioritize ethical provenance signaling in solitaire purchases. BIS enforcement protocols elevate compliance costs that favor scaled specialty store operators. The Delhi-Gurgaon corridor concentrates premium positioning through exclusive retail partnerships in metro malls.
Telangana
Hyderabad retail corridors remain underdeveloped for assisted-selling formats relative to Mumbai and Delhi. DGFT frameworks enable SEZ status for duty-free rough import and re-export of finished jewelry to Gulf markets. The city represents a target for tier-II city penetration strategies in specialty store expansion.
India Lab Grown Diamond Jewelry Market Competitive Landscape
On the supply side, the industry is tiered between captive rough producers, polished jewelry specialists, and direct-to-consumer platforms. Asset-light leasing models for CVD reactor equipment narrow capital barriers for mid-tier entrants. Two strategic archetypes dominate: vertically integrated manufacturers controlling rough-to-retail pipelines, and digitally native brands bypassing legacy intermediaries. Competitive moves concentrate on exclusive retail partnerships and EMI financing platform integration.
Among polished jewelry specialists, Bhanderi Lab Grown Diamonds and Limelight Diamonds exemplify contrasting channel strategies. Bhanderi occupies a position representing captive rough supply integration across the polishing pipeline. Limelight anchors premium positioning through metro mall presence. Fiona Diamonds sits within the direct-to-consumer archetype, representing digital-first customer acquisition that bypasses traditional bourse structures.
| Leading Market Players |
|---|
| Ivana Jewels |
| Bhanderi Lab Grown Diamonds |
| Emori |
| Nuvo Diamonds |
| Fiona Diamonds |
| Limelight Diamonds |
| ABD Diamonds |
| Maitri Lab-grown Diamonds |
| Varniya |
| Others |
Supply & Pricing Matrix
Synthetic rough import checkpoints through CDSCO-adjacent monitoring concentrate upstream supply control in Gujarat, compressing margin pools toward polished jewelry specialists in Surat who integrate CVD seed procurement with captive cutting capacity.
Pricing Analysis
BIS certification grade creates the primary spread between premium and standard tiers, with laser-inscribed D-F color stones commanding positioning advantages in Mumbai metro mall locations. Three-tier pricing structure across premium, standard, and economy levels reflects clarity differentiation and provenance documentation depth. Pricing pressure stems from power cost volatility in Maharashtra and Gujarat reactor operations. Online shoppers exhibit highest price sensitivity through EMI-dependent purchase behavior, while luxury brand partnerships sustain least sensitivity via exclusive distribution control.
Supply Chain Analysis
Surat polishing clusters anchor contract manufacturing concentration for domestic jewelry setting, with Bhanderi Lab Grown Diamonds and ABD Diamonds holding calibrated melee capacity. China, USA, and domestic CVD seed producers feed synthetic rough dependencies, while reactor equipment and seed crystals constitute critical input tiers. Single-source vulnerability concentrates in CDSCO-monitored import channels for high-purity synthetic rough. Distribution runs through specialty store assisted-selling formats in metro malls and direct-to-consumer platform endpoints that bypass legacy bourse intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's lab grown diamond jewelry sector represents early-cycle expansion, with BIS disclosure mandates accelerating quality standardization and consumer trust thresholds that compress adoption timelines for first-time purchasers.
For Market Incumbents: Insulate margin pools through captive CVD seed production investments in Karnataka and Telangana, reducing import dependency exposure. Deepen spectroscopic verification equipment deployment across Maharashtra and Gujarat specialty stores to defend against digitally native entrants bypassing assisted-selling formats. Channel control through exclusive retail partnerships in Delhi-Gurgaon metro malls remains critical.
For New Entrants and Emerging Players: Build out virtual try-on infrastructure targeting Bangalore and Hyderabad online shoppers, where augmented reality adoption collapses purchase friction fastest. Pune and Ahmedabad fashion jewelry segments offer penetrable white-space for stackable ring and convertible earring designs. Direct-to-consumer positioning with embedded EMI financing at checkout captures EMI-dependent urban millennials.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed polished jewelry specialists holding Surat cutting capacity and captive rough arrangements. Long-term viability hinges on downstream integration depth rather than standalone brand positioning. Watch BIS enforcement intensity and state-level GST audit frequency as inflection indicators for working capital requirements across inventory-heavy retail operators.
| Strategic Initiative | Industry Significance |
|---|---|
| CVD Seed Production Expansion | PLI scheme incentives reduce import dependency for domestic reactor operations. |
| Virtual Try-On Platform Integration | Augmented reality tools accelerate conversion timelines for Bangalore online shoppers. |
| Spectroscopic Verification Equipment Deployment | BIS compliance costs favor scaled specialty store operators in metro malls. |
| Exclusive Retail Partnership Formation | Limelight Diamonds anchors premium positioning through controlled distribution channels. |
| EMI Financing Platform Integration | Fintech partnerships embedded at checkout displace lump-sum payment expectations. |
Research Methodology
The analysis maps CVD reactor equipment, synthetic rough procurement, polishing operations, and retail distribution channels, each validated through CVD equipment suppliers, Surat polishing cluster managers, specialty store operators, and direct-to-consumer platform executives. Primary fieldwork combined with secondary validation draws from BIS disclosure filings, CDSCO import monitoring records, PLI scheme beneficiary disclosures, and gem and jewelry trade association data. Bottom-up segmentation sizing triangulates against top-down market envelope estimates.
Forecast assumptions hold BIS enforcement protocols, PLI incentive continuity, and power tariff trajectories within observed patterns across the projection horizon. Segmentation dimensions span product type, customer type, application, and distribution channel, with regional production cluster and certification tier as industry-specific modeling variables. CAGRs derive from segment-level growth rate synthesis applied to base-year value distributions. CVD reactor capacity expansion timelines and bridal-set purchase penetration curves constitute key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by captive rough producers or regulatory acceleration by BIS would shift outcomes. Quarterly review of CDSCO import checkpoint volumes, BIS certification issuance rates, and state-level electricity tariff adjustments is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Goods
Italy Luxury Goods Market
Luxury Goods
Luxury Handbag Market
Luxury Goods
Luxury Watches Market
Luxury Goods
Asia-Pacific Luxury Goods Market
Luxury Goods
France Luxury Goods Market
Luxury Goods
Global Gold and Diamond Jewellery Market
Luxury Goods
GCC Secondhand Luxury Goods Market
Luxury Goods
Luxury Pen Market
Luxury Goods
United States Secondhand Luxury Goods Market
Luxury Goods
China Luxury Market
Luxury Goods
Luxury Piano Market
Luxury Goods
Singapore Luxury Goods Market
Luxury Goods
GCC Personal Luxury Goods Market
Luxury Goods
China Luxury Goods Market
Luxury Goods
United Kingdom Luxury Goods Market
Luxury Goods
GCC Luxury Goods Market