
 United Arab Emirates Luxury Goods Market | 2026-2036
United Arab Emirates Luxury Goods Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Luxury Goods Market Analytics
The UAE's dual carbon goals and MOHAP cosmetic ingredient transparency mandates are pivoting procurement standards across luxury retail. LVMH Moët Hennessy Louis Vuitton leverages its vertical fragrance manufacturing to preempt regulatory compliance. Chalhoub Group anchors regional distribution through controlled boutique networks in Dubai Mall and Mall of the Emirates. Kering SA differentiates via dedicated sustainability scoring for leather goods entering the Emirates.
Luxury goods comprise high-value, non-essential products distinguished by superior craftsmanship, brand heritage, and scarcity-driven pricing, typically utilizing precious metals, exotic leathers, and limited-batch production runs to signal exclusivity and social capital. Fashion and jewelry segments dominate volume throughput in Dubai's retail corridors, while ultra-luxury watches capture concentrated margin pools among Emirati collectors. Tourist-facing sales channels sustain higher transaction frequencies than resident-dependent independent boutiques, reflecting Dubai's positioning as a regional shopping destination.
MOHAP enforces cosmetic safety and labeling standards that determine import eligibility for beauty and fragrance categories, while the UAE's dual carbon goals pressure logistics and packaging specifications across luxury supply chains. Dubai's Department of Economy and Tourism coordinates retail licensing that shapes where ultra-luxury brands establish flagship presence. Stakeholders must monitor evolving Emirati consumer protection frameworks and carbon disclosure requirements that will determine which brand positioning tiers sustain market access.
Market Dynamics
MOHAP cosmetic ingredient transparency mandates and the UAE's dual carbon goals are restructuring procurement standards across luxury retail, forcing brands to reconfigure supply chains and packaging specifications to maintain market access.
Growth Catalysts
- High-net-worth resident demand:Ultra-luxury jewelry and watches consumption by Emirati collectors is strengthening alongside tourist spending recovery in Dubai's mall ecosystems.
- MOHAP regulatory clarity:The Ministry of Health and Prevention's cosmetic safety standards provide predictable import eligibility frameworks that reduce compliance uncertainty for fragrance and beauty categories.
- Dubai retail free zones:Jebel Ali Free Zone and Dubai Airport Freezone offer duty advantages and streamlined logistics that concentrate luxury distribution infrastructure.
Market Restraints
- Exotic leather input costs:CITES-regulated python and crocodile leather sourcing faces escalating permit costs and supply concentration among European tanneries.
- Carbon disclosure requirements:The UAE's dual carbon goals pressure logistics providers to retrofit cold-chain transport and sustainable packaging, raising operational overhead.
- Limited domestic manufacturing:Absence of captive production for precious metals and gem-setting creates dependency on Swiss and Italian workshops, extending lead times.
Strategic Opportunities
- Abu Dhabi cultural retail corridors:Saadiyat Island and Al Maryah Island developments offer underpenetrated flagship positioning outside Dubai's saturated mall density.
- Blockchain authentication convergence:Integration of NFC chips with heritage craftsmanship is creating digital provenance verification for secondary market resale value protection.
- MOHAP pre-certification pathways:Early ingredient disclosure submissions enable faster product registration cycles, rewarding compliant brands with first-mover shelf positioning.
Industry Challenges
- Master craftsperson scarcity:Gem-setting and haute horlogerie finishing skills concentrate in Geneva and Vallee de Joux, constraining UAE-based service center expansion.
- Legacy ERP integration:Boutique point-of-sale systems require costly reconfiguration to connect with MOHAP track-and-trace databases for cosmetic batch monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Luxury Goods Market |
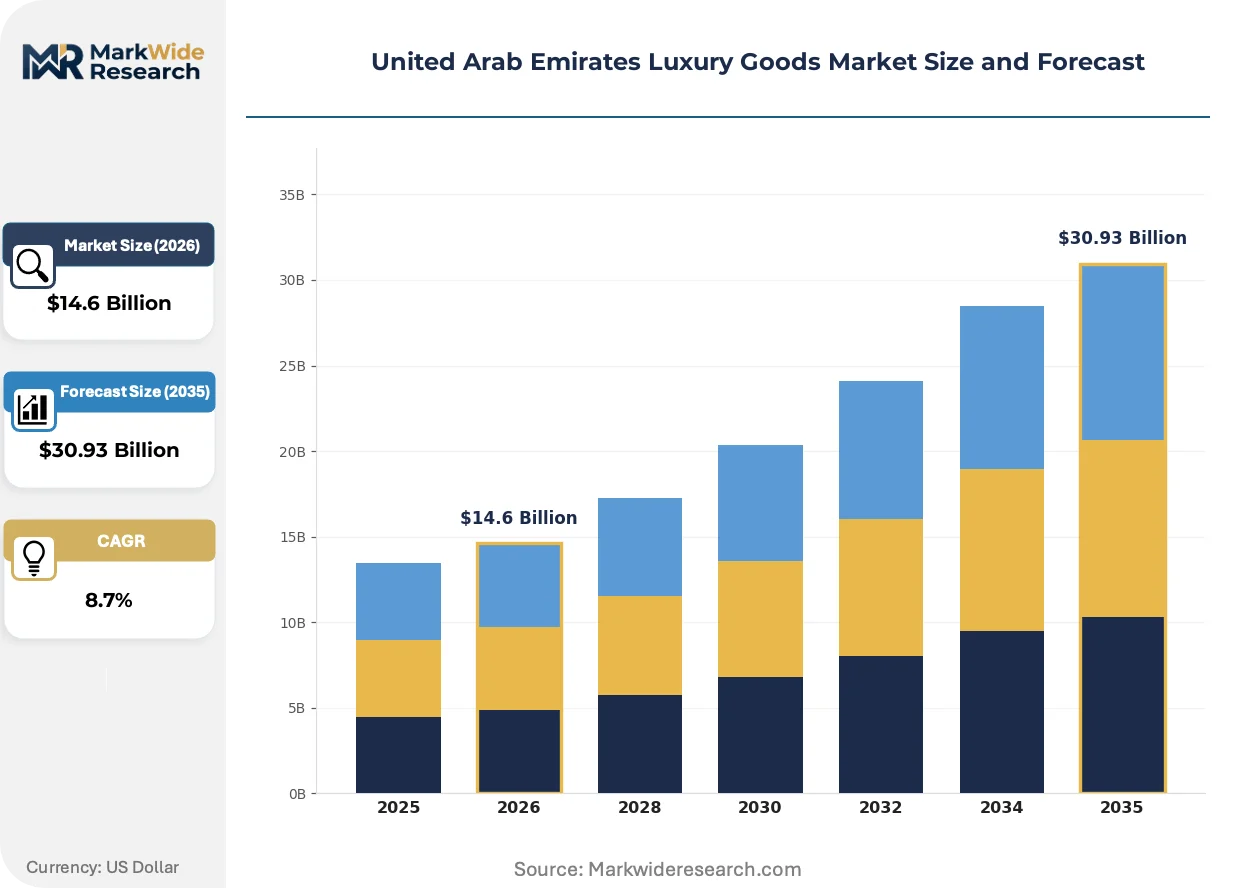
| Market Size in 2026 | $14.6 Billion |
| Market Size in 2035 | $30.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fashion, Jewelry, Watches, Cosmetics Customer Type: Affluent Individuals, Tourists, Expatriates, Celebrities Sales Channel: Online Retail, Independent Boutiques, Multi-brand Stores, Department Stores Brand Positioning: Premium, Ultra-luxury, Accessible Luxury, Emerging Brands |
| Companies Covered | LVMH Moët Hennessy Louis Vuitton, Kering SA, Hermès International SA, Rolex SA, Chanel SA, Chalhoub Group, Al Tayer Group, Azadea Group, Compagnie Financière Richemont SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Luxury Goods Market Evolving Landscape
Digital authentication technologies and regulatory transparency mandates are compressing traditional opacity in luxury supply chains, while experiential retail formats reshape how ultra-high-net-worth consumers engage with heritage brands.
Near-field communication chips embedded in watch cases and leather goods is electrifying provenance verification across the secondary market. Emirati collectors and Dubai-based dealers are adopting NFC-enabled authentication at accelerating rates. This technology is compressing warranty fraud and gray-market arbitrage that previously eroded brand equity.
MOHAP's cosmetic ingredient disclosure requirements are mandating full supply chain visibility for fragrance and skincare imports entering the Emirates. Manufacturers must submit complete raw material sourcing documentation to secure product registration. Beauty categories face the steepest compliance burden, with reformulation timelines extending six to twelve months for non-compliant legacy portfolios.
Private appointment-only salons are displacing open-floor boutique browsing among ultra-high-net-worth Emirati buyers. Chalhoub Group and independent operators are converting Mall of the Emirates and Dubai Mall spaces into by-invitation showrooms with dedicated clienteling staff. This behavioral pivot concentrates transaction values and reduces tourist-dependent foot traffic volatility in Abu Dhabi's emerging retail corridors.
United Arab Emirates Luxury Goods Market Segmentation
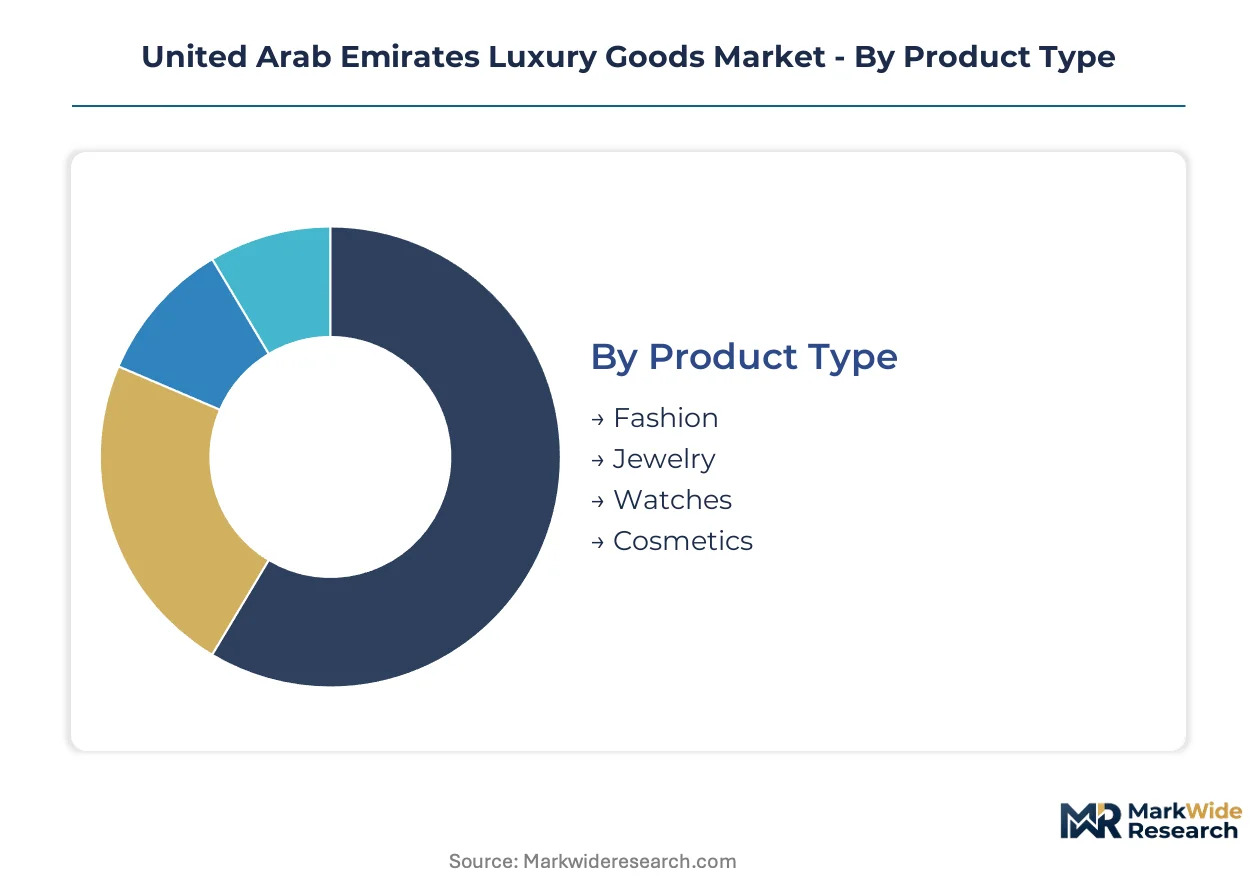
Segmentation in the UAE luxury goods market reveals distinct consumption patterns between resident collectors and transient visitors. Dubai's mall ecosystems concentrate volume throughput while Abu Dhabi's cultural corridors attract premium positioning. Understanding these divides enables precise inventory allocation and storefront strategy across Emirates.
Product Type:
Fashion and jewelry dominate transaction volumes in Dubai's retail corridors, while watches command concentrated margin pools among Emirati collectors.
- Fashion:Ready-to-wear and leather goods utilizing exotic skins and Italian craftsmanship anchor Dubai Mall flagship footprints. Tourists from Saudi Arabia and Kuwait drive seasonal volume spikes in Mall of the Emirates locations during Ramadan and Eid periods.
- Jewelry:High-carat gold and gemstone pieces incorporating Emirati design motifs serve wedding and inheritance customs among local families. Demand concentrates in Gold Souk extensions and dedicated salon spaces within Galleria Mall on Al Maryah Island.
- Watches:Haute horlogerie complications from Swiss manufactures dominate collector circles in Abu Dhabi.
- Cosmetics:MOHAP-regulated fragrances and skincare face six-to-twelve month reformulation cycles for ingredient compliance.
Today's leader: Fashion. Tomorrow's challenger: Watches.
Customer Type:
Resident purchasing power sustains margin stability while tourist flows introduce transaction volatility.
- Affluent Individuals:Emirati collectors pursuing limited-edition releases and bespoke commissioning represent the highest per-transaction value segment. Private appointment salons in Dubai Mall now require seven-figure annual spend thresholds for access to haute joaillerie previews.
- Tourists:Visitors from Russia, China, and GCC neighbors concentrate spending in duty-advantaged free zone retail. Chalhoub Group's tourist-facing boutiques generate transaction frequencies triple those of resident-dependent independent operators.
- Expatriates:Long-term residents from Europe and South Asia favor accessible luxury tiers for workplace and social signaling.
- Celebrities:Influencer seeding programs target regional entertainment figures for red carpet placement and social media amplification.
Affluent Individuals anchor current profitability. Tourists offer the steepest expansion trajectory as flight capacity normalizes.
Sales Channel:
Physical retail infrastructure commands premium positioning while digital channels capture convenience-oriented replenishment.
- Online Retail:Brand-owned e-commerce and Farfetch partnerships serve expatriates seeking home delivery of cosmetics and small leather goods. MOHAP batch tracking requirements complicate direct-to-consumer fragrance fulfillment.
- Independent Boutiques:Single-brand flagships in Dubai Design District and Saadiyat Island enable controlled experiential environments. These locations depend on resident foot traffic rather than tourist volume.
- Multi-brand Stores:Chalhoub Group's Level Shoes and Tanagra aggregate competing labels under unified clienteling programs.
- Department Stores:Harvey Nichols and Bloomingdale's Dubai maintain beauty hall dominance through exclusive launch partnerships.
Multi-brand Stores currently capture the widest SKU exposure. Online Retail faces regulatory friction but offers long-term cost advantages.
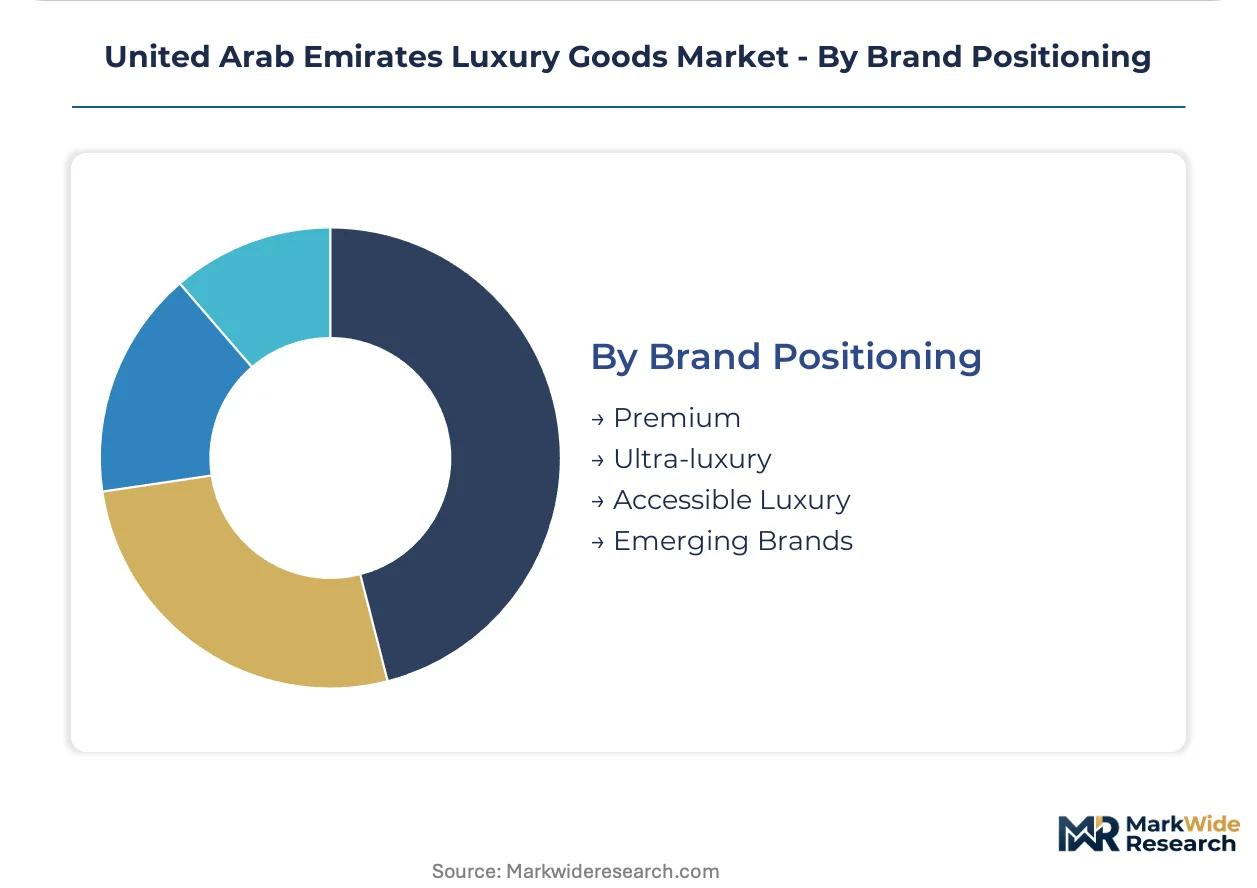
Brand Positioning:
Price tier stratification determines mall placement, with ultra-luxury commanding ground-floor flagship positioning.
- Premium:Diffusion lines and core collections from established maisons occupy high-traffic atrium locations. These SKUs generate volume throughput that subsidizes experiential investments in ultra-luxury salons.
- Ultra-luxury:Bespoke commissioning and limited editions with waiting lists concentrate in by-invitation spaces. Kering's sustainability scoring and LVMH's vertical fragrance manufacturing differentiate supply chain credentials for this tier.
- Accessible Luxury:Contemporary labels target expatriate professionals with entry-level leather goods and cosmetics.
- Emerging Brands:Regional designers from Lebanon and Saudi Arabia leverage Dubai Fashion Week for market entry.
Ultra-luxury defines margin structure. Emerging Brands present acquisition targets for conglomerates seeking regional authenticity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Master craftspeople in Swiss ateliers and Italian tanneries anchor the talent pipeline feeding UAE luxury demand. Their concentrated expertise determines product availability and pricing power across Emirates retail corridors.
Dubai
High-net-worth Emirati collectors drive ultra-luxury watch and jewelry demand through Mall of the Emirates and Dubai Mall flagships. MOHAP cosmetic safety standards determine import eligibility for fragrance houses establishing Gulf headquarters. The Dubai Design District cluster concentrates independent boutique operators and regional brand incubators alongside established maisons.
Abu Dhabi
Cultural retail corridors on Saadiyat Island and Al Maryah Island attract premium positioning outside Dubai's saturated mall density. The Department of Culture and Tourism coordinates licensing that shapes ultra-luxury flagship placement. Galleria Mall anchors high-carat gold and gemstone demand among local families observing wedding and inheritance customs.
Sharjah
Value-conscious expatriate professionals from South Asia and the Levant accessible luxury tiers for workplace signaling. The emirate's logistics free zones support redistribution to Northern Emirates markets. Sharjah's retail corridors concentrate mid-tier leather goods and cosmetics volume outside Dubai-Abu Dhabi premium positioning.
Northern Emirates
Ajman, Fujairah, Ras Al Khaimah, and Umm Al Quwain serve as emerging distribution nodes for tourist-facing duty-advantaged retail. The country's dual carbon goals pressure cold-chain logistics retrofitting across these less-developed retail corridors. E-commerce fulfillment centers here capture convenience-oriented replenishment from expatriate residents.
United Arab Emirates Luxury Goods Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the UAE luxury landscape. Vertically integrated European maisons control manufacturing and distribution, while regional retail conglomerates anchor local market access. Three archetypes dominate: Swiss- and French-based heritage houses with captive ateliers, Gulf family-owned distribution groups controlling mall positioning, and independent regional operators specializing in experiential retail formats. Competitive moves concentrate on flagship expansion into Abu Dhabi's underpenetrated corridors and blockchain authentication integration for secondary market protection.
Within the heritage house tier, LVMH Moët Hennessy Louis Vuitton and Kering SA exemplify vertical manufacturing control that preempts regulatory compliance. Among Gulf-based distributors, Chalhoub Group occupies a position bridging European brand relationships with Emirates mall dominance. These three entities represent the structural separation between production-origin power and retail-destination access that defines competitive positioning.
| Leading Market Players |
|---|
| LVMH Moët Hennessy Louis Vuitton |
| Kering SA |
| Hermès International SA |
| Rolex SA |
| Chanel SA |
| Chalhoub Group |
| Al Tayer Group |
| Azadea Group |
| Compagnie Financière Richemont SA |
| Others |
Value Network & Pricing Analysis
Ultra-luxury versus accessible luxury tier divergence compresses margin structures through divergent service bundling and sourcing intensity. Haute horlogerie and bespoke jewelry command bundled after-sales servicing and provenance verification that justify premium positioning, while accessible leather goods face unbundled transactional pricing and compressed sourcing flexibility due to CITES-regulated exotic skin permit costs.
Pricing Analysis
Bundled after-sales service versus unbundled product-only transactions defines the pricing architecture across Emirates retail corridors. Ultra-luxury maisons embed lifetime servicing, authentication, and resale support into initial price points, while accessible tiers separate warranty extensions and repair services as add-on revenue streams. Price differentiation hinges on heritage certification and customization depth, with Swiss-made provenance and bespoke gem-setting commanding substantial premiums. Cost compression in accessible leather goods is intensifying as CITES permit costs for python and crocodile skins escalate, squeezing margin pools for non-vertically integrated brands. Tourist-facing duty-advantaged channels exhibit the lowest price sensitivity among Russian and Chinese visitors, while expatriate professionals demonstrate acute responsiveness to promotional cycles.
Supply Chain Analysis
Freight cost volatility from European ateliers to Dubai free zones is reshaping inventory positioning strategies across luxury distribution networks. Manufacturing gravity centers on Switzerland for haute horlogerie complications, Italy for exotic leather finishing and precious metal jewelry, and France for fragrance compounding and cosmetics formulation. Raw material dependencies encompass CITES-regulated reptile skins from European tanneries, conflict-free gem parcels from Antwerp and Mumbai trading hubs, and rare earth components for NFC authentication chips. Single-source vulnerability concentrates in Geneva and Vallee de Joux for master gem-setters and watch finishers, constraining UAE-based service center scaling. Distribution runs through Jebel Ali Free Zone and Dubai Airport Freezone for duty-advantaged consolidation before mall and boutique allocation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE luxury goods market functions as a regulatory compounder where MOHAP cosmetic ingredient transparency mandates and dual carbon disclosure requirements continuously elevate compliance thresholds that favor capital-intensive incumbents with captive manufacturing infrastructure.
For Market Incumbents: Deploy blockchain authentication infrastructure to protect secondary market resale value and compress gray-market arbitrage. Establish dedicated Abu Dhabi flagship presence on Saadiyat Island before mall density saturation replicates Dubai's competitive intensity. Preempt MOHAP pre-certification pathways for fragrance portfolios to secure first-mover shelf positioning against reformulation-lagged competitors. For New Entrants and Emerging Players: Expatriate professionals in Sharjah and Northern Emirates represent an underserved buyer archetype seeking accessible luxury tiers for workplace signaling without Dubai premium positioning overhead. Private appointment salon formats in Al Maryah Island's Galleria Mall offer white-space positioning outside Chalhoub Group's mall dominance. Digital-native direct-to-consumer fulfillment with MOHAP-compliant batch tracking enables regulatory-compliant market entry without legacy ERP reconfiguration burdens. For Investors and Strategic Acquirers: Asymmetric upside sits with regional design houses from Lebanon and Saudi Arabia that leverage Dubai Fashion Week visibility for conglomerate acquisition premiums. Long-term viability hinges on vertical manufacturing control or exclusive distribution relationships with Emirates mall operators. Watch for MOHAP enforcement intensity against non-compliant fragrance imports as the inflection indicator separating compliant from distressed acquisition targets.| Strategic Initiative | Industry Significance |
|---|---|
| NFC Authentication Integration | Digital provenance verification protects resale value for Emirati collector circles. |
| Abu Dhabi Flagship Expansion | Saadiyat Island positioning escapes Dubai mall density saturation. |
| MOHAP Pre-Certification Investment | Early ingredient disclosure accelerates fragrance registration cycles. |
| Private Appointment Salon Conversion | By-invitation formats concentrate transaction value among ultra-high-net-worth residents. |
| Sustainable Leather Sourcing | Kering's sustainability scoring preempts CITES permit cost escalation. |
Research Methodology
Multiple input streams — structured interviews with luxury retail executives, regulatory affairs specialists at MOHAP, and procurement directors at European maisons — were reconciled against secondary validation from customs records, mall operator leasing disclosures, and fragrance registration databases. Primary fieldwork encompassed boutique operations managers, free zone logistics coordinators, and collector community representatives across Dubai and Abu Dhabi. Secondary sources included Dubai Department of Economy and Tourism retail licensing data, MOHAP cosmetic safety filings, and Swiss watch export statistics. Bottom-up SKU-level demand modeling and top-down macroeconomic consumption projections were triangulated to anchor volume and value estimates.
Data-stream reconciliation across the projection horizon employed segmented demand modeling by product type, customer archetype, and sales channel, with additional dimensioning by brand positioning tier and Emirates geography. CAGRs were derived from trend extrapolation adjusted for regulatory milestone impacts and tourist flow normalization assumptions. Industry-specific forecast inputs incorporated MOHAP compliance timeline probabilities, CITES permit cost trajectories, and NFC authentication adoption curves among Emirati collectors.
Underlying measurement precision varies by segment; fashion and cosmetics carry tighter precision than ultra-luxury watches due to standardized customs classification and retail audit coverage. Forecasts reflect documented assumptions regarding tourist recovery velocity, regulatory enforcement intensity, and carbon disclosure implementation timelines. A model refresh is warranted upon material change in MOHAP ingredient transparency enforcement or dual carbon goal acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Goods
Luxury Pen Market
Luxury Goods
Asia-Pacific Luxury Goods Market
Luxury Goods
United Kingdom Luxury Goods Market
Luxury Goods
Designer Bags and Luxury Handbags Market
Luxury Goods
Brazil Luxury Goods Market
Luxury Goods
Thailand Luxury Goods Market
Luxury Goods
Singapore Luxury Goods Market
Luxury Goods
Mens Watch Market
Luxury Goods
China Luxury Market
Luxury Goods
France Luxury Goods Market
Luxury Goods
Europe Secondhand Luxury Goods Market
Luxury Goods
Hard Luxury Goods Market
Luxury Goods
Qatar Luxury Good Market
Luxury Goods
North America Luxury Goods Market
Luxury Goods
Luxury Piano Market
Luxury Goods
United States Secondhand Luxury Goods Market