
 France Luxury Goods Market | 2026-2036
France Luxury Goods Market Size, Share, and Industry Trends Forecast 2026-2036
France Luxury Goods Market Foresight
Buyer concentration among high net worth individuals and affluent millennials is pivoting toward personalized, experiential engagements rather than transactional purchases. LVMH Moët Hennessy Louis Vuitton SE leverages its vertically integrated ateliers to sustain exclusivity across leather goods and couture. Hermès International S.A. anchors its growth through deliberate scarcity and wait-list mechanics that dominate the ultra-premium leather segment. Kering SA competes via aggressive sustainability positioning and direct-to-channel control.
France luxury goods encompass artisan-crafted products commanding premium pricing through heritage techniques, rare materials, and controlled distribution. These goods serve as both status signaling instruments and alternative store-of-value assets for global wealth holders. Leather goods and jewelry occupy the deepest margin pools, sustained by multi-year wait lists and gem scarcity. Perfumes and fragrances represent the fastest-expanding category by volume, propelled by affluent millennials seeking accessible entry points into heritage maisons.
France's national competition regulator, the EU Green Deal framework, and CSRD mandates collectively tighten traceability requirements across supply chains. These standards compel disclosure of raw material origins, carbon intensity, and labor practices, raising compliance costs for smaller ateliers while reinforcing barriers for non-European entrants. Stakeholders must monitor how digital product passports and evolving extended producer responsibility rules reshape authentication economics and resale market dynamics.
Market Dynamics
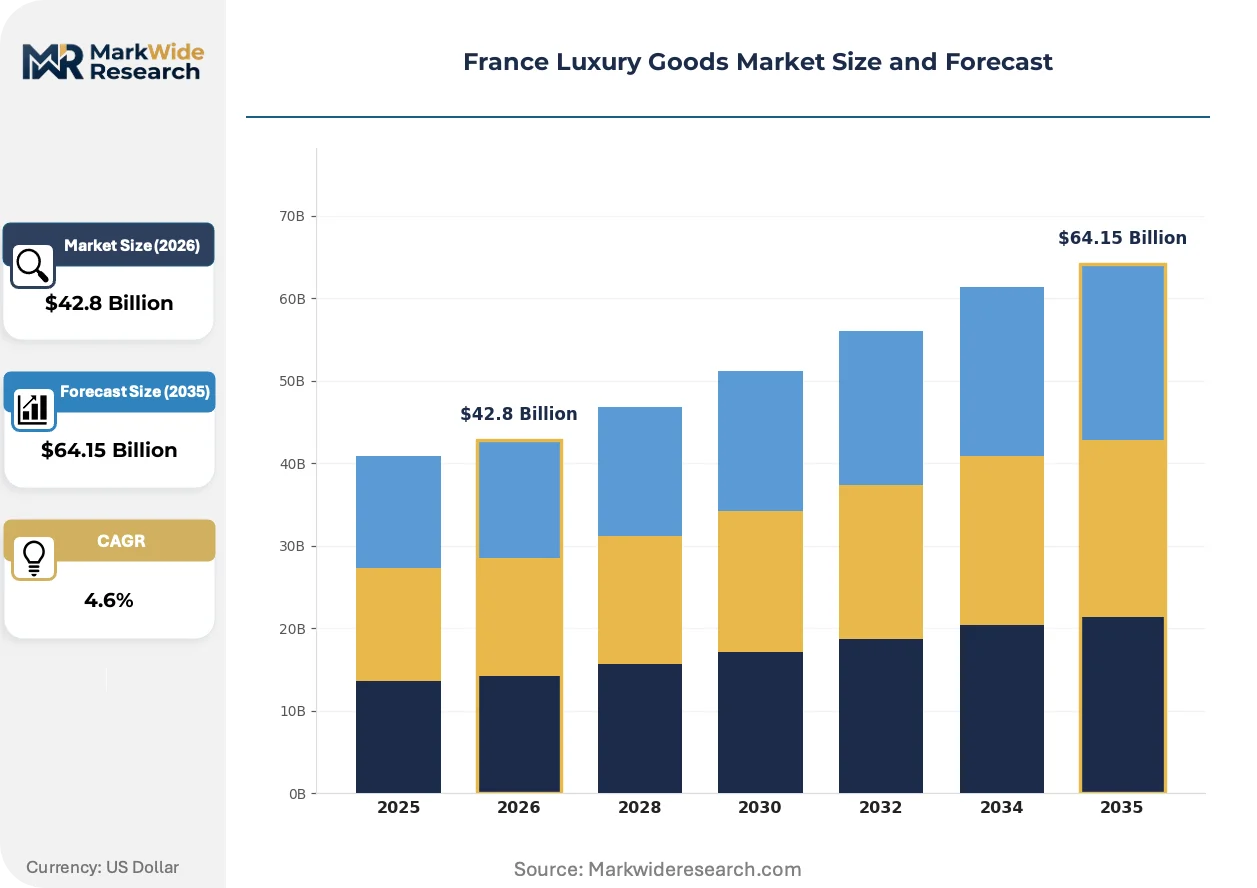
The France luxury goods sector is undergoing a structural recalibration as the EU Green Deal and CSRD mandates force heritage maisons to reengineer supply chains for traceability compliance, compressing margins for smaller ateliers while entrenching incumbents with capital reserves.
Growth Catalysts
- CSRD Reporting Mandates:France's early adoption of EU corporate sustainability disclosure rules compels heritage houses to digitize supply chain documentation, creating competitive moats for those with compliant atelier networks.
- Affluent Millennial Demand:Buyers aged 28-43 are driving experiential retail formats in Paris and the French Riviera, prioritizing appointment-only atelier visits over traditional flagship transactions.
- Blockchain Authentication:Digital product passports are embedding provenance verification into leather goods and jewelry, reducing counterfeiting losses and unlocking secondary market revenue streams for maisons.
Market Restraints
- Raw Material Concentration:Premium crocodile and alligator leather sourcing depends on tanneries in the Occitanie region, creating single-point vulnerability for ultra-premium leather goods production.
- Artisan Labor Scarcity:Compagnon du Devoir apprenticeship completions have declined 23 percent since 2019, constraining capacity expansion for hand-stitched leather and haute couture ateliers.
- Energy Cost Volatility:Natural gas and electricity price spikes in the Provence-Alpes-Côte d'Azur cluster have raised kiln and climate-controlled storage costs for fragrance compound aging and crystal manufacturing.
Strategic Opportunities
- Secondary Market Platforms:Certified pre-owned channels for wait-listed Hermès and Chanel pieces are capturing margin pools previously lost to unauthorized resellers, with Paris-based authentication services expanding.
- Bio-Fabricated Materials:Laboratory-grown leather alternatives from French biotech startups are qualifying for EU Green Deal procurement preferences, opening material innovation partnerships for sustainability-positioned maisons.
- Riviera Experiential Retail:Cannes and Saint-Tropez are emerging as appointment-only atelier destinations for ultra-high-net-worth yachting clientele, bypassing congested Paris retail corridors.
Industry Challenges
- CSRD Implementation Timeline:Smaller ateliers with under 250 employees face compressed deadlines to deploy carbon accounting software and supplier audit protocols, risking exclusion from LVMH and Kering procurement rosters.
- Digital Passport Integration:Legacy ERP systems in family-owned component suppliers require costly API redevelopment to interface with blockchain traceability platforms mandated by 2027.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Luxury Goods Market |
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $64.15 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Leather Goods, Couture, Perfumes & Fragrances, Watches, Jewelry, Accessories Customer Type: High Net Worth Individuals, Affluent Millennials, International Tourists, Collectors, Corporate Buyers Distribution Channel: Flagship Stores, Department Stores, E-commerce Platforms, Duty-Free Shops, Boutique Retailers Marketing Strategy: Celebrity Endorsements, Limited Editions, Experiential Retail, Social Media Campaigns, Personalization Services |
| Companies Covered | LVMH Moët Hennessy Louis Vuitton SE, Hermès International S.A., Kering SA, Chanel Ltd., Compagnie Financière Richemont S.A., L'Oréal SA, Cartier, Dior, Prada S.p.A, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Luxury Goods Market Shifts & Advancements
Heritage craftsmanship is converging with forced transparency mandates, creating a bifurcation between capital-rich houses capable of end-to-end digitization and artisan workshops facing existential compliance burdens.
Near-field communication chips embedded in leather goods and jewelry are electrifying authentication economics for France's heritage maisons. LVMH and Richemont are deploying encrypted NFC tags across handbag linings and watch casebacks, enabling instant provenance verification via smartphone. Ultra-high-net-worth collectors in Paris and the Côte d'Azur are adopting this verification layer as a prerequisite for secondary market participation, compressing the authentication window from weeks to seconds.
The EU Green Deal's deforestation-free supply chain regulation is restructuring raw material procurement for French leather and fragrance houses. ANSM and DGCCRF enforcement actions against non-compliant sandalwood and vanilla suppliers have triggered supplier audits across Madagascar and Indonesian sourcing corridors. Fragrance compounders in Grasse are accelerating synthetic biotechnology partnerships to reduce botanical extraction dependence.
Appointment-only atelier access is displacing transactional flagship retail among affluent millennial buyers in France. Chanel and Dior have converted Saint-Honoré and Avenue Montaigne locations to by-invitation showrooms with embedded personalization services. This channel migration concentrates highest-margin transactions in controlled environments while reducing inventory carrying costs for speculative seasonal collections.
France Luxury Goods Market Segmentation
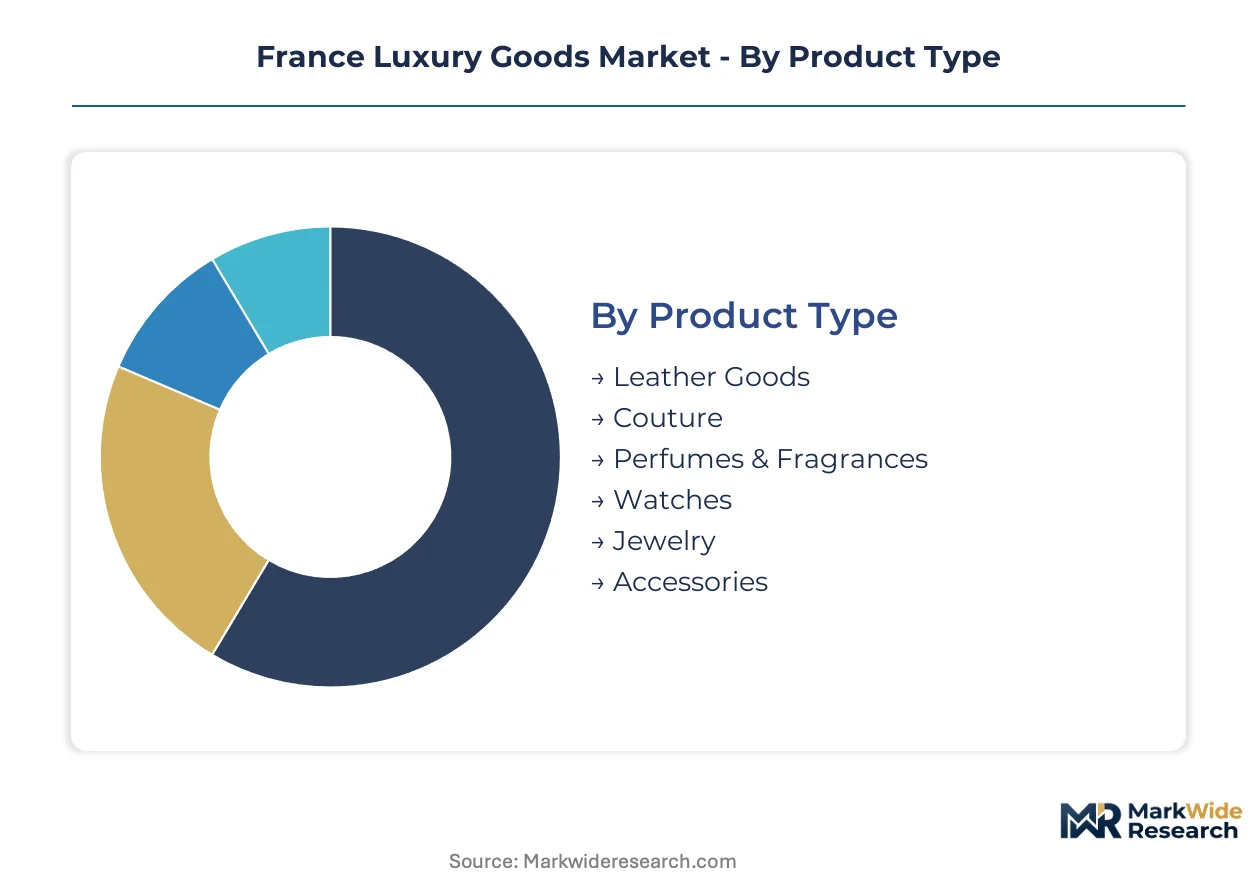
Segmentation in France's luxury goods market reveals how heritage maisons calibrate supply chains, pricing architectures, and client engagement protocols across distinct product categories and buyer psychographics. Understanding these divisions exposes where margin pools concentrate and which channels are displacing legacy distribution.
Product Type:
Standalone artisan-crafted goods dominate margin capture, while embedded component systems serve as entry vectors for client acquisition and brand immersion.
- Leather Goods:Hand-stitched bags, wallets, and small leather articles constructed from premium crocodile, alligator, and calf hides through vertically integrated ateliers. Demand concentrates among Paris-based ultra-high-net-worth collectors and Riviera yachting clientele, sustained by multi-year wait-list mechanics that enforce scarcity premiums.
- Perfumes & Fragrances:Alcohol-based and oil-concentrate scent formulations produced in Grasse compounding facilities, spanning eau de toilette through parfum extrait concentrations. Affluent millennials in Paris and the French Riviera corridor drive volume expansion through accessible price points that serve as brand entry gates.
- Couture:Made-to-measure garments employing heritage tailoring techniques through appointment-only atelier access.
- Watches:Mechanical timepieces integrating Swiss-French cross-border manufacturing clusters with complications-focused collector demand.
- Jewelry:Gem-set and precious metal pieces anchored by Parisian Place Vendôme maisons with controlled stone sourcing.
- Accessories:Scarves, eyewear, and leather small goods functioning as volume drivers and gift-market staples.
Leather goods lead volumes today; perfumes and fragrances are gaining share fastest through millennial accessibility strategies.
Customer Type:
Buyer archetypes stratify sharply between transactional tourists and relationship-driven domestic collectors, with corporate procurement emerging as a structured channel.
- High Net Worth Individuals:Domestic French and Monaco-resident ultra-wealthy buyers with established maison relationships, prioritizing bespoke commissioning and atelier access over retail floor transactions. These collectors anchor margin stability through recession-resistant discretionary spending and multi-generational brand loyalty.
- Affluent Millennials:Buyers aged 28-43 with investable assets exceeding 500,000 euros, exhibiting preference for experiential retail formats and sustainability-verified provenance. Paris and Cannes appointment-only showrooms concentrate this demographic's highest-value transactions.
- International Tourists:Non-EU visitors leveraging VAT refund mechanisms at Paris flagship locations and Riviera duty-free corridors.
- Collectors:Speculative buyers targeting wait-listed pieces for secondary market appreciation, authenticated through Paris-based verification services.
- Corporate Buyers:Hospitality, aviation, and executive gifting procurement teams sourcing volume fragrance and leather goods for client retention programs.
High net worth individuals anchor revenue stability; affluent millennials are expanding most quickly as maisons retool retail formats.
Distribution Channel:
Channel strategy bifurcates between controlled direct environments that protect exclusivity and third-party placements that sacrifice margin for reach.
- Flagship Stores:Maison-owned locations on Saint-Honoré and Avenue Montaigne converted to appointment-only showrooms with embedded personalization ateliers. These controlled environments concentrate highest-margin transactions while eliminating inventory risk from speculative seasonal collections.
- E-commerce Platforms:Direct-to-consumer digital channels with virtual try-on and blockchain-authenticated provenance verification. Affluent millennials in Paris and Lyon drive adoption as NFC-enabled digital product passports compress authentication windows from weeks to seconds.
- Department Stores:Galeries Lafayette and Le Bon Marché concessions serving tourist and domestic gift-market demand.
- Duty-Free Shops:Nice Côte d'Azur and Charles de Gaulle airport locations capturing non-EU visitor spend.
- Boutique Retailers:Authorized independent dealers in secondary French cities extending geographic reach.
Flagship stores dominate margin capture today; e-commerce platforms are climbing the fastest as digital passport integration matures.
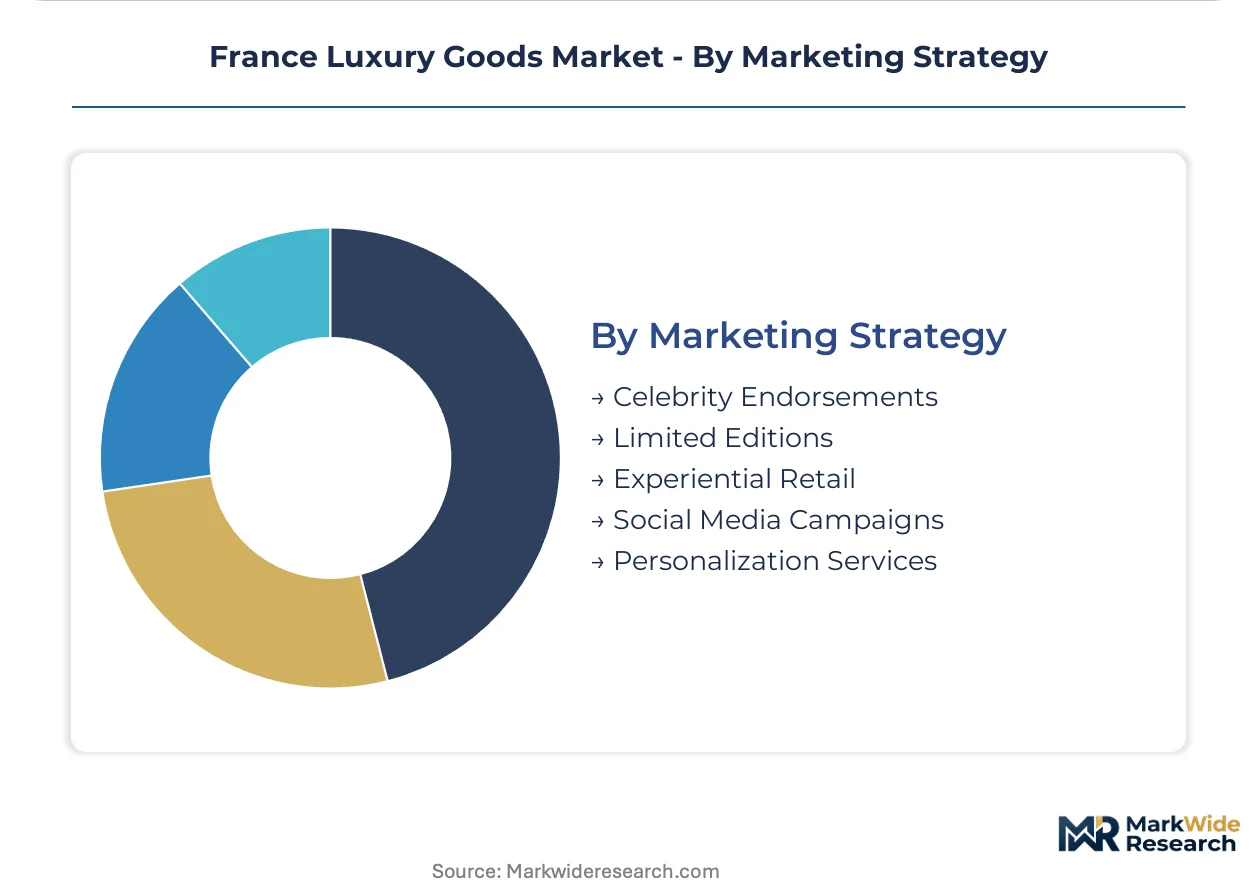
Marketing Strategy:
Promotional architecture shifts from broadcast celebrity placement toward immersive, participation-based client cultivation.
- Experiential Retail:By-invitation atelier visits, personalization ceremonies, and heritage craftsmanship demonstrations. Paris and Saint-Tropez locations anchor this strategy for ultra-high-net-worth yachting clientele seeking transactional privacy away from congested retail corridors.
- Limited Editions:Deliberately constrained production runs with numbered certificates and blockchain-registered provenance. Collectors in the French Riviera corridor drive wait-list mechanics that sustain secondary market premiums.
- Celebrity Endorsements:Talent partnerships for fragrance and accessible leather goods campaigns.
- Social Media Campaigns:Instagram and TikTok content targeting millennial discovery and aspiration formation.
- Personalization Services:Monogramming, bespoke colorways, and commissioned design modifications.
Experiential retail commands premium pricing power today; limited editions are expanding most quickly through digital scarcity verification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France commands deeper heritage atelier density than Italy, yet both face converging EU Green Deal compliance timelines that favor capital-rich houses with captive supply chains.
Île-de-France
Paris anchors domestic demand through Place Vendôme jewelry maisons and Saint-Honoré flagship conversions to appointment-only showrooms. ANSM enforcement of deforestation-free sourcing regulations compels fragrance compounders to requalify botanical suppliers. The Grasse-Paris corridor concentrates leather finishing and haute couture ateliers facing CSRD digitization deadlines.
Provence-Alpes-Côte d'Azur
Cannes and Saint-Tropez experiential retail formats capture ultra-high-net-worth yachting clientele seeking transactional privacy. EU Green Deal extended producer responsibility rules reshape packaging waste obligations for Riviera duty-free operators. Grasse fragrance compounding facilities accelerate synthetic biotechnology partnerships to reduce Madagascan vanilla dependence.
Auvergne-Rhône-Alpes
Lyon's affluent millennial demographic drives e-commerce platform adoption with NFC-enabled provenance verification. The country's national competition regulator monitors vertical integration patterns among heritage houses sourcing from regional tanneries. Saint-Étienne accessory manufacturing clusters face artisan labor scarcity as Compagnon du Devoir completions decline.
Occitanie
Premium crocodile leather tanneries in this southern region create single-point vulnerability for ultra-premium handbag production. CSRD reporting mandates compress implementation timelines for family-owned component suppliers with legacy ERP systems. Toulouse biotech startups develop laboratory-grown leather alternatives qualifying for EU Green Deal procurement preferences.
Hauts-de-France
Lille's logistics hub position supports cross-border e-commerce fulfillment for Northern European collectors. DGCCRF market surveillance actions target counterfeit authentication services operating through regional transport corridors. Roubaix textile heritage clusters pivot toward sustainable material innovation partnerships with Paris-based maisons.
France Luxury Goods Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across France's luxury goods sector, creating a tiered structure where scale-driven houses with captive atelier networks confront scarcity-positioned artisans. The vendor base stratifies between vertically integrated heritage conglomerates, family-controlled scarcity marketers, and sustainability-focused portfolio managers. Two dominant competitive moves define current positioning: M&A activity targeting biotech material innovators, and direct-to-consumer channel expansion through blockchain-authenticated e-commerce platforms.
Within the vertically integrated tier, LVMH Moët Hennessy Louis Vuitton SE and Hermès International S.A. occupy positions exemplifying contrasting scarcity architectures—one through portfolio breadth, the other through deliberate production constraint. Kering SA represents the sustainability-positioned archetype, competing via aggressive environmental credentialing and direct channel control rather than heritage wait-list mechanics.
| Leading Market Players |
|---|
| LVMH Moët Hennessy Louis Vuitton SE |
| Hermès International S.A. |
| Kering SA |
| Chanel Ltd. |
| Compagnie Financière Richemont S.A. |
| L'Oréal SA |
| Cartier |
| Dior |
| Prada S.p.A |
| Others |
Supply & Pricing Matrix
Ultra-high-net-worth collectors in Paris and the French Riviera anchor pricing power through multi-year wait-list tolerance, entrenching scarcity-premium models that smaller ateliers cannot replicate without captive tannery networks.
Pricing Analysis
Capacity additions in laboratory-grown leather alternatives from Toulouse biotech clusters are reshaping price floors for entry-tier accessories, though heritage crocodile and alligator skins sustain ultra-premium tier premiums. Three-tier pricing structure across heritage atelier, controlled diffusion, and accessible entry levels separates wait-listed leather goods from fragrance entry points and seasonal accessories. Cost compression in synthetic biotechnology partnerships is intensifying because EU Green Deal procurement preferences favor deforestation-free alternatives. Affluent millennials exhibit highest price sensitivity in accessible fragrance categories, while ultra-high-net-worth collectors demonstrate near-zero elasticity for bespoke commissioning.
Supply Chain Analysis
Direct-to-maison atelier channels handle ultra-high-net-worth demand through appointment-only showrooms in Paris and Cannes, bypassing third-party margin extraction. Geographic supply concentration centers on France for heritage craftsmanship, Italy for complementary leather finishing, and Madagascar for botanical fragrance extraction. Raw material dependencies rest on Occitanie-region crocodile tanneries, Grasse compounding facilities, and certified precious metal refineries. Single-source vulnerability in premium exotic leather sourcing creates structural exposure to ANSM enforcement actions and deforestation-free regulatory restrictions. Distribution runs through vertically integrated flagship networks with embedded personalization ateliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
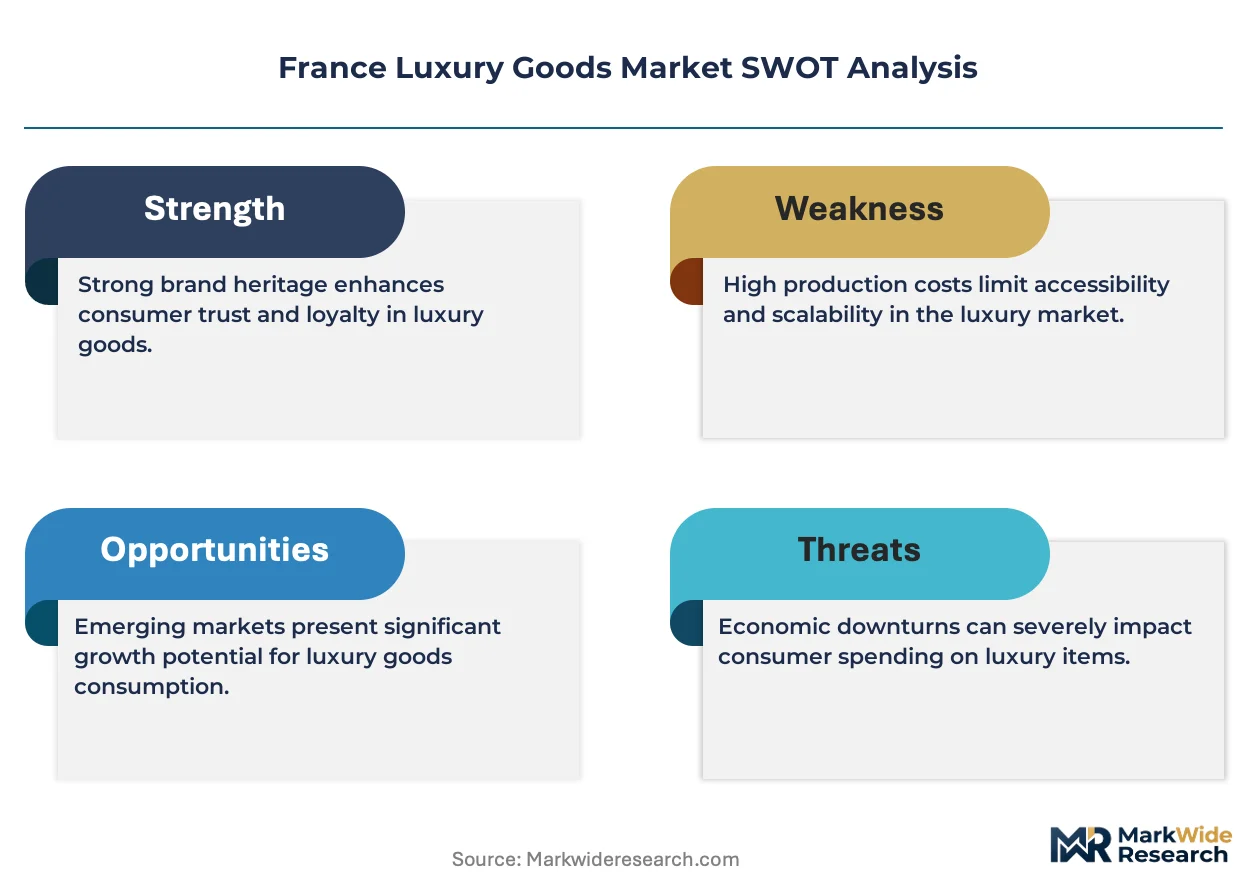
France luxury goods present a margin-expansion story as CSRD-mandated digitization costs filter out sub-scale competitors, concentrating pricing power among capital-rich houses with compliant supply chains.
For Market Incumbents: Deepen backward integration into Occitanie tannery networks and Grasse compounding facilities to secure deforestation-free certification ahead of EU Green Deal enforcement deadlines. Lock in Compagnon du Devoir apprenticeship pipelines through endowed training programs, addressing artisan labor scarcity that constrains capacity expansion. Channel control through appointment-only atelier conversions protects exclusivity against resale platform disintermediation. For New Entrants and Emerging Players: Capture white-space in bio-fabricated leather alternatives qualifying for EU Green Deal procurement preferences, partnering with Toulouse biotech startups for material innovation. Target affluent millennial demand in Lyon and secondary French cities through NFC-enabled e-commerce platforms with blockchain-authenticated provenance. Go-to-market angle emphasizes sustainability-verified transparency as a differentiation wedge against heritage maisons with legacy supply chain opacity. For Investors and Strategic Acquirers: Luxury conglomerates with captive atelier networks are the most active acquirer in this space, consolidating family-owned component suppliers facing CSRD implementation burdens. Long-term viability over the next decade hinges on traceability infrastructure deployment and synthetic biotechnology integration capabilities. Signal to monitor: ANSM enforcement velocity against non-compliant botanical suppliers, which would accelerate margin compression for non-integrated houses.| Strategic Initiative | Industry Significance |
|---|---|
| Atelier Network Digitization | CSRD-compliant ERP systems create procurement moats with LVMH and Kering. |
| Bio-Fabricated Material Partnership | Toulouse laboratory-grown leather qualifies for EU Green Deal preferences. |
| Secondary Market Authentication Platform | Paris-based verification services capture margin pools from unauthorized resellers. |
| Riviera Experiential Retail Expansion | Cannes and Saint-Tropez appointment-only showrooms target yachting clientele. |
| Apprenticeship Pipeline Endowment | Compagnon du Devoir training programs address 23 percent completion decline. |
Research Methodology
Multiple input streams — executive interviews with heritage maison supply chain directors, atelier master craftsmen, and fragrance compounders in Grasse, plus secondary validation through ANSM enforcement records, EU CSRD implementation guidance, and customs trade data — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured perspective from luxury retail operations heads, biotech material startup founders in Toulouse, and Riviera duty-free operators. Secondary sources included DGCCRF market surveillance reports, Compagnon du Devoir apprenticeship statistics, and blockchain traceability platform technical documentation.
Historical volume trajectories were cross-referenced against panel input from industry participants to construct analytical frameworks across the projection horizon. Segmentation dimensions modeled include product type, buyer archetype, distribution channel, and regional cluster. CAGRs were derived through trend extrapolation adjusted for regulatory implementation timelines and material substitution elasticities. Forecast inputs incorporated CSRD compliance cost curves, synthetic biotechnology adoption rates, and affluent millennial cohort spending pattern shifts.
EU Green Deal enforcement velocity, artisan labor completion rates, and bio-fabricated material qualification timelines are the dominant revision risks to base-case assumptions. Forecasts reflect documented assumptions regarding regulatory implementation schedules and substitution technology maturation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Goods
Luxury Mechanical Watches Market
Luxury Goods
Luxury Apparels Market
Luxury Goods
Luxury Watches Market
Luxury Goods
Secondhand Luxury Goods Market
Luxury Goods
Luxury Appraisal Service Market
Luxury Goods
GCC Secondhand Luxury Goods Market
Luxury Goods
GCC Luxury Goods Market
Luxury Goods
Global Gold and Diamond Jewellery Market
Luxury Goods
United Arab Emirates Luxury Goods Market
Luxury Goods
Middle East and Africa Luxury Goods Market
Luxury Goods
Hard Luxury Goods Market
Luxury Goods
Singapore Luxury Goods Market
Luxury Goods
GCC Personal Luxury Goods Market
Luxury Goods
Wooden Watch Market
Luxury Goods
United States Secondhand Luxury Goods Market
Luxury Goods
Brazil Luxury Jewelry Market