
 China Luxury Goods Market | 2026-2036
China Luxury Goods Market Size, Share, and Industry Trends Forecast 2026-2036
China Luxury Goods Market Analysis
Italian leather goods manufacturing is broadening capacity allocations toward China-bound production lines. LVMH leverages vertical integration across tannery-to-boutique supply chains to secure margin control. Richemont anchors watch and jewelry distribution through controlled retail networks in tier-one cities. Hermès differentiates through artisan-led scarcity models that sustain pricing power.
China luxury goods encompass premium apparel, leather accessories, fine jewelry, and high-end timepieces crafted from specified precious metals, exotic skins, and gemological-grade stones, with manufacturing governed by artisanal hand-finishing protocols and authenticated provenance documentation. These products serve status-signaling, wealth preservation, and personal identity functions for affluent consumer segments. Jewelry dominates margin pools due to material intrinsic value and customization premiums, while Accessories captures volume leadership through repeat purchase frequency among Fashion Enthusiasts. Heritage Brands within the Brand Influence dimension command pricing authority, whereas Emerging Designers compete through cultural localization and digital-native engagement.
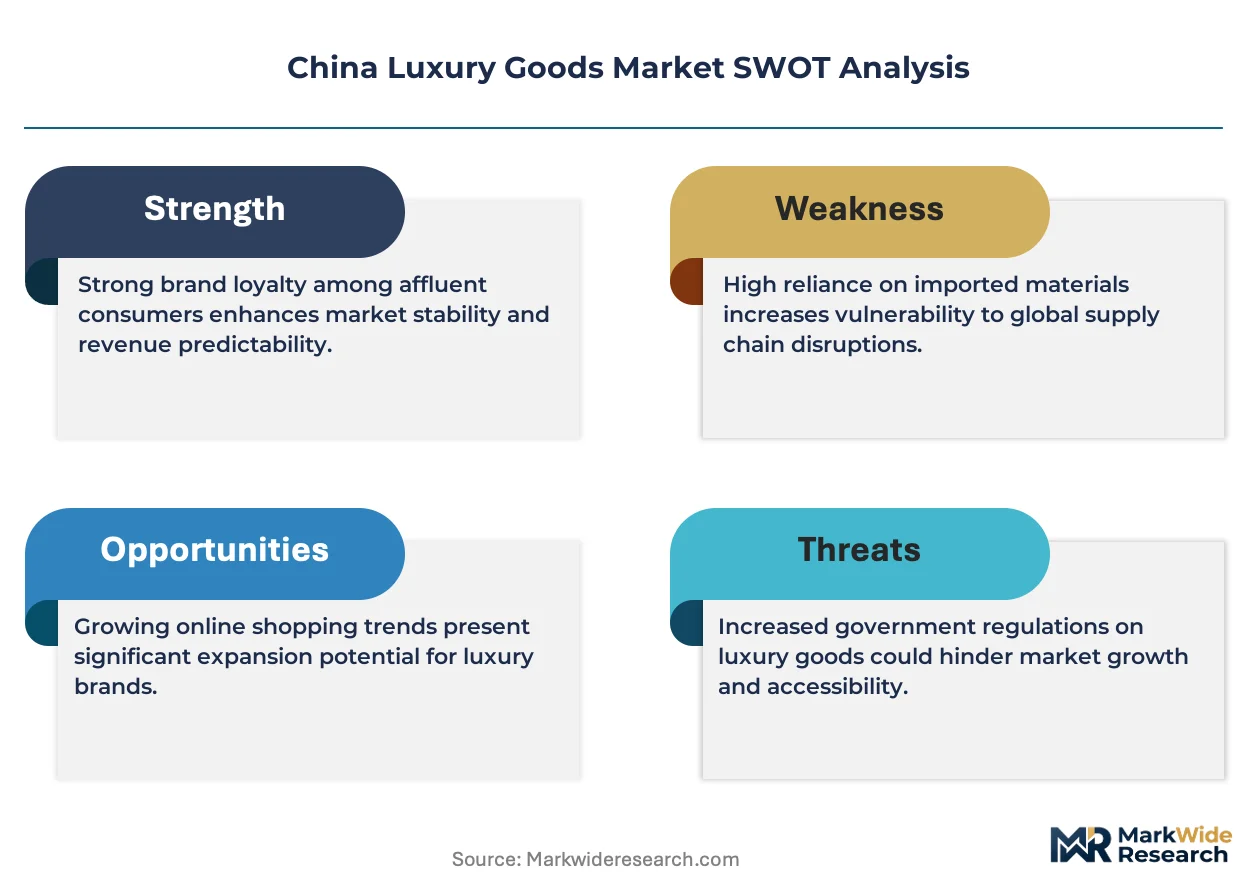
SAMR enforces anti-counterfeiting standards and pricing transparency rules that reshape brand protection investments and channel compliance costs. NMPA cosmetics registration requirements and GB standards for product safety define market access thresholds for beauty-adjacent luxury categories. MIIT data governance frameworks constrain customer data utilization in Online Retail and Luxury E-Commerce channels. Stakeholders must monitor regulatory alignment between cross-border e-commerce protocols and domestic flagship expansion strategies.
Market Dynamics
SAMR anti-counterfeiting enforcement and MIIT data governance frameworks are restructuring how heritage houses authenticate products and manage customer intelligence across flagship and digital channels.
Growth Catalysts
- Hainan duty-free expansion:Offshore shopping zones attract domestic tourists seeking VAT-exempt pricing on leather goods and timepieces, redirecting spending from overseas travel retail.
- GB standards harmonization:Aligned product safety protocols reduce technical barriers for European tanneries and Swiss watchmakers entering domestic distribution.
- Carbon-neutral manufacturing mandates:Dual carbon goals incentivize solar-powered ateliers and recycled precious metal sourcing, appealing to environmentally conscious HNWIs in first-tier cities.
Market Restraints
- Exotic skin import quotas:CITES documentation requirements and customs clearance delays restrict crocodile and python leather availability for artisan workshops.
- Shanghai-Beijing retail concentration:Flagship saturation in these municipalities limits comparable store growth potential for established maisons.
- Blockchain provenance infrastructure gaps:Incomplete distributed ledger adoption across mid-tier suppliers creates authentication vulnerabilities in secondary markets.
Strategic Opportunities
- Chengdu and Hangzhou boutique expansion:Second-tier city wealth accumulation outpaces luxury retail penetration, creating whitespace for controlled retail networks.
- Livestream commerce integration:Douyin and Xiaohongshu native selling formats enable direct-to-consumer engagement bypassing traditional department store concessions.
- Cross-border e-commerce pilot zones:Bonded warehouse models in Guangdong and Zhejiang streamline import logistics for limited-edition drops and pre-order campaigns.
Industry Challenges
- Artisan apprenticeship pipeline:Hand-finishing expertise for leather marquetry and gem-setting requires decade-long training cycles that outpace workforce expansion needs.
- CRM system localization:MIIT data localization mandates force replacement of global customer data platforms with domestic-compliant alternatives, fragmenting unified client profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Luxury Goods Market |
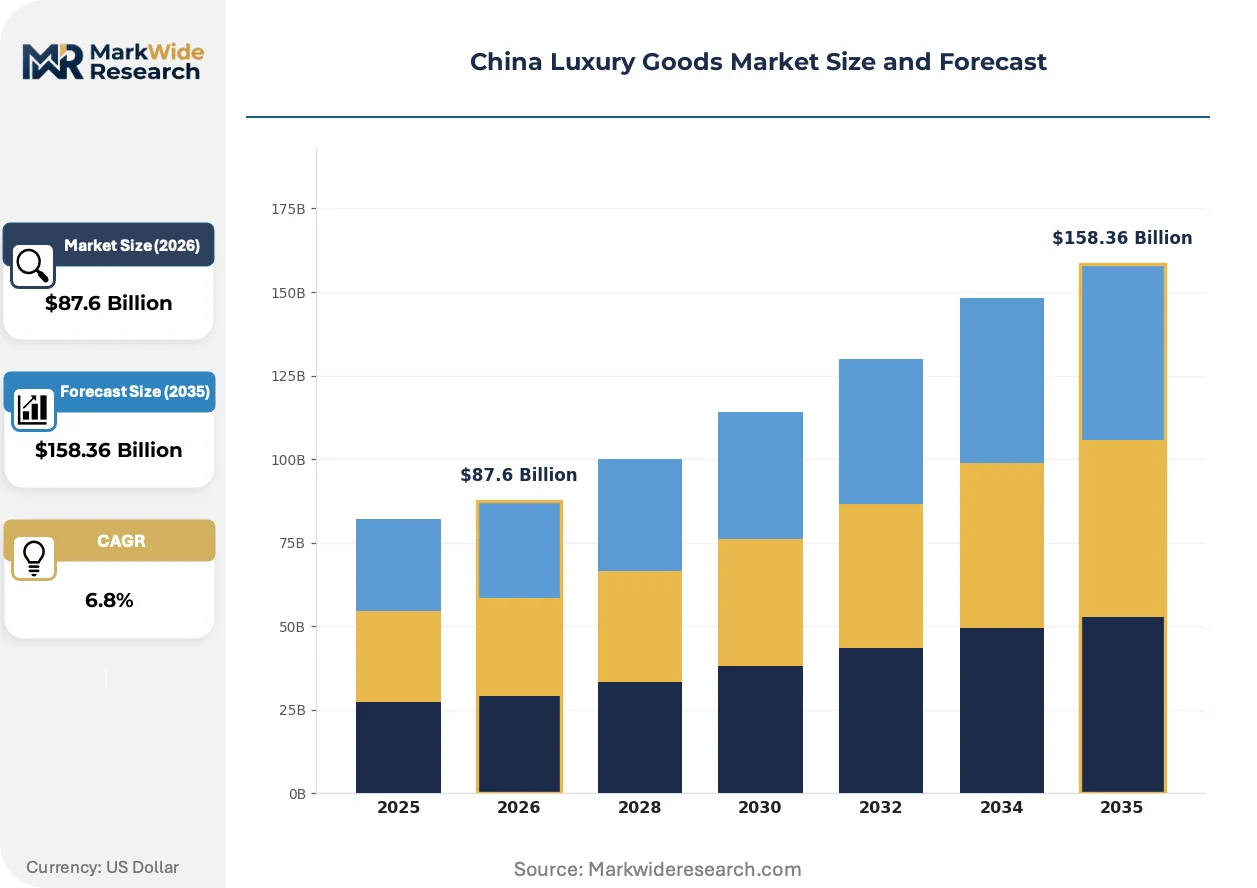
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apparel, Footwear, Accessories, Jewelry Consumer Demographic: Affluent Millennials, High-Net-Worth Individuals, Fashion Enthusiasts, Luxury Travelers Purchase Channel: Online Retail, High-End Department Stores, Flagship Boutiques, Luxury E-Commerce Brand Influence: Heritage Brands, Emerging Designers, Boutique Labels, Celebrity Collaborations |
| Companies Covered | Richemont, Laopu Gold, LVMH, ICICLE, Songmont, Hermès, Chow Tai Fook, Shang Xia, Kering, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Luxury Goods Market Emerging Trajectories
Digital authentication layers and experiential retail formats are displacing conventional transactional boutique models, while regulatory pressure on supply chain transparency accelerates technology adoption across the value chain.
Near-field communication chips embedded in leather goods and watch cases enable smartphone-based provenance verification and ownership transfer documentation. HNW collectors in Shanghai and Shenzhen are adopting these features fastest, demanding tamper-evident digital certificates for resale value protection. This capability is integrating physical craftsmanship with secondary market liquidity, compressing authentication friction for auction houses and consignment platforms.
NMPA cosmetics registration requirements now extend to fragrance and beauty-adjacent luxury categories, mandating animal testing alternatives and ingredient disclosure thresholds. Swiss and French houses are reformulating product lines to meet GB standards for skin sensitization documentation. Fragrance launches face six-to-nine month approval timelines that compress seasonal campaign windows and force pre-registration inventory builds.
Private clienteling through WeChat ecosystem tools is replacing anonymous walk-in traffic as the dominant acquisition model. Sales associates in Beijing flagship locations now conduct seventy percent of client interactions through mini-program appointments and personalized content feeds. This behavioral pivot is most pronounced among Fashion Enthusiasts under age forty, who expect curated drops and early access invitations rather than browse-and-buy experiences.
China Luxury Goods Market Segmentation
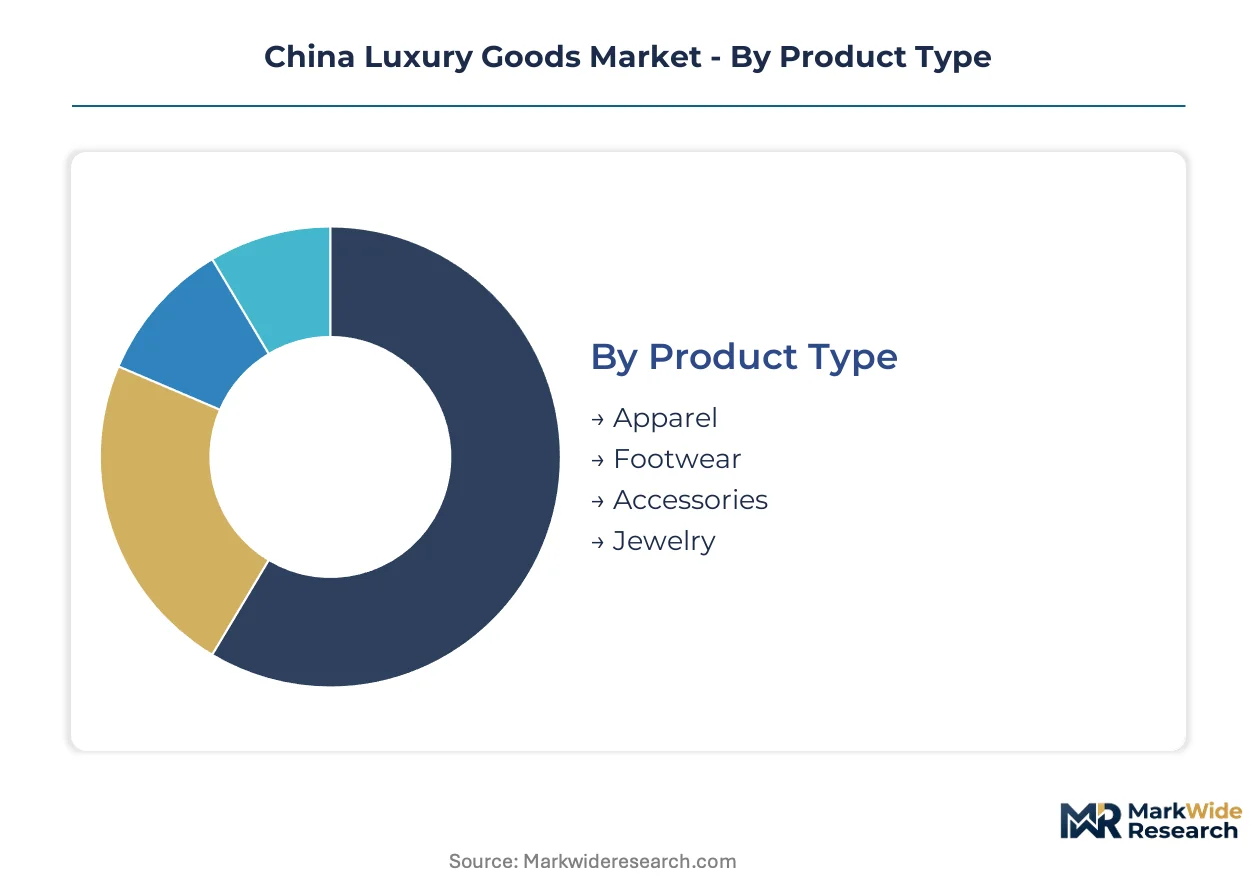
Segmentation in China's luxury market reveals how purchasing power, digital behavior, and brand mythology intersect to determine margin capture. Understanding these divisions exposes where heritage houses defend pricing authority and where insurgent labels find whitespace.
Product Type:
Upgrade cycles vary dramatically by category, with some segments driven by seasonal wardrobe refresh and others by generational wealth transfer events.
- Apparel:Ready-to-wear collections incorporate silk linings and hand-finished seams that command three-to-five-year replacement intervals among established clients. Shanghai and Beijing account for disproportionate volume as climate-appropriate seasonal drops align with regional weather patterns and social calendar density.
- Jewelry:Pieces crafted from gemological-grade stones and specified precious metals function as portable wealth preservation vehicles with minimal depreciation. High-Net-Worth Individuals in Shenzhen and Guangzhou drive demand for bespoke commissions tied to family milestone celebrations and portfolio diversification strategies.
- Footwear:Artisanal construction with leather soles and hand-stitched uppers serves both functional and ceremonial purposes across consumer tiers.
- Accessories:Leather goods with exotic skin components and hardware customization sustain repeat purchase frequency through limited-edition releases.
Accessories sits at the top of the volume ranking, with Jewelry climbing the fastest.
Consumer Demographic:
Customer lifetime value stratifies sharply across age and wealth tiers, with acquisition costs and service models diverging accordingly.
- High-Net-Worth Individuals:Households with investable assets exceeding established thresholds prioritize scarcity-driven allocation systems and private salon access over transactional convenience. First-tier city concentration enables concierge-level fulfillment through dedicated clienteling teams and pre-collection previews.
- Fashion Enthusiasts:Digital-native consumers under forty engage through livestream drops and social commerce integration, demanding rapid product education and peer-validated purchase decisions. Hangzhou and Chengdu show steepest expansion trajectory as wealth accumulation outpaces traditional retail penetration.
- Affluent Millennials:Career-advanced professionals balance entry-luxury accessibility with aspiration for heritage brand entry points.
- Luxury Travelers:Hainan duty-free zone visitors and overseas excursionists redirect spending toward VAT-exempt channels during travel windows.
High-Net-Worth Individuals anchor margin pools, though Fashion Enthusiasts are gaining share fastest through digital channel migration.
Purchase Channel:
Channel economics reflect regulatory pressure on data utilization and the physical-digital integration required for authentication and clienteling.
- Flagship Boutiques:Controlled retail networks in Shanghai and Beijing deliver immersive brand environments with artisan demonstrations and bespoke customization services. SAMR pricing transparency rules and MIIT data governance frameworks elevate compliance investments while protecting margin integrity through direct distribution.
- Luxury E-Commerce:Cross-border pilot zones in Guangdong and Zhejiang enable bonded warehouse fulfillment for limited-edition inventory with streamlined customs clearance. NMPA registration requirements for beauty-adjacent categories extend approval timelines, compressing campaign windows and forcing pre-positioned stock builds.
- Online Retail:Domestic platform integration faces fragmentation from data localization mandates requiring replacement of global CRM systems.
- High-End Department Stores:Concession models in historic retail addresses sustain foot traffic through tourism and gift-purchase occasions.
Flagship Boutiques maintain the highest transaction values, while Luxury E-Commerce shows the steepest expansion trajectory as logistics infrastructure matures.
Brand Influence:
Brand architecture determines pricing authority and customer acquisition economics across the maturity spectrum.
- Heritage Brands:Maisons with century-plus histories leverage archival narratives and controlled scarcity to sustain premium positioning without promotional discounting. Artisan apprenticeship pipelines and vertical tannery-to-boutique supply chains defend margin control against input cost volatility.
- Emerging Designers:Culturally localized creators deploy digital-native engagement through Douyin and Xiaohongshu to bypass traditional gatekeeper relationships. Chengdu and Hangzhou present whitespace for controlled retail expansion where heritage saturation remains limited.
- Boutique Labels:Niche positioning through material experimentation and limited production runs targets collector segments seeking differentiation from mass-luxury recognition.
- Celebrity Collaborations:Time-bound capsule releases generate event-driven demand spikes with compressed inventory risk and accelerated sell-through cycles.
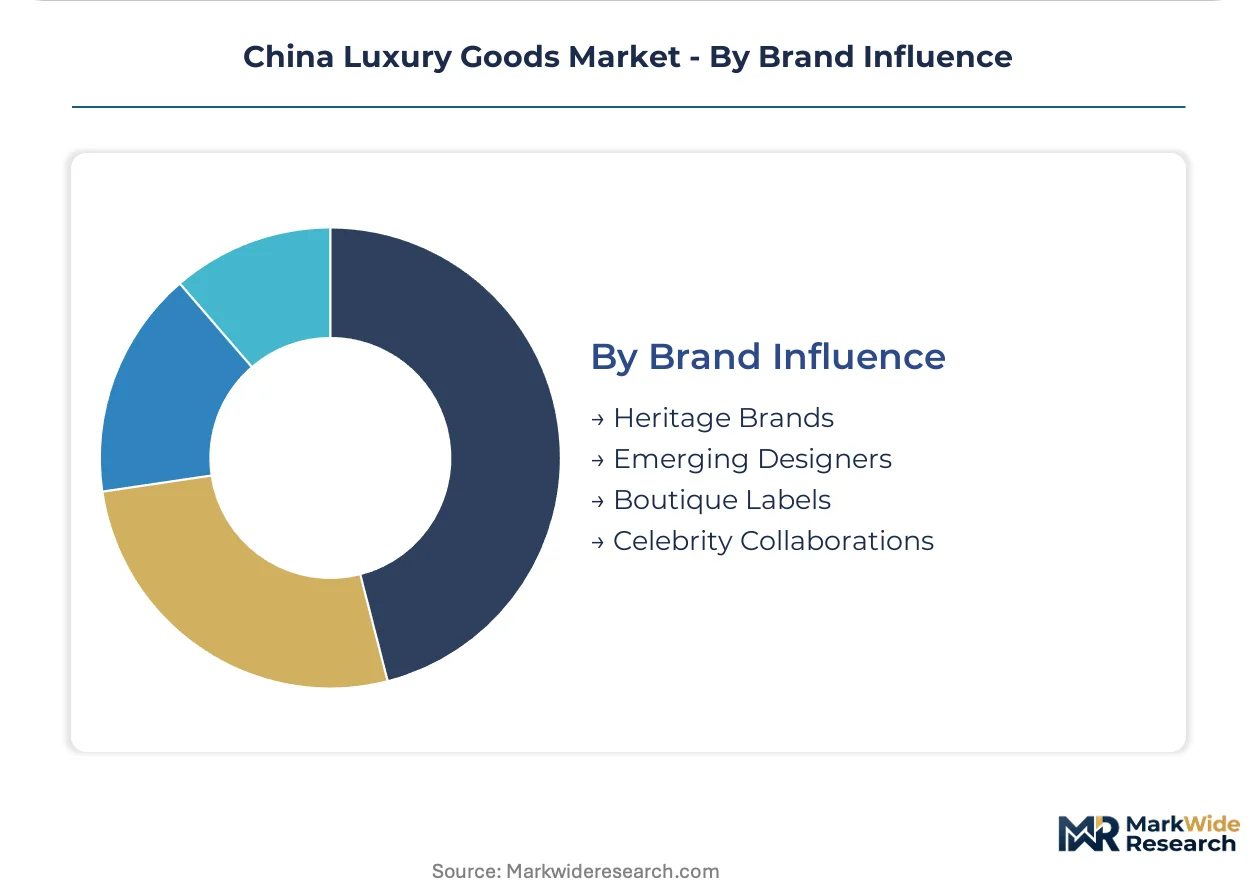
Heritage Brands dominate pricing authority, with Emerging Designers expanding most quickly through social commerce integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting artisan capacity toward jurisdictions with streamlined customs protocols and harmonized product safety standards. European tanneries and Swiss watchmakers are reallocating finishing operations to bonded zones that expedite CITES documentation for exotic materials.
France
Heritage maisons in Paris and Lyon drive demand for gemological-grade stones and specified precious metals in haute joaillerie. ANSM fragrance registration requirements align with NMPA cosmetics protocols to streamline cross-border beauty launches. Champagne-Ardenne leatherworking clusters supply crocodile and python skins to artisan workshops facing CITES quota constraints.
Switzerland
Swiss watchmakers anchor fine timepiece production through vertically integrated ateliers in Geneva and Le Locle. Swissmedic medical device standards overlap with luxury wearable compliance frameworks. Jura Arc manufacturers are expanding solar-powered facilities to meet carbon-neutral mandates from Chinese import partners.
Italy
Tuscan tanneries in Santa Croce sull'Arno concentrate exotic skin finishing for China-bound leather goods. REACH chemical safety protocols and GB standards harmonization reduce technical barriers for domestic distribution. Milan flagship density supports experiential retail formats that bypass department store concession models.
United States
New York and Los Angeles HNWIs sustain demand for limited-edition drops and bespoke commissions. FDA cosmetic labeling requirements create compliance friction for fragrance houses entering cross-border e-commerce channels. Miami retail clusters serve Latin American clientele seeking VAT-advantaged purchasing structures.
Japan
Tokyo and Osaka collectors drive adoption of NFC-enabled provenance verification in secondary markets. METI data governance frameworks constrain CRM system architectures for brands operating dual domestic-China clienteling platforms. Kansai manufacturing clusters supply precision components for mechanical watch movements.
China Luxury Goods Market Vendor Landscape
French and Italian producers anchor the heritage tier; Swiss specialists hold precision manufacturing dominance. The vendor base stratifies across century-plus maisons with captive supply chains and digital-native insurgents leveraging social commerce bypass. Three archetypes prevail: vertically integrated heritage houses, culturally localized emerging designers, and scale-driven accessible-luxury platforms. Competitive moves concentrate on controlled retail network expansion and artisan apprenticeship pipeline development.
Within the heritage tier, LVMH and Richemont exemplify vertical integration strategies spanning tannery-to-boutique operations. Hermès occupies a position defined by artisan-led scarcity models and decade-long training pipelines for leather marquetry expertise. Among China-origin specialists, Laopu Gold and Chow Tai Fook represent jewelry-focused archetypes with domestic distribution density in first-tier cities.
| Leading Market Players |
|---|
| Richemont |
| Laopu Gold |
| LVMH |
| ICICLE |
| Songmont |
| Hermès |
| Chow Tai Fook |
| Shang Xia |
| Kering |
| Others |
Supply Flow & Price Mechanics
NFC chip embedding and blockchain provenance verification are compressing authentication costs while concentrating premium pricing power among houses with captive digital infrastructure. SAMR anti-counterfeiting mandates and MIIT data governance frameworks simultaneously elevate compliance investments and fragment customer intelligence platforms, reshaping how heritage brands defend margin integrity across flagship and digital channels.
Pricing Analysis
Direct-to-consumer flagships in Shanghai and Beijing capture the highest channel margins by eliminating department store concession fees and controlling end-to-end clienteling. Pricing stratifies across heritage scarcity tiers, emerging designer accessibility, and mass-luxury entry points, with brand mythology and artisan provenance driving differentiation. Cost compression in accessible-luxury tiers intensifies as digital-native insurgents bypass traditional gatekeeper relationships. Fashion Enthusiasts under forty show highest price elasticity, while High-Net-Worth Individuals prioritize allocation systems and private salon access over transactional discounts.
Supply Chain Analysis
Air freight and bonded warehouse logistics from European tanneries and Swiss ateliers to Hainan duty-free zones and Guangdong pilot zones dominate inbound cost structures. Manufacturing concentrates in France, Italy, and Switzerland for heritage leather goods, fine jewelry, and mechanical timepieces. Exotic skin finishing draws from Tuscan clusters, gemological-grade stones from Antwerp cutters, and precision movements from Jura Arc workshops. CITES documentation delays and customs clearance chokepoints create single-source vulnerability for crocodile and python leather. Distribution runs through controlled flagship networks in tier-one cities, with cross-border e-commerce pilot zones gaining share for limited-edition inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China luxury goods function as a geographic-arbitrage play where Hainan duty-free pricing differentials and streamlined bonded-zone logistics redirect spending from overseas travel retail. SAMR enforcement intensity versus European regulatory alignment creates compliance cost asymmetries that favor vertically integrated houses with captive supply chains.
For Market Incumbents: To counter digital-native insurgents bypassing traditional department store concessions, deepen artisan apprenticeship pipelines in leather marquetry and gem-setting to defend scarcity-driven pricing power. Channel control through WeChat ecosystem private clienteling replaces anonymous walk-in traffic as the dominant acquisition model, requiring CRM system localization to meet MIIT data governance mandates. For New Entrants and Emerging Players: Launch via Douyin and Xiaohongshu livestream commerce to access Fashion Enthusiasts in Chengdu and Hangzhou where heritage flagship saturation remains limited. Second-tier city wealth accumulation outpaces controlled retail penetration, creating whitespace for culturally localized positioning and experiential boutique formats that bypass traditional gatekeeper relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among emerging designers with proven social commerce traction and incomplete retail footprint expansion. Long-term viability hinges on artisan capacity scalability and regulatory compliance infrastructure across the analysis window. Watch NMPA cosmetics registration timeline compression and MIIT data localization mandate enforcement intensity as inflection indicators for margin structure shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Artisan Apprenticeship Pipeline Expansion | Decade-long training cycles for leather marquetry defend scarcity positioning against input cost volatility. |
| WeChat Ecosystem Private Clienteling | Mini-program appointments and personalized content feeds capture seventy percent of Beijing flagship interactions. |
| Hainan Duty-Free Zone Flagship Expansion | VAT-exempt pricing redirects domestic tourist spending from overseas travel retail channels. |
| NFC-Enabled Provenance Verification | Smartphone-based authentication integrates physical craftsmanship with secondary market liquidity protection. |
| Cross-Border E-Commerce Pilot Zone Integration | Bonded warehouse models in Guangdong streamline import logistics for limited-edition drops and pre-order campaigns. |
Methodological Framework
Multiple input streams — executive interviews with heritage house brand directors and emerging designer founders, secondary validation through SAMR enforcement records and MIIT policy circulars, and customs trade data reconciliation — were synthesized to construct market size and growth projections. Primary fieldwork encompassed discussions with Shanghai flagship sales associates, Hangzhou livestream commerce operators, and Shenzhen jewelry atelier managers alongside secondary sources including NMPA registration databases, GB standards documentation, and sector-specific trade publications. Bottom-up SKU-level demand modeling and top-down macroeconomic triangulation were cross-referenced to anchor volume and value estimates.
Data-stream reconciliation across product type, consumer demographic, purchase channel, and brand influence dimensions informed the analytical framework over the projection horizon. CAGRs were derived from trend extrapolation of HNW household formation rates, digital channel penetration curves, and regulatory compliance cost trajectories. Segmentation modeling incorporated tier-one versus second-tier city wealth accumulation differentials, heritage versus emerging designer pricing authority gaps, and flagship versus e-commerce channel economics.
Forecast precision tightens around the base case; tail outcomes carry wider variance under exotic skin import quota tightening or blockchain provenance infrastructure adoption delays. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Goods
Personal Luxury Goods Market
Luxury Goods
Accessible Luxury Goods Market
Luxury Goods
Luxury Apparels Market
Luxury Goods
Germany Luxury Goods Market
Luxury Goods
Europe Secondhand Luxury Goods Market
Luxury Goods
Brazil Luxury Jewelry Market
Luxury Goods
Brazil Luxury Goods Market
Luxury Goods
Spain Luxury Jewelry Market
Luxury Goods
Global Gold Jewelry Market
Luxury Goods
Luxury Goods Market
Luxury Goods
Designer Bags and Luxury Handbags Market
Luxury Goods
Luxury Mechanical Watches Market
Luxury Goods
United States Secondhand Luxury Goods Market
Luxury Goods
Luxury Resale Platform Market
Luxury Goods
Luxury Pen Market
Luxury Goods
Used Luxury Bags Trading Service Market