
 Spain Luxury Jewelry Market | 2026-2036
Spain Luxury Jewelry Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Luxury Jewelry Market Insights
Buyer concentration among affluent millennials and established collectors is realigning purchasing patterns across Spain's luxury jewelry landscape. Richemont anchors its position through Piaget's heritage watch-jewelry fusion and Cartier's iconic panther motifs, while LVMH leverages Tiffany & Co.'s expanded Madrid flagship to compete for transatlantic clientele. UNOde50 differentiates through its handcrafted silver collections manufactured in Madrid, and Aristocrazy specializes in accessible luxury positioning that extends its retail footprint beyond Barcelona into secondary Spanish cities.
Spain luxury jewelry encompasses high-value ornamental pieces crafted from precious metals and gemstones, typically employing lost-wax casting, hand-engraving, and pavé setting techniques that demand artisan expertise exceeding fifty hours per piece. These items serve as wealth preservation instruments, ceremonial markers, and status signals within Iberian and international elite circles. Gold necklaces and gemstone rings command the deepest margin pools among product types, while platinum materials attract the fastest-growing collector segment seeking scarcity-driven value appreciation. Online stores now capture accelerating transaction volume among younger affluent buyers, though luxury boutiques sustain higher average ticket values through personalized atelier consultations.
Spain's national markets regulator enforces EU anti-money laundering frameworks requiring detailed provenance documentation for jewelry transactions exceeding specified thresholds, while the Spanish Customs Service coordinates with EU REACH standards governing nickel release and cadmium content in metal alloys. The national financial intelligence unit scrutinizes cash-intensive purchases to prevent illicit capital flows through collectible assets. Stakeholders must monitor evolving EU Digital Product Passport requirements that will mandate blockchain-traceable supply chain disclosure across gemstone and precious metal sourcing.
Market Dynamics
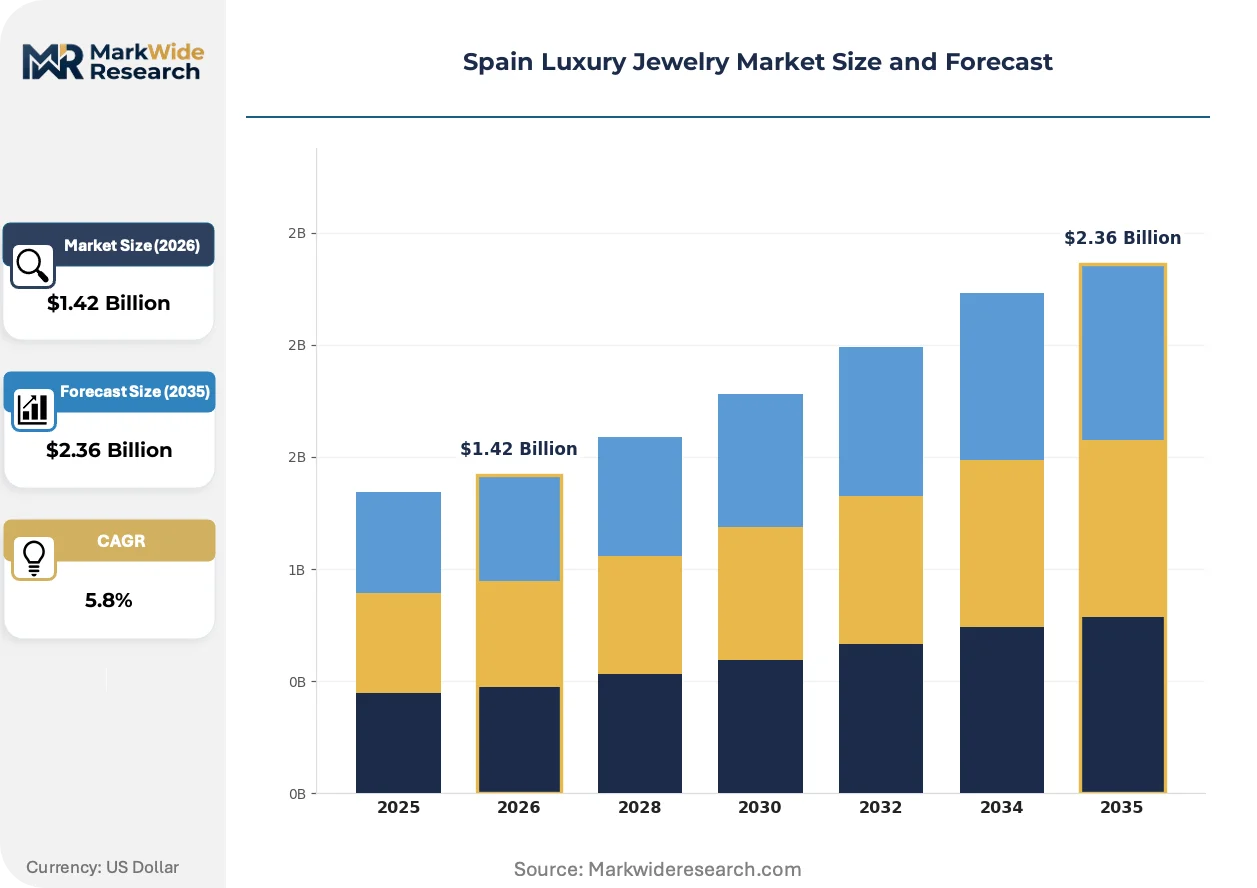
Spain's luxury jewelry sector confronts a structural pivot where EU Digital Product Passport mandates are forcing blockchain-traceable supply chain disclosure across gemstone sourcing, compressing legacy documentation timelines while elevating compliance costs for artisan ateliers.
Growth Catalysts
- EU REACH standards:Nickel release and cadmium content limits for metal alloys are accelerating investment in hypoallergenic platinum and palladium alloys among Madrid-based manufacturers.
- Heritage craftsmanship:Lost-wax casting and hand-engraving techniques exceeding fifty hours per piece command premium positioning among affluent millennial collectors seeking scarcity value.
- Andalusian and Balearic resort corridors:Seasonal tourist expenditure in coastal cities concentrates discretionary spending during peak months, sustaining inventory turnover for seasonal collections.
Market Restraints
- Input cost volatility:Rhodium plating and ethically sourced sapphire prices fluctuate with South African mining output disruptions, compressing margin pools on entry-luxury pieces.
- Supply concentration risk:Colombian emerald and Burmese ruby cutters dominate fine gemstone procurement, creating single-source dependency for heritage Spanish houses.
- Technical limitation:Artisan expertise thresholds exceeding fifty hours per piece constrain production scalability for handcrafted silver collections.
Strategic Opportunities
- Underpenetrated secondary cities:Valencia and Seville retail corridors show whitespace for accessible luxury positioning beyond Madrid and Barcelona saturation.
- Regulatory tailwind:Spain's national financial intelligence unit scrutiny of cash-intensive purchases creates competitive advantage for houses with pre-established digital transaction infrastructure.
- Online channel innovation:Virtual atelier consultations and augmented reality try-on tools are capturing accelerating transaction volume among Gen-Z affluent buyers.
Industry Challenges
- Master artisan scarcity:Pavé setting and micro-engraving specializations require decade-long training pipelines that Madrid manufacturing clusters struggle to replenish.
- Compliance timeline compression:EU Digital Product Passport blockchain integration demands capex outlays for legacy inventory management system overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Luxury Jewelry Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Necklaces, Bracelets, Earrings, Rings Material: Gold, Platinum, Silver, Gemstones Customer Type: Affluent Individuals, Couples, Gift Givers, Collectors Distribution Channel: Online Stores, Luxury Boutiques, Department Stores, Auction Houses |
| Companies Covered | Richemont (Piaget), Puig, LVMH (Tiffany & Co.), Singularu, Aristocrazy, Richemont (Cartier), Chopard International, UNOde50, Richemont (Van Cleef & Arpels), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Luxury Jewelry Market Trends and Innovations
Blockchain-traceable provenance systems are compressing documentation workflows while elevating transparency expectations across Spain's heritage atelier network. Three intersecting developments are reconfiguring competitive positioning.
Laser inscription and spectroscopic gemstone fingerprinting is unifying authentication and resale value preservation into single-platform solutions. Affluent collectors in Barcelona and Madrid are adopting these verification tools at accelerating rates. The technology is unifying primary purchase confidence with secondary market liquidity, compressing traditional appraisal intermediation.
Spain's implementation of EU anti-money laundering directives through its national financial intelligence unit is tightening cash transaction thresholds for high-value jewelry purchases. Retailers must now document provenance chains for transactions exceeding specified limits. Madrid flagship locations are responding by migrating clientele toward digital payment rails and structured financing instruments.
Collector procurement patterns are fragmenting across channel types, with younger affluent buyers initiating discovery online before completing high-value transactions through personalized atelier consultations. Boutique channels sustain superior average ticket values through experiential service design. This behavioral bifurcation is most visible among Gen-Z purchasers in Barcelona's Eixample district and Madrid's Salamanca quarter.
Spain Luxury Jewelry Market Segmentation
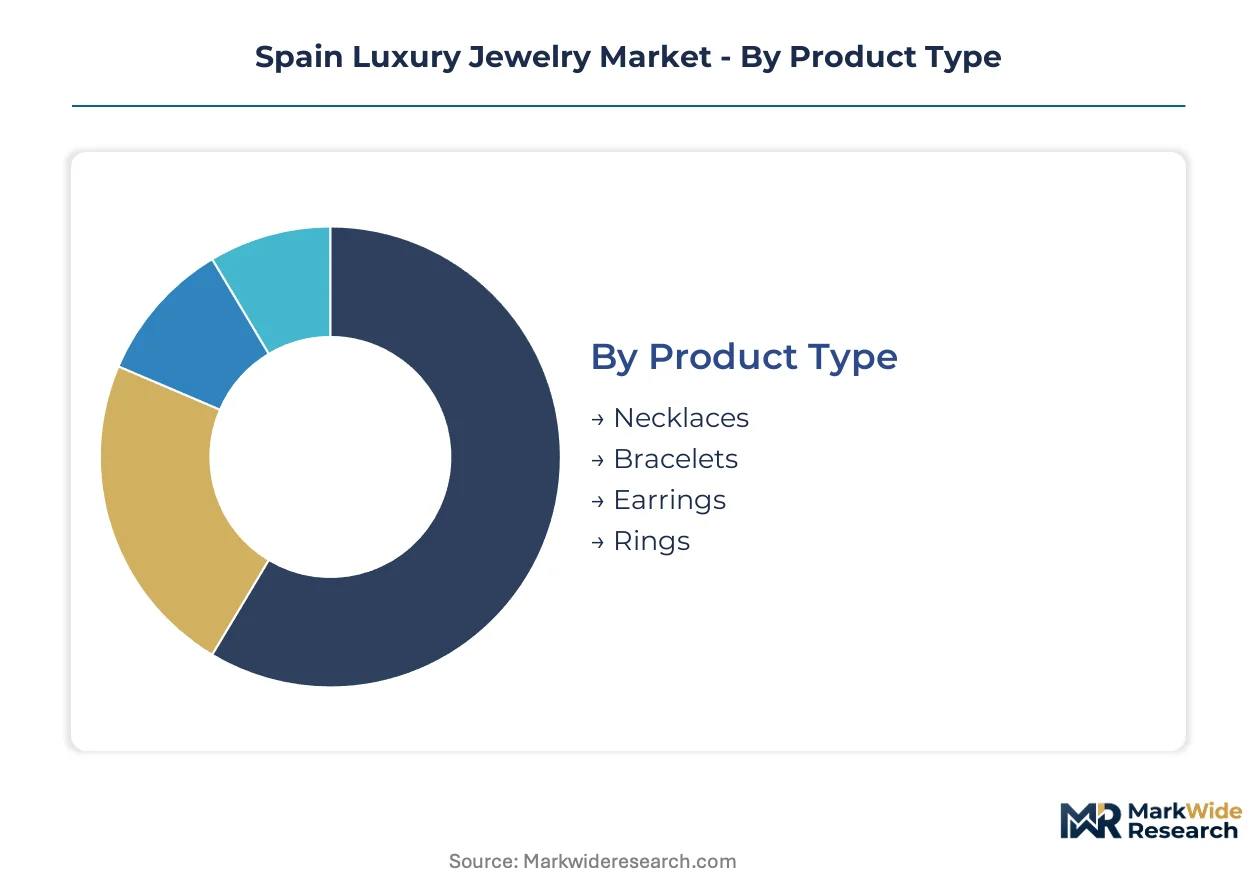
Segmentation in Spain's luxury jewelry market reveals how distinct buyer motivations and procurement channels create divergent margin structures. Artisan ateliers and heritage houses calibrate inventory depth and certification protocols differently across each dimension.
Product Type:
Certification burden varies sharply by product complexity, with gemstone-intensive pieces requiring spectroscopic fingerprinting and chain-of-custody documentation under Spain's national financial intelligence unit protocols.
- Necklaces:Gold necklaces employing lost-wax casting and pavé setting command the deepest margin pools, with affluent millennial collectors in Madrid's Salamanca quarter driving demand for statement pieces exceeding fifty hours of artisan labor.
- Rings:Gemstone rings, particularly those featuring ethically sourced sapphires and Colombian emeralds, concentrate discretionary spending among couples and collectors seeking scarcity-driven value appreciation in Barcelona's Eixample district.
- Bracelets:Handcrafted silver collections from Madrid-based manufacturers appeal to accessible luxury positioning.
- Earrings:Platinum and palladium alloy designs meet EU REACH nickel release standards for hypoallergenic compliance.
Leading the category by volume: Necklaces. Growing fastest: Rings.
Material:
Cost tier stratification separates investment-grade precious metals from accessible silver collections, with platinum attracting the steepest expansion trajectory among scarcity-seeking collectors.
- Gold:Yellow and rose gold alloys dominate ceremonial and wealth preservation applications, with Madrid and Barcelona flagship locations sustaining higher average ticket values through personalized atelier consultations.
- Gemstones:Colombian emerald and Burmese ruby procurement creates single-source dependency for heritage Spanish houses, compressing margin pools when South African mining disruptions affect sapphire and rhodium pricing.
- Platinum:Hypoallergenic alloys accelerate investment among collectors seeking scarcity-driven appreciation.
- Silver:Handcrafted collections manufactured in Madrid serve accessible luxury positioning in secondary cities.
Highest revenue concentration: Gold. Expanding most quickly: Platinum.
Customer Type:
Procurement patterns fragment across generational cohorts, with Gen-Z affluent buyers initiating discovery online before completing high-value transactions through experiential boutique channels.
- Affluent Individuals:Millennial and Gen-Z collectors in coastal resort cities of Andalusia and the Balearic Islands accelerate demand for heritage craftsmanship and ethically sourced gemstones during peak seasonal months.
- Collectors:Established collectors prioritize blockchain-traceable provenance systems and laser inscription authentication tools that unify primary purchase confidence with secondary market liquidity.
- Couples:Ceremonial purchasing concentrates in Madrid and Barcelona retail corridors.
- Gift Givers:Seasonal expenditure patterns align with resort tourism cycles in coastal cities.
Deepest engagement by transaction value: Collectors. Fastest digital migration: Affluent Individuals.
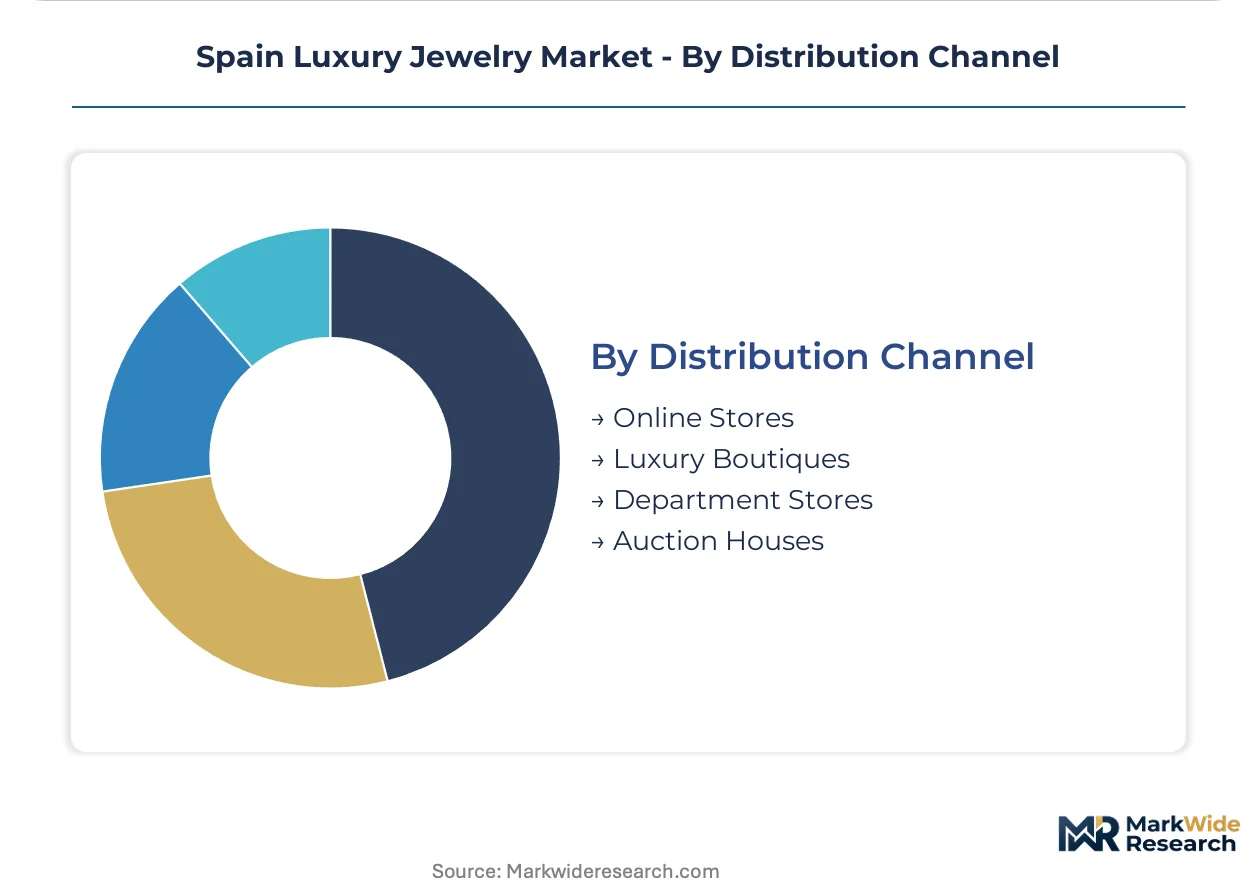
Distribution Channel:
Channel selection determines compliance infrastructure requirements, with auction houses and luxury boutiques facing the most intensive scrutiny from Spain's national financial intelligence unit for cash-intensive purchase documentation.
- Luxury Boutiques:Flagship locations in Madrid and Barcelona sustain superior average ticket values through experiential service design, with personalized atelier consultations capturing high-value transactions from collectors seeking artisan expertise.
- Online Stores:Virtual atelier consultations and augmented reality try-on tools capture accelerating transaction volume among Gen-Z affluent buyers, though average ticket values trail physical channels.
- Auction Houses:Secondary market liquidity depends on blockchain-traceable provenance documentation.
- Department Stores:Accessible luxury positioning extends retail footprint into Valencia and Seville corridors.
Highest average ticket: Luxury Boutiques. Steepest volume expansion: Online Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's luxury jewelry demand concentrates in Madrid and Barcelona, where affluent millennial collectors and seasonal tourist flows from Andalusia and the Balearic Islands drive transaction volume. The country's national financial intelligence unit enforces EU anti-money laundering directives that tighten provenance documentation requirements for high-value purchases.
Madrid
Madrid anchors Spain's luxury jewelry purchasing power through its Salamanca quarter flagship locations. The national financial intelligence unit scrutinizes cash-intensive transactions exceeding specified thresholds, forcing retailers toward digital payment infrastructure. Heritage ateliers in the capital specialize in lost-wax casting and pavé setting techniques exceeding fifty hours per piece.
Catalonia
Barcelona's Eixample district captures significant collector demand for gemstone rings featuring ethically sourced sapphires and Colombian emeralds. Spain's implementation of EU REACH standards governs nickel release and cadmium content in metal alloys sold through Catalan retail corridors. Local manufacturers accelerate investment in hypoallergenic platinum and palladium alloys to meet compliance requirements.
Andalusia
Coastal resort cities in Andalusia concentrate seasonal tourist expenditure during peak months, sustaining inventory turnover for accessible luxury collections. The region's retail channels face intensified documentation requirements under Spain's anti-money laundering frameworks for transactions involving international visitors. Seville shows whitespace for retail expansion beyond saturated Madrid and Barcelona markets.
Valencia
Valencia's retail corridors represent underpenetrated territory for accessible luxury positioning extending from Barcelona's established footprint. Spain's national markets regulator enforces EU Digital Product Passport requirements that will mandate blockchain-traceable supply chain disclosure across gemstone sourcing. Department store channels in the city capture middle-tier demand for handcrafted silver collections.
Basque Country
San Sebastián and Bilbao sustain niche demand from established collectors prioritizing provenance documentation and authentication tools. The region's affluent demographic aligns with EU-wide transparency expectations for ethically sourced gemstones. Local boutiques serve ceremonial purchasing concentrated among couples seeking heritage craftsmanship.
Spain Luxury Jewelry Market Competitive Landscape
Swiss and French luxury conglomerates anchor the premium tier; Spanish artisan specialists hold differentiated positions in accessible luxury and handcrafted silver segments. The market structure reflects consolidation among heritage houses with century-old atelier networks alongside fragmentation among regional craft producers. Three archetypes dominate: vertically integrated Swiss-French conglomerates with multi-brand portfolios, Madrid-based artisan manufacturers emphasizing domestic craftsmanship, and digitally native direct-to-consumer brands capturing Gen-Z discovery patterns. Competitive moves center on blockchain-traceable provenance system investments and virtual atelier consultation capabilities.
Within the conglomerate tier, Richemont occupies a position exemplifying heritage watch-jewelry fusion through Piaget and iconic panther motifs through Cartier, while LVMH anchors transatlantic clientele competition through Tiffany & Co.'s expanded Madrid flagship. Among Spanish-based specialists, UNOde50 represents handcrafted silver collections manufactured in Madrid, and Aristocrazy exemplifies accessible luxury positioning extending retail footprint into secondary cities beyond Barcelona saturation.
| Leading Market Players |
|---|
| Richemont (Piaget) |
| Puig |
| LVMH (Tiffany & Co.) |
| Singularu |
| Aristocrazy |
| Richemont (Cartier) |
| Chopard International |
| UNOde50 |
| Richemont (Van Cleef & Arpels) |
| Others |
Pricing and Supply Chain Analysis
Captive sourcing of Colombian emeralds and Burmese rubies by heritage Spanish houses anchors both supply security and premium pricing power, yet single-origin dependency compresses margins when South African mining disruptions spike rhodium plating costs. This vertical integration into gemstone procurement insulates Madrid-based ateliers from spot-market volatility but concentrates risk exposure in geopolitically sensitive extraction corridors.
Pricing Analysis
Volume concentrates in accessible luxury silver collections while margin pools deepen in artisan gold necklaces and platinum pieces exceeding fifty hours of hand-engraving labor. Pricing stratifies across heritage craftsmanship tiers, with EU Digital Product Passport compliance costs and spectroscopic fingerprinting certification driving differentiation between entry-luxury and collector-grade segments. Cost compression in silver collections intensifies because Madrid manufacturers face artisan scarcity and rising precious metal alloy inputs. Younger affluent buyers in Barcelona's Eixample district show highest price sensitivity, while established collectors in Madrid's Salamanca quarter prioritize provenance documentation over absolute cost.
Supply Chain Analysis
Spain's national financial intelligence unit documentation mandates for high-value transactions are reshaping sourcing toward blockchain-traceable suppliers with pre-established digital infrastructure. Gemstone supply concentrates in Colombia, Myanmar, and South Africa, while precious metal refining feeds from Swiss and German processors. Raw material dependencies span ethically sourced sapphires, rhodium plating solutions, and hypoallergenic palladium alloys. Single-source vulnerability in Colombian emerald cutting creates procurement risk for heritage houses dependent on specific artisan networks. Distribution runs through Madrid and Barcelona flagship boutiques for high-value transactions, with online channels capturing discovery-phase volume among Gen-Z buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's luxury jewelry sector presents a consolidation play as EU Digital Product Passport mandates and master artisan scarcity force undercapitalized regional producers toward exit or acquisition.
For Market Incumbents: To counter blockchain-traceable provenance requirements compressing legacy documentation timelines, heritage houses should deepen backward integration into gemstone sourcing through direct cutter partnerships in Bogotá and Yangon, while investing in captive Madrid-based training pipelines for pavé setting and micro-engraving specializations that replenish decade-long artisan expertise gaps. For New Entrants and Emerging Players: Virtual atelier consultation platforms offer the lowest-friction entry vector for capturing Gen-Z affluent buyer discovery patterns before competitors deploy augmented reality try-on tools. White-space targets include Seville and Valencia retail corridors for accessible luxury positioning, with direct-to-consumer digital channels bypassing saturated Madrid and Barcelona boutique saturation. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by Swiss-French conglomerates seeking provenance-authenticated atelier networks. Long-term viability hinges on pre-established digital transaction infrastructure that satisfies Spain's national financial intelligence unit scrutiny. The signal to watch is EU Digital Product Passport implementation timelines accelerating compliance cost burdens for artisan producers lacking capex reserves.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Provenance Integration | EU Digital Product Passport mandates compress documentation timelines for Madrid heritage ateliers. |
| Artisan Training Pipeline Investment | Decade-long pavé setting specialization gaps threaten production scalability for handcrafted collections. |
| Virtual Atelier Platform Launch | Augmented reality try-on tools capture accelerating Gen-Z transaction volume ahead of competitors. |
| Secondary City Retail Expansion | Valencia and Seville corridors show whitespace beyond saturated Madrid and Barcelona markets. |
| Hypoallergenic Alloy Development | EU REACH nickel release standards accelerate platinum and palladium investment among Catalan manufacturers. |
Research Methodology
Multi-period observation of artisan labor-hour benchmarks, gemstone procurement patterns, and regulatory compliance cost trajectories anchored the trend analysis, supplemented by interviews with Madrid atelier owners, Barcelona retail corridor managers, Colombian gemstone cutters, EU regulatory affairs specialists, and Spanish financial intelligence unit compliance officers. Secondary validation drew from EU REACH implementation filings, Spain's national anti-money laundering directive transposition documents, customs records of precious metal imports, and heritage house annual disclosures. Bottom-up segment sizing triangulated against top-down macroeconomic consumption indicators for luxury goods.
Segment-weighting across product type, material tier, customer archetype, and distribution channel dimensions structured the analytical framework across the projection horizon. CAGRs derived from regression analysis of historical purchasing power trends, tourist expenditure cyclicality in Andalusian and Balearic resort corridors, and generational wealth transfer patterns among affluent millennial and Gen-Z collectors. Industry-specific forecast inputs incorporated EU Digital Product Passport implementation schedules and master artisan pipeline replenishment rates.
The model holds under steady EU regulatory implementation timelines and stable South African mining output; deviation in Colombian emerald supply disruptions or accelerated compliance deadlines would shift trajectory. Forecasts reflect documented assumptions regarding artisan labor availability and blockchain infrastructure adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Goods
Pre-Owned Luxury Watches Market
Luxury Goods
Brazil Luxury Goods Market
Luxury Goods
China Luxury Market
Luxury Goods
Global Gold and Diamond Jewellery Market
Luxury Goods
Luxury Resale Platform Market
Luxury Goods
Luxury Appraisal Service Market
Luxury Goods
Singapore Luxury Goods Market
Luxury Goods
Mexico Luxury Goods Market
Luxury Goods
Russia Luxury Goods Market
Luxury Goods
Used Luxury Bags Trading Service Market
Luxury Goods
United Kingdom Luxury Goods Market
Luxury Goods
Malaysia Luxury Goods Market
Luxury Goods
United States Luxury Goods Market
Luxury Goods
Hard Luxury Goods Market
Luxury Goods
Personal Luxury Goods Market
Luxury Goods
Mens Watch Market