
 North America Luxury Goods Market | 2026-2036
North America Luxury Goods Market Size, Share, and Industry Trends Forecast 2026-2036
North America Luxury Goods Market Analytics
Modular product bundling is shifting buyer choice across the North America Luxury Goods Market as houses combine core accessories with digital services and repair programs. LVMH Moët Hennessy Louis Vuitton leverages its vertical control over tanneries and ateliers to sustain margin-rich leather goods production. Chanel Limited anchors its North American position through exclusive distribution and controlled scarcity in handbags and fine jewelry. Kering Group differentiates via aggressive digital integration and direct-to-consumer channel investments.
Luxury goods encompass high-value apparel, accessories, footwear, and watches characterized by superior craftsmanship, premium materials such as full-grain leather and precious metals, and controlled production volumes that signal exclusivity. These products serve commercial purposes centered on status signaling, personal expression, and wealth preservation for affluent buyers. Accessories and watches capture concentrated margin pools due to material intensity and brand heritage premiums, while Generation Z and Millennial customer segments represent the fastest-growing demand cohorts reshaping channel strategy. Online retail and specialty stores now dominate distribution architecture as department stores recede in relevance.
The Federal Trade Commission enforces truth-in-advertising standards that constrain claims around material provenance and manufacturing origin, while U.S. Customs and Border Protection administers tariff classifications affecting import costs for European and Asian finished goods. The Consumer Product Safety Commission monitors jewelry and children's apparel for hazardous substances, compelling brands to maintain rigorous supply-chain documentation. Stakeholders must monitor evolving digital resale authentication requirements and state-level luxury tax proposals that could alter pricing architecture and geographic demand flows.
Market Dynamics
Digital authentication protocols and blockchain-based provenance tracking are compressing verification cycles across resale channels, forcing houses to rebuild trust infrastructure around secondary-market participation.
Growth Catalysts
- USMCA Duty Framework:Streamlined customs procedures under the United States-Mexico-Canada Agreement reduce cross-border friction for European finished goods entering Canadian and American markets.
- Nearshored Leather Tanning:Vertical control over North American tannery operations shortens lead times for full-grain accessories and protects margin pools from currency volatility.
- Experiential Retail Formats:Private client salons and appointment-only showrooms in Manhattan, Beverly Hills, and Yorkville deepen wallet share among ultra-high-net-worth households.
Market Restraints
- European Supply Concentration:Finished handbag and watch movements depend heavily on Italian and Swiss manufacturing clusters, exposing brands to single-source disruption risk.
- Input Cost Volatility:Precious metal prices and exotic leather auction premiums fluctuate with commodity cycles, compressing gross margins on entry-luxury price tiers.
- FTC Truth-in-Advertising Enforcement:The Federal Trade Commission's material provenance investigations constrain marketing claims around domestic manufacturing content.
Strategic Opportunities
- Secondary Market Authentication Services:Resale platforms in Miami and Los Angeles seek third-party verification partnerships, creating white space for house-controlled certification programs.
- Repair and Restoration Subscriptions:Leather goods houses can bundle lifetime care services with initial purchases, locking in recurring revenue from Millennial and Generation Z buyers.
- State-Level Luxury Tax Exemptions:Oregon and New Hampshire impose no sales tax on high-value goods, redirecting purchasing flows from taxed metropolitan corridors.
Industry Challenges
- Artisan Skill Pipeline:Master leatherworkers and fine jewelry setters face generational succession gaps as training programs fail to match retirement rates in New York and Toronto ateliers.
- Digital-Physical Integration Complexity:NFT-linked product passports and augmented reality try-on tools require legacy ERP reconfiguration that strains IT budgets and vendor coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Luxury Goods Market |
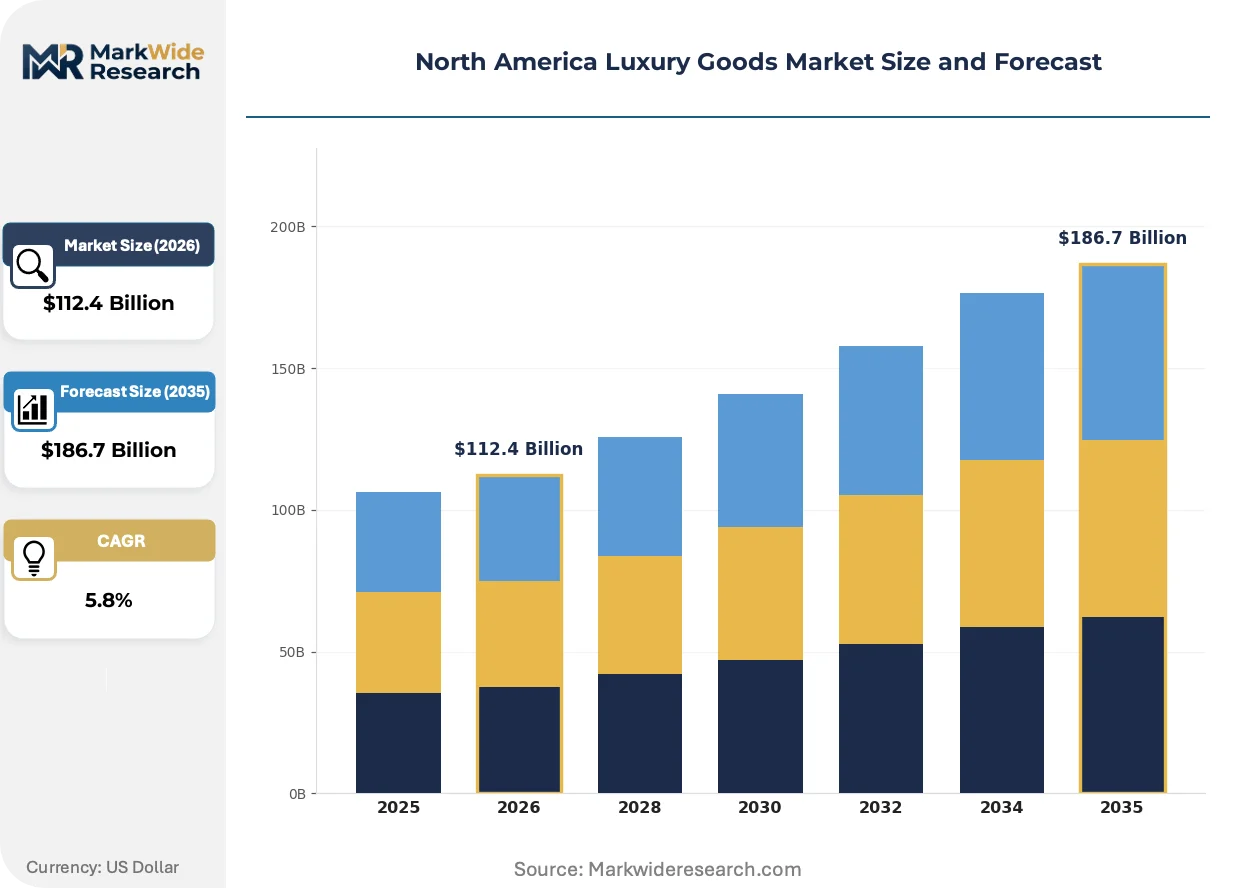
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $186.7 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apparel, Accessories, Footwear, Watches Customer Type: Affluent Consumers, HNWIs, Millennials, Generation Z Distribution Channel: Online Retail, Specialty Stores, Department Stores, Pop-Up Shops Price Tier: Premium, Super Premium, Ultra Luxury, Affordable Luxury |
| Companies Covered | Chanel Limited, Richemont, LVMH Moët Hennessy Louis Vuitton, Tapestry, Inc., The Estée Lauder Companies, Kering Group, Prada S.p.A., Gucci, Hermès International, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Luxury Goods Market Evolving Landscape
Authentication infrastructure and channel reconfiguration dominate competitive investment priorities as houses defend exclusivity against digital resale proliferation and shifting generational loyalties.
Blockchain-based provenance registries is automating ownership verification for pre-owned handbags and watches. Secondary platforms in Los Angeles and Miami adopt these tools to reduce return fraud and accelerate transaction velocity. The technology is automating trust reconstruction between buyers and consignors who lack direct brand relationships.
The Consumer Product Safety Commission tightens hazardous substance monitoring for children's apparel and costume jewelry, compelling brands to expand supply-chain documentation beyond European REACH compliance. California's Proposition 65 disclosure requirements add parallel labeling obligations for products sold through Los Angeles and San Francisco retail doors. Fine jewelry houses now dedicate compliance teams to dual-track American and European chemical standards.
Generational purchasing rotation concentrates demand among Millennial and Generation Z collectors who prioritize resale value retention and circular service bundles over traditional retail experiences. Department store doors in Manhattan and Chicago lose traffic to direct-to-consumer flagships and appointment-only salons. This behavioral pivot is most visible in Toronto's Yorkville district, where heritage houses have converted wholesale space to client-only showrooms with bespoke customization services.
North America Luxury Goods Market Segmentation
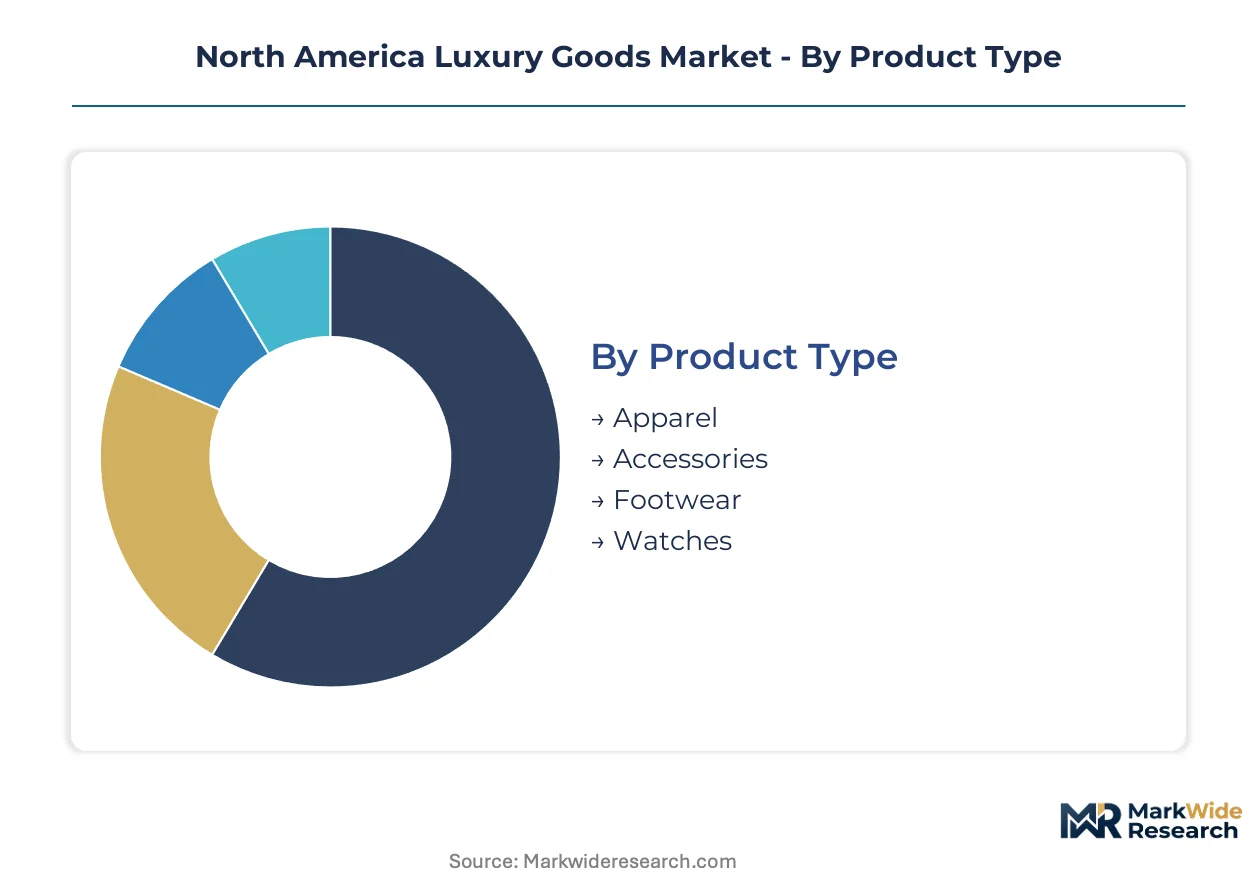
Segmentation in luxury goods reveals how supply chain configuration and customer access patterns diverge across product categories and price tiers. Understanding these divisions exposes where margin pools concentrate and which channels are displacing legacy distribution.
Product Type:
Supply concentration varies sharply across finished goods categories, with European manufacturing clusters dominating certain segments while North American ateliers anchor others.
- Accessories:Full-grain leather handbags and small goods command the highest gross margins due to material intensity and brand heritage premiums. Demand clusters in Manhattan and Beverly Hills, where private client services drive repeat purchases among ultra-high-net-worth households.
- Watches:Swiss movement dependency creates single-source exposure for mechanical timepieces, though smartwatch assembly has regionalized to Texas and California facilities. Toronto's Yorkville district has emerged as a concentrated secondary market for pre-owned verification.
- Apparel:Italian and French cut-and-sew operations supply ready-to-wear collections for flagship doors in Los Angeles and Miami.
- Footwear:Portuguese and Italian manufacturing feeds sneaker-luxe hybrids and formal leather soles alike.
Today's leader: Accessories. Tomorrow's challenger: Watches.
Customer Type:
Generational purchasing rotation is redrawing customer segment boundaries, with digital-native cohorts forcing channel reconfiguration.
- Generation Z:Circular service bundles and resale value retention now outweigh traditional retail experiences for this cohort. Los Angeles and New York consignment platforms report the steepest expansion trajectory among authentication-seeking buyers.
- Millennials:Experiential categories and repair subscriptions lock in lifetime value as this segment ages into peak earning years. Miami's appointment-only salons target this demographic with bespoke customization.
- HNWIs:Ultra-high-net-worth individuals concentrate spending in private client programs across Beverly Hills and Yorkville.
- Affluent Consumers:Entry-luxury price sensitivity exposes this segment to input cost volatility in precious metals and exotic leathers.
Today's leader: Millennials. Tomorrow's challenger: Generation Z.
Distribution Channel:
Channel strategy now determines exclusivity defense, with direct control displacing wholesale relationships.
- Online Retail:Direct-to-consumer flagships and resale platforms capture the fastest-growing transaction volume. Blockchain-based provenance tracking automates trust reconstruction between buyers and consignors lacking direct brand relationships.
- Specialty Stores:Heritage houses have converted wholesale space to client-only showrooms with bespoke services, deepening wallet share in Manhattan and Toronto.
- Pop-Up Shops:Temporary activations in Miami and Los Angeles test experiential formats before permanent investment.
- Department Stores:Traffic erosion in Chicago and Manhattan doors accelerates as flagship retail anchors regional consumption patterns.
Today's leader: Specialty Stores. Tomorrow's challenger: Online Retail.
Price Tier:
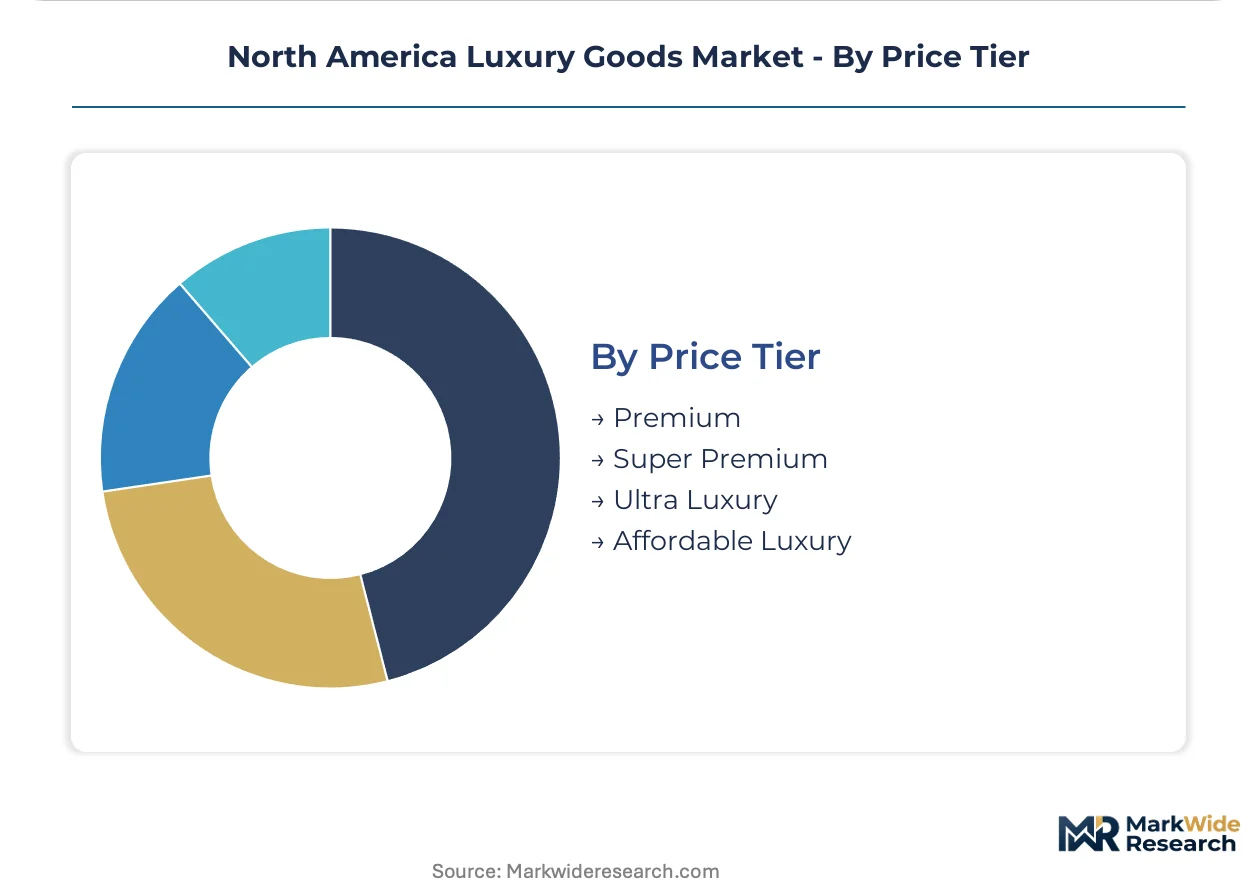
Margin architecture stratifies across four distinct levels, with raw material exposure concentrated at entry points.
- Ultra Luxury:One-of-a-kind pieces and limited editions bypass commodity price cycles through auction-based allocation. Beverly Hills and New York ateliers concentrate bespoke orders for this tier.
- Super Premium:Hand-finished leather goods and complications maintain pricing power through controlled scarcity. Italian tannery partnerships protect margin pools from currency volatility.
- Premium:Diffusion lines and core collections face compressed gross margins when precious metal prices spike.
- Affordable Luxury:Entry price points absorb the brunt of exotic leather auction premiums and FTC compliance costs.
Today's leader: Super Premium. Tomorrow's challenger: Ultra Luxury.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European ateliers in France and Italy birthed modern luxury craftsmanship during the 19th century, establishing the artisan traditions that North American houses later adapted. The United States scaled these methods through industrial organization, while Canada developed parallel expertise in fur and leather processing. Mexico's emerging manufacturing corridors now attract tanning and finishing operations seeking USMCA tariff advantages.
United States
Ultra-high-net-worth households in Manhattan and Beverly Hills drive concentrated demand for bespoke leather goods and fine jewelry. The Federal Trade Commission enforces truth-in-advertising standards that constrain material provenance claims, compelling brands to maintain rigorous documentation. Los Angeles has emerged as the dominant authentication hub for secondary-market luxury watches, with blockchain verification startups clustering near consignment platforms.
Canada
Toronto's Yorkville district anchors private client services for affluent households across Ontario and Quebec. Health Canada monitors jewelry and children's apparel for hazardous substances under the Canada Consumer Product Safety Act. Montreal's historic fur trade infrastructure now supports exotic leather finishing operations serving North American handbag manufacturers.
Mexico
Rising aspirational consumption in Mexico City and Monterrey expands demand for entry-luxury accessories and cosmetics. The United States-Mexico-Canada Agreement streamlines customs procedures for European finished goods entering through Laredo and Tijuana corridors. Guanajuato's leatherworking traditions attract nearshoring investments from brands seeking to shorten supply chains for North American distribution.
North America Luxury Goods Market Competitive Landscape
Premium-margin players sit above commodity-margin players across heritage depth and distribution control, with French and Italian houses commanding pricing power through century-old artisan networks. The vendor base concentrates around vertically integrated conglomerates that control tanning, manufacturing, and retail doors. Three archetypes dominate: heritage maisons with controlled scarcity models, digital-native challengers leveraging direct-to-consumer channels, and conglomerate platforms optimizing portfolio synergies. Capacity expansion and exclusive retail footprint growth represent the dominant competitive moves as houses convert wholesale space to owned flagships.
Within the heritage maison tier, Chanel Limited and Hermès International exemplify controlled scarcity architecture through limited distribution and artisan-dependent production. LVMH Moët Hennessy Louis Vuitton anchors the conglomerate platform model, integrating upstream tannery control with downstream retail dominance. These three entities represent contrasting approaches to margin defense: exclusivity through constraint, exclusivity through vertical integration, and scale through portfolio breadth.
| Leading Market Players |
|---|
| Chanel Limited |
| Richemont |
| LVMH Moët Hennessy Louis Vuitton |
| Tapestry, Inc. |
| The Estée Lauder Companies |
| Kering Group |
| Prada S.p.A. |
| Gucci |
| Hermès International |
| Others |
Value Network & Pricing Analysis
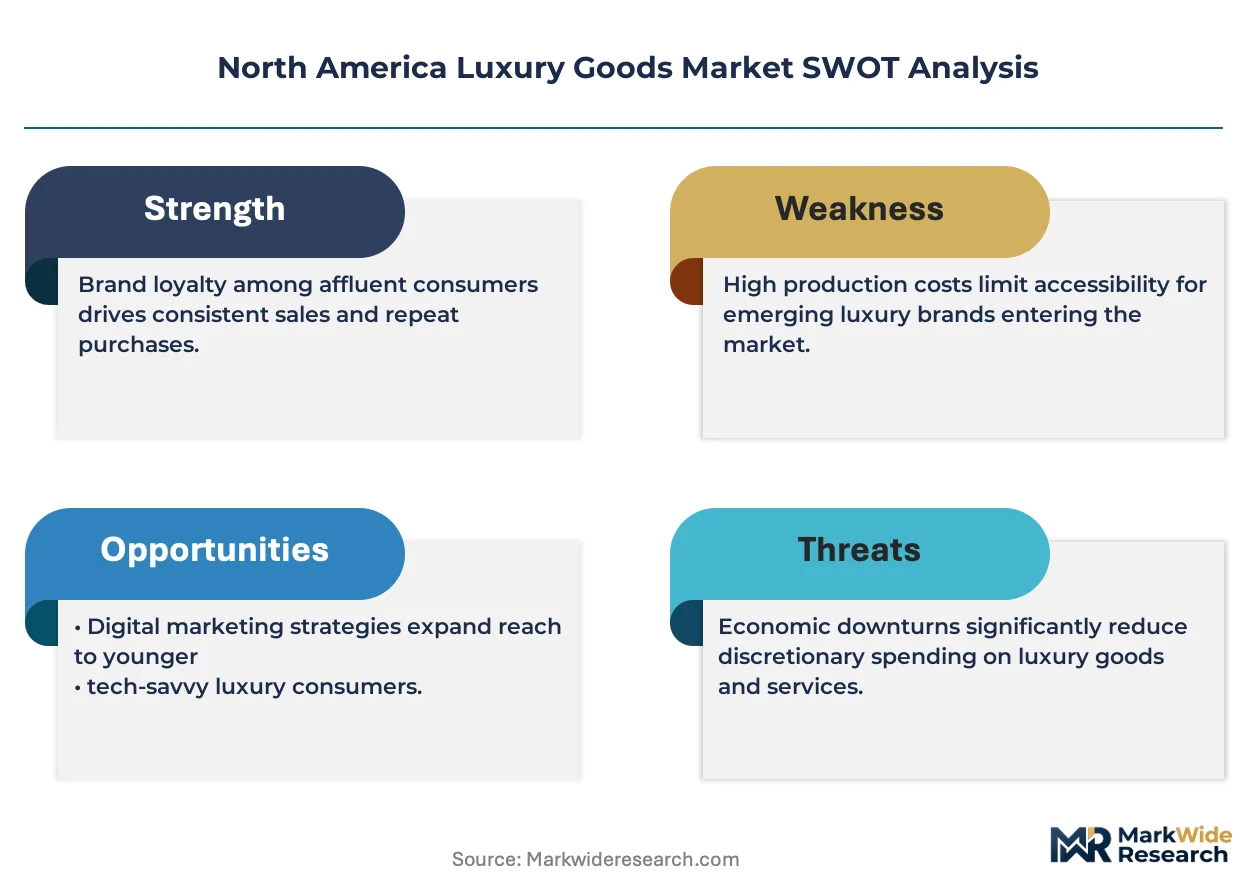
Exotic leather auction premiums at French and Italian tanneries cascade through finished goods pricing, concentrating margin compression at entry-luxury tiers while super-premium and ultra-luxury segments absorb volatility through controlled scarcity allocation.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates heritage maisons from diffusion lines and mass-market accessible luxury. Price differentiation hinges on artisan labor intensity and FTC-compliant material provenance documentation. Cost compression in affordable luxury intensifies because exotic leather auction premiums and precious metal spot prices feed directly into COGS. Entry-luxury buyers exhibit acute price sensitivity, whereas ultra-high-net-worth households demonstrate inelastic demand for bespoke pieces.
Supply Chain Analysis
REACH compliance and California Proposition 65 certification requirements gate supplier participation, compelling brands to maintain dual-track documentation for European and North American regulatory frameworks. Manufacturing concentrates in Italy, Switzerland, and France for finished leather goods and mechanical watch movements, while Mexico's Guanajuato corridor attracts nearshored tanning operations. Raw material dependencies include full-grain hides from French and Italian tanneries, Swiss mechanical movements, and precious metals from accredited refiners. Single-source vulnerability in Italian cut-and-sew clusters exposes brands to disruption risk. Distribution runs through direct-to-consumer flagships, appointment-only salons, and authenticated resale platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Luxury Goods Market represents a late-cycle quality story as generational purchasing rotation concentrates demand among Millennial and Generation Z collectors prioritizing resale value retention and circular service bundles over traditional retail experiences.
For Market Incumbents: Extend private client program coverage into secondary authentication services, capturing margin pools from Miami and Los Angeles resale platforms. Deepen backward integration into North American tannery operations to shorten lead times and insulate margin pools from currency volatility. Counter digital-native challenger encroachment by converting wholesale doors to owned flagships with bespoke customization capabilities.
For New Entrants and Emerging Players: Launch via authenticated resale partnerships targeting Generation Z collectors in Los Angeles and New York consignment channels. Exploit white space in repair and restoration subscriptions for leather goods, locking in recurring revenue from circular-minded buyers. Penetrate the experiential retail segment through pop-up activations in Miami and Toronto before permanent investment.
For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated heritage maisons controlling upstream tannery access and downstream flagship distribution. Long-term viability favors entities with century-old artisan networks and controlled scarcity architecture. Monitor blockchain-based provenance adoption rates as inflection indicator for secondary market authentication infrastructure maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| Secondary Market Authentication Program | Blockchain verification partnerships with Los Angeles and Miami resale platforms rebuild trust infrastructure. |
| Nearshored Tannery Investment | Mexico's Guanajuato corridor offers USMCA tariff advantages for North American leather finishing. |
| Repair Subscription Bundling | Lifetime care services lock in Millennial and Generation Z recurring revenue streams. |
| Private Client Salon Expansion | Appointment-only showrooms in Manhattan and Yorkville deepen ultra-high-net-worth wallet share. |
| Digital-Physical Integration | NFT-linked product passports require ERP reconfiguration but defend exclusivity against resale proliferation. |
Research Methodology
Multiple input streams — executive interviews with leather goods brand managers and fine jewelry atelier directors, secondary validation through U.S. Customs and Border Protection tariff classifications and FTC enforcement actions, and trade data from European tannery associations — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged category buyers at heritage house flagships, supply chain directors overseeing Italian manufacturing partnerships, and authentication platform founders in Los Angeles and Miami. Secondary sources included customs records for finished goods imports, Consumer Product Safety Commission hazard monitoring databases, and Canada Consumer Product Safety Act compliance filings.
Data-stream reconciliation anchored volume and value outputs across product type, customer generation, distribution channel, and price tier segmentation dimensions. CAGRs were derived from trend extrapolation moderated by input cost volatility assumptions and generational purchasing rotation patterns. Forecast inputs incorporated USMCA customs procedure evolution, digital authentication technology adoption curves, and state-level luxury tax proposal tracking.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt precious metal price spikes or FTC material provenance enforcement escalations. A model refresh is warranted upon material change in secondary market authentication infrastructure deployment or USMCA tariff classification revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Goods
Accessible Luxury Goods Market
Luxury Goods
Used Luxury Bags Trading Service Market
Luxury Goods
Luxury Apparels Market
Luxury Goods
Luxury Goods Market
Luxury Goods
Global Gold Jewelry Market
Luxury Goods
Germany Luxury Goods Market
Luxury Goods
Brazil Luxury Goods Market
Luxury Goods
United States Secondhand Luxury Goods Market
Luxury Goods
Malaysia Luxury Goods Market
Luxury Goods
Italy Luxury Goods Market
Luxury Goods
Spain Luxury Goods Market
Luxury Goods
GCC Personal Luxury Goods Market
Luxury Goods
Luxury Pen Market
Luxury Goods
China Luxury Goods Market
Luxury Goods
Luxury Products for Kids Market
Luxury Goods
Russia Luxury Goods Market