
 Singapore Luxury Goods Market | 2026-2036
Singapore Luxury Goods Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Luxury Goods Market Analytics
CE marking alignment for imported European luxury goods is rotating as a de facto gatekeeping standard for brands seeking duty-free retail licenses at Changi Airport. LVMH Moët Hennessy Louis Vuitton leverages its integrated maisons structure to dominate leather goods and spirits categories simultaneously. The Hour Glass Ltd anchors watch distribution through controlled boutique networks across Southeast Asia. Hermès International S.A. sustains scarcity-driven pricing through deliberate production caps on signature leather pieces.
Singapore luxury goods comprise high-value, non-essential consumer products characterized by superior craftsmanship, premium materials including full-grain leather and precious metals, and conspicuous brand heritage signaling social status. These items function primarily as wealth displays and investment vehicles for ultra-high-net-worth individuals. Ultra-premium watches command the deepest margin pools due to limited production runs and secondary market premiums. Tourist purchases through airport boutiques represent the fastest-growing channel segment as post-pandemic travel normalizes across Asia-Pacific corridors. Accessible luxury bags face margin compression as entry-level consumers shift toward experiential spending.
Singapore Customs enforces strict import documentation and anti-counterfeiting protocols under the Trade Marks Act, while the Competition and Consumer Commission of Singapore monitors pricing transparency in duty-free zones. Monetary Authority of Singapore regulations on anti-money laundering now extend to high-value goods transactions exceeding specified thresholds. Stakeholders must monitor evolving cross-border e-commerce tax treatments and digital authentication mandates that could reshape online luxury retail mechanics.
Market Dynamics
Scarcity-driven production caps at heritage maisons are compressing secondary market liquidity while amplifying price premiums on authenticated pre-owned pieces. This artificial supply constraint reshapes inventory velocity across Orchard Road boutiques and digital resale platforms alike.
Growth Catalysts
- High-Net-Worth Tourist Inflows:Post-pandemic normalization of Asia-Pacific travel corridors is replenishing duty-free purchase volumes at Changi Airport retail zones. Visitor spending on ultra-premium watches now exceeds pre-crisis benchmarks.
- Trade Marks Act Enforcement:Singapore Customs' stringent anti-counterfeiting protocols under this legislation preserve brand integrity and consumer confidence in authenticated retail channels. Confiscation rates of counterfeit luxury goods deter gray market infiltration.
- Ultra-Premium Watch Demand:Limited production runs from Swiss manufactures are creating waitlist dynamics that sustain margin pools and investment-grade resale values. Collectors treat complications as portable wealth stores.
Market Restraints
- Precious Metal Input Volatility:Fluctuations in gold and platinum pricing compress margin predictability for jewelry and watch case manufacturers. Hedging costs add operational complexity to inventory planning.
- Production Concentration Risk:European artisan clusters in Florence and Paris control critical leatherworking and métiers d'art capacity. Geopolitical disruptions to these supply nodes cascade through finished goods availability.
- Experiential Substitution Threat:Affluent consumers under forty redirect discretionary spending toward travel and dining experiences rather than tangible luxury acquisitions. This generational pivot constrains entry-level leather goods volume.
Strategic Opportunities
- Digital Authentication Mandates:Emerging blockchain-based provenance tracking creates regulatory tailwinds for platforms verifying secondary market authenticity. Singapore's Monetary Authority guidelines on high-value transactions favor transparent ownership chains.
- Experiential Retail Integration:Maison-hosted ateliers and private client salons transform transactional boutiques into relationship-building venues. These immersive formats deepen customer lifetime value beyond single purchases.
- Pre-Owned Platform Expansion:Underpenetrated digital resale infrastructure in Southeast Asia presents white space for curated authentication services. Regional wealth managers seek alternative investment vehicles for client portfolios.
Industry Challenges
- Artisan Talent Scarcity:Multi-year apprenticeship requirements for leatherworking and horological finishing create pipeline bottlenecks. Maisons compete for limited cohorts trained in heritage techniques.
- Cross-Border E-Commerce Tax Complexity:Evolving duty treatments for online luxury purchases complicate pricing parity across jurisdictions. Retailers face compliance friction in harmonizing digital and physical channel economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Luxury Goods Market |
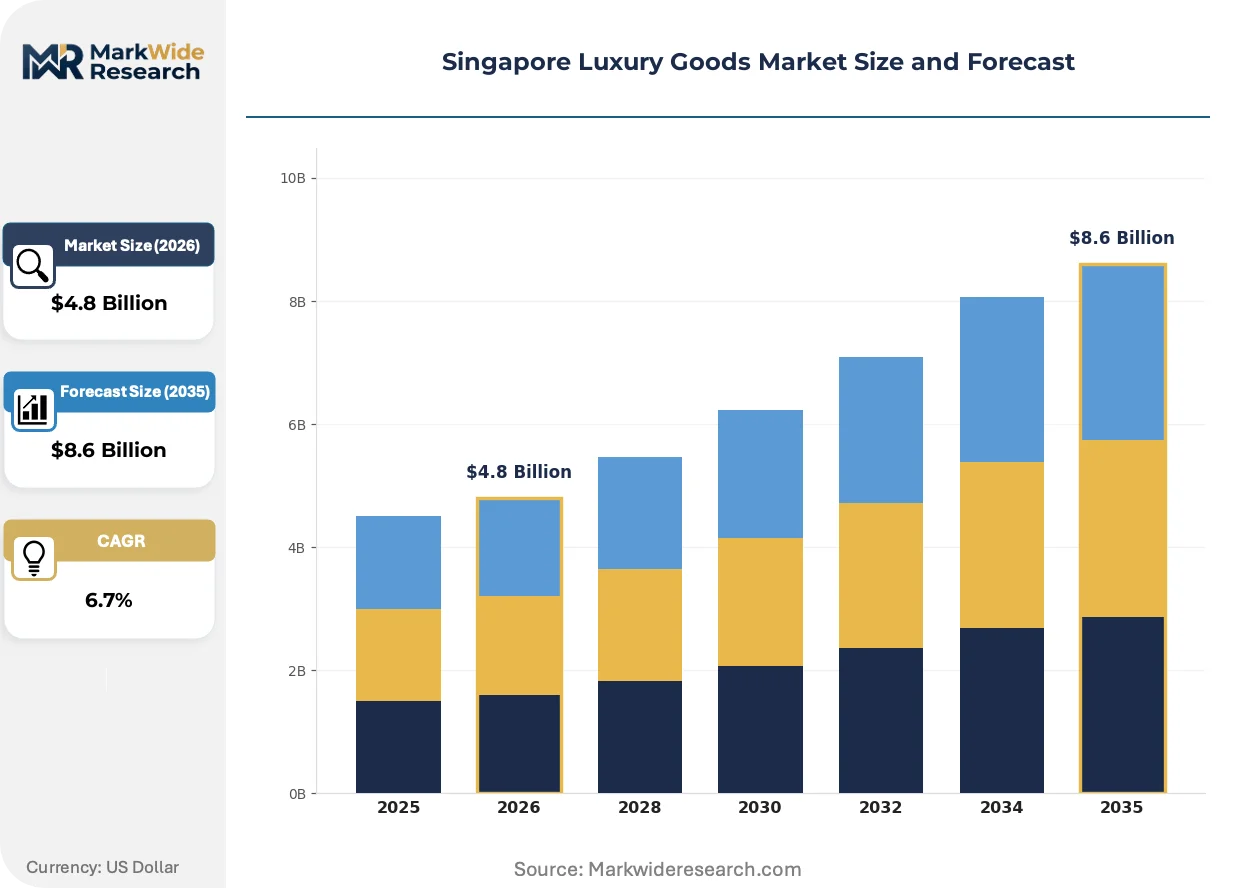
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Jewelry, Watches, Apparel Distribution Channel: Online, Department Stores, Specialty Stores, Boutiques Customer Profile: Affluent Consumers, Tourists, Business Professionals, Celebrities Brand Positioning: Premium, Ultra-Premium, Accessible Luxury, High-End |
| Companies Covered | LVMH Moët Hennessy Louis Vuitton, Kering SA, Richemont SA, The Swatch Group Ltd, Rolex SA, Chanel SA, Hermès International S.A., The Estée Lauder Companies, The Hour Glass Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Luxury Goods Market Evolving Landscape
Physical-digital hybrid authentication is restructuring trust mechanics across primary and secondary sales channels. This convergence of materials science and distributed ledger technology redefines how provenance is verified and transferred between owners.
Near-field communication chips embedded in leather goods and watch components are miniaturizing to sub-millimeter scales without compromising signal integrity. High-net-worth collectors in Singapore and Hong Kong are adopting these enabled pieces at accelerating rates. This technology is miniaturizing the authentication burden from external verification services onto the object itself, compressing transaction friction in private sales.
Singapore's Monetary Authority regulations extending anti-money laundering protocols to high-value goods transactions above specified thresholds are tightening documentation requirements. Retailers must now capture enhanced buyer identity data and source-of-funds declarations. Ultra-premium watch boutiques and auction houses are most affected, responding through dedicated compliance personnel and automated screening systems.
Secondary market purchasing through authenticated digital platforms is displacing traditional consignment relationships among younger affluent buyers. Orchard Road maisons now operate certified pre-owned programs to recapture this demand rather than cede it to independent platforms. This behavioral shift is most visible in Singapore's collector community, where liquidity preference favors immediate digital transactions over relationship-dependent resale channels.
Singapore Luxury Goods Market Segmentation
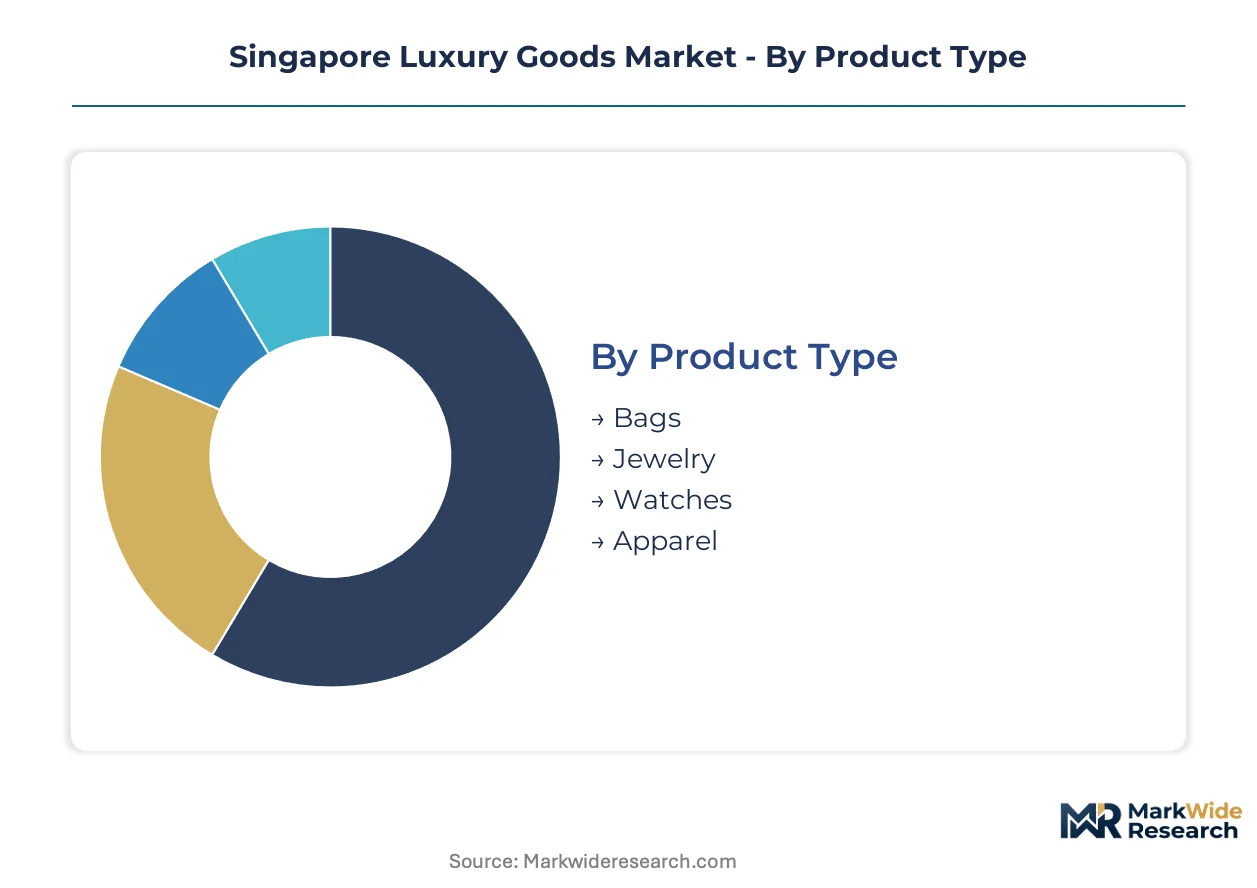
Segmentation in Singapore's luxury goods market reveals distinct margin architectures across product categories and channel structures. Each dimension carries unique regulatory exposure and customer acquisition economics that shape competitive positioning.
Product Type:
Ultra-premium watches command the deepest margin pools within this category, followed by heritage leather goods with scarcity-driven pricing power.
- Bags:Full-grain leather construction with hand-stitched detailing defines this segment. Orchard Road boutiques and Changi Airport duty-free zones concentrate demand among high-net-worth tourists seeking investment-grade pieces. Scarcity protocols at European maisons sustain waitlist dynamics.
- Jewelry:Precious metal and gemstone compositions with certified provenance documentation. Affluent local collectors in Sentosa Cove and Nassim Road districts drive demand, though gold price volatility compresses margin predictability for retailers.
- Watches:Swiss-manufactured complications with limited production runs. Secondary market premiums and portable wealth storage characteristics attract ultra-high-net-worth investors.
- Apparel:Ready-to-wear and made-to-measure collections from heritage fashion houses. Business professionals in the Central Business District sustain volume for tailored suiting and occasion dressing.
The dominant share belongs to Watches, while Bags is closing the gap fastest through authenticated pre-owned platform expansion.
Distribution Channel:
Channel economics in Singapore reflect the city-state's compact geography and strict regulatory environment for high-value transactions.
- Online:Curated e-commerce platforms with blockchain-based authentication protocols. Younger affluent buyers in Singapore and Hong Kong favor immediate digital transactions over relationship-dependent resale channels.
- Department Stores:Tangs and Takashimaya anchor consignment retail with fixed-location traffic. Tourist footfall recovery post-pandemic has replenished volumes in Orchard Road corridors.
- Specialty Stores:Multi-brand watch and jewelry retailers with certified pre-owned programs. The Hour Glass Ltd operates controlled boutique networks that deepen customer lifetime value through private client services.
- Boutiques:Maison-owned flagships with experiential atelier integration. LVMH and Hermès leverage these formats to transform transactional retail into relationship-building venues with dedicated compliance personnel for Monetary Authority anti-money laundering protocols.
Boutiques capture the dominant revenue concentration, though Online is expanding most quickly through digital-native collector adoption.
Customer Profile:
Customer acquisition costs and lifetime value diverge sharply across demographic segments with distinct spending patterns.
- Affluent Consumers:Singapore-based ultra-high-net-worth individuals with generational wealth concentration in Districts 9, 10, and 11. These buyers treat complications and leather goods as portable wealth stores with secondary market liquidity.
- Tourists:Asia-Pacific visitors purchasing through Changi Airport duty-free zones. Post-pandemic normalization of travel corridors has pushed visitor spending on ultra-premium watches beyond pre-crisis benchmarks.
- Business Professionals:Corporate executives in finance and technology sectors seeking status-signaling accessories for client-facing roles. Entry-level leather goods face pressure as this cohort shifts toward experiential spending.
- Celebrities:High-visibility personalities with brand ambassador relationships and custom commission access. These relationships generate halo effects for maisons across Southeast Asian markets.
Affluent Consumers hold the dominant share, while Tourists is gaining share fastest through airport retail volume recovery.
Brand Positioning:
Positioning tiers in Singapore reflect deliberate scarcity architecture and production cap strategies from European parent companies.
- Ultra-Premium:Hermès International S.A. and independent haute horlogerie manufactures with multi-year waitlists. Deliberate production caps on signature leather pieces sustain price premiums and secondary market liquidity.
- Premium:Established heritage houses with controlled distribution and seasonal collection drops. These brands balance accessibility with exclusivity through selective wholesale partnerships.
- High-End:Contemporary luxury labels with direct-to-consumer digital presence and rapid product cadences. Younger demographics in Singapore's creative industries gravitate toward these formats.
- Accessible Luxury:Diffusion lines and entry-tier leather goods facing margin compression. Generational pivot toward travel and dining experiences constrains volume in this tier.
Ultra-Premium commands the dominant margin pool, while High-End is climbing the fastest through digital-native customer acquisition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ultra-high-net-worth individuals concentrate in Singapore's prime districts, driving demand for portable wealth stores and status-signaling acquisitions across Southeast Asian corridors.
Orchard Road Retail Corridor
Luxury maisons anchor flagship boutiques along this shopping belt, capturing tourist and local affluent spending simultaneously. Singapore Customs enforces strict anti-counterfeiting protocols under the Trade Marks Act, preserving authenticated retail channel integrity. LVMH and Hermès operate experiential ateliers here, transforming transactional visits into relationship-building engagements.
Sentosa Cove District
Waterfront villa residents sustain demand for ultra-premium watches and bespoke jewelry commissions. Monetary Authority of Singapore regulations extend anti-money laundering protocols to high-value transactions, requiring enhanced buyer documentation. Private client salons from Swiss manufactures concentrate here, serving collectors treating complications as investment vehicles.
Changi Airport Duty-Free Zone
Asia-Pacific transit passengers replenish post-pandemic purchase volumes for leather goods and spirits categories. CE marking alignment serves as de facto gatekeeping for duty-free retail licenses under Singapore's strict import documentation standards. The Hour Glass Ltd and airport consortium partners control watch distribution through controlled boutique networks in these terminals.
Central Business District
Finance and technology executives seek status-signaling accessories for client-facing professional roles. Competition and Consumer Commission of Singapore monitors pricing transparency across retail zones serving this demographic. Tailored suiting from heritage fashion houses concentrates along Raffles Place and Marina Bay commercial clusters.
Nassim Road Enclave
Generational wealth holders in colonial-era bungalows drive demand for scarcity-driven leather pieces with multi-year waitlists. Singapore's Customs regulations on high-value goods imports protect brand exclusivity through rigorous documentation requirements. Hermès International S.A. sustains deliberate production caps on signature pieces for this collector base.
Singapore Luxury Goods Market Competitive Landscape
Player mix skews toward integrated luxury conglomerates with multi-brand portfolios spanning leather goods, watches, and beauty categories. Market structure concentrates around European heritage maisons with century-old craftsmanship credentials and controlled distribution networks. Two strategic archetypes dominate: vertically integrated Swiss watch manufactures with limited production runs, and French leather goods houses leveraging scarcity-driven pricing. Competitive moves center on experiential retail integration and certified pre-owned program launches.
Within the integrated conglomerate tier, LVMH Moët Hennessy Louis Vuitton anchors multi-category dominance through its maisons structure, while Kering SA and Richemont SA occupy positions as diversified portfolio holders across leather goods and hard luxury segments. Among specialized distribution players, The Hour Glass Ltd exemplifies the controlled boutique network archetype, and Rolex SA represents the independent manufacture model with deliberate scarcity protocols. These entities collectively shape competitive dynamics through production cap strategies and direct-to-consumer channel expansion.
| Leading Market Players |
|---|
| LVMH Moët Hennessy Louis Vuitton |
| Kering SA |
| Richemont SA |
| The Swatch Group Ltd |
| Rolex SA |
| Chanel SA |
| Hermès International S.A. |
| The Estée Lauder Companies |
| The Hour Glass Ltd |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation agreements with Swiss manufactures and Florentine leatherworking ateliers lock in supply access and price visibility for Singapore's ultra-premium watch and leather goods segments. These contractual structures insulate heritage maisons from spot market volatility while embedding multi-year price escalation clauses tied to artisan labor costs and precious metal indices.
Pricing Analysis
Cost-plus contracts with gold and platinum indexation dominate jewelry and watch case manufacturing, passing metal volatility through to retail price points. Price differentiation rests on scarcity tiering—waitlisted signature pieces command substantial premiums over standard collections, while entry-level leather goods face compression as younger buyers redirect spending. Pricing pressure intensifies in accessible luxury tiers due to experiential substitution, whereas ultra-premium complications show minimal buyer price sensitivity among wealth-preservation collectors.
Supply Chain Analysis
Inventory lead times for Swiss-manufactured movements and full-grain leather from Italian tanneries now stretch across multi-year horizons, constraining finished goods availability. Supply concentrates in Switzerland for horological components, France and Italy for leatherworking, and Singapore for final assembly and retail distribution. Raw material dependencies span gold and platinum from South African mines, alligator skins from certified farms, and sapphire crystals from specialized growers. Single-source vulnerability around European artisan clusters poses structural risk, while distribution runs through controlled boutique networks and airport duty-free consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore's luxury goods sector sits in early-cycle expansion as post-pandemic Asia-Pacific travel normalization replenishes high-net-worth tourist flows and duty-free purchase volumes.
For Market Incumbents: Shield scarcity-driven pricing power by deepening backward integration into European artisan training pipelines and expanding certified pre-owned programs to recapture secondary market demand. The experiential substitution threat among affluent consumers under forty demands immersive atelier investments that transform transactional retail into relationship-building venues with dedicated compliance personnel for Monetary Authority protocols. For New Entrants and Emerging Players: Anchor in underpenetrated digital authentication services for Southeast Asian collectors seeking verified pre-owned liquidity, targeting Singapore-based wealth managers who seek alternative investment vehicles for client portfolios. The white space lies in curated resale platforms with blockchain provenance tracking, entering through partnerships with established auction houses rather than competing against controlled boutique networks. For Investors and Strategic Acquirers: Specialized authentication technology providers with embedded NFC chip capabilities and distributed ledger infrastructure represent the most compelling acquisition target archetype for long-term viability across the next decade. Watch for inflection signals around regulatory mandates from Singapore's Monetary Authority extending digital ownership documentation requirements to high-value goods transactions above specified thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Experiential Atelier Integration | LVMH and Hermès transform Orchard Road boutiques into immersive relationship-building venues deepening customer lifetime value. |
| Certified Pre-Owned Program Launch | Heritage maisons recapture secondary market demand from independent digital platforms among Singapore's collector community. |
| Blockchain Authentication Infrastructure | Platforms align with Monetary Authority guidelines favoring transparent ownership chains for high-value transactions. |
| Artisan Talent Pipeline Investment | Maisons secure multi-year apprenticeship commitments addressing critical leatherworking and horological finishing scarcity. |
| Duty-Free Retail License Expansion | Changi Airport consortium partners leverage CE marking alignment as de facto gatekeeping for spirits and leather goods categories. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade records, and luxury retail audit data. Primary interviews engaged brand executives at heritage maisons, duty-free retail operators, private client advisors at wealth management firms, and compliance officers at auction houses. Secondary sources encompassed Singapore Customs import documentation, Monetary Authority of Singapore regulatory circulars, Competition and Consumer Commission pricing transparency reports, and SEC filings from listed luxury conglomerates. Bottom-up demand modeling triangulated against top-down market sizing across product categories and distribution channels.
Segmentation dimensions modeled include product type across bags, jewelry, watches, and apparel; distribution channel spanning boutiques, specialty stores, department stores, and online platforms; customer profile covering affluent consumers, tourists, business professionals, and celebrities; and brand positioning tiers from ultra-premium through accessible luxury. CAGRs were derived through trend extrapolation and adoption curve analysis across the projection horizon, incorporating tourist arrival recovery trajectories, secondary market liquidity indicators, and regulatory enforcement intensity as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of continued Asia-Pacific travel normalization and stable precious metal pricing; material deviation in tourist flows or gold volatility would warrant model refresh. Specific company strategies, undisclosed production capacities, and evolving cross-border e-commerce tax treatments introduce uncertainty. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Goods
Germany Luxury Goods Market
Luxury Goods
Malaysia Luxury Goods Market
Luxury Goods
Luxury Pen Market
Luxury Goods
Middle East and Africa Luxury Goods Market
Luxury Goods
United Arab Emirates Luxury Goods Market
Luxury Goods
Mens Watch Market
Luxury Goods
Italy Luxury Goods Market
Luxury Goods
Luxury Mechanical Watches Market
Luxury Goods
Luxury Watches Market
Luxury Goods
Luxury Products for Kids Market
Luxury Goods
Secondhand Luxury Goods Market
Luxury Goods
Spain Luxury Goods Market
Luxury Goods
Wooden Watch Market
Luxury Goods
UAE Luxury Jewelry Market
Luxury Goods
United States Luxury Goods Market
Luxury Goods
Spain Luxury Jewelry Market