
 Wireless Power Transmission Market | 2026-2036
Wireless Power Transmission Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Power Transmission Market Intelligence
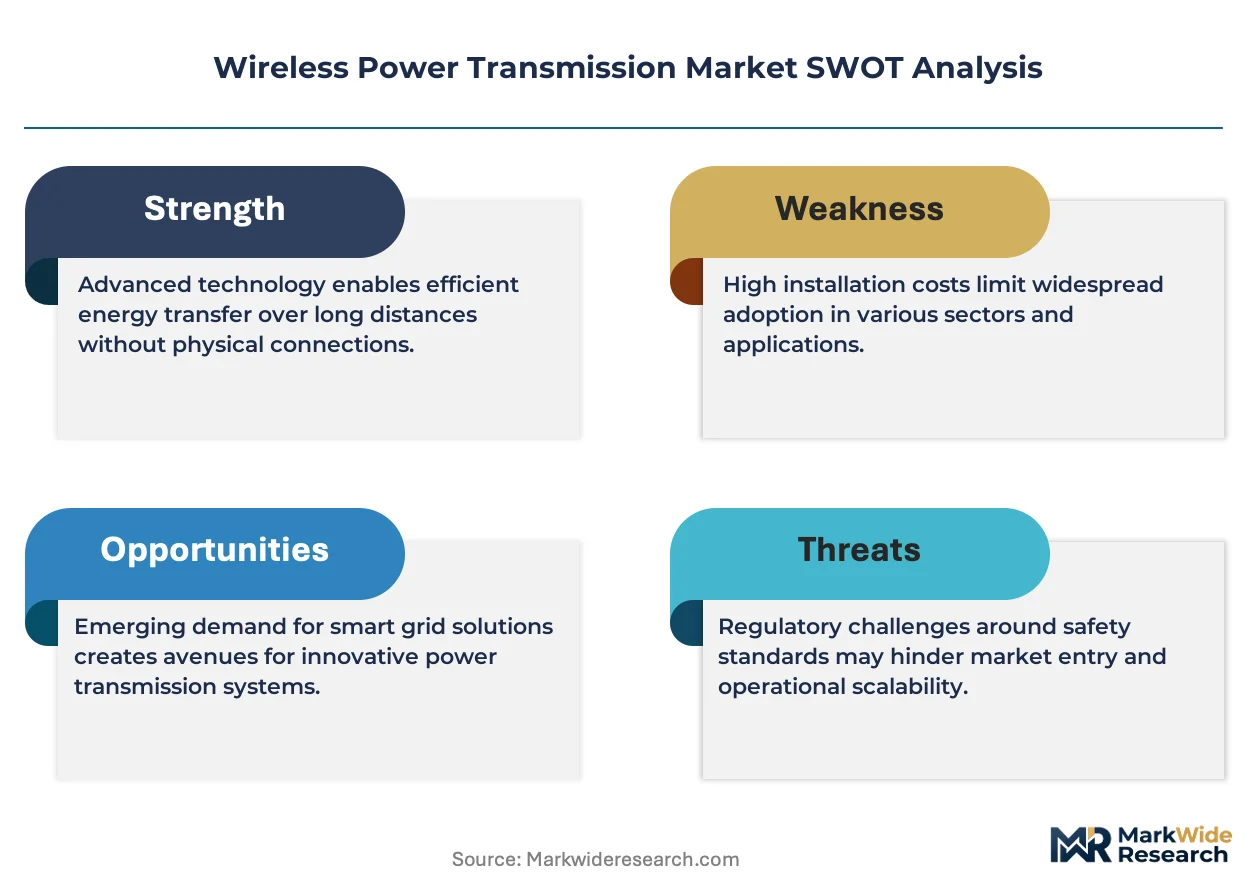
Project finance for large-scale charging infrastructure is reconfiguring competitive entry barriers in wireless power transmission. WiTricity Corporation leverages its patent position in magnetic resonance architectures to dominate licensing negotiations with automotive OEMs. Texas Instruments Inc. sustains component supply advantages through captive fabrication of integrated coil drivers and power management chipsets. Samsung Electronics Co. Ltd. anchors consumer-facing demand by controlling retail channel placement for Qi-compatible devices across multiple continents.
Wireless power transmission transfers electrical energy across air gaps through oscillating magnetic fields, typically operating at frequencies between 100 kHz and 6.78 MHz for near-field inductive and resonant systems. The technology eliminates conductive connectors in environments where moisture, vibration, or frequent mating cycles degrade conventional contacts. Inductive coupling occupies the largest installed base due to mature Qi standardization in consumer electronics, though resonant inductive coupling captures expanding margin pools as automakers specify higher-clearance vehicle charging. Microwave transmission remains specialized for long-range drone and satellite applications where beamforming precision justifies lower efficiency trade-offs.
The FCC in the United States governs RF emission limits for wireless power devices under Part 18 rules, while the EU Green Deal and REACH framework restrict hazardous substances in coil assemblies and mandate recyclability disclosures. China's MIIT enforces GB standards for electromagnetic compatibility that foreign suppliers must satisfy for market access. Stakeholders should monitor evolving interoperability mandates between regional standards bodies, as fragmentation in certification requirements threatens to segment addressable markets by geography rather than by technical capability.
Market Dynamics
Magnetic resonance architectures are displacing inductive coupling in automotive specifications, forcing component suppliers to retool coil fabrication and power electronics assembly lines around higher-clearance, multi-kilowatt systems.
Growth Catalysts
- EU F-Gas Regulation:Tightening energy efficiency mandates for power electronics are accelerating demand for resonant inductive systems that minimize thermal losses in charging infrastructure.
- Electric vehicle fleet electrification:Automakers in Germany, China, and the United States are integrating wireless charging pads into premium vehicle platforms to eliminate conductive connector wear.
- Qi standard maturation:Interoperability certification for consumer electronics has collapsed technical barriers for accessory manufacturers entering medical device and industrial tool segments.
Market Restraints
- Copper and ferrite supply concentration:Coil core material sourcing clusters in Chinese processing facilities, exposing price volatility to export quota fluctuations.
- RF emission compliance costs:FCC Part 18 testing for magnetic field leakage adds twelve to eighteen months to product launch timelines for foreign entrants.
- Conductive fast-charging substitution:Silicon carbide-based wired systems above 350 kW capture fleet operator preference where dwell time minimization dominates.
Strategic Opportunities
- India PLI scheme for electronics:Production-linked incentives for component manufacturing attract coil driver assembly investments serving domestic medical device demand.
- Drone logistics microwave transmission:Beamforming precision systems enable beyond-line-of-sight power delivery for unmanned aerial vehicle fleets in agricultural and emergency response applications.
- Japan METI carbon neutrality roadmap:Public procurement preferences for contactless charging infrastructure accelerate municipal bus and taxi fleet electrification tenders.
Industry Challenges
- Electromagnetic compatibility certification backlog:China's GB standard testing queue extends twelve months for foreign suppliers seeking MIIT approval.
- Legacy grid integration complexity:Resonant systems above 11 kW require distribution network upgrades that strain utility capex planning cycles.
- Patent licensing fragmentation:Magnetic resonance IP pools span multiple university consortia and corporate holders, complicating royalty stack negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Power Transmission Market |
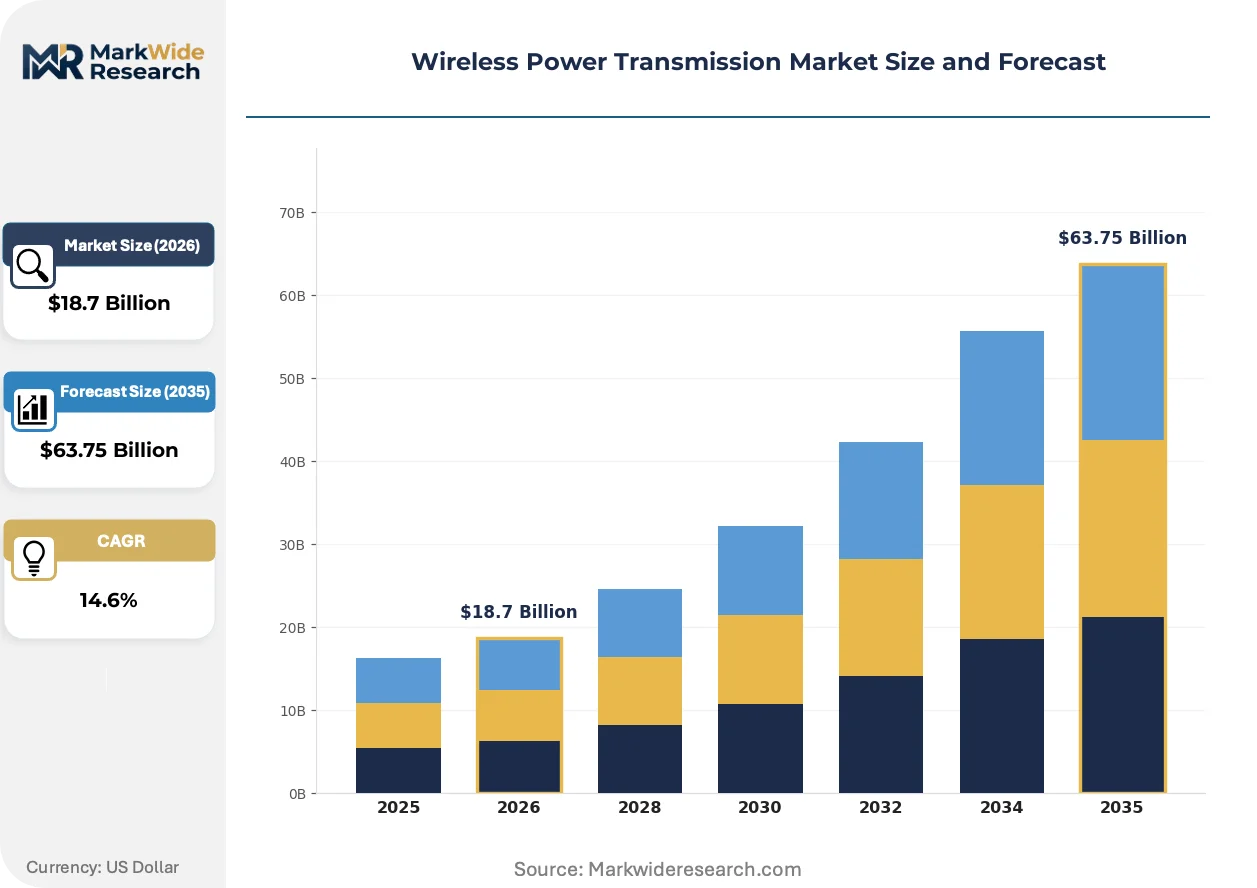
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $63.75 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Inductive Coupling, Resonant Inductive Coupling, Capacitive Coupling, Microwave Transmission End User: Consumer Electronics, Automotive, Healthcare, Industrial Equipment Application: Charging Stations, Electric Vehicles, Medical Devices, Drones Installation: Fixed Systems, Portable Solutions, Integrated Designs, Smart Grids |
| Companies Covered | Energous Corporation, Texas Instruments Inc., Qualcomm Inc., Ossia Inc., Powermat Technologies Ltd., WiTricity Corporation, Semtech Corporation, Murata Manufacturing Co. Ltd., Samsung Electronics Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Power Transmission Market Strategic Shifts & Innovations
Software-defined power control is collapsing the traditional hardware boundary between transmitter and receiver architectures, enabling dynamic impedance matching that adapts to variable coil misalignment and foreign object intrusion.
GaN-based inverter modules are virtualizing the discrete component stack in high-frequency wireless power systems. Tier 1 automotive suppliers in South Korea and Germany are adopting these compact architectures for 22 kW passenger vehicle charging. The technology is virtualizing thermal management requirements and collapsing enclosure volume constraints that previously limited installation flexibility.
REACH substance restrictions on halogenated flame retardants are forcing coil assembly manufacturers to reformulate insulation materials and substrate coatings. The industrial consequence is a qualification bottleneck as suppliers retest dielectric performance under revised material compositions. Medical device manufacturers in Switzerland and the Netherlands face the steepest compliance ramps due to biocompatibility layering requirements.
Fleet operators are unbundling charging infrastructure procurement from vehicle acquisition contracts, treating wireless pads as dedicated utility assets with separate financing structures. This separation is displacing bundled OEM-service packages in municipal bus and logistics depot deployments. The shift is most visible in California and the Netherlands, where power purchase agreements for charging-as-a-service have proliferated.
Wireless Power Transmission Market Segmentation
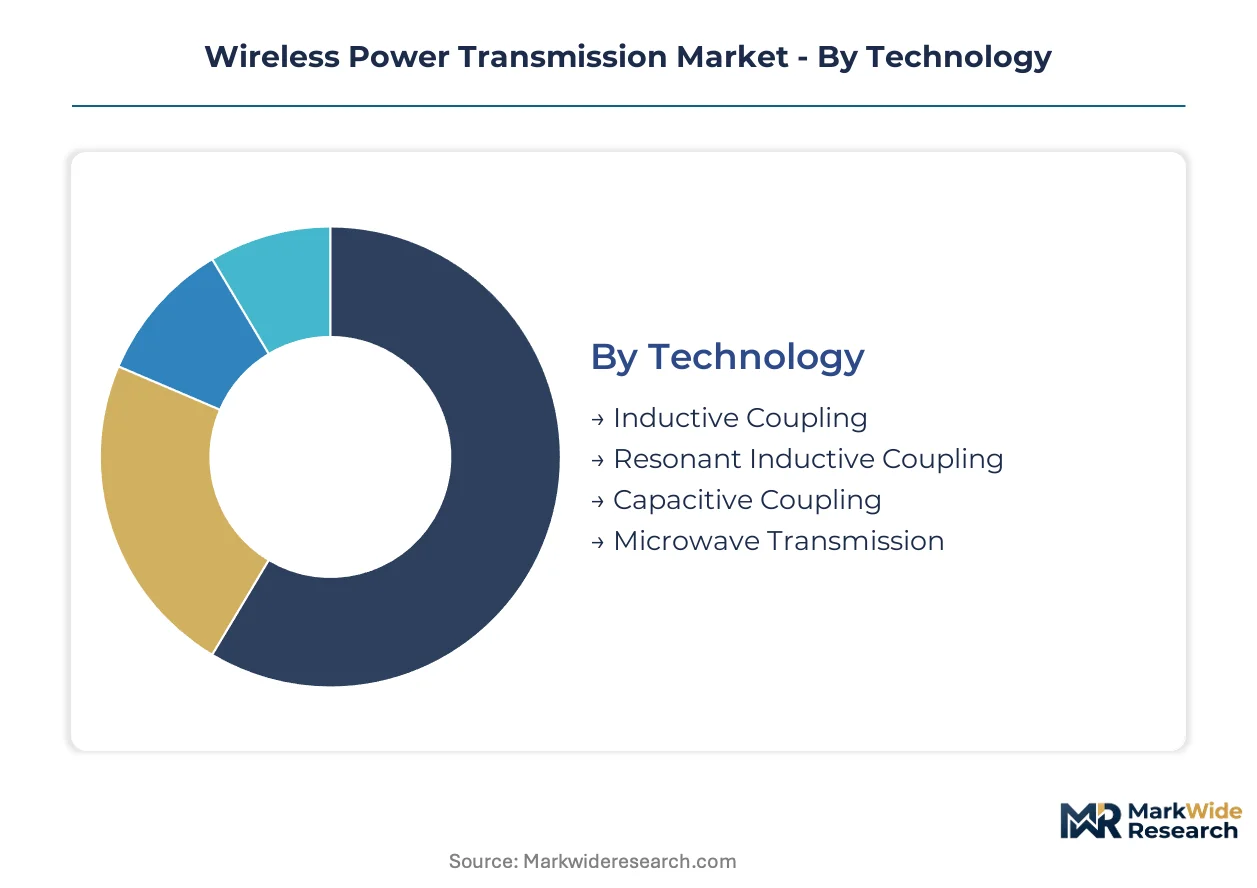
Technology heterogeneity in wireless power transmission demands precise segment targeting. Coil architectures, clearance specifications, and frequency bands vary dramatically across end-use environments from implantable medical devices to heavy-duty vehicle charging.
Technology:
After-sales service intensity escalates with system complexity—resonant architectures require field calibration that inductive systems rarely need.
- Inductive Coupling:Near-field energy transfer through tightly coupled coils operating below 300 kHz dominates Qi-certified consumer electronics. Smartphone and wearable manufacturers in China specify these systems for their mature certification pathways and minimal electromagnetic interference.
- Resonant Inductive Coupling:Loosely coupled coils tuned to matched frequencies enable charging across 10-25 cm air gaps. Automotive OEMs in Germany and the United States specify these architectures for under-vehicle pads where ground clearance varies by load.
- Capacitive Coupling:Electric field transmission through paired electrode plates suits compact, flat-surface applications. Industrial tool manufacturers favor these systems where metallic foreign objects would disturb magnetic fields.
- Microwave Transmission:Directed RF beamforming enables kilometer-range power delivery for unmanned aerial systems. Agricultural drone operators in Japan and Australia deploy these systems for beyond-visual-line-of-sight crop monitoring missions.
Inductive coupling holds the largest share; momentum sits with resonant inductive coupling.
End User:
Cost tier stratification separates premium automotive specifications from high-volume consumer electronics procurement.
- Consumer Electronics:Qi-compatible smartphones, earbuds, and wearables constitute the highest shipment volumes. Retail channel placement by electronics distributors in South Korea and the United States drives accessory ecosystem expansion.
- Automotive:Passenger and commercial vehicle integration demands multi-kilowatt systems with active foreign object detection. German premium OEMs now specify 11-22 kW pads as factory options on electric SUV platforms.
- Healthcare:Implantable devices and sterilizable surgical tools require biocompatible coil encapsulation. Swiss and Dutch manufacturers face steep REACH compliance ramps for halogen-free insulation materials.
- Industrial Equipment:Harsh-environment charging for automated guided vehicles and mining equipment prioritizes sealed, vibration-resistant architectures. Australian and Chilean mining operators specify these systems for dust-contaminated depots.
Consumer electronics captures the greatest volume; healthcare offers the steepest margin expansion trajectory.
Application:
Customer type divergence separates fleet operators seeking charging-as-a-service from individual consumers purchasing standalone pads.
- Charging Stations:Fixed infrastructure for public and workplace deployment integrates payment systems and grid communication protocols. Municipal tender specifications in California and the Netherlands now unbundle pad procurement from vehicle acquisition.
- Electric Vehicles:Passenger cars, buses, and light commercial vehicles specify ground-based or under-vehicle receiver coils. Chinese battery-electric bus fleets in Shenzhen and Beijing deploy opportunity charging at route terminals.
- Medical Devices:Implantable neurostimulators and external diagnostic equipment demand precise power telemetry. FDA Part 18 compliance and NMPA electromagnetic compatibility testing create dual-track certification requirements.
- Drones:Unmanned aerial systems for logistics and agriculture require lightweight receiver arrays. Japanese agricultural cooperatives test microwave beaming for extended crop-survey missions.
Charging stations dominate infrastructure investment; electric vehicles are climbing the fastest.
Installation:
Supply concentration in coil fabrication and power electronics assembly shapes regional deployment patterns.
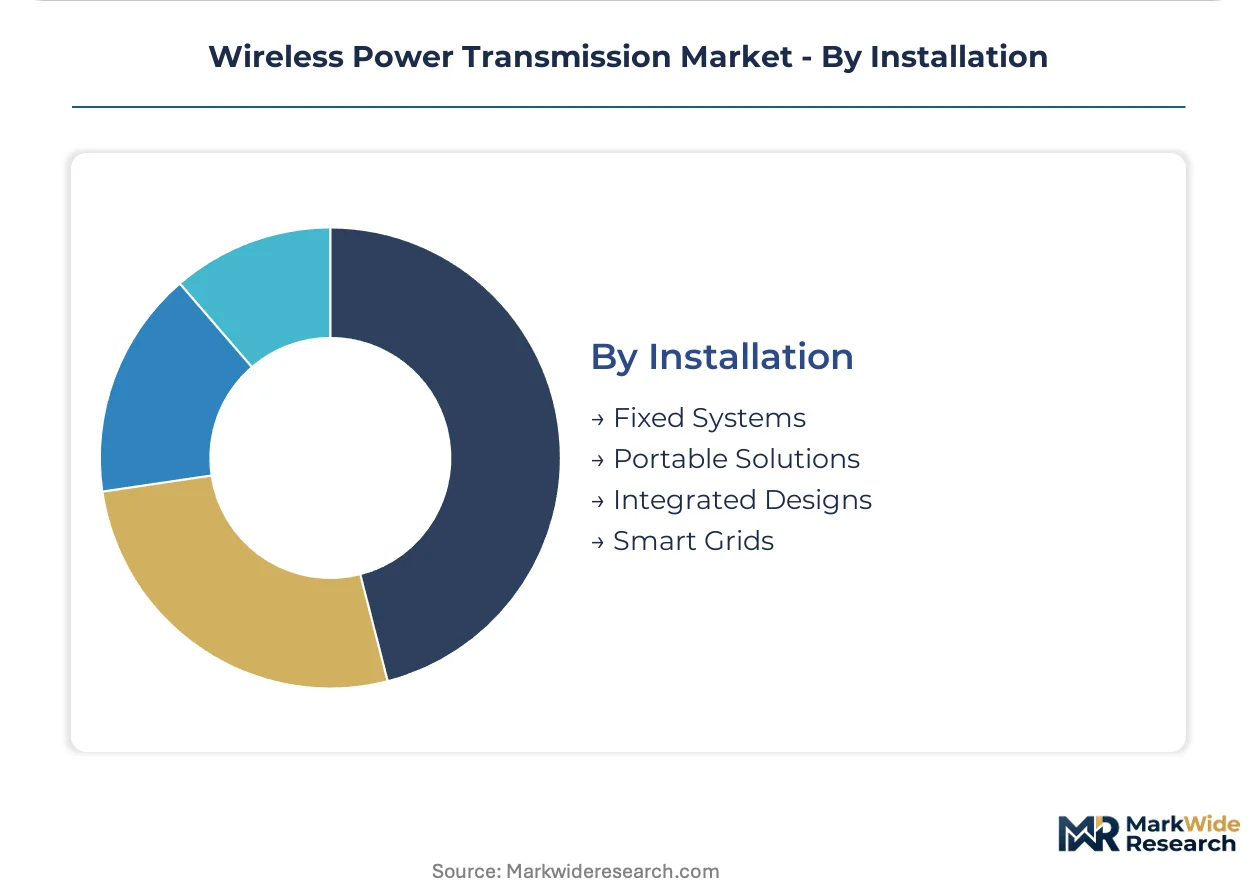
- Fixed Systems:Permanently embedded pads in parking structures, factory floors, and public curbside locations. German automotive suppliers integrate these into premium residential garage specifications.
- Portable Solutions:Mobile charging pads and temporary deployment kits for construction sites and emergency response. Indian medical device distributors favor these for rural clinic outreach programs.
- Integrated Designs:Receiver coils embedded directly into product chassis during manufacturing. South Korean electronics manufacturers embed these in television stands and furniture surfaces.
- Smart Grids:Bi-directional vehicle-to-grid systems with dynamic load balancing and utility communication. Dutch distribution network operators pilot these for peak-shaving in residential neighborhoods.
Fixed systems account for the majority of installed base; smart grids represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Public procurement incentives and carbon neutrality roadmaps are reconfiguring deployment patterns across major economies. Government-backed fleet electrification programs and tightening efficiency regulations are concentrating infrastructure investment in specific metropolitan clusters.
United States
FCC Part 18 compliance timelines and municipal fleet tenders are accelerating charging pad deployment. California's public utility commission has approved rate structures for wireless charging-as-a-service. The San Francisco Bay Area hosts pilot programs for bi-directional vehicle-to-grid integration in residential neighborhoods.
Germany
Premium automotive OEM specifications for 11-22 kW under-vehicle charging are driving component demand. The EU F-Gas Regulation mandates minimum efficiency thresholds for power electronics in charging infrastructure. Stuttgart and Munich anchor development clusters where Tier 1 suppliers retool coil fabrication lines.
China
NMPA electromagnetic compatibility standards and MIIT GB certification requirements are filtering market entry for foreign suppliers. Shenzhen and Beijing battery-electric bus fleets deploy opportunity charging at route terminals. The dual carbon goals framework prioritizes contactless infrastructure in municipal procurement.
Japan
METI carbon neutrality roadmaps are steering public procurement toward contactless charging for municipal bus and taxi electrification. Agricultural cooperatives test microwave beaming systems for extended drone crop-survey missions. Nagoya and Osaka manufacturing belts concentrate GaN inverter module assembly.
Netherlands
Unbundled charging infrastructure procurement from vehicle acquisition is displacing bundled OEM-service packages in municipal tenders. Distribution network operators pilot smart grid peak-shaving systems in residential neighborhoods. Rotterdam and Amsterdam host power purchase agreement structures for charging-as-a-service.
Wireless Power Transmission Market Key Industry Players
Channel-controlling players compete with product-specialist players across distinct value capture layers. The market exhibits tiered concentration with patent-holding licensors, component fabricators, and systems integrators occupying separate margin pools. Two strategic archetypes dominate: magnetic resonance IP licensors extracting royalties from automotive OEMs, and captive semiconductor manufacturers supplying integrated coil drivers. Competitive moves center on technology licensing negotiations and backward integration into coil fabrication capacity.
Within the IP-licensor archetype, WiTricity Corporation occupies a position anchoring automotive magnetic resonance negotiations. Texas Instruments Inc. exemplifies the captive semiconductor model through in-house production of power management chipsets. Samsung Electronics Co. Ltd. represents channel-control leverage through retail placement of Qi-compatible devices.
| Leading Market Players |
|---|
| Energous Corporation |
| Texas Instruments Inc. |
| Qualcomm Inc. |
| Ossia Inc. |
| Powermat Technologies Ltd. |
| WiTricity Corporation |
| Semtech Corporation |
| Murata Manufacturing Co. Ltd. |
| Samsung Electronics Co. Ltd. |
| Others |
Cost & Logistics Intelligence
Overcapacity in Chinese coil fabrication facilities is compressing component pricing while simultaneously eroding supplier negotiating leverage with automotive OEMs. This utilization dynamic forces Tier 2 suppliers to absorb margin pressure from raw material volatility rather than pass through costs.
Pricing Analysis
Certification level (FCC Part 18/CE/GB-standard) creates the primary spread between premium resonant automotive systems and economy-grade Qi consumer pads. Licensing royalty stacks for magnetic resonance IP add 15-25 percentage points to landed costs for non-captive manufacturers. Cost compression in the consumer electronics tier is intensifying because Chinese accessory manufacturers are flooding retail channels with uncertified alternatives. Fleet operators demonstrate the lowest price sensitivity due to charging-as-a-service financing structures that amortize hardware across operational leases.
Supply Chain Analysis
Foxconn, Luxshare Precision, and BYD Electronics hold the dominant contract-manufacturing capacity for coil driver assembly and power module integration. China, Vietnam, and Mexico anchor coil winding and ferrite core processing, with Germany retaining specialized automotive validation testing. Copper and ferrite supply draws from concentrated Chinese mining and processing operations, creating tariff exposure to export quota fluctuations. Distribution runs through electronics distributors in South Korea and the United States for consumer segments, while automotive channels feed directly into Tier 1 supplier integration plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation in municipal bus and logistics depot procurement is shifting bargaining power toward buyers who unbundle charging infrastructure from vehicle acquisition. This fragmentation among incumbent OEM-service packages creates entry openings for independent charging-as-a-service providers.
For Market Incumbents: Pre-empt patent licensing fragmentation by consolidating magnetic resonance IP pools through cross-licensing consortia before university-held patents expire into open competition. Backward integration into GaN inverter module fabrication in South Korea or Germany defends margin position against semiconductor foundry concentration. FCC Part 18 certification investment creates switching costs that bind fleet operators to validated system architectures. For New Entrants and Emerging Players: Mid-market commercial vehicle depots in India and Southeast Asia represent the most penetrable entry point, as PLI scheme incentives reduce capital barriers for coil driver assembly. Portable medical charging solutions for rural clinic outreach programs in Africa and South Asia offer white-space expansion with minimal incumbent presence. A licensing-plus-hardware hybrid go-to-market model accelerates regulatory clearance without requiring full manufacturing scale. For Investors and Strategic Acquirers: Capital is best deployed toward captive semiconductor manufacturers with in-house power management chipset production and existing automotive qualification pathways. The acquisition target archetype combines magnetic resonance IP holdings with established Tier 1 supplier relationships. Watch for inflection signals in municipal tender unbundling rates, as charging-as-a-service contract proliferation indicates infrastructure asset valuation decoupling from vehicle OEM balance sheets.| Strategic Initiative | Industry Significance |
|---|---|
| Patent Portfolio Consolidation | Cross-licensing magnetic resonance IP reduces royalty stack complexity for automotive OEM negotiations. |
| GaN Inverter Module Investment | South Korean and German foundry partnerships collapse thermal management constraints in 22 kW systems. |
| FCC Part 18 Pre-Certification | Early regulatory validation compresses twelve-to-eighteen month launch timelines for foreign market entry. |
| Charging-as-a-Service Platform | Unbundled infrastructure financing in California and Netherlands municipalities displaces bundled OEM-service packages. |
| REACH-Compliant Material Reformulation | Halogen-free insulation qualification opens Swiss and Dutch medical device procurement channels. |
Research Approach
A spread of perspectives from automotive platform engineers, Tier 1 supplier procurement leads, charging infrastructure project developers, and FCC compliance consultants converged on the working assumptions. Primary fieldwork with coil fabrication plant managers and power electronics R&D directors was cross-referenced against secondary validation from SEC filings, MIIT GB standard documentation, EU F-Gas Regulation impact assessments, and IEA electrification deployment databases. Bottom-up shipment modeling and top-down infrastructure investment tracking were reconciled through iterative triangulation.
Demand-supply balance framing anchored the analytical framework, with adoption curves for resonant versus inductive architectures modeled across the projection horizon. Segmentation dimensions included technology type, end-user vertical, application environment, and installation configuration, with additional granularity on certification tier and power rating. CAGRs were derived from installed base accumulation rates and replacement cycle assumptions, incorporating GaN cost-down curves and copper price volatility scenarios as sensitivity inputs.
Stress conditions across FCC Part 18 compliance timeline extensions, Chinese export quota fluctuations, and silicon carbide wired charging substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on fleet electrification policy continuity and interoperability standard convergence. Quarterly review of municipal tender unbundling rates, NMPA certification queue lengths, and GaN foundry utilization indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Flexible AC Transmission Systems Market
Transmission and Distribution
Europe Active Network Management Market
Transmission and Distribution
Japan High Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Fuse Rails Market
Transmission and Distribution
Substation Monitoring System Market
Transmission and Distribution
United States High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
High Voltage Distribution Substation Market
Transmission and Distribution
Transmission Line Market
Transmission and Distribution
Asia Pacific LNG Infrastructure Market
Transmission and Distribution
Global Load Break Switch Market
Transmission and Distribution
Submarine Electricity Transmission Systems Market
Transmission and Distribution
Southeast Asia Power Transmission and Distribution Market
Transmission and Distribution
Power Transmission Cables Market
Transmission and Distribution
Pipeline Services Market
Transmission and Distribution
Gas Insulated Substation Market
Transmission and Distribution
United Kingdom High-Voltage Direct Current (HVDC) Transmission Systems Market