
 AR in Retail Market | 2026-2036
AR in Retail Market Size, Share, and Industry Trends Forecast 2026-2036
AR in Retail Market Analysis
Enterprise buyers in furniture and electronics categories is bifurcating away from boutique pilot budgets toward scaled deployment mandates. Apple leverages its spatial computing ecosystem to anchor premium retail partnerships. Meta competes through open-platform AR tools that sustain developer density across mid-market brands. Nike differentiates by controlling end-to-end virtual try-on workflows that merge body-scan accuracy with direct-to-consumer checkout.
Augmented reality in retail overlays computer-generated imagery onto physical store environments or consumer devices, typically operating through camera-fed SLAM tracking with sub-10 millimeter spatial anchoring precision to reduce product return rates and extend dwell time. Mobile Apps currently dominate transaction volume because every smartphone becomes an instant deployment surface without hardware capex. Cloud-Based Systems represent the fastest-expanding integration level, since centralized rendering pipelines let retailers update 3D asset libraries across thousands of endpoints simultaneously. Markerless technology leads R&D allocation as computer vision advances eliminate the need for printed triggers or dedicated floor markers.
FDA oversight applies where AR interfaces integrate with biometric measurement tools for virtual fitting, while the EU AI Act imposes conformity assessments on algorithmic recommendation engines embedded in immersive shopping experiences. The FCC governs spectrum allocation for in-store AR displays operating on millimeter-wave or Wi-Fi 6E backbones. Stakeholders must decide whether to build captive spatial computing teams or rely on platform providers whose roadmap priorities may diverge from retail-specific use cases.
Market Dynamics
Spatial computing platforms are forcing retailers to choose between proprietary ecosystems and open AR development frameworks, compressing deployment timelines while fragmenting vendor relationships across the value chain.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic transparency requirements for immersive shopping interfaces are accelerating standardization investments among mid-market apparel chains.
- Cloud-based rendering pipelines:Centralized 3D asset management is enabling simultaneous updates across thousands of retail endpoints without hardware replacement cycles.
- Clothing retailer adoption clusters:Virtual try-on deployment in the United States and Germany is creating reference architectures that adjacent verticals replicate.
Market Restraints
- 3D asset production costs:Photogrammetry and manual modeling workflows for product digitization consume 40-60% of initial AR program budgets.
- Platform dependency risk:Spatial computing roadmap priorities controlled by Apple and Meta may diverge from retail-specific feature requirements.
- Millimeter-wave spectrum scarcity:FCC allocation constraints limit in-store AR display density for high-fidelity immersive experiences.
Strategic Opportunities
- Underpenetrated grocery and CPG segments:Shelf-scanning and nutritional visualization AR remains below 5% adoption among top 50 global food retailers.
- Convergence of SLAM tracking with edge AI:On-device inference is reducing latency for markerless spatial anchoring below 10 milliseconds.
- India PLI scheme for electronics manufacturing:Domestic component production incentives are lowering hardware costs for AR-enabled point-of-sale terminals.
Industry Challenges
- Spatial computing talent scarcity:Computer vision engineers with retail application experience command 2-3x standard software development salaries.
- Legacy POS integration complexity:AR checkout workflows require API reconstruction with 15-20 year old transaction processing architectures.
- FDA biometric measurement compliance:Virtual fitting tools integrating body-scan data face 12-18 month pre-market notification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AR in Retail Market |
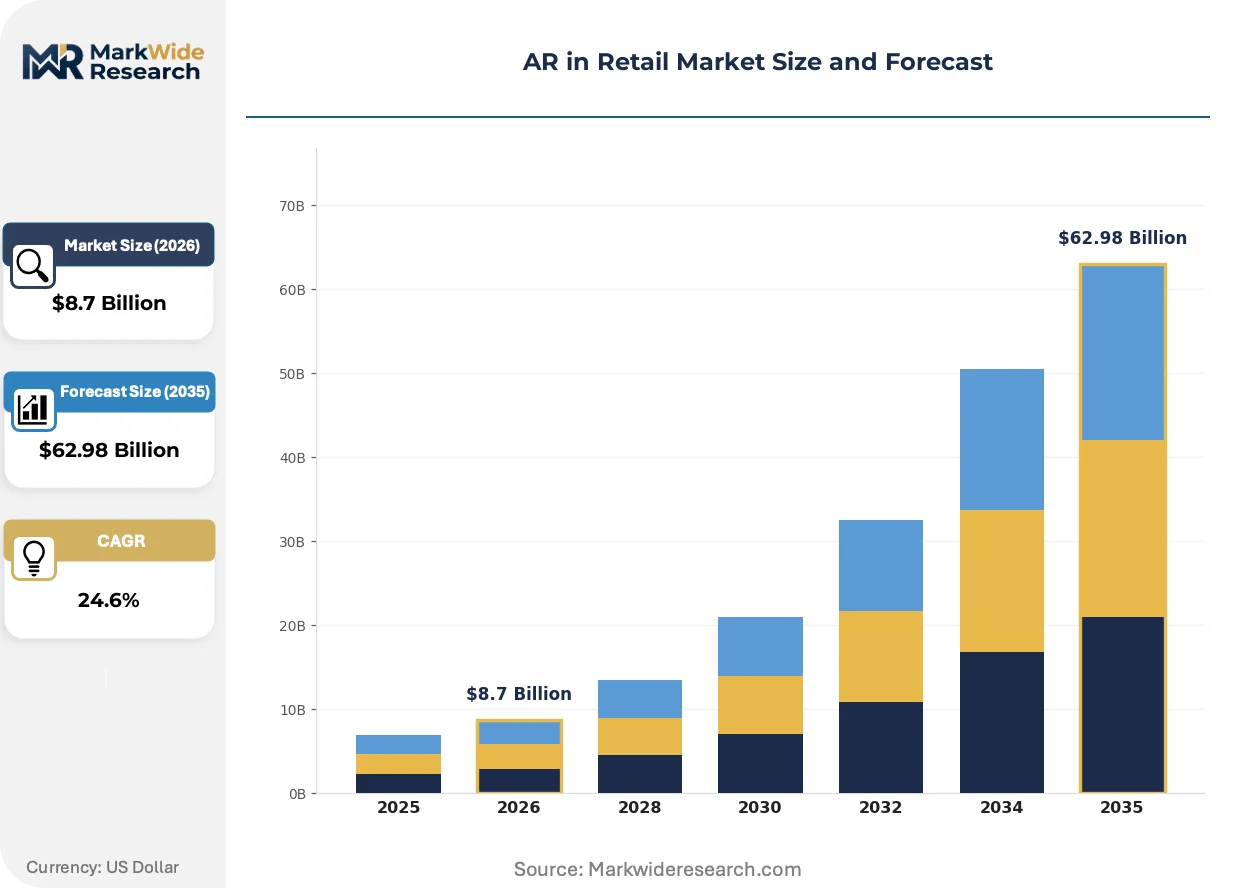
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $62.98 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AR Glasses, Mobile Apps, In-Store Displays, Virtual Mirrors Technology: Marker-Based, Markerless, Projection-Based, Superimposition End User: Clothing Retailers, Electronic Stores, Furniture Outlets, Grocery Chains Integration Level: Standalone Solutions, API-Integrated, Cloud-Based Systems, Multi-Channel Platforms |
| Companies Covered | Apple, Google, Microsoft, Meta, Shopify, Samsung Electronics, Magic Leap, Vuzix, Nike, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AR in Retail Market Emerging Trajectories
Retail AR is pivoting from novelty deployment toward operational infrastructure, with spatial computing investments now evaluated against same-store sales lift and return rate reduction metrics rather than brand perception alone.
Markerless SLAM technology is fragmenting hardware requirements across the retail stack. Computer vision advances eliminate printed triggers and dedicated floor markers, allowing deployment on existing smartphone cameras and in-store security systems. Department store chains in Japan and South Korea are adopting this architecture fastest, compressing pilot-to-scale timelines from 18 months to under 6 months.
The EU AI Act conformity assessment framework is reshaping algorithmic accountability for immersive shopping. Recommendation engines embedded in AR interfaces must now document training data provenance and decision logic for market surveillance authorities. French and German luxury retailers are pre-emptively restructuring their virtual try-on pipelines to satisfy these documentation requirements before the 2026 enforcement deadline.
Buyer concentration among clothing retailers is compressing vendor negotiation cycles. Virtual try-on procurement now flows through centralized innovation teams rather than dispersed brand managers, consolidating annual contract values with preferred AR platform providers. This pattern is most visible in the United States, where flagship experience deployments at hundreds of store locations have created template contracts that regional chains adopt with minimal modification.
AR in Retail Market Segmentation
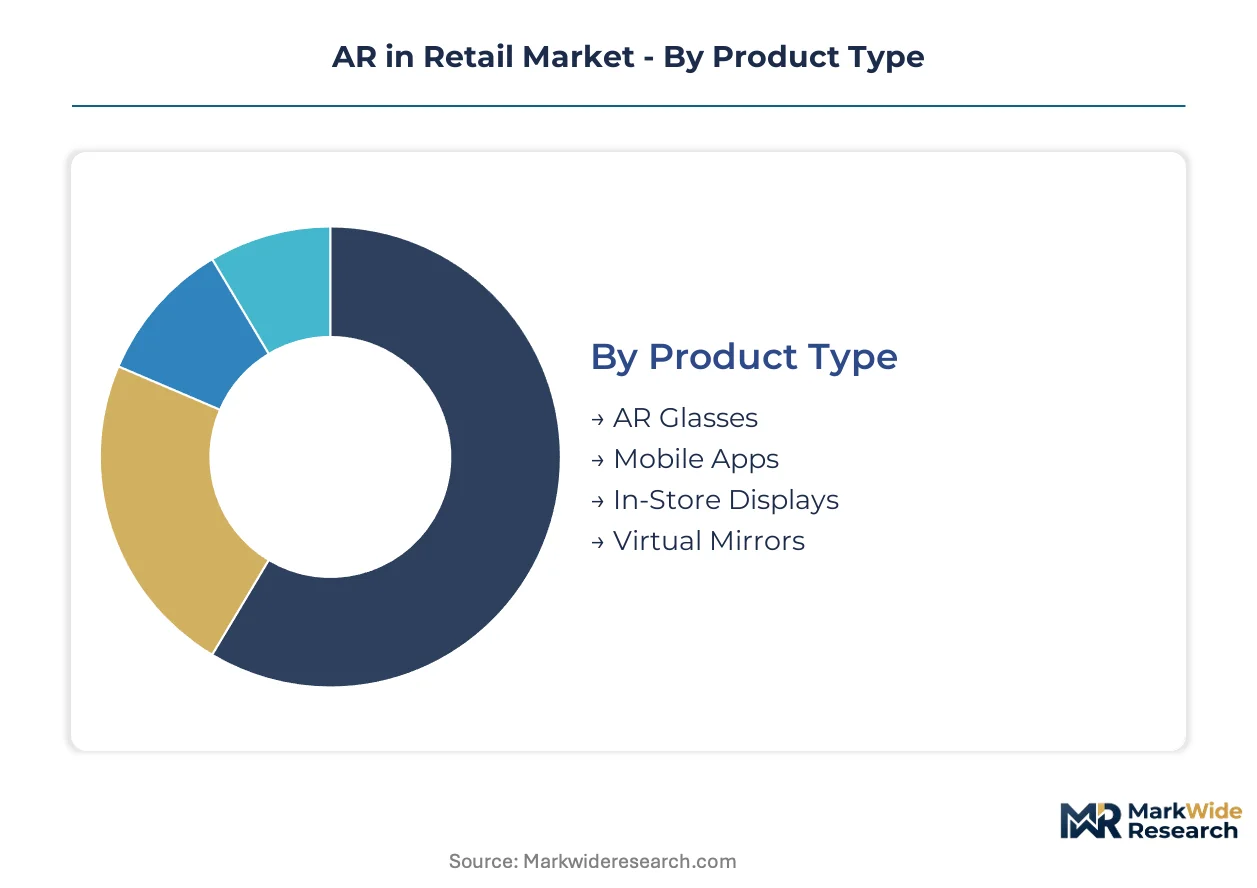
AR retail deployments fragment across hardware form factors, tracking methodologies, and backend integration architectures. Each segmentation axis carries distinct regulatory exposure and capital intensity profiles that shape procurement patterns.
Product Type:
FDA scrutiny falls most heavily on biometric-enabled hardware, while mobile deployments escape pre-market notification requirements entirely.
- AR Glasses:Head-worn displays with optical waveguide engines deliver hands-free inventory navigation and immersive product visualization. Deployment concentrates in flagship electronics stores across Germany and Japan, constrained by FCC and METI radio-frequency certification timelines.
- Mobile Apps:Camera-fed SLAM tracking on iOS and Android devices processes spatial anchoring without dedicated hardware capex. Clothing retailers in the United States drive procurement volume, prioritizing virtual try-on modules that reduce return rates.
- In-Store Displays:Fixed-location screens with depth sensors enable collaborative shopping experiences.
- Virtual Mirrors:Wall-mounted panels with integrated body-scanning cameras face FDA oversight when capturing biometric measurements.
Established volume favors Mobile Apps; emerging adoption favors AR Glasses.
Technology:
Computer vision maturity determines whether retailers must maintain printed trigger infrastructure or deploy on existing surfaces.
- Markerless:Simultaneous localization and mapping algorithms anchor digital content to arbitrary environmental features without prepared markers. R&D allocation concentrates here as SLAM latency drops below 10 milliseconds through edge AI inference.
- Marker-Based:Printed QR codes or proprietary glyphs provide deterministic spatial reference points with minimal processing overhead. Grocery chains retain this architecture for price-scanning applications where precision requirements remain modest.
- Projection-Based:Spatial light modulators cast imagery directly onto physical surfaces.
- Superimposition:Real-time occlusion handling layers virtual objects behind physical geometry.
Development investment concentrates on Markerless; legacy stability sustains Marker-Based.
End User:
Return-rate economics vary dramatically across product categories, reshaping AR business case thresholds.
- Clothing Retailers:Virtual fitting rooms with body-scan accuracy below 10 millimeters reshape purchase confidence and reduce return processing costs. Flagship deployments across hundreds of United States store locations now serve as reference architectures for mid-market chains.
- Furniture Outlets:Room-scale spatial anchoring lets consumers visualize dimensional products in their actual living spaces. German and South Korean department store chains compress pilot-to-scale timelines fastest here.
- Electronic Stores:Specification overlay and comparison tools dominate use cases.
- Grocery Chains:Shelf-scanning and nutritional visualization applications remain below 5% adoption among top 50 global food retailers.
Procurement maturity favors Clothing Retailers; whitespace opportunity concentrates in Grocery Chains.
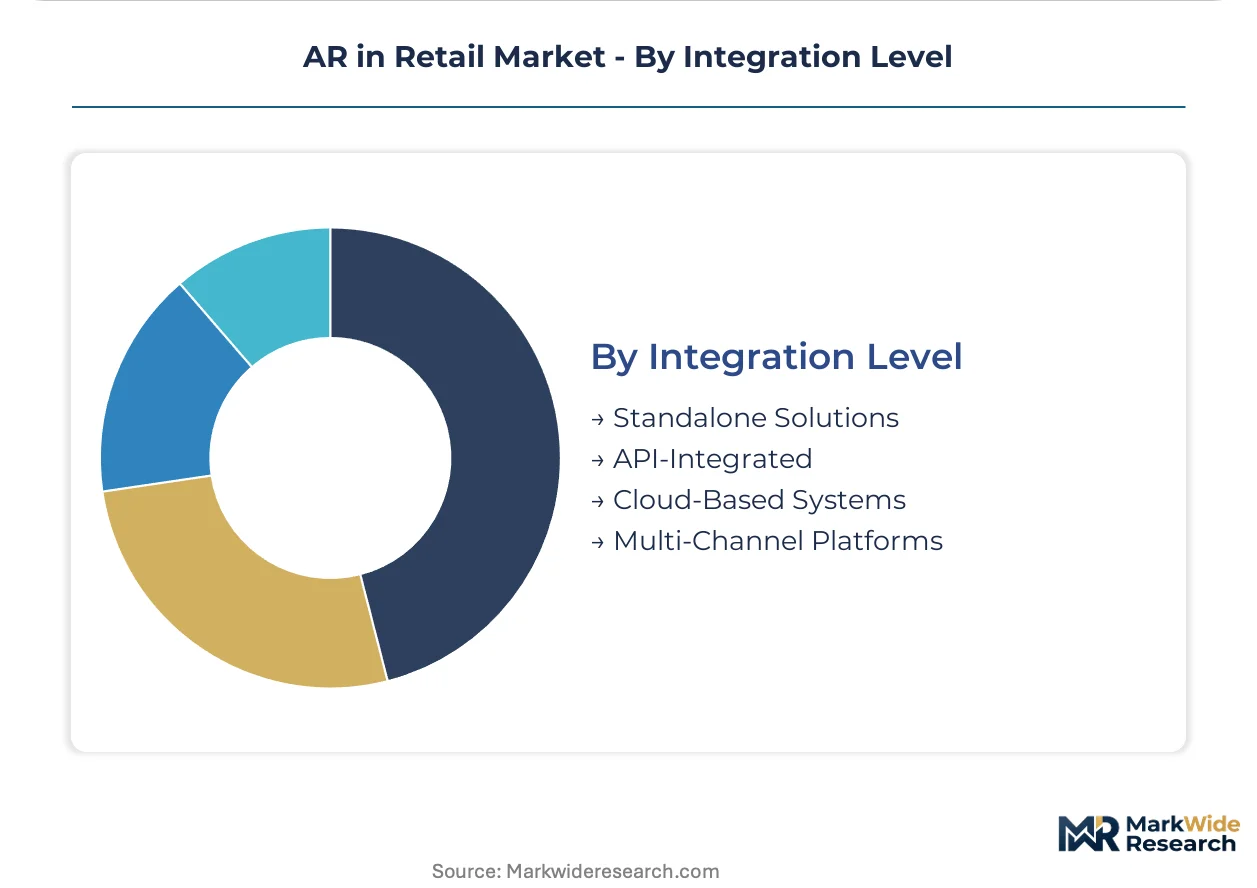
Integration Level:
Backend architecture determines update velocity and vendor lock-in exposure across distributed retail footprints.
- Cloud-Based Systems:Centralized rendering pipelines synchronize 3D asset libraries across thousands of endpoints simultaneously. French and German luxury retailers prioritize this architecture to satisfy EU AI Act documentation requirements for algorithmic recommendation engines.
- API-Integrated:Middleware connections to existing e-commerce stacks preserve legacy transaction processing while adding spatial visualization layers.
- Standalone Solutions:Self-contained deployments operate without external data dependencies.
- Multi-Channel Platforms:Unified orchestration across mobile, web, and in-store touchpoints demands complex synchronization logic.
Operational flexibility favors Cloud-Based Systems; integration simplicity sustains API-Integrated.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spatial computing infrastructure investment clusters in the United States, Germany, and Japan, where flagship retail deployments attract vendor engineering resources and compress implementation timelines. The EU AI Act is accelerating standardization investments among mid-market apparel chains in France and Germany. India PLI scheme incentives are lowering hardware costs for AR-enabled point-of-sale terminals.
United States
Clothing retailers drive procurement volume through centralized innovation teams consolidating annual contracts with preferred AR platform providers. The FCC governs spectrum allocation for in-store AR displays operating on millimeter-wave or Wi-Fi 6E backbones. Flagship experience deployments across hundreds of store locations in New York, Los Angeles, and Chicago now serve as reference architectures that regional chains adopt with minimal modification.
Germany
French and German luxury retailers prioritize cloud-based systems to satisfy EU AI Act documentation requirements for algorithmic recommendation engines. ECHA REACH compliance overlays additional substance restrictions on hardware components with optical waveguide engines. Department store chains in Berlin and Munich are adopting markerless SLAM architecture fastest, compressing pilot-to-scale timelines from 18 months to under 6 months.
Japan
METI radio-frequency certification timelines constrain deployment of head-worn displays with optical waveguide engines in flagship electronics stores. Computer vision advances eliminate printed triggers, allowing deployment on existing smartphone cameras and in-store security systems. Tokyo and Osaka retail clusters are replicating reference architectures from German and United States clothing retailer deployments.
India
Domestic component production incentives under the India PLI scheme for electronics manufacturing are lowering hardware costs for AR-enabled point-of-sale terminals. BIS standards apply to imported optical components and depth sensors. Mumbai and Bangalore retail technology clusters are attracting vendor engineering resources for cloud-based rendering pipeline development.
South Korea
MFDS oversight applies where AR interfaces integrate with biometric measurement tools for virtual fitting applications. Computer vision maturity is eliminating printed trigger infrastructure requirements across Seoul retail deployments. Department store chains in Seoul are adopting markerless SLAM technology fastest after Japanese and German counterparts.
AR in Retail Market Vendor Landscape
Concentration sits with platform providers controlling spatial computing ecosystems, with Apple and Meta capturing premium and mid-market deployment channels respectively. Three strategic archetypes dominate: ecosystem gatekeepers with proprietary hardware-software stacks, open-platform enablers sustaining developer density, and vertical specialists controlling end-to-end workflows. Competitive moves center on strategic partnerships with flagship retailers and technology licensing to compress implementation timelines.
Within the ecosystem gatekeeper tier, Apple and Meta exemplify divergent platform philosophies, with the former anchoring premium retail partnerships through spatial computing integration and the latter competing through open-platform AR tools. Google occupies a position bridging mobile deployment surfaces with cloud-based rendering infrastructure. Among vertical specialists, Nike represents end-to-end workflow control, merging body-scan accuracy with direct-to-consumer checkout capabilities.
| Leading Market Players |
|---|
| Apple |
| Microsoft |
| Meta |
| Shopify |
| Samsung Electronics |
| Magic Leap |
| Vuzix |
| Nike |
| Others |
Supply Flow & Price Mechanics
Cloud-based rendering pipelines substituting for on-premise GPU clusters simultaneously redistribute supply geography toward centralized hyperscaler regions and compress pricing economics for mid-market clothing retailers in Germany and the United States. This substitution dynamic fragments hardware procurement patterns while concentrating software licensing leverage with platform providers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates AR retail deployments. Price differentiation hinges on SLAM latency performance and EU AI Act compliance documentation depth. Cost compression in standard-tier subscriptions is intensifying because cloud rendering commoditizes baseline spatial anchoring capabilities. Clothing retailers in the United States exhibit highest price sensitivity, while French and German luxury houses prioritize compliance-grade premiums.
Supply Chain Analysis
Taiwanese optical waveguide foundries and South Korean depth sensor fabs constitute critical chokepoints for AR Glasses production. Component sourcing draws from Chinese lithium polymer cell manufacturers, Japanese precision lens suppliers, and German automotive-grade sensor specialists. Single-source vulnerability concentrates in waveguide etching equipment. Distribution runs through hyperscaler cloud marketplaces and direct OEM procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among United States clothing retailers through centralized innovation teams, compressing vendor negotiation cycles and consolidating annual contract values with preferred platform providers.
For Market Incumbents: Secure exclusive cloud rendering partnerships with flagship retail chains before open-platform alternatives commoditize spatial computing infrastructure. Deepen backward integration into 3D asset production pipelines to offset photogrammetry cost inflation. Counter Meta's developer density strategy by controlling end-to-end virtual try-on workflow integration. For New Entrants and Emerging Players: Lead with shelf-scanning AR modules for grocery chains in India and South Korea where adoption sits below 5% among top 50 global food retailers. Prioritize API-first architectures that bypass legacy POS reconstruction complexity. Target mid-market apparel chains in Japan seeking compressed pilot-to-scale timelines. For Investors and Strategic Acquirers: The market sits at a standardization phase that favors vertical specialists with captive body-scan accuracy IP and direct checkout integration. Long-term viability across the projection horizon rests on controlling algorithmic recommendation engine documentation for EU AI Act pre-certification. Monitor FDA pre-market notification timelines for biometric-enabled virtual fitting tools as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Rendering Partnership | Centralized 3D asset pipelines satisfy EU AI Act documentation requirements for French luxury retailers. |
| Markerless SLAM Acquisition | Edge AI inference capabilities compress latency below 10 milliseconds for Japanese department store chains. |
| Biometric Compliance Investment | FDA pre-market notification pathways secure 12-18 month lead times for virtual fitting deployments. |
| Grocery White-Space Entry | Shelf-scanning AR modules address underpenetrated segments among Indian and South Korean food retailers. |
| Legacy POS API Reconstruction | Middleware integration overcomes 15-20 year old transaction architecture barriers for cloud-based checkout. |
Methodological Framework
Initial hypotheses were tested against primary input from spatial computing engineering leads, retail innovation directors, platform partnership managers, and computer vision researchers, then refined against secondary validation from SEC hyperscaler capex disclosures, App Annie mobile SDK adoption data, FDA 510(k) clearance databases, and EU AI Act implementation guidance documents. Bottom-up endpoint deployment counts triangulated against top-down cloud infrastructure spend allocations.
Variance decomposition across hardware form factors, tracking methodologies, backend integration architectures, and geographic regulatory clusters shaped the analytical framework throughout the forecast period. CAGRs derived from logistic diffusion curves fitted to flagship deployment timelines and mid-market replication patterns. Industry-specific inputs included SLAM latency benchmarks, 3D asset production cost curves, and spectrum allocation constraints from FCC filings.
Forecasts assume regulatory continuity in EU AI Act enforcement regimes and FDA biometric oversight pathways; material policy shifts would require re-modeling algorithmic transparency timelines and pre-market notification procedures. Practitioners should keep alternative scenarios live as cloud rendering cost curves and edge AI inference capabilities evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retail Technology
US Retail Recon Software Market
Retail Technology
Retail-As-A-Service (Raas) Market
Retail Technology
Omni-Channel Retail Solutions Market
Retail Technology
Enterprise Mobility in Retail Market
Retail Technology
Smart Shelf Market
Retail Technology
United States Grocery and Pharmacy Point of Sale (POS) Terminal Market
Retail Technology
Retail Sourcing and Procurement Market
Retail Technology
Smart Kitchen Solutions Market
Retail Technology
Selfservice Technologies Market
Retail Technology
Cash Register Machines Market
Retail Technology
Digital Kiosk Market
Retail Technology
Self-Checkout in Retail Market
Retail Technology
Connected Retail Market
Retail Technology
North America Automation in Retail Market
Retail Technology
Smart Grocery Cart Market
Retail Technology
Smart Retail Systems Market