
 Argentina Food Colorants Market | 2026-2036
Argentina Food Colorants Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Food Colorants Market Outlook
Reformulation services and clean-label consulting is realigning how colorant suppliers capture value in Argentina. Chr Hansen Holdings leverages its fermentation-derived pigment portfolio to anchor natural color supply for dairy processors. Sensient Technologies Corporation competes through application-specific technical support that sustains loyalty among beverage formulators. BASF Argentina dominates synthetic color distribution by controlling import logistics and local blending capacity for confectionery clients.
Food colorants comprise pigments and dyes—whether anthocyanin extracts, caramelized sugars, or azo compounds—that impart, enhance, or restore visual appeal in processed foods, typically dosed at 0.01% to 0.5% by weight depending on substrate and light stability requirements. Natural Colors leads product type demand as Argentine consumers reject synthetic alternatives, though Caramel Colors retains volume leadership in soft drinks and spirits. Powder form concentrates margin pools in industrial bakeries where shelf stability and precise dosing reduce waste, while Liquid form grows fastest in beverage lines seeking streamlined batch processing.
ANMAT enforces Mercosur food additive harmonization that restricts certain synthetic dyes and mandates labeling disclosures, directly steering manufacturers toward natural and caramel-based alternatives. The country's national standards body, IRAM, certifies colorant purity grades that determine eligibility for export to Brazil and other Mercosur partners. Stakeholders must monitor pending ANMAT consultations on titanium dioxide and azo compound restrictions to anticipate reformulation timelines and inventory transitions.
Market Dynamics
ANMAT's Mercosur-aligned tightening of synthetic dye approvals is forcing Argentine food manufacturers into accelerated reformulation cycles, restructuring procurement relationships and technical service dependencies across the colorant supply base.
Growth Catalysts
- Clean-label mandates:ANMAT's disclosure requirements for synthetic additives are pushing dairy and confectionery processors toward anthocyanin and betalain-based alternatives. Reformulation contracts now bundle colorant supply with technical validation services.
- Premium bakery expansion:Patisserie chains in Buenos Aires and Córdoba are specifying natural colorant grades certified for export to Brazil. This creates pull-through demand for IRAM-certified pigment suppliers.
- Fermentation-derived pigments:Advances in microbial production of carotenoids and phycocyanins are reducing cost premiums versus synthetic equivalents. Dairy processors are adopting these for aged cheese rind applications.
Market Restraints
- Beetroot and grape input volatility:Argentine agricultural output fluctuations for natural colorant feedstocks create margin compression for extract processors. Drought cycles in Mendoza directly affect anthocyanin supply security.
- Import dependency for specialty synthetics:Tariff structures and foreign exchange constraints limit domestic blending capacity for azo compounds still permitted under Mercosur standards. Confectionery clients face extended lead times.
- Light stability limitations:Natural colorants degrade faster than synthetic alternatives in transparent beverage packaging. This technical ceiling restricts penetration in retail-ready soft drink lines.
Strategic Opportunities
- Underpenetrated northwest provinces:Salta and Tucumán food processors remain underserved by technical colorant distributors. Local blending facilities could capture artisanal confectionery and regional spirits markets.
- Clean-label convergence with organic certification:SENASA organic standards for processed foods create dual-certification demand. Colorant suppliers bundling organic and natural claims command pricing premiums in export-oriented segments.
- E-commerce ingredient platforms:Direct procurement portals for small-batch bakeries and craft breweries are bypassing traditional distributor networks. Digital channels enable technical documentation and sample fulfillment at lower transaction costs.
Industry Challenges
- Reformulation chemist scarcity:Argentine universities produce limited specialists in natural colorant stability and substrate interaction. Food manufacturers compete for talent with pharmaceutical and cosmetic sectors.
- Dual certification timelines:Simultaneous ANMAT approval and IRAM purity certification for export eligibility extends product launch cycles. Inventory transitions require parallel stockholding that strains working capital.
- Legacy equipment incompatibility:Powder-to-liquid conversion systems in older beverage plants cannot handle high-viscosity natural colorant concentrates. Capital retrofit requirements delay adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Food Colorants Market |
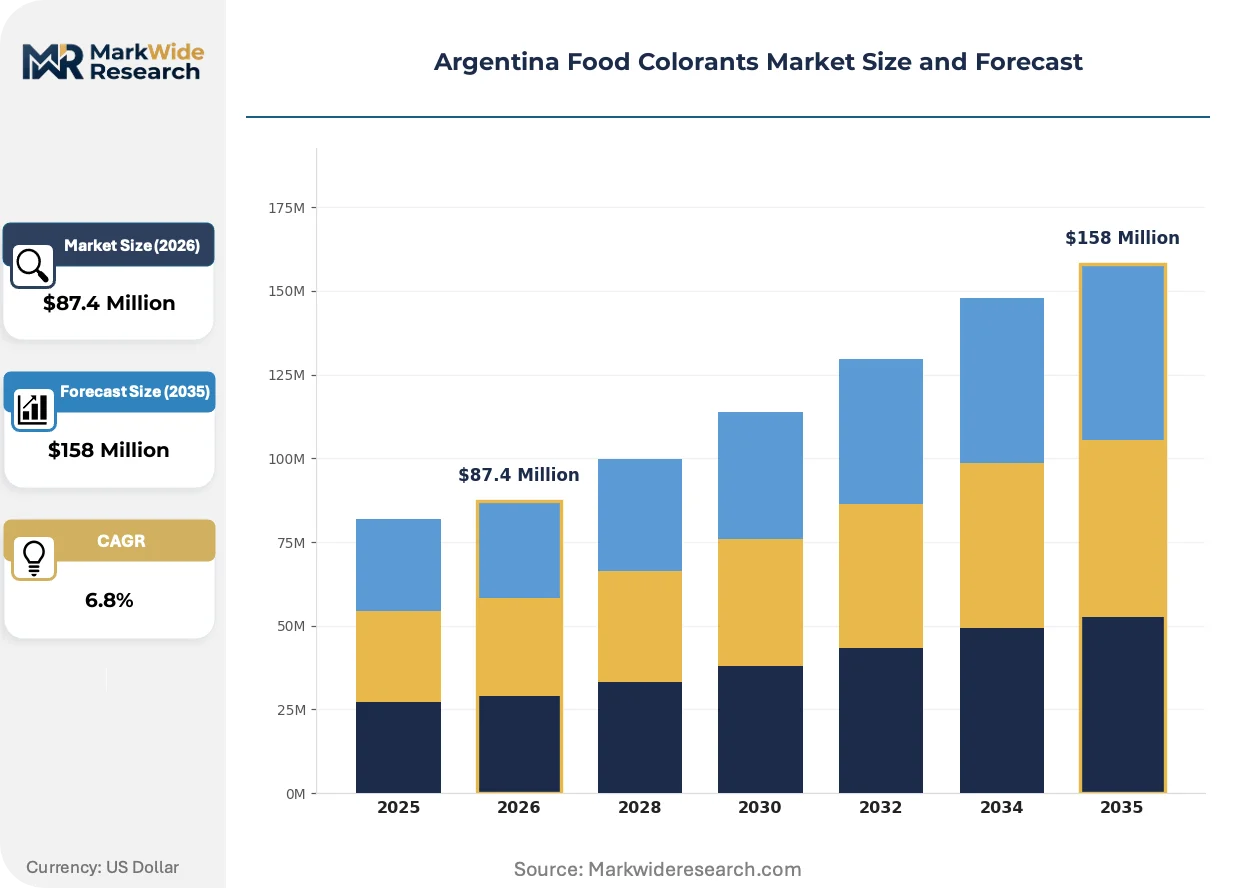
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Colors, Synthetic Colors, Caramel Colors, Lake Colors Application: Beverages, Dairy Products, Bakery, Confectionery Form: Liquid, Powder, Gel, Granular End User: Food Manufacturers, Beverages Industry, Confectionery Makers, Restaurants |
| Companies Covered | Chr Hansen Holdings, D.D. Williamson & Co., Kalsec Inc, Michrom, Sensient Technologies Corporation, Red Sun Dye Chem, Koninklijke DSM N.V., Kerry Group, BASF Argentina, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Food Colorants Market Strategic Shifts
Microencapsulation technologies and fermentation-based pigment production are restructuring how Argentine suppliers deliver stability and cost performance. Technical service bundling now determines competitive positioning as much as pigment specifications.
Encapsulated natural colorants using modified starch and gum arabic shells are expanding into heat-processed applications previously reserved for synthetics. Confectionery manufacturers in Greater Buenos Aires are adopting these for hard candy and panned chocolate at accelerating rates. This is expanding into industrial bakery segments where thermal degradation had blocked natural pigment adoption.
ANMAT's pending consultation on titanium dioxide restrictions is accelerating migration to calcium carbonate and starch-based whitening alternatives. Dairy and confectionery formulators are pre-emptively reformulating to avoid supply disruption. The premium ice cream and yogurt segments are most affected, with processors demanding technical documentation for substitute whitening systems.
Direct technical partnerships between colorant suppliers and mid-sized food manufacturers are displacing traditional distributor-mediated procurement. Beverage formulators in Córdoba and Rosario now expect on-site application support and stability testing as standard contract terms. This behavioral shift concentrates purchasing among suppliers with regional technical presence rather than lowest unit pricing.
Argentina Food Colorants Market Segmentation
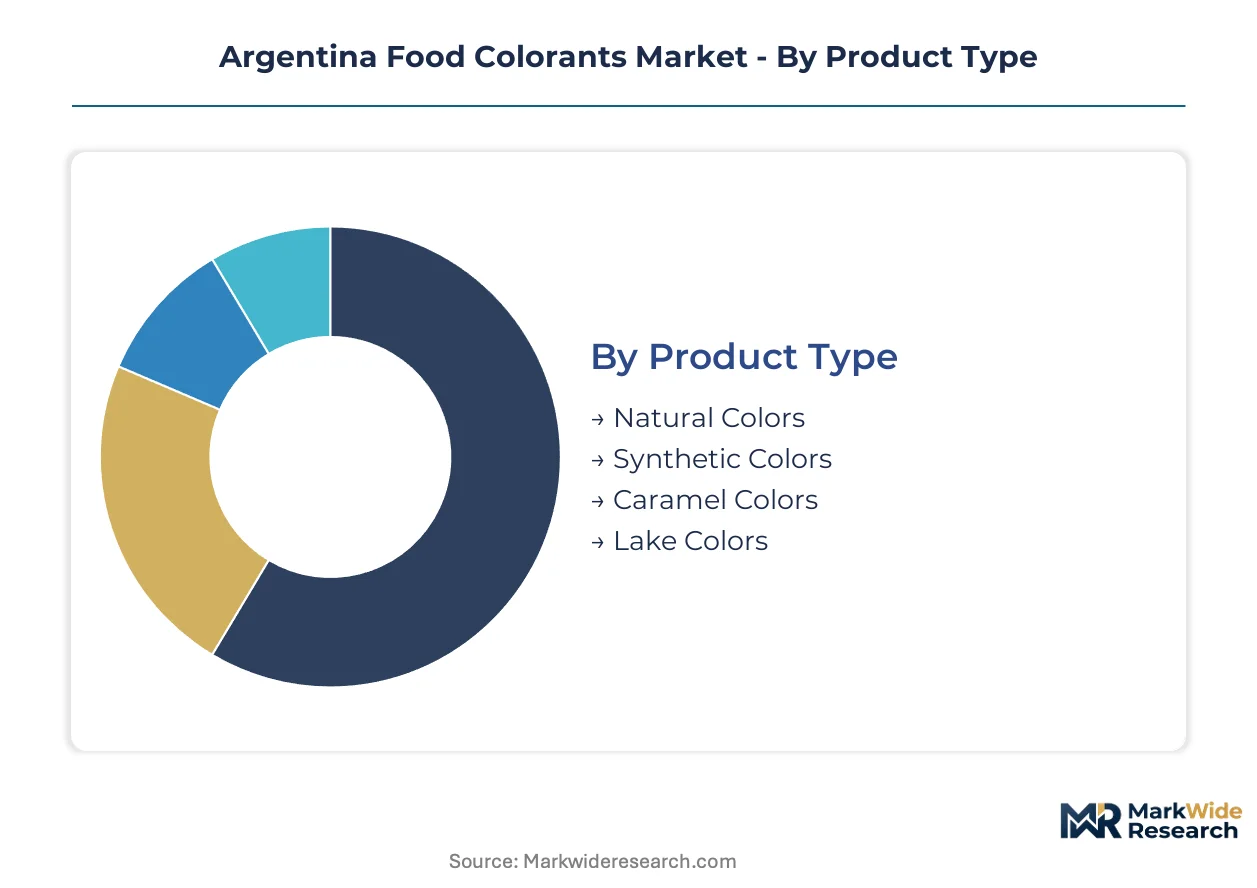
ANMAT's tightening synthetic dye restrictions are fragmenting procurement patterns across Argentina's colorant market. Food manufacturers now segment suppliers by technical validation capabilities and reformulation support rather than pigment cost alone. This reclassification is redistributing margin pools between commodity distributors and application-specialized providers.
Product Type:
Natural Colors demand the heaviest capital investment in extraction infrastructure, fermentation capacity, and stability testing laboratories. Synthetic Colors require lower fixed costs but face accelerating regulatory obsolescence under Mercosur harmonization.
- Natural Colors:Anthocyanin extracts from Mendoza grapes and betalains from Buenos Aires Province beets dominate formulations. Dairy processors in the Pampas region specify these for premium cheese rind applications as ANMAT disclosure mandates tighten. Supply security fluctuates with drought cycles affecting agricultural feedstock yields.
- Synthetic Colors:Azo compounds and triphenylmethane dyes retain cost advantages in mass-market confectionery. Import dependency for permitted synthetics creates working capital strain under Argentina's foreign exchange constraints. Lead times extend as distributors navigate tariff structures for specialty dyes still compliant with Mercosur standards.
- Caramel Colors:Heat-treated sugars supply soft drink and spirits manufacturers with cost-stable brown hues. Class I through IV caramel grades span acid-stable to beer-compatible specifications.
- Lake Colors:Aluminum-chelated pigments deliver opacity in fat-based confectionery coatings. Powder handling systems and dust containment equipment raise facility capital requirements.
Natural Colors absorbs the bulk of installed capacity; Caramel Colors is expanding most quickly in regional spirits production.
Application:
Procurement sophistication varies sharply by application, with beverage formulators demanding the most intensive technical partnership and confectionery buyers prioritizing batch-to-batch consistency.
- Beverages:Transparent packaging exposes natural colorants to photodegradation, driving demand for encapsulated anthocyanins and microemulsion systems. Córdoba-based formulators now require on-site stability testing as standard contract terms. Light-fastness limitations in retail-ready soft drinks restrict natural pigment penetration despite clean-label pressures.
- Dairy Products:Aged cheese rinds, yogurt fruit preparations, and ice cream variegates specify fermentation-derived carotenoids. Chr Hansen's technical presence anchors supply relationships with Pampas processors seeking export certification to Brazil.
- Bakery:Heat-processed applications favor encapsulated natural colorants using modified starch shells. Powder concentrates enable precise dosing in industrial mixing lines.
- Confectionery:Hard candy and panned chocolate manufacturers in Greater Buenos Aires adopt microencapsulated pigments for thermal stability. Sensient's application laboratories sustain loyalty through reformulation support during ANMAT transition periods.
Beverages commands the deepest technical service relationships; Bakery is climbing the fastest as encapsulated natural pigments displace synthetics in heat-processed applications.
Form:
Processing equipment compatibility determines form selection, with legacy beverage plants requiring capital retrofit to handle high-viscosity concentrates.
- Liquid:Streamlined batch processing and reduced dust exposure drive adoption in Córdoba and Rosario beverage lines. Viscosity variations between natural and synthetic concentrates complicate dosing system calibration.
- Powder:Shelf stability and precise weighing accuracy concentrate margin pools in industrial bakeries. Powder-to-liquid conversion incompatibility in older plants delays natural colorant adoption.
- Gel:Intermediate viscosity suits artisanal confectionery and small-batch bakery operations requiring manual incorporation.
- Granular:Free-flowing properties reduce caking in humid storage conditions common to Atlantic coastal processing facilities.
Powder retains volume leadership in established industrial bakeries; Liquid is gaining share fastest as new beverage capacity incorporates compatible dosing infrastructure.
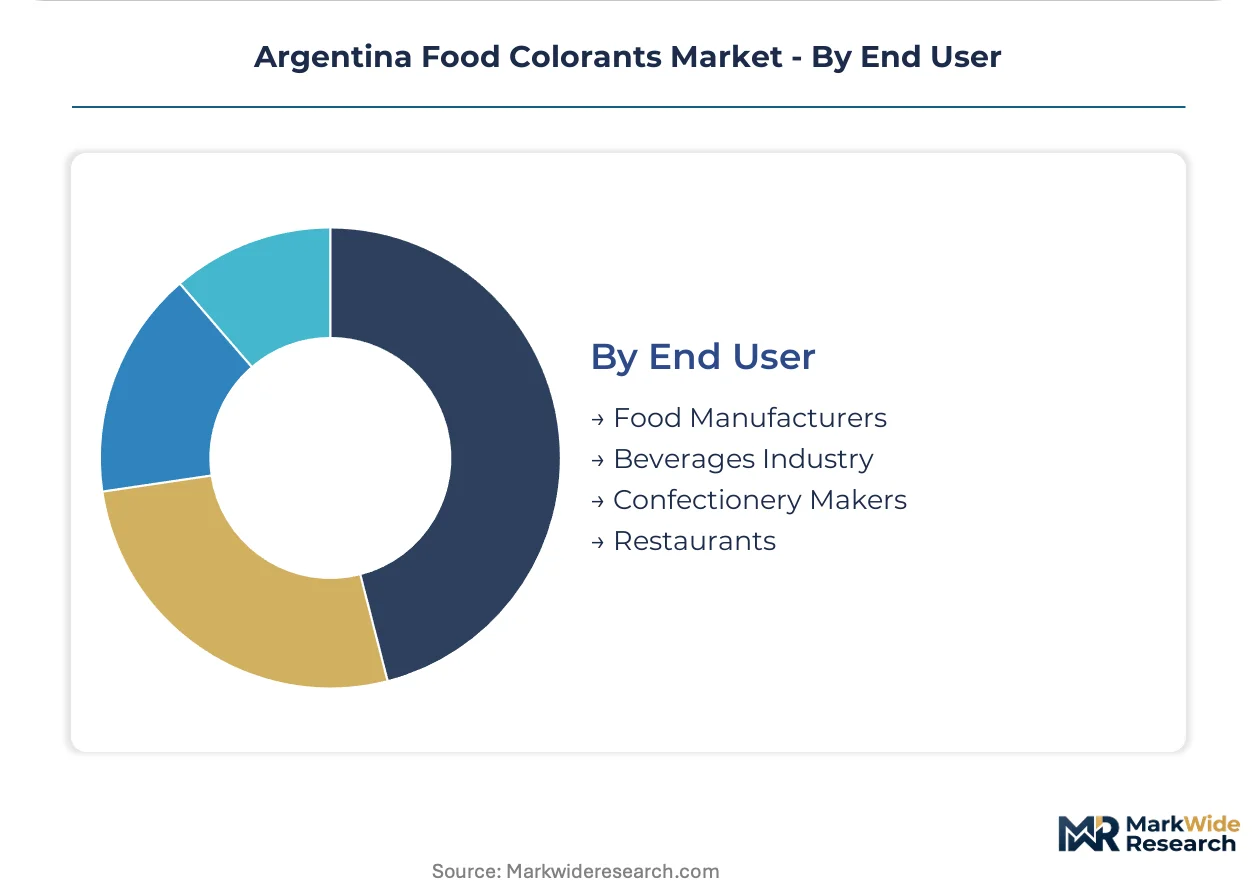
End User:
Scale and technical capability divide end users, with large food manufacturers internalizing reformulation expertise while smaller confectionery makers rely on supplier technical support.
- Food Manufacturers:Multi-category processors in Buenos Aires and Córdoba negotiate integrated colorant contracts spanning dairy, bakery, and prepared foods. Dual ANMAT approval and IRAM purity certification requirements extend procurement cycles.
- Beverages Industry:Soft drink and spirits formulators prioritize light stability documentation and accelerated shelf-life testing. Direct technical partnerships with pigment suppliers displace traditional distributor relationships.
- Confectionery Makers:Artisanal producers in Salta and Tucumán remain underserved by technical distributors. E-commerce ingredient platforms are penetrating this gap with sample fulfillment and digital documentation.
- Restaurants:Commercial kitchens and catering operations source through food service distributors with limited technical support. Volume scale constrains direct supplier engagement.
Food Manufacturers absorb the bulk of supplier technical resources; Confectionery Makers is expanding most quickly as e-commerce platforms reduce transaction barriers for small-batch procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentina's food colorant production concentrates in the Pampas dairy belt and Mendoza extraction facilities, while consumption clusters in Buenos Aires and Córdoba processing corridors. This geographic split shapes logistics costs and technical service deployment strategies across the supply base.
Buenos Aires Province
Beetroot cultivation for betalain extraction supplies domestic dairy processors with red-purple pigments. ANMAT disclosure mandates for synthetic additives accelerate reformulation demand among confectionery manufacturers. Greater Buenos Aires hosts the densest concentration of industrial bakeries adopting encapsulated natural colorants for thermal stability.
Córdoba
Beverage formulators in this central hub specify liquid natural colorants for streamlined batch processing. Mercosur-aligned import tariffs on specialty synthetics create working capital strain for regional soft drink producers. Rosario's agro-industrial complex generates spillover demand for caramel colors in spirits and malt beverages.
Mendoza
Grape anthocyanin extraction facilities face drought-driven feedstock volatility that compresses processor margins. IRAM purity certification requirements determine export eligibility to Brazilian dairy and wine markets. Local extraction cooperatives supply pigment concentrates to Pampas cheese processors seeking natural rind coloration.
Salta and Tucumán
Artisanal confectionery makers in these northwest provinces remain underserved by technical colorant distributors. SENASA organic certification standards create dual-compliance demand for export-oriented regional food processors. E-commerce ingredient platforms are penetrating this gap with sample fulfillment and digital documentation capabilities.
Argentina Food Colorants Market Competitive Environment
Top-tier vendors anchor supply relationships with multi-category food manufacturers, while mid-tier distributors serve regional confectionery and bakery accounts. The market structure tilts toward technical service bundling rather than commodity pigment trading. Strategic archetypes include fermentation-derived pigment specialists, application-focused technical consultants, and import-logistics controllers managing synthetic dye distribution. Competitive moves concentrate on regional technical laboratory expansion and reformulation service partnerships during ANMAT transition periods.
Within the fermentation-derived tier, Chr Hansen Holdings and Koninklijke DSM N.V. occupy positions emphasizing microbial pigment production for dairy applications. Sensient Technologies Corporation exemplifies the application-specialist archetype through its technical support infrastructure. BASF Argentina represents the import-logistics controller model, managing synthetic color distribution networks under foreign exchange constraints. These three anchors demonstrate how competitive positioning in Argentina increasingly depends on reformulation capabilities and regulatory navigation expertise rather than unit pricing alone.
| Leading Market Players |
|---|
| Chr Hansen Holdings |
| D.D. Williamson & Co. |
| Kalsec Inc |
| Michrom |
| Sensient Technologies Corporation |
| Red Sun Dye Chem |
| Koninklijke DSM N.V. |
| Kerry Group |
| BASF Argentina |
| Others |
Value Chain & Pricing Dynamics
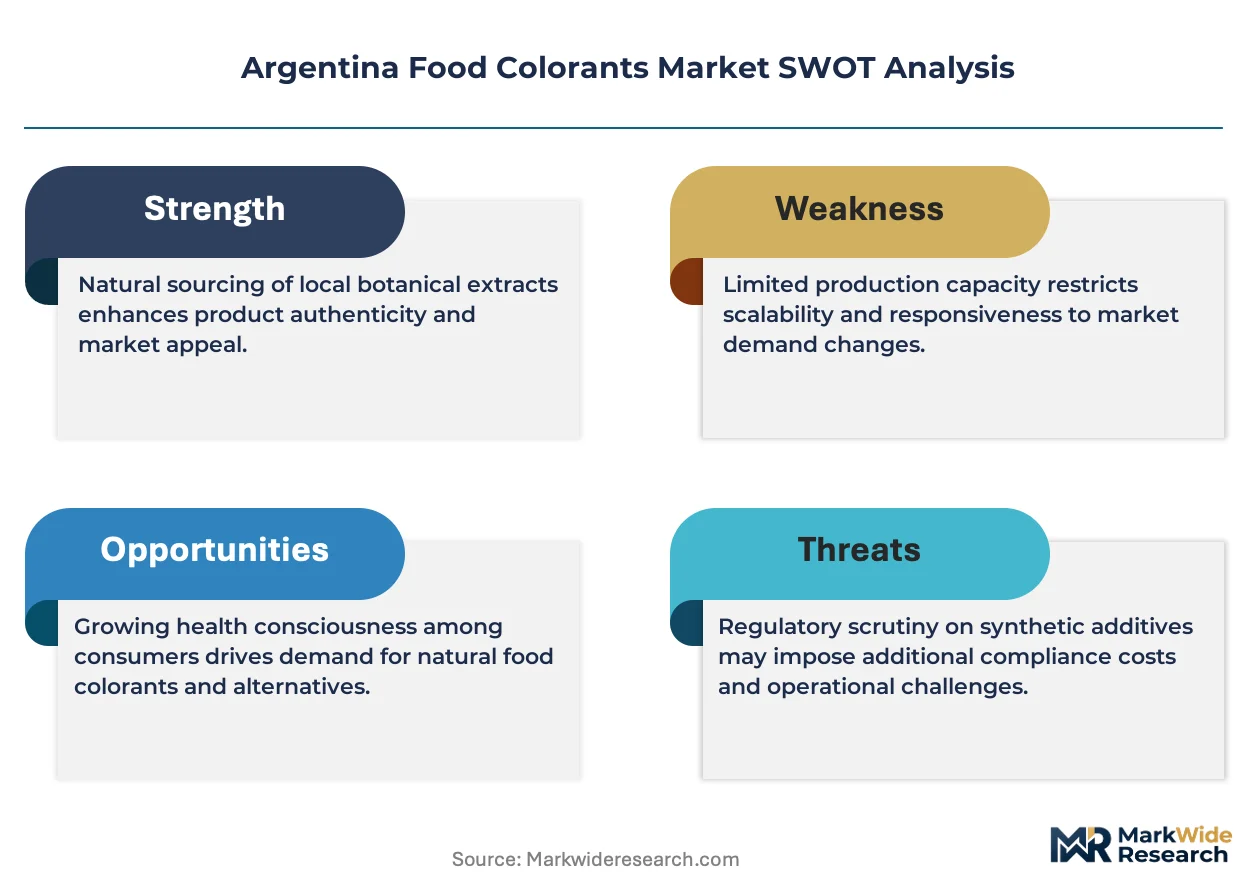
Family-owned extraction cooperatives in Mendoza and Buenos Aires Province anchor upstream supply for betalain and anthocyanin pigments, concentrating pricing power among a handful of processors while limiting margin compression for downstream blenders. This ownership pattern tightens feedstock availability during drought cycles, forcing synthetic dye distributors to absorb foreign exchange volatility without passing full cost increases to confectionery clients locked in annual contracts.
Pricing Analysis
Margin tightening in natural colorant tiers reflects drought-driven feedstock scarcity and IRAM certification premiums for export-grade pigments. Three-tier pricing structure across premium certified-natural, standard food-grade, and economy caramel alternatives stratifies buyer segments, with Pampas dairy processors least sensitive and Salta artisanal confectioners most price-elastic. Cost-down pressure on synthetic dye distributors accelerates because ANMAT disclosure mandates erode volume commitments from reformulating manufacturers.
Supply Chain Analysis
Freight costs from Mendoza extraction facilities to Buenos Aires blending plants consume disproportionate working capital given Argentina's fuel price adjustments and Pampas logistics bottlenecks. Supply concentrates in domestic agricultural zones for natural feedstocks and draws from China, India, and Germany for permitted azo compounds and specialty lake pigments. Distribution runs through ANMAT-licensed importers controlling foreign exchange access, creating single-source vulnerability for confectionery clients dependent on extended-payment-term suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints from Mendoza grape harvest variability prop natural colorant pricing, creating durable margin pools for processors with captive agricultural contracts or fermentation-derived alternatives.
For Market Incumbents: Deploy technical service bundling as the primary retention lever against emerging e-commerce platforms targeting small-batch confectioners. Chr Hansen and Sensient should expand Córdoba application laboratories to preempt distributor disintermediation in beverage formulation support. BASF must secure longer-dated foreign exchange hedges to defend synthetic dye pricing stability during ANMAT transition periods. For New Entrants and Emerging Players: Capture the Salta and Tucumán artisanal confectionery gap through direct e-commerce ingredient platforms offering SENASA organic certification documentation and sample fulfillment. Microencapsulation technology licensing from European specialists enables entry into heat-processed bakery segments without capital-intensive extraction infrastructure. For Investors and Strategic Acquirers: Distressed-cycle entries favor fermentation-derived pigment specialists with existing ANMAT approvals and IRAM certification infrastructure in the Pampas region. Watch for ANMAT titanium dioxide restriction finalization as the signal triggering accelerated reformulation service acquisitions by multi-category food manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mendoza Grape Cultivation | Captive anthocyanin feedstock supply secures margin pools during drought cycles affecting competitor processors. |
| Microencapsulation Technology Licensing | Enables natural pigment penetration into heat-processed confectionery previously reserved for synthetic alternatives. |
| Córdoba Technical Laboratory Expansion | On-site stability testing anchors beverage formulator loyalty against distributor-mediated procurement displacement. |
| SENASA Organic Certification Bundling | Dual natural-organic claims command export pricing premiums to Brazilian premium bakery segments. |
| Direct E-Commerce Platform Launch | Bypasses traditional distributor networks for Salta artisanal confectioners with digital documentation capabilities. |
Study Parameters
Independent corroboration across ANMAT regulatory filings, IRAM purity certification records, and SENASA organic registration databases underwrites the qualitative findings on reformulation timelines and export eligibility requirements. Primary interviews with extraction cooperative managers, dairy processor procurement leads, beverage formulator technical directors, and confectionery distributor sales heads combined with secondary validation from Mercosur harmonization documents and Argentine customs trade data. Bottom-up volume modeling from application-specific consumption rates triangulates against top-down market sizing from supplier revenue disclosures.
Rate-of-change decomposition across the projection horizon separates volume growth from pricing dynamics and mix shift toward natural alternatives. Segmentation dimensions modeled include product type, application category, physical form, and end-user scale tier. CAGRs derive from regression analysis of historical consumption patterns adjusted for ANMAT regulatory phase-in schedules and agricultural yield variance. Forecast inputs incorporate Mendoza grape harvest variability indices and foreign exchange volatility assumptions affecting synthetic dye import economics.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ANMAT consultation finalization timelines and Mercosur tariff restructuring negotiations. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Beverage Stabilizer Market
Food Additives and Ingredients
Sri Lanka Starch and Starch Derivative Market
Food Additives and Ingredients
Japan Food Additives Market
Food Additives and Ingredients
Global Calcium Propionate Market
Food Additives and Ingredients
Mediterranean Sourdough Starter Cultures Market
Food Additives and Ingredients
Food Supplement Ingredients Market
Food Additives and Ingredients
Canada Food Additives Market
Food Additives and Ingredients
Food Emulsifiers Market
Food Additives and Ingredients
Non-GMO Citric Acid Market
Food Additives and Ingredients
Global Canthaxanthin Market
Food Additives and Ingredients
Xanthan Gum Market
Food Additives and Ingredients
Australia Food Preservatives Market
Food Additives and Ingredients
Egypt Food Emulsifiers Market
Food Additives and Ingredients
Spain Food Acidulants Market
Food Additives and Ingredients
Natural Food and Beverage Preservatives Market
Food Additives and Ingredients
Gum Hydrocolloid Market