
 Banana Powder Market | 2026-2036
Banana Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Banana Powder Market Intelligence
Multi-source raw material procurement is expanding across the banana powder value chain as processors diversify beyond captive plantations to secure year-round supply. Taj Agro International leverages its pan-India sourcing network to maintain consistent feedstock access. Chiquita Brands International Sàrl anchors its procurement strength through Central American supply bases. Naturalin Bio-Resources Co. Ltd. differentiates via organic certification coverage across its supplier base.
Banana powder consists of dehydrated or freeze-dried banana pulp milled to a fine particle size, typically retaining moisture below 5% to ensure shelf stability and microbial safety; manufacturers employ drum drying, spray drying, or freeze-drying depending on target application and cost structure. The ingredient serves primarily as a natural sweetener, binder, and potassium source across food, nutraceutical, and cosmetic formulations. Organic and freeze-dried product types command premium positioning due to clean-label alignment and superior nutrient retention. Bakery ingredients and dietary supplements represent the most structurally attractive application segments, where functional claims support margin expansion.
India's FSSAI mandates specific microbiological limits and labeling disclosures for banana powder sold into infant food channels, while the US FDA exercises oversight through GRAS determinations and food additive regulations for imported powder. The EU's EFSA evaluates novel food applications and pesticide residue thresholds under REACH-aligned protocols. Stakeholders must monitor evolving fortification mandates and organic equivalency agreements to preserve market access across priority destinations.
Market Dynamics
India's FSSAI fortification tightening is compressing purity thresholds for banana powder entering infant nutrition channels, forcing processors to rebuild quality assurance protocols around microbiological limits and labeling disclosures that now exceed baseline food-grade specifications.
Growth Catalysts
- Infant nutrition channel expansion:Complementary food manufacturers in southern Indian states of Kerala and Tamil Nadu are scaling procurement volumes as birth rates stabilize and urban disposable incomes rise.
- Clean-label bakery reformulation:European and North American bakers are substituting refined sugars with banana powder's natural fructose-glucose matrix to meet reduced-sugar claims without artificial sweeteners.
- REACH-aligned residue protocols:The EU's EFSA pesticide threshold harmonization is advantaging Indian exporters with certified organic supply chains over conventional competitors facing detention risk.
Market Restraints
- Raw material seasonality:Cavendish and Nendran banana harvest cycles concentrate supply windows to 6-8 months annually, forcing processors to absorb working capital costs for buffer stock maintenance.
- Energy-intensive drying economics:Drum drying and spray drying operations face margin compression from natural gas and electricity tariff volatility in processing clusters.
- Infant-grade certification friction:FSSAI's tightened microbiological limits for Staphylococcus aureus and Salmonella spp. are disqualifying smaller processors lacking in-house testing infrastructure.
Strategic Opportunities
- Freeze-dried premium tier development:Cosmetic formulators in South Korea and Japan are sourcing low-temperature dried powder for active polyphenol retention in topical applications.
- Direct-to-ingredient platform distribution:Specialty chemical distributors are disintermediating commodity traders to capture margin in pharmaceutical-grade banana powder for excipient applications.
- PLI scheme alignment:India's production-linked incentive scheme for food processing is subsidizing capital expenditure for integrated drying and milling capacity in Tamil Nadu processing zones.
Industry Challenges
- Skilled drying technician scarcity:Optimal moisture control below 5% requires experienced operators familiar with heat transfer dynamics across drum, spray, and freeze-drying configurations.
- Organic equivalency documentation:Exporters must maintain parallel certification trails under USDA NOP, EU 2018/848, and India Organic to prevent market access interruption during regulatory audits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Banana Powder Market |
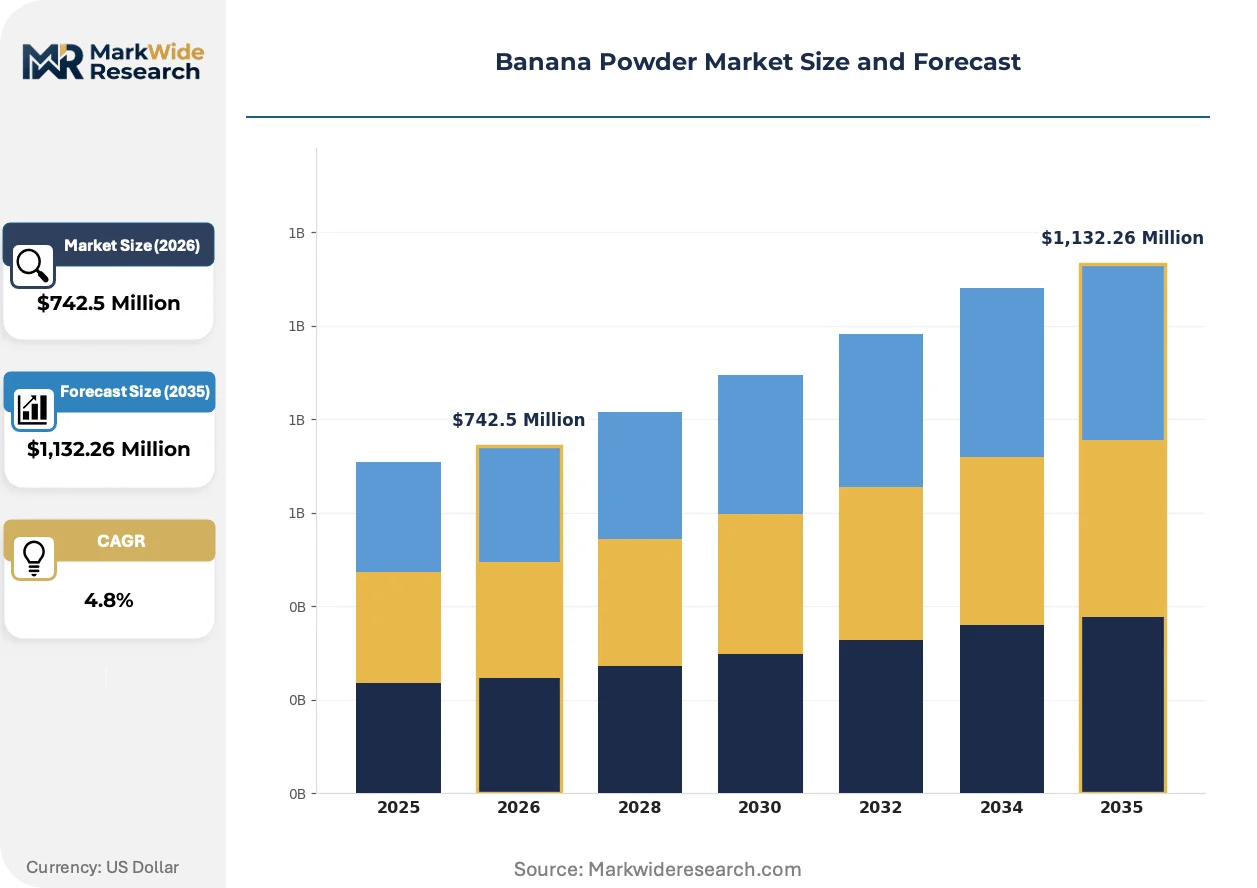
| Market Size in 2026 | $742.5 Million |
| Market Size in 2035 | $1,132.26 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Green Banana, Ripe Banana, Dehydrated, Freeze-dried Application: Bakery Ingredients, Beverage Enhancers, Dietary Supplements, Baby Food, Confectionery End User: Food & Beverage Manufacturers, Nutraceutical Companies, Cosmetic Producers, Animal Feed Industry Packaging Type: Flexible Pouches, Stand-up Bags, Sachets, Bulk Containers, Paper Bags |
| Companies Covered | Taj Agro International, Vinayak Ingredients Pvt. Ltd., Chiquita Brands International Sàrl, Sumitomo Corporation, Naturalin Bio-Resources Co. Ltd., Fresh Del Monte Produce Inc., Kanegrade Limited, GRUPO JUGAL Inc., Dole plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Banana Powder Market Strategic Shifts & Innovations
Processing technology convergence with quality verification systems is compressing the gap between commodity-grade and specialty-grade banana powder production, enabling mid-scale processors to contest premium segments previously reserved for freeze-dried specialists.
Low-temperature vacuum belt drying is rewriting moisture removal economics for heat-sensitive bioactive compounds. Nutraceutical formulators in Germany and Switzerland are adopting this technology to preserve resistant starch and potassium ratios in dietary supplement applications. The process is compressing the cost premium between spray-dried and freeze-dried outputs by approximately half in pilot-scale deployments.
The EU's F-Gas Regulation phase-down is accelerating refrigerant-dependent freeze-drying facility investments toward alternative cooling architectures. Industrial consequence includes extended equipment procurement lead times and retrofit obligations for existing lyophilization capacity. South Indian processors with export exposure are responding by diversifying into hybrid drying configurations that reduce cryogenic dependency.
Ingredient buyers are consolidating supplier relationships around vertically integrated processors with captive organic plantations and in-house laboratory certification capabilities. This pattern is displacing spot-market procurement through commodity brokers in favor of annual volume contracts with quality guarantees. The shift is most visible in Netherlands and UK distribution channels serving clean-label bakery and infant food manufacturers.
Banana Powder Market Segmentation
Banana powder processors segment output across four dimensions that determine pricing power and customer stickiness. Product type and application drive margin stratification, while end-user concentration and packaging format shape distribution economics.
Product Type:
Buyers differentiate banana powder primarily by processing intensity and certification burden, which directly determines shelf-life claims and clean-label positioning.
- Freeze-dried:Low-temperature sublimation preserves resistant starch and polyphenol integrity for cosmetic and premium nutraceutical applications. South Korean and Japanese formulators in topical skincare channels absorb the 40-60% cost premium over conventional drying methods.
- Organic:USDA NOP, EU 2018/848, and India Organic certification trails enable duty-advantaged access into European clean-label bakery and infant nutrition channels. FSSAI's tightened microbiological limits for complementary foods disproportionately favor certified organic supply chains with existing laboratory infrastructure.
- Green Banana:Unripe pulp retains higher resistant starch content for glycemic management supplements.
- Ripe Banana:Elevated natural sugar concentration suits bakery sweetener replacement applications.
- Dehydrated:Drum-dried or spray-dried formats serve commodity food-grade specifications at lowest unit cost.
Ripe banana leads volumes today; freeze-dried is gaining share fastest.
Application:
Margin capture varies sharply by channel, with regulatory scrutiny and functional claim substantiation determining price realization.
- Baby Food:FSSAI fortification mandates for complementary foods impose Staphylococcus aureus and Salmonella spp. thresholds that disqualify smaller processors lacking in-house pathogen testing. Kerala and Tamil Nadu manufacturers with integrated drying and laboratory capacity capture procurement volumes from pan-India infant nutrition brands.
- Dietary Supplements:German and Swiss nutraceutical formulators specify vacuum belt-dried powder to preserve potassium ratios and resistant starch bioavailability. The technology compresses cost premiums versus freeze-dried alternatives by approximately half.
- Bakery Ingredients:European bakers substitute refined sugars with banana powder's fructose-glucose matrix to meet reduced-sugar claims.
- Beverage Enhancers:Instant drink mixes leverage natural sweetness and potassium fortification.
- Confectionery:Chocolate and candy applications exploit binding properties and clean-label appeal.
Bakery ingredients leads volumes today; baby food is climbing the fastest.
End User:
Procurement sophistication separates price-tolerant specialty buyers from volume-driven commodity purchasers.
- Food & Beverage Manufacturers:Pan-India sourcing networks and annual volume contracts with quality guarantees displace spot-market procurement through commodity brokers. Netherlands and UK distribution channels serving clean-label bakery manufacturers consolidate supplier relationships around vertically integrated processors.
- Nutraceutical Companies:Pharmaceutical-grade specifications for excipient applications drive direct-to-ingredient platform distribution, bypassing traditional traders.
- Cosmetic Producers:South Korean and Japanese formulators source low-temperature dried powder for active polyphenol retention in topical applications.
- Animal Feed Industry:Commodity-grade specifications prioritize cost minimization over nutrient retention metrics.
Food & Beverage Manufacturers leads volumes today; Nutraceutical Companies is expanding most quickly.
Packaging Type:
Supply chain configuration and customer scale determine format selection, with export-facing processors favoring formats that minimize moisture reabsorption risk.
- Bulk Containers:Food & Beverage Manufacturers with integrated blending operations purchase 500kg to 1-tonne quantities to minimize unit handling costs.
- Stand-up Bags:Retail-channel dietary supplement brands specify resealable formats with oxygen barrier layers.
- Flexible Pouches:Cost-efficient option for commodity-grade bakery ingredient distribution.
- Sachets:Single-serve beverage enhancer applications in hospitality and airline channels.
- Paper Bags:Eco-conscious positioning for organic-certified retail SKUs with shorter shelf-life requirements.
Bulk Containers leads volumes today; Stand-up Bags is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tamil Nadu's integrated processing corridors anchor banana powder manufacturing capacity, with Kerala's raw material clusters and export infrastructure completing India's southern supply architecture. Germany's nutraceutical formulators and the United States' clean-label food manufacturers drive import demand for certified organic grades.
India
FSSAI fortification mandates for complementary foods compress microbiological thresholds for infant-grade powder, disqualifying processors lacking laboratory infrastructure. The PLI scheme subsidizes capital expenditure for integrated drying capacity in Tamil Nadu processing zones. Kerala's Nendran banana cultivation belts supply raw material to exporters targeting European clean-label channels.
Germany
German nutraceutical formulators specify vacuum belt-dried powder to preserve resistant starch bioavailability in dietary supplement applications. EFSA pesticide residue protocols under REACH-aligned standards advantage certified organic supply chains over conventional competitors. Processing technology distributors in Bavaria pilot hybrid drying configurations that reduce cryogenic dependency for export-facing South Asian suppliers.
United States
Clean-label bakery manufacturers substitute refined sugars with banana powder's natural fructose-glucose matrix to meet reduced-sugar claims. FDA GRAS determinations govern food additive regulations for imported powder entering infant nutrition and beverage channels. California-based natural food brands consolidate supplier relationships around vertically integrated processors with captive organic certification.
South Korea
Cosmetic formulators in Seoul source low-temperature dried powder for active polyphenol retention in topical skincare applications. MFDS cosmetic ingredient regulations require documentation of drying temperatures and moisture specifications for imported botanical materials. Busan-Ulsan distribution hubs handle transshipment volumes destined for Japanese pharmaceutical-grade excipient manufacturers.
Netherlands
Amsterdam-Rotterdam distribution channels serving European clean-label bakery manufacturers displace spot-market procurement through commodity brokers. EFSA novel food evaluations and organic equivalency agreements under EU 2018/848 govern import documentation requirements. Dutch ingredient platforms consolidate annual volume contracts with quality guarantees from Indian processors with in-house certification capabilities.
Banana Powder Market Key Industry Players
Global majors compete with regional champions across procurement networks and certification coverage. The vendor base stratifies into three tiers: multinational fruit conglomerates with Central American supply bases, Indian agro-processors with pan-India sourcing networks, and Chinese organic specialists with multi-jurisdictional certification trails. Dominant competitive moves include backward integration into captive plantation control and technology licensing for low-temperature drying configurations.
Among India-based processors, Taj Agro International exemplifies the pan-India sourcing archetype, while Vinayak Ingredients Pvt. Ltd. occupies a position within the domestic infant nutrition supply tier. Chiquita Brands International Sàrl represents the multinational fruit conglomerate structure with established Central American raw material access. These three anchors illustrate the competitive tension between geographic specialization and vertical integration strategies across the value chain.
| Leading Market Players |
|---|
| Taj Agro International |
| Vinayak Ingredients Pvt. Ltd. |
| Chiquita Brands International Sàrl |
| Sumitomo Corporation |
| Naturalin Bio-Resources Co. Ltd. |
| Fresh Del Monte Produce Inc. |
| Kanegrade Limited |
| GRUPO JUGAL Inc. |
| Dole plc |
| Others |
Cost & Logistics Intelligence
The EU's F-Gas Regulation phase-down gates qualified supply for freeze-dried premium tiers and compresses pricing access to processors with hybrid drying architectures or non-refrigerant cooling systems. Buyers without documented low-temperature drying protocols face exclusion from South Korean cosmetic and German nutraceutical channels where residue-compliant organic certification commands measurable premiums.
Pricing Analysis
Natural gas and electricity tariff pass-through directly shapes margin structures across drum-dried and spray-dried commodity tiers. Three-tier pricing structure across organic-certified, food-grade, and feed-grade levels reflects FSSAI laboratory infrastructure requirements and EU 2018/848 equivalency documentation burdens. Cost compression in conventional dehydrated segments is intensifying because energy-intensive processors lack pricing power against bulk bakery ingredient purchasers. Infant nutrition manufacturers exhibit lowest price sensitivity due to fortification mandate compliance costs; animal feed compounders remain most elastic.
Supply Chain Analysis
Skilled drying technician scarcity in Tamil Nadu and Kerala processing corridors constrains capacity expansion for moisture-controlled operations below 5% thresholds. Raw material supply draws from India's Nendran cultivation belts, Ecuador's Cavendish plantations, and Costa Rica's organic-certified estates. Single-source vulnerability concentrates in Central American banana supply during hurricane season disruption windows. Distribution runs through Amsterdam-Rotterdam hubs for European clean-label channels and Busan-Ulsan transshipment nodes for Northeast Asian cosmetic formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. German and Swiss nutraceutical formulators are shifting procurement specifications toward vacuum belt-dried grades with documented resistant starch retention.
For Market Incumbents: Deploy in-house laboratory certification capabilities as the anchor lever. Taj Agro International and comparable pan-India processors should deepen backward integration into captive organic plantations to secure year-round Nendran feedstock against seasonal concentration. Chiquita Brands International Sàrl must retrofit Central American lyophilization capacity toward alternative cooling architectures before EU F-Gas enforcement tightens equipment procurement lead times. For New Entrants and Emerging Players: Specialty chemical distributors serving pharmaceutical-grade excipient applications represent the most accessible channel partner type for bypassing entrenched commodity traders. Freeze-dried cosmetic supply to South Korean formulators offers white-space penetration with lower certification friction than infant nutrition channels. Direct-to-ingredient platform relationships with German nutraceutical compounders provide the cleanest go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale Indian processors with integrated drying and laboratory infrastructure because FSSAI's tightened microbiological limits are disqualifying smaller competitors lacking pathogen testing capabilities. Target acquisition archetypes include Kerala-based operators with existing EU 2018/848 certification trails and Tamil Nadu facilities eligible for PLI scheme capital subsidies. Watch for inflection when hybrid drying technology licensing agreements displace conventional freeze-drying capacity investments.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Drying Technology Licensing | South Indian processors reduce cryogenic dependency while preserving EU market access under REACH-aligned protocols. |
| Backward Integration into Organic Plantations | Captive Nendran supply secures year-round feedstock against 6-8 month harvest concentration windows. |
| In-House Laboratory Certification Investment | FSSAI's tightened Staphylococcus aureus thresholds disqualify processors lacking pathogen testing infrastructure. |
| Direct-to-Ingredient Platform Distribution | Specialty chemical distributors disintermediate commodity traders in pharmaceutical-grade excipient channels. |
| PLI Scheme Capacity Alignment | India's production-linked incentive subsidizes integrated drying and milling investment in Tamil Nadu zones. |
Research Approach
Direct dialogue with banana powder plant managers, FSSAI compliance officers at infant nutrition manufacturers, procurement leads at German nutraceutical formulators, and Amsterdam-Rotterdam distribution channel heads grounded qualitative findings. Secondary validation drew from FSSAI fortification guidelines, EU EFSA novel food evaluations, ECHA REACH substance registrations, and India PLI scheme disbursement records. Bottom-up capacity assessments across Tamil Nadu processing corridors triangulated against top-down demand estimates from clean-label bakery and dietary supplement channels.
Segment-level outputs across product type, application, end user, and packaging format dimensions stabilized through iterative reconciliation across the projection horizon. CAGRs emerged from slope analysis of historical price-volume relationships and forward capacity buildout announcements. Key inputs included Nendran banana harvest cycle data, EU F-Gas Regulation implementation timelines, and FSSAI laboratory infrastructure investment patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU organic equivalency agreement renegotiations and energy tariff trajectories in South Indian processing clusters. Assumptions reflect current regulatory trajectories without anticipating unannounced FSSAI microbiological threshold revisions or unforeseen Central American supply disruptions. Material deviation in EU F-Gas enforcement timing or PLI scheme eligibility criteria warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Bread Emulsifier Market
Food Additives and Ingredients
Activated Cake Emulsifier Market
Food Additives and Ingredients
Spain Food Additives Market
Food Additives and Ingredients
Brazil Feed Additives Market
Food Additives and Ingredients
Mexico Food Additives Market
Food Additives and Ingredients
Asia Pacific Food Acidulants Market
Food Additives and Ingredients
Natural Food Color Additives Market
Food Additives and Ingredients
Food Grade Dipotassium Phosphate Market
Food Additives and Ingredients
South America Food Colorants Market
Food Additives and Ingredients
Tapioca Starch Market
Food Additives and Ingredients
Food Humectants Market
Food Additives and Ingredients
Japan Food Acidulants Market
Food Additives and Ingredients
Protective Cultures Market
Food Additives and Ingredients
Asia Food Emulsifiers Market
Food Additives and Ingredients
Granulated Tapioca Market
Food Additives and Ingredients
Food Grade Stearic Acid Market