
 China Anti-Caking Market | 2026-2036
China Anti-Caking Market Size, Share, and Industry Trends Forecast 2026-2036
China Anti-Caking Market Outlook
Market Context
Domestic fertilizer manufacturers is reorganizing procurement priorities toward higher-performance anti-caking solutions as compound fertilizer output expands. Solvay S.A. leverages its silica-based technology leadership to serve high-specification agricultural clients along the Yangtze River corridor. Evonik Industries AG sustains competitive positioning through specialized precipitated silica grades tailored to humidity-variable storage conditions in southern China. BASF SE anchors its presence with integrated supply chains reaching Jiangsu and Zhejiang formulation plants.
Technical Definition and Segments
Anti-caking agents are hygroscopic control additives—typically silica-based compounds, carbonates, or silicates—applied in 0.1% to 2.0% concentrations to maintain free-flow properties in granular and powdered materials during transport and storage. These agents function by absorbing surface moisture, modifying crystal morphology, or creating physical barriers between particles to prevent bridge formation and lumping in bulk solids handling. Powder formulations command the dominant share due to compatibility with existing blending equipment across Chinese fertilizer and food processing plants, while liquid application systems are gaining traction in automated coating lines where uniform distribution and reduced dust exposure matter. Sodium silicate leads product type demand through cost-effective performance in agricultural applications, though magnesium carbonate variants are extending into pharmaceutical-grade specifications where inertness and purity thresholds are stricter.
Regulatory Outlook
China's SAMR enforces GB standards for food additive purity and labeling, while the MEE implements dual carbon goals that tighten energy intensity benchmarks for anti-caking agent production facilities. GB 2760 food safety standards and evolving environmental compliance requirements from provincial ecology departments are elevating qualification barriers for domestic manufacturers and imported substitutes alike. Stakeholders must monitor how Shandong and Jiangsu provincial authorities interpret national emission caps for silica processing, as these interpretations will determine which production technologies secure operating permits.
Market Dynamics
Fertilizer producers across Shandong and Jiangsu are consolidating procurement specifications around silica-based coatings that withstand humidity-variable storage, forcing domestic anti-caking manufacturers to upgrade precipitation reactor technology or exit agricultural supply chains.
Growth Catalysts
- Compound fertilizer expansion:Chinese agrochemical clusters in Lianyungang and Weifang are scaling urea coating lines, pulling demand for sodium silicate formulations that prevent caking during monsoon-season distribution.
- GB 2760 food additive compliance:SAMR enforcement of purity thresholds for magnesium carbonate in infant formula and salt processing is qualifying higher-grade domestic suppliers for premium food manufacturing contracts.
- Dual carbon energy intensity mandates:MEE emission caps on silica calcination furnaces are accelerating replacement of coal-fired production with natural gas and electric thermal systems in Jiangsu chemical parks.
Market Restraints
- Soda ash price volatility:Sodium silicate production costs fluctuate with domestic soda ash contract pricing, compressing margins for mid-tier anti-caking blenders serving bulk fertilizer accounts.
- Import dependency for pharmaceutical grades:High-purity precipitated silica for drug excipients concentrates among European and Japanese suppliers, limiting domestic substitution in CDSCO-regulated applications.
- Technical ceiling in ultra-fine particle engineering:Domestic manufacturers lack controlled agglomeration technology below 5-micron median diameter, ceding specification-driven food and pharma segments to foreign competitors.
Strategic Opportunities
- Henan and Hubei fertilizer corridor penetration:Emerging compound fertilizer capacity in Zhengzhou and Jingmen offers first-mover positioning for coating suppliers with logistics infrastructure west of coastal clusters.
- Pharmaceutical excipient qualification:NMPA's streamlined DMF filing pathway for inert additives creates entry point for domestic silica producers meeting USP-NF monograph standards.
- Automated liquid coating systems:Integration of precision spray applicators with fertilizer blending lines enables uniform anti-caking distribution and dust reduction, displacing manual powder dosing in Yangtze River Delta plants.
Industry Challenges
- Reactor engineering talent scarcity:Precipitated silica process optimization requires expertise in pH-controlled nucleation kinetics that domestic universities and vocational programs underproduce.
- GB standard certification timelines:SAMR food additive safety assessments average 18-24 months, delaying revenue recognition for reformulated magnesium carbonate variants targeting infant nutrition.
- Legacy blending equipment incompatibility:Liquid anti-caking application systems demand pneumatic spray infrastructure that 60% of Shandong fertilizer plants lack, complicating technology transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Anti-Caking Market |
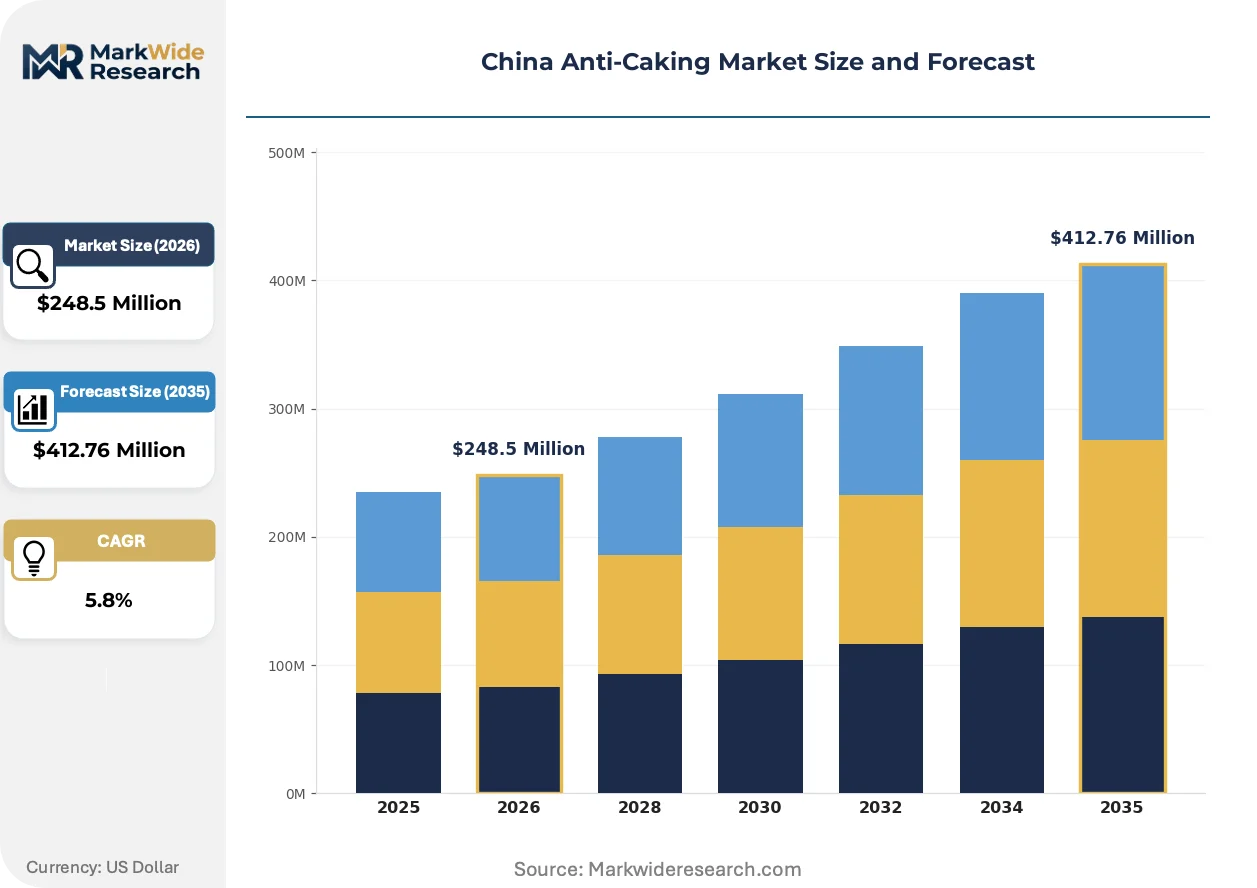
| Market Size in 2026 | $248.5 Million |
| Market Size in 2035 | $412.76 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Silicate, Calcium Carbonate, Magnesium Carbonate, Talc Application: Food Industry, Pharmaceuticals, Agriculture, Construction Form: Granular, Powder, Liquid, Pellets End User: Manufacturers, Distributors, Retailers, Wholesalers |
| Companies Covered | Solvay S.A., Kao Corporation, Evonik Industries AG, W. R. Grace & Co., PQ Corporation, BASF SE, Cabot Corporation, IMERYS S.A., PPG Industries Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Anti-Caking Market Strategic Shifts
Synthetic amorphous silica production methods are undergoing selective substitution as environmental compliance costs and performance specifications reshape supplier R&D priorities across Chinese chemical manufacturing.
Surface-modified hydrophobic precipitated silica is displacing untreated grades in humidity-exposed fertilizer storage applications. Jiangsu-based compound fertilizer exporters are specifying silane-treated particles for Southeast Asian and African distribution chains. This displacement is compressing commodity silica margins while expanding premium formulation service contracts.
MEE enforcement of dual carbon emission intensity benchmarks for chemical processing is tightening operating permits for calcination-based silica facilities. Shandong provincial ecology departments are requiring continuous emissions monitoring systems for furnaces above 500-kilowatt thermal input. Agricultural-grade anti-caking producers in Weifang and Qingdao are responding with natural gas retrofit investments and carbon accounting documentation for export customers.
Direct procurement relationships between fertilizer formulators and anti-caking technology providers are shortening traditional distributor channels. Large urea manufacturers in Lianyungang and Yantai are negotiating multi-year coating supply agreements with silica producers, bypassing regional chemical traders. This concentration is most visible in Jiangsu, where three compound fertilizer groups now account for majority coating volume and dictate formulation specifications to suppliers.
China Anti-Caking Market Segmentation
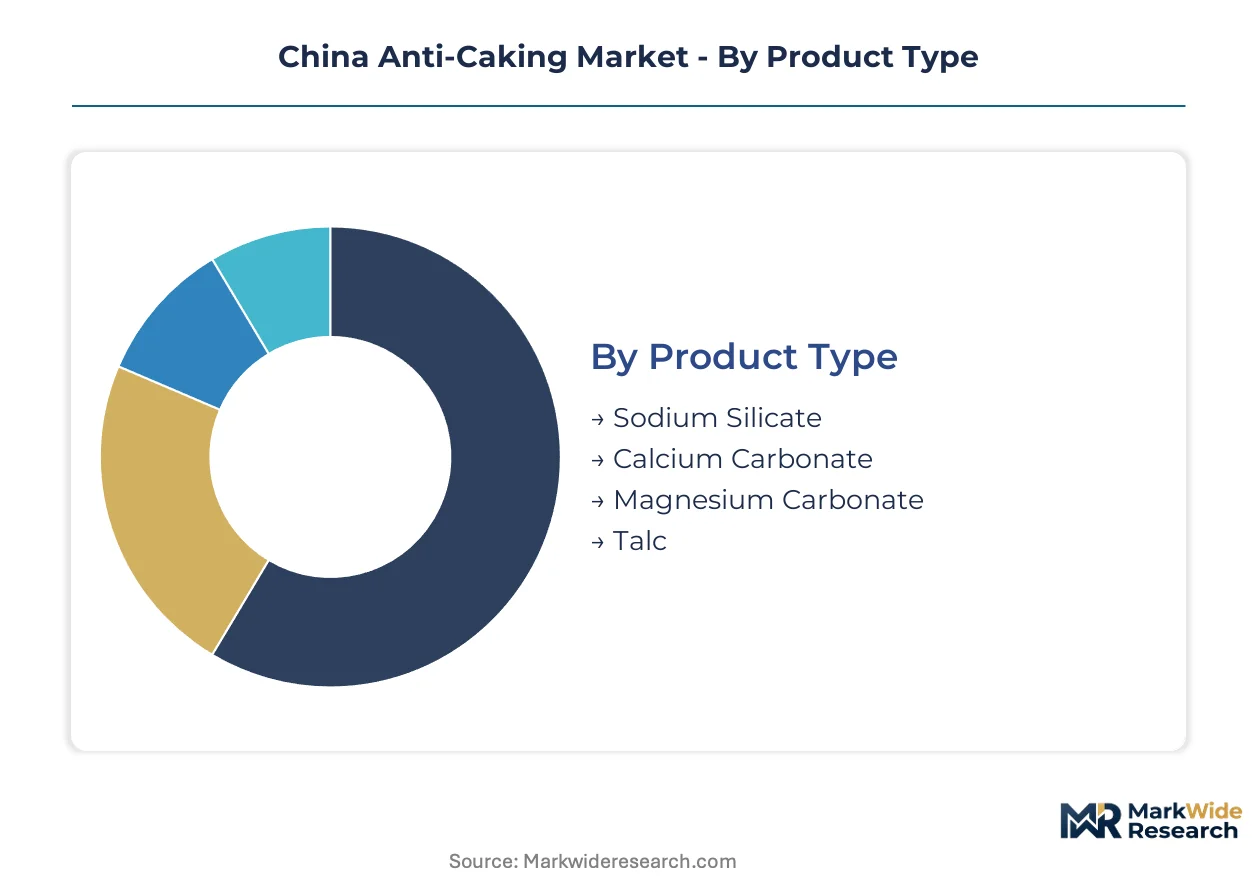
Segmentation reveals how procurement specifications diverge across Chinese end-use sectors. Fertilizer manufacturers prioritize cost-effective moisture control while food processors demand certified purity thresholds under GB 2760.
Product Type:
Surface-modified precipitated silica is displacing untreated commodity grades in humidity-exposed applications, forcing carbonate producers to defend positioning through price aggression or pharmaceutical-grade qualification.
- Sodium Silicate:Alkaline silicate solution precipitated into amorphous solids with high surface area-to-mass ratios. Jiangsu compound fertilizer clusters in Lianyungang specify this grade for urea coating lines serving monsoon-exposed distribution networks. Soda ash feedstock volatility compresses blender margins during contract renegotiations.
- Calcium Carbonate:Ground or precipitated calcium salt functioning through moisture absorption and particle separation. Construction material processors in Shandong prefer this lower-cost alternative for cement additive applications where food-grade purity is unnecessary. Environmental scrutiny of limestone calcination emissions is tightening permit renewals in Weifang chemical parks.
- Magnesium Carbonate:Lightweight carbonate with superior inertness for pharmaceutical excipient specifications. NMPA DMF filing pathways are opening for domestic producers meeting USP-NF monograph standards.
- Talc:Hydrated magnesium silicate with lamellar particle structure providing physical barrier properties. Limited penetration in Chinese food applications due to stricter GB standards on asbestos fiber content.
Sodium silicate anchors the volume base while magnesium carbonate gains share at the steepest rate.
Application:
End-use diversification follows regional industrial clustering patterns, with agricultural demand concentrating in coastal provinces and pharmaceutical qualification efforts centering on regulatory-compliant manufacturing zones.
- Food Industry:GB 2760-regulated applications spanning salt processing, infant formula, and powdered seasonings. SAMR enforcement of purity thresholds is disqualifying legacy carbonate suppliers from premium manufacturing contracts.
- Pharmaceuticals:High-purity precipitated silica serving as tablet disintegrant and glidant excipient. Import dependency persists for sub-5-micron controlled agglomeration grades used in CDSCO-regulated drug formulations.
- Agriculture:Fertilizer anti-caking coatings for urea, compound fertilizers, and ammonium nitrate. Shandong and Jiangsu procurement consolidation around performance-based specifications is squeezing commodity-grade producers.
- Construction:Cement and gypsum board additives preventing moisture-induced clumping. Lower specification barriers attract regional carbonate grinding operations with minimal R&D investment.
Agriculture commands absolute volume leadership while pharmaceuticals exhibits the steepest expansion trajectory.
Form:
Equipment compatibility and labor cost considerations are shifting preference curves between physical delivery formats across Chinese processing facilities.
- Powder:Standard pulverized formulations compatible with existing blending equipment. Dominates fertilizer processing in Shandong where manual dosing remains prevalent at smaller compound plants.
- Liquid:Suspension or solution formats applied through precision spray systems. Yangtze River Delta fertilizer groups are retrofitting automated coating lines to reduce dust exposure and improve distribution uniformity.
- Granular:Agglomerated particles with controlled dissolution rates. Preferred in construction applications where slow-release moisture control extends material workability windows.
- Pellets:Compressed spherical formats for specialized pharmaceutical tableting feedstocks. Limited domestic production capacity constrains penetration in high-specification drug manufacturing.
Powder retains volume dominance while liquid formats climb the fastest as automation investments accelerate.
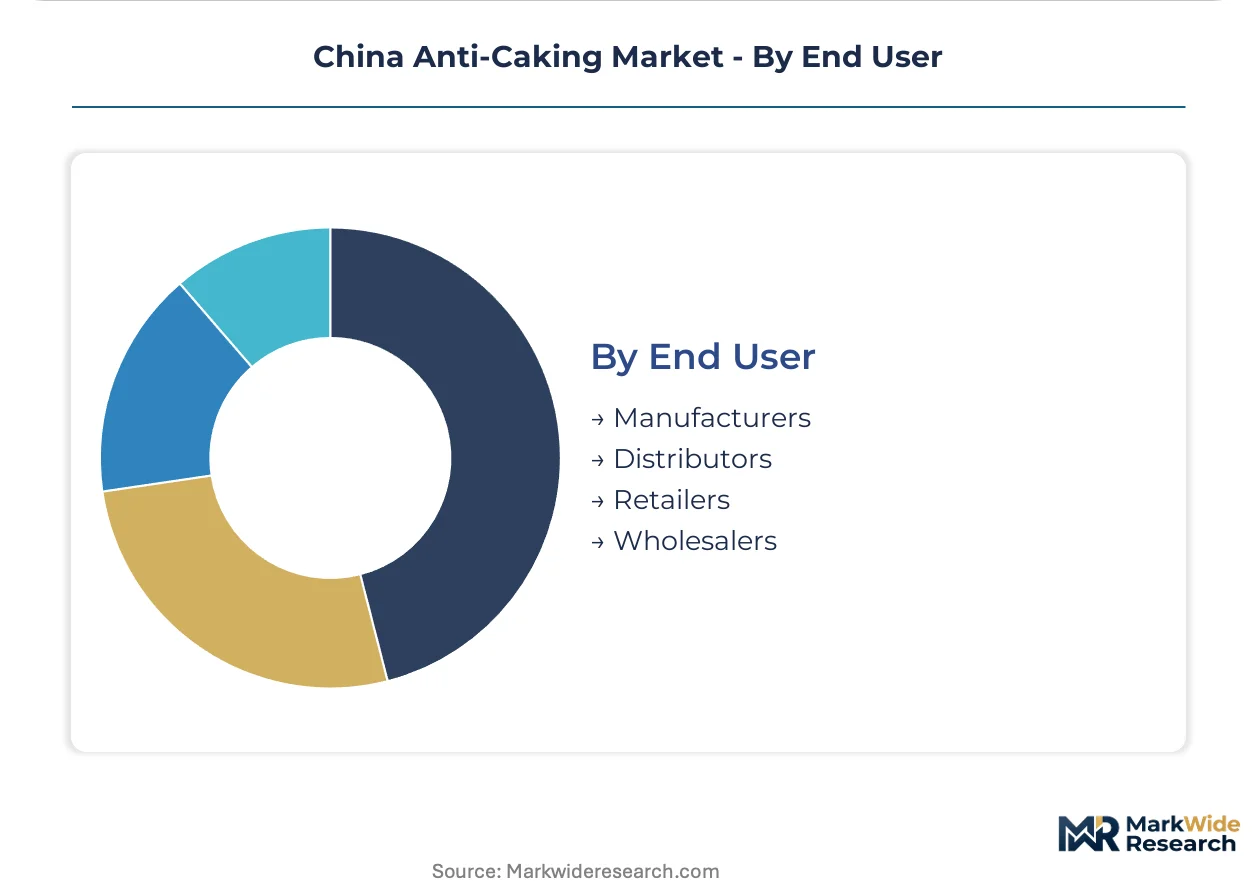
End User:
Channel structure is compressing as direct procurement relationships between fertilizer formulators and coating technology providers displace traditional chemical distributors.
- Manufacturers:Integrated fertilizer, food, and pharmaceutical producers sourcing anti-caking agents as direct inputs. Three Jiangsu compound fertilizer groups now dictate formulation specifications to suppliers through multi-year coating agreements.
- Distributors:Regional chemical traders historically intermediating between anti-caking producers and smaller processors. Margin pressure from direct procurement is forcing consolidation or specialty service pivots.
- Retailers:Limited role in bulk industrial chemical distribution. Occasional presence in packaged food-grade additive sales to small-scale food processors.
- Wholesalers:Volume aggregators serving construction material processors with undifferentiated carbonate grades. Price transparency from digital platforms is eroding traditional markup structures.
Manufacturers anchor procurement volume while distributor channel share contracts under direct sourcing pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ningbo-Zhoushan Port complex anchors anti-caking agent distribution across eastern China, handling silica imports and fertilizer exports through deepwater berths connected to Yangtze River inland waterways.
Jiangsu Province
Compound fertilizer manufacturers in Lianyungang and Nanjing are consolidating procurement around performance-based silica specifications for urea coating lines. SAMR enforcement of GB 2760 additive purity standards is disqualifying legacy carbonate suppliers from premium food manufacturing contracts. The Yangtze River Delta chemical parks host concentrated precipitated silica production serving both agricultural and pharmaceutical-grade demand.
Shandong Province
Weifang and Qingdao fertilizer clusters are scaling automated coating lines that pull sodium silicate formulations for monsoon-season distribution networks. MEE dual carbon emission caps are forcing natural gas retrofits at calcination furnaces above 500-kilowatt thermal input. Provincial ecology departments now require continuous emissions monitoring systems for silica processing permits.
Zhejiang Province
Hangzhou and Ningbo food processors are qualifying magnesium carbonate suppliers under streamlined NMPA DMF filing pathways for infant formula applications. The Ningbo-Zhoushan Port infrastructure supports direct import of high-purity precipitated silica grades for pharmaceutical excipient specifications. Local chemical parks are attracting surface-modified silica producers targeting Southeast Asian export markets.
Henan Province
Zhengzhou's emerging compound fertilizer capacity offers first-mover positioning for coating suppliers with logistics infrastructure west of coastal clusters. The province's central rail hub connects to northwest agricultural markets underserved by existing silica distribution networks. Domestic manufacturers are establishing tolling agreements with Jiangsu technology providers to bypass reactor engineering talent scarcity.
Hubei Province
Jingmen phosphate fertilizer complexes are integrating anti-caking coatings into compound fertilizer output expansion plans. The Yangtze River corridor links these facilities to downstream blending operations in Jiangsu and Anhui. Provincial industrial parks are offering preferential energy pricing to attract silica producers meeting MEE emission intensity benchmarks.
China Anti-Caking Market Competitive Environment
Concentration sits with multinational chemical conglomerates possessing integrated silica technology platforms and established relationships with Chinese fertilizer formulators. The vendor base spans three distinct tiers: global specialty chemical majors with precipitation reactor expertise, regional Chinese manufacturers competing on soda ash feedstock proximity, and niche pharmaceutical-grade importers serving CDSCO-regulated applications. Strategic moves center on direct procurement relationship cultivation with large urea manufacturers and natural gas furnace retrofits to secure operating permits under tightening MEE emission caps.
Among European-headquartered specialty chemical producers, Solvay S.A., Evonik Industries AG, and BASF SE occupy positions exemplifying technology-led competitive archetypes. Solvay S.A. represents silica-based technology leadership serving high-specification agricultural clients. Evonik Industries AG exemplifies specialized precipitated silica grades tailored to humidity-variable storage conditions. BASF SE anchors integrated supply chain positioning reaching Jiangsu and Zhejiang formulation plants. These three entities collectively illustrate how foreign technology providers are defending positioning against domestic carbonate grinding operations through performance-based specification capture.
| Leading Market Players |
|---|
| Solvay S.A. |
| Kao Corporation |
| Evonik Industries AG |
| W. R. Grace & Co. |
| PQ Corporation |
| BASF SE |
| Cabot Corporation |
| IMERYS S.A. |
| PPG Industries Inc. |
| Others |
Value Chain & Pricing Dynamics
Multi-year coating supply agreements between Lianyungang urea manufacturers and Jiangsu silica producers lock in both feedstock access and price visibility across monsoon-season distribution cycles. These contracts insulate compound fertilizer formulators from soda ash volatility while binding anti-caking suppliers to performance-based specification tiers.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, food-certified, and agricultural-grade levels separates magnesium carbonate excipients from sodium silicate commodity coatings. GB 2760 certification status and dual carbon compliance documentation drive price differentiation between domestic and import-substitute tiers. Cost compression in agricultural-grade sodium silicate is intensifying because soda ash contract volatility squeezes mid-tier blender margins. Bulk fertilizer accounts exhibit highest price sensitivity, while infant formula processors accept premium positioning for USP-NF monograph compliance.
Supply Chain Analysis
Strategic stockpiling of surface-modified precipitated silica dominates Jiangsu fertilizer corridor procurement, contrasting with just-in-time carbonate sourcing at Shandong construction material plants. Production gravity centers on Jiangsu, Shandong, and Zhejiang chemical parks, with raw material sourcing drawing from domestic soda ash deposits and imported silane coupling agents. Single-source vulnerability concentrates in sub-5-micron controlled agglomeration technology for pharmaceutical applications. Distribution runs through Ningbo-Zhoushan Port deepwater berths connecting to Yangtze River inland waterways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Anti-caking formulation services and technical support contracts are expanding faster than commodity silica sales, creating service-attach opportunities for suppliers with reactor optimization expertise. Recurring revenue from multi-year coating agreements now exceeds spot transaction growth in Jiangsu fertilizer clusters.
For Market Incumbents: Fortify direct procurement relationships with Lianyungang and Yantai urea manufacturers through integrated technical service teams. Backward integration into silane surface treatment capacity defends margin position against domestic carbonate grinding operations. Natural gas furnace retrofits in Jiangsu chemical parks secure operating permits under tightening MEE emission intensity benchmarks. For New Entrants and Emerging Players: Anchor in Henan and Hubei fertilizer corridor expansion, where Zhengzhou and Jingmen compound capacity lacks established coating supplier relationships. Toll manufacturing partnerships with Jiangsu technology providers bypass reactor engineering talent scarcity. Position through automated liquid coating system integration as Yangtze River Delta plants retrofit precision spray infrastructure. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among surface-modified silica producers with multi-year pharmaceutical excipient qualification pipelines. Long-term viability favors domestic manufacturers achieving NMPA DMF filing pathways for USP-NF monograph compliance. Watch NMPA streamlined approval timelines as inflection indicator for domestic substitution acceleration in CDSCO-regulated applications.| Strategic Initiative | Industry Significance |
|---|---|
| Natural Gas Furnace Retrofit | MEE dual carbon compliance secures operating permits for Jiangsu and Shandong silica calcination facilities. |
| Surface Modification Capacity Addition | Silane treatment lines capture premium positioning in Southeast Asian fertilizer export specifications. |
| Pharmaceutical Excipient Qualification | NMPA DMF filing pathways open domestic substitution opportunities in CDSCO-regulated drug formulations. |
| Automated Liquid Coating Integration | Precision spray systems displace manual powder dosing at Yangtze River Delta fertilizer blending plants. |
| Direct Procurement Relationship Cultivation | Multi-year coating agreements with Lianyungang urea manufacturers compress traditional distributor channels. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across fertilizer formulators in Jiangsu and Shandong, anti-caking plant managers in Yangtze River Delta chemical parks, and SAMR regulatory affairs specialists. Secondary validation drew from MEE emission intensity disclosures, GB 2760 food additive safety standards, customs trade data for precipitated silica imports, and provincial ecology department permit filings. Bottom-up volume modeling triangulated against top-down value estimates from procurement contract analysis.
Across the projection horizon, the analytical framework segmented volume and value by product type, application, physical form, and end-user channel structure. CAGRs were derived from regression analysis of historical procurement patterns and forward-looking capacity expansion announcements. Modeled inputs included soda ash price elasticity coefficients, MEE emission cap implementation timelines, and NMPA DMF filing velocity for pharmaceutical-grade qualifications.
Material uncertainties — regulatory interpretation variance across Shandong and Jiangsu provincial ecology departments, reactor engineering talent scarcity constraining precipitation technology upgrades — sit outside the modeled envelope. Forecasts reflect assumptions about SAMR enforcement consistency and MEE dual carbon benchmark stringency. Revision becomes warranted when provincial emission cap interpretations diverge significantly from national MEE guidance thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Phosphated Distarch Phosphate Market
Food Additives and Ingredients
Carmine Alternatives Market
Food Additives and Ingredients
Asia-Pacific Fermented Ingredient Market
Food Additives and Ingredients
Food Fungal Enzyme Market
Food Additives and Ingredients
Nanoencapsulated Food Additives Market
Food Additives and Ingredients
Spain Food Emulsifiers Market
Food Additives and Ingredients
Global Food Release Agents Market
Food Additives and Ingredients
Global Natamycin Market
Food Additives and Ingredients
Monostarch Phosphate Market
Food Additives and Ingredients
Global Food Bulking Agents Market
Food Additives and Ingredients
Allulose for Food Market
Food Additives and Ingredients
Food Humectants Market
Food Additives and Ingredients
Mexico Food Preservatives Market
Food Additives and Ingredients
South Africa Food Enzymes Market
Food Additives and Ingredients
Alpha-Linolenic Acid Market
Food Additives and Ingredients
Australia Anti Caking Market