
 Food Blue 5 Market | 2026-2036
Food Blue 5 Market Size, Share, and Industry Trends Forecast 2026-2036
Food Blue 5 Market Foresight
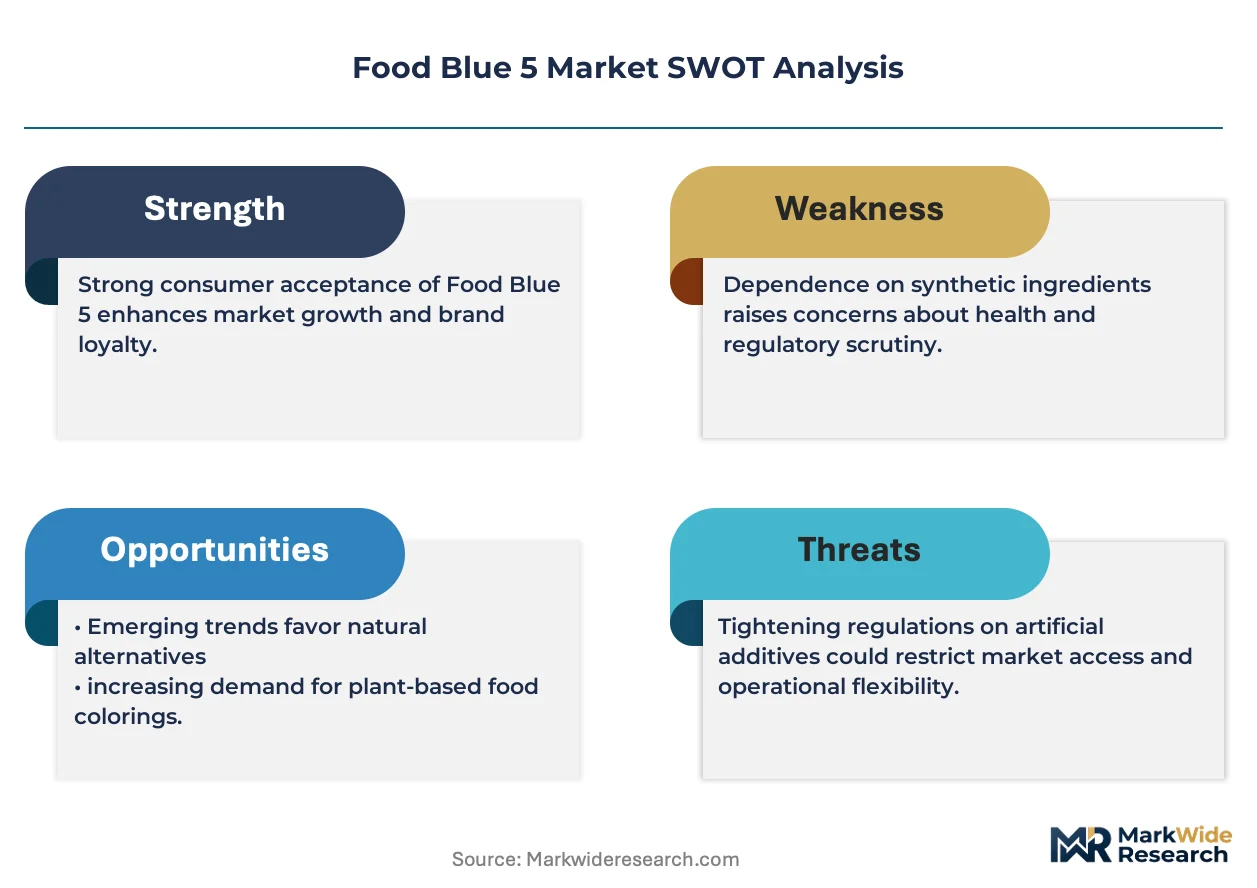
Asset-light toll manufacturing and third-party colorant blending is tilting competitive dynamics toward smaller regional formulators. Sensient Colors LLC leverages captive extraction capabilities to sustain margin control across natural and synthetic pigment lines. Chr. Hansen Holding A/S anchors its position through deep fermentation-derived colorant expertise. DDW differentiates via heritage positioning in caramel and burnt sugar adjacencies that complement blue colorant portfolios.
Food Blue 5 denotes the synthetic colorant Brilliant Blue FCF, a triphenylmethane dye with maximum absorption near 630 nm, manufactured through sulfonation and copper-complex formation to yield the disodium salt of ethyl[4-[p-[ethyl(m-sulfobenzyl)amino]-alpha-(o-sulfophenyl)benzylidene]-2,5-cyclohexadien-1-ylidene](m-sulfobenzyl)ammonium hydroxide. The liquid formulation segment leads volume share due to dosing precision in automated beverage lines, while powder grades command premium positioning in dry-mix bakery applications where shelf stability determines procurement decisions. Confectionery end users increasingly specify low-moisture powder variants to prevent bleeding across layered candy matrices.
The FDA maintains strict batch certification requirements for Food Blue 5 under 21 CFR 74.101, while EFSA enforces purity thresholds through the re-evaluation program for food additives. India's FSSAI alignment with Codex specifications is reshaping import documentation burdens for multinational suppliers. Stakeholders must monitor evolving maximum permitted level revisions across major import jurisdictions to preempt reformulation cycles.
Market Dynamics
The EU's Food Improvement Agent Package is compressing synthetic dye specifications while beverage processors accelerate clean-label procurement, creating simultaneous pull and push forces that reshape supplier positioning across formulation tiers.
Growth Catalysts
- FSSAI Codex Alignment:India's harmonization with international purity standards is streamlining import documentation for multinational colorant suppliers entering South Asian confectionery markets.
- Automated Beverage Lines:Liquid Food Blue 5 formulations are capturing volume share through dosing precision in high-speed bottling operations across North American soft drink manufacturing.
- German Premium Confectionery:Layered candy manufacturers are specifying low-moisture powder variants to prevent bleeding across product matrices, concentrating demand in Europe's high-value segment.
Market Restraints
- Copper Complex Input Volatility:Sulfonation and copper-complex formation chemistry ties production costs to metal commodity swings, squeezing margin predictability for triphenylmethane dye manufacturers.
- FDA Batch Certification Burden:21 CFR 74.101 mandates individual lot testing for Food Blue 5, creating timeline friction and inventory holding costs that disadvantage smaller formulators.
- Natural Colorant Substitution:Spirulina-derived blue alternatives are capturing clean-label share in premium beverage applications, threatening synthetic positioning in health-positioned product lines.
Strategic Opportunities
- EFSA Re-Evaluation Tailwind:The ongoing food additive re-evaluation program creates openings for suppliers demonstrating enhanced purity profiles to secure preferred supplier status with reformulating manufacturers.
- Dry-Mix Bakery Channel:Powder grade shelf stability requirements are opening premium positioning in automated bakery premix operations where moisture control determines procurement decisions.
- Toll Manufacturing Convergence:Asset-light third-party colorant blending is enabling regional formulators to compete without captive extraction infrastructure, lowering capital barriers to market entry.
Industry Challenges
- Fermentation Expertise Scarcity:Natural blue alternatives require specialized bioprocess engineering talent that concentrates in Danish and Dutch biotechnology clusters, creating recruitment bottlenecks for synthetic suppliers pivoting to hybrid portfolios.
- Maximum Permitted Level Tracking:Multinational suppliers must monitor evolving MPL revisions across FDA, EFSA, and FSSAI jurisdictions simultaneously, multiplying compliance documentation complexity and reformulation cycle risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Blue 5 Market |
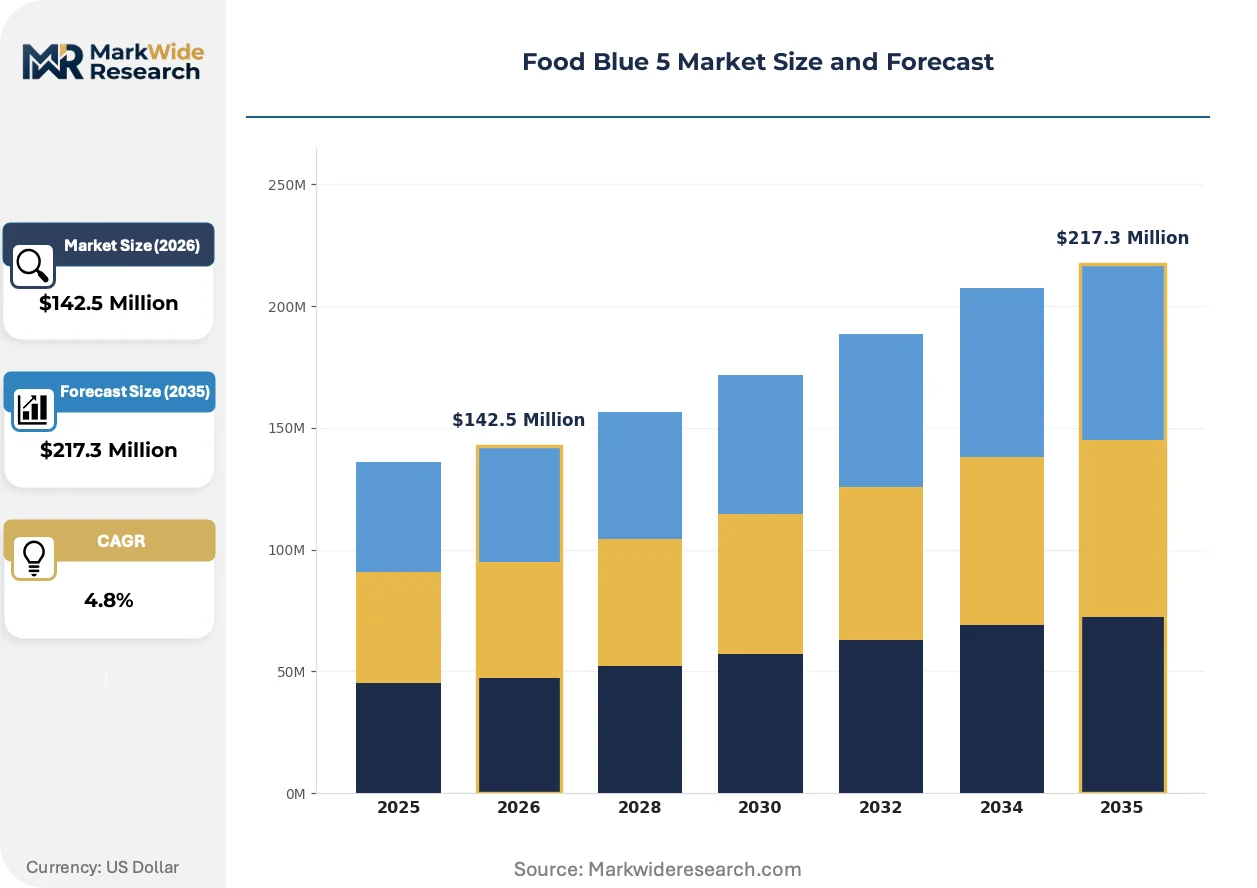
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $217.3 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Paste, Granules Application: Beverages, Confectionery, Dairy Products, Bakery End User: Food Manufacturers, Beverage Processors, Bakeries, Confectioners Packaging Type: Glass Bottles, Plastic Containers, Sachets, Bulk Bags |
| Companies Covered | Sensient Colors LLC, Symrise AG, Chr. Hansen Holding A/S, DIC Corporation, Archer Daniels Midland Company, DSM, Givaudan, DDW, San-Ei Gen F.F.I., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Blue 5 Market Shifts & Advancements
Spectrophotometric quality control and batch-level traceability systems are digitizing how colorant consistency is verified, while regulatory divergence between major import jurisdictions forces parallel specification management.
Inline spectrophotometry is digitizing real-time colorant verification at production lines. Beverage bottlers in the United States are adopting these systems to reduce offline laboratory testing cycles. The technology is digitizing quality assurance workflows, compressing batch release timelines from hours to minutes and reducing FDA certification documentation preparation burden.
REACH substance evaluation expansions are extending scrutiny to triphenylmethane dye metabolites. Industrial consequence includes mandatory extended toxicity dossier submissions for continued market access. German confectionery exporters are responding by accelerating natural colorant blend development to preempt authorization uncertainty.
Direct procurement from specialized colorant formulators is displacing traditional distributor intermediation in North American beverage manufacturing. Large soft drink processors are establishing preferred supplier agreements with toll manufacturers possessing captive extraction capabilities. This pattern concentrates most visibly in California and Texas production corridors where clean-label formulation mandates from retail buyers drive supplier consolidation.
Food Blue 5 Market Segmentation
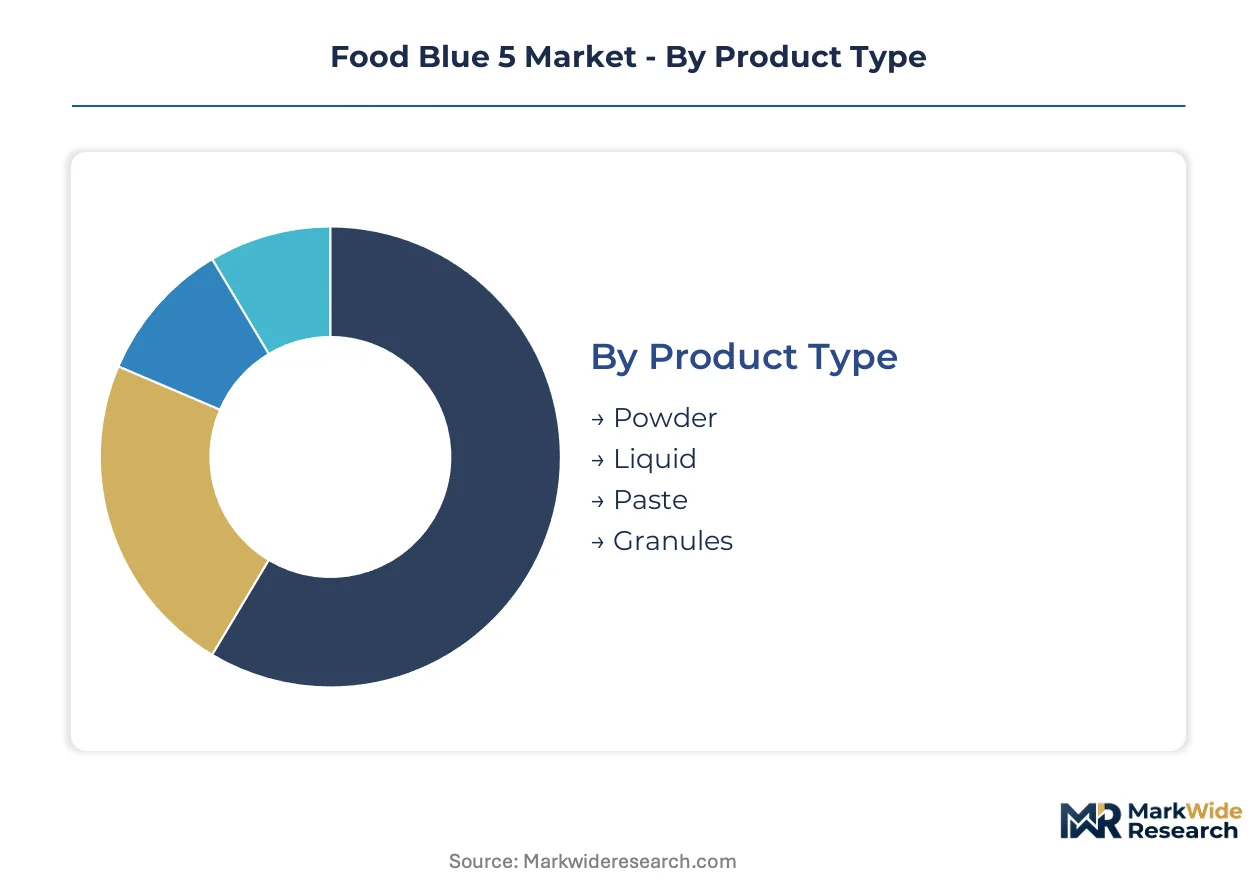
Food Blue 5 procurement patterns diverge sharply across physical formats and end-use specifications. Automated dosing systems favor liquid delivery, while shelf-stability requirements in dry-mix channels elevate powder premiums. Understanding these segment boundaries clarifies where formulation investments concentrate versus where toll manufacturing suffices.
Product Type:
Liquid formulations dominate high-throughput beverage operations where precision metering determines batch consistency, while powder grades command premium positioning in moisture-sensitive applications.
- Liquid:Aqueous solutions with standardized dye concentrations enable automated dosing in high-speed bottling lines. Beverage processors in Texas and California production corridors specify liquid delivery to minimize batch-to-batch variation and reduce offline laboratory testing cycles.
- Powder:Spray-dried or precipitated crystalline grades with controlled particle size distribution optimize reconstitution properties. German premium confectionery manufacturers specify low-moisture powder variants to prevent bleeding across layered candy matrices where moisture migration compromises visual integrity.
- Paste:High-solids concentrated suspensions suit artisanal bakery applications requiring manual incorporation.
- Granules:Free-flowing agglomerated forms address dust-control priorities in industrial dry-mix operations.
The dominant share belongs to Liquid, while Powder is closing the gap fastest through premium positioning in clean-label confectionery.
Application:
End-use differentiation tracks regulatory exposure and visual performance requirements across formulation categories.
- Beverages:Carbonated soft drinks, sports drinks, and flavored waters constitute the volume anchor. FDA batch certification under 21 CFR 74.101 creates compliance documentation burdens that favor suppliers with dedicated regulatory affairs infrastructure.
- Confectionery:Hard candies, gummies, and panned coatings demand heat-stable colorant performance during high-temperature processing. EFSA purity threshold enforcement through the re-evaluation program is compressing synthetic dye specifications and accelerating natural blend development among German exporters.
- Dairy Products:Ice cream and flavored milk applications require fat-compatible dispersion systems.
- Bakery:Dry-mix premixes and frostings prioritize shelf-stable powder grades with extended color retention.
Beverages maintains volume leadership, though Confectionery is expanding most quickly through premiumization in European markets.
End User:
Customer scale and captive formulation capability determine procurement channel selection and supplier relationship intensity.
- Food Manufacturers:Integrated processors with in-house R&D laboratories negotiate directly with colorant formulators. Large soft drink manufacturers are establishing preferred supplier agreements with toll manufacturers possessing captive extraction capabilities, displacing traditional distributor intermediation.
- Beverage Processors:Specialized bottling operations concentrate procurement decisions in automated production corridors where clean-label mandates from retail buyers drive supplier consolidation.
- Bakeries:Regional and artisanal operations rely on distributor networks for smaller-volume powder procurement.
- Confectioners:Layered candy specialists specify technical-grade powders with documented moisture specifications.
Food Manufacturers command the largest procurement volumes, while Beverage Processors are gaining negotiating leverage fastest through direct sourcing consolidation.
Packaging Type:
Packaging selection tracks handling scale, contamination risk, and inventory turnover velocity across customer tiers.
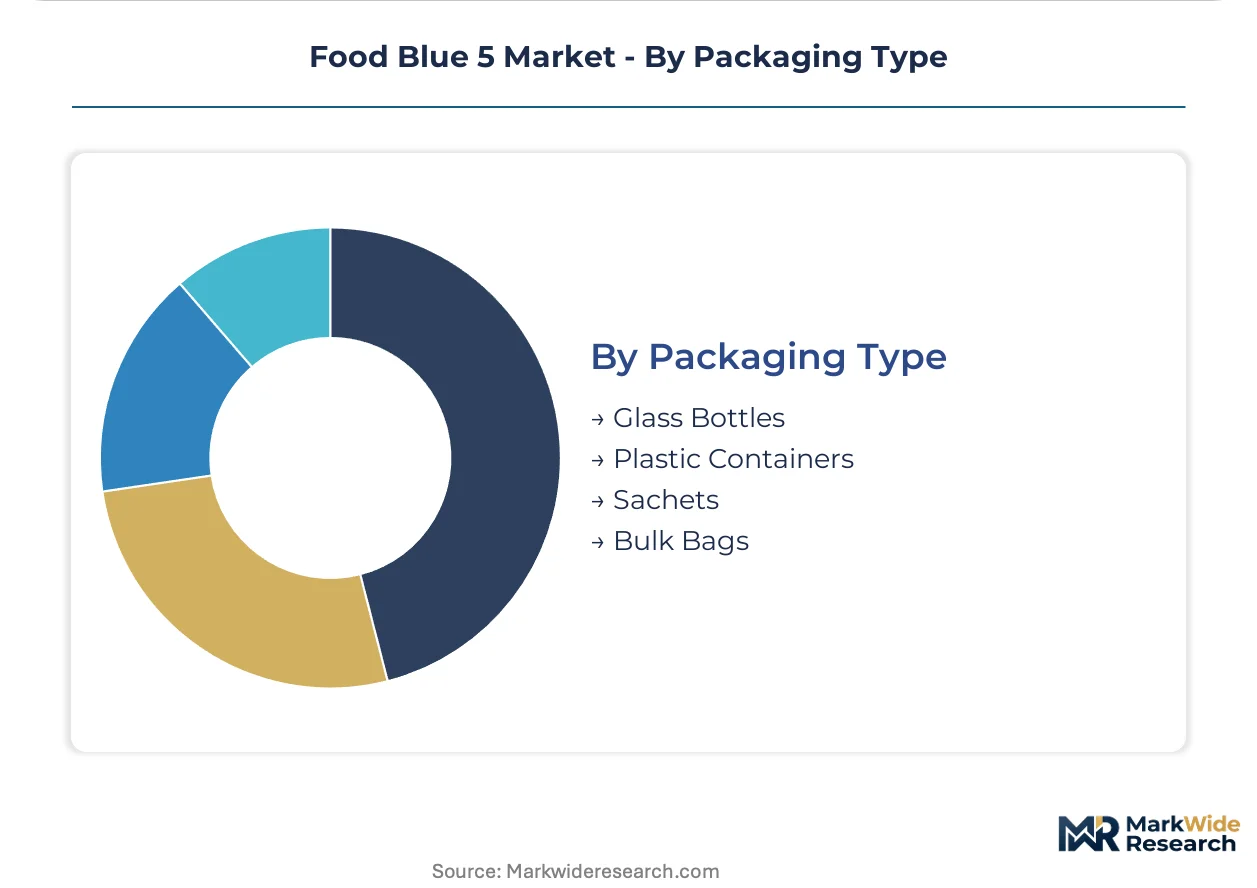
- Glass Bottles:Amber or cobalt glass containers protect photosensitive liquid formulations during extended storage. Premium beverage brands specify glass for brand positioning alignment, though freight costs constrain geographic distribution radius.
- Plastic Containers:High-density polyethylene drums and totes dominate industrial liquid procurement. North American beverage processors favor plastic for cost efficiency in high-volume automated lines.
- Sachets:Single-use foil laminations serve artisanal bakeries and small-batch confectioners with intermittent usage patterns.
- Bulk Bags:Flexible intermediate bulk containers address powder procurement at industrial food manufacturing scale.
Plastic Containers holds the dominant position, with Bulk Bags climbing fastest through dry-mix bakery channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA's Food Improvement Agent Package is tightening purity specifications across European confectionery supply chains, while India's FSSAI Codex alignment is streamlining import documentation for multinational colorant suppliers. These regulatory shifts are redistributing procurement decisions toward jurisdictions with harmonized standards.
United States
Automated beverage bottling corridors in Texas and California are driving liquid Food Blue 5 procurement volumes. FDA batch certification under 21 CFR 74.101 creates compliance documentation burdens that favor suppliers with dedicated regulatory affairs infrastructure. Inline spectrophotometry adoption in Midwest production facilities is compressing batch release timelines from hours to minutes.
Germany
Premium confectionery manufacturers in Bavaria and North Rhine-Westphalia are specifying low-moisture powder variants to prevent bleeding across layered candy matrices. REACH substance evaluation expansions are extending scrutiny to triphenylmethane dye metabolites, forcing mandatory extended toxicity dossier submissions. Hamburg-based exporters are accelerating natural colorant blend development to preempt authorization uncertainty.
India
FSSAI harmonization with Codex specifications is reshaping import documentation burdens for multinational suppliers entering South Asian markets. Maharashtra's confectionery processing clusters are expanding synthetic dye procurement as domestic production scales. Gujarat-based food manufacturers are negotiating directly with toll manufacturers to bypass traditional distributor intermediation.
Japan
San-Ei Gen F.F.I.'s domestic positioning anchors synthetic colorant demand within precision-oriented food manufacturing. METI standards alignment with international purity specifications is streamlining cross-border procurement for multinational beverage processors. Osaka-Kobe industrial corridors concentrate high-throughput bottling operations specifying liquid formulation delivery systems.
Brazil
ANVISA enforcement of food additive purity thresholds is compressing synthetic dye specifications for confectionery exporters. São Paulo state's beverage processing corridors are adopting automated dosing systems that favor liquid Food Blue 5 procurement. Minas Gerais-based dairy manufacturers are specifying fat-compatible dispersion systems for ice cream and flavored milk applications.
Food Blue 5 Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers: multinational pigment houses with captive extraction infrastructure, specialized fermentation-derived colorant specialists, and asset-light toll manufacturers serving regional formulators. Strategic archetypes include backward-integrated extraction operators, hybrid natural-synthetic portfolio builders, and third-party blending service providers. Dominant competitive moves center on preferred supplier agreement consolidation with large beverage processors and geographic expansion through toll manufacturing partnerships.
Within the hybrid portfolio tier, Sensient Colors LLC and Chr. Hansen Holding A/S exemplify divergent strategic anchors. Sensient leverages captive extraction capabilities across natural and synthetic pigment lines, while Chr. Hansen anchors positioning through fermentation-derived colorant expertise. DDW occupies a heritage-focused position in caramel and burnt sugar adjacencies that complement blue colorant portfolios. Among European-headquartered specialists, Symrise AG and Givaudan sit within the flavor-color integration archetype, while DIC Corporation represents Japanese precision manufacturing capabilities. Archer Daniels Midland Company and DSM exemplify agricultural-input-to-colorant vertical integration strategies.
| Leading Market Players |
|---|
| Sensient Colors LLC |
| Symrise AG |
| Chr. Hansen Holding A/S |
| DIC Corporation |
| Archer Daniels Midland Company |
| DSM |
| Givaudan |
| DDW |
| San-Ei Gen F.F.I., Inc. |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese sulfonation facilities is compressing spot pricing for triphenylmethane dye intermediates while simultaneously pushing European toll manufacturers toward long-term offtake contracts to secure margin predictability.
Pricing Analysis
Certification level creates the primary spread across Food Blue 5 procurement tiers. FDA-grade liquid formulations command substantial premiums over FSSAI-aligned import grades due to batch certification documentation burdens. Powder grades with documented low-moisture specifications attract further premiums from German confectionery exporters. Cost compression in standard-grade liquid supply is intensifying as Indian toll manufacturers expand sulfonation capacity.
Supply Chain Analysis
Contract manufacturing concentration rests with Sensient Colors LLC and Chr. Hansen Holding A/S, which maintain captive extraction infrastructure across North American and European production hubs. Sulfonation chemistry feeds from copper complex and benzene derivative inputs sourced primarily from Chinese and German chemical corridors. Single-source vulnerability concentrates in copper sulfate supply from Chilean mining operations. Distribution runs through direct procurement agreements with large beverage processors, displacing traditional distributor networks in Texas and California bottling corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food Blue 5 procurement is evolving into a service-attach opportunity as regulatory compliance documentation and inline spectrophotometry integration expand faster than base colorant volume growth.
For Market Incumbents: Harden regulatory affairs infrastructure to preempt EFSA re-evaluation documentation requirements while accelerating natural colorant blend development to counter spirulina-derived substitution threats. Backward integration into copper complex supply chains secures margin control against metal commodity volatility. For New Entrants and Emerging Players: Pursue toll manufacturing partnerships with Indian FSSAI-certified facilities to serve South Asian confectionery expansion while targeting dry-mix bakery channels where powder grade shelf stability requirements create technical barriers to incumbent liquid-focused portfolios. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because asset-light regional formulators lack the capital intensity to match captive extraction capabilities. Acquisition targets should demonstrate fermentation-derived colorant expertise or established preferred supplier agreements with automated beverage bottling corridors. The signal to watch is FDA batch certification timeline compression as inline spectrophotometry adoption accelerates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Complex Supply | Captive sulfonation inputs insulate margin from Chilean mining commodity swings. |
| EFSA Re-Evaluation Compliance Investment | Enhanced purity dossiers secure preferred supplier status with reformulating German exporters. |
| Fermentation-Derived Colorant R&D Partnership | Bioprocess engineering access addresses natural substitution threats in premium beverage tiers. |
| Direct Procurement Agreement Consolidation | Bypassing distributor intermediation captures margin from Texas and California bottling corridors. |
| Inline Spectrophotometry Service Bundling | Real-time quality verification reduces FDA certification documentation preparation burden. |
Research Methodology
Cross-validation between primary interviews with colorant procurement managers, regulatory affairs directors at multinational food manufacturers, toll manufacturing operators, and bakery premix formulators anchors the qualitative findings against secondary validation through FDA 21 CFR filings, EFSA food additive re-evaluation dossiers, FSSAI import documentation records, and customs trade data. Bottom-up segmentation modeling triangulates against top-down market sizing.
Calibration against historical volume trajectories and documented capacity expansions informs the projection framework across the analysis window. Segmentation dimensions include physical format, application category, end-user scale tier, and regional regulatory cluster. CAGRs derive from weighted average growth assumptions applied to each segment, with specific inputs from beverage bottling automation adoption rates and confectionery premiumization indices.
Macroeconomic conditions sit as an overlay; deviation in copper commodity pricing, euro-dollar exchange rates, or Indian import tariff schedules would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory timeline adherence and technology adoption curves. Quarterly review of EFSA re-evaluation announcements, FSSAI Codex alignment implementation, and toll manufacturing capacity utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Argentina Food Acidulants Market
Food Additives and Ingredients
North America Food Anti Caking Agents Market
Food Additives and Ingredients
Italy Food Additives Market
Food Additives and Ingredients
Lactoperoxidase Market
Food Additives and Ingredients
North America Food Additives Market
Food Additives and Ingredients
France Feed Additives Market
Food Additives and Ingredients
Food Inclusions Market
Food Additives and Ingredients
China Emulsifiers Market
Food Additives and Ingredients
Liquid Caramel Color Market
Food Additives and Ingredients
Argentina Gellan Gum Market
Food Additives and Ingredients
Granulated Tapioca Market
Food Additives and Ingredients
Wine Fining Agent Market
Food Additives and Ingredients
Glandular Ingredients Market
Food Additives and Ingredients
Natural Food Preservatives Market
Food Additives and Ingredients
Bread Preservatives Market
Food Additives and Ingredients
Emulsifiers Market