
 Microbial Food Culture Market | 2026-2036
Microbial Food Culture Market Size, Share, and Industry Trends Forecast 2026-2036
Microbial Food Culture Market Outlook
The EU Green Deal is realigning starter culture procurement across European dairy supply chains. Chr. Hansen leverages deep strain libraries to dominate culture supply for continental cheese producers. Kerry Group PLC anchors North American bakery culture demand through specialized yeast portfolios. Lallemand Inc competes in probiotic applications with manufacturing scale across multiple fermentation platforms.
Microbial food cultures consist of viable bacteria, yeasts, or molds propagated under controlled fermentation conditions, typically delivered at concentrations exceeding 10^9 CFU per gram for industrial inoculation. These cultures drive acidification, flavor biogenesis, and texture modification in commercial food manufacturing. Bacterial cultures command the largest share of industrial volume due to indispensability in cheese and yogurt production. Yeast cultures generate premium margins in craft beverage segments where strain-specific aromatic profiles differentiate supplier offerings. Probiotic cultures represent the fastest-expanding category as functional food positioning intensifies across retail channels.
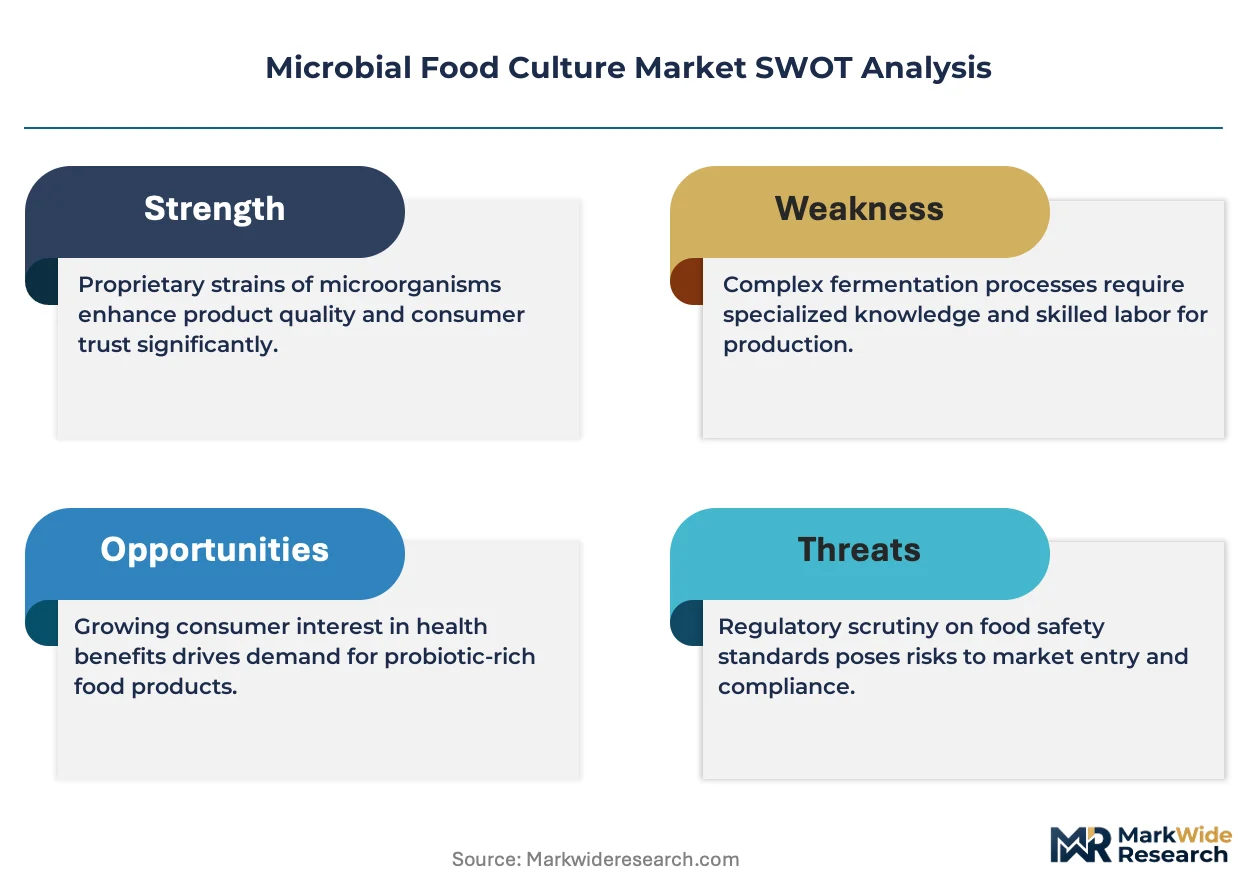
EFSA novel food assessments and FDA GRAS notifications create dual compliance thresholds for culture suppliers seeking transatlantic market access. EMA pharmacovigilance frameworks and WHO Codex guidelines on probiotics further constrain health claim substantiation, forcing reformulation investments. Stakeholders must monitor evolving strain-level regulatory classifications to preempt market exclusion.
Market Dynamics
Strain-level regulatory reclassification under EU Green Deal sustainability protocols is forcing wholesale reformulation of starter culture supply chains across European dairy manufacturing.
Growth Catalysts
- EU Green Deal strain selection mandates:Dairy processors in Germany and France must now document carbon footprint per culture batch, creating procurement urgency for verified low-emission strains.
- Fermented beverage functional positioning:METI guidelines in Japan and MFDS standards in South Korea explicitly permit digestive health claims for specified probiotic strains, accelerating category-specific culture demand.
- Precision fermentation infrastructure:Bioreactor capacity expansion in Singapore and Denmark enables contract manufacturing of high-value yeast cultures for craft beverage producers seeking aromatic differentiation.
Market Restraints
- Freeze-dried culture input cost volatility:Skim milk powder and cryoprotectant prices swing with dairy commodity cycles, compressing margins for culture suppliers without backward integration into fermentation media production.
- Strain IP concentration:Patent thickets around Lactobacillus rhamnosus GG and comparable flagship strains limit new entrants to royalty-bearing licensing arrangements with incumbent culture houses.
- EFSA novel food assessment timelines:Strain-specific safety dossiers require 18-24 month review cycles, freezing product pipelines for suppliers lacking pre-approved strain libraries.
Strategic Opportunities
- Alternative protein fermentation:Mycoprotein and precision fermentation meat startups in the Netherlands and Israel require specialized fungal and bacterial cultures currently underserved by dairy-focused suppliers.
- Direct-to-manufacturer digital platforms:Culture suppliers bypassing distributor networks can capture margin from mid-sized plant-based dairy processors in California and Victoria lacking technical service access.
- Indian FSSAI probiotic notification pathway:India's 2022 functional food regulations created a streamlined strain approval mechanism for documented cultures, opening a previously restricted market for validated suppliers.
Industry Challenges
- PhD-level strain characterization talent scarcity:Genomic screening and metabolomic profiling capabilities require specialized fermentation scientists concentrated in Danish and Dutch research clusters.
- Multi-site GMP certification burden:Culture suppliers serving both food and pharmaceutical probiotic markets must maintain simultaneous FDA GRAS, EFSA QPS, and Health Canada NHP compliance across production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microbial Food Culture Market |
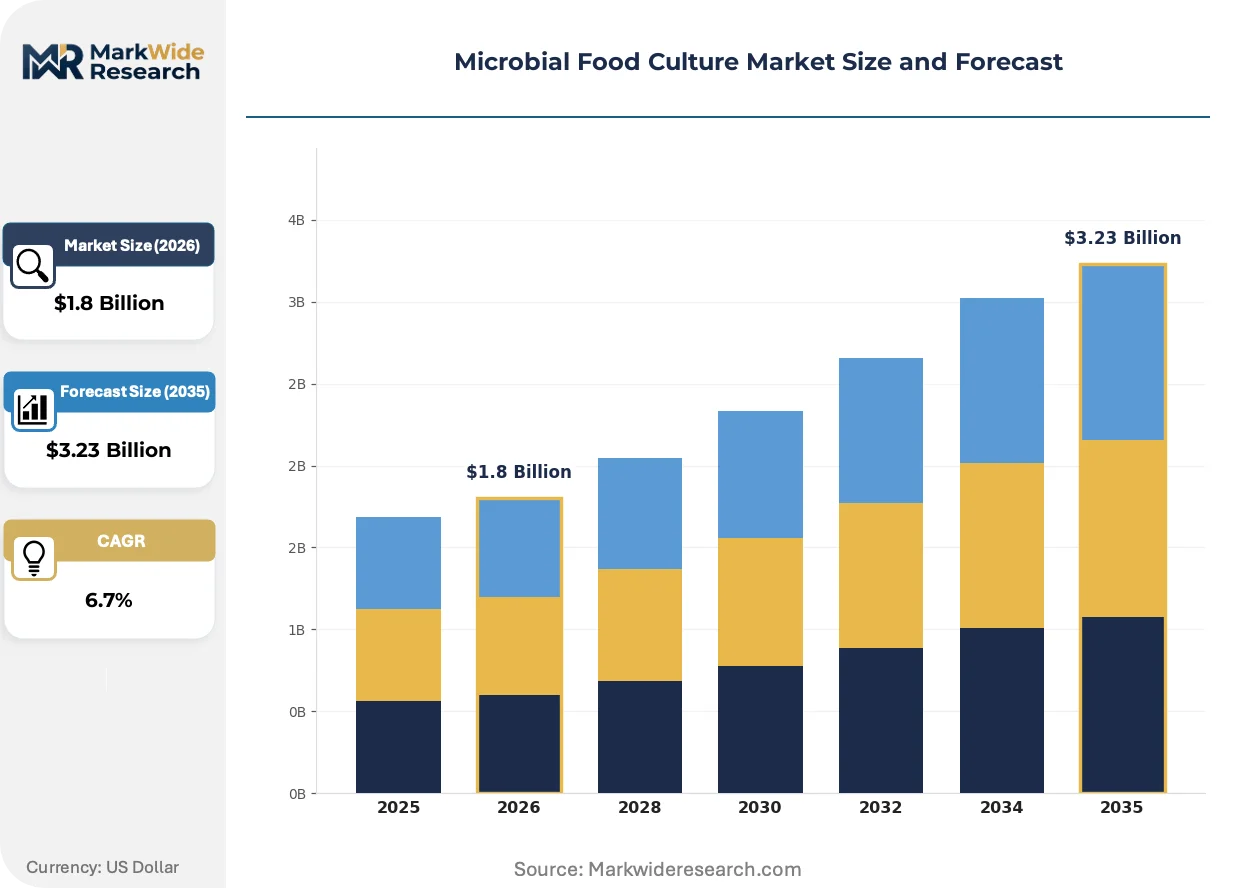
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bacterial Cultures, Yeast Cultures, Fungal Cultures, Probiotic Cultures Application: Fermented Beverages, Dairy Products, Bakery Items, Meat Products End User: Food Manufacturers, Restaurants, Home Cooks, Catering Services Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Corbion NV, Lallemand Inc, Kerry Group PLC, CSK Food Enrichment, Chr. Hansen, Koninklijke DSM NV, Cargill Incorporated, UAS Labs, DuPont de Nemours Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microbial Food Culture Market Strategic Shifts
Next-generation sequencing and CRISPR-based strain engineering are compressing development timelines while regulatory frameworks race to classify novel organism categories.
CRISPR-edited starter cultures with enhanced phage resistance and accelerated acidification kinetics are expanding into continental European cheese manufacturing. Dutch and Italian mozzarella producers pilot these strains to reduce vat turnover time without altering proteolytic flavor profiles. Traditional culture suppliers face pressure to demonstrate equivalent performance or cede share to gene-edited alternatives.
EU F-Gas Regulation phase-down schedules are forcing refrigeration-dependent culture supply chains toward cryogenic shipping alternatives. Logistics providers in Belgium and Germany now offer liquid nitrogen container services for high-value probiotic strains, though this adds 15-20 percent to landed costs. Smaller culture houses without cold-chain scale concentrate on ambient-stable dried formats.
Foodservice operators in Japan and South Korea now specify strain-level documentation for fermented menu items, mirroring pharmaceutical-grade traceability expectations. This certification-driven preference shift compresses supplier qualification timelines and favors culture houses with integrated quality management systems. Independent regional culture producers without ISO 22000 certification face exclusion from premium channel procurement.
Microbial Food Culture Market Segmentation
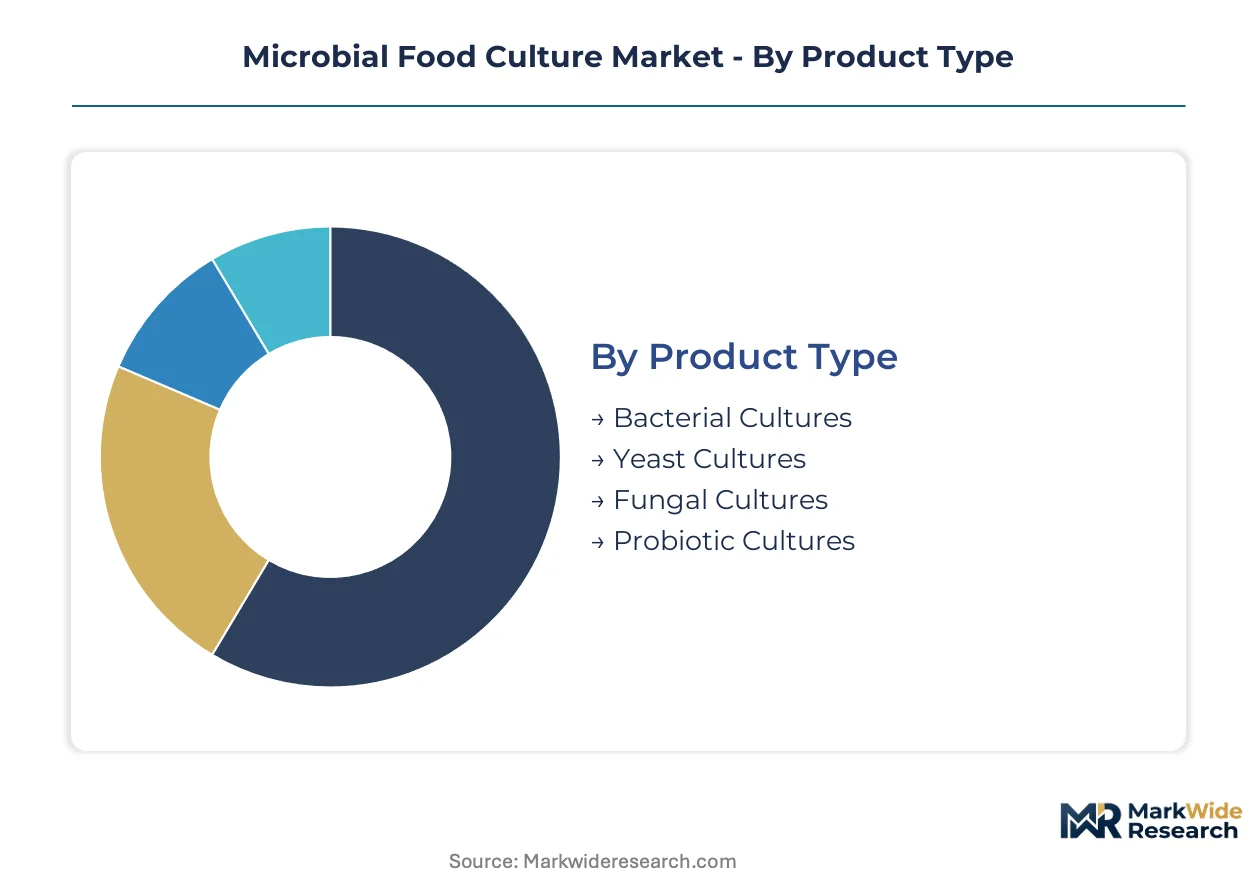
Segmentation in microbial food cultures reveals distinct capital requirements, technical barriers, and margin profiles that shape supplier positioning. Each dimension—product chemistry, application target, end-user scale, and channel structure—imposes different fermentation infrastructure investments and regulatory compliance burdens.
Product Type:
Bacterial cultures demand the heaviest upfront investment in bioreactor capacity and phage-containment infrastructure, while probiotic strains require parallel pharmaceutical-grade GMP certification.
- Bacterial Cultures:Mesophilic and thermophilic starter strains for cheese and yogurt production require 10,000+ liter fermentation vessels with strict phage isolation protocols. Demand concentrates among German and French dairy cooperatives facing EU Green Deal carbon accounting mandates for culture batch documentation.
- Probiotic Cultures:Live microorganisms delivered at 10^9–10^11 CFU/gram with documented strain-specific health benefits. Japanese and South Korean fermented beverage manufacturers drive procurement under METI and MFDS functional claim guidelines that permit digestive health positioning for validated strains.
- Yeast Cultures:Saccharomyces and non-Saccharomyces strains for alcoholic fermentation and flavor modulation, typically requiring lower capital intensity than bacterial systems but premium pricing in craft beverage segments.
- Fungal Cultures:Molds including Penicillium and Aspergillus species for cheese ripening and alternative protein fermentation, with demand emerging from Dutch and Israeli mycoprotein startups.
Bacterial cultures absorb the bulk of installed capacity; probiotic cultures are expanding most quickly.
Application:
Application segmentation tracks where culture functionality commands price premiums versus commodity positioning, with fermented beverages and dairy products representing divergent margin architectures.
- Dairy Products:Cheese, yogurt, and fermented milk applications consume the largest culture volumes by mass, with starter culture performance directly determining manufacturing throughput and yield economics.
- Fermented Beverages:Kombucha, kefir, and functional drinks leverage strain-specific aromatic and health-positioning attributes. Japanese beverage manufacturers now require strain-level documentation mirroring pharmaceutical traceability standards.
- Bakery Items:Sourdough starters and yeast leavening systems, with North American demand anchored by specialized yeast portfolios from established suppliers.
- Meat Products:Fermented and cured meat applications including starter cultures for salami and dry sausage production, representing a smaller volume segment with regional concentration in Mediterranean and Eastern European processing.
Dairy applications command the greatest absolute volume; fermented beverages show the steepest expansion trajectory.
End User:
End-user scale determines technical service intensity, with food manufacturers requiring integrated strain optimization support while foodservice operators prioritize certification documentation.
- Food Manufacturers:Industrial-scale dairy, beverage, and bakery processors purchasing cultures in bulk with embedded technical service for strain selection and process integration.
- Restaurants:Foodservice operators in Japan and South Korea increasingly specifying strain-level provenance for fermented menu items, compressing supplier qualification timelines.
- Catering Services:Mid-scale prepared food operations with growing interest in house-fermented products but limited in-house microbiological expertise.
- Home Cooks:Consumer-packaged cultures through retail channels, a marginal segment with seasonal demand concentration.
Food manufacturers represent the dominant procurement volume; restaurants are gaining share fastest as certification requirements spread.
Distribution Channel:
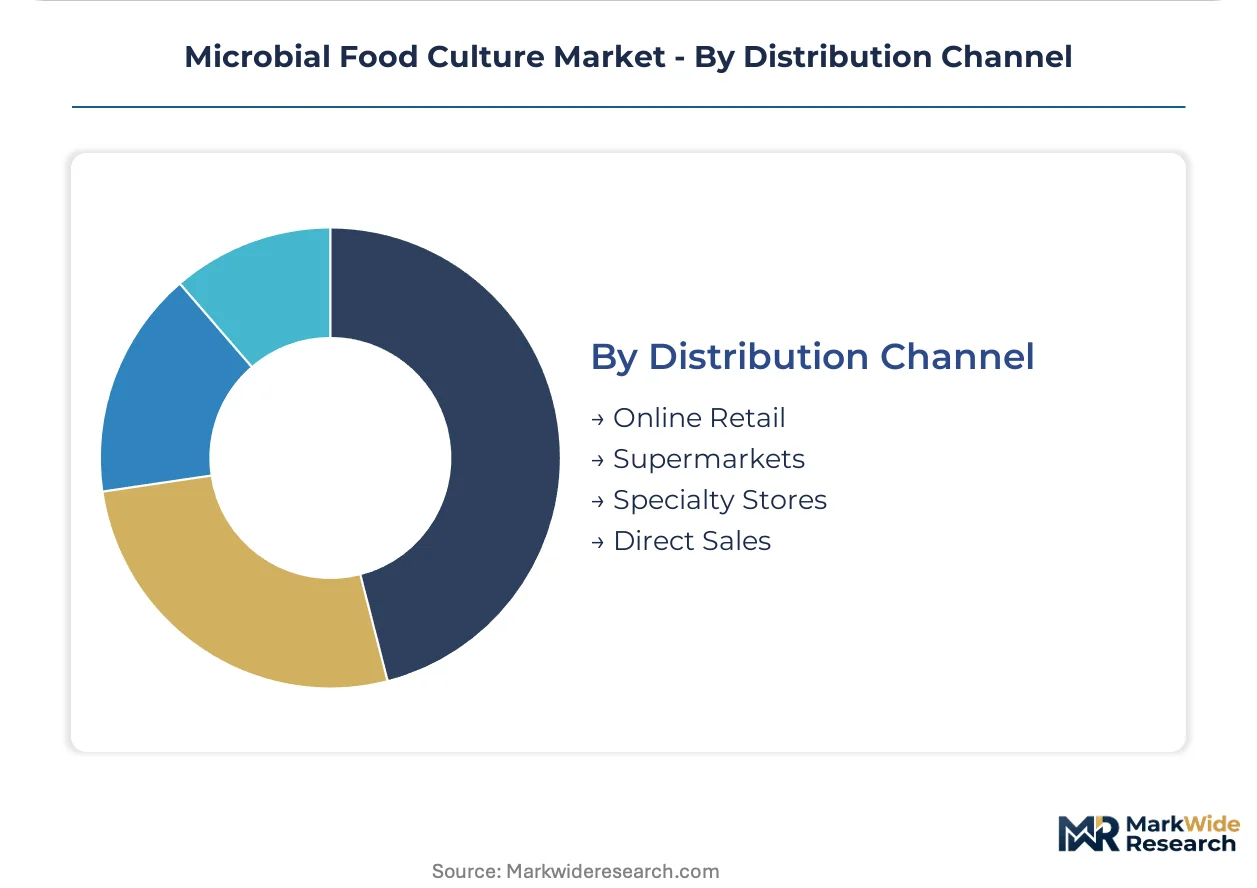
Channel structure reflects customer scale and technical complexity, with direct sales capturing the most sophisticated accounts and online retail emerging for underserved mid-market processors.
- Direct Sales:Technical field teams serving multinational dairy and beverage processors with customized strain development and fermentation optimization support.
- Specialty Stores:Regional distributors with technical expertise serving craft producers and smaller manufacturers lacking direct supplier relationships.
- Supermarkets:Limited culture availability through food ingredient aisles, primarily for consumer-oriented applications.
- Online Retail:Digital platforms enabling culture suppliers to bypass distributor networks and capture margin from mid-sized plant-based dairy processors in California and Victoria lacking technical service access.
Direct sales channels handle the majority of high-value culture volume; online retail is climbing the fastest as platform infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copenhagen anchors the global microbial food culture industry through concentrated fermentation science expertise and regulatory influence. The city hosts specialized strain libraries and phage-containment facilities that supply continental European dairy cooperatives. This Danish concentration shapes procurement standards across multiple jurisdictions.
United States
Wisconsin and California dairy processors drive starter culture procurement volumes under FDA GRAS notification requirements. The FDA maintains dual compliance thresholds for transatlantic market access alongside EFSA standards. Madison and Fresno manufacturing clusters now document carbon footprint per culture batch to satisfy emerging sustainability audit demands from multinational customers.
Germany
Bavarian cheese cooperatives expand mesophilic culture procurement as EU Green Deal strain selection mandates tighten documentation protocols. The European Commission's sustainability criteria now require verified low-emission strain verification for public procurement eligibility. Munich-based technical service teams embed directly into dairy processing facilities to optimize fermentation kinetics.
Japan
Tokyo and Osaka beverage manufacturers concentrate probiotic culture demand under METI functional food guidelines that explicitly permit digestive health claims. The Ministry of Economy, Trade and Industry maintains strain-specific approval lists that accelerate product development timelines. Kanto region fermentation facilities now require pharmaceutical-grade traceability documentation mirroring foodservice operator specifications.
South Korea
Seoul Capital Area kefir and kombucha producers drive premium culture procurement under MFDS standards governing live microorganism health claims. The Ministry of Food and Drug Safety operates accelerated strain validation pathways for documented cultures from established suppliers. Busan-Ulsan logistics hubs now specialize in cryogenic shipping infrastructure for high-value probiotic distribution.
India
Maharashtra and Gujarat dairy processors access previously restricted probiotic markets through FSSAI's 2022 streamlined strain approval mechanism. The Food Safety and Standards Authority of India created dedicated notification pathways for cultures with documented safety dossiers. Mumbai-Ahmedabad industrial corridors attract technical service investments from suppliers seeking first-mover positioning in emerging functional food segments.
Microbial Food Culture Market Competitive Environment
The competitive structure tilts toward integrated culture houses with captive strain libraries and multi-site GMP certification capabilities. Three to five multinational suppliers command the majority of high-volume dairy starter culture contracts through embedded technical service relationships. Two strategic archetypes dominate: heritage fermentation specialists with century-old strain collections, and diversified ingredient conglomerates leveraging cross-category manufacturing scale. Competitive moves concentrate on precision fermentation infrastructure expansion and direct-to-manufacturer digital platform development to bypass distributor networks.
Among heritage specialists, Chr. Hansen and CSK Food Enrichment occupy positions anchored by deep strain libraries and continental European dairy relationships. Lallemand Inc exemplifies the diversified fermentation platform archetype with manufacturing scale spanning multiple microorganism categories. Kerry Group PLC represents the ingredient conglomerate vector, leveraging specialized yeast portfolios to anchor North American bakery culture demand. Corbion NV and Koninklijke DSM NV sit within the nutrition-science tier, applying pharmaceutical-grade quality systems to food culture applications. These five named entities collectively illustrate the competitive segmentation between strain-library depth, manufacturing breadth, and technical service intensity.
| Leading Market Players |
|---|
| Corbion NV |
| Lallemand Inc |
| Kerry Group PLC |
| CSK Food Enrichment |
| Chr. Hansen |
| Koninklijke DSM NV |
| Cargill Incorporated |
| UAS Labs |
| DuPont de Nemours Inc |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal carbon accounting mandates for culture batch documentation are forcing dairy processors in Germany and France to consolidate procurement around verified low-emission strain suppliers, compressing supplier margins while rewarding backward-integrated culture houses with captive fermentation media production.
Pricing Analysis
Yield-based pricing anchors bacterial culture contracts, with German dairy cooperatives paying premiums for strains demonstrating accelerated acidification kinetics that reduce vat turnover time. Price differentiation separates pharmaceutical-grade GMP-certified probiotic strains from standard food-grade cultures, with cryogenic shipping requirements adding cost tiers for temperature-sensitive deliveries. Cost compression in standard starter cultures is intensifying because skim milk powder and cryoprotectant input costs swing with dairy commodity cycles. Mid-sized plant-based dairy processors in California and Victoria exhibit highest price sensitivity due to limited technical service access, while Japanese beverage manufacturers under METI guidelines show lowest sensitivity given regulatory compliance imperatives.
Supply Chain Analysis
ISO 22000 and pharmaceutical-grade GMP certification gating excludes independent regional culture producers from premium Japanese and South Korean foodservice channels, concentrating qualified supply among integrated culture houses with multi-site compliance capabilities. Manufacturing gravity centers on Denmark, Germany, and the United States, with Copenhagen hosting specialized strain libraries and phage-containment facilities serving continental European dairy cooperatives. Raw material dependencies include skim milk powder fermentation media, cryoprotectant formulations, and liquid nitrogen for cryogenic logistics. Single-source vulnerability runs through Danish phage-containment expertise concentrated in specialized research clusters. Distribution runs through direct technical field teams for multinational processors, with digital platforms emerging for mid-sized accounts lacking distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CRISPR-based strain engineering is displacing traditional selection methods, compressing development timelines while regulatory frameworks race to classify novel organism categories and creating asymmetric opportunity for technology-advantaged suppliers.
For Market Incumbents: Deploy precision fermentation infrastructure expansion to defend against gene-edited strain competitors entering continental European cheese manufacturing. Deepen captive supply of fermentation media to offset skim milk powder cost volatility compressing margins. Accelerate EFSA QPS pre-approval dossiers to freeze out suppliers lacking pre-approved strain libraries.
For New Entrants and Emerging Players: CRISPR-edited phage-resistant starter cultures offer a technology-first wedge into Dutch and Italian mozzarella production seeking reduced vat turnover time. Target mycoprotein and precision fermentation meat startups in the Netherlands and Israel currently underserved by dairy-focused suppliers. Pursue direct-to-manufacturer digital platforms to capture margin from mid-sized plant-based dairy processors lacking technical service access.
For Investors and Strategic Acquirers: The window for entry favors heritage fermentation specialists with century-old strain collections and embedded continental European dairy relationships. Long-term viability hinges on regulatory navigation capabilities across EFSA, FDA, and emerging FSSAI pathways. Watch for Indian FSSAI probiotic notification pathway acceleration as inflection indicator for emerging market functional food penetration.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Infrastructure Expansion | Bioreactor capacity in Singapore and Denmark enables contract manufacturing for craft beverage aromatic differentiation. |
| Direct-to-Manufacturer Digital Platform Launch | Bypassing distributor networks captures margin from California and Victoria plant-based dairy processors lacking technical access. |
| Pharmaceutical-Grade GMP Certification Investment | Simultaneous FDA GRAS, EFSA QPS, and Health Canada NHP compliance opens dual food-pharmaceutical probiotic markets. |
| CRISPR Strain Library Development | Gene-edited phage resistance and accelerated acidification kinetics threaten traditional culture suppliers in European cheese manufacturing. |
| Cryogenic Cold-Chain Partnership | Liquid nitrogen container services from Belgium and Germany logistics providers address EU F-Gas Regulation phase-down schedules. |
Study Parameters
Independent corroboration across fermentation science executives, dairy procurement directors, and regulatory affairs specialists underwrites the qualitative findings, validated against EFSA novel food assessment records, FDA GRAS notification filings, FSSAI functional food regulations, and customs trade data for culture import flows. Bottom-up strain-level demand modeling triangulates against top-down dairy processing capacity estimates across the analysis window.
Comparable-period anchoring to historical culture procurement volumes and fermentation infrastructure utilization rates shapes the projection framework across bacterial, probiotic, yeast, and fungal culture segments, with application splits for dairy, fermented beverage, bakery, and meat processing end-uses. CAGRs derive from segment-specific growth drivers including EU Green Deal sustainability mandates, METI and MFDS functional claim guidelines, and precision fermentation capacity expansion trajectories.
Several conditions sit outside the modeled scope, including unannounced strain-level regulatory reclassifications, abrupt cryoprotectant commodity price shocks, and phage contamination events disrupting established starter culture supply relationships. A model refresh is warranted upon material change in EFSA novel food assessment timelines or FSSAI probiotic notification pathway implementation pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
Probiotic Confectionery Market
Probiotic Supplements
Asia-Pacific Probiotics Market
Probiotic Supplements
Vegan Probiotics Market
Probiotic Supplements
United Kingdom Probiotics Market
Probiotic Supplements
Single-Strain Probiotics Market
Probiotic Supplements
Europe Microbial Food Culture Market
Probiotic Supplements
Japan Probiotics Market
Probiotic Supplements
Asia-Pacific Drinkable Yogurt Market
Probiotic Supplements
Poultry Probiotics Market
Probiotic Supplements
Bifidobacteria Lysates Market
Probiotic Supplements
South America Feed Probiotics Market
Probiotic Supplements
United States Digestive Supplement Market
Probiotic Supplements
Global Enteric Softgel Capsules Market
Probiotic Supplements
United States Probiotics Market
Probiotic Supplements
Probiotics Gummies Market
Probiotic Supplements
Digestive and Intestinal Remedies Market