
 Probiotics Dietary Supplements Market | 2026-2036
Probiotics Dietary Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Probiotics Dietary Supplements Market Intelligence
The US FDA's updated guidance on New Dietary Ingredient (NDI) notifications is realigning the cost-of-entry calculus for new probiotic formulations. This requires more substantial safety and efficacy data before market launch. Chr. Hansen Holding A/S specializes in the research and large-scale production of documented probiotic strains for B2B partners. In contrast, Nestlé S.A. leverages its global distribution network to market finished consumer goods, while Bayer AG positions its products within its broader consumer healthcare portfolio.
Probiotics dietary supplements consist of live microorganisms, typically from Lactobacillus and Bifidobacterium genera, formulated to deliver a specific dosage measured in Colony Forming Units (CFUs). Their primary purpose is to support gut microbial balance and associated health functions. While capsules remain the dominant product type due to delivery stability, multi-strain formulations are increasingly preferred over single-strain options for perceived broader efficacy. The online retail channel represents the fastest-growing distribution path, displacing some traditional pharmacy sales.
Market access is governed by varied regulatory frameworks, including the US FDA's supplement regulations, the stringent health claim evaluations by the European Food Safety Authority (EFSA), and China's NMPA registration for health foods. These rules dictate labeling, marketing claims, and required evidence of efficacy. Consequently, manufacturers face a critical decision point regarding the level of investment in clinical trials to substantiate specific health benefits versus relying on general wellness positioning.
Market Dynamics
The central market force is the escalating regulatory demand for scientific substantiation, particularly from the US FDA. This pressure is compelling a strategic pivot from general wellness marketing to clinically validated, benefit-specific product development and positioning.
Growth Catalysts
- Athlete Segment Adoption:Focus on gut health for performance is driving targeted product uptake among athletes, creating a high-value consumer niche.
- Synbiotic Formulations:Combining prebiotics with probiotic strains enhances efficacy, creating a value-added product category appealing to informed consumers.
- Wellness Demand in China:Concentrated demand from health-conscious consumers in China creates a significant, expanding market for premium probiotic supplements.
Market Restraints
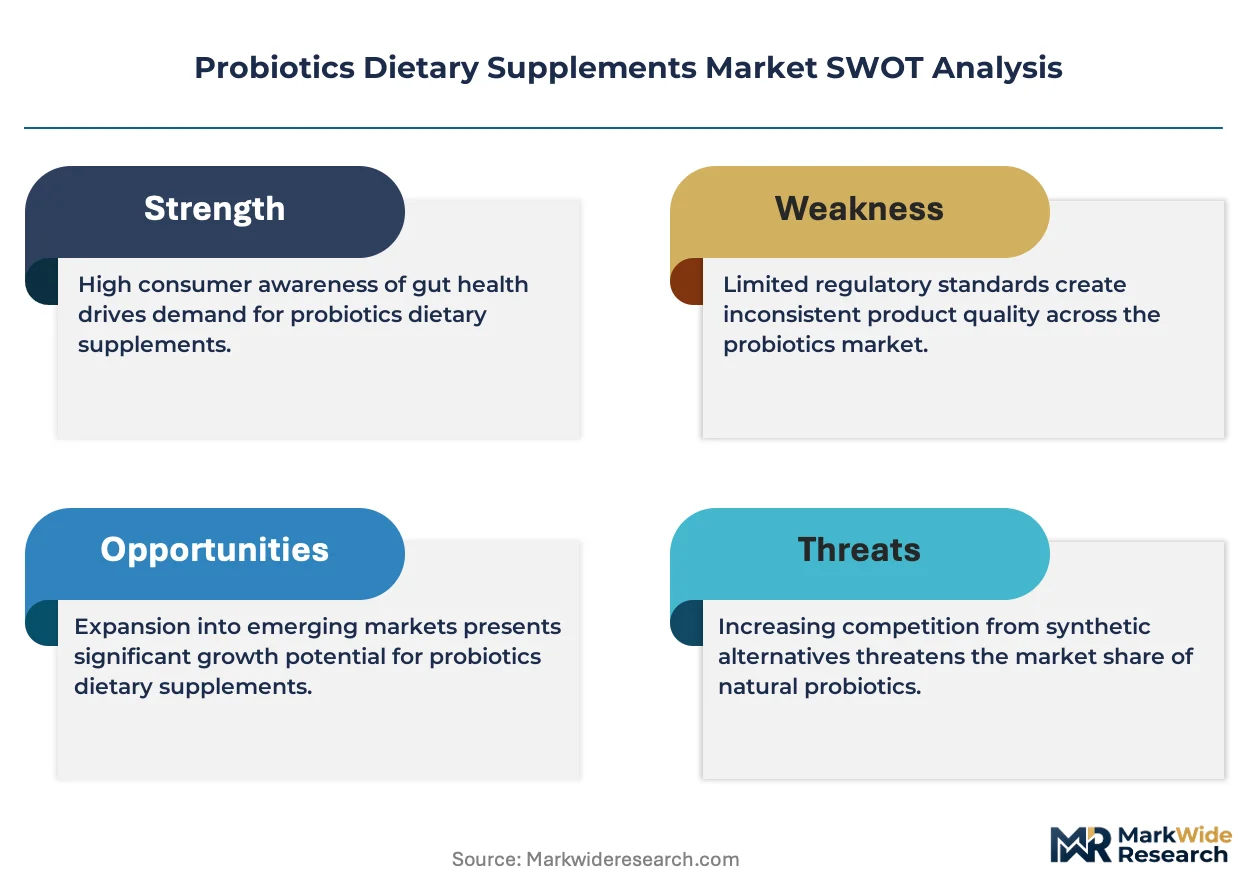
- EFSA Health Claim Restrictions:The European Food Safety Authority’s strict evaluation process limits specific health claims, constraining marketing in Europe.
- CFU Viability:Maintaining the stability and specified Colony Forming Unit counts of live microbes through the supply chain is a primary technical hurdle.
- Clinical Trial Costs:The high cost of clinical trials required to substantiate health benefits for novel strains represents a significant market entry barrier.
Strategic Opportunities
- Personalized Probiotics:Using microbiome data to create customized formulations offers a path to product differentiation and premium pricing.
- New Health Endpoints:Expanding R&D into non-gut applications like the gut-skin or gut-brain axis opens new addressable markets.
- Direct-to-Consumer Channels:Online D2C models allow brands to bypass traditional retail, build customer relationships, and capture higher margins.
Industry Challenges
- Regulatory Fragmentation:Manufacturers must navigate divergent and complex registration requirements for health foods and supplements across the US, EU, and China.
- Consumer Education Burden:Differentiating scientifically validated products from generic wellness offerings requires substantial investment in educating a crowded marketplace.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Probiotics Dietary Supplements Market |
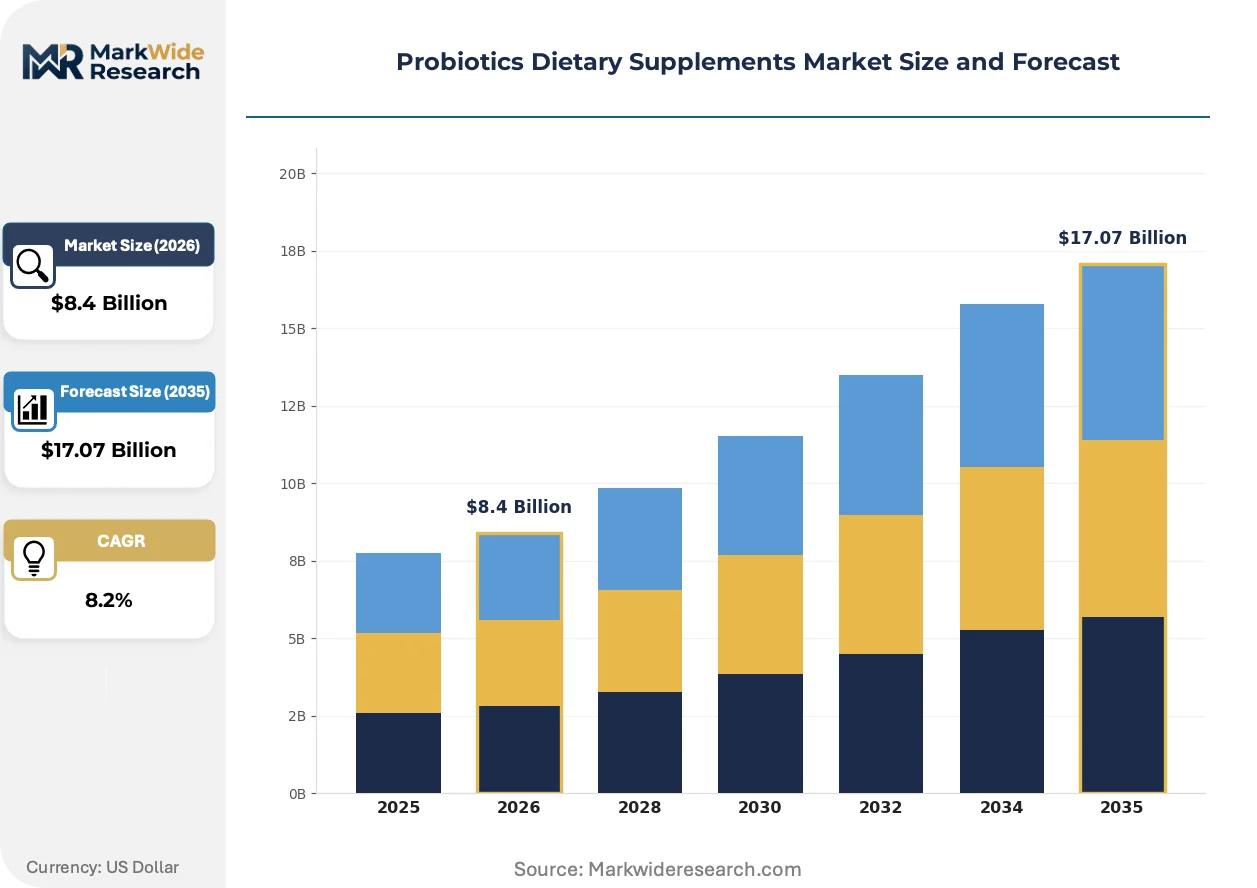
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $17.07 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Powders, Gummies, Liquid Target Consumer: Adults, Children, Seniors, Athletes Distribution Channel: Online Retail, Supermarkets, Pharmacies, Health Stores Formulation: Single-Strain, Multi-Strain, Enhanced, Soil-Based |
| Companies Covered | BioGaia AB, Bayer AG, Nestlé S.A., Chr. Hansen Holding A/S, Custom Probiotics Inc., Archer Daniels Midland Co., DuPont de Nemours Inc., Koninklijke DSM N.V., Reckitt Benckiser Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Probiotics Dietary Supplements Market Strategic Shifts & Innovations
Product innovation is shifting from increasing CFU counts toward formulating for specific outcomes and enhanced biological activity. This evolution prioritizes clinical evidence and targeted functionality over generalized, high-dosage approaches to gut health supplementation.
Synbiotic formulations combine specific probiotic strains with prebiotic fibers to improve microbial survival and metabolic activity. Health-conscious consumers and athletes are rapidly adopting these more complex products seeking enhanced efficacy. This development is unifying the previously distinct categories of fiber supplements and live cultures into a single, synergistic intervention.
The US FDA’s updated guidance for New Dietary Ingredient (NDI) notifications imposes more stringent data requirements for novel ingredients. This policy elevates the cost and complexity of launching new probiotic strains, demanding more robust preclinical safety data. Consequently, smaller firms are increasingly affected, often choosing general wellness claims over specific benefit positioning.
A pronounced shift in consumer purchasing is moving from traditional pharmacies toward online retail and direct-to-consumer subscription models. This channel disintermediation allows brands to control messaging and capture valuable first-party customer data. The trend is most advanced in the United States and China, where mature e-commerce ecosystems facilitate D2C logistics.
Probiotics Dietary Supplements Market Segmentation
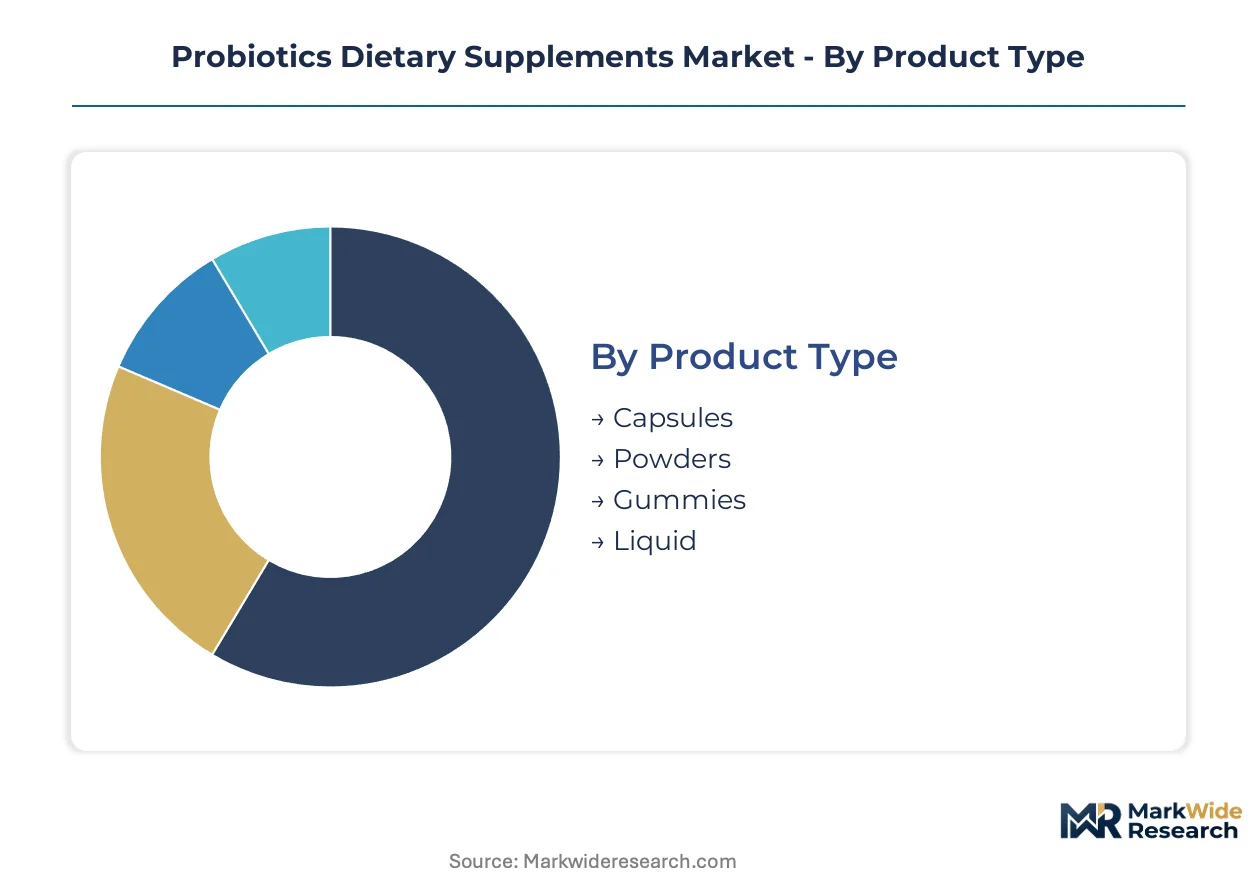
Probiotics dietary supplements are segmented across various dimensions, reflecting diverse consumer needs, product functionalities, and market access strategies. Understanding these segmentations is critical for manufacturers to align product development with regulatory pathways and consumer preferences in a competitive landscape.
Product Type:
The regulatory burden for new product types often depends on their delivery method and perceived safety, with novel forms like gummies facing increased scrutiny from bodies like the US FDA regarding stability and dosage claims.
- Capsules:Encapsulated forms protect live microorganisms from gastric acid, ensuring targeted delivery to the intestinal tract. Demand concentrates among wellness-focused consumers in the United States, driven by perceived efficacy and precise dosage.
- Gummies:Chewable gummy formats offer a palatable and convenient delivery method, often fortified with additional vitamins. Demand is expanding rapidly among children and adult consumers seeking an easy-to-consume supplement in China.
- Powders:Powders provide versatile dosing options, frequently mixed into beverages for daily consumption.
- Liquid:Liquid probiotics offer rapid absorption and are suitable for individuals with swallowing difficulties.
Leading the category by volume: Capsules. Growing fastest: Gummies.
Target Consumer:
Application-specific product development tailors probiotic formulations to the distinct physiological needs and health objectives of different consumer cohorts.
- Adults:The adult segment encompasses a broad demographic seeking general gut health maintenance and immune system support. Demand is consistently high across developed markets, including Germany and Japan, for daily wellness routines.
- Athletes:This segment focuses on specific probiotic strains designed to support athletic performance, recovery, and gut integrity under physical stress. Demand is concentrating in competitive sports communities within the United States and Australia.
- Children:Children's probiotics often target immune development and digestive comfort, frequently in palatable forms like gummies.
- Seniors:Seniors consume probiotics for digestive regularity and immune system support, addressing age-related physiological changes.
Adults represent the largest consumer base; the Athletes segment exhibits the steepest expansion trajectory.
Distribution Channel:
Volume distribution through various channels reflects consumer purchasing habits and the level of product education required at the point of sale.
- Online Retail:E-commerce platforms facilitate direct-to-consumer sales, offering convenience, broader product selection, and subscription models. This channel is gaining share fastest in the United States and China, leveraging mature digital infrastructure.
- Pharmacies:Pharmacies provide a trusted point of sale, often with pharmacist recommendations for specific health concerns. Demand remains consistent in European markets like France and Italy, where medical advice is valued.
- Supermarkets:Supermarkets offer mass-market accessibility for general wellness probiotics, integrated into routine grocery shopping.
- Health Stores:Health stores cater to consumers seeking specialized or organic probiotic formulations, emphasizing natural health.
Online Retail is capturing market share most quickly; Pharmacies maintain a significant base.
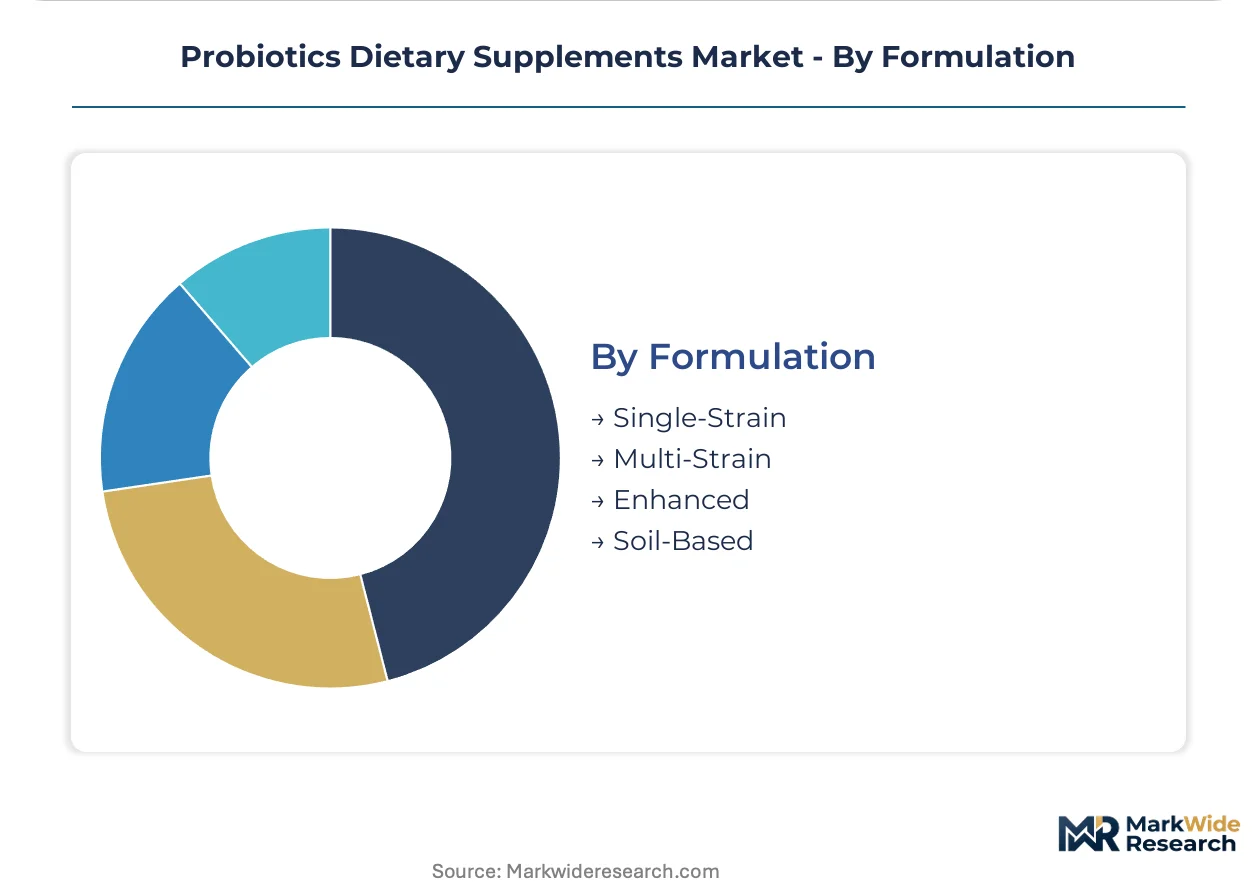
Formulation:
The maturity of formulation technologies ranges from established single-strain products to advanced synbiotic and enhanced options, each offering distinct benefits and market positioning.
- Single-Strain:Single-strain probiotics target specific health conditions, offering precise interventions for particular gut issues.
- Multi-Strain:These formulations combine several different probiotic species or strains, aiming for broader gut microbiome support. Demand is accelerating among informed consumers in Germany and Canada seeking comprehensive health benefits.
- Enhanced:Enhanced formulations often include prebiotics (synbiotics) or other functional ingredients to improve probiotic survival and activity. Demand is expanding rapidly for these value-added products among performance-oriented consumers.
- Soil-Based:Soil-based probiotics are spore-forming bacteria known for their resilience, often appealing to consumers seeking natural alternatives.
Multi-Strain formulations command significant market presence; Enhanced formulations are experiencing rapid uptake.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Free Trade Zones, designed to attract foreign investment and foster innovation, drive a concentration of health food manufacturing and distribution for the broader Asian market. This strategic focus on regional economic hubs facilitates the expansion of probiotic dietary supplement production and market access across the continent. Such zones offer regulatory advantages and streamlined processes for companies entering the dynamic health and wellness sector.
United States
Wellness-focused consumers and athletes in the United States generate substantial demand for advanced probiotic formulations. The US FDA's updated guidance on New Dietary Ingredient (NDI) notifications influences product development and market entry. California's nutraceutical innovation hubs are actively developing and testing novel probiotic strains for diverse health applications.
China
China's health-conscious consumers demonstrate concentrated demand for premium probiotic supplements, particularly for digestive health. The country's NMPA registration process for health foods dictates stringent market access requirements. The Yangtze River Delta region, a major economic zone, serves as a significant hub for e-commerce distribution and health food manufacturing.
Germany
German consumers consistently seek probiotics for general gut health maintenance and immune system support, favoring multi-strain formulations. The European Food Safety Authority's (EFSA) strict evaluation of health claims indirectly influences marketing strategies within Germany. Bavaria's robust food and supplement industry is a center for product development and quality assurance.
Japan
Japan exhibits consistent demand for probiotics integrated into daily wellness routines, emphasizing digestive comfort. The Ministry of Health, Labour and Welfare (MHLW) regulates Foods with Function Claims, guiding product development. Tokyo's numerous research institutions and pharmaceutical companies contribute to probiotic science and innovation.
Australia
Competitive sports communities in Australia are driving demand for performance-oriented probiotic supplements, focusing on gut integrity and recovery. The Therapeutic Goods Administration (TGA) oversees the regulation of listed medicines and dietary supplements. Melbourne's sports science and nutrition research centers are at the forefront of developing specialized formulations.
Probiotics Dietary Supplements Market Key Industry Players
North American producers anchor one tier, emphasizing advanced formulation and direct-to-consumer models, while European specialists hold significant positions in B2B ingredient supply. The market structure is tiered, with global consumer goods conglomerates, specialized ingredient manufacturers, and agile direct-to-consumer brands. Portfolio diversification into synbiotic formulations and strategic partnerships to navigate regulatory complexities are dominant competitive moves.
Within the specialized ingredient supplier archetype, Chr. Hansen Holding A/S, a Danish-based company, exemplifies a focus on documented probiotic strains for B2B partners. Nestlé S.A., a Swiss-headquartered corporation, represents the global consumer goods conglomerate, leveraging its vast distribution network for finished products. Bayer AG, a German public limited company, positions its offerings within its broader consumer healthcare portfolio, capitalizing on established brand trust.
| Leading Market Players |
|---|
| BioGaia AB |
| Bayer AG |
| Nestlé S.A. |
| Chr. Hansen Holding A/S |
| Custom Probiotics Inc. |
| Archer Daniels Midland Co. |
| DuPont de Nemours Inc. |
| Koninklijke DSM N.V. |
| Reckitt Benckiser Group plc |
| Others |
Cost & Logistics Intelligence
Clinically validated, benefit-specific probiotic formulations represent a distinct tier divergence, influencing both pricing premiums and the complexity of their supply chain configurations. This separation impacts market access and consumer trust.
Pricing Analysis
Lead-time-driven pricing for novel probiotic strains commands a premium, reflecting the extensive research and development required for clinical validation. Contract-based long-term offtake agreements characterize the B2B ingredient market, while finished goods often utilize per-unit transactional models. Price differentiation stems from clinical evidence substantiating specific health benefits and the complexity of multi-strain formulations. Pricing pressure for scientifically backed products increases due to high clinical trial costs, with wellness-focused consumers and athletes demonstrating lower price sensitivity than general wellness buyers.
Supply Chain Analysis
Workforce availability in specialized biotech manufacturing hubs like Denmark and the United States underpins the supply of documented probiotic strains. The supply chain draws from specific bacterial genera, such as Lactobacillus and Bifidobacterium, and often includes prebiotic fibers. Maintaining Colony Forming Unit (CFU) viability through temperature-controlled logistics represents a critical structural risk. Distribution runs through B2B channels for ingredient suppliers and increasingly via online retail and direct-to-consumer models for finished products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The probiotics market is fundamentally a cost-of-compliance narrative, where the US FDA's updated New Dietary Ingredient guidance establishes a significant barrier-to-entry moat for new formulations. This regulatory pressure favors established players capable of substantial investment in safety and efficacy data.
For Market Incumbents: To counter rising regulatory compliance costs and market fragmentation, established incumbents must deepen their investment in clinical trials for novel strains. Strategic partnerships with B2B ingredient specialists, like Chr. Hansen, can secure access to documented strains, mitigating R&D expenditure. Expanding into personalized probiotic solutions offers a premium segment defense against generic wellness offerings. Leveraging existing global distribution networks provides a strong channel control advantage.
For New Entrants and Emerging Players: Microbiome data analysis for customized probiotic formulations presents a technology-first wedge for new entrants. Targeting the high-value athlete segment and wellness-focused consumers in China offers addressable white space. A direct-to-consumer subscription model provides a viable go-to-market angle, bypassing traditional retail channels and building direct customer relationships. This approach allows for rapid iteration and tailored product delivery.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized ingredient manufacturers and scientifically validated direct-to-consumer brands, given the escalating demand for clinically proven health benefits. Long-term viability across the next decade favors companies with proprietary strains and robust R&D pipelines for new health endpoints. Acquisition targets should demonstrate strong intellectual property in synbiotic formulations or established D2C customer relationships. Increased M&A activity for specific strain IP will signal market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Essential for substantiating specific health claims, especially under US FDA NDI guidance. |
| Synbiotic Formulation Development | Enhances product efficacy and appeals to informed consumers seeking comprehensive solutions. |
| Direct-to-Consumer Channel Expansion | Allows brands to control messaging and capture valuable first-party customer data. |
| Geographic Regulatory Compliance | Navigates diverse frameworks like China's NMPA registration and EFSA health claim evaluations. |
| Microbiome Data Integration | Drives product differentiation through personalized probiotic formulations for specific consumer needs. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, providing a robust foundation for market understanding. Primary research involved in-depth interviews with R&D directors, regulatory affairs specialists, brand managers, and procurement leads across key geographies. This primary intelligence was triangulated with secondary sources including US FDA filings, EFSA reports, NMPA guidelines, and academic journals. Both bottom-up and top-down approaches validated market sizing.
Granularity in modeling extended to product type, target consumer, distribution channel, and formulation, alongside regional regulatory clusters. The analytical framework projected market evolution across the analysis window, with compound annual growth rates derived from historical trends and anticipated shifts in market dynamics. Key forecast inputs included clinical trial investment trends and consumer wellness spending patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under significant regulatory shifts or unexpected scientific breakthroughs. The analysis reflects assumptions regarding evolving health claim standards and consumer acceptance of novel formulations. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
Probiotics Market
Probiotic Supplements
Bifidobacteria Lysates Market
Probiotic Supplements
Synbiotic Product Market
Probiotic Supplements
Lactobacillus Acidophilus Market
Probiotic Supplements
Europe Microbial Food Culture Market
Probiotic Supplements
Shelf Stable Probiotics Market
Probiotic Supplements
Global Liquid Feed Supplements Market
Probiotic Supplements
Stirred Yogurt Culture Market
Probiotic Supplements
Infant and Kids Probiotics Market
Probiotic Supplements
Bifidobacterium Probiotics Market
Probiotic Supplements
Digestion Aids Market
Probiotic Supplements
D-Lactate Free Probiotics Market
Probiotic Supplements
Probiotic Strains Market
Probiotic Supplements
South America Digestive Health Supplements Market
Probiotic Supplements
Asia-Pacific Drinkable Yogurt Market
Probiotic Supplements
Probiotics for Kids Market