
 Grass-Fed Meat Market | 2026-2036
Grass-Fed Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Grass-Fed Meat Market Analysis
Direct-to-consumer online channels is reshaping how premium grass-fed meat reaches buyers, bypassing traditional wholesale intermediaries. JBS Foods leverages its global processing footprint to secure consistent supply for grass-fed product lines across multiple continents. Australian Agricultural Company Limited anchors its competitive position through integrated cattle stations and export-oriented abattoirs in Queensland and the Northern Territory. Strauss Brands specializes in midwestern US grass-fed beef programs, controlling breed selection and finishing protocols to meet retailer specifications.
Grass-fed meat denotes ruminant livestock finished on pasture and forage rather than grain-based feedlot rations, with finished cattle typically exhibiting lower intramuscular fat percentages and distinct fatty acid profiles compared to conventional counterparts. The category serves health-conscious consumers, premium foodservice operators, and retailers seeking differentiated protein assortments with verifiable production claims. Beef dominates product type volumes due to established consumer recognition and extensive ranching infrastructure, while lamb captures premium positioning in Middle Eastern and Mediterranean culinary channels. Supermarkets and restaurants represent the most contested end-user segments, with margin pools shifting toward certified organic and animal welfare approved designations that command shelf-space premiums.
USDA Agricultural Marketing Service maintains official grass-fed marketing claim standards, while EU Green Deal farm-to-fork strategies impose methane reduction targets on livestock producers across member states. Australia's Department of Agriculture, Fisheries and Forestry administers export certification protocols that determine market access for grass-fed beef shipments into Japan, South Korea, and China. Producers and distributors must monitor evolving carbon accounting methodologies and country-of-origin labeling enforcement, as these frameworks increasingly determine eligibility for premium pricing tiers and procurement contracts.
Market Dynamics
Carbon accounting methodologies are forcing grass-fed meat producers to document pasture-based methane emissions and soil carbon sequestration, reshaping procurement contracts and export eligibility across major beef-exporting nations.
Growth Catalysts
- EU Green Deal farm-to-fork targets:Methane reduction mandates create preferential market access for verified low-emission grass-fed operations, redirecting institutional procurement toward certified suppliers.
- Direct-to-consumer e-commerce platforms:Online subscription models bypass conventional wholesale markups, enabling ranchers to capture margin previously lost to intermediaries while building traceable brand relationships.
- Australian rangeland infrastructure:Extensive pastoral lease networks and established live-export protocols provide scalable feedstock for premium grass-fed programs serving East Asian markets.
Market Restraints
- Grain price volatility:Drought-induced feed cost spikes in major producing regions compress margins for operations finishing cattle on supplementary rations during pasture deficits.
- Processing concentration:Export-licensed abattoir capacity clusters in Queensland and New South Wales, creating bottlenecks and freight disadvantages for producers in remote Western Australian stations.
- Extended finishing timelines:Pasture-only protocols require 6-12 additional months to reach market weight compared to grain-fed systems, tying up working capital and increasing weather exposure.
Strategic Opportunities
- Regenerative agriculture certification:USDA's emerging soil health verification standards offer premium pricing tiers for producers documenting rotational grazing and carbon drawdown practices.
- Cell-cultured hybrid positioning:Convergence of precision fermentation and traditional ranching enables "blended" product lines that leverage grass-fed branding while addressing yield constraints.
- Specialty foodservice penetration:Fine-dining operators in Dubai and Singapore seek differentiated protein provenance, creating demand for single-origin grass-fed programs with verified station traceability.
Industry Challenges
- Veterinary telemedicine skill gaps:Remote pasture operations struggle to recruit veterinarians trained in remote diagnostics and reproductive management without physical handling facilities.
- Multi-jurisdictional certification timelines:Simultaneous compliance with USDA grass-fed claims, EU organic equivalence, and Japan's GACC export protocols extends approval cycles by 18-24 months.
- Cold chain reconfiguration:Shift from commodity boxed beef to branded retail cuts requires investment in portion-controlled processing and modified atmosphere packaging systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grass-Fed Meat Market |
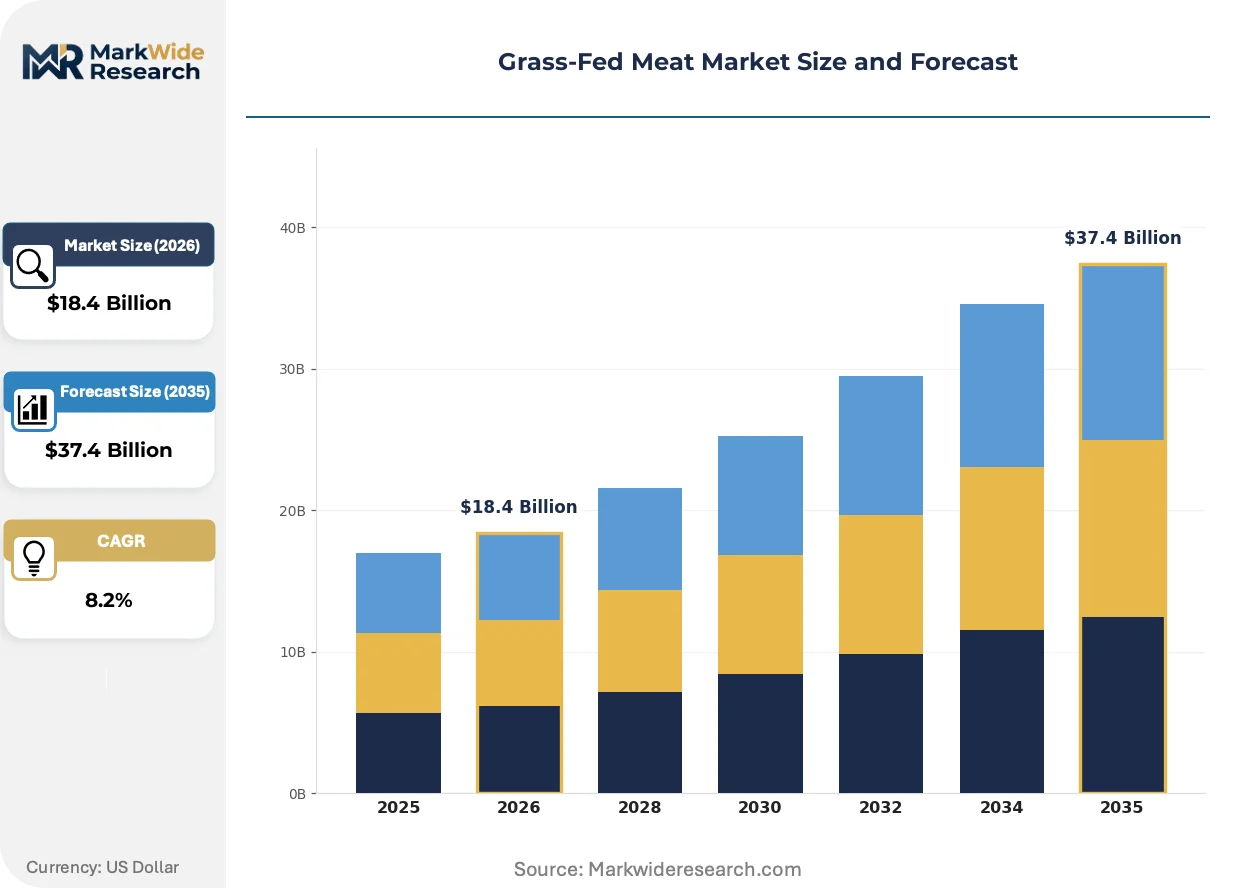
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $37.4 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Lamb, Pork, Goats End User: Restaurants, Supermarkets, Retail Consumers, Online Retailers Distribution Channel: Direct Sales, Wholesale, Online, Farmers Markets Certification: Organic, Grass-Fed, Non-GMO, Animal Welfare Approved |
| Companies Covered | JBS Foods, Australian Agricultural Company Limited, Tyson Foods, Hormel Foods Corporation, Strauss Brands, Verde Farms, Panorama Organic, Creekstone Farms Premium Beef, Conagra Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grass-Fed Meat Market Emerging Trajectories
Pasture management systems are integrating satellite-derived biomass monitoring with automated water point controls, compressing labor requirements while improving grazing intensity metrics that underpin carbon credit claims.
Precision grazing technology is hybridizing traditional rotational protocols with IoT-enabled fenceless boundary systems. Australian station operators deploy GPS-collared cattle and virtual paddock algorithms to optimize forage utilization without fixed infrastructure investments. This convergence is compressing the labor-to-hectare ratios that historically constrained scale in extensive ranching systems.
EU Green Deal agricultural reforms are mandating farm-level nutrient accounting and biodiversity reporting for livestock operations accessing Common Agricultural Policy payments. Producers must document pasture species composition and watercourse setbacks, with compliance costs falling disproportionately on mid-sized mixed operations lacking dedicated sustainability staff. Dutch and Irish beef enterprises are responding by consolidating into specialized grass-only entities that can amortize monitoring systems across larger herd bases.
Subscription-based meat buying cooperatives are displacing conventional retail procurement for affluent urban households. These member-owned pools aggregate demand across 200-500 households, contracting directly with named ranches for quarterly delivery of frozen primal cuts. The model concentrates most visibly in coastal US metropolitan areas and Australian capital cities, where consumers prioritize provenance transparency over immediate availability.
Grass-Fed Meat Market Segmentation
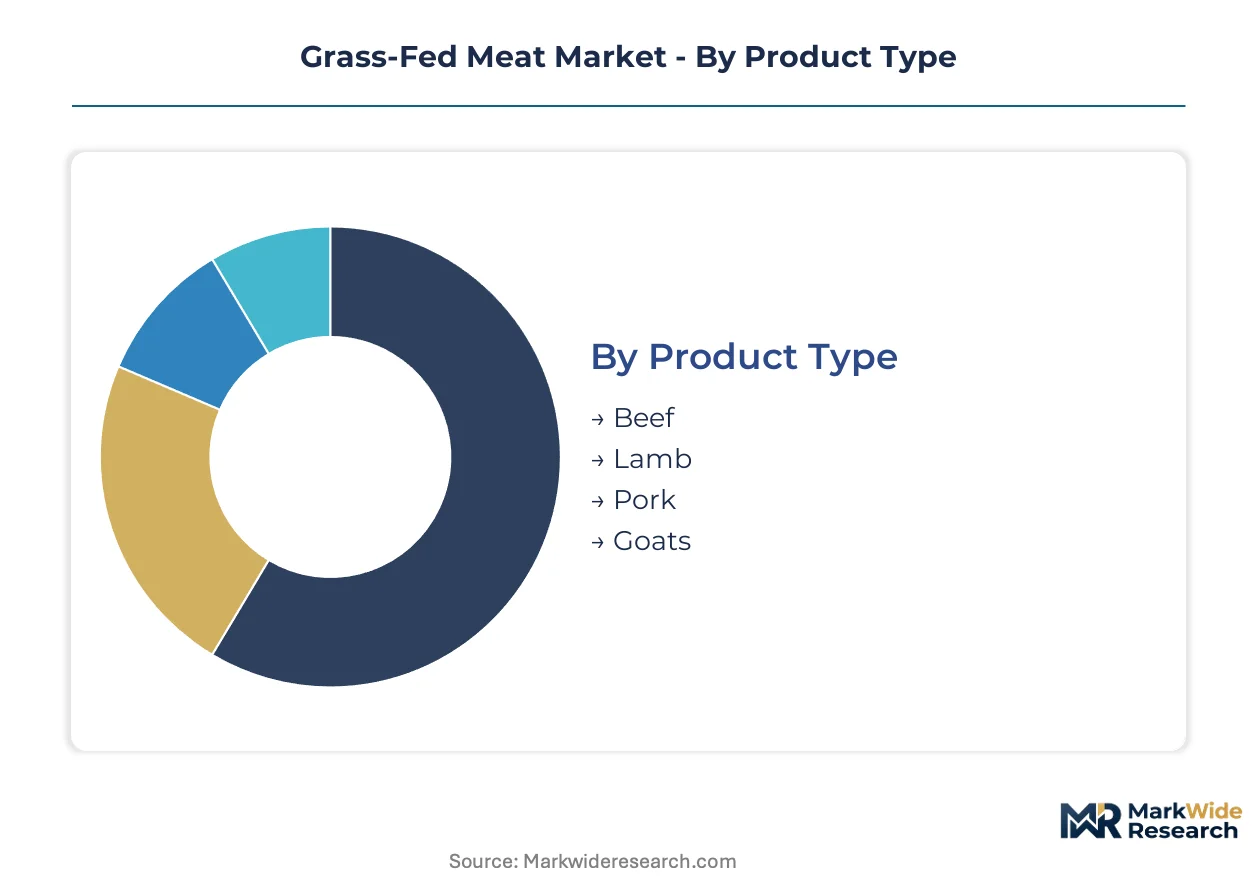
Segmentation in grass-fed meat markets determines procurement contract structures, cold chain investments, and margin capture potential across divergent buyer requirements. Producers aligning product specifications with channel-specific certification demands secure shelf-space premiums and foodservice exclusivity.
Product Type:
After-sales service intensity varies sharply across species, with beef commanding dedicated quality assurance teams and lamb requiring specialized halal certification support for Middle Eastern export channels.
- Beef:Finished cattle on pasture exhibit lower intramuscular fat and distinct omega-3 profiles compared to grain-fed counterparts. Demand concentrates in Australian export programs serving Japan and South Korea, where marbling standards and traceability documentation determine eligibility for premium pricing tiers.
- Lamb:Young sheep finished on native grasses deliver lean protein with terroir-linked flavor profiles valued in Mediterranean and Gulf state culinary channels. Australian rangeland operations and New Zealand hill-country stations dominate supply, with Dubai and Singapore fine-dining operators driving single-origin procurement contracts.
- Pork:Pasture-raised swine operations remain niche due to longer finishing timelines and lower feed conversion efficiency versus conventional systems.
- Goats:Boer and Kiko breeds finished on brush and forage serve ethnic foodservice segments in North American and Australian urban centers.
By volume, beef leads. By growth pace, lamb is ahead.
End User:
Cost tier stratification separates institutional buyers seeking commodity-scale supply from premium channels prioritizing provenance verification and batch-level traceability.
- Restaurants:Fine-dining operators in Dubai, Singapore, and Sydney command station-specific origin documentation and dry-aging protocols. Menu differentiation through verified grass-fed claims supports check averages and media coverage.
- Supermarkets:Retail chains negotiate private-label grass-fed programs requiring consistent grading, modified atmosphere packaging, and weekly replenishment cadence.
- Retail Consumers:Direct purchasing through butcher counters and subscription cooperatives prioritizes breed identification and finishing duration transparency.
- Online Retailers:E-commerce platforms aggregate fragmented ranch supply into curated assortments with frozen logistics and recurring delivery scheduling.
Supermarkets move the most tonnage. Online retailers are climbing the fastest.
Distribution Channel:
Customer type concentration shapes channel selection, with institutional buyers defaulting to wholesale and affluent households migrating toward direct relationships that bypass intermediaries.
- Direct Sales:Ranch-to-consumer models capture margin previously allocated to distributors, requiring investment in e-commerce infrastructure and cold chain logistics.
- Wholesale:Processor-aggregator networks consolidate supply from multiple stations for export-licensed abattoir throughput.
- Online:Subscription platforms and meat-specific marketplaces enable discovery of regional producers beyond geographic proximity.
- Farmers Markets:Weekend retail presence builds brand recognition and supports premium pricing for cuts with limited shelf stability.
Wholesale channels dominate volume flow. Online distribution is gaining share fastest.
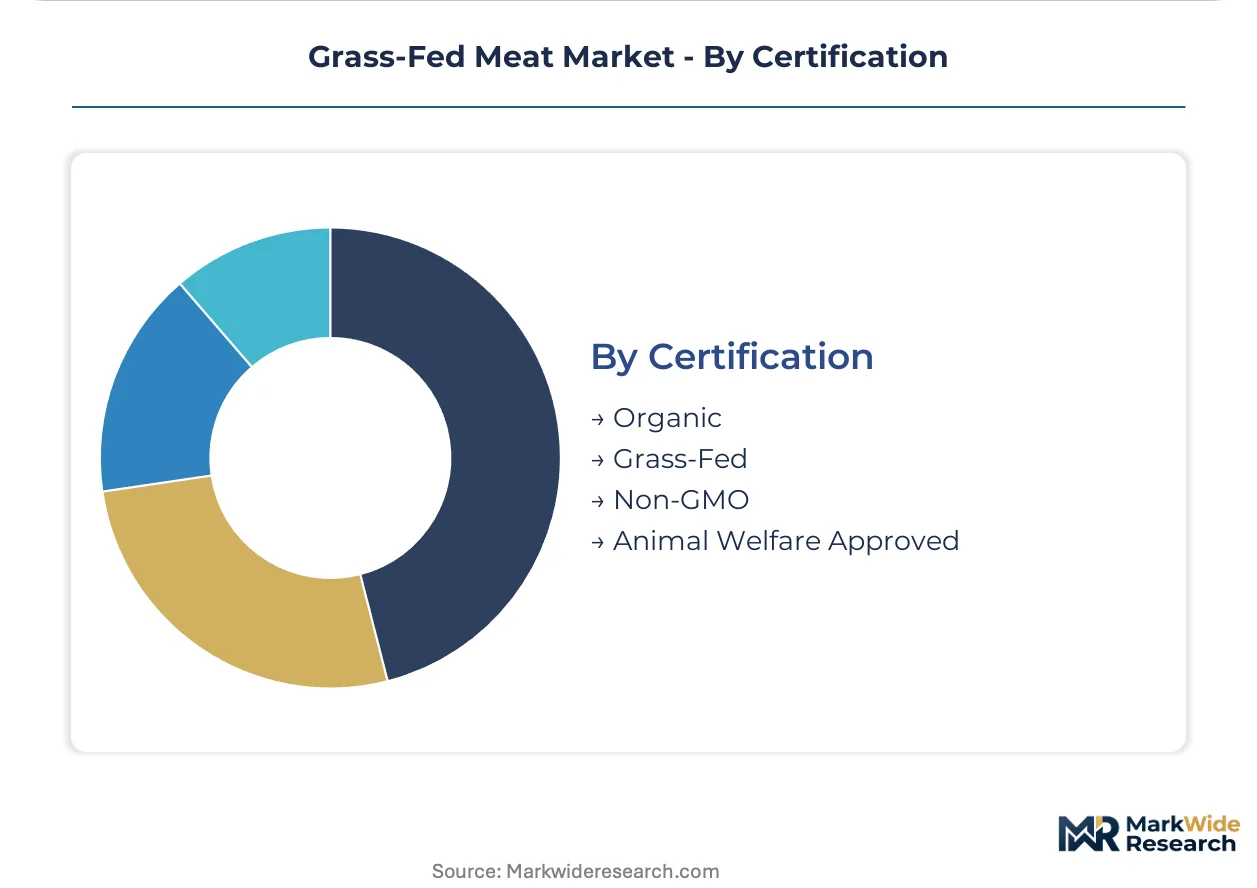
Certification:
Margin differentiation accrues to multi-certified products commanding simultaneous compliance with animal welfare, environmental, and processing standards.
- Organic:USDA National Organic Program and EU organic equivalence requirements prohibit synthetic inputs and mandate pasture access, with compliance costs amortized across larger herd bases.
- Grass-Fed:USDA AMS marketing claim standards define continuous pasture access and forage finishing, verified through third-party audits and documentation systems.
- Non-GMO:Feed verification protocols address consumer skepticism about genetically modified pasture species and supplementary forages.
- Animal Welfare Approved:Independent certification programs audit handling facilities, transport duration, and slaughter protocols for ethical positioning.
Grass-Fed certification leads by volume. Animal Welfare Approved shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australian rangeland operations capture 40-60% pricing premiums over Argentine grass-fed exports into Asian markets, reflecting traceability infrastructure gaps that disadvantage South American supply. This asymmetry shapes procurement patterns across East Asian import channels.
United States
Midwestern direct-to-consumer subscription cooperatives and specialty retailers in coastal metros drive premium demand for verified grass-fed programs. USDA Agricultural Marketing Service maintains official grass-fed marketing claim standards that determine eligibility for federal procurement contracts. Strauss Brands anchors midwestern supply chains through controlled breed selection protocols serving Chicago and Minneapolis retail networks.
Australia
Queensland and Northern Territory cattle stations supply export-licensed abattoirs serving Japan, South Korea, and China with traceable station-origin documentation. The Department of Agriculture, Fisheries and Forestry administers export certification protocols that determine market access eligibility. Australian Agricultural Company Limited integrates pastoral lease networks with export-oriented processing capacity in Queensland.
Japan
Tokyo and Osaka fine-dining operators command single-origin documentation and extended dry-aging protocols for premium menu positioning. The General Administration of Customs of China (GACC) equivalent import standards and bilateral protocols with Australia's Department of Agriculture shape eligible supplier lists. Kansai region distributors consolidate Queensland-sourced grass-fed beef for hotel and restaurant channels.
United Arab Emirates
Dubai luxury hospitality operators seek differentiated protein provenance with verified station traceability for fine-dining differentiation. The Ministry of Climate Change and Environment (MOCCAE) administers halal certification and import health requirements for ruminant products. Jebel Ali free zone cold chain infrastructure enables Australian and Argentine re-export consolidation for Gulf state distribution.
Germany
Berlin and Munich retail cooperatives prioritize multi-certified organic and animal welfare approved designations for shelf-space premiums. EU Green Deal farm-to-fork strategies impose methane reduction targets and nutrient accounting requirements on livestock producers. Bavarian and Lower Saxony mixed farming operations face compliance cost pressures driving consolidation into specialized grass-only entities.
Grass-Fed Meat Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream, supplying raw material to branded programs. The market structures around three tiers: multinational protein conglomerates with global processing footprints, integrated pastoral operators controlling station-to-abattoir supply chains, and specialist mid-scale programs focused on breed-specific finishing protocols. Strategic moves concentrate on backward integration into captive cattle supply and certification stacking to access premium pricing tiers.
Within the multinational processor tier, JBS Foods and Tyson Foods occupy positions leveraging global abattoir networks to aggregate grass-fed supply across multiple continents. Australian Agricultural Company Limited exemplifies the integrated pastoral archetype, anchoring competitive position through Queensland and Northern Territory station infrastructure. Strauss Brands represents the specialist program model, controlling midwestern US grass-fed beef protocols through direct retailer relationships.
| Leading Market Players |
|---|
| JBS Foods |
| Australian Agricultural Company Limited |
| Tyson Foods |
| Hormel Foods Corporation |
| Strauss Brands |
| Verde Farms |
| Panorama Organic |
| Creekstone Farms Premium Beef |
| Conagra Brands |
| Others |
Supply Flow & Price Mechanics
Queensland and Northern Territory pastoral lease networks concentrate upstream cattle supply, anchoring margin pools with export-licensed abattoirs that command station-origin premiums over Argentine competitors in East Asian procurement channels.
Pricing Analysis
Certification-premium spreads separate Animal Welfare Approved and organic designations from baseline USDA grass-fed claims, with three-tier pricing structure across premium, standard, and economy levels. Quality grade and certification level drive price differentiation, while extended finishing timelines compress margins in standard tiers. Pricing pressure stems from drought-induced supplementary feed costs during pasture deficits. Institutional buyers in foodservice channels exhibit lowest price sensitivity; commodity-scale wholesalers face highest pressure.
Supply Chain Analysis
Australian Department of Agriculture, Fisheries and Forestry export certification protocols function as restricted-technology controls limiting market access flows. Supply concentrates in Australia, Argentina, and the United States. Raw material dependencies center on pasture biomass, breeding stock genetics, and veterinary pharmaceuticals. Single-source vulnerability clusters in Queensland and New South Wales abattoir capacity. Distribution runs through processor-aggregator networks consolidating station supply for export throughput.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Grass-fed meat sits in early-cycle expansion as direct-to-consumer subscription models penetrate affluent urban households, with EU Green Deal methane mandates accelerating certified supplier procurement timelines.
For Market Incumbents: Entrench station-to-abattoir integration through captive cattle supply in Queensland and Northern Territory pastoral leases. Cell-cultured hybrid positioning threatens brand differentiation; counter through certification stacking combining USDA grass-fed claims with regenerative agriculture verification. Prioritize backward integration into breeding stock genetics to control finishing protocol consistency.
For New Entrants and Emerging Players: Establish a beachhead in subscription-based meat buying cooperatives serving coastal US metropolitan areas. White-space targets include regenerative agriculture certification programs and specialty foodservice penetration in Dubai and Singapore. Deploy ranch-to-consumer e-commerce infrastructure with frozen logistics capabilities to bypass incumbent wholesale markups.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated pastoral operators with export-licensed processing capacity and multi-jurisdictional certification infrastructure. Long-term viability over the next decade rests on carbon accounting methodology compliance and soil carbon sequestration documentation. Monitor EU Green Deal farm-to-fork implementation velocity as inflection indicator for certified supplier demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pastoral Leases | Captures margin pools previously allocated to third-party cattle procurement in Queensland rangelands. |
| Multi-Certification Stacking | Unlocks premium pricing tiers through simultaneous USDA grass-fed and Animal Welfare Approved compliance. |
| Direct-to-Consumer Platform Launch | Bypasses wholesale intermediaries via subscription models aggregating 200-500 household demand pools. |
| Regenerative Agriculture Certification | Positions for USDA soil health verification standards commanding carbon credit-linked premiums. |
| Export Market Expansion | Secures GACC protocol compliance for China access and bilateral agreements with Japan's METI-aligned import standards. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with ranch operations managers, export certification officers at Australia's Department of Agriculture, retail category buyers, and fine-dining procurement directors; and secondary validation through USDA Agricultural Marketing Service filings, EU Green Deal regulatory texts, Australian Bureau of Agricultural and Resource Economics trade data, and station-level carbon accounting disclosures. Bottom-up herd inventory modeling triangulated against top-down export volume aggregation.
Forecast inputs span product type segmentation across beef, lamb, pork, and goat species; end-user channels separating restaurants, supermarkets, retail consumers, and online retailers; distribution mode differentiation; and certification tier stratification. CAGRs were derived through regression analysis of historical export pricing and projected pasture capacity expansion across the analysis window. Industry-specific inputs incorporate EU methane reduction mandate compliance timelines and Australian rangeland infrastructure utilization rates.
Stress conditions across drought frequency, grain price volatility, and multi-jurisdictional certification approval timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding pasture productivity and export protocol stability. Material shifts in EU Green Deal implementation velocity or Australian-China trade protocol access would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Saudi Arabia Red Meat Market
Meat Products
Bacon Slicers Market
Meat Products
Brazil Meat Products Market
Meat Products
Beef Liver Market
Meat Products
Oman Poultry Meat Market
Meat Products
Global Edible Meat Market
Meat Products
Mechanically Separated Meat Market
Meat Products
North America Edible Meat Market
Meat Products
Blended Meat Market
Meat Products
Meat Emulsions Market
Meat Products
North America Processed Meat Market
Meat Products
Pork Meat Market
Meat Products
Saudi Arabia Edible Meat Market
Meat Products
United States Red Meat Market
Meat Products
Europe Processed Meat Market
Meat Products
Fresh Organic Chicken Market