

Meat Tenderizer Market Size, Share, and Industry Trends Forecast 2026-2036
Meat Tenderizer Market Insights
Commercial foodservice procurement is rotating from small-batch marinade solutions toward industrial enzymatic systems that deliver consistent texture at volume. McCormick & Company leverages its retail spice distribution network to anchor consumer-grade tenderizer penetration in North American supermarkets. AB Enzymes competes through specialized protease formulations engineered for poultry and red meat applications. Kerry Group dominates clean-label enzyme development, positioning its portfolio to capture reformulation demand as processors reduce phosphate additives.
Meat tenderizers comprise mechanical devices, enzyme preparations, acidic chemical agents, and seasoned marinades designed to disrupt collagen and myofibrillar structures in raw muscle tissue. Enzymatic variants typically deploy fungal or plant-derived proteases such as papain, bromelain, or ficin at specified activity levels measured in tyrosine units per gram. Mechanical tenderizers command the largest installed base in industrial settings, while enzymatic solutions represent the fastest-expanding category as processors pursue yield optimization and uniform portion control. Marinades retain margin strength in premium retail channels where flavor positioning justifies higher per-unit pricing.
The FDA oversees GRAS self-affirmation for food enzymes in the United States, while the USDA FSIS mandates accurate ingredient disclosure on meat product labels. The EU EFSA evaluates novel enzyme preparations under updated food improvement agent protocols, creating compliance thresholds that favor established suppliers with dossier experience. Stakeholders must monitor regulatory divergence between enzyme approval pathways in the United States and Europe, as asynchronous clearances threaten product launch timing and cross-border formulation standardization.
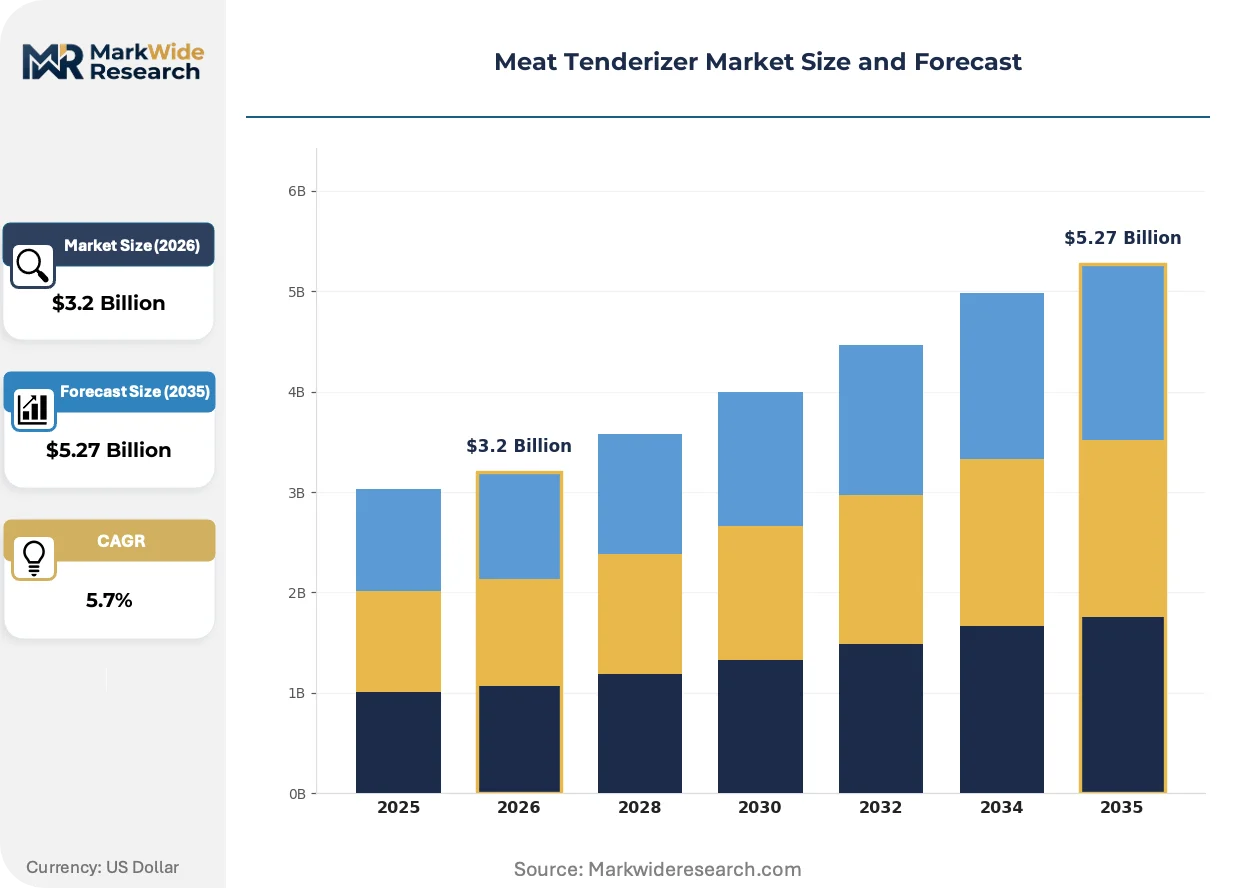
Market Dynamics
Commercial foodservice chains are consolidating procurement around enzymatic tenderizing systems to eliminate texture inconsistency across thousands of locations. This standardization mandate is compressing the addressable market for small-batch marinade suppliers while expanding industrial enzyme throughput requirements.
Growth Catalysts
- USDA FSIS Labeling Harmonization:Unified disclosure requirements for enzyme-treated meats reduce formulation complexity for multi-state processors. Large operators now specify tenderized proteins without state-by-state compliance friction.
- Poultry Processing Automation:Automated injection systems integrate protease dosing directly into brine lines. Brazil's integrators deploy these configurations to accelerate line speeds while maintaining tenderness specifications.
- Collagen-Heavy Cuts:Demand for underutilized beef primals—chuck roll, brisket, plate—requires enzymatic intervention to render them grill-ready. Foodservice distributors specify activity-calibrated papain to transform these cuts into premium menu items.
Market Restraints
- Papain Price Volatility:Raw papaya latex supply concentrates in East African and Indian extraction facilities. Weather-driven crop failures transmit directly to enzyme cost structures without viable synthetic substitutes at scale.
- Mechanical Tenderizer Capital Requirements:Industrial needle and blade systems demand stainless steel fabrication and precision alignment. Mid-size processors defer replacement cycles, extending equipment life beyond optimal sanitation windows.
- EU EFSA Dossier Burden:Novel protease approvals require extensive toxicology packages. Smaller enzyme houses lack resources to navigate food improvement agent protocols, ceding position to established suppliers with regulatory infrastructure.
Strategic Opportunities
- India Food Processing Zones:FSSAI modernization and PLI scheme incentives attract cold-chain infrastructure investment. Domestic bromelain extraction from pineapple waste streams offers localized supply security for regional meat processors.
- Clean-Label Phosphate Replacement:Kerry Group and AB Enzymes position transglutaminase-protease blends as phosphate alternatives. Reformulation demand accelerates as processors respond to consumer ingredient-panel scrutiny.
- E-Commerce Direct-to-Consumer Marinades:Subscription meat-box services specify co-branded tenderizer sachets. This channel bypasses traditional retail slotting fees while capturing premium positioning through recipe integration.
Industry Challenges
- Enzyme Activity Calibration:Protease potency varies by batch and storage condition. Quality control teams require specialized training to titrate dosing against incoming meat pH and temperature, extending onboarding timelines.
- Cross-Contamination Protocols:Shared equipment between allergen-containing and allergen-free enzyme lines demands validated cleaning procedures. USDA FSIS inspectors flag inadequate sanitation documentation during routine audits.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meat Tenderizer Market Trends and Innovations
Enzyme engineering and processing automation are converging to redefine protein texture management. Suppliers now compete on precision dosing, activity stability, and integration with existing production lines rather than commodity protease sourcing.
High-pressure processing technology is fragmenting traditional tenderizing workflows. HPP units apply isostatic pressure to raw muscle, disrupting myofibrillar structure without chemical additives. Premium beef packers in Australia and the United States install these systems to serve clean-label retail programs. The technology is fragmenting the tenderizer market into chemical-dependent and chemical-free processing silos with diverging equipment requirements.
EU EFSA updated its food improvement agent guidance in 2023, tightening submission requirements for novel enzyme sources. Industrial suppliers must now demonstrate substrate specificity and allergen absence through extended studies. This regulatory recalibration delays product launches by 18-24 months. Established enzyme houses with existing dossiers exploit this friction to lock out emerging competitors.
Foodservice procurement teams now specify outcome-based tenderizing contracts rather than ingredient purchasing. Operators pay per consistent texture outcome, transferring enzymatic optimization risk to enzyme suppliers. This model compresses supplier margins while demanding real-time production monitoring. Brazil's beef processing sector pilots these arrangements most aggressively, driven by export quality consistency requirements.
Meat Tenderizer Market Segmentation
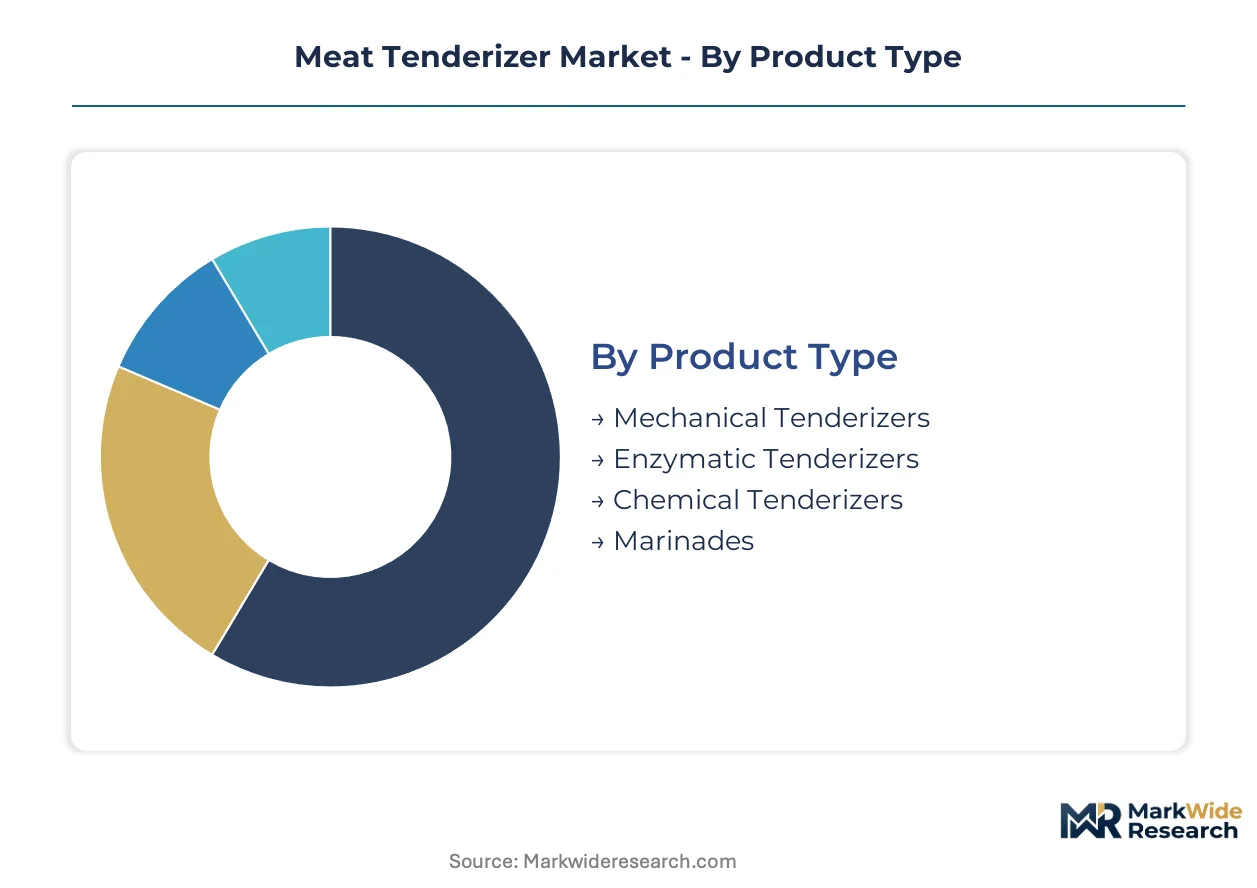
Meat tenderizer procurement patterns diverge sharply across equipment, enzyme formulations, and consumer formats. Understanding where margin pools concentrate within each category reveals how suppliers prioritize R&D investment and channel strategy.
Product Type:
Margin pools concentrate in enzymatic systems where proprietary protease formulations command recurring revenue through activity-calibrated supply contracts.
- Mechanical Tenderizers:Industrial needle and blade systems physically disrupt collagen structures through calibrated penetration depth. Brazil's beef processing sector concentrates demand for high-throughput configurations that integrate with existing slaughter line layouts. Capital intensity and stainless steel fabrication requirements sustain pricing power for established equipment manufacturers.
- Enzymatic Tenderizers:Fungal and plant-derived protease preparations—papain, bromelain, ficin—deliver targeted myofibrillar breakdown at specified tyrosine activity levels. Commercial foodservice chains in the United States specify these systems to eliminate texture inconsistency across thousands of locations. Kerry Group and AB Enzymes compete on clean-label positioning and poultry-specific formulations.
- Chemical Tenderizers:Acidic agents including vinegar, citrus extracts, and phosphate compounds modify surface protein structures. Limited penetration in premium channels due to clean-label headwinds.
- Marinades:Seasoned liquid preparations combining tenderizing acids with flavor compounds. Retail supermarkets and direct-to-consumer subscription services sustain margin strength through recipe integration and premium positioning.
The dominant share belongs to Mechanical Tenderizers, while Enzymatic Tenderizers is closing the gap fastest.
Application:
Volume concentration tracks automation intensity, with integrated processing lines driving the steepest throughput requirements.
- Food Processing Units:Industrial-scale facilities deploy automated injection systems that integrate protease dosing directly into brine lines. Brazil's poultry integrators and Australian beef packers lead adoption of these configurations to accelerate line speeds while maintaining tenderness specifications. USDA FSIS labeling harmonization reduces compliance friction for multi-state operators.
- Restaurants:Chain foodservice operators specify outcome-based tenderizing contracts, paying per consistent texture outcome rather than ingredient volume. This procurement shift transfers enzymatic optimization risk to suppliers while demanding real-time production monitoring.
- Household Kitchens:Consumer-grade powdered and liquid preparations distributed through supermarket spice aisles. McCormick & Company leverages retail distribution networks to anchor penetration.
- Butcher Shops:Small-batch mechanical tenderizing and custom marinade preparation for local protein sourcing.
- Catering Services:Event-scale protein preparation requiring rapid turnaround on collagen-heavy cuts.
Food Processing Units captures the largest volume share, with Restaurants expanding most quickly through specification-driven procurement.
End User:
Customer scale determines contract structure, with largest operators consolidating supply relationships around technical service capabilities.
- Foodservice Providers:National and regional chains standardizing protein texture across distributed locations. Enzymatic system adoption eliminates location-to-location variation that plagued traditional marinade approaches.
- Meat Processing Plants:Integrated slaughter and further-processing facilities requiring industrial-scale mechanical and enzymatic systems. Brazil's export-oriented beef sector concentrates demand for equipment that meets international quality consistency requirements.
- Catering Companies:Volume-event operators with intermittent high-throughput needs and limited capital for dedicated equipment.
- Retail Butchers:Independent operators maintaining small-batch mechanical tenderizing for local customer relationships.
Meat Processing Plants holds the dominant procurement position, while Foodservice Providers gains share fastest through standardization mandates.
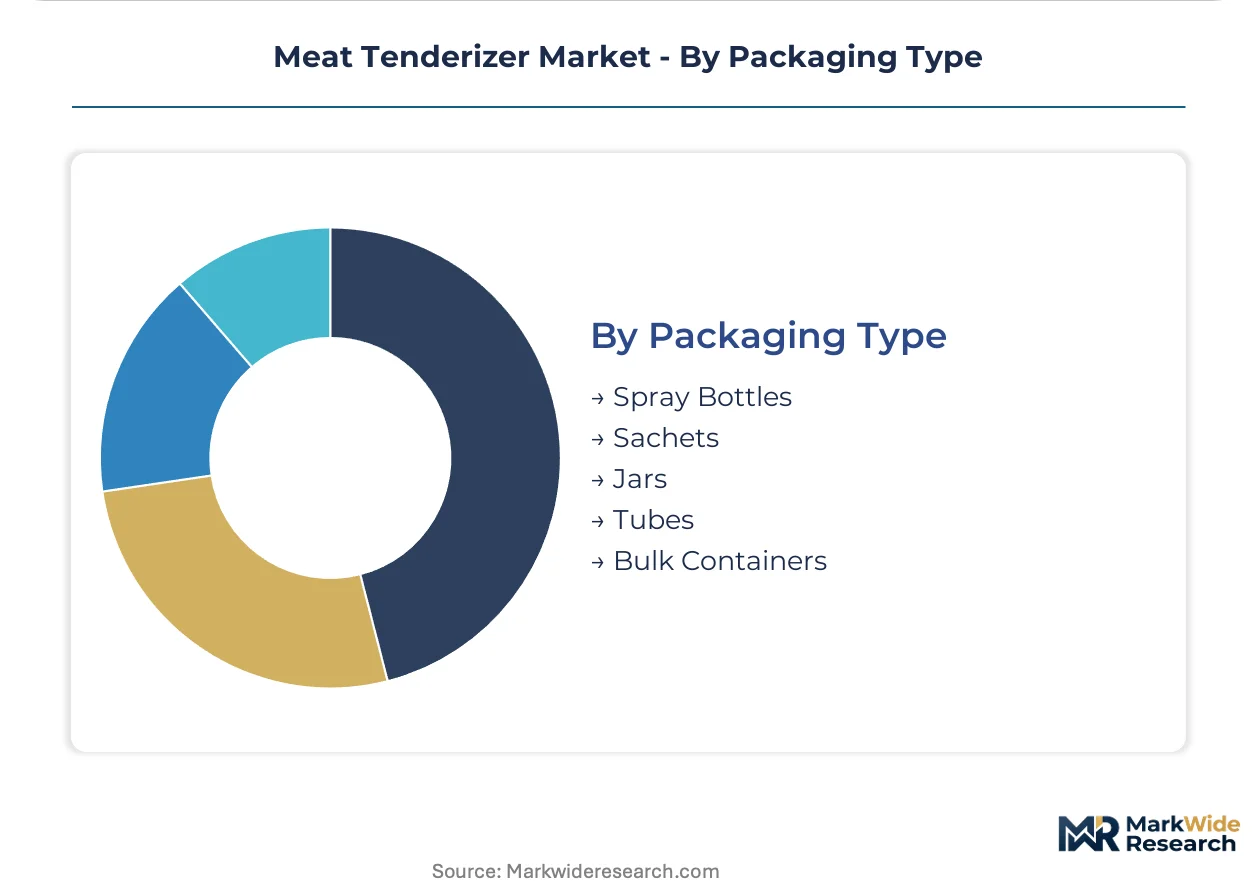
Packaging Type:
Format selection tracks channel economics and usage occasion, with single-serve configurations capturing premium positioning.
- Spray Bottles:Consumer kitchen convenience format enabling controlled application on individual cuts. Supermarket placement competes for shelf space against established spice brands.
- Sachets:Single-use portions specified by subscription meat-box services for recipe-integrated delivery. E-commerce direct-to-consumer channels bypass traditional retail slotting fees while capturing premium positioning.
- Jars:Bulk retail formats for household pantries with repeat-purchase loyalty.
- Tubes:Foodservice portion control for back-of-house consistency.
- Bulk Containers:Industrial totes for high-volume enzymatic dosing in automated processing lines.
Bulk Containers dominates industrial procurement, though Sachets climbs fastest through e-commerce channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Raw papaya latex extraction facilities in East Africa and India anchor upstream supply for papain-derived enzymes. Brazil's beef processing sector and the United States' commercial foodservice chains concentrate downstream equipment procurement.
United States
Commercial foodservice chains standardize protein texture across thousands of locations through enzymatic tenderizing systems. The FDA oversees GRAS self-affirmation for food enzymes while the USDA FSIS mandates accurate ingredient disclosure on meat product labels. Chicago and Dallas processing hubs deploy automated injection systems integrating protease dosing into brine lines.
Brazil
Export-oriented beef packers concentrate demand for industrial-scale mechanical tenderizing equipment meeting international quality consistency requirements. ANVISA regulates food additive approvals including enzyme preparations for meat processing. São Paulo state's integrated poultry and beef processing facilities pilot outcome-based tenderizing contracts with enzyme suppliers.
Germany
Industrial enzyme houses leverage established regulatory dossiers to supply protease formulations across European meat processing networks. EFSA evaluates novel enzyme preparations under food improvement agent protocols that favor suppliers with submission experience. Bavaria's food technology cluster hosts formulation development for clean-label phosphate replacement solutions.
India
FSSAI modernization and PLI scheme incentives attract cold-chain infrastructure investment into domestic meat processing. Domestic bromelain extraction from pineapple waste streams offers localized supply security for regional processors. Maharashtra and Karnataka food processing zones develop enzymatic tenderizing capabilities for expanding domestic protein demand.
Australia
Premium beef packers install high-pressure processing units to serve clean-label retail programs without chemical additives. TGA oversight applies to processing equipment standards while state-level food safety authorities regulate enzyme-treated meat labeling. Queensland and New South Wales processing facilities fragment tenderizing workflows between chemical-dependent and chemical-free processing silos.
Meat Tenderizer Market Competitive Landscape
Concentration sits with diversified ingredient suppliers and specialized enzyme houses rather than equipment fabricators alone. The vendor base spans three tiers: multinational flavor and ingredient conglomerates with enzyme divisions, dedicated biotechnology firms focused on protease engineering, and stainless steel equipment manufacturers serving industrial processing lines. Dominant competitive moves include strategic partnerships between enzyme suppliers and automation integrators, plus portfolio diversification into clean-label phosphate replacement formulations.
Among the specialized biotechnology tier, AB Enzymes and Kerry Group exemplify contrasting strategic positioning within protease development. AB Enzymes occupies a position emphasizing poultry and red meat application-specific formulations. Kerry Group anchors the clean-label enzyme development segment, capturing reformulation demand as processors reduce phosphate additives. JBT Corporation represents the industrial equipment archetype, with its corporate suffix indicating incorporated status typical of US-based machinery suppliers. These three entities collectively illustrate how competitive positioning fragments across enzymatic formulation expertise, regulatory navigation capability, and production line integration scale.
| Leading Market Players |
|---|
| JBT Corporation |
| McCormick & Company |
| Amano Enzyme |
| AB Enzymes |
| Specialty Enzymes & Probiotics |
| Enzyme Development Corporation |
| Enzyme Bioscience |
| Enzybel Group |
| Kerry Group |
| Others |
Pricing and Supply Chain Analysis
FDA GRAS self-affirmation protocols gate both supplier qualification and price differentiation in enzymatic tenderizers, forcing buyers to pay premiums for dossier-complete suppliers while excluding uncertified competitors from foodservice contracts.
Pricing Analysis
USDA FSIS labeling harmonization dictates the pricing tier structure across the meat tenderizer market. Three-tier pricing separates pharmaceutical-grade enzyme preparations from industrial bulk formulations and consumer retail formats. Price differentiation rests on GRAS certification status and activity calibration precision. Cost compression in commodity papain is intensifying because East African crop volatility transmits directly to enzyme cost structures. Small-batch marinade suppliers exhibit the highest price sensitivity, while national foodservice chains prioritize outcome consistency over unit economics.
Supply Chain Analysis
Port congestion on East African and Indian shipping lanes elevates inbound logistics costs for papain-derived enzymes before processing. Raw material sourcing draws from papaya latex extraction in Kenya and Tanzania, bromelain recovery from Philippine pineapple waste, and fungal protease fermentation in Germany. Single-source vulnerability concentrates in East African papain supply, where weather-driven crop failures lack synthetic substitutes. Distribution runs through cold-chain logistics networks serving Brazil's beef processing corridors and United States foodservice hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a defensive moat, where established enzyme houses with existing EFSA dossiers lock out emerging competitors through compliance friction that extends product launch timelines.
For Market Incumbents: Consolidate regulatory dossier advantages by accelerating novel protease submissions ahead of EFSA guidance tightening. Deepen backward integration into papaya cultivation partnerships in East Africa to neutralize raw material volatility. Kerry Group and AB Enzymes demonstrate how clean-label phosphate replacement capabilities anchor multi-year supply contracts against mechanical tenderizer substitution threats. For New Entrants and Emerging Players: FSSAI fast-track certification for bromelain extraction from pineapple waste streams unlocks white-space penetration in India's expanding food processing zones. Target Maharashtra and Karnataka state processing facilities with localized enzyme supply security propositions. Direct-to-consumer sachet formats for subscription meat-box services offer channel bypass advantages against retail slotting fee barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across high-pressure processing equipment as Australian and United States beef packers fragment tenderizing workflows into chemical-free silos. Acquisition candidates should display integrated automation capabilities spanning protease dosing and real-time texture monitoring. Watch for USDA FSIS enforcement actions on cross-contamination protocols as signal for regulatory compliance premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Papaya Cultivation | Kenyan and Tanzanian estate partnerships neutralize latex supply volatility for papain producers. |
| Clean-Label Phosphate Replacement Formulation | Kerry Group's transglutaminase-protease blends capture reformulation demand from ingredient-panel scrutiny. |
| Automated Injection System Integration | Brazilian poultry integrators deploy brine-line protease dosing to accelerate line speeds. |
| Outcome-Based Tenderizing Contracts | São Paulo beef processors pilot per-texture-outcome pricing transferring optimization risk to suppliers. |
| High-Pressure Processing Capacity Buildout | Queensland packers install HPP units to serve clean-label retail programs without chemical additives. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across this study's primary research phase. Enzyme procurement directors at Brazilian beef processors, foodservice chain menu development executives, and USDA FSIS compliance officers provided operational perspective. Secondary validation drew from FDA GRAS notifications, EFSA food improvement agent submissions, ANVISA additive approval records, and customs trade data on papain imports. Bottom-up volume modeling triangulated against top-down expenditure analysis across the projection horizon.
Across the analysis window, forecasts segmented by product type, application intensity, end-user scale, and packaging format. CAGRs derived from regression analysis against protein processing automation indices and foodservice outlet expansion trajectories. Enzyme activity calibration standards and mechanical tenderizer replacement cycles served as industry-specific forecast inputs.
Underlying assumptions cover sustained FDA-USDA regulatory alignment, with deviation risk concentrated in asynchronous EFSA clearance timelines for novel protease sources. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.