
 Beef Tallow Market | 2026-2036
Beef Tallow Market Size, Share, and Industry Trends Forecast 2026-2036
Beef Tallow Market Analysis
Advanced rendering automation is rewriting tallow processing economics by cutting energy use and improving yield recovery from raw fatstock. Darling Ingredients leverages vertical integration across rendering and value-added ingredient streams to sustain margin capture from feedstock to finished oleochemicals. Cargill Incorporated anchors North American supply through controlled rendering networks and captive access to cattle processing byproducts. Tyson Foods competes on manufacturing scale, operating multi-facility rendering complexes that convert slaughter waste into standardized tallow grades at high throughput.
Beef tallow is the rendered form of bovine fat tissue, typically yielding a composition of roughly 50% saturated fatty acids with a melting point between 40°C and 46°C, produced through wet or dry rendering of slaughterhouse trimmings and used across food, oleochemical, and personal care applications. Rendered tallow dominates volume throughput due to established supply chains linking meatpackers to industrial buyers, while fully refined tallow commands premium positioning in cosmetics and pharmaceutical-grade applications where color stability and low free fatty acid content determine qualification. Organic tallow occupies a narrowing but defended niche among artisan soap makers and clean-label personal care brands that reject conventional rendering inputs.
USDA grading standards and FDA food-contact regulations govern tallow purity for edible and cosmetic applications in the United States, while REACH registration and ECHA substance evaluation shape market access for European-bound oleochemical derivatives. Brazil's ANVISA and China's SAMR impose divergent import testing protocols that fragment compliance burdens across export destinations. Stakeholders must monitor rendering technology licensing costs and regional feedstock competition from poultry fat and palm oil stearin to preserve processing margins.
Market Dynamics
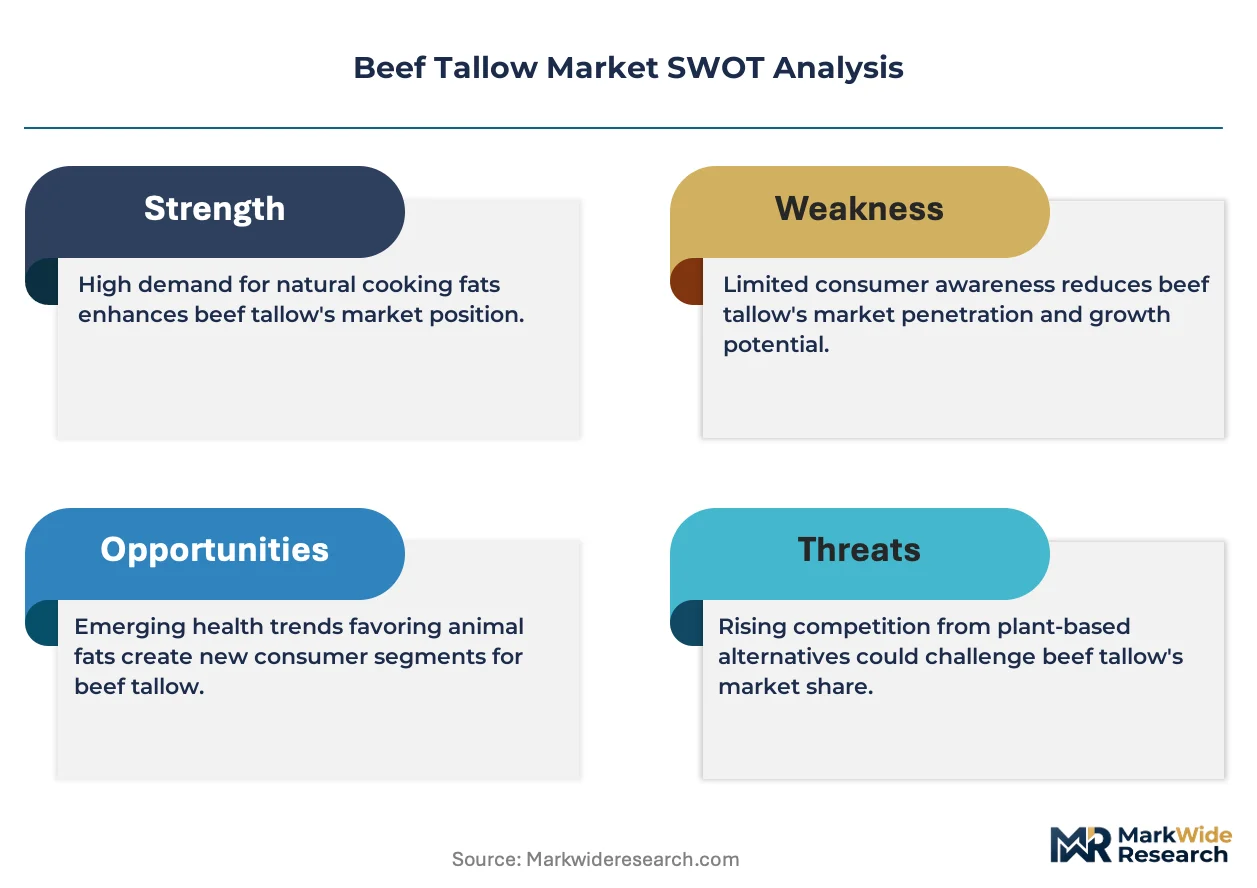
Rendering automation and EU F-Gas Regulation compliance are compressing margins for smaller processors while rewarding capital-intensive operators with captive feedstock supply. The structural shift toward certified oleochemical inputs is bifurcating the market into commodity tallow and pharmaceutical-grade refined products.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on synthetic refrigerants and fluorinated gases are redirecting industrial buyers toward bio-based alternatives, elevating tallow-derived fatty acids as compliant feedstock for lubricant and surfactant manufacturing.
- Biodiesel blending mandates:Brazil's ANP biofuel policies and renewable diesel incentives in multiple jurisdictions are absorbing surplus tallow volumes that previously flowed to lower-value feed applications.
- Wet rendering technology:Continuous centrifugal separation systems are improving yield recovery from raw fatstock, lowering unit processing costs for industrial-scale operators serving food and oleochemical buyers.
Market Restraints
- Cattle cycle volatility:Brazilian and Australian herd liquidation phases create irregular fatstock availability, forcing renderers to absorb input cost swings or pass them to contract customers.
- Palm oil stearin substitution:Southeast Asian palm derivatives compete directly on price for soap and surfactant applications, compressing tallow's addressable market in cost-sensitive formulations.
- REACH registration burdens:ECHA substance evaluation and registration requirements impose fixed compliance costs that disproportionately burden small-volume exporters to European oleochemical markets.
Strategic Opportunities
- Pharmaceutical-grade refinement:Low-FFA, color-stable tallow fractions command substantial premiums in cosmetic and API applications where USP-NF compliance opens access to contract manufacturing networks.
- Artisan channel penetration:Direct-to-craft soap maker and boutique candle producer channels bypass commodity pricing, capturing value from clean-label and grass-fed certification narratives.
- Carbon accounting integration:Lifecycle assessment methodologies and Scope 3 reporting requirements are positioning tallow as a lower-carbon alternative to petroleum-derived oleochemicals in corporate sustainability programs.
Industry Challenges
- Skilled rendering technician shortage:Automated plant operations require cross-trained personnel capable of managing centrifugal separation, quality control, and regulatory documentation simultaneously.
- Multi-jurisdiction certification timelines:Parallel FDA food-contact, REACH, and ANVISA approval processes extend product qualification cycles for exporters serving diversified end-use markets.
- Legacy facility retrofit costs:Dry rendering plants face capital-intensive upgrades to meet energy efficiency and effluent discharge standards imposed by EPA and state environmental regulators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beef Tallow Market |
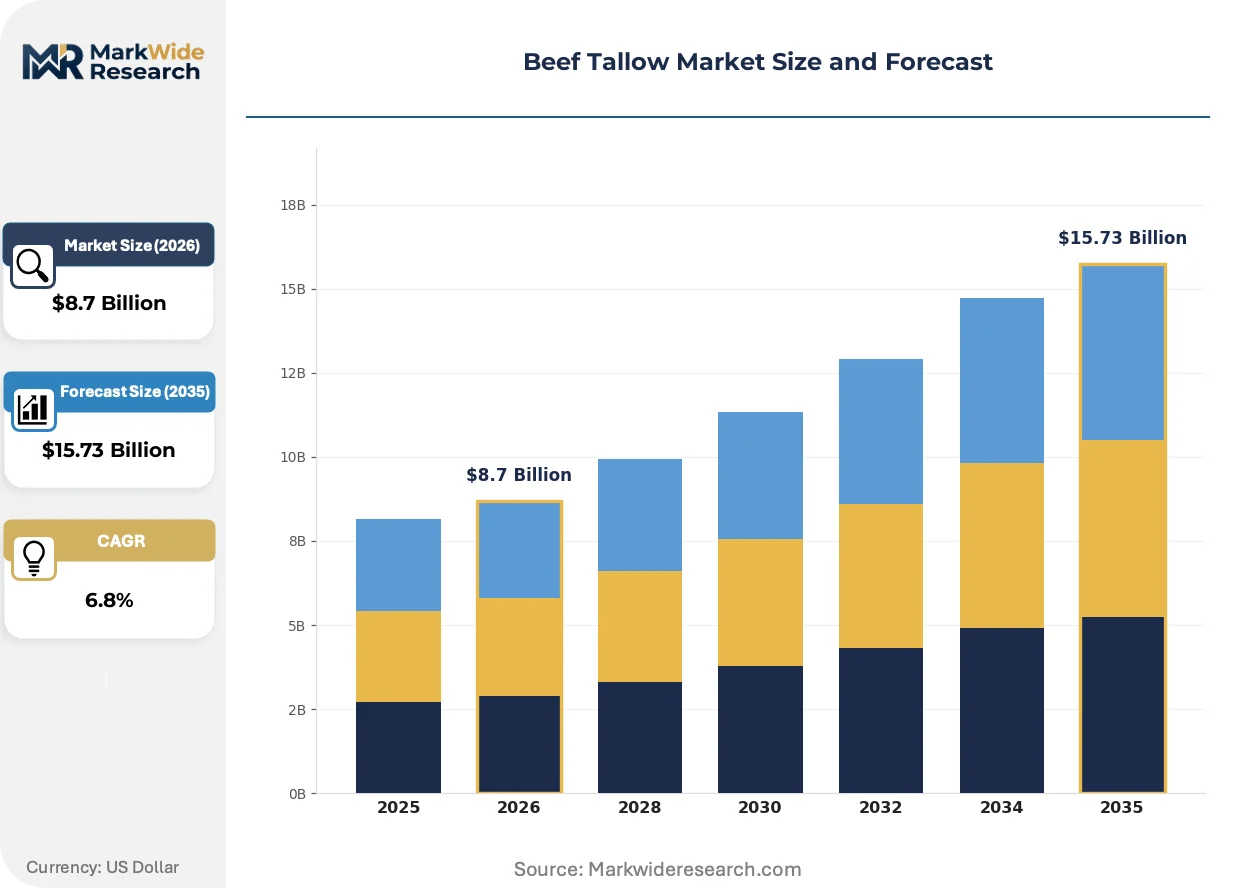
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Tallow, Rendered Tallow, Fully Refined Tallow, Blended Tallow Application: Cosmetics, Food Processing, Soap Making, Candle Production End User: Food Manufacturers, Personal Care Brands, Artisans, Retail Outlets Distribution Channel: Online Retail, Specialty Stores, Wholesale Distributors, Supermarkets |
| Companies Covered | Ajinomoto Co., Inc., Jacob Stern & Sons Inc, Darling Ingredients, JBS, Sanimax ABP Inc, Cargill Incorporated, Baker Commodities, Inc., Tyson Foods, SARIA SE & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beef Tallow Market Emerging Trajectories
Processing technology convergence and regulatory stringency are elevating product purity thresholds while compressing acceptable batch-to-batch variation. These forces are reshaping capital allocation and competitive positioning across the value chain.
Supercritical CO2 extraction is hybridizing conventional rendering with precision fractionation, enabling selective recovery of specific fatty acid profiles for pharmaceutical and nutraceutical applications. Specialty chemical manufacturers in Germany and Switzerland are adopting these systems to produce USP-grade glycerides and sterol concentrates. The technology is compressing the traditional separation between commodity rendering and fine chemical processing, forcing mid-scale operators to choose between capital investment and market exit.
REACH authorization and restriction procedures are tightening control over tallow-derived substances classified as SVHCs or subject to sunset dates, compelling European oleochemical formulators to secure supply chain documentation from rendering sources. The industrial consequence is a documentation burden that favors vertically integrated meatpackers with captive rendering over independent processors. Cosmetic and personal care manufacturers sourcing European-bound ingredients are responding by consolidating supplier bases and demanding batch-level traceability certifications.
Direct procurement from rendering facilities is displacing traditional broker-mediated spot market transactions among mid-volume soap and candle manufacturers. These buyers are establishing annual contracts with named rendering plants to secure price stability and provenance claims for grass-fed or organic product lines. The shift is most visible in North American and Australian markets where artisan brand differentiation depends on verifiable supply chain narratives rather than commodity exchange pricing.
Beef Tallow Market Segmentation
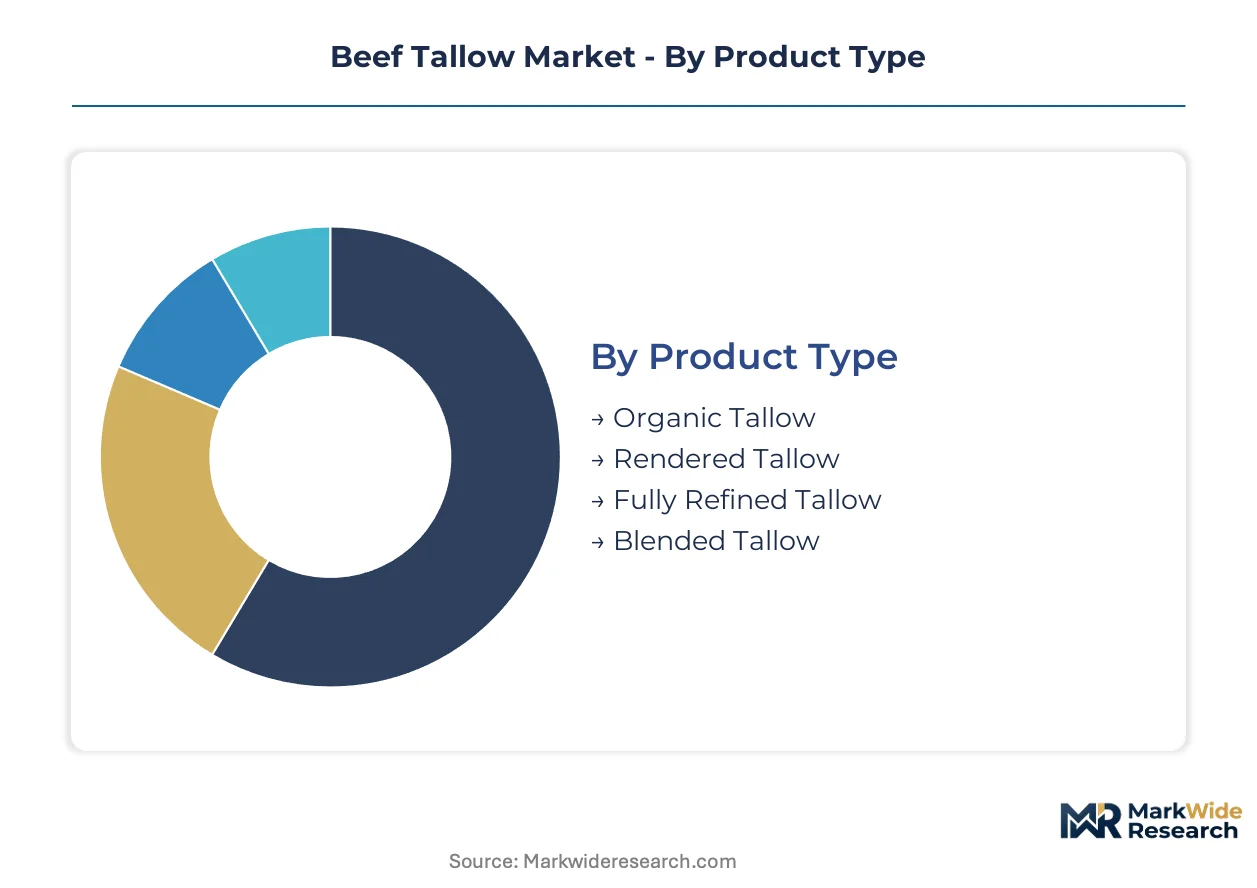
Product differentiation in beef tallow tracks closely to purity thresholds and certification requirements. Application splits reveal divergent margin profiles between commodity feedstock and premium cosmetic-grade sales.
Product Type:
Cost tier determines processing investment and margin capture across the four product categories.
- Rendered Tallow:Standard-grade product from wet or dry rendering of slaughterhouse trimmings, typically carrying 50% saturated fatty acids and melting between 40°C and 46°C. Food manufacturers in Brazil absorb the largest volumes under biodiesel blending mandates and feed compound formulations. Rendered tallow holds installed capacity. Fully refined tallow is rotating up the share rankings.
- Fully Refined Tallow:Low-FFA, color-stable fractions meeting USP-NF or cosmetic-grade specifications through additional bleaching and deodorization steps. Personal care brands in Germany and Switzerland source these grades for API and nutraceutical applications where ECHA documentation requirements favor qualified suppliers.
- Organic Tallow:Grass-fed certified fatstock from cattle raised without synthetic inputs, commanding premium positioning among artisan soap makers rejecting conventional rendering. Supply concentrates in Australian and North American ranching regions with verifiable pasture protocols.
- Blended Tallow:Formulations combining tallow with poultry fat or palm stearin to achieve target melting points and cost positions for industrial soap and surfactant manufacturing.
Rendered tallow holds installed capacity. Fully refined tallow is rotating up the share rankings.
Application:
End-use specifications fragment the market across four distinct performance requirements and regulatory exposures.
- Cosmetics:Pharmaceutical-grade refined fractions with strict limits on free fatty acids and peroxide values. REACH registration and ECHA substance evaluation govern European market access, favoring vertically integrated meatpackers with captive rendering and batch-level traceability.
- Food Processing:Edible-grade tallow governed by FDA food-contact regulations in the United States and analogous standards from Brazil's ANVISA. Bakery and frying applications dominate volume offtake.
- Soap Making:Both commodity-grade for mass production and artisan-channel organic grades for boutique brands. Palm oil stearin substitution pressure concentrates in this segment.
- Candle Production:Clean-burning tallow fractions competing with paraffin and soy wax on scent throw and combustion characteristics. Direct procurement from named rendering plants is displacing broker-mediated spot transactions.
Food processing commands volume leadership. Cosmetics is climbing the fastest on value contribution.
End User:
Customer type shapes procurement patterns from annual contracts to spot market purchasing.
- Food Manufacturers:Industrial-scale buyers with captive rendering relationships or long-term supply agreements tied to cattle processing volumes.
- Personal Care Brands:Formulators requiring REACH-compliant documentation and USP-grade certifications for European and North American cosmetic markets.
- Artisans:Small-batch soap makers and candle producers sourcing organic or grass-fed certified tallow through direct rendering facility relationships.
- Retail Outlets:Supermarket and specialty store channels moving packaged tallow for home cooking and DIY personal care applications.
Food manufacturers anchor procurement scale. Personal care brands are expanding most quickly on specification premiums.
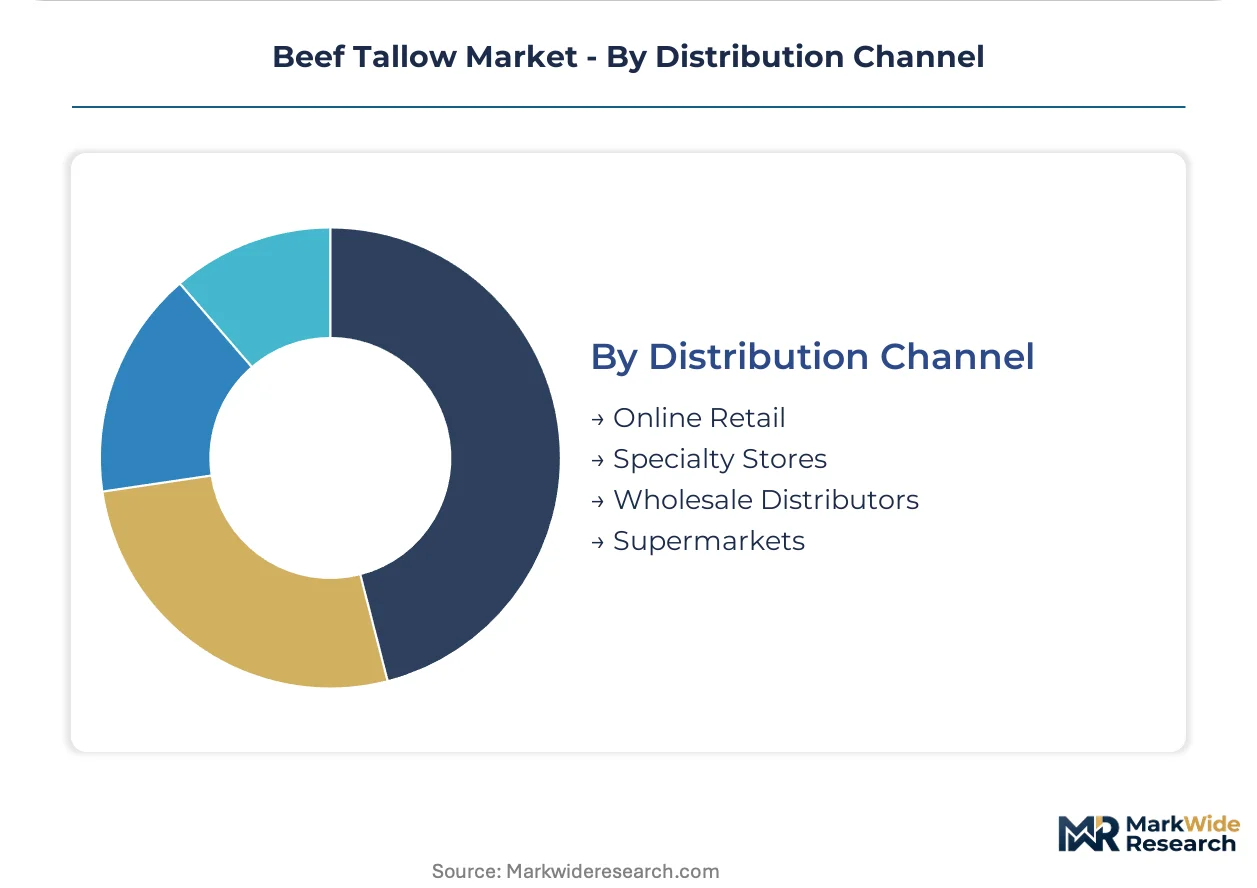
Distribution Channel:
Channel selection determines price realization and supply chain documentation depth.
- Wholesale Distributors:Traditional intermediaries serving industrial food and oleochemical buyers with volume aggregation and logistics services.
- Online Retail:Direct-to-artist platforms enabling grass-fed and organic certification narratives for boutique soap and candle makers.
- Specialty Stores:Natural products retailers targeting clean-label consumers with premium-positioned organic tallow SKUs.
- Supermarkets:Mass-market retail moving standard-grade tallow for household cooking applications.
Wholesale distributors retain volume throughput. Online retail is gaining share fastest on artisan channel penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil exports refined tallow fractions to European oleochemical manufacturers under REACH-registered supply chains, while Australian organic-certified grades reach North American artisan channels through direct rendering facility contracts.
United States
Food manufacturers absorb rendered tallow volumes for frying and bakery applications, while personal care brands in New Jersey and California demand USP-grade certifications. FDA food-contact regulations govern edible-grade purity standards. Rendering complexes in the Midwest cattle belt convert slaughterhouse trimmings into standardized grades at high throughput.
Brazil
Biodiesel blending mandates from ANP absorb surplus tallow previously directed to feed applications, while export markets in Germany and Switzerland pull pharmaceutical-grade refined fractions. ANVISA import testing protocols shape documentation requirements for outbound shipments. São Paulo state rendering capacity leverages captive cattle stock availability to serve both domestic biofuel and European oleochemical buyers.
Germany
Specialty chemical manufacturers adopt supercritical CO2 extraction systems to produce USP-grade glycerides for cosmetic and nutraceutical applications. ECHA substance evaluation and REACH authorization procedures tighten control over tallow-derived SVHC classifications. Industrial clusters in North Rhine-Westphalia consolidate supplier bases and demand batch-level traceability certifications from rendering sources.
Australia
Grass-fed certified organic tallow commands premium positioning among North American artisan soap makers rejecting conventional rendering inputs. The country's national agricultural regulator oversees pasture protocol verification for export eligibility. Queensland and New South Wales ranching regions concentrate supply for clean-label personal care brands sourcing through direct rendering facility relationships.
China
Industrial soap and surfactant manufacturers blend tallow with palm stearin to achieve target cost positions for domestic mass-market formulations. SAMR import testing protocols fragment compliance burdens for inbound oleochemical derivatives. Shandong Peninsula rendering operations process both domestic fatstock and imported grades for regional distribution.
Beef Tallow Market Vendor Landscape
On the supply side, the industry is consolidating around vertically integrated meatpackers with captive rendering networks and independent processors competing on specialty fractionation capabilities. Three strategic archetypes dominate: scale-driven commodity renderers serving biodiesel and feed markets, precision refiners targeting pharmaceutical-grade cosmetic applications, and organic-certified specialists capturing artisan channel premiums. Competitive moves center on backward integration into cattle processing byproducts and technology licensing for supercritical extraction systems.
Within the integrated processor tier, Darling Ingredients and Cargill Incorporated exemplify archetypes combining rendering scale with value-added oleochemical streams, while Tyson Foods anchors North American supply through multi-facility rendering complexes. Among specialty operators, Jacob Stern & Sons Inc occupies a position representing independent renderers serving diversified industrial buyers with customized tallow grades.
| Leading Market Players |
|---|
| Ajinomoto Co., Inc. |
| Jacob Stern & Sons Inc |
| Darling Ingredients |
| JBS |
| Sanimax ABP Inc |
| Cargill Incorporated |
| Baker Commodities, Inc. |
| Tyson Foods |
| SARIA SE & Co. KG |
| Others |
Supply Flow & Price Mechanics
Brazilian rendering capacity concentration around São Paulo state cattle processing clusters funnels margin capture toward integrated meatpackers with captive fatstock supply, while independent processors absorb input cost volatility from irregular Brazilian and Australian herd liquidation cycles.
Pricing Analysis
Dry rendering technology maintains economy-tier positioning against wet rendering's standard-grade premiums and supercritical CO2 extraction's pharmaceutical-grade price multiples. Price differentiation hinges on free fatty acid thresholds and REACH batch-traceability certification depth. Cost compression in commodity rendered tallow intensifies as palm oil stearin substitution pressure from Southeast Asian oleochemical exporters erodes addressable market share in mass-market soap formulations. Food manufacturers in Brazil exhibit highest price sensitivity due to biodiesel blending mandate absorption of surplus volumes, while German and Swiss cosmetic formulators demonstrate lowest sensitivity given USP-NF compliance premiums.
Supply Chain Analysis
EU F-Gas Regulation restrictions on synthetic refrigerant feedstock flows reshape oleochemical sourcing patterns toward bio-based fatty acid alternatives. Geographic supply concentration centers on Brazil, Australia, and the United States as dominant fatstock origins. Raw material dependencies include slaughterhouse trimmings, grass-fed certified cattle, and poultry fat blending inputs. Single-source vulnerability from Brazilian herd cycle volatility threatens renderers without diversified feedstock contracts. Distribution runs through wholesale distributors for industrial food and oleochemical buyers, with online retail platforms gaining share among artisan soap and candle channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Beef tallow sits in early-cycle expansion as EU F-Gas Regulation adoption redirects industrial lubricant and surfactant buyers toward bio-based fatty acid feedstock alternatives.
For Market Incumbents: Build certification moats around REACH-registered supply chains and USP-NF pharmaceutical-grade refinement capabilities. Darling Ingredients and Cargill Incorporated anchor positions through backward integration into cattle processing byproducts and captive rendering networks. Independent processors face margin compression from wet rendering automation capital requirements and palm oil stearin substitution in cost-sensitive soap applications. Defensive priorities center on supercritical CO2 extraction technology licensing and multi-jurisdiction FDA-ECHA-ANVISA qualification timelines. For New Entrants and Emerging Players: Australian organic-certified grass-fed tallow penetration into North American artisan channels offers white-space capture with direct-to-soap-maker procurement models bypassing wholesale distributor markups. Boutique candle producers in California and New Jersey represent underpenetrated demand for clean-burning tallow fractions with verifiable pasture protocol documentation. The most penetrable segment clusters around personal care brands requiring ECHA-compliant batch traceability for European cosmetic markets. Go-to-market execution should leverage online retail platform partnerships enabling grass-fed certification narratives. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated rendering specialists with captive cattle processing supply and supercritical extraction technology assets. Long-term viability across a five-to-ten-year horizon rests on carbon accounting integration positioning tallow as lower-carbon oleochemical alternatives in corporate Scope 3 reporting programs. Acquisition target archetypes include Australian organic-certified renderers with North American distribution relationships and German specialty chemical manufacturers with USP-grade glyceride production capabilities. The signal to watch is biodiesel blending mandate expansion across additional jurisdictions absorbing surplus tallow volumes.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Extraction Licensing | German and Swiss manufacturers deploy precision fractionation for pharmaceutical-grade glyceride recovery. |
| Backward Integration into Rendering | Tyson Foods and JBS secure captive fatstock supply from multi-facility cattle processing complexes. |
| REACH-Registered Supply Chain Certification | European oleochemical formulators consolidate supplier bases around batch-level traceability documentation. |
| Direct-to-Artisan Channel Expansion | Online retail platforms enable grass-fed and organic certification narratives for boutique soap makers. |
| Carbon Accounting Integration | Lifecycle assessment methodologies position tallow in corporate sustainability Scope 3 reporting programs. |
Methodological Framework
Initial hypotheses were tested against primary input from rendering plant managers, personal care brand procurement leads, biodiesel blending mandate regulators, and artisan soap maker channel partners and refined through secondary validation against customs and trade data, ANP biofuel policy filings, ECHA substance evaluation registers, and SEC 10-K disclosures from integrated meatpackers. Bottom-up segmentation modeling across product type, application, and end user combined with top-down macroeconomic triangulation anchored volume and value estimates.
Demand-supply balance dynamics shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include purity grade tier, end-use regulatory exposure, distribution channel structure, and regional rendering capacity concentration. CAGRs derived from historical volume trajectory analysis adjusted for biodiesel policy absorption rates and EU F-Gas Regulation compliance timelines. Industry-specific forecast inputs incorporated cattle cycle volatility patterns and supercritical extraction technology adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by palm oil stearin exporters or synthetic oleochemical manufacturers would shift outcomes. Material shifts in Brazilian ANP biofuel policy stringency, ECHA SVHC reclassification procedures, or Australian organic certification protocol changes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Dehydrated Meat Products Market
Meat Products
North America Processed Meat Market
Meat Products
Ham Slicers Market
Meat Products
United States Poultry Meat Market
Meat Products
Europe Processed Meat Market
Meat Products
Grass-Fed Meat Market
Meat Products
United States Frozen Meat Market
Meat Products
Qatar Poultry Meat Market
Meat Products
United States Edible Meat Market
Meat Products
United Arab Emirates Edible Meat Market
Meat Products
North America Poultry Meat Market
Meat Products
Global Canned Meat Market
Meat Products
United Arab Emirates Red Meat Market
Meat Products
Saudi Arabia Red Meat Market
Meat Products
Asia-Pacific Red Meat Market
Meat Products
Grass Fed Beef Market