
 India Home Loan Market | 2026-2036
India Home Loan Market Size, Share, and Industry Trends Forecast 2026-2036
India Home Loan Market Insights
Buyer concentration across salaried individuals and first-time buyers is rebalancing as housing finance reaches deeper into smaller cities and semi-urban centers. State Bank of India anchors its position through extensive rural branch networks and government-linked affordable housing schemes. HDFC Bank differentiates via digital origination platforms that compress turnaround times for metropolitan borrowers. Bajaj Housing Finance competes on flexible eligibility criteria tailored to self-employed professionals in growth corridors.
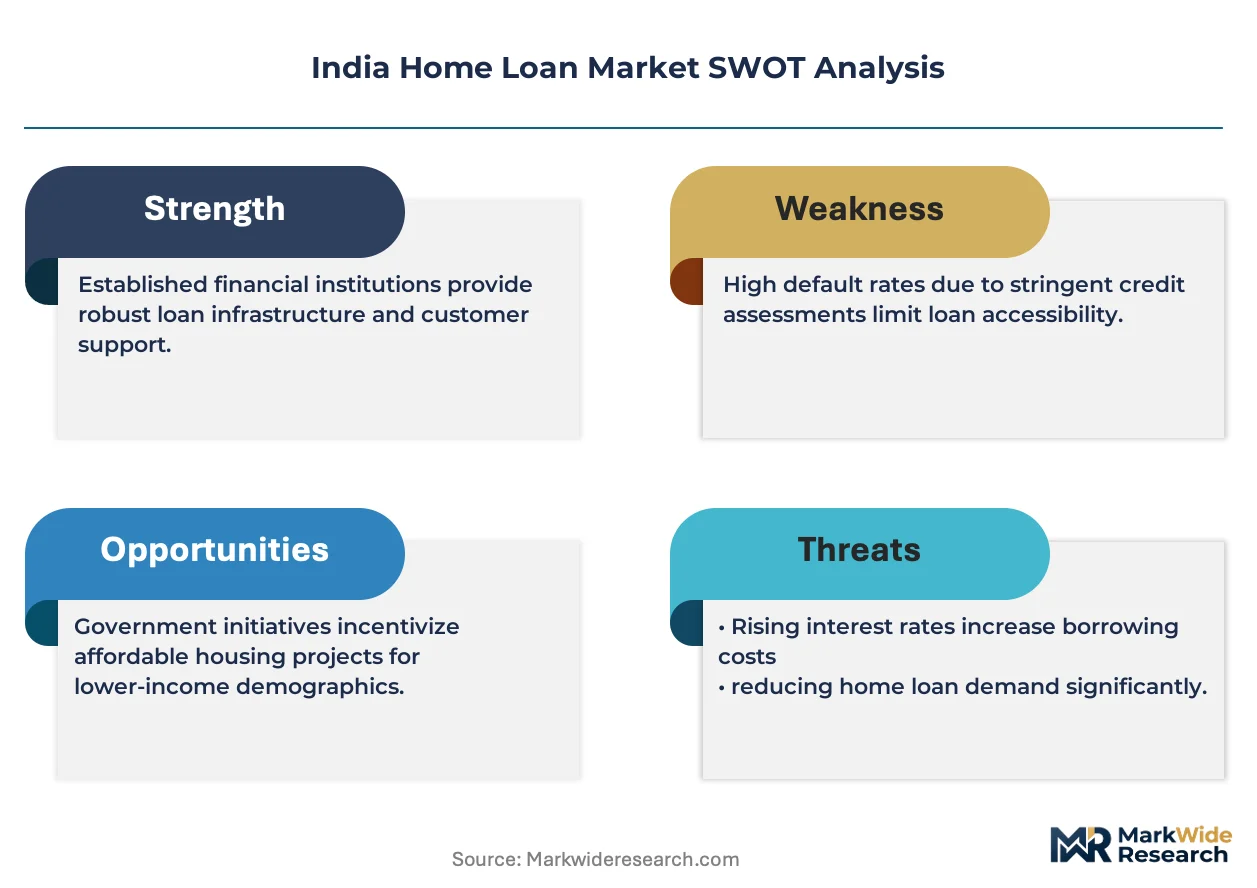
A home loan constitutes a secured term credit instrument collateralized by residential real estate, typically structured with tenures spanning 15 to 30 years and governed by benchmark-linked interest rate mechanisms including external benchmark-based lending rates. Its primary commercial purpose channels household savings into property acquisition while generating interest income for financial intermediaries. Floating rate instruments dominate origination volumes due to borrower preference for transmission of policy rate reductions. Home purchase loans command the largest share of outstanding credit, while home improvement loans represent the fastest-growing category as existing homeowners renovate rather than relocate amid elevated property prices. Public sector banks sustain the deepest penetration in semi-urban and rural geographies, though private sector banks capture disproportionate margin pools in premium urban segments.
RBI regulates capital adequacy, loan-to-value ceilings, and risk weights for housing finance exposures, while NHB oversees refinancing operations and liquidity support to housing finance companies. SEBI guidelines govern mortgage-backed securities that enable lenders to recycle capital into fresh originations. Stakeholders must monitor evolving RBI stance on personal loan risk weights and NHB liquidity windows as these directly constrain or expand balance sheet capacity across the lending ecosystem.
Market Dynamics
RBI's prudential norms on risk weights and loan-to-value ratios are compressing balance sheet capacity across housing finance companies while simultaneously redirecting origination flows toward salaried borrowers in tier-2 and tier-3 urban clusters.
Growth Catalysts
- Credit Linked Subsidy Scheme:Central government interest subvention for economically weaker sections is expanding formal housing finance penetration into semi-urban Maharashtra and Karnataka corridors previously served by informal money markets.
- First-time buyer concentration:Demographic cohorts aged 28-35 in Telangana and Tamil Nadu IT employment zones are creating sustained origination pipelines for lenders with digital income verification capabilities.
- Rural branch infrastructure:Public sector banks with extensive tier-3 networks are capturing deposit-funded cost advantages that translate into competitive pricing for agricultural income-backed housing loans.
Market Restraints
- Risk weight escalation:RBI's 2024 upward revision of risk weights for housing finance company exposures is constraining capital adequacy buffers and compressing lending capacity across non-bank originators.
- Collateral valuation opacity:Absence of standardized property price indices in tier-2 and tier-3 cities creates asset-liability mismatch risks for lenders extending long-tenure instruments against illiquid collateral.
- Interest rate transmission lag:Fixed deposit rate rigidity in public sector banks delays external benchmark-linked lending rate reductions, eroding borrower affordability during monetary easing cycles.
Strategic Opportunities
- Co-lending with regional banks:Housing finance companies can deploy balance sheet light models through priority sector lending partnerships with tier-2 city cooperative banks in Gujarat and Rajasthan.
- Green housing certification integration:Bureau of Indian Standards energy efficiency ratings for residential construction are creating differentiated pricing windows for lenders with specialized appraisal capabilities.
- Property technology convergence:Integration of satellite imagery with land registry databases is enabling automated title verification that reduces fraud risk in semi-urban origination.
Industry Challenges
- Digital underwriting talent scarcity:Shortage of data science professionals capable of deploying alternative credit scoring models for self-employed borrower segments is constraining product innovation timelines.
- Legacy core banking integration:Housing finance companies migrating to cloud-native origination platforms face API compatibility failures with decades-old loan servicing systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Home Loan Market |
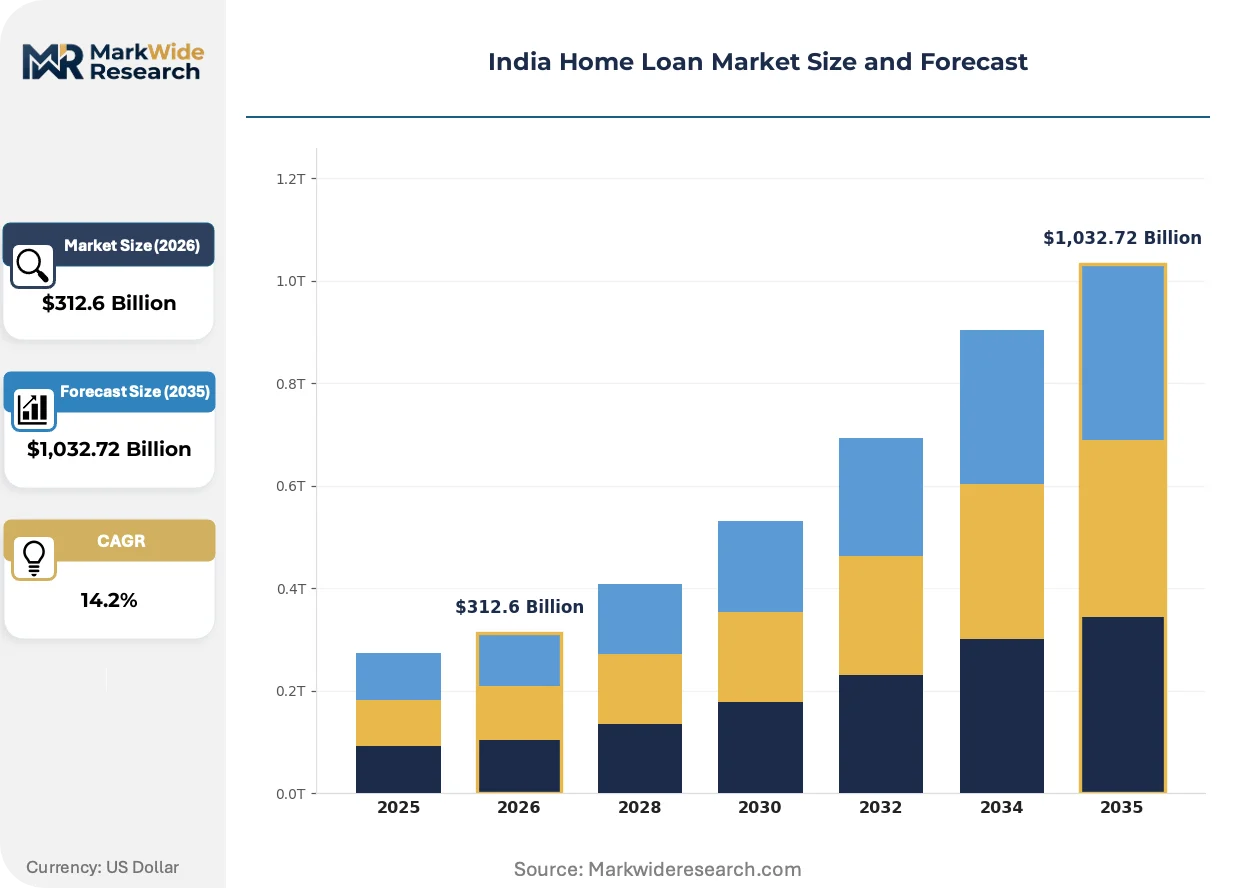
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $1,032.72 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: Home Purchase, Home Construction, Home Improvement, Land Purchase Interest Rate Type: Fixed Rate, Floating Rate, Hybrid Rate, Reverse Mortgage Customer Segment: First-time Buyers, Non-Resident Indians, Senior Citizens, Salaried Individuals Bank Type: Public Sector Banks, Private Sector Banks, Housing Finance Companies, Co-operative Banks |
| Companies Covered | ICICI Bank, Bajaj Housing Finance, State Bank of India, Tata Capital Housing Finance, PNB Housing Finance, HDFC Bank, Axis Bank, Kotak Mahindra Bank, LIC Housing Finance, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Home Loan Market Trends and Innovations
Digital origination infrastructure is compressing turnaround times from application to disbursement while simultaneously enabling alternative data-based underwriting for borrower segments excluded from traditional credit bureau scoring.
Application programming interface architectures for income verification and property valuation are consolidating vendor relationships among tier-1 private banks. HDFC Bank and ICICI Bank have deployed unified platforms that aggregate salary slip parsing, employer database validation, and automated collateral assessment into single-workflow origination. This consolidation is eliminating point-solution vendors and compressing procurement cycles from eighteen months to under ninety days.
RBI's 2023 mandate linking all floating rate retail loans to external benchmark-based lending rates has standardized pricing transparency across the housing finance ecosystem. The regulation forces housing finance companies to abandon internal benchmark systems that obscured transmission efficiency. Borrowers in Karnataka and Telangana are now switching lenders at accelerated pace when policy rate reductions materialize.
Aggregator platforms for loan comparison and digital documentation are displacing direct branch walk-ins as the dominant acquisition channel among salaried professionals aged 25-40. BankBazaar and Paisabazaar capture borrower intent through search-optimized interfaces, then auction leads to competing lenders. This channel shift is most pronounced in Mumbai and Bangalore metropolitan regions where property transaction velocity demands rapid financing commitment.
India Home Loan Market Segmentation
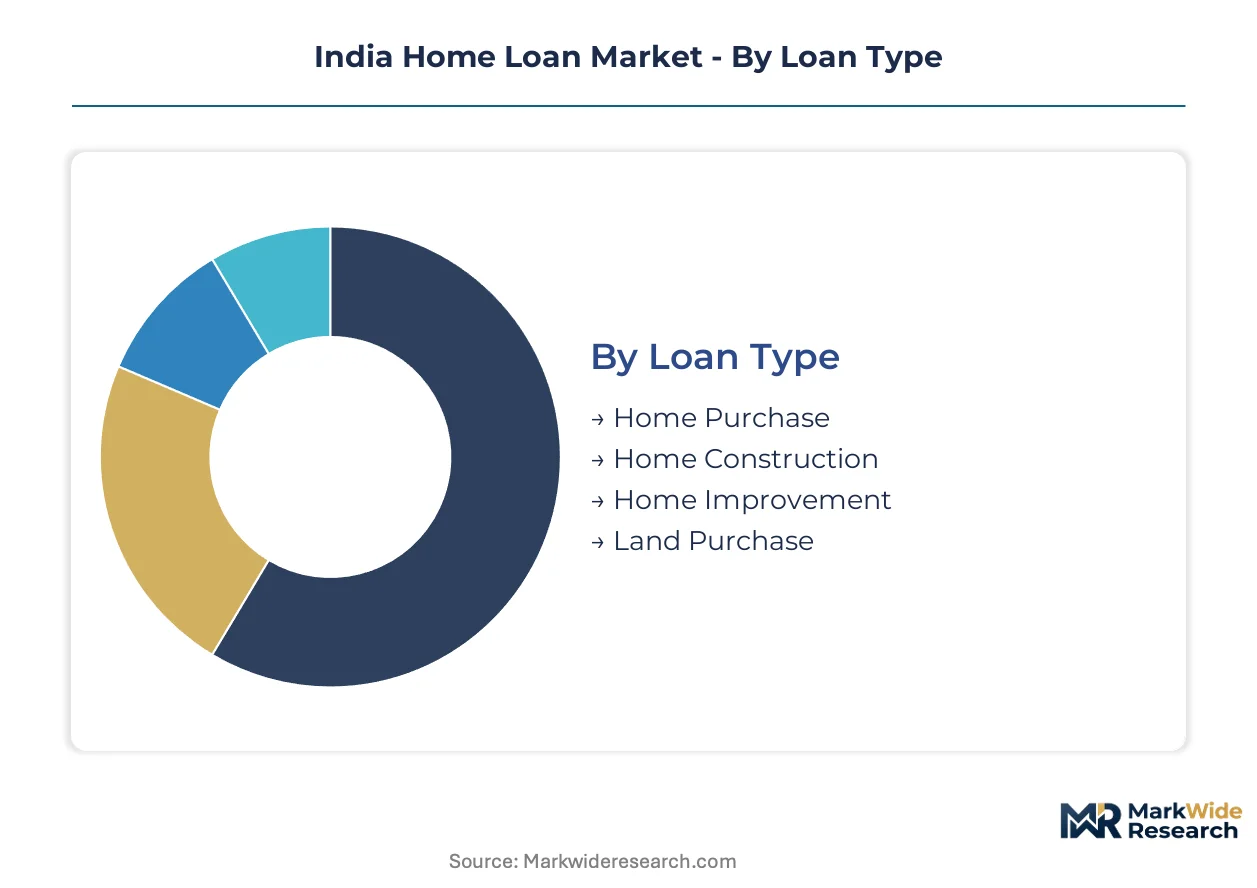
Home loan segmentation in India reflects the structural diversity of housing demand across income tiers, property types, and institutional channels. Lenders configure product architectures around collateral characteristics, borrower employment profiles, and balance sheet funding sources to optimize risk-adjusted returns.
Loan Type:
Collateral purpose and construction stage define the risk-return profile across loan type categories, with lenders applying differentiated loan-to-value ceilings and documentation requirements based on asset completion status.
- Home Purchase:Secured term credit collateralized by completed residential units, typically structured with tenures spanning 15 to 30 years. Demand concentrates in Maharashtra and Karnataka urban clusters where salaried IT professionals execute property transactions. RBI prudential norms cap loan-to-value ratios at 75-90% depending on property value, constraining leverage for premium segment acquisitions.
- Home Improvement:Shorter-tenure facilities financing renovation, extension, or structural upgrades to existing owner-occupied properties. Existing homeowners in Telangana and Tamil Nadu are deploying these instruments amid elevated replacement costs in metropolitan property markets. Documentation requirements emphasize title clarity rather than builder track record, compressing origination cycles relative to purchase loans.
- Home Construction:Disbursement-linked credit facilities releasing tranches against construction milestones verified by engineer certifications. Borrowers in tier-2 Gujarat and Rajasthan cities utilize these structures for self-built residential units on owned land parcels.
- Land Purchase:Higher-risk secured credit collateralized by undeveloped residential plots, subject to elevated risk weights and stricter income verification protocols. Demand localizes in peri-urban corridors surrounding Bangalore and Hyderabad where speculative land banking persists among investor cohorts.
Home Purchase leads on scale; Home Improvement leads on momentum.
Interest Rate Type:
Borrower preference for rate risk exposure and policy transmission efficiency shapes origination flows across interest rate structures, with regulatory mandates accelerating standardization.
- Floating Rate:Instruments linked to external benchmark-based lending rates that transmit RBI policy rate adjustments with quarterly reset frequencies. These dominate origination volumes across all lender categories, particularly among salaried borrowers in metropolitan markets who prioritize payment reduction during monetary easing cycles.
- Fixed Rate:Contracts locking initial rates for defined periods, typically 2-3 years, before converting to floating structures. Senior citizens in Kerala and Tamil Nadu favor these instruments for cash flow predictability in retirement planning.
- Hybrid Rate:Products combining initial fixed-rate periods with subsequent floating-rate mechanisms, balancing short-term payment certainty with long-term transmission benefits. Housing finance companies deploy these to differentiate from public sector bank offerings.
- Reverse Mortgage:Equity release instruments enabling senior citizens to monetize residential assets without sale or vacancy, with lump-sum or annuity disbursement options. Penetration remains concentrated in urban Maharashtra among property-rich, income-constrained retiree households.
Floating Rate commands volume dominance; Hybrid Rate is gaining share fastest among product innovation pipelines.
Customer Segment:
Employment documentation accessibility and credit bureau traceability determine underwriting economics across borrower categories, with lenders optimizing acquisition channel mix by segment.
- Salaried Individuals:Employees of organized sector enterprises with documented income streams verifiable through employer databases and tax withholding records. This segment concentrates in Bangalore, Hyderabad, and Pune IT corridors where digital income verification enables compressed turnaround times.
- First-time Buyers:Demographic entrants aged 28-35 accessing formal housing finance for initial property acquisition, frequently combining home purchase loans with Credit Linked Subsidy Scheme benefits. Demand accelerates in tier-2 Karnataka and Telangana cities where nuclear family formation drives independent housing demand.
- Non-Resident Indians:Overseas Indian nationals remitting foreign currency income to acquire residential properties in origin cities, subject to FEMA regulations and enhanced KYC documentation. Origination concentrates in Kerala, Punjab, and Gujarat districts with established diaspora networks.
- Senior Citizens:Retiree borrowers aged 60-plus with limited income documentation but substantial unencumbered property equity, accessing specialized products with extended tenures or co-applicant requirements. Public sector banks with rural branch networks capture this segment through relationship-based underwriting.
Salaried Individuals anchor origination volumes; First-time Buyers exhibit the steepest expansion trajectory amid demographic tailwinds.
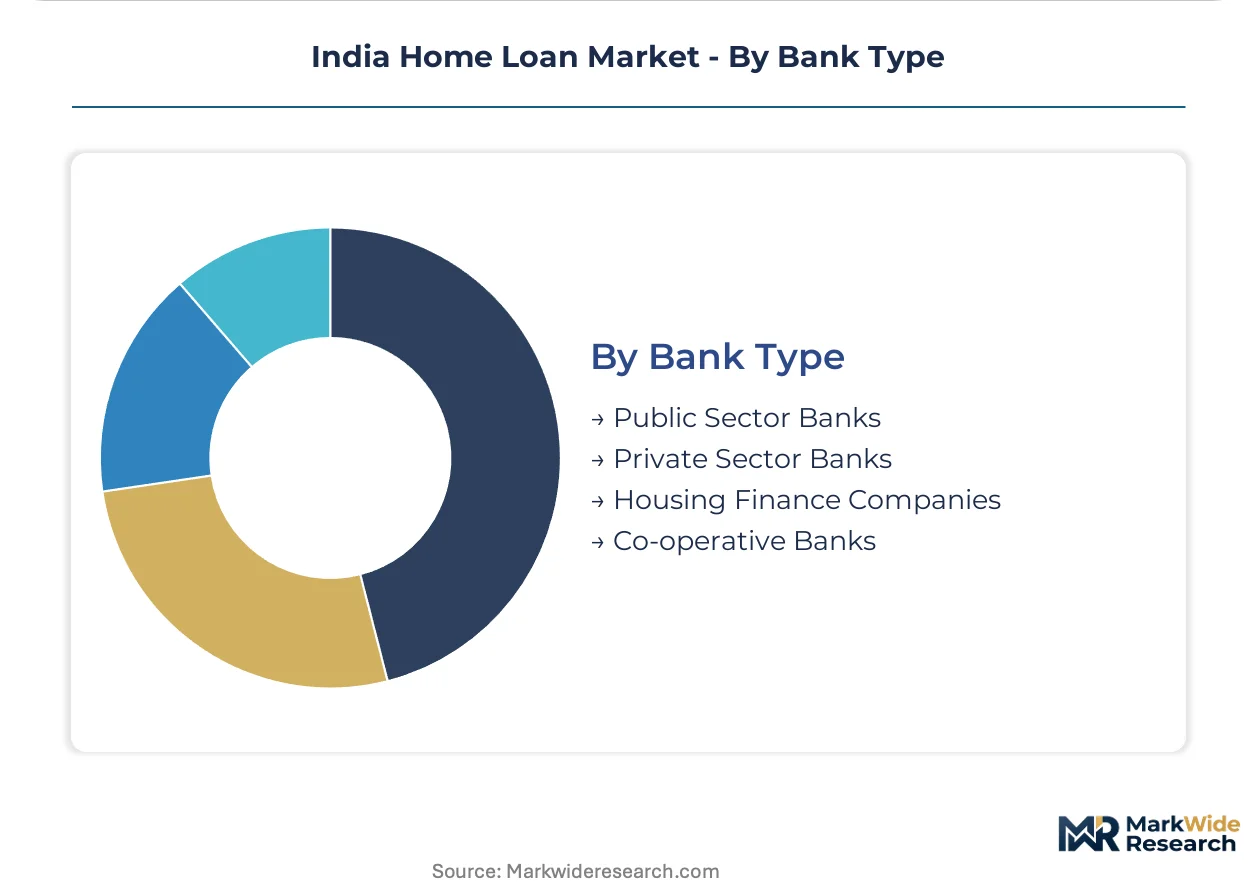
Bank Type:
Funding structure and regulatory jurisdiction create distinct competitive positioning across institutional categories, with capital adequacy requirements and deposit access shaping pricing power.
- Public Sector Banks:Government-owned institutions with extensive tier-2 and tier-3 branch networks, funding operations through retail deposit bases. State Bank of India and Punjab National Bank leverage rural penetration to capture agricultural income-backed housing demand.
- Private Sector Banks:Shareholder-owned institutions prioritizing digital origination infrastructure and metropolitan salaried segments. HDFC Bank and ICICI Bank deploy unified API platforms aggregating income verification and collateral assessment into single-workflow systems.
- Housing Finance Companies:Specialized non-bank lenders regulated by NHB, accessing wholesale funding markets and refinancing windows. These entities compete on flexible eligibility criteria for self-employed professionals in Gujarat and Rajasthan growth corridors.
- Co-operative Banks:Member-owned institutions with localized deposit bases and priority sector lending mandates, originating housing credit in semi-urban Maharashtra and Karnataka markets. Balance sheet constraints limit scale but enable relationship-based underwriting for informal income borrowers.
Public Sector Banks lead on geographic penetration; Private Sector Banks lead on margin capture and digital throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
IT employment clusters in Bangalore, Hyderabad, and Pune anchor housing finance demand, while government housing schemes penetrate tier-2 and tier-3 cities. Salaried professionals and first-time buyers concentrate in southern and western states where formal credit expansion accelerates.
Maharashtra
Mumbai and Pune metropolitan corridors generate concentrated demand from salaried IT and financial services professionals. The Pradhan Mantri Awas Yojana subsidizes first-time buyer acquisitions in Nagpur and Nashik satellite cities. Thane and Navi Mumbai sub-markets absorb spillover demand as Mumbai core prices escalate beyond affordability thresholds.
Karnataka
Bangalore's technology parks sustain origination pipelines for lenders with digital income verification platforms. The Credit Linked Subsidy Scheme expands penetration into Mysore and Mangalore tier-2 markets. Whitefield and Electronic City employment clusters concentrate floating-rate loan demand among 28-35 age cohorts.
Telangana
Hyderabad's pharmaceutical and IT corridors drive salaried borrower concentration comparable to Bangalore. RBI external benchmark-linked lending rate mandates accelerate lender switching behavior in this price-sensitive market. Cyberabad and Gachibowli sub-markets exhibit compressed turnaround time expectations from digitally native borrowers.
Tamil Nadu
Chennai's automotive and IT manufacturing base supports documented income pools attractive to risk-calibrated lenders. Coimbatore and Madurai tier-2 cities emerge as affordable housing finance growth corridors. The state's documented property registration systems reduce collateral valuation opacity relative to comparable markets.
Gujarat
Self-employed professional segments in Ahmedabad and Surat access housing finance through flexible eligibility criteria offered by non-bank lenders. Co-lending partnerships between housing finance companies and cooperative banks penetrate Rajkot and Vadodara semi-urban markets. GIFT City development generates niche demand from expatriate and high-net-worth segments.
India Home Loan Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across origination channels and borrower segments. Public sector banks leverage deposit-funded cost structures and rural branch density, while private sector banks capture margin pools through digital throughput and metropolitan concentration. Strategic archetypes include universal banks with housing divisions, specialized housing finance companies, and cooperative banks with localized relationship networks. Competitive moves center on co-lending partnerships with regional banks and API-based origination platform consolidation.
Among universal bank competitors, State Bank of India anchors the public sector tier through extensive tier-2 and tier-3 penetration, while HDFC Bank exemplifies digital-first positioning with unified income verification and collateral assessment workflows. Bajaj Housing Finance occupies a specialized non-bank position competing on flexible eligibility criteria for self-employed segments.
| Leading Market Players |
|---|
| ICICI Bank |
| Bajaj Housing Finance |
| State Bank of India |
| Tata Capital Housing Finance |
| PNB Housing Finance |
| HDFC Bank |
| Axis Bank |
| Kotak Mahindra Bank |
| LIC Housing Finance |
| Others |
Pricing and Supply Chain Analysis
RBI green housing certification mandates for energy-efficient residential construction gate both qualified builder supply and premium-tier pricing access for lenders with specialized appraisal capabilities. Borrowers in tier-2 Karnataka and Telangana markets face compressed loan-to-value ratios when projects lack Bureau of Indian Standards ratings, while certified developments command basis point concessions that reshape origination economics.
Pricing Analysis
Bundled processing-fee-plus-insurance products dominate against unbundled rate-only offerings across the housing finance ecosystem. Pricing stratifies across premium, standard, and economy tiers based on borrower credit bureau scores and property location grades. Cost compression in economy-tier originations is intensifying because public sector banks deploy deposit-funded rate advantages. First-time buyers in semi-urban Maharashtra exhibit highest price sensitivity; non-resident Indian borrowers in Kerala markets demonstrate lowest sensitivity due to foreign currency income buffers.
Supply Chain Analysis
Logistics and freight cost volatility in construction material distribution feeds into collateral valuation uncertainty across tier-2 and tier-3 origination markets. Cement and steel supply concentrates in India, China, and Vietnam, with finished residential inventory pipelines drawing from these inputs. Single-source vulnerability in satellite imagery verification services creates appraisal bottlenecks for lenders expanding into semi-urban Gujarat and Rajasthan corridors. Distribution runs through direct sales force networks anchored by public sector bank branches and housing finance company dealer tie-ups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India home loan market functions as a stable compounder where demographic tailwinds from nuclear family formation in tier-2 cities generate sustained origination velocity regardless of cyclical rate fluctuations.
For Market Incumbents: To counter digital-native fintech entrants compressing turnaround times, public sector banks should accelerate API integration with land registry databases for automated title verification. Private sector lenders must deepen vertical integration into property technology partnerships that reduce fraud risk in semi-urban origination. For New Entrants and Emerging Players: Satellite imagery-based collateral assessment technology offers a technology-first wedge into tier-2 Gujarat and Rajasthan markets where incumbent appraisal capabilities remain underdeveloped. Target self-employed professional segments in Ahmedabad and Surat through flexible income documentation products. Deploy co-lending partnerships with cooperative banks as capital-light distribution architecture. For Investors and Strategic Acquirers: Roll-up economics work for regional housing finance company consolidation because RBI risk weight escalation is constraining standalone capital adequacy and forcing balance sheet light models. Target specialized non-bank lenders with established tier-2 penetration and NHB refinancing relationships. Watch RBI stance on personal loan risk weights as the inflection signal for sector-wide capacity expansion or contraction.| Strategic Initiative | Industry Significance |
|---|---|
| Co-Lending Partnership Expansion | Priority sector lending tie-ups with cooperative banks in semi-urban Maharashtra reduce capital intensity for housing finance companies. |
| Digital Origination Platform Consolidation | Unified API architectures aggregating income verification and collateral assessment compress procurement cycles for private sector banks. |
| Green Housing Certification Integration | Bureau of Indian Standards energy efficiency ratings enable differentiated pricing windows for lenders with specialized appraisal capabilities. |
| Alternative Data Underwriting Investment | Machine learning models parsing utility payments and rental history expand addressable market for self-employed borrower segments. |
| Rural Branch Network Optimization | Deposit-funded cost structures in tier-3 locations translate into competitive pricing for agricultural income-backed housing loans. |
Research Methodology
Multiple input streams — primary interviews with housing finance executives, regulatory affairs specialists at NHB, and digital product heads at tier-1 banks — were reconciled against secondary validation from RBI circulars, NHB annual reports, and SEBI mortgage-backed securities disclosures. Conversations with branch operations managers at public sector banks and underwriting leads at housing finance companies informed origination economics. Trade data on cement and steel pricing, property registration statistics from state revenue departments, and credit bureau disbursement trends supplied volume anchors. Bottom-up loan book analysis and top-down macroeconomic projections were triangulated for consistency.
Data-stream reconciliation across the modeling period applied segment-specific growth coefficients to loan type, interest rate structure, customer archetype, and institutional channel dimensions. CAGRs were derived from trend extrapolation adjusted for regulatory intervention points including RBI risk weight revisions and external benchmark mandate implementation. Forecast inputs incorporated urbanization velocity in tier-2 corridors, IT employment cluster expansion in southern states, and Credit Linked Subsidy Scheme penetration rates.
The model holds under stable monetary policy transmission and continued urbanization; deviation in RBI risk weight stance or prolonged property price stagnation would shift origination volume trajectories. Stakeholders should weight assumptions against their own operating context and regional exposure concentrations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Canada Mortgage/Loan Brokers Market
Loans and Leasing
Brazil Home Loan Market
Loans and Leasing
Used Car Financing Market
Loans and Leasing
Automotive Finance Market
Loans and Leasing
United States Material Handling Leasing and Financing Market
Loans and Leasing
Global Commercial Loan Software Market
Loans and Leasing
Renting and Leasing Test and Measurement Equipment Market
Loans and Leasing
Home Equity Lending Market
Loans and Leasing
China Auto Loan Market
Loans and Leasing
Global Revenue-Based Financing Market
Loans and Leasing
China Mortgage/Loan Brokers Market
Loans and Leasing
Digital Lending Market
Loans and Leasing
Japan Car Loan Market
Loans and Leasing
Europe Used Car Financing Market
Loans and Leasing
South Korea Car Loan Market
Loans and Leasing
United States Car Loan Market