
 Europe Auto Loan Market | 2026-2036
Europe Auto Loan Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Auto Loan Market Insights
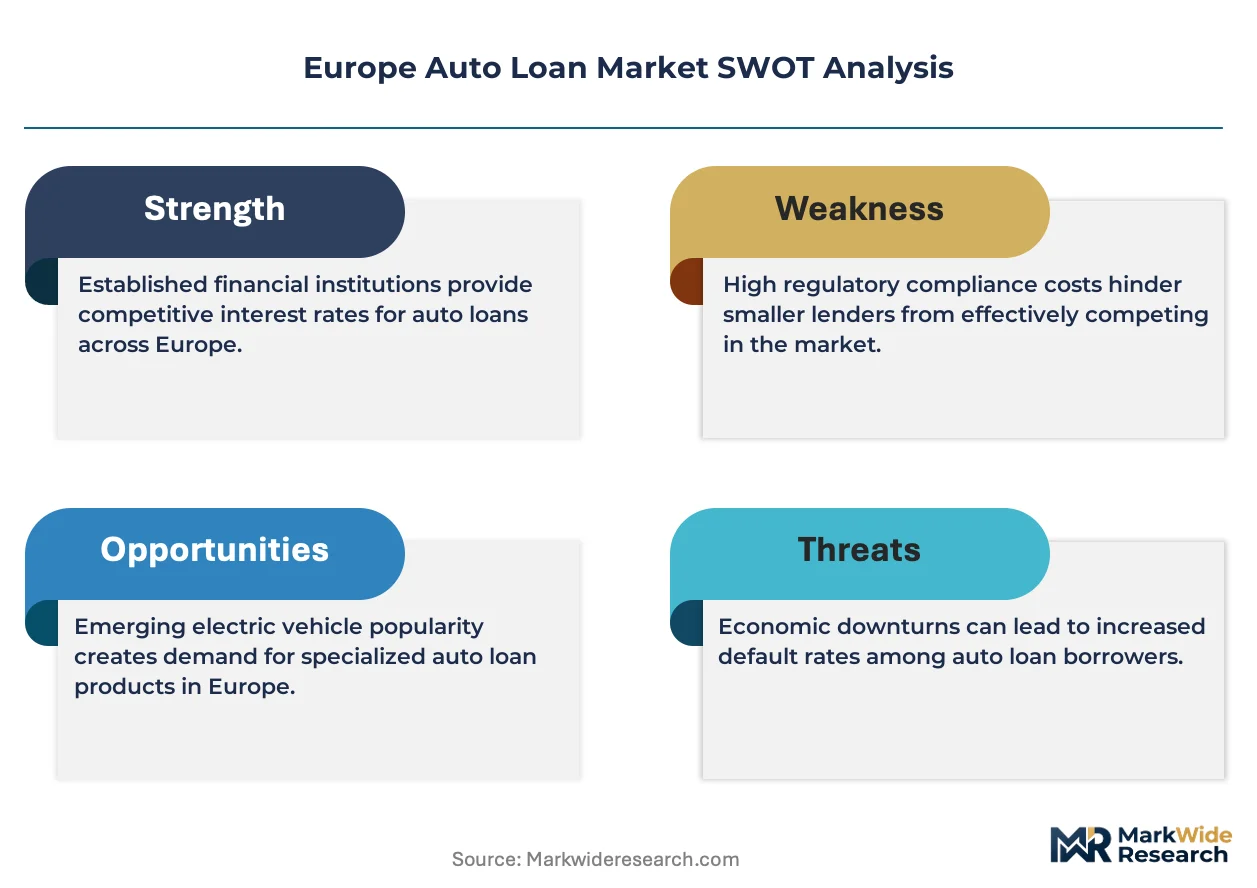
CE marking for digital lending platforms is collapsing the barrier between traditional banks and fintech originators across European auto finance. Santander Consumer Finance leverages its pan-European branch network to sustain volume leadership in Southern Europe. Volkswagen Financial Services anchors captive financing dominance through direct integration with OEM distribution channels. BNP Paribas Personal Finance competes aggressively on unsecured used-vehicle products where manufacturer-affiliated lenders hold weaker positions.
An auto loan is a secured or unsecured credit instrument collateralized by a vehicle title, structured with fixed or variable interest schedules over 24-to-84-month tenors, designed to transfer automotive asset ownership while distributing capital recovery across the usable life of the underlying vehicle. Its commercial purpose centers on bridging the liquidity gap between consumer purchasing power and manufacturer production economics. Secured loan products dominate portfolio composition where balloon payment structures concentrate margin pools in residual value underwriting. First-time buyer segments represent the fastest-growing customer category as entry-level electrification expands addressable cohorts. Fixed-rate instruments anchor European consumer preference amid ECB policy volatility.
ECB interest rate policy and the EU Consumer Credit Directive shape origination economics and disclosure standards across all twenty-seven member states. EBA stress testing requirements govern capital reserve treatment for auto loan portfolios held by European banks. ESMA's sustainable finance taxonomy is beginning to classify green vehicle financing for preferential regulatory treatment. Stakeholders must monitor how the EU AI Act's credit-scoring provisions will restructure automated underwriting workflows before implementation deadlines crystallize.
Market Dynamics
ECB interest rate volatility is fragmenting borrower preference across fixed and variable rate structures, forcing lenders to reprice residual value risk in electrified vehicle portfolios.
Growth Catalysts
- EU Green Deal vehicle emissions standards:Mandatory fleet CO2 reduction targets are redirecting origination capacity toward battery electric vehicle loan products across all twenty-seven member states.
- Logistics operator electrification:Commercial fleet procurement programs in Germany and the Netherlands are expanding addressable financing volume for heavy-duty electric vehicles.
- CE marking for digital lending platforms:Harmonized fintech authorization standards are collapsing barriers between traditional bank branches and algorithmic originators.
Market Restraints
- Residual value uncertainty:Rapid battery technology depreciation curves are compressing collateral coverage ratios for used electric vehicle portfolios.
- Capital reserve requirements:EBA stress testing mandates are elevating risk-weighted asset treatment for auto loan books held by European depositary institutions.
- Interbank funding cost volatility:ECB policy rate transmission lags are squeezing net interest margins on fixed-rate consumer products.
Strategic Opportunities
- ESMA sustainable finance taxonomy:Green vehicle financing classification is unlocking preferential regulatory capital treatment for qualifying loan originations.
- Used vehicle unsecured lending:Manufacturer-affiliated captives hold weaker positions in this segment, creating white space for independent personal finance specialists.
- Subscription-to-ownership conversion:Fleet management operators are building captive finance arms to convert short-term mobility subscriptions into long-dated loan structures.
Industry Challenges
- EU AI Act credit-scoring provisions:Automated underwriting workflow redesign must complete before implementation deadlines crystallize, requiring substantial compliance technology investment.
- Legacy core banking integration:Real-time loan decisioning engines require API-layer reconstruction atop decades-old batch-processing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Auto Loan Market |
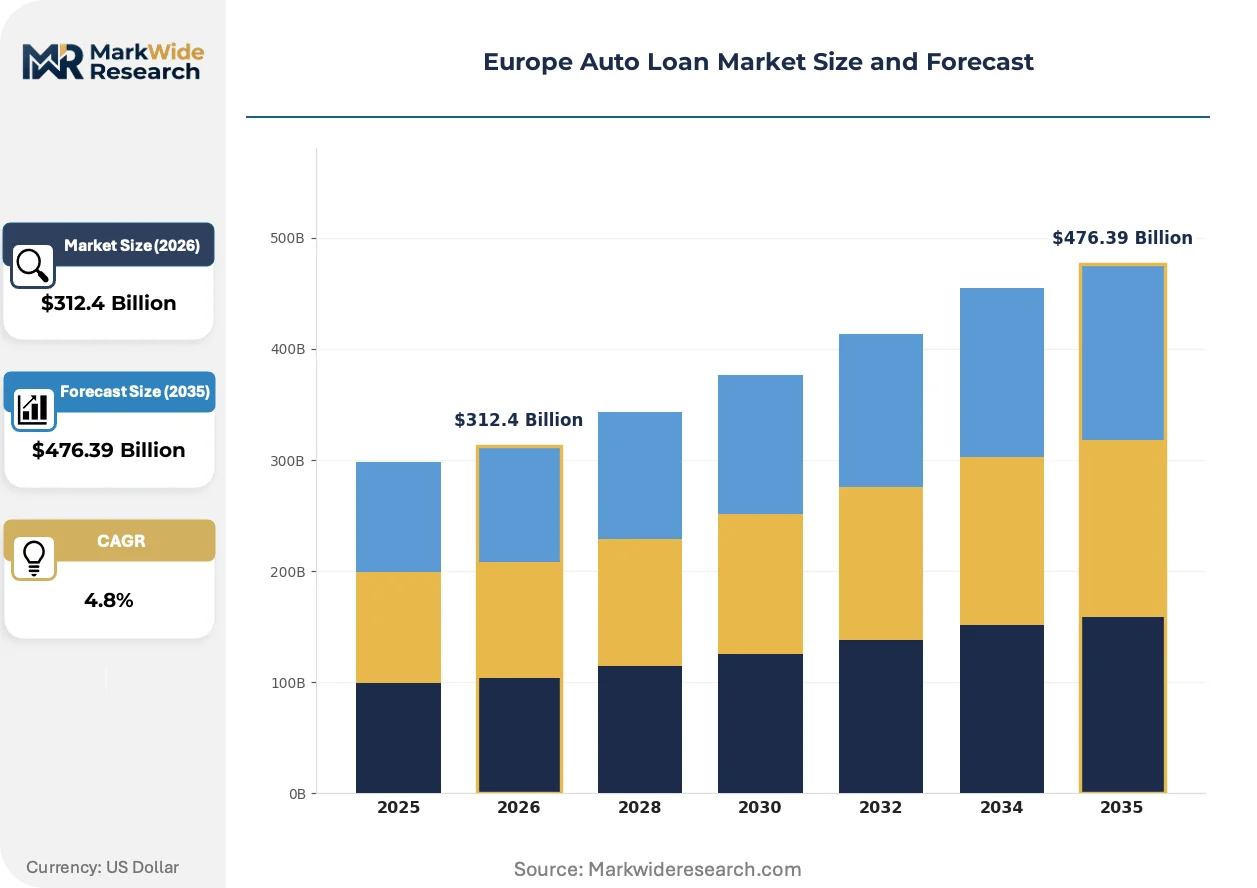
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $476.39 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: Secured, Unsecured, Short-Term, Long-Term Customer Segment: First-Time Buyers, Fleet Customers, Pre-Owned Buyers, Luxury Vehicle Buyers Repayment Model: Installment, Balloon Payment, Lease Purchase, Deferred Interest Rate Type: Fixed Rate, Variable Rate, Hybrid Rate, Promotional Rate |
| Companies Covered | Santander Consumer Finance, Volkswagen Financial Services, Stellantis Financial Services, BNP Paribas Personal Finance, Mercedes-Benz Financial Services, RCI Banque, Ford Credit Europe, Toyota Financial Services, Crédit Agricole Consumer Finance, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Auto Loan Market Trends and Innovations
Digital origination infrastructure is fragmenting the traditional branch-based distribution model, while regulatory classification schemes are reordering capital allocation toward electrified asset classes.
Embedded finance APIs are decomposing the traditional auto loan application journey into micro-interactions distributed across OEM websites, dealership management systems, and mobility apps. German automotive groups are deploying these interfaces to capture financing decisions at the point of vehicle configuration. The technology is decomposing the historical separation between vehicle selection and credit origination into a single seamless transaction.
EU AI Act provisions governing automated credit decisions are mandating explainability overlays atop machine learning underwriting models. Lenders must now document algorithmic decision pathways for regulatory examination. Southern European markets with higher manual underwriting penetration are experiencing steeper compliance cost escalation than Nordic markets with established digital infrastructure.
First-time buyer segments are rotating toward entry-level electric vehicle financing as manufacturer pricing strategies compress acquisition thresholds. Direct-to-consumer digital channels are displacing dealership-arranged credit intermediation for this cohort. France and Italy exhibit the most pronounced channel shift, where fintech originators have secured CE marking authorization ahead of incumbent branch networks.
Europe Auto Loan Market Segmentation
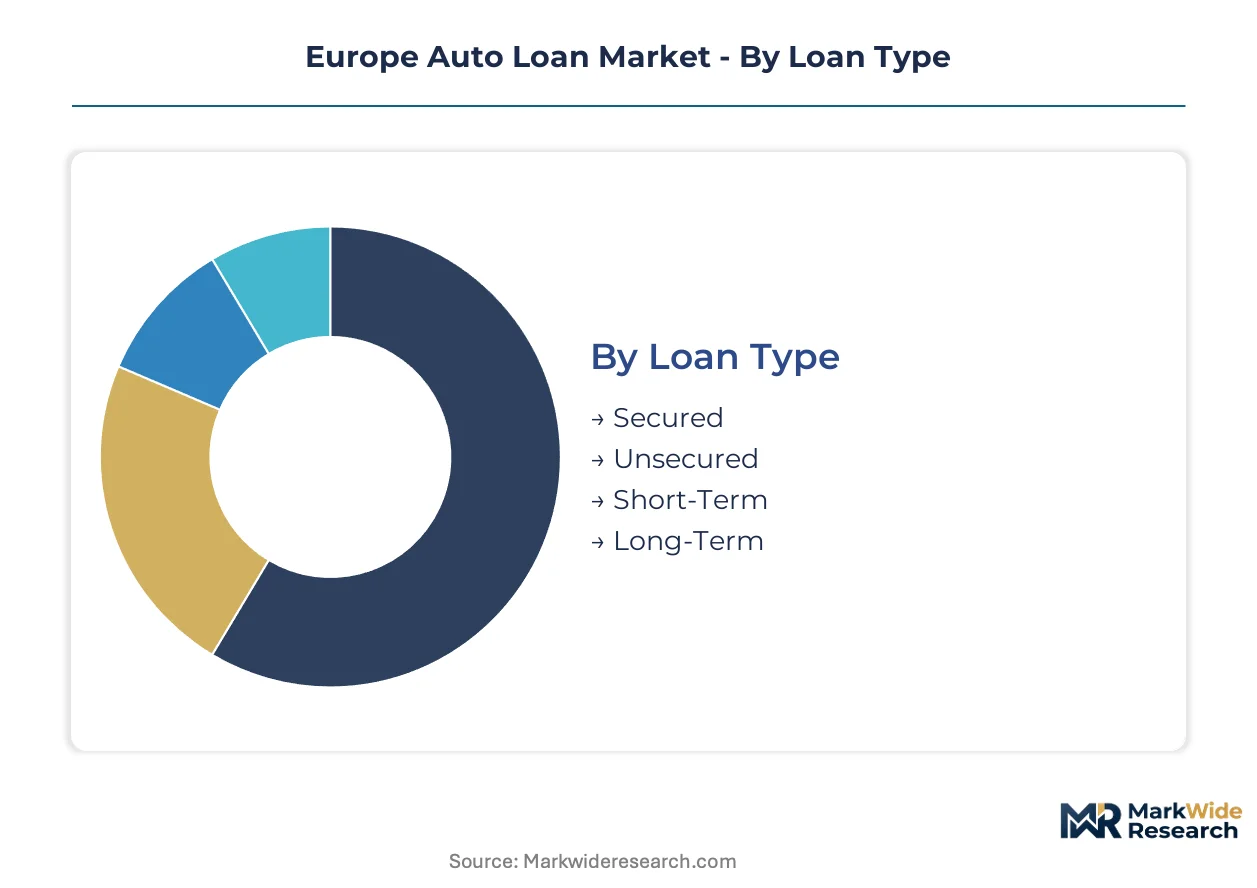
Segmentation in European auto finance determines capital allocation, pricing power, and channel strategy across divergent risk profiles. Loan structure and customer type combinations dictate whether originators compete through branch networks, digital platforms, or captive OEM integration.
Loan Type:
Channel distribution varies sharply across collateralization structures, with secured products flowing through dealer-arranged financing while unsecured loans concentrate in direct-to-consumer digital channels.
- Secured:Vehicle title collateralization structures dominate German and French originations, where balloon payment residuals concentrate margin pools in captive finance arms. Volkswagen Financial Services and BNP Paribas Personal Finance compete intensely for this collateralized volume across Southern Europe.
- Unsecured:Personal loan products without asset attachment command premium pricing in used-vehicle segments where manufacturer-affiliated lenders maintain weaker positions. Independent specialists exploit this white space through algorithmic credit scoring and rapid digital disbursement.
- Short-Term:Tenors under 36 months serve fleet replacement cycles and subscription-to-ownership conversion programs.
- Long-Term:Extended amortization beyond 72 months supports battery electric vehicle affordability in Netherlands and Norway markets.
Secured instruments dominate installed base across all twenty-seven member states. Unsecured products are where expansion concentrates as fintech originators gain CE marking authorization.
Customer Segment:
Acquisition economics and lifetime value calculations diverge substantially across buyer maturity levels, with first-time entrants requiring higher servicing investment than established fleet relationships.
- First-Time Buyers:Entry-level electrification is compressing acquisition thresholds for this cohort, with direct-to-consumer channels displacing dealership intermediation in France and Italy. Digital-native originators capture this segment through embedded finance APIs at vehicle configuration points.
- Fleet Customers:Logistics operators in Germany and the Netherlands are expanding heavy-duty electric vehicle procurement programs, creating concentrated financing demand with standardized underwriting and bulk pricing structures.
- Pre-Owned Buyers:Used vehicle price transparency platforms are shortening decision cycles in this price-sensitive segment.
- Luxury Vehicle Buyers:Manufacturer captive arms retain near-monopoly positions through exclusive access to limited-production allocation systems.
Fleet customers anchor portfolio yield stability. First-time buyers are climbing the fastest as electrification expands addressable cohorts.
Repayment Model:
Structural payment engineering determines residual value risk allocation between originator and borrower, with balloon structures concentrating exposure in lender balance sheets.
- Installment:Equal periodic payments across fixed tenors align with ECB policy volatility and European consumer preference for predictable obligations. This structure dominates retail originations where fixed-rate instruments anchor product design.
- Balloon Payment:Terminal residual obligations concentrate margin pools in residual value underwriting expertise, with German automotive groups deploying captive arms to manage electrified vehicle depreciation curves. Rapid battery technology evolution compresses collateral coverage ratios for this structure.
- Lease Purchase:Title transfer upon final payment structures serve commercial fleet operators seeking ownership conversion pathways.
- Deferred:Payment holidays and graduated schedules support seasonal income patterns in Southern European agricultural and tourism-dependent regions.
Installment structures command the majority of outstanding volume. Balloon payment products are gaining share fastest as electrification demands sophisticated residual management.
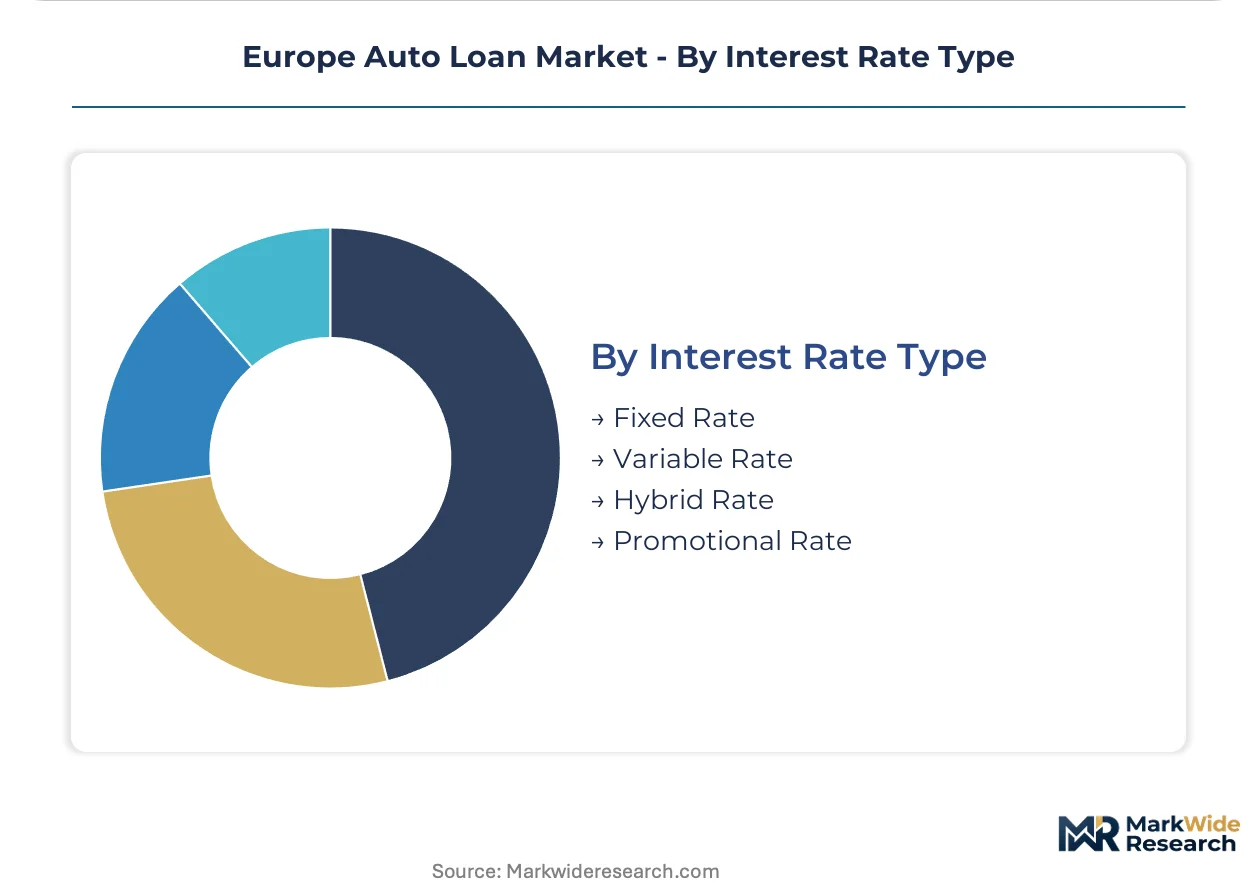
Interest Rate Type:
ECB policy transmission lags and borrower risk aversion are fragmenting preference across rate structure categories, forcing repricing discipline on originators.
- Fixed Rate:Locked obligations throughout the loan tenor dominate European consumer preference amid monetary policy volatility, with Santander Consumer Finance and Volkswagen Financial Services competing on rate lock guarantees across pan-European distribution networks.
- Variable Rate:ECB reference rate linkage concentrates in commercial fleet products where sophisticated treasury functions manage interest exposure through hedging instruments.
- Hybrid Rate:Fixed-to-float conversion features attract transitional borrowers in markets with steep yield curve inversion.
- Promotional Rate:Subsidized manufacturer incentives support new vehicle volume objectives with below-market carrying costs.
Fixed rate instruments dominate outstanding portfolio composition. Hybrid rate products are expanding most quickly as originators seek to bridge borrower preference fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine corridor's freight rail density underwrites Germany's dominance in European automotive logistics and captive finance concentration. This infrastructure backbone connects manufacturing clusters across the continent's most penetrated consumer credit market.
Germany
Automotive manufacturing density and captive finance integration drive origination volume, with Volkswagen Financial Services and Mercedes-Benz Financial Services anchoring portfolio concentration. The KBA enforces type-approval standards that cascade into residual value underwriting for electrified vehicle fleets. Bavaria's Munich-Stuttgart manufacturing corridor hosts the densest captive finance origination infrastructure in Europe.
France
BNP Paribas Personal Finance and Crédit Agricole Consumer Finance compete aggressively on unsecured used-vehicle products where manufacturer captives hold weaker positions. ANSM and CNIL oversight intersect with EU AI Act implementation timelines for automated credit-scoring compliance. The Paris-Île-de-France financial cluster concentrates algorithmic underwriting talent and regulatory technology investment.
Netherlands
Logistics operator electrification programs expand heavy-duty electric vehicle financing demand with standardized fleet underwriting structures. The Dutch central bank implements ECB stress testing requirements for auto loan portfolios held by depositary institutions. Rotterdam's port logistics ecosystem generates concentrated commercial fleet replacement financing cycles.
Italy
First-time buyer segments rotate toward entry-level electric vehicle financing as direct-to-consumer channels displace dealership intermediation. CE marking authorization for digital lending platforms has enabled fintech originators to secure market position ahead of incumbent branch networks. Turin-Milan industrial corridor maintains automotive manufacturing heritage while Southern regions exhibit steeper manual-to-digital underwriting transition costs.
Spain
Santander Consumer Finance leverages its pan-European branch network to sustain volume leadership in secured auto loan origination across Iberian markets. The Bank of Spain enforces EBA capital reserve requirements that elevate risk-weighted asset treatment for fixed-rate consumer products. Barcelona-Madrid urban corridor concentrates electric vehicle adoption financing for subscription-to-ownership conversion programs.
Europe Auto Loan Market Competitive Landscape
Listed leaders compete with private specialists across regulatory capital treatment and digital origination infrastructure. The market structure consolidates around three tiers: pan-European universal bank captives, OEM-affiliated finance arms with direct distribution integration, and algorithmic fintech originators with CE marking authorization. Strategic archetypes include residual value underwriters, unsecured personal finance specialists, and embedded finance API providers. Competitive moves center on M&A for digital origination capabilities and strategic partnerships for fleet management integration.
Within the captive finance tier, Volkswagen Financial Services and Mercedes-Benz Financial Services exemplify OEM-affiliated structures with direct distribution channel control. BNP Paribas Personal Finance occupies a position among independent personal finance specialists competing on unsecured used-vehicle products. These three anchors represent divergent strategic positions: manufacturing-captive integration versus algorithmic credit scoring versus universal bank branch network leverage.
| Leading Market Players |
|---|
| Santander Consumer Finance |
| Volkswagen Financial Services |
| Stellantis Financial Services |
| BNP Paribas Personal Finance |
| Mercedes-Benz Financial Services |
| RCI Banque |
| Ford Credit Europe |
| Toyota Financial Services |
| Crédit Agricole Consumer Finance |
| Others |
Pricing and Supply Chain Analysis
CE marking for digital lending platforms gates both supply qualification and price differentiation simultaneously, as fintech originators without authorization face exclusion from embedded finance distribution channels while certified platforms command rate premiums through algorithmic underwriting efficiency.
Pricing Analysis
Certification level (CE marking authorization) creates the primary spread between algorithmic originators and traditional branch-based lenders. Pricing stratifies across fully-digital, hybrid, and branch-dependent tiers based on origination cost structure and speed-to-decision. Pricing pressure stems from ECB rate transmission squeezing net interest margins on fixed-rate products. Fleet customers exhibit lowest price sensitivity due to standardized bulk underwriting, while first-time buyers in Southern Europe show highest sensitivity to rate differentials.
Supply Chain Analysis
Rotterdam port congestion and container availability fluctuations on Asia-Europe trade lanes elevate inbound logistics costs for physical vehicle collateral movement. Vehicle supply concentrates in Germany, Czech Republic, and Spain manufacturing clusters. Raw material dependencies include lithium battery cells, semiconductor components, and specialized steel alloys. Single-source vulnerability in battery cell supply from Asian producers threatens collateral availability timelines. Distribution runs through captive OEM finance arms, independent dealer networks, and direct-to-consumer digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Channel fragmentation across the Europe Auto Loan Market creates multiple entry points, as electrification expands first-time buyer cohorts faster than incumbent branch networks can capture them.
For Market Incumbents: Fortify residual value underwriting capabilities through captive integration with battery lifecycle data providers, as rapid technology depreciation threatens balloon payment structures. Deepen API-layer investment to defend against CE-marked fintechs displacing dealership-arranged financing in France and Italy. Prioritize ESMA green taxonomy qualification for preferential capital treatment on electrified portfolios. For New Entrants and Emerging Players: CE marking fast-track authorization unlocks embedded finance integration at German OEM vehicle configuration points, the most penetrable white space for algorithmic originators. Target unsecured used-vehicle lending in Southern Europe where manufacturer captives hold weaker positions. Deploy subscription-to-ownership conversion programs targeting Barcelona-Madrid urban mobility subscribers. For Investors and Strategic Acquirers: EU AI Act implementation deadlines reshape the acquisition landscape toward compliance-technology-enabled originators with explainable underwriting infrastructure. Five-to-ten-year viability favors algorithmic platforms with CE marking and residual value data partnerships over branch-dependent legacy models. Monitor EBA stress testing requirement evolution as the signal for risk-weighted asset treatment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Fast-Track Authorization | Unlocks embedded finance API distribution at German OEM configuration points ahead of incumbent branch networks. |
| Residual Value Data Partnership | Captive integration with battery lifecycle analytics secures balloon payment product viability amid technology depreciation. |
| ESMA Green Taxonomy Qualification | Preferential regulatory capital treatment reduces risk-weighted asset requirements for electrified vehicle originations. |
| Subscription-to-Ownership Conversion | Fleet management captive arms capture long-dated loan structures from short-term mobility subscribers in urban corridors. |
| Explainable AI Compliance Investment | EU AI Act-mandated algorithmic documentation satisfies regulatory examination requirements for automated underwriting workflows. |
Research Methodology
Operator-level perspectives from captive finance executives, digital lending platform CTOs, dealership operations managers, and fleet procurement officers anchored the qualitative base. Secondary validation drew from ECB statistical data releases, EBA stress testing disclosures, ESMA sustainable finance taxonomy documentation, and EU Consumer Credit Directive implementation reports. Bottom-up loan origination volume estimates triangulated against top-down European vehicle registration data.
Sensitivity analysis across interest rate trajectory scenarios and electrification adoption curves informed the analytical framework. Segmentation dimensions modeled include loan collateralization structure, customer maturity tier, repayment engineering, and interest rate fixation period. CAGRs derived from regression analysis against vehicle production forecasts and consumer credit penetration indices. Battery technology depreciation curves and ECB policy rate assumptions served as primary forecast inputs.
Underlying assumptions cover sustained EU Green Deal emissions standard enforcement and CE marking authorization timelines, with deviation risk concentrated in residual value volatility for electrified collateral and EBA capital requirement recalibration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Global Automotive Fleet Leasing Market
Loans and Leasing
Australia Automotive Financing Market
Loans and Leasing
Home Equity Lending Market
Loans and Leasing
Payday Loans Market
Loans and Leasing
Alternative Financing Market
Loans and Leasing
Europe Motorcycle Loan Market
Loans and Leasing
Europe Mortgage / Loan Broker Market
Loans and Leasing
Construction Equipment Finance Market
Loans and Leasing
Solar Lease Service Market
Loans and Leasing
Commercial Lending Market
Loans and Leasing
Working Capital Loan Market
Loans and Leasing
Russia Auto Loan Market
Loans and Leasing
UK Home Equity Lending Market
Loans and Leasing
US Home Equity Lending Market
Loans and Leasing
Global Commercial Loan Software Market
Loans and Leasing
Car Finance Market