
 United States Contract Packaging Market | 2026-2036
United States Contract Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
United States Contract Packaging Market Analytics
Outsourced pharmaceutical packaging is consolidating as branded drug makers shed captive facilities to preserve capital for R&D. Sonoco Products Company leverages its thermoforming and sterile barrier expertise to anchor high-value medical device contracts. WestRock Company sustains dominant positions in paperboard-based rigid packaging through integrated fiber sourcing and converting assets. Pharma Tech Industries specializes in potent compound handling, differentiating its offering for cytotoxic and hormonal drug formats.
Contract packaging encompasses third-party execution of primary and secondary packaging operations, including filling, sealing, labeling, and serialization, performed under client specifications or co-developed protocols. The practice eliminates capital expenditure on packaging lines while ensuring compliance with child-resistant closures, tamper-evidence, and track-and-trace requirements. Flexible packaging leads volume in food and beverage applications where pouch and film formats reduce material cost and shipping weight. Blister packs represent the fastest-expanding pharmaceutical segment as unit-dose compliance packaging gains preference for chronic disease therapies. Quality control services command premium margins due to FDA validation requirements and batch release documentation burdens.
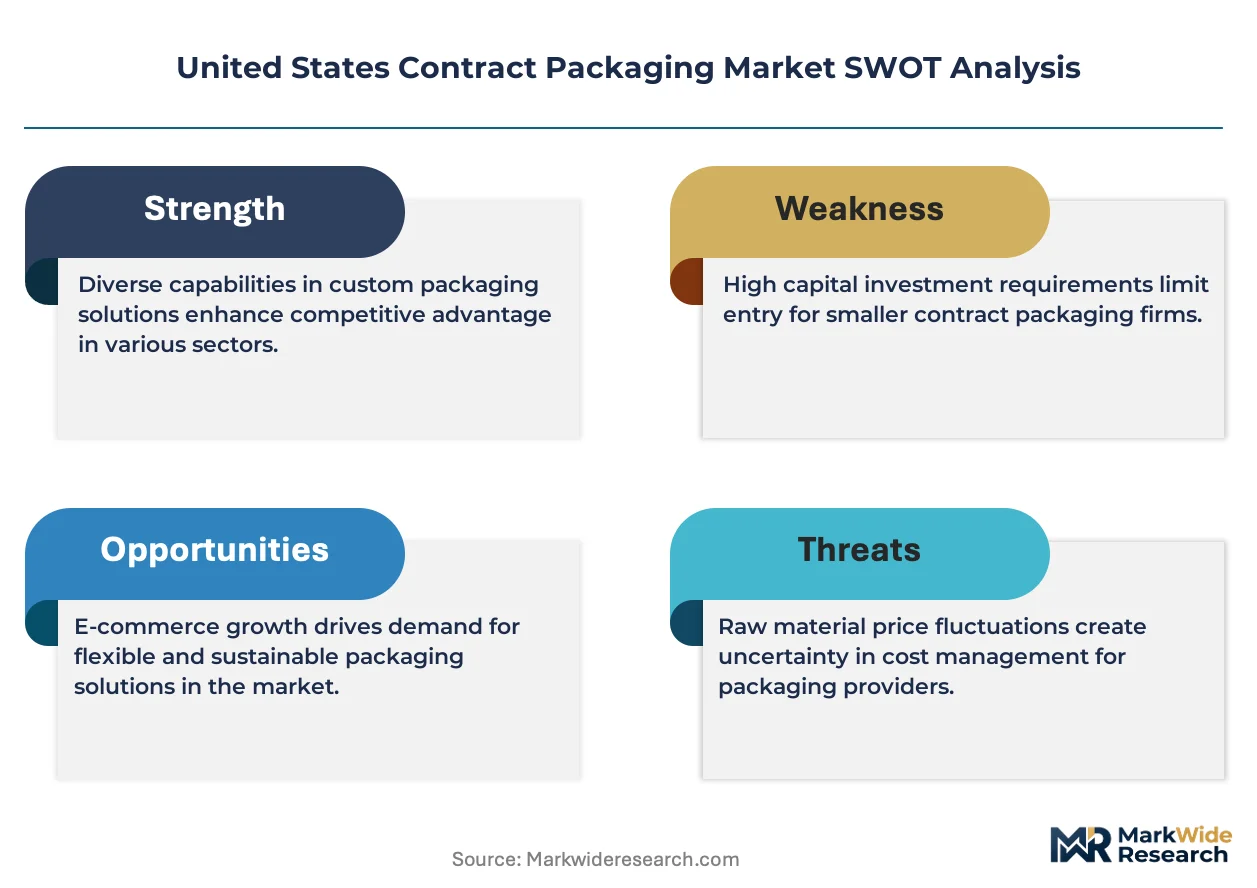
FDA cGMP regulations and the Drug Supply Chain Security Act mandate unit-level traceability, compelling contract packagers to invest in serialization infrastructure and validated software systems. EPA hazardous waste rules and OSHA worker exposure limits govern chemical handling protocols in facilities processing solvents, adhesives, and sterilants. State-level extended producer responsibility frameworks in California and New York pressure packagers to document recycled content and design for recyclability. Stakeholders must weigh facility consolidation against regional regulatory specialization when allocating capital across the US footprint.
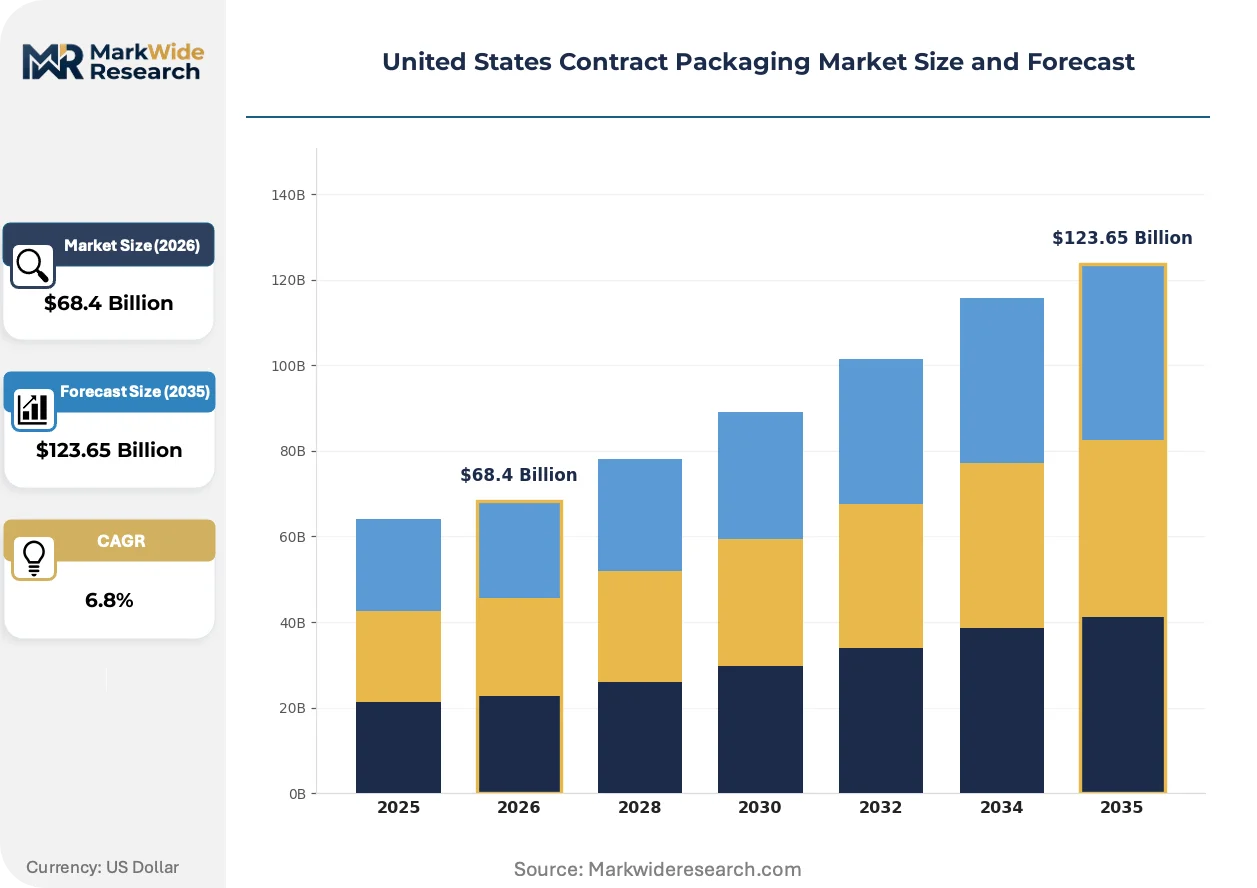
Market Dynamics
Pharmaceutical serialization mandates and EPA hazardous waste protocols are compressing margins while forcing contract packagers to consolidate facility footprints and upgrade validated software infrastructure.
Growth Catalysts
- FDA Drug Supply Chain Security Act:Unit-level traceability requirements compel pharmaceutical manufacturers to outsource serialization-capable packaging operations to specialized contract providers.
- Biologics manufacturing expansion:Cell and gene therapy producers in Massachusetts and North Carolina require sterile barrier packaging expertise that captive facilities cannot economically maintain.
- Midwest manufacturing corridor concentration:Proximity to Chicago and Indianapolis pharmaceutical hubs reduces logistics costs and enables just-in-time packaging workflows for oral solid dose products.
Market Restraints
- Resin price volatility:Polypropylene and polyethylene input cost swings compress margins on food-grade flexible packaging contracts with limited pass-through clauses.
- Equipment supplier oligopoly:European machinery vendors dominate high-speed blister packaging lines, creating lead time bottlenecks for US facility expansions.
- Extended producer responsibility laws:California and New York recycling content mandates force packagers to absorb design-for-recyclability costs without commensurate pricing power.
Strategic Opportunities
- Cell and gene therapy cold chain packaging:Cryogenic label adhesion and ultra-low temperature secondary packaging services command premium pricing from Boston and San Francisco biotech clusters.
- US-Mexico nearshoring:Medical device manufacturers relocating assembly from Asia create demand for US-based sterile packaging validation and final kitting operations.
- IRA domestic content incentives:Pharmaceutical packaging for Medicare-negotiated drugs qualifies for tax credits when executed in qualified US contract facilities.
Industry Challenges
- Serialized data management talent:FDA-validated track-and-trace software administration requires scarce IT professionals with pharmaceutical compliance experience.
- Legacy line integration:Brownfield facilities struggle to retrofit mechanical packaging equipment with vision inspection and aggregation stations without production downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Contract Packaging Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics Packaging Type: Flexible Packaging, Rigid Packaging, Labels, Blister Packs End User: Food Manufacturers, Cosmetic Brands, Pharmaceutical Companies, Electronics Producers Service Type: Filling Services, Labeling Services, Quality Control, Storage Solutions |
| Companies Covered | Multipack Solutions LLC, Sonoco Products Company, Aaron Thomas Company, Jones Healthcare Group Inc., WestRock Company, Sharp Packaging Services, Pharma Tech Industries, Pacmoore Products Inc, Reed-Lane Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Contract Packaging Market Evolving Landscape
Automation and sustainable material science are compressing cycle times while regulatory pressure on traceability and recyclability forces simultaneous investment across incompatible capability stacks.
Near-infrared spectroscopy for inline quality verification is electrifying pharmaceutical contract packaging lines by enabling real-time moisture and chemical composition checks without destructive sampling. Mid-sized generics manufacturers in New Jersey and Pennsylvania are adopting these systems to reduce batch release timelines from weeks to days. The technology is electrifying competitive positioning by allowing contract packagers to guarantee zero-defect shipments and capture multi-year agreements with risk-averse branded drug makers.
EPA hazardous waste generator status rules are tightening manifest documentation for facilities handling solvent-based adhesives and sterilants. Contract packagers in Ohio and Illinois must now deploy electronic waste tracking systems and secondary containment infrastructure that add fixed cost per square foot. Food-contact packaging operations face parallel pressure from state-level PFAS restrictions in Maine and Washington, forcing material substitutions that require revalidation of sealing parameters.
Brand owners are unbundling packaging specification development from manufacturing execution, retaining design control while outsourcing production to lowest-validated-bidder contract facilities. This procurement fragmentation concentrates negotiating power with pharmaceutical and CPG headquarters in New York and Chicago while compressing contract packager margins through annual rebidding cycles. The pattern is most visible in over-the-counter healthcare products, where private label proliferation demands rapid format changeovers that only automated Midwest facilities can execute profitably.
United States Contract Packaging Market Segmentation
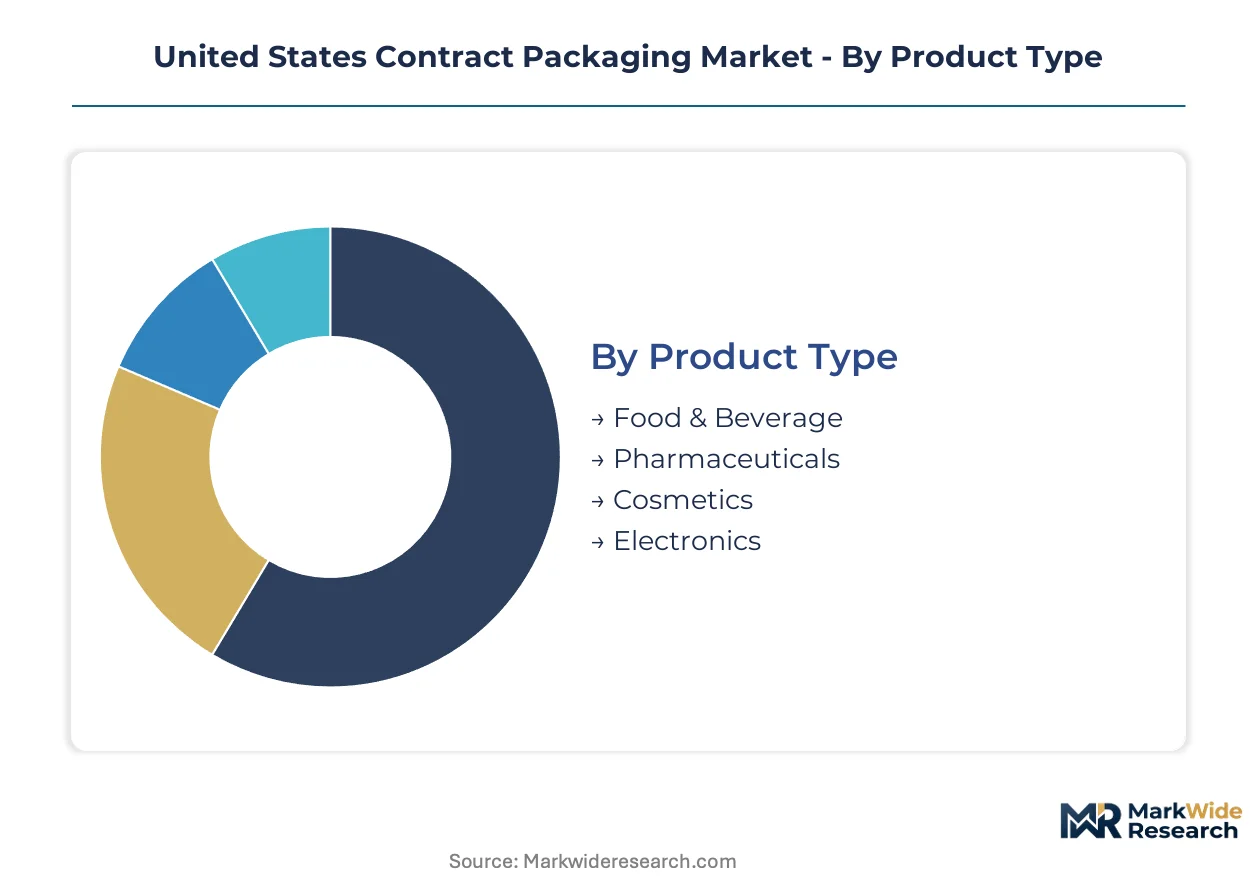
Contract packaging segmentation reflects divergent capital intensity and compliance burdens across end-use sectors. Pharmaceutical and food manufacturers impose fundamentally different validation requirements, equipment specifications, and geographic proximity needs on their third-party packaging partners.
Product Type:
Buyers in this category separate by regulatory exposure and batch complexity rather than unit volume alone.
- Pharmaceuticals:Serialization-capable lines and FDA-validated cleanroom environments dominate capital allocation. Demand concentrates in Massachusetts and North Carolina biotech corridors where cell therapy producers outsource sterile barrier packaging to avoid captive facility costs.
- Food & Beverage:High-throughput flexible film operations serve national CPG brands with format changeover flexibility. Midwest contract packagers near Chicago and Indianapolis capture volume through just-in-time pouch and tray sealing workflows for private label proliferation.
- Cosmetics:Premium secondary packaging and kit assembly services target direct-to-consumer subscription models with seasonal demand spikes.
- Electronics:ESD-protected rigid packaging and foam-in-place cushioning address semiconductor and medical device manufacturers relocating assembly from Asia.
Volume sits with Food & Beverage; growth tilts toward Pharmaceuticals.
Packaging Type:
Material science sophistication and automation compatibility divide procurement priorities in this dimension.
- Flexible Packaging:Roll-fed film and preformed pouch systems minimize material cost and shipping weight for dry goods and snacks. Southeast converters near Atlanta leverage resin supplier proximity to manage polypropylene price volatility on food-grade contracts.
- Blister Packs:Thermoformed cavities with lidding foil deliver unit-dose compliance packaging for chronic disease therapies. European machinery lead times constrain US capacity expansion despite FDA serialization mandates driving pharmaceutical demand.
- Rigid Packaging:Paperboard cartons and thermoformed trays sustain dominant positions in medical device kitting through integrated fiber sourcing.
- Labels:Pressure-sensitive and shrink-sleeve formats require rapid digital printing turnaround for promotional versioning and regulatory updates.
Flexible Packaging commands the largest share; Blister Packs are expanding most quickly.
End User:
Customer scale and outsourcing maturity determine service bundling expectations and contract duration.
- Pharmaceutical Companies:Branded drug makers shed captive facilities to preserve R&D capital, demanding multi-year agreements with validated serialization infrastructure and batch release documentation capabilities.
- Food Manufacturers:National CPG headquarters in Chicago and New York concentrate negotiating power through annual rebidding cycles, fragmenting procurement across lowest-validated-bidder facilities.
- Cosmetic Brands:Direct-to-consumer and prestige channels require rapid format changeovers and premium unboxing experiences with limited production runs.
- Electronics Producers:US-Mexico nearshoring trends create demand for sterile packaging validation and final kitting operations for medical device manufacturers.
Food Manufacturers generate the highest throughput; Pharmaceutical Companies deliver the steepest expansion trajectory.
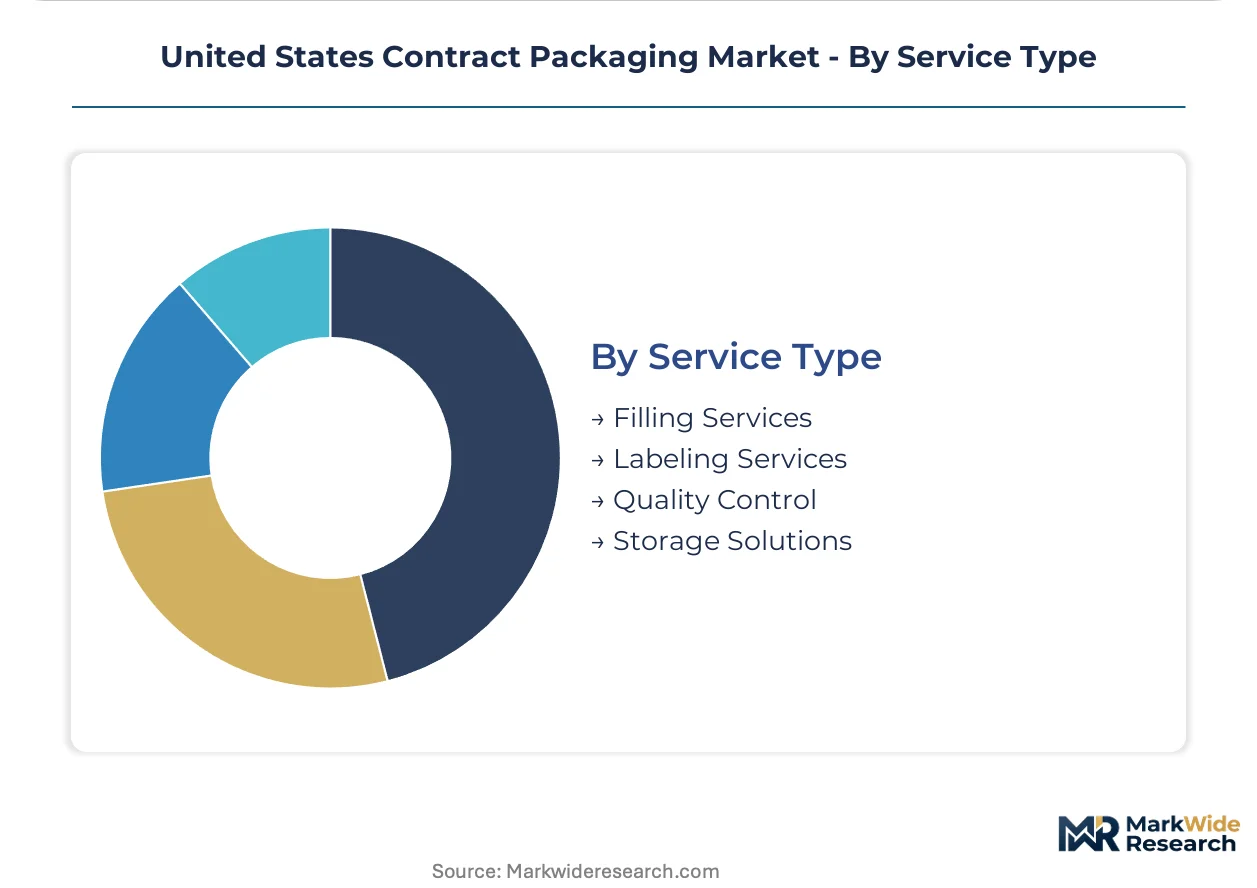
Service Type:
Value-added depth and regulatory liability exposure differentiate pricing tiers in service procurement.
- Quality Control:FDA validation requirements and batch release documentation burdens command premium margins. Near-infrared spectroscopy for inline moisture and chemical composition verification reduces release timelines from weeks to days.
- Filling Services:Powder, liquid, and semi-solid dosing operations span food-grade to potent compound handling with divergent containment infrastructure.
- Labeling Services:Serialization software administration and vision inspection systems require scarce IT professionals with pharmaceutical compliance experience.
- Storage Solutions:Temperature-controlled warehousing and inventory management services extend contract packager relationships beyond production into distribution.
Filling Services anchor volume; Quality Control captures the fastest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polypropylene resin suppliers anchor the Gulf Coast petrochemical corridor, feeding flexible film converters across Texas and Louisiana. This feedstock proximity shapes contract packaging cost structures and capacity distribution nationwide.
Midwest Manufacturing Corridor
Chicago and Indianapolis pharmaceutical hubs drive demand for oral solid dose packaging and serialization services. FDA cGMP inspections concentrate validation expertise in Illinois and Indiana facilities. Contract packagers cluster along Interstate 65 between Indianapolis and Louisville to capture just-in-time workflows for generic drug manufacturers.
Southeast Atlantic States
Atlanta and Charlotte serve as distribution nodes for food-grade flexible packaging serving southeastern CPG brands. EPA hazardous waste rules tighten solvent handling protocols at Georgia and North Carolina converting facilities. Blister packaging capacity expands near Research Triangle Park to serve emerging biologics producers.
Northeast Biotech Belt
Greater Boston and New Jersey pharmaceutical corridors outsource sterile barrier packaging for cell and gene therapies. OSHA worker exposure limits govern potent compound handling at New Jersey contract facilities. Massachusetts packagers invest in cryogenic label adhesion capabilities for ultra-low temperature biologics distribution.
Texas Gulf Coast
Houston and Corpus Christi resin production supplies polypropylene and polyethylene to regional flexible film converters. Texas facilities leverage feedstock proximity to manage resin price volatility on high-volume food packaging contracts. Port of Houston access supports export-oriented medical device kitting operations for Mexican assembly plants.
California Pacific Coast
Los Angeles and San Francisco Bay Area cosmetic brands demand premium secondary packaging with rapid format changeovers. California extended producer responsibility laws mandate recycled content documentation and design-for-recyclability compliance. Contract packagers absorb these compliance costs while serving direct-to-consumer subscription box fulfillment.
United States Contract Packaging Market Competitive Landscape
Global majors compete with regional champions across serialization infrastructure and sterile barrier capabilities. The market structures around three tiers: diversified packaging conglomerates with integrated fiber sourcing, pharmaceutical specialists with FDA-validated cleanrooms, and regional food-grade converters with format flexibility. Strategic moves concentrate on M&A to acquire serialization software assets and capacity expansion near biotech manufacturing clusters.
Among diversified packaging conglomerates, Sonoco Products Company and WestRock Company exemplify scale-driven archetypes with thermoforming and paperboard rigid capabilities. Pharma Tech Industries occupies a specialist position within the pharmaceutical tier, representing validated handling expertise for cytotoxic and hormonal drug formats. These three companies anchor competitive positioning across the compliance-capability spectrum.
| Leading Market Players |
|---|
| Multipack Solutions LLC |
| Sonoco Products Company |
| Aaron Thomas Company |
| Jones Healthcare Group Inc. |
| WestRock Company |
| Sharp Packaging Services |
| Pharma Tech Industries |
| Pacmoore Products Inc |
| Reed-Lane Inc. |
| Others |
Value Network & Pricing Analysis
Polypropylene resin futures on the Gulf Coast petrochemical corridor cascade through contract packaging pricing tiers, compressing margins on high-volume food-grade flexible contracts while serialization-validated pharmaceutical services command premium spreads insulated from commodity swings.
Pricing Analysis
Warranty and batch-release documentation bundling separates pharmaceutical contract tiers from unbundled food-grade procurement. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA validation depth and serialization infrastructure maturity. Price differentiation hinges on cleanroom certification grade and geographic proximity to Indianapolis and Chicago pharmaceutical hubs. Pricing pressure stems from annual rebidding cycles concentrated with CPG headquarters in New York, while generic drug manufacturers in New Jersey exhibit highest price sensitivity and biologics producers in Massachusetts show least.
Supply Chain Analysis
Direct-to-pharma-manufacturer channels handle serialized dose packaging demand, while food-grade volume flows through distributor-mediated procurement. Raw material sourcing draws from Texas and Louisiana resin production, European machinery vendors for blister lines, and Southeast Asian film substrates. Supply chain risk centers on single-source dependency for high-speed serialization equipment from German and Italian vendors. Distribution runs through Midwest manufacturing corridors anchored by Chicago logistics nodes and Southeast Atlantic distribution hubs near Atlanta.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States contract packaging market functions as a cost-of-compliance story where FDA Drug Supply Chain Security Act serialization mandates erect barrier-to-entry moats favoring incumbent players with validated infrastructure investments.
For Market Incumbents: To counter margin compression from annual CPG rebidding cycles, consolidate facility footprints in Midwest pharmaceutical corridors to capture just-in-time generic drug workflows. Deepen backward integration into thermoforming tooling and sterile barrier material production to defend pricing power against resin volatility.
For New Entrants and Emerging Players: Regional distributors serving mid-sized generics manufacturers in Pennsylvania and Ohio represent the most penetrable channel partner type for serialization-capable contract packaging entry. Target cold chain biologics packaging for cell therapy producers in North Carolina's Research Triangle Park, leveraging cryogenic label adhesion capabilities as differentiated go-to-market positioning.
For Investors and Strategic Acquirers: Distressed-cycle entries favor FDA-validated cleanroom facilities in Illinois and Indiana with underutilized serialization capacity. Long-term viability over a five-to-ten year horizon rests on acquiring pharmaceutical-specialist archetypes with established batch release documentation capabilities. Watch IRA domestic content incentive implementation as inflection signal for Medicare-negotiated drug packaging demand shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Serialization Infrastructure Investment | FDA DSCSA compliance deadlines force validated software and aggregation line deployment across pharmaceutical contract facilities. |
| Sterile Barrier Capacity Expansion | Cell and gene therapy manufacturing growth in Massachusetts and North Carolina drives demand for cryogenic-compatible packaging validation. |
| Backward Integration into Resin Converting | Gulf Coast petrochemical proximity enables margin protection against polypropylene price volatility on high-volume food contracts. |
| Midwest Corridor Facility Consolidation | Interstate 65 clustering between Indianapolis and Louisville captures just-in-time workflows for generic drug manufacturers. |
| Quality Control Technology Adoption | Near-infrared spectroscopy deployment reduces pharmaceutical batch release timelines from weeks to days, locking multi-year agreements. |
Research Methodology
Multi-period observation of FDA inspection citation patterns, resin price indices, and serialization infrastructure deployment anchored the trend analysis, supplemented by interviews with contract packaging operations directors, pharmaceutical supply chain executives, regulatory affairs specialists at FDA-registered facilities, and flexible film procurement managers at CPG brands. Secondary validation drew from FDA cGMP inspection databases, EPA hazardous waste generator manifests, SEC 10-K disclosures of diversified packaging conglomerates, and customs trade data on European machinery imports. Bottom-up facility capacity modeling and top-down end-use demand estimation were triangulated against reported industry utilization rates.
The input-output matrix framed demand as function of pharmaceutical outsourcing intensity, biologics manufacturing expansion, and food-grade private label proliferation across the projection horizon. Segmentation dimensions spanned product type, packaging format, end-user scale, and service depth including quality control bundling. CAGRs were derived from trend extrapolation of validation-driven pricing premiums and commodity-exposed food-grade compression, stress-tested against IRA domestic content incentive uptake and state-level extended producer responsibility implementation.
Caveats apply where FDA enforcement discretion on DSCSA deadlines or abrupt resin price spikes could materially shift the outlook. Forecasts reflect assumptions on serialization technology adoption curves and biologics manufacturing geographic concentration. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
North America Child Resistant Packaging Market
Packaging Solutions
Contract Packaging and Fulfillment Service Market
Packaging Solutions
Custom Packaging Market
Packaging Solutions
Shelf Stable Packaging Market
Packaging Solutions
Sterilized Packaging Market
Packaging Solutions
Hermetic Packaging Market
Packaging Solutions
Global Packaging Market
Packaging Solutions
Mexico Packaging Market
Packaging Solutions
Saudi Arabia Packaging Market
Packaging Solutions
Suspension and Retention Packaging Market
Packaging Solutions
Anti-Counterfeit Clothing Packaging Market
Packaging Solutions
Consumer Packaging Market
Packaging Solutions
Global Coding and Marking Solutions Market
Packaging Solutions
Halal Packaging Market
Packaging Solutions
Portable UV Sanitizing Boxes Market
Packaging Solutions
Europe Temperature Controlled Packaging Solutions Market