
 Suspension and Retention Packaging Market | 2026-2036
Suspension and Retention Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Suspension and Retention Packaging Market Analytics
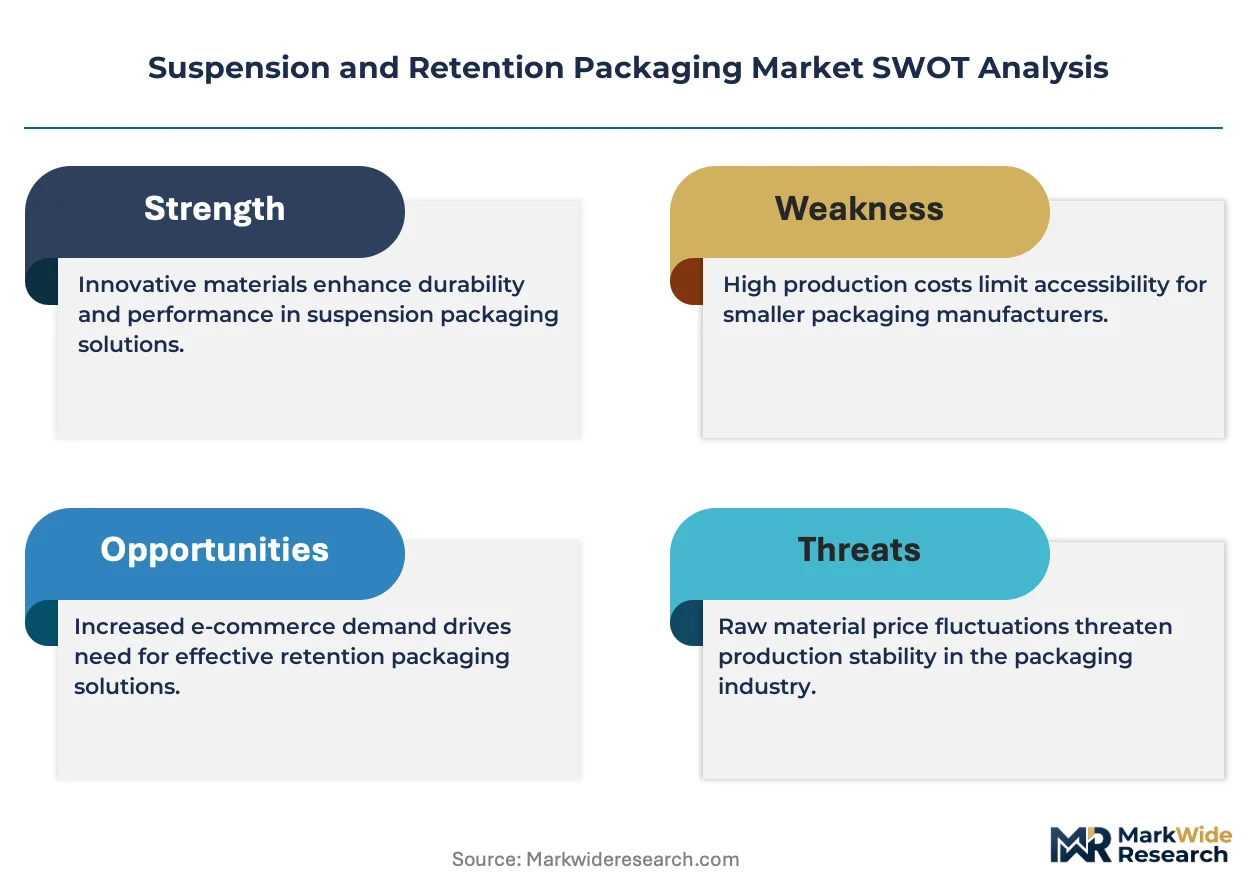
Asset-light leasing models for protective packaging systems is narrowing the capital barrier for mid-tier logistics providers entering the suspension and retention segment. Sealed Air Corporation leverages its global manufacturing footprint to sustain pricing power across protective packaging categories. Mondi anchors its European operations with integrated paper-based retention solutions that compete against plastic alternatives. NEFAB specializes in engineered-to-order suspension frames for industrial equipment, occupying a premium niche with long contract cycles.
Suspension and retention packaging encompasses systems that immobilize products within a pack using tensioned films, elastic membranes, or molded cavities to absorb shock and vibration during distribution. Polyethylene films dominate flexible retention applications due to their tear resistance and clarity, while polystyrene trays provide rigid structural support for electronics and pharmaceutical kits. The food industry drives volume demand for clamshell retention packs that extend produce shelf life through controlled atmosphere properties. Flexible packaging formats capture the fastest growth trajectory as e-commerce fulfillment centers adopt stretch-suspension bags to reduce dimensional weight shipping penalties.
The EPA regulates volatile organic compound emissions from polyethylene and polystyrene manufacturing processes, pushing converters toward low-solvent lamination technologies. REACH compliance in Europe restricts certain plasticizers in retention films, compelling material suppliers to certify alternative formulations for pharmaceutical and electronics end users. The FDA maintains biocompatibility standards for direct-contact pharmaceutical packaging, creating a compliance moat around qualified suspension pack suppliers. Stakeholders must monitor evolving extended producer responsibility frameworks that shift end-of-life collection costs onto packaging producers.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing design cycles for suspension and retention systems as material recovery targets force converters to requalify film formulations and tray geometries ahead of enforcement deadlines.
Growth Catalysts
- E-commerce fulfillment automation:Distribution centers in Germany and the Netherlands are deploying stretch-suspension bagging systems to minimize dimensional weight penalties on parcel networks. Polyethylene film consumption for these applications is expanding in line with automated sortation throughput.
- REACH plasticizer restrictions:The European Chemicals Agency's phased limitations on phthalate-based plasticizers in retention films is accelerating certification of bio-based alternatives for pharmaceutical and electronics packaging.
- Automotive precision logistics:German automotive parts exporters are specifying engineered retention frames for powertrain components requiring vibration isolation across multimodal transit to assembly plants in Mexico and China.
Market Restraints
- Petrochemical input volatility:Linear low-density polyethylene resin prices fluctuate with naphtha cracking margins, compressing converter margins on long-term suspension film contracts.
- East Asian mold tooling concentration:Polystyrene tray production relies on injection molding equipment sourced predominantly from Chinese and Taiwanese machinery builders, creating lead time exposure for European and North American retention packagers.
- Mechanical recycling incompatibility:Multi-layer suspension films combining polyethylene with ethylene-vinyl acetate barrier layers face technical limitations in current mechanical recycling streams, constraining circular economy claims.
Strategic Opportunities
- Indian pharmaceutical cold chain:CDSCO biocompatibility requirements for direct-contact packaging create entry barriers that qualified suspension pack suppliers can leverage as domestic vaccine and biologics production scales.
- Cell-cultured protein packaging:Controlled-atmosphere retention clamshells developed for produce shelf-life extension are being adapted for cell-cultured meat products requiring precise gas barrier performance during refrigerated distribution.
- Digital product passport mandates:The EU Green Deal's packaging traceability requirements will favor suspension and retention suppliers with integrated serialization and blockchain verification capabilities.
Industry Challenges
- Multilayer film requalification timelines:FDA biocompatibility testing protocols for direct-contact pharmaceutical suspension packs extend 18-24 months, freezing formulation innovation cycles for qualified suppliers.
- Legacy warehouse management integration:Automated suspension bagging systems require API connectivity with existing WMS platforms, creating implementation friction for mid-tier 3PLs with heterogeneous IT estates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Suspension and Retention Packaging Market |
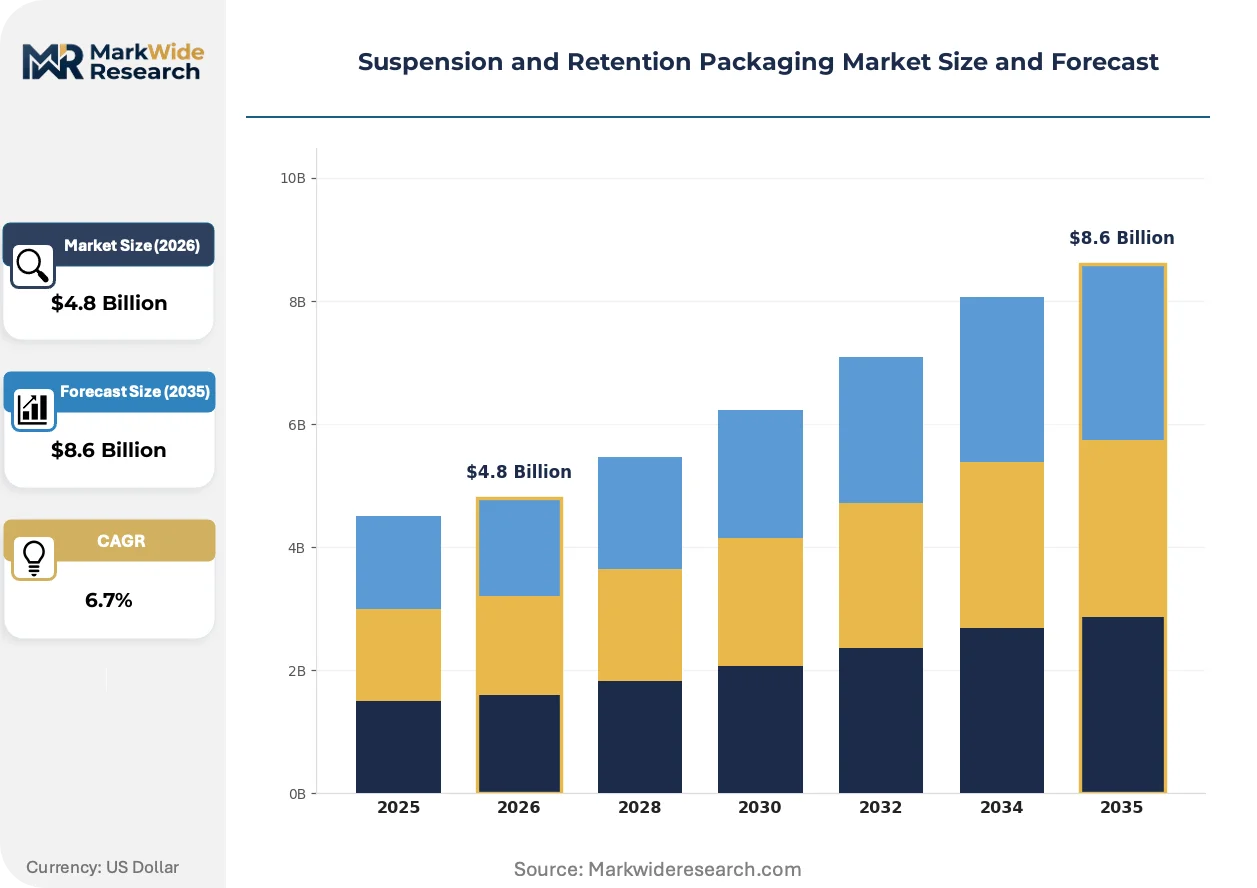
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Trays, Clamshells, Bags, Films Material: Polyethylene, Polystyrene, Aluminum, Cardboard End User: Food Industry, Electronics, Pharmaceuticals, Consumer Goods Packaging Type: Flexible Packaging, Rigid Packaging, Protective Packaging, Specialty Packaging |
| Companies Covered | NEFAB, A E Sutton, Sealed Air Corporation, Samuel Grant Packaging, Secure Pak Packaging, Mondi, Protega Global, Coral Packaging, Amcor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Suspension and Retention Packaging Market Evolving Landscape
Active intelligence embedded in packaging substrates is compressing the information gap between shipment origin and destination, enabling predictive intervention before damage events occur.
Printed sensor arrays using conductive inks are digitizing condition monitoring for high-value electronics in suspension transit. Pharmaceutical distributors in Switzerland and semiconductor logistics providers in South Korea are piloting these systems on temperature-sensitive and shock-critical lanes. The technology is digitizing quality assurance workflows by replacing manual inspection with automated exception flagging at transfer points.
The EPA's pending rulemaking on per- and polyfluoroalkyl substances in packaging substrates is forcing polyethylene film converters to eliminate fluorinated processing aids. Suspension film manufacturers serving aerospace and medical device sectors are requalifying non-fluorinated slip agents ahead of anticipated enforcement. Electronics retention packagers in California and Washington state are accelerating compliance timelines beyond federal minimums to meet state-level precursor regulations.
Consolidated buying by platform-based freight marketplaces is compressing supplier negotiation cycles for protective packaging procurement. Large e-commerce sellers are aggregating suspension and retention demand across multiple fulfillment nodes, displacing site-specific supplier relationships. This concentration is most visible in Germany's Rhine-Ruhr logistics corridor and the Netherlands' Venlo distribution cluster, where 3PLs are rationalizing protective packaging vendor bases from dozens to single-digit approved lists.
Suspension and Retention Packaging Market Segmentation
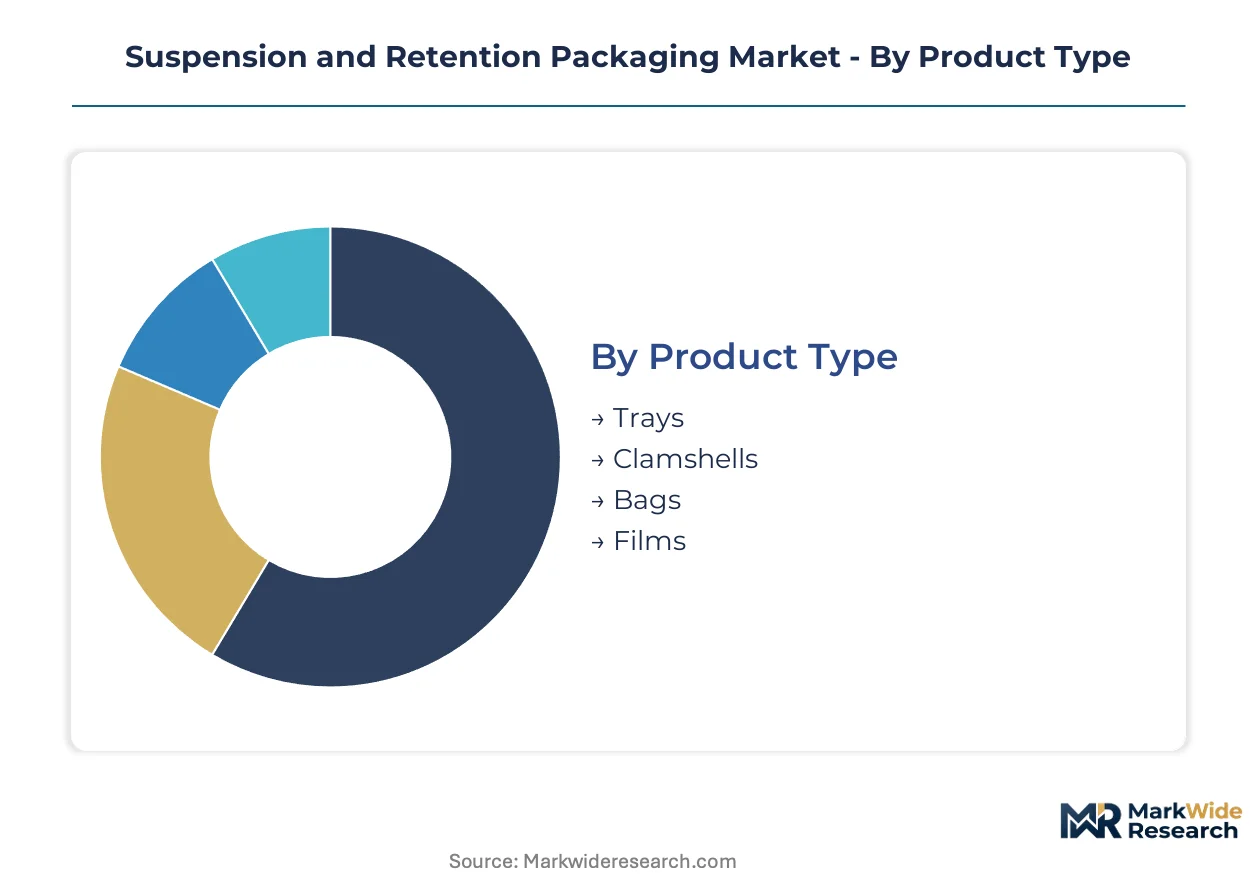
Suspension and retention packaging serves heterogeneous protection requirements across product fragility, transit distance, and regulatory exposure. Segmentation reveals how material selection and format geometry align with end-use risk profiles and automation compatibility.
Product Type:
Mature formats dominate established verticals while emerging configurations capture e-commerce automation demand.
- Trays:Molded polystyrene or polyethylene structures with precision-engineered cavities immobilize components through mechanical retention. Automotive parts exporters in Germany specify engineered trays for powertrain components requiring vibration isolation across multimodal transit to assembly plants in Mexico and China.
- Clamshells:Hinged two-piece rigid shells with controlled atmosphere properties extend produce shelf life while providing tamper-evident security. The food industry drives volume demand for clamshell retention packs that balance gas barrier performance with retail visibility requirements.
- Bags:Stretch-suspension configurations using tensioned polyethylene films reduce dimensional weight penalties in parcel networks. Distribution centers in Germany and the Netherlands are deploying automated bagging systems to minimize shipping costs.
- Films:Elastic membranes and multilayer barrier films provide flexible retention for irregular geometries. REACH plasticizer restrictions are accelerating certification of bio-based alternatives for pharmaceutical and electronics packaging applications.
Trays retain volume leadership; bags hold the steepest expansion curve.
Material:
Cost tier stratification separates commodity resins from performance-grade substrates with compliance premiums.
- Polyethylene:Linear low-density and high-density grades dominate flexible retention applications due to tear resistance, clarity, and heat-seal compatibility. E-commerce fulfillment centers are expanding polyethylene film consumption for stretch-suspension systems in line with automated sortation throughput.
- Polystyrene:Crystal and high-impact grades provide rigid structural support for electronics and pharmaceutical kits through injection-molded trays and clamshells. East Asian mold tooling concentration creates lead time exposure for European and North American retention packagers.
- Aluminum:Foil laminates and formed trays deliver superior moisture and gas barrier performance for sensitive pharmaceuticals. FDA biocompatibility standards create a compliance moat around qualified suspension pack suppliers serving direct-contact applications.
- Cardboard:Integrated paper-based retention solutions compete against plastic alternatives in European markets facing tightening material recovery targets under the EU Packaging and Packaging Waste Regulation.
Polyethylene dominates flexible applications; aluminum commands the highest unit margins.
End User:
Application-driven specification intensity varies from standardized produce packs to engineered pharmaceutical systems.
- Food Industry:Volume demand concentrates in clamshell retention packs for produce shelf-life extension through controlled atmosphere properties. Cell-cultured protein packaging is emerging as an adaptation opportunity for existing gas barrier technologies.
- Electronics:Printed sensor arrays using conductive inks are digitizing condition monitoring for high-value components in suspension transit. Semiconductor logistics providers in South Korea are piloting these systems on shock-critical lanes.
- Pharmaceuticals:CDSCO biocompatibility requirements for direct-contact packaging create entry barriers that qualified suspension pack suppliers can leverage as Indian vaccine and biologics production scales. FDA testing protocols extend 18-24 months, freezing formulation innovation cycles.
- Consumer Goods:Platform-based freight marketplaces are consolidating procurement, displacing site-specific supplier relationships with approved vendor lists.
Food Industry retains volume leadership; Pharmaceuticals holds the steepest expansion curve.
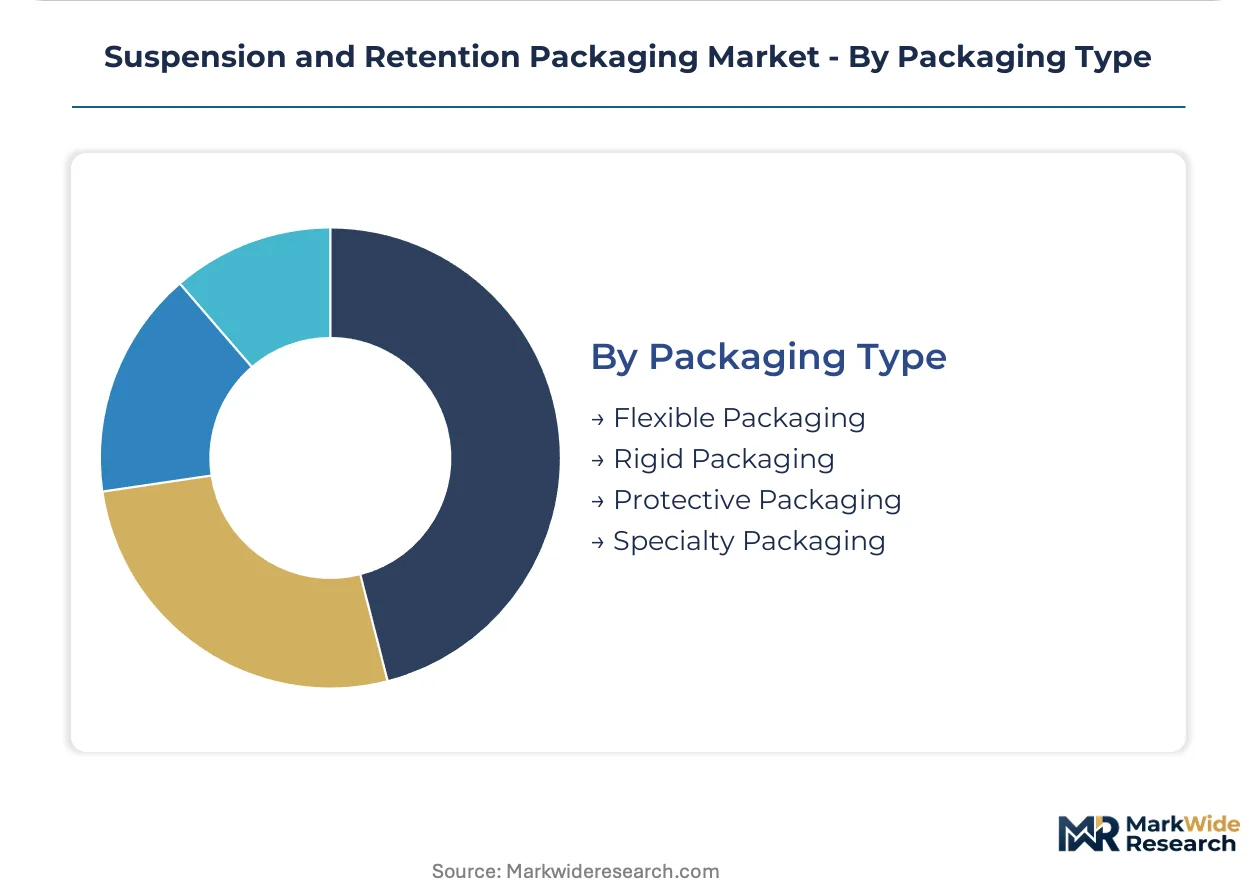
Packaging Type:
Supply concentration in automated equipment manufacturing shapes format adoption timelines across customer tiers.
- Flexible Packaging:Stretch-suspension bags and elastic membrane systems capture the fastest growth trajectory as e-commerce fulfillment centers adopt formats to reduce dimensional weight shipping penalties. The EPA regulates volatile organic compound emissions from manufacturing processes, pushing converters toward low-solvent lamination technologies.
- Rigid Packaging:Molded trays, clamshells, and engineered frames provide structural integrity for heavy or fragile components. German automotive parts exporters require precision retention systems for multimodal transit.
- Protective Packaging:Systems specifically engineered for shock and vibration absorption span both flexible and rigid substrates. Asset-light leasing models for protective packaging systems are narrowing the capital barrier for mid-tier logistics providers.
- Specialty Packaging:Custom-engineered solutions for unique product geometries or extreme transit conditions command premium pricing. NEFAB occupies this niche with long contract cycles for industrial equipment suspension frames.
Flexible Packaging is expanding most quickly; Rigid Packaging maintains established vertical dominance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German automotive corridors where engineered retention systems command premiums, while Southeast Asian converters compete on polyethylene film throughput. Regulatory divergence between REACH-mandated plasticizer transitions and EPA volatile organic compound limits is fragmenting formulation strategies across Atlantic supply chains.
Germany
Automotive powertrain exporters in Baden-Württemberg and Bavaria specify precision retention frames for multimodal transit to Mexico and China. The EU Packaging and Packaging Waste Regulation tightens material recovery targets, forcing converters in the Rhine-Ruhr corridor to requalify film formulations ahead of enforcement deadlines. Stuttgart and Munich industrial clusters drive demand for vibration-isolation systems.
United States
E-commerce fulfillment centers in California and Washington accelerate stretch-suspension bag adoption to minimize dimensional weight penalties. The EPA regulates volatile organic compound emissions from polyethylene manufacturing, pushing converters toward low-solvent lamination technologies. The Pacific Northwest and Texas distribution clusters concentrate automated bagging system deployment.
China
Domestic vaccine and biologics production expansion drives demand for qualified suspension pack suppliers meeting biocompatibility standards. The country's national pharmaceutical regulator enforces direct-contact packaging requirements that create compliance moats for certified converters. Yangtze River Delta pharmaceutical clusters anchor cold chain retention system demand.
India
CDSCO biocompatibility requirements for direct-contact packaging create entry barriers as domestic vaccine manufacturing scales. The national pharmaceutical regulator mandates certification protocols that qualified suspension pack suppliers leverage. Maharashtra and Gujarat pharmaceutical corridors concentrate demand for compliant retention systems.
Netherlands
Venlo distribution cluster 3PLs rationalize protective packaging vendor bases from dozens to single-digit approved lists under platform-based freight marketplace consolidation. REACH plasticizer restrictions accelerate bio-based alternative certification for pharmaceutical and electronics applications. Automated stretch-suspension systems expand throughput at Rotterdam-adjacent fulfillment nodes.
Suspension and Retention Packaging Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in film and resin supply. The market structures around three tiers: multinational converters with integrated global manufacturing, regional engineering houses serving automotive and pharmaceutical verticals, and specialized fabricators focused on custom-molded retention geometries. Two dominant competitive moves define current positioning: strategic partnerships between film converters and automated equipment OEMs, and backward integration into captive resin compounding for REACH-compliant formulations.
Within the multinational converter tier, Sealed Air Corporation and Mondi exemplify scale-driven platform strategies. Sealed Air leverages its global manufacturing footprint across protective packaging categories, while Mondi anchors European operations with integrated paper-based retention solutions competing against plastic alternatives. NEFAB occupies the engineered-to-order niche, representing the specialist archetype with long contract cycles for industrial equipment suspension frames. These three players illustrate how competitive positioning stratifies between volume throughput and premium customization vectors.
| Leading Market Players |
|---|
| NEFAB |
| A E Sutton |
| Sealed Air Corporation |
| Samuel Grant Packaging |
| Secure Pak Packaging |
| Mondi |
| Protega Global |
| Coral Packaging |
| Amcor |
| Others |
Value Network & Pricing Analysis
Petrochemical input volatility determines both pricing tier spreads and supply chain shape in suspension and retention packaging. Linear low-density polyethylene resin price swings compress converter margins on long-term suspension film contracts while forcing buyers into shorter procurement cycles.
Pricing Analysis
Industrial OEM buyers anchor a contract-based pricing structure with three-tier differentiation across premium, standard, and economy levels. Price differentiation rests on REACH certification status and volume scale commitments, with pharmaceutical-grade films commanding substantial premiums over commodity e-commerce grades. Pricing pressure stems from consolidated buying by platform-based freight marketplaces that aggregate demand across fulfillment nodes. Mid-tier 3PLs exhibit highest price sensitivity due to thin operating margins, while automotive OEMs prioritize performance over cost.
Supply Chain Analysis
Extended payment terms from German automotive exporters have become standard supply-chain finance facilities for tier-one retention system suppliers. Manufacturing concentrates in Germany, China, and the Netherlands, with East Asian mold tooling for polystyrene trays creating single-source vulnerability for European and North American packagers. Raw material dependencies center on naphtha-derived polyethylene, high-impact polystyrene resin, and aluminum foil laminates. Distribution runs through 3PL consolidation in the Rhine-Ruhr corridor and Venlo cluster, where vendor rationalization intensifies margin pressure on upstream converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified suspension pack suppliers for pharmaceutical direct-contact applications represent a narrowing capability pool as FDA and CDSCO biocompatibility testing timelines extend qualification cycles.
For Market Incumbents: Insulate market position by deepening backward integration into captive resin compounding for REACH-compliant formulations ahead of plasticizer restriction enforcement. Secure long-term supply agreements with German automotive OEMs for precision retention frames to lock out specialized engineering competitors. Prioritize API connectivity investments for automated suspension bagging systems to capture mid-tier 3PL upgrade cycles. For New Entrants and Emerging Players: Establish a beachhead in Indian pharmaceutical cold chain retention systems where CDSCO certification creates defendable entry barriers against unqualified competitors. Target cell-cultured protein packaging adaptation as a white-space application leveraging existing controlled-atmosphere clamshell technology. Lead with digital product passport capabilities to align with EU Green Deal traceability mandates as a differentiated go-to-market angle. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors engineered-to-order specialists with long contract cycles and regulatory moats. Five-to-ten year viability hinges on positioning upstream of platform-based freight marketplace procurement concentration. Watch for inflection signals in EPA per- and polyfluoroalkyl substances rulemaking enforcement timelines that would force accelerated requalification spending across the installed base.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive supply of REACH-compliant formulations insulates margins from ECHA plasticizer restriction volatility. |
| Automated Equipment OEM Partnership | API-integrated suspension bagging systems capture 3PL upgrade demand in Germany and Netherlands fulfillment clusters. |
| CDSCO Certification Investment | Biocompatibility qualification creates entry barriers for Indian pharmaceutical cold chain retention contracts. |
| Digital Product Passport Development | Blockchain-verified traceability aligns with EU Green Deal packaging mandates ahead of enforcement deadlines. |
| Non-Fluorinated Slip Agent Requalification | EPA compliance for aerospace and medical device suspension films ahead of anticipated per- and polyfluoroalkyl substances rulemaking. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with packaging procurement managers at German automotive OEMs, pharmaceutical quality assurance directors, 3PL operations executives, and flexible film converters. Secondary validation drew from EPA emission filings, ECHA REACH substance restrictions, FDA biocompatibility guidance documents, and EU Packaging and Packaging Waste Regulation impact assessments. Bottom-up demand modeling across end-use segments triangulated against top-down petrochemical consumption data.
Calibration against historical capacity utilization rates and resin price elasticity informed projections across the analysis window. Segmentation dimensions included product type, material substrate, end-use industry, packaging format, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted volume trajectories incorporating e-commerce fulfillment automation penetration curves and pharmaceutical cold chain expansion rates.
Stress conditions across naphtha cracking margin volatility, REACH enforcement timeline acceleration, and platform-based procurement concentration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory implementation schedules and automation adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
India Packaging Market
Packaging Solutions
Vacuum Skin Packaging Market
Packaging Solutions
Anti-Counterfeit Clothing Packaging Market
Packaging Solutions
Europe Temperature Controlled Packaging Solutions Market
Packaging Solutions
Void Fill Packaging Systems Market
Packaging Solutions
Patisserie Packaging Market
Packaging Solutions
Single Dose Packaging Market
Packaging Solutions
Secondary Packaging Market
Packaging Solutions
Global Shelf Ready Packaging Market
Packaging Solutions
Sterilized Packaging Market
Packaging Solutions
Contract Packaging Market
Packaging Solutions
United Kingdom Packaging Market
Packaging Solutions
FMCG Packaging Market
Packaging Solutions
North America Child Resistant Packaging Market
Packaging Solutions
Europe Modified Atmosphere Packaging Market
Packaging Solutions
Cohesive Packaging Solutions Market