
 Hermetic Packaging Market | 2026-2036
Hermetic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Hermetic Packaging Market Analysis
Market Context
East Asian ceramic-to-metal seal producers is recalibrating capacity allocation toward automotive lidar and quantum computing sensor housings. Schott AG leverages its borosilicate glass expertise to dominate photonic device enclosures. Materion Corporation anchors North American supply for beryllium-copper hermetic connectors used in oil exploration electronics. Kyocera Corporation specializes in multilayer ceramic packages for high-frequency telecommunications infrastructure.
Technical Definition and Segments
Hermetic packaging denotes enclosure systems engineered to maintain gas-tight seals below helium leak rates of 1x10⁻⁸ atm·cc/s, typically employing glass, metal, or composite material combinations to shield sensitive electronics from moisture, corrosion, and pressure differentials. Metal packages capture the dominant margin pool in aerospace and defense applications where thermal cycling resistance commands premium pricing, while composite formats are gaining fastest in wearable medical devices where weight reduction intersects with biocompatibility requirements. Glass segments sustain stable demand from legacy optoelectronic transmitter markets even as plastic alternatives penetrate cost-sensitive consumer electronics moisture barriers.
Regulatory Frame
FDA 21 CFR Part 820 quality system regulations and EU MDR compliance frameworks dictate validation protocols for hermetic seals in implantable cardiac devices and drug-delivery systems, directly influencing material selection and testing documentation burdens. REACH restrictions on lead-bearing solders and chrome plating are forcing European converters to certify alternative metallization chemistries. Stakeholders must monitor evolving IEC 60068 environmental testing standards for space-grade hermeticity as low-Earth orbit satellite constellations proliferate.
Market Dynamics
Helium leak rate specifications below 1x10⁻⁸ atm·cc/s are hardening across aerospace and medical device specifications, compressing qualification timelines and forcing converters toward automated laser welding systems to maintain throughput.
Growth Catalysts
- EU MDR sterilization mandates:Implantable device manufacturers must demonstrate validated hermetic barrier integrity, expanding demand for glass-to-metal seal documentation packages.
- Low-Earth orbit satellite proliferation:Constellation operators require thermal cycling-resistant enclosures for radiation-hardened electronics, concentrating procurement in German precision seal clusters.
- Quantum computing sensor housings:Cryogenic operation demands are pulling ceramic-to-metal formats into previously metal-dominated research applications.
Market Restraints
- Beryllium-copper supply concentration:North American specialty alloy availability constrains connector production for oil exploration electronics.
- REACH solder restrictions:Lead-bearing alloy phase-outs force European converters to recertify alternative metallization chemistries at elevated cost.
- Plastic moisture barrier substitution:Cost-sensitive consumer electronics segments are accepting reduced hermeticity in exchange for weight and cost advantages.
Strategic Opportunities
- Wearable medical device convergence:Biocompatibility-weight tradeoffs favor composite package formats in glucose monitoring and neurostimulation applications.
- Automotive lidar sensor scaling:Advanced driver-assistance system deployment is creating volume demand for automotive-grade ceramic housings.
- IEC 60068 space certification expansion:Environmental testing standard evolution opens qualification pathways for new market entrants in satellite component supply.
Industry Challenges
- Glass-to-metal seal technician scarcity:Precision furnace operation and metallurgical bonding expertise resides with aging workforces in traditional manufacturing clusters.
- Multi-standard certification burden:Simultaneous FDA 21 CFR Part 820, EU MDR, and IEC qualification creates documentation complexity for cross-border suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hermetic Packaging Market |
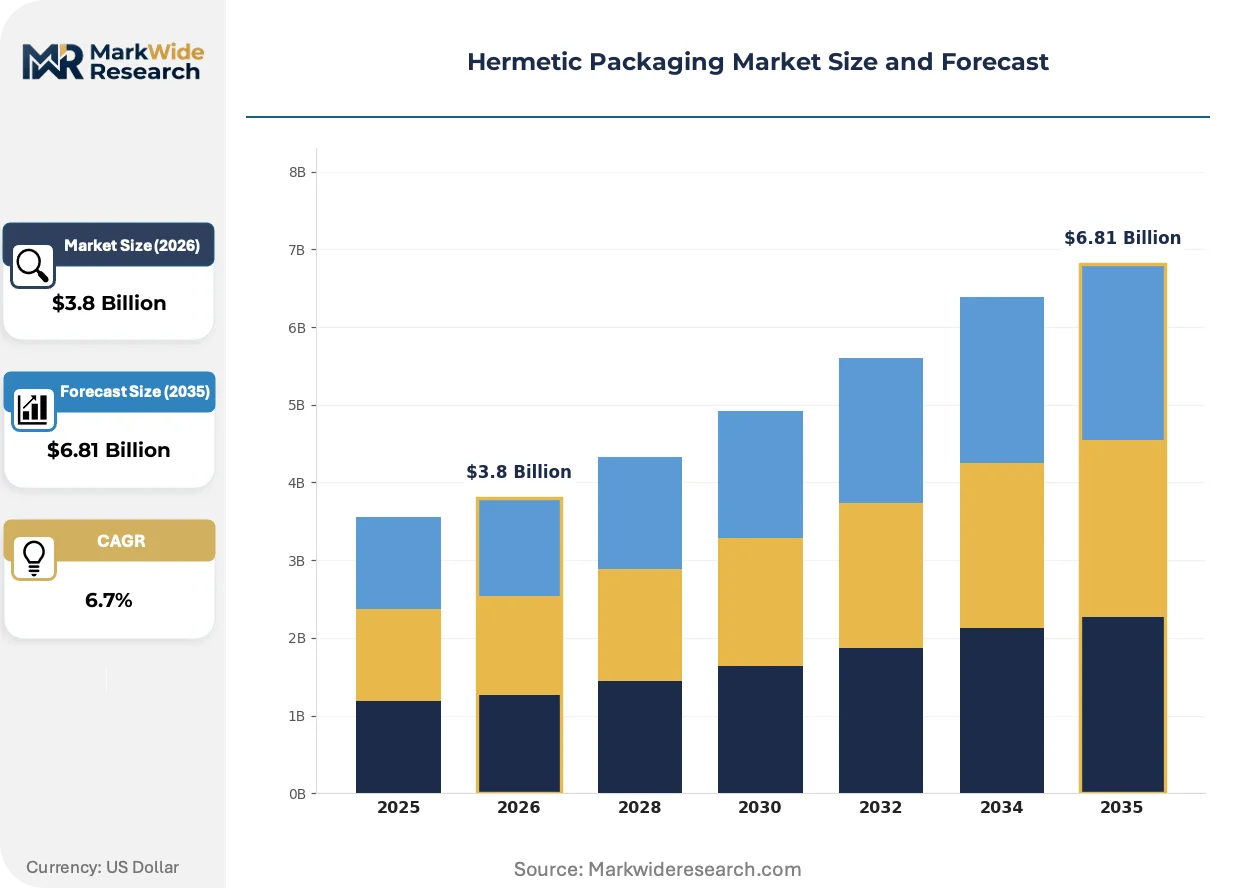
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass, Metal, Plastic, Composite Application: Food & Beverage, Pharmaceuticals, Electronics, Medical Devices Form: Rigid, Flexible, Semi-Rigid, Blister End User: Manufacturers, Distributors, Retailers, Consumers |
| Companies Covered | Schott AG, AMETEK, Amkor Technology, Materion Corporation, Texas Instruments Incorporated, Kyocera Corporation, NGK Spark Plug, Egide, Teledyne Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hermetic Packaging Market Emerging Trajectories
Material science advances and regulatory harmonization pressures are compressing traditional package format lifecycles while opening entry points for specialized converters.
Laser-assisted glass sealing is rewriting throughput economics for photonic device enclosures. Optical transceiver manufacturers are adopting fiber-fed solid-state systems to replace batch furnace processing. This shift is compressing lead times from weeks to days for high-volume telecom component supply.
REACH authorization requirements for hexavalent chromium plating are forcing European hermetic connector producers toward nickel-palladium-gold surface finishes. The industrial consequence is elevated material cost and extended plating line conversion timelines. Medical device OEMs in Germany and Switzerland are qualifying these alternative chemistries ahead of aerospace contractors.
Specification consolidation among prime defense contractors is narrowing approved vendor lists for mission-critical semiconductor protection. Tier-two suppliers are responding through captive testing laboratory investment and direct qualification relationships with system integrators. This concentration is most visible in US satellite and missile guidance electronics procurement.
Hermetic Packaging Market Segmentation
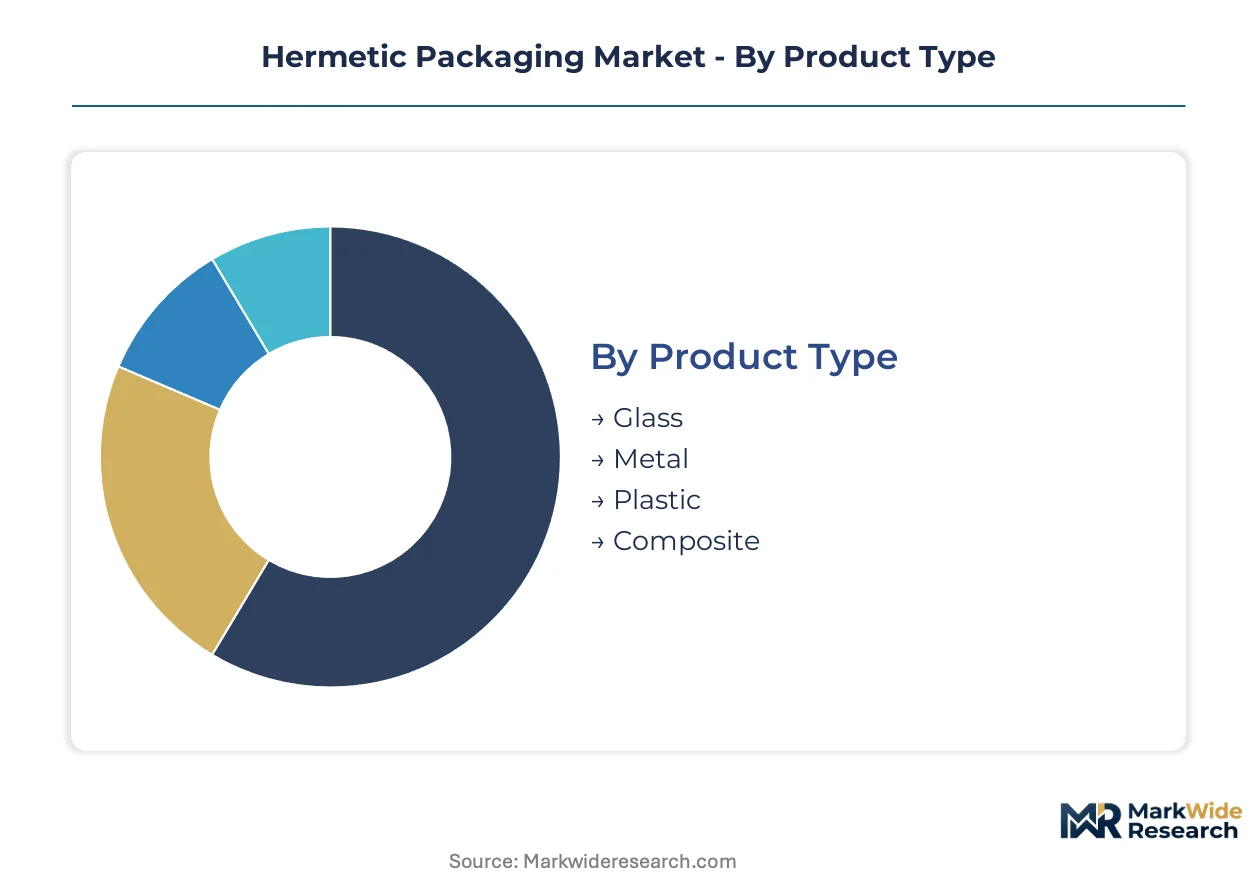
Material selection and application-specific performance requirements fragment the hermetic packaging landscape across distinct technical tiers. Each segmentation axis reveals divergent margin structures, qualification burdens, and supply chain configurations that reshape competitive positioning.
Product Type:
Metal formats command aerospace procurement budgets while composite alternatives capture wearable medical device volumes.
- Glass:Borosilicate and aluminosilicate compositions achieve helium leak rates below 1x10⁻⁸ atm·cc/s through precision furnace bonding. Optoelectronic transmitter manufacturers in Germany and Japan sustain demand despite slower growth curves.
- Metal:Kovar, stainless steel, and titanium enclosures dominate satellite and missile guidance electronics where thermal cycling resistance justifies premium pricing. Defense contractor vendor list consolidation concentrates procurement among qualified North American and European suppliers.
- Plastic:Polymer moisture barriers serve cost-sensitive consumer electronics where reduced hermeticity tolerance enables weight and manufacturing advantages.
- Composite:Ceramic-polymer hybrids address biocompatibility-weight tradeoffs in implantable neurostimulation and glucose monitoring devices.
Today's leader: Metal. Tomorrow's challenger: Composite.
Application:
Regulatory intensity varies sharply across end-use sectors, with medical and aerospace applications demanding documentation packages that consumer segments escape.
- Electronics:Semiconductor protection for oil exploration, telecommunications infrastructure, and quantum computing sensor housings drives ceramic-to-metal and glass-to-metal seal demand. East Asian producers are recalibrating capacity toward automotive lidar and cryogenic research applications.
- Medical Devices:Implantable cardiac devices and drug-delivery systems require FDA 21 CFR Part 820 and EU MDR validated barrier integrity. German and Swiss OEMs are qualifying nickel-palladium-gold surface finishes ahead of REACH deadlines.
- Food & Beverage:Extended shelf-life packaging employs lower-specification hermetic seals where cost minimization dominates material selection.
- Pharmaceuticals:Sterile barrier systems for biologics and parenteral drugs must demonstrate container closure integrity under ICH guidelines.
Electronics captures current procurement volume; medical devices present the steepest expansion trajectory as sterilization mandates tighten.
Form:
Structural rigidity requirements map directly to pressure differential tolerance and handling automation compatibility.
- Rigid:Machined metal housings and pressed glass enclosures serve aerospace and defense applications where dimensional stability under thermal stress is non-negotiable.
- Flexible:Polymer films and laminates penetrate disposable medical device segments where conformability to anatomical contours matters.
- Semi-Rigid:Hybrid constructions balance protection with weight reduction in portable diagnostic equipment.
- Blister:Thermoformed cavities with lidding films address unit-dose pharmaceutical packaging where hermeticity requirements are moderate.
Rigid formats anchor premium pricing; flexible formats are climbing fastest in point-of-care diagnostics.
End User:
Procurement sophistication and qualification authority concentrate at the manufacturer tier, with downstream channels serving primarily logistical functions.
- Manufacturers:Satellite OEMs, implantable device producers, and automotive Tier-1s dictate specifications and maintain approved vendor lists. Direct qualification relationships with system integrators are becoming mandatory for Tier-two seal suppliers.
- Distributors:Specialized electronics and medical device component distributors carry inventory for qualified converters serving mid-volume applications.
- Retailers:Pharmacy and medical supply chains handle packaged pharmaceuticals and consumer diagnostic devices with minimal technical involvement.
- Consumers:End-user exposure is limited to pre-packaged medical devices and diagnostics with factory-sealed barriers.
Manufacturers control specification authority; distributors are gaining importance as qualification timelines compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as European REACH compliance costs push seal fabrication toward East Asian ceramic-to-metal specialists and North American defense-qualified suppliers.
United States
Defense contractor vendor list consolidation concentrates procurement for satellite and missile guidance electronics among qualified domestic suppliers. FDA 21 CFR Part 820 documentation requirements for implantable cardiac devices drive seal validation protocols. Materion Corporation anchors beryllium-copper connector supply from its Ohio base for oil exploration electronics.
Germany
Precision glass-to-metal seal clusters in Bavaria and Baden-Württemberg serve satellite OEMs and implantable device manufacturers with helium leak rates below 1x10⁻⁸ atm·cc/s. EU MDR sterilization mandates are accelerating nickel-palladium-gold surface finish qualifications ahead of REACH hexavalent chromium restrictions. Stuttgart-area fabricators are expanding automated laser welding capacity for photonic device enclosures.
Japan
Kyocera Corporation specializes in multilayer ceramic packages for high-frequency telecommunications infrastructure from its Kyoto operations. METI industrial standards govern cryogenic sensor housing specifications for quantum computing research applications. Nagoya-area producers are recalibrating capacity toward automotive lidar ceramic housings as advanced driver-assistance systems scale.
China
East Asian ceramic-to-metal seal producers are reallocating capacity toward quantum computing sensor housings and automotive lidar applications. GB standards and MIIT regulations shape domestic qualification protocols for space-grade hermeticity. Yangtze River Delta clusters are expanding photonic device enclosure output through fiber-fed solid-state laser sealing systems.
Switzerland
Swissmedic regulations for implantable neurostimulation devices drive demand for biocompatible composite package formats. Geneva and Zurich-area converters are qualifying alternative metallization chemistries ahead of EU REACH authorization timelines. Precision fabrication clusters serve glucose monitoring OEMs with ceramic-polymer hybrid constructions.
Hermetic Packaging Market Vendor Landscape
German producers anchor the premium glass-to-metal tier; Japanese specialists hold ceramic-to-metal dominance for high-frequency applications. The vendor base splits between consolidated defense-aerospace suppliers with captive testing laboratories and fragmented medical device converters facing multi-standard certification burdens. Two strategic archetypes predominate: vertically integrated material-science conglomerates controlling borosilicate glass and specialty alloy supply, and precision fabrication specialists leveraging regional cluster density. Competitive moves center on automated laser welding system deployment and direct qualification relationships with satellite constellation operators.
Among German material-science conglomerates, Schott AG exemplifies the vertically integrated archetype through its borosilicate glass expertise. Kyocera Corporation represents the ceramic-to-metal specialization vector from its Japanese manufacturing base. Materion Corporation occupies a position within North American specialty alloy supply for hermetic connectors. These three anchors illustrate how geographic concentration intersects with material-specific competitive positioning across the value chain.
| Leading Market Players |
|---|
| Schott AG |
| AMETEK |
| Amkor Technology |
| Materion Corporation |
| Texas Instruments Incorporated |
| Kyocera Corporation |
| NGK Spark Plug |
| Egide |
| Teledyne Technologies |
| Others |
Supply Flow & Price Mechanics
REACH hexavalent chromium authorization timelines gate qualified supply for European hermetic connector producers and anchor premium-tier pricing access for nickel-palladium-gold surface finishes serving medical device OEMs. Defense contractor vendor list consolidation compresses channel margins for unqualified Tier-two suppliers while rewarding captive testing laboratory investment with direct-to-OEM pricing power.
Pricing Analysis
Distributor margins for standard-grade ceramic-to-metal seals run thinner than direct-to-OEM contracts for aerospace-qualified metal enclosures. Three-tier pricing structure across aerospace-certified, medical-grade, and industrial-standard levels separates helium leak rate performance tiers. Pricing pressure stems from plastic moisture barrier substitution in cost-sensitive consumer electronics segments. Automotive Tier-1s demonstrate lowest price sensitivity for automotive lidar ceramic housings; commodity electronics assemblers drive hardest bargain.
Supply Chain Analysis
Domestic-content mandates in US satellite procurement reshape sourcing toward Ohio-based beryllium-copper suppliers and German precision glass-to-metal clusters. Raw material supply draws from Japanese borosilicate glass, US specialty alloys, and Chinese rare-earth ceramics. Single-source vulnerability concentrates in aging technician workforces for precision furnace operation. Distribution runs through specialized electronics and medical device component distributors carrying qualified converter inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through automated laser welding adoption compressing production costs while quantum computing sensor housing demand pulls premium ceramic-to-metal formats.
For Market Incumbents: Extend qualification relationships with satellite constellation operators before IEC 60068 certification pathways open to new entrants. Deepen backward integration into borosilicate glass or specialty alloy supply to offset REACH-driven material cost elevation. Lock in automated laser welding capacity ahead of technician scarcity tightening in Bavarian and Baden-Württemberg fabrication clusters. For New Entrants and Emerging Players: Capture wearable medical device composite package volumes where biocompatibility-weight tradeoffs favor ceramic-polymer hybrids over incumbent metal formats. Target Swiss and German glucose monitoring OEMs ahead of nickel-palladium-gold surface finish standardization. Lead with direct qualification partnerships bypassing distributor margin layers. For Investors and Strategic Acquirers: Roll-up economics work for precision fabrication specialists because defense contractor vendor list consolidation concentrates procurement authority among qualified suppliers with captive testing laboratories. Five-to-ten year viability hinges on quantum computing cryogenic housing demand scaling. Watch IEC 60068 space certification expansion as inflection signal for new entrant supply absorption.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Laser Welding Deployment | Stuttgart-area fabricators compress photonic enclosure lead times from weeks to days. |
| Nickel-Palladium-Gold Surface Finish Qualification | Swiss and German OEMs certify REACH-compliant chemistries ahead of aerospace contractors. |
| Cryogenic Sensor Housing Development | Ceramic-to-metal formats displace metal-dominated quantum computing research applications. |
| Captive Testing Laboratory Investment | Tier-two suppliers bypass distributor channels through direct satellite integrator relationships. |
| Automotive Lidar Ceramic Capacity Expansion | Nagoya-area producers recalibrate from telecommunications toward ADAS sensor volumes. |
Methodological Framework
Multiple input streams — primary interviews with hermetic seal fabrication engineers, biomedical device procurement managers, and satellite OEM supply chain directors; secondary validation through FDA 510(k) filings, EMA MDR technical documentation, IEC 60068 test standard evolution, and customs trade data for borosilicate glass and specialty alloy shipments — were reconciled through bottom-up and top-down triangulation.
Historical capacity utilization and panel-based demand signals were cross-referenced across the projection horizon. Segmentation dimensions modeled include material format, application sector, helium leak rate tier, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles and emerging application penetration curves, with quantum computing sensor housing demand and automotive lidar scaling as industry-specific volume drivers.
Regulatory timeline acceleration, raw material alloy availability disruptions, and defense procurement budget reallocation are the dominant revision risks. Forecasts reflect documented assumptions about REACH enforcement intensity and satellite constellation deployment schedules. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
Vacuum Skin Packaging Market
Packaging Solutions
India E-Commerce Packaging Market
Packaging Solutions
Temperature Controlled Packaging Solutions Market
Packaging Solutions
Strawless Lids Market
Packaging Solutions
Contract Packaging Market
Packaging Solutions
Custom Packaging Market
Packaging Solutions
Supplements and Nutrition Packaging Market
Packaging Solutions
Cohesive Packaging Solutions Market
Packaging Solutions
North America E-Commerce Packaging Market
Packaging Solutions
Global E-Commerce Packaging Market
Packaging Solutions
Korea E-Commerce Packaging Market
Packaging Solutions
Suspension and Retention Packaging Market
Packaging Solutions
Europe Contract Packaging Market
Packaging Solutions
CBD Product Packaging Market
Packaging Solutions
Decoys and Dispensers Market
Packaging Solutions
Global Bespoke Packaging Market