
 Consumer Packaging Market | 2026-2036
Consumer Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Consumer Packaging Market Analysis
E-commerce fulfillment channels is tilting procurement priorities toward damage-resistant formats and right-sized secondary packaging. Amcor leverages its global film and flexible packaging network to serve omnichannel brands with shelf-ready solutions. Berry Global sustains dominance in healthcare and food-grade thermoformed containers through vertical control over resin conversion.
Consumer packaging encompasses primary and secondary enclosures designed to protect, preserve, and present goods for retail sale, typically manufactured through blow molding, thermoforming, folding carton production, or flexible film extrusion with barrier properties measured in oxygen transmission rates and moisture vapor transmission rates. Its essential purpose spans containment, shelf-life extension, brand communication, and logistics efficiency across the value chain. Paper-based formats now lead volume in corrugated and folding carton segments as brand owners respond to recyclability mandates, while pouches represent the fastest-growing structural category driven by lightweighting and format versatility in beverages and personal care. Metal cans occupy a mature but defensible position in alcoholic beverages and ready-to-drink coffee, where oxygen exclusion and pasteurization compatibility preserve margin pools.
The EPA regulates municipal recycling streams and extended producer responsibility frameworks in the United States, while the EU Green Deal and REACH restrict certain plastic additives and mandate recycled content thresholds that reshape material specifications. China's SAMR enforces GB standards for food-contact materials that dictate migration limits and labeling requirements for both domestic and imported packaging. Stakeholders must monitor how fragmented national recycling infrastructure investments determine which material platforms achieve circularity compliance at competitive unit economics.
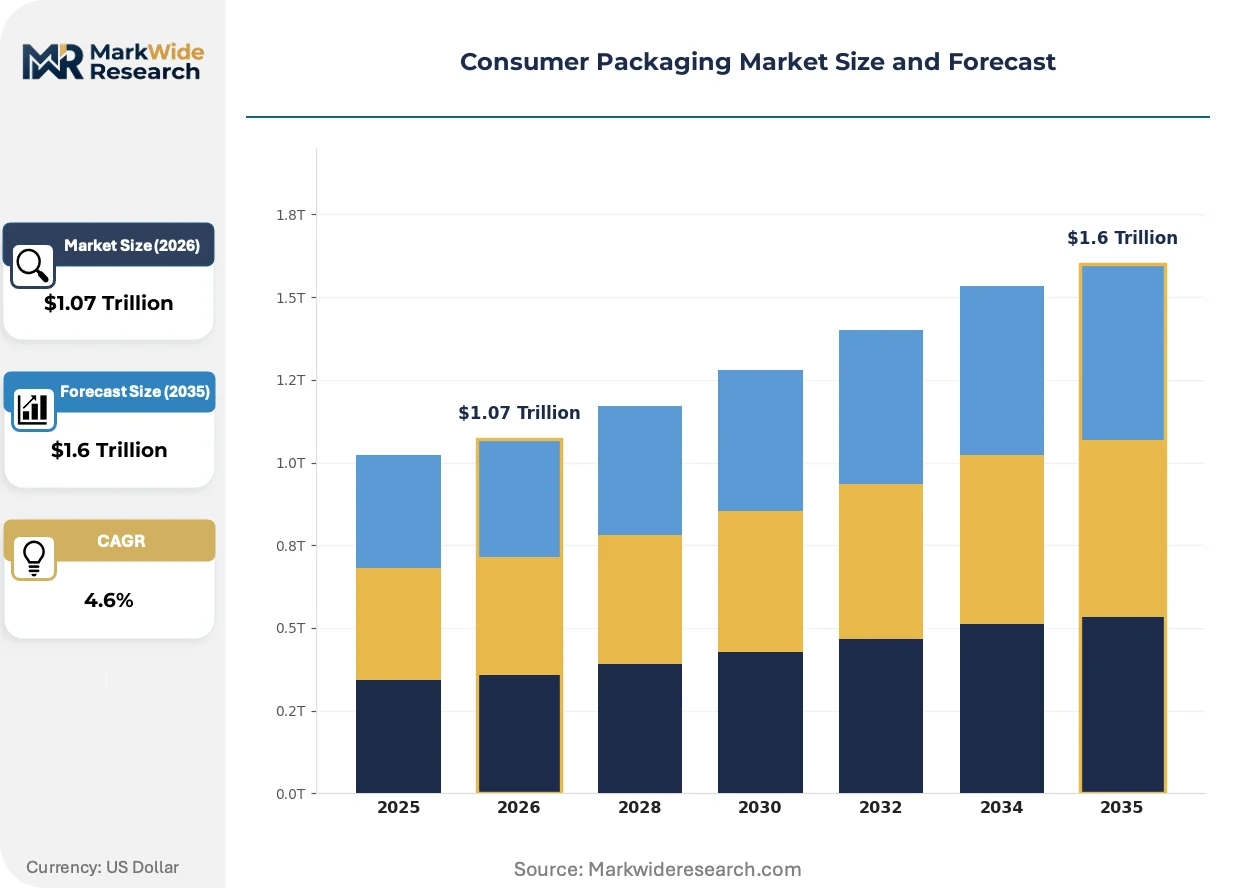
Market Dynamics
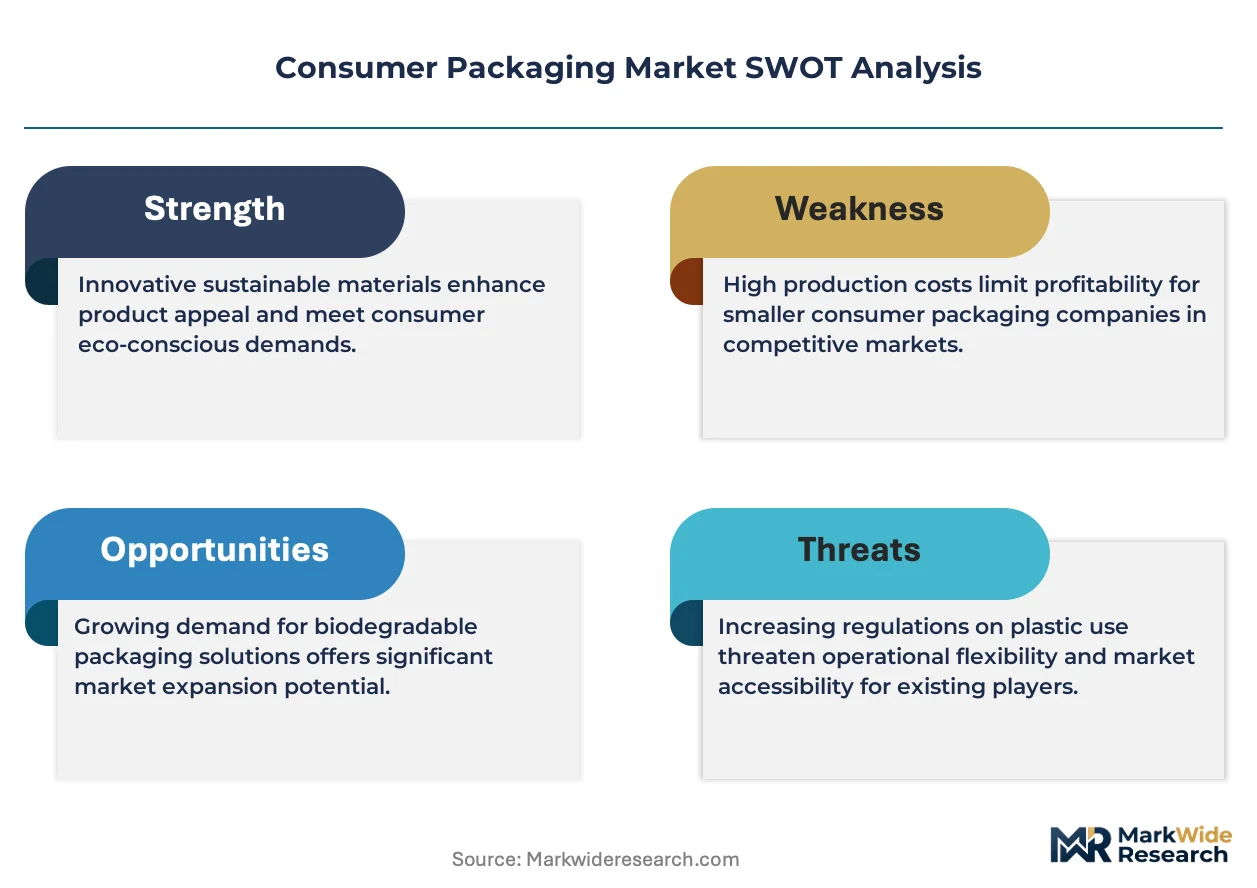
EU REACH compliance and single-use plastics directives are forcing material transitions toward fiber-based alternatives, reshaping supplier portfolios and capex allocation across the value chain.
Growth Catalysts
- E-commerce fulfillment surge:Protective formats for food and beverage shipments are expanding as direct-to-consumer channels require damage-resistant secondary packaging with optimized cube utilization.
- REACH chemical restrictions:The EU's additive prohibitions are accelerating migration to bio-based barrier coatings and mineral-filled thermoplastics in flexible film applications.
- China domestic consumption:Local brand expansion and procurement localization are concentrating demand within Chinese manufacturing clusters, reducing import dependency.
Market Restraints
- Resin price volatility:Fossil-based polymer feedstock costs fluctuate with crude oil benchmarks, compressing margins for converters lacking backward integration into resin production.
- Recycling infrastructure fragmentation:Inconsistent municipal sorting capabilities across US states limit circular material availability at scale, forcing reliance on virgin inputs.
- Barrier performance gaps:Fiber-based alternatives struggle to match oxygen transmission rates of metallized films in shelf-stable protein applications.
Strategic Opportunities
- India organized retail expansion:Modern trade penetration in tier-2 and tier-3 cities is creating demand for printed folding cartons and labeled flexible pouches previously served by loose formats.
- Extended Producer Responsibility frameworks:EU Green Deal implementation is creating compliance service markets for packaging data management and recyclability verification.
- Smart packaging convergence:Integration of printed electronics with thermoformed trays is enabling temperature logging and authentication in pharmaceutical cold chains.
Industry Challenges
- Migration testing bottlenecks:GB standards enforcement by China's SAMR requires extended laboratory validation timelines for imported food-contact materials, delaying market entry.
- Legacy equipment retooling:Converting from rigid to flexible formats demands extrusion line modifications and operator retraining that strain mid-tier converter balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumer Packaging Market |
| Market Size in 2026 | $1.07 Trillion |
| Market Size in 2035 | $1.6 Trillion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Cans, Boxes, Pouches Material: Plastic, Glass, Paper, Metal End User: Food, Beverages, Personal Care, Household Size: Small, Medium, Large, Bulk |
| Companies Covered | Ball Corporation, Berry Global, Amcor, Sealed Air, WestRock, International Paper, Crown Holdings, Smurfit Kappa, Smurfit Westrock, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumer Packaging Market Emerging Trajectories
Material science breakthroughs and regulatory chemistry restrictions are converging to redefine barrier performance standards and end-of-life pathways for consumer packaging formats.
Mono-material polyethylene structures are hybridizing multilayer barrier performance through advanced coextrusion and coating technologies. Beverage and personal care brands are accelerating adoption to meet recyclability claims without sacrificing shelf life. This convergence is compressing demand for legacy metallized laminates in mid-tier applications.
REACH authorization requirements for phthalate plasticizers and bisphenol-based coatings are eliminating incumbent chemistries from food-contact applications. Converters must reformulate adhesives and heat-seal layers to maintain compliance, raising R&D intensity. Flexible pouch segments in dairy and ready-meal categories face the steepest reformulation timelines.
Direct-store-delivery models are collapsing traditional distributor tiers in beverage and snack categories. Brand owners are consolidating secondary packaging specifications to reduce SKU complexity and warehouse handling costs. This consolidation is most visible in North American retail chains where private-label expansion intensifies price pressure on national brands.
Consumer Packaging Market Segmentation
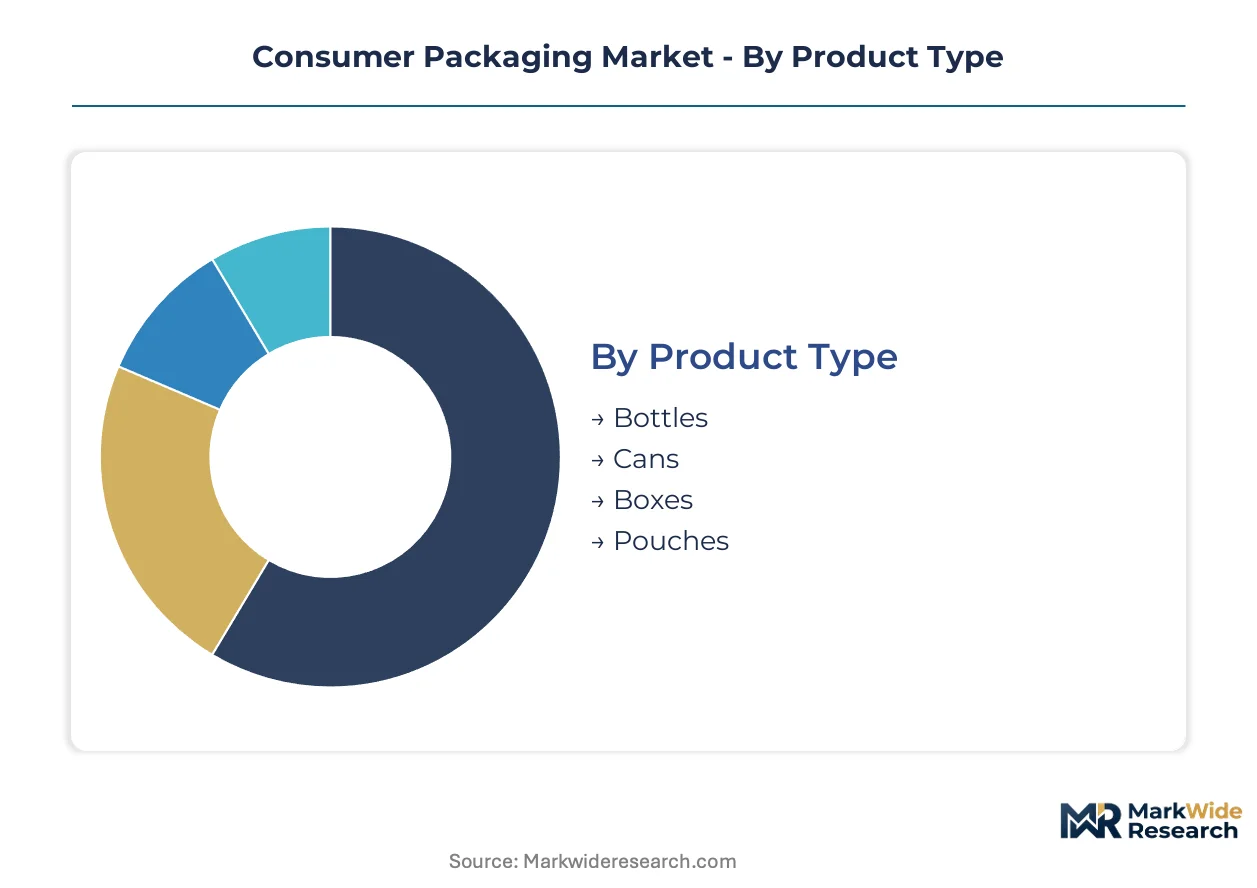
Consumer packaging formats diverge sharply across use-case requirements, from shelf-stable barrier performance to e-commerce durability. Material selection and structural geometry determine compliance pathways, recyclability claims, and logistics economics for brand owners.
Product Type:
Bottles dominate liquid containment across carbonated drinks, dairy, and personal care, while pouches capture share in lightweighting-sensitive categories.
- Bottles:Blow-molded PET and HDPE structures provide oxygen barrier and carbonation retention for beverages. Demand concentrates in North American CPG brands optimizing for conveyor-line compatibility and label adhesion performance.
- Pouches:Flexible multilayer films with spout fitments reduce material intensity versus rigid alternatives. Adoption accelerates in Chinese single-serve beverage and personal care sachets where logistics cube efficiency drives procurement.
- Cans:Two-piece aluminum and steel draw-redraw containers preserve flavor in alcoholic beverages and ready-to-drink coffee through absolute oxygen exclusion.
- Boxes:Folding cartons and corrugated cases serve secondary protection and shelf-ready presentation for dry goods and electronics.
Established volume favors bottles; emerging adoption favors pouches.
Material:
Cost tiers separate commodity feedstocks from performance-engineered substrates with specialized barrier properties.
- Plastic:Polyethylene, polypropylene, and PET films dominate flexible and rigid formats through tunable clarity, sealability, and moisture resistance. Regulatory pressure from EU REACH additive restrictions is forcing reformulation toward mineral-filled and bio-based alternatives.
- Paper:Kraft liners, folding boxboard, and molded fiber gain share as fiber-based replacements for single-use plastics in food service and dry goods. Recyclability mandates in EU member states accelerate capex allocation toward barrier-coated grades.
- Metal:Aluminum and tinplate occupy defensible positions in thermal processing and long shelf-life applications.
- Glass:Borosilicate and soda-lime containers preserve premium positioning in spirits and perfumery where inertness and aesthetics command price premiums.
Plastic retains volume leadership; paper climbs the fastest on sustainability-driven substitution.
End User:
Application requirements dictate barrier specifications, regulatory scrutiny intensity, and format innovation priorities.
- Food:Modified atmosphere packaging and vacuum skin formats extend protein and produce shelf life. Migration testing under China's GB standards creates entry barriers for imported flexible films.
- Beverages:Carbonation retention and UV protection drive material selection in beer, soft drinks, and functional waters. E-commerce fulfillment channels demand damage-resistant secondary packaging for direct-to-consumer shipments.
- Personal Care:Airless pumps and dispensing closures differentiate premium skincare through oxidation prevention and dosing precision.
- Household:Chemical resistance and child-resistant closures dominate cleaning product specifications.
Food commands absolute volume; beverages show steepest expansion trajectory from channel shift.
Size:
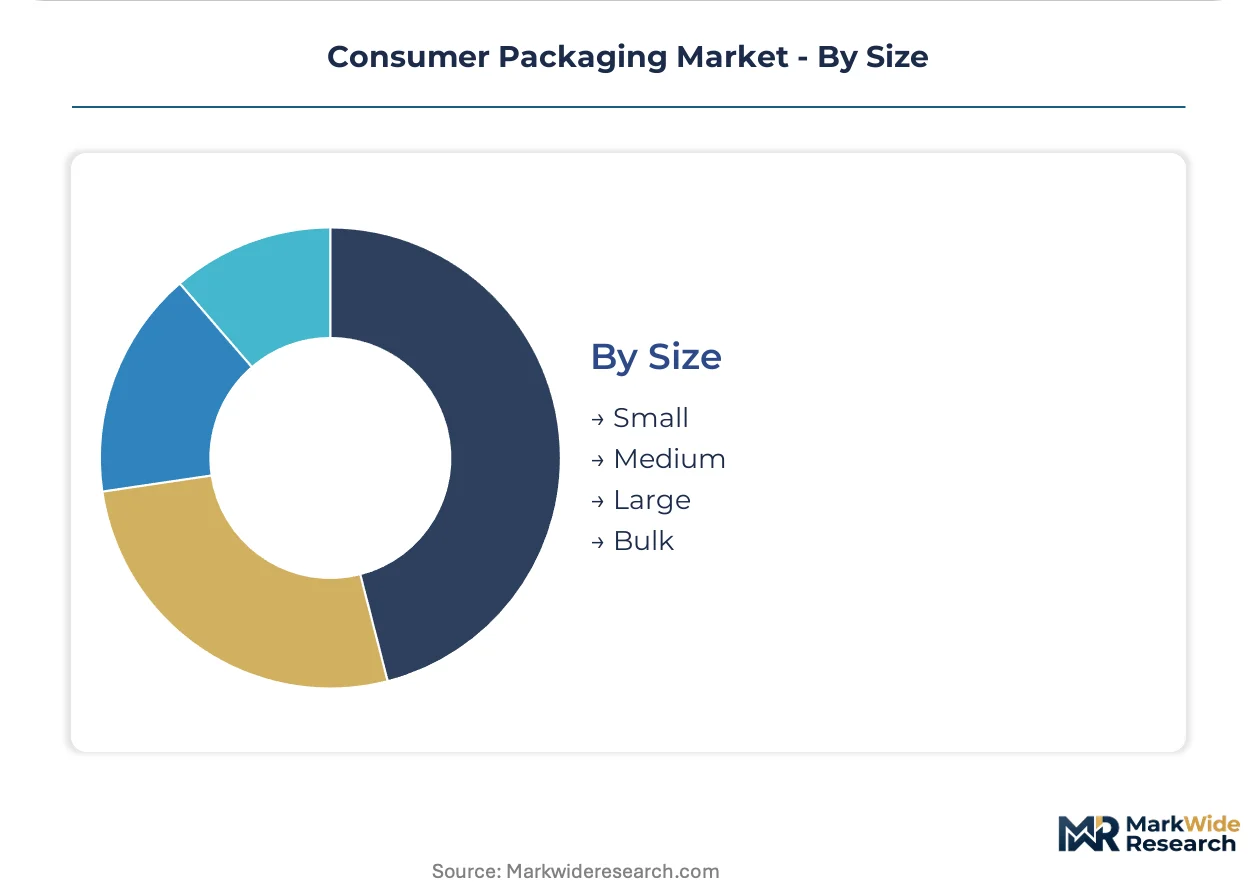
Volume scale determines equipment compatibility, retail slotting economics, and consumption occasion targeting.
- Small:Single-serve portions under 250ml target convenience and trial in on-the-go consumption. Travel-size personal care and beverage formats expand in airport retail and subscription sampling.
- Medium:Standard retail sizes from 250ml to 2 liters balance household consumption cycles with shelf space efficiency.
- Large:Club store and family formats reduce per-unit packaging intensity while requiring reinforced structural rigidity.
- Bulk:Industrial and foodservice formats prioritize cube utilization over aesthetics in B2B procurement.
Medium formats anchor retail economics; small sizes gain share fastest from convenience culture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's SAMR enforces GB standards that reshape procurement patterns across Asia-Pacific. The EPA and EU REACH create divergent compliance pathways in North America and Europe. Material substitution pressures concentrate investment in Germany, India, and the United States.
China
Domestic brand expansion drives demand for flexible pouches and folding cartons in tier-2 cities. SAMR's GB standards enforce migration limits that delay imported film approvals. Manufacturing clusters in Guangdong and Zhejiang provinces localize supply chains for beverage and personal care converters.
Germany
REACH chemical restrictions accelerate bio-based barrier coating adoption in dairy and ready-meal packaging. The EU Green Deal mandates recycled content thresholds that reshape converter capex allocation. Industrial concentration in North Rhine-Westphalia hosts thermoforming and extrusion specialists serving pan-European brand owners.
United States
E-commerce fulfillment channels expand demand for damage-resistant secondary formats in food and beverage shipments. EPA extended producer responsibility frameworks vary by state, fragmenting circular material availability. Converter networks in the Midwest and Southeast optimize for conveyor-line compatibility with major retail chains.
India
Organized retail penetration in tier-2 and tier-3 cities creates demand for printed folding cartons and labeled flexible pouches. FSSAI food-contact regulations align with BIS standards for imported packaging materials. Manufacturing corridors in Maharashtra and Gujarat attract investment in gravure printing and pouch converting capacity.
Japan
Premium positioning in spirits and cosmetics preserves glass and metal container demand. METI circular economy guidelines drive mono-material polyethylene adoption in convenience store formats. Converter expertise concentrates in the Kansai region around Osaka, serving pharmaceutical and food-grade specifications.
Consumer Packaging Market Vendor Landscape
Integrated multinationals and regional specialists split the market across material platforms and geographic coverage tiers. Consolidation pressure intensifies as converters seek scale to absorb resin price volatility and compliance costs. Three archetypes dominate: resin-integrated rigid format producers, film-flexible network operators, and fiber-based structural packaging specialists. Competitive moves center on backward integration into resin production and strategic partnerships for bio-based material sourcing.
Within the integrated multinational tier, Amcor and Berry Global exemplify divergent strategic positions. Amcor's global film and flexible packaging network serves omnichannel brands with shelf-ready solutions across multiple continents. Berry Global occupies a position in healthcare and food-grade thermoformed containers through captive supply of resin conversion. Sealed Air represents the protective packaging archetype, anchoring damage-resistant format development for e-commerce fulfillment channels.
| Leading Market Players |
|---|
| Ball Corporation |
| Berry Global |
| Amcor |
| Sealed Air |
| WestRock |
| International Paper |
| Crown Holdings |
| Smurfit Kappa |
| Smurfit Westrock |
| Others |
Supply Flow & Price Mechanics
Guangdong province's thermoforming and extrusion clusters feed downstream pricing power to converters serving pan-Asian beverage brands. Resin feedstock volatility and REACH compliance costs compress margins unevenly across rigid and flexible format producers.
Pricing Analysis
Price spreads between European and Chinese flexible film deliveries have widened as EU REACH additive restrictions force reformulation investments. Three-tier pricing structure across premium, standard, and economy levels separates barrier-coated fiber grades from commodity PE films and virgin resin-dependent rigid containers. Pricing pressure stems from fossil-based polymer feedstock volatility that squeezes converters lacking backward integration. Small and mid-tier brand owners exhibit highest price sensitivity, while pharmaceutical and premium personal care buyers absorb certification-driven premiums.
Supply Chain Analysis
Export-control regimes on advanced barrier coating technologies limit equipment and chemistry flows between EU specialists and Asian converters. Supply concentrates in China, Germany, and the United States, with manufacturing clusters in Zhejiang, North Rhine-Westphalia, and the American Midwest anchoring capacity. Raw material dependencies center on PE and PP resin, aluminum coil stock, and kraft pulp. Single-source vulnerability runs through Chinese resin production for non-integrated converters. Distribution runs through converter-direct relationships with multinational CPG brand owners and tiered distributor networks serving regional food and beverage processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where regulatory entrenchment creates durable advantages. Switching costs for food-contact certification and validated production lines lock in incumbent relationships.
For Market Incumbents: Insulate margin pools by deepening captive resin production and acquiring regional folding carton specialists in India's Maharashtra corridor. Berry Global's thermoforming dominance demonstrates how backward integration into resin conversion defends against feedstock volatility. Prioritize GB standards pre-certification for Chinese market access before SAMR enforcement tightens. For New Entrants and Emerging Players: Establish a beachhead in India's tier-2 organized retail expansion where printed folding carton demand outpaces local gravure capacity. Bio-based barrier coatings for dairy applications offer the most penetrable white space given REACH-driven incumbent reformulation timelines. Lead with FSSAI-compliant food-contact certification as a go-to-market differentiator against import-dependent competitors. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors mono-material PE specialists with coextrusion patent portfolios over legacy metallized laminate producers. Long-term viability hinges on circular material verification capabilities and EPR compliance service infrastructure. Watch for EU Green Deal recycled content threshold announcements as the inflection signal for converter capex reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive feedstock supply insulates Berry Global and Amcor from crude oil benchmark volatility. |
| Mono-Material PE Platform Investment | Advanced coextrusion patents enable recyclability claims without sacrificing oxygen barrier performance. |
| GB Standards Pre-Certification | SAMR migration testing compliance accelerates market entry ahead of import approval bottlenecks. |
| India Tier-2 Manufacturing Footprint | Gravure printing and pouch converting capacity in Maharashtra captures organized retail expansion demand. |
| EPR Compliance Service Development | Packaging data management and recyclability verification services monetize EU Green Deal implementation. |
Methodological Framework
A spread of perspectives from plant managers at extrusion facilities, procurement leads at beverage and dairy OEMs, distribution channel partners, and technical R&D directors converged on the working assumptions. Primary fieldwork combined with secondary validation from customs and trade data, SEC 10-K filings, ACC and Cefic industry reports, and national packaging association statistics. Bottom-up capacity modeling and top-down demand estimation triangulated volume figures across the analysis window.
Demand-supply balance dynamics anchored the analytical framework throughout the forecast period. Segmentation dimensions modeled include product type, material platform, end-use application, and geographic production hub. CAGRs derived from trend extrapolation of historical volume trajectories adjusted for regulatory inflection points. Industry-specific inputs incorporated EU REACH chemical restriction timelines and China's SAMR enforcement intensity for imported food-contact materials.
Sensitivities concentrate around resin price volatility, recycling infrastructure investment pace, and regulatory enforcement intensity in China and the EU. Forecasts reflect assumptions about continued e-commerce fulfillment expansion and fiber-based material substitution rates. Material shifts in EU Green Deal recycled content mandates or SAMR GB standards revision would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
Anti-Counterfeit Clothing Packaging Market
Packaging Solutions
Secondary Packaging Market
Packaging Solutions
India E-Commerce Packaging Market
Packaging Solutions
North America Child Resistant Packaging Market
Packaging Solutions
Korea E-Commerce Packaging Market
Packaging Solutions
Interior Packaging Market
Packaging Solutions
Promotional Packaging Market
Packaging Solutions
Single Dose Packaging Market
Packaging Solutions
Cohesive Packaging Solutions Market
Packaging Solutions
India Packaging Market
Packaging Solutions
Shelf Stable Packaging Market
Packaging Solutions
Global Packaging Market
Packaging Solutions
Custom Packaging Market
Packaging Solutions
Contract Packaging and Fulfillment Service Market
Packaging Solutions
Global Shelf Ready Packaging Market
Packaging Solutions
United Kingdom Packaging Market