
 Mexico Packaging Market | 2026-2036
Mexico Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Packaging Market Insights
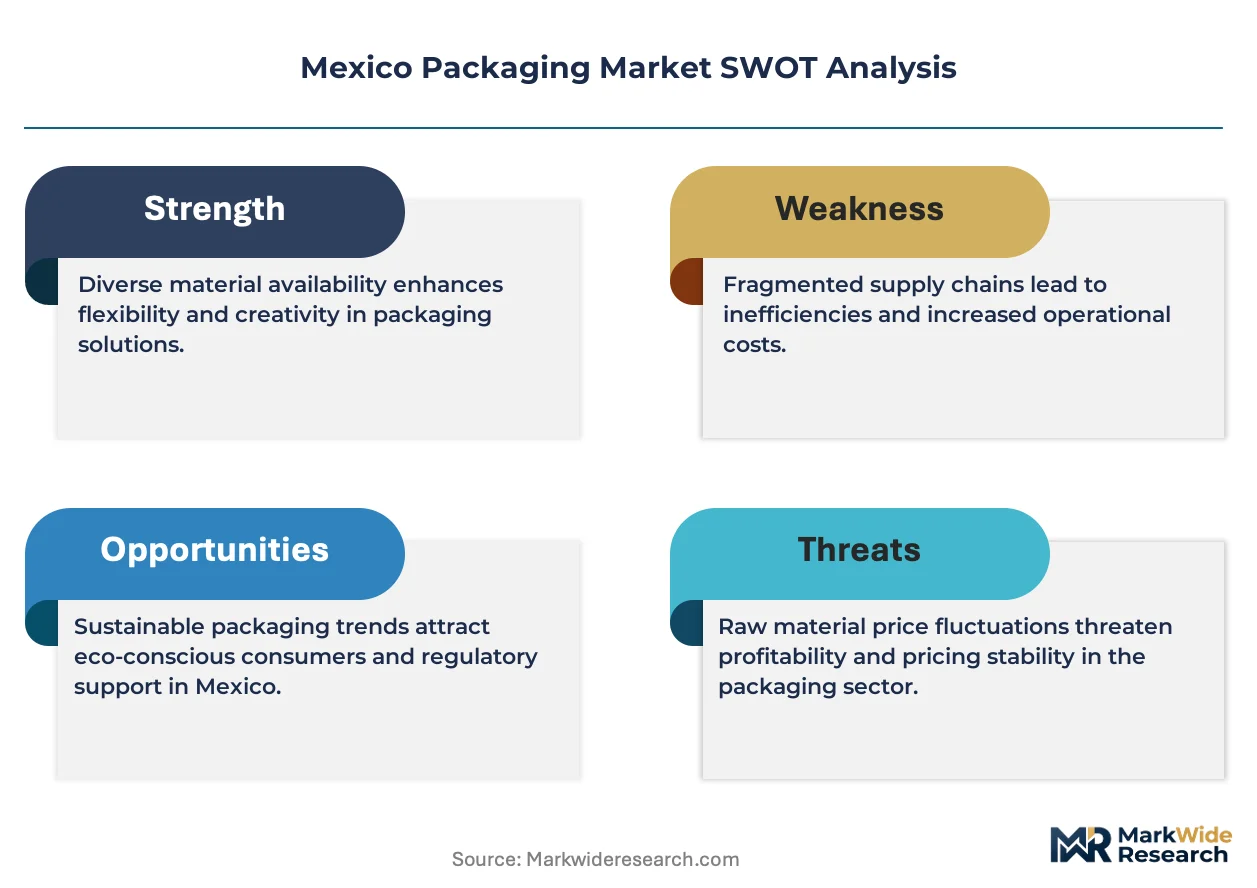
COFEPRIS food-contact material standards and PROFEPA environmental compliance rules are shifting the cost-of-entry calculus for new packaging suppliers. Grupo Gondi leverages its integrated pulp-to-box operations across Veracruz and Mexico State to sustain cost leadership in corrugated. Smurfit Kappa México anchors the northern market through its Monterrey recycling complex and high-volume beverage account base. Amcor competes via barrier film specialization for protein and dairy exports to the United States.
Packaging in Mexico encompasses material enclosures, protective structures, and information-bearing surfaces engineered from plastics, paper substrates, metals, or glass to contain, preserve, transport, and merchandise goods through industrial and consumer supply chains. Corrugated boxes dominate volume due to e-commerce fulfillment expansion and agricultural export requirements, while flexible packaging captures margin pools in snack foods and frozen produce through multi-layer barrier films. Rigid plastic containers lead pharmaceutical and personal care segments where COFEPRIS child-resistance and serialization mandates apply.
BIS-equivalent Mexican standards through CONAMER, PROFEPA waste-stream regulations, and state-level single-use plastic bans in Mexico City and Oaxaca shape material substitution timelines and recycling infrastructure investment. COFEPRIS updated food-contact notification requirements extend compliance burdens to imported packaging substrates. Stakeholders must monitor pending federal extended producer responsibility legislation and assess fiber-based alternatives before state deadlines cascade across additional Mexican jurisdictions.
Market Dynamics
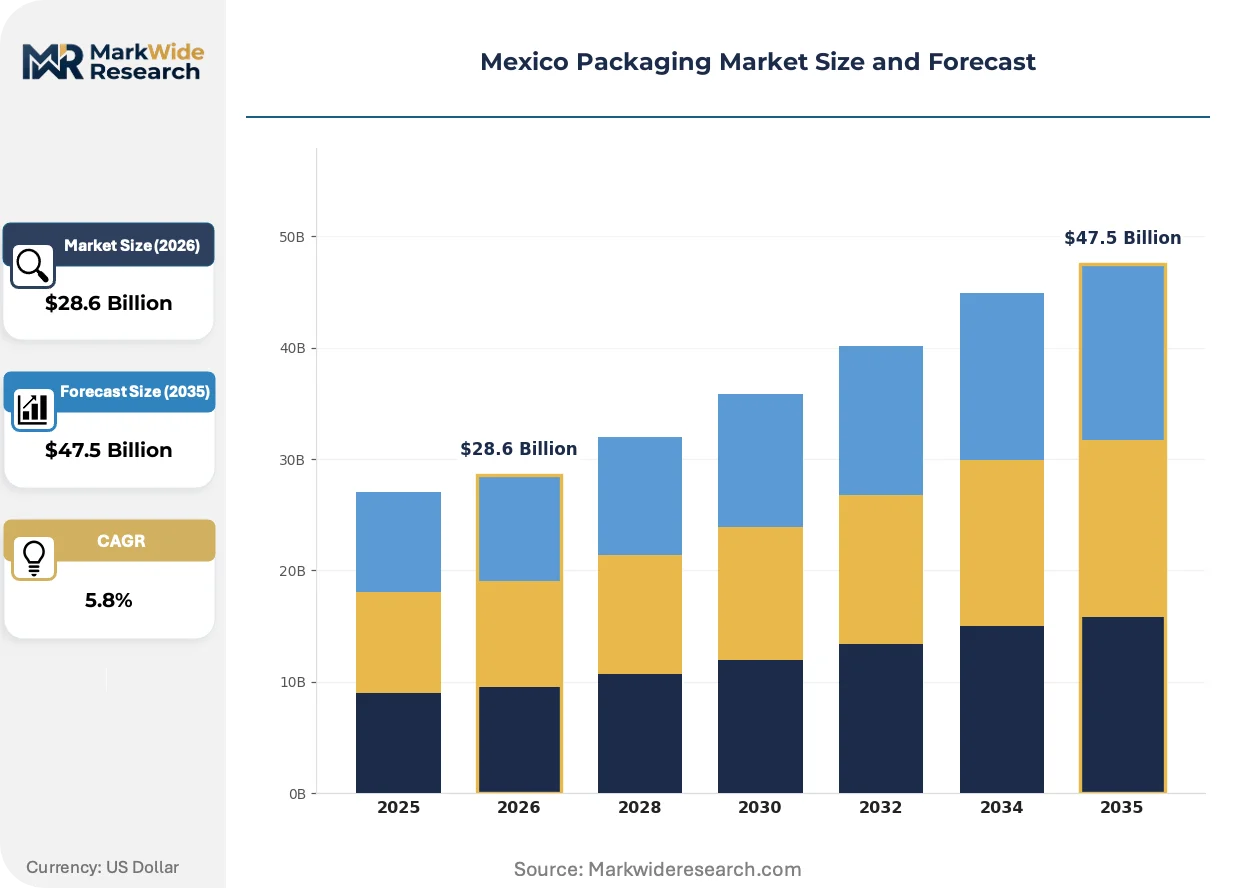
COFEPRIS food-contact notification requirements and PROFEPA waste-stream regulations are compressing supplier margins while accelerating material substitution timelines across Mexican packaging value chains.
Growth Catalysts
- PROFEPA environmental enforcement:State-level single-use plastic bans in Mexico City and Oaxaca are forcing brand owners toward fiber-based alternatives, opening procurement windows for domestic molded pulp suppliers.
- Bajío automotive corridor expansion:Tier-1 suppliers to Volkswagen and BMW assembly plants are scaling durable returnable packaging programs for precision component transit.
- Barrier film technology:Multi-layer coextrusion advances are enabling avocado and berry exporters in Jalisco to extend shelf life for US-bound shipments without cold-chain degradation.
Market Restraints
- Recycled fiber cost volatility:OCC (old corrugated containers) pricing swings tied to US export demand are squeezing converter margins in Monterrey and Mexico State.
- Resin import dependence:PE and PP pellet supply concentrates at Veracruz port terminals, exposing flexible film producers to peso-dollar exchange rate shocks and maritime delays.
- COFEPRIS notification timelines:Extended food-contact material approval cycles for imported substrates are delaying new product launches by multinational CPG brands.
Strategic Opportunities
- Michoacán fresh produce cluster:Protective packaging demand from avocado and berry packers is outpacing local converter capacity, creating entry points for specialized foam and molded fiber suppliers.
- Extended producer responsibility legislation:Pending federal EPR mandates will obligate brand owners to fund collection infrastructure, advantaging integrated recyclers with existing post-consumer networks.
- E-commerce fulfillment automation:Right-sized corrugated and paper-based void fill systems are displacing plastic air pillows in Mexico City and Guadalajara distribution centers.
Industry Challenges
- COFEPRIS serialization compliance:Pharmaceutical packagers must retrofit lines for track-and-trace codes by statutory deadlines, requiring capital outlays that mid-tier contract packers struggle to finance.
- Legacy equipment integration:Converters with 1990s-era flexographic presses face technical debt when retrofitting for water-based inks and thinner substrate gauges demanded by sustainability specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Packaging Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Packaging, Corrugated Boxes, Labels Material: Plastic, Paper, Metal, Glass End User: Food & Beverage, Pharmaceuticals, Cosmetics, Personal Care Distribution Channel: Online Retail, Supermarkets, Wholesale, Convenience Stores |
| Companies Covered | Grupo Gondi, Smurfit Kappa México, Amcor, Vitro, Tetra Pak, Sealed Air, Berry Global, Alpla, AptarGroup, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Packaging Market Trends and Innovations
Material science advances and regulatory pressure are converging to restructure Mexico's packaging supplier base, with fiber-based solutions and barrier coatings capturing investment previously directed toward conventional plastics.
Barrier-coated paperboard is absorbing volume from multi-layer plastic laminates in snack food and frozen produce applications. Grupo Bimbo and Sigma Alimentos are piloting grease-resistant mineral coatings for tortilla and prepared meal packaging. The technology is absorbing margin pools that previously accrued to PE film converters as brand owners face PROFEPA plastic reduction targets.
PROFEPA waste-stream regulations and Mexico City single-use plastic prohibitions are tightening enforcement timelines for foodservice operators. QSR chains and delivery platforms must eliminate PS foam and conventional plastic cutlery by municipal deadlines. Fresh produce exporters in Jalisco and Sinaloa are accelerating fiber tray adoption to preempt compliance disruptions in their largest domestic sales corridor.
Consolidated buying by OXXO, Walmart México, and Amazon México MX is compressing supplier negotiation cycles and unbundling legacy service components. Direct material sourcing through digital platforms is displacing distributor-mediated procurement for standard corrugated and flexible film specifications. The shift is most visible in Mexico State and Nuevo León, where large-format retail distribution centers are consolidating packaging specifications across private-label and national brand portfolios.
Mexico Packaging Market Segmentation
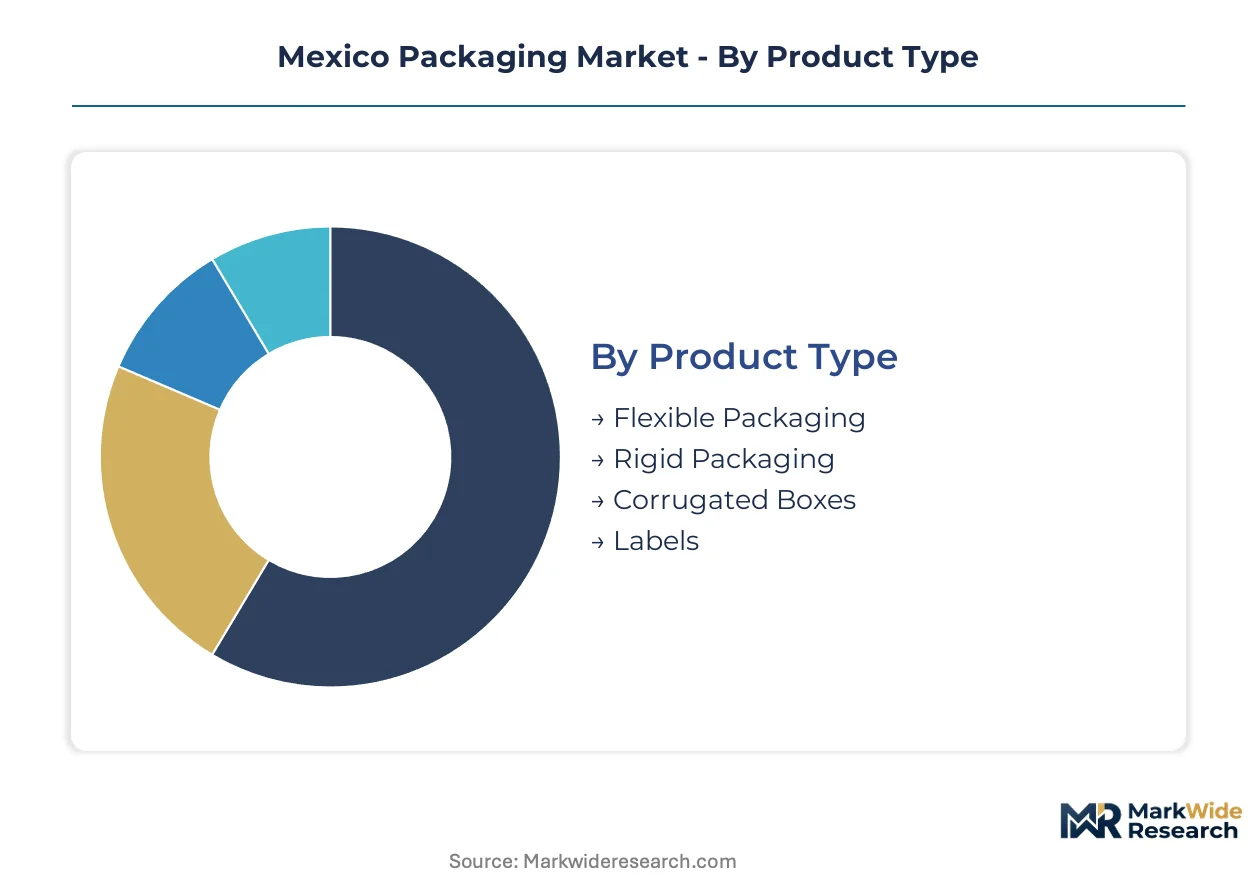
Mexico's packaging market fragments across regulatory boundaries that determine COFEPRIS notification burdens, PROFEPA waste-stream obligations, and state-level plastic prohibitions. Each segment carries distinct compliance costs and material substitution timelines that reshape supplier economics.
Product Type:
COFEPRIS food-contact notification requirements apply differentially across product categories, with flexible films facing the most complex multi-layer substrate approvals while corrugated benefits from grandfathered fiber standards.
- Flexible Packaging:Multi-layer coextruded films and laminated pouches incorporate EVOH or metallized barriers for oxygen and moisture resistance. Demand concentrates in Jalisco and Sinaloa berry packers extending shelf life for US export corridors, though resin import dependence at Veracruz terminals exposes converters to peso-dollar volatility.
- Corrugated Boxes:Fluted fiberboard structures range from single-wall B-flute to triple-wall heavy-duty configurations for automotive component transit. Bajío corridor Tier-1 suppliers to Volkswagen and BMW assembly plants are scaling returnable packaging programs that displace one-way shipping containers.
- Rigid Packaging:Injection-molded or thermoformed containers serve pharmaceutical serialization mandates and personal care dispensing functions. COFEPRIS child-resistance certification requirements limit qualified supplier pools for prescription drug formats.
- Labels:Pressure-sensitive, shrink-sleeve, and in-mold formats carry branding and regulatory information. Pharmaceutical track-and-trace serialization is forcing adhesive and substrate upgrades to accommodate 2D code legibility requirements.
Corrugated boxes sit at the top of the volume ranking, with flexible packaging climbing the fastest as barrier film technology penetrates fresh produce export applications.
Material:
Cost tier separation runs deepest in raw material sourcing, where integrated pulp-to-box operators command margin advantages over resin-dependent converters exposed to import pricing swings.
- Plastic:PE, PP, PET, and PS resins dominate flexible films, rigid containers, and foam protective formats. Veracruz port concentration for pellet imports creates supply vulnerability for Monterrey and Mexico State film extruders when maritime delays cascade through logistics networks.
- Paper:Kraft linerboard, corrugating medium, and molded pulp formats absorb volume from plastic substitution mandates in Mexico City and Oaxaca. OCC pricing volatility tied to US export demand squeezes converter margins during demand spikes in Q4 e-commerce fulfillment cycles.
- Metal:Aluminum and steel cans, aerosols, and closures serve beverage carbonation and pharmaceutical light-protection requirements. Two-piece aluminum can demand tracks Cervecería Modelo and Heineken México bottling line expansions in Yucatán and Chihuahua.
- Glass:Borosilicate and soda-lime containers lead premium spirits and pharmaceutical sterile packaging segments. Energy-intensive melting furnace operations concentrate in Guadalajara and Monterrey industrial corridors.
Paper materials command the widest volume base, with plastic formats facing steepest substitution pressure from PROFEPA enforcement timelines.
End User:
Application-specific performance requirements create margin stratification, with pharmaceutical serialization mandates supporting price premiums versus commodity foodservice formats facing plastic ban displacement.
- Food & Beverage:Spanning fresh produce export packaging, snack film laminates, beverage bottles, and QSR disposables. Grupo Bimbo and Sigma Alimentos pilot mineral-coated paperboard for tortilla and prepared meal formats to preempt Mexico City PS foam prohibitions.
- Pharmaceuticals:Blister packs, vials, ampoules, and compliance-prompting containers requiring COFEPRIS track-and-trace serialization. Retrofit capital requirements for line integration are filtering contract packer viability toward larger integrated players.
- Cosmetics:Airless pumps, premium glass, and decorative folding cartons serving brand differentiation objectives. Monterrey and Mexico State manufacturing clusters supply North American beauty brand regional distribution.
- Personal Care:Shampoo bottles, toothpaste tubes, and soap wrappers balancing shelf impact with PROFEPA plastic reduction targets. Flexible tube converters are accelerating laminate thinning and recyclable mono-material development.
Food and beverage applications anchor volume demand, with pharmaceutical packaging expanding most quickly on compliance-driven technology upgrades.
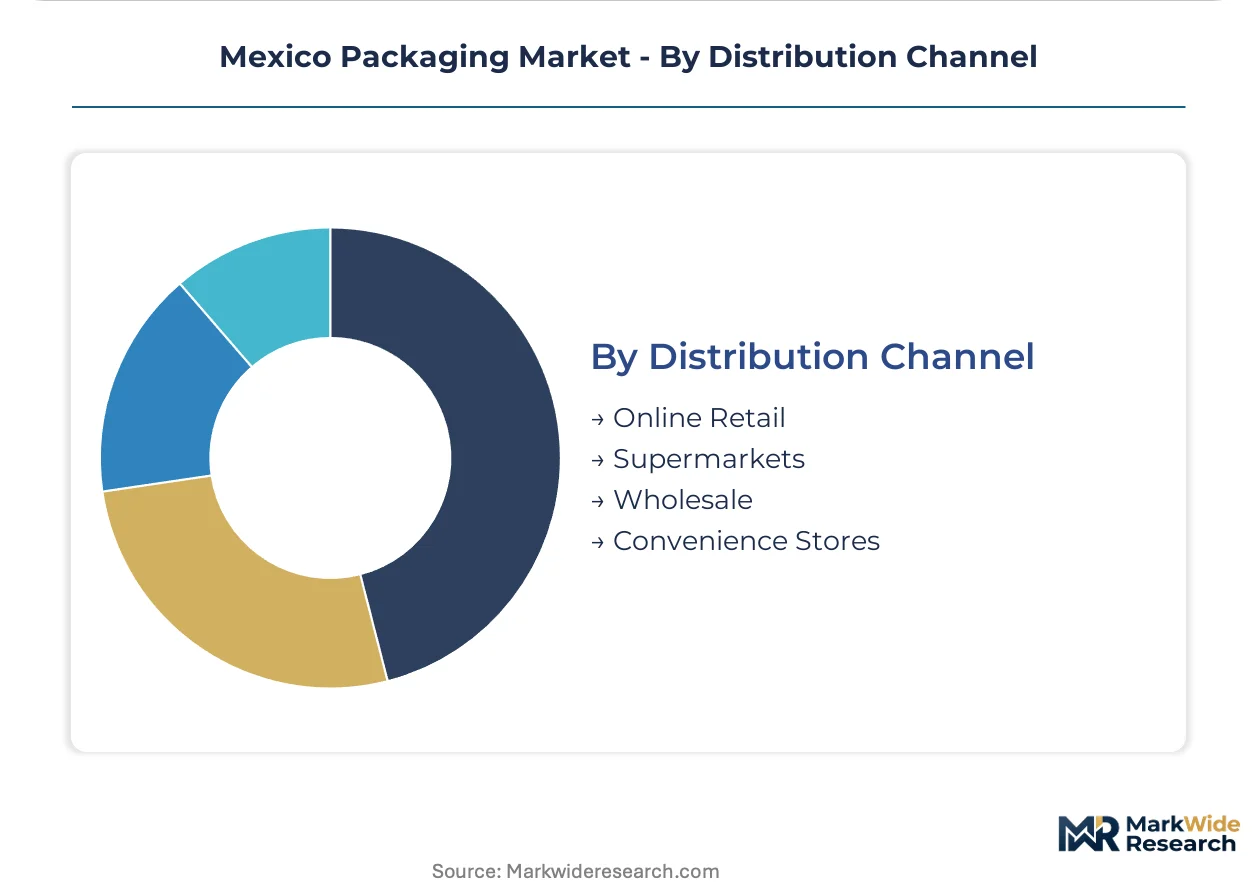
Distribution Channel:
Customer type concentration determines specification consolidation, with large-format retail and e-commerce platforms unbundling legacy distributor relationships in favor of direct material sourcing.
- Online Retail:Amazon México MX and Mercado Libre fulfillment centers drive right-sized corrugated and paper void fill specifications. Automation investments in Mexico City and Guadalajara distribution centers are displacing plastic air pillows with fiber-based alternatives.
- Supermarkets:Walmart México and Chedraui private-label consolidation is compressing supplier negotiation cycles and standardizing packaging specifications across national brand portfolios. Direct platform procurement is visible in Mexico State and Nuevo León distribution centers.
- Wholesale:Costco and Sam's Club bulk formats require heavy-duty corrugated and palletization systems. Club store pack specifications differ from retail multiples, requiring dedicated line configurations at converter plants.
- Convenience Stores:OXXO's consolidated buying power shapes single-serve beverage and snack packaging formats. Smaller case packs and shelf-ready displays predominate in this high-velocity, limited-shelf-space channel.
Supermarkets retain the largest volume position, with online retail gaining share fastest on fulfillment automation investment cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled packaging technicians and corrugated machine operators concentrate in Mexico's industrial corridors, anchoring regional production capacity across multiple manufacturing clusters.
Nuevo León
Automotive Tier-1 suppliers to KIA and Tesla suppliers drive durable transit packaging demand. PROFEPA enforcement timelines for industrial waste streams are tightening compliance requirements. Monterrey's recycling complex anchors northern Mexico's corrugated supply chain for beverage and industrial accounts.
Jalisco
Avocado and berry exporters require extended-shelf-life barrier films for US-bound shipments. COFEPRIS updated food-contact notification rules are extending substrate approval cycles. Guadalajara's packaging converter cluster is scaling protective foam and molded fiber capacity for fresh produce packers.
Bajío Region
Volkswagen and BMW assembly plants are scaling returnable packaging programs for precision component transit. State environmental agencies are aligning with federal PROFEPA waste-stream regulations. Querétaro and Guanajuato industrial parks house dedicated automotive packaging lines for just-in-sequence delivery.
Mexico City Metro
E-commerce fulfillment centers for Amazon México MX and Mercado Libre are automating right-sized corrugated specifications. Municipal single-use plastic bans are forcing QSR chains toward fiber-based alternatives. Toluca and Cuautitlán distribution hubs are displacing plastic void fill with paper-based systems.
Veracruz
PE and PP resin imports through port terminals supply flexible film extruders statewide. The country's national environmental regulator is monitoring marine plastic leakage from packaging waste streams. The port city's logistics infrastructure exposes inland converters to maritime delay risks and currency volatility.
Mexico Packaging Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Mexico's packaging value chain. The supplier base fragments along material lines, with integrated fiber operators commanding cost advantages over resin-dependent converters. Three archetypes dominate: multinational barrier film specialists, regional corrugated converters with captive recycling networks, and rigid container manufacturers serving pharmaceutical serialization mandates. Competitive moves center on backward integration into raw material sourcing and geographic expansion into produce-export corridors.
Among integrated fiber operators, Grupo Gondi exemplifies the pulp-to-box archetype with Veracruz and Mexico State manufacturing presence. Smurfit Kappa México occupies a position within the northern corrugated tier, while Amcor represents multinational barrier film specialization for protein and dairy export applications. These three anchors illustrate divergent strategic postures across material substrates and end-use concentrations.
| Leading Market Players |
|---|
| Grupo Gondi |
| Smurfit Kappa México |
| Amcor |
| Vitro |
| Tetra Pak |
| Sealed Air |
| Berry Global |
| Alpla |
| AptarGroup |
| Others |
Pricing and Supply Chain Analysis
Barrier-coated paperboard substitution for multi-layer plastic laminates is compressing converter margins while redistributing pricing power toward integrated pulp-to-box operators with captive fiber supply. This production-method transition simultaneously raises capital thresholds for new entrants and rewards backward-integrated incumbents who control OCC sourcing networks across Veracruz and Mexico State.
Pricing Analysis
The bundled-vs-unbundled service split defines competitive pricing, with legacy distributors losing ground to direct platform procurement by Walmart México and Amazon México MX. Three-tier pricing structure across premium, standard, and economy levels separates COFEPRIS-certified pharmaceutical formats from commodity foodservice disposables. Cost compression in corrugated runs through OCC pricing volatility tied to US export demand spikes. Small-format fresh produce packers in Michoacán exhibit highest price sensitivity, while pharmaceutical contract packers absorb premiums for serialization compliance.
Supply Chain Analysis
Direct-to-converter channels handle hyperscale demand from OXXO and Chedraui, while distributor-mediated procurement persists for mid-tier regional brands. Geographic supply concentration centers on Mexico for corrugated fiberboard, the United States for specialty barrier films, and China for PE/PP resin pellets feeding Veracruz port terminals. Raw material dependencies include OCC bales, metallized film substrates, and imported polymer resins. Single-source vulnerability at Veracruz port exposes inland converters to maritime delay cascades and peso-dollar exchange rate shocks. Distribution runs through integrated recycler networks in Monterrey and Mexico City metro hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in fiber-based substitution plays, where COFEPRIS compliance burdens and PROFEPA enforcement timelines reward operators with integrated pulp supply and pre-approved substrate libraries.
For Market Incumbents: Deploy captive OCC sourcing networks to defend corrugated margin position against resin-dependent flexible film converters facing peso volatility. Accelerate barrier-coated paperboard R&D to capture snack food laminate volumes before Mexico City PS foam prohibitions cascade statewide. Consolidate molding capacity in Jalisco to serve avocado exporter protective packaging demand outpacing local supply. For New Entrants and Emerging Players: Capture white-space in Michoacán molded fiber tray supply, where berry packer demand exceeds regional converter capacity by measurable margin. Target pharmaceutical serialization retrofit services for mid-tier contract packers unable to finance COFEPRIS track-and-trace line upgrades independently. Pursue partnership routes with Bajío automotive Tier-1 suppliers seeking durable returnable packaging program partners. For Investors and Strategic Acquirers: Valuations sit cheapest among regional corrugated converters lacking vertical integration into recycling networks, presenting rollup candidates for fiber supply security. Long-term viability favors integrated operators with PROFEPA-compliant post-consumer collection infrastructure ahead of federal EPR legislation. Monitor pending extended producer responsibility bill progression through CONAMER as inflection signal for recycling asset repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into OCC Recycling | Grupo Gondi's captive fiber supply anchors cost leadership against resin-exposed competitors. |
| Barrier-Coated Paperboard Scale-Up | Grupo Bimbo's mineral coating pilots preempt PROFEPA plastic reduction targets in prepared meals. |
| Automotive Returnable Packaging Programs | Bajío corridor Volkswagen and BMW suppliers displace one-way containers with precision transit formats. |
| Pharmaceutical Serialization Line Retrofit | COFEPRIS track-and-trace mandates filter contract packer viability toward capitalized integrated players. |
| Direct Platform Procurement Expansion | Amazon México MX and Mercado Libre unbundle distributor relationships for standard corrugated specifications. |
Research Methodology
Multiple input streams — converter production data, brand owner procurement patterns, and regulatory filing documentation — were reconciled across primary interviews with corrugated plant managers, flexible film procurement leads at CPG brands, PROFEPA compliance officers, and automotive Tier-1 packaging engineers. Secondary validation drew from CONAMER regulatory databases, COFEPRIS food-contact notification records, customs trade statistics for resin imports through Veracruz, and SEC filings of multinational packaging parents. Bottom-up volume builds by substrate and end-use were cross-checked against top-down market sizing through triangulation.
Historical volume trajectories were cross-referenced against expert panel inputs to establish growth assumptions across the analysis window. Segmentation dimensions modeled include material substrate, product format, end-use industry, geographic production cluster, and COFEPRIS compliance tier. CAGRs were derived from slope analysis of normalized historical data applied to structural demand drivers. Forecast inputs incorporated e-commerce fulfillment automation penetration rates, state-level plastic prohibition rollout schedules, and automotive assembly plant capacity additions in the Bajío corridor.
Regulatory enforcement intensity, resin import disruption events, and EPR legislation passage delays are the dominant revision risks to modeled outputs. Forecasts reflect base-case assumptions regarding PROFEPA timeline adherence and currency stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
Packaging Solutions Market
Packaging Solutions
North America Child Resistant Packaging Market
Packaging Solutions
India Packaging Market
Packaging Solutions
Global Coding and Marking Solutions Market
Packaging Solutions
Hermetic Packaging Market
Packaging Solutions
Package Drop Box Market
Packaging Solutions
North America Secondary Packaging Market
Packaging Solutions
Promotional Packaging Market
Packaging Solutions
Portable UV Sanitizing Boxes Market
Packaging Solutions
Topical Dispenser Market
Packaging Solutions
Korea E-Commerce Packaging Market
Packaging Solutions
Global Peel and Reseal Packaging Market
Packaging Solutions
Custom Packaging Market
Packaging Solutions
Contract Packaging Market
Packaging Solutions
Global Lithium Ion Battery Packaging Solutions Market
Packaging Solutions
Contract Packaging and Fulfillment Service Market