
 Exterior Automotive Plastics Market | 2026-2036
Exterior Automotive Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Exterior Automotive Plastics Market Intelligence
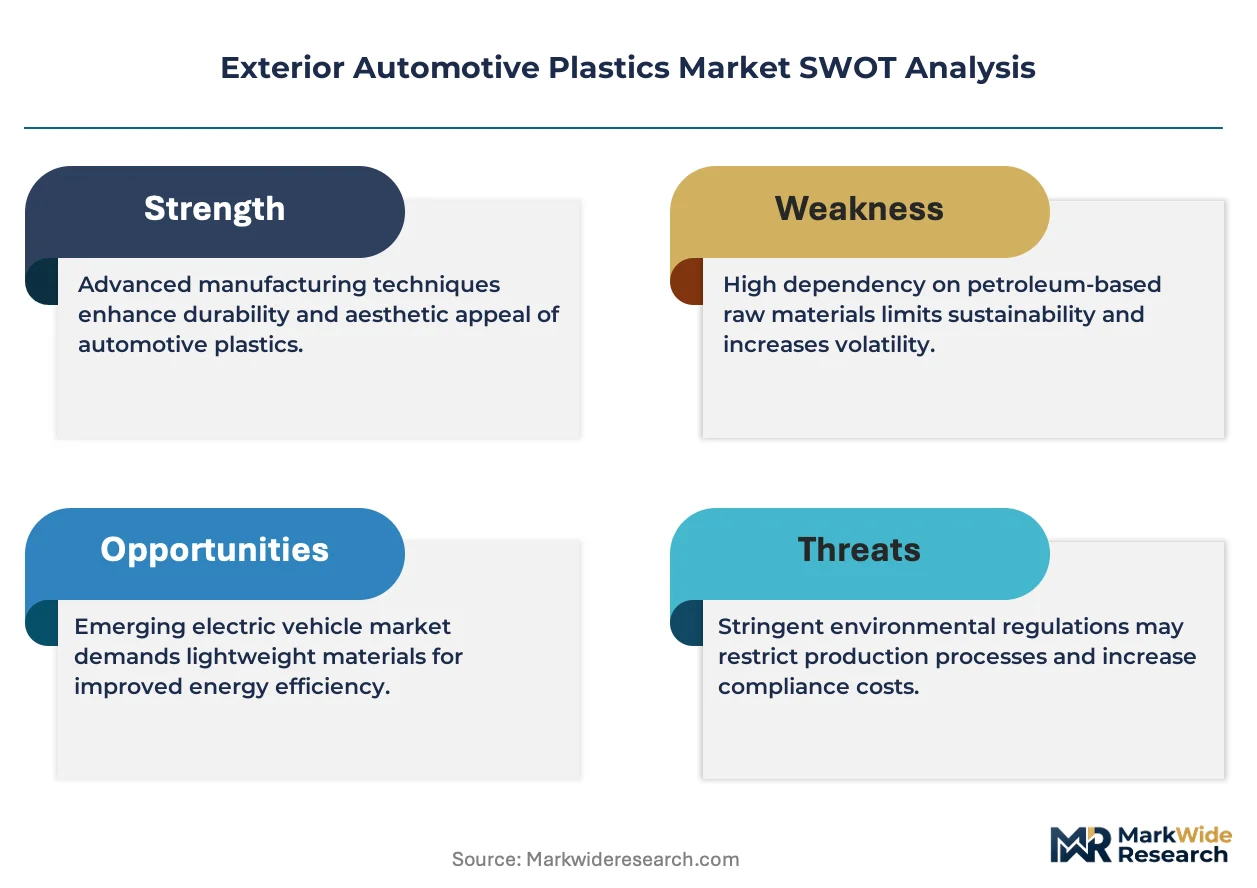
The EU Green Deal is expanding the addressable market for recycled and bio-based exterior plastics as European OEMs face binding fleet emissions ceilings. BASF SE leverages its integrated polymer research infrastructure to develop certified sustainable polypropylene grades for bumper systems. Covestro AG anchors its competitive position through specialized polycarbonate blends engineered for mirror housings and glazing applications. LyondellBasell Industries competes on manufacturing scale, operating dedicated compounding assets across multiple European production corridors.
Exterior automotive plastics comprise engineered thermoplastics and thermosets molded into structural and aesthetic vehicle body components, typically formulated with fillers, stabilizers, and colorants to achieve impact resistance, UV durability, and Class-A surface finish. Injection molding dominates high-volume production of bumpers and door panels due to dimensional precision and cycle efficiency. Polypropylene leads by installed volume across bumper and fender applications, while polycarbonate gains share in transparent and semi-transparent lighting enclosures where optical clarity and thermal stability command premium positioning. Polyurethane retains structural importance in energy-absorbing bumper cores and fascia substrates where energy management properties justify material cost.
EMA maintains active oversight of chemical migration limits from automotive interior and exterior materials through REACH compliance protocols, while the EU F-Gas Regulation indirectly shapes polymer selection by restricting blowing agents used in polyurethane foam production. OEMs must navigate CE marking requirements for aftermarket body components alongside type-approval standards administered by KBA in Germany and national transport authorities across member states. Stakeholders should monitor evolving end-of-life vehicle directives that will mandate minimum recycled content thresholds in exterior applications.
Market Dynamics
Electric vehicle platform architectures are forcing a wholesale redesign of exterior body-in-white strategies, with polymer-intensive modular assemblies displacing traditional steel stampings in closure panels and structural skins. OEMs now specify thermoplastic composites for hoods, liftgates, and fenders to offset battery pack mass, creating cascading demand for high-flow polypropylene grades and fiber-reinforced compounds.
Growth Catalysts
- EU Green Deal fleet emissions ceilings:Binding CO2 targets for 2030 compel European OEMs to adopt lightweight exterior polymers, expanding specification volumes for bumper fascias and aerodynamic addenda.
- Battery-electric platform proliferation:Dedicated BEV architectures from Volkswagen, Stellantis, and Hyundai-Kia integrate polymer-intensive front and rear modules to maximize range efficiency.
- Injection molding cycle efficiency:Advanced hot-runner systems and in-mold labeling reduce unit costs for Class-A body panels, accelerating substitution in high-volume nameplates.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracking economics and regional refinery utilization swings transmit directly to polypropylene compound pricing, compressing processor margins.
- Tooling capex intensity:Large-tonnage injection molds for bumper systems require 12-18 month lead times and seven-figure capital commitments, freezing out mid-tier suppliers.
- REACH chemical migration protocols:ECHA substance restrictions on plasticizers and flame retardants force reformulation cycles that delay platform approvals by 6-9 months.
Strategic Opportunities
- Post-industrial recycled content mandates:End-of-life vehicle directives will require minimum recycled polymer thresholds in exterior applications, favoring compounders with mechanical recycling integration.
- Structural battery enclosure integration:Thermoplastic composite load floors and underbody shields represent unpenetrated volume as cell-to-pack designs proliferate.
- Digital twin-enabled mold flow optimization:Convergence of CAE simulation and real-time cavity pressure sensing reduces warpage defects and accelerates time-to-production for new exterior programs.
Industry Challenges
- Color-matching complexity across suppliers:Metallic and effect pigments in Class-A finishes require spectrophotometric alignment across multiple compounding sites, creating batch-to-batch variation risks.
- Paint shop thermal compatibility:E-coat bake cycles at 180-200°C demand heat-stabilized polymer grades that maintain dimensional tolerance through OEM corrosion protection processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Exterior Automotive Plastics Market |
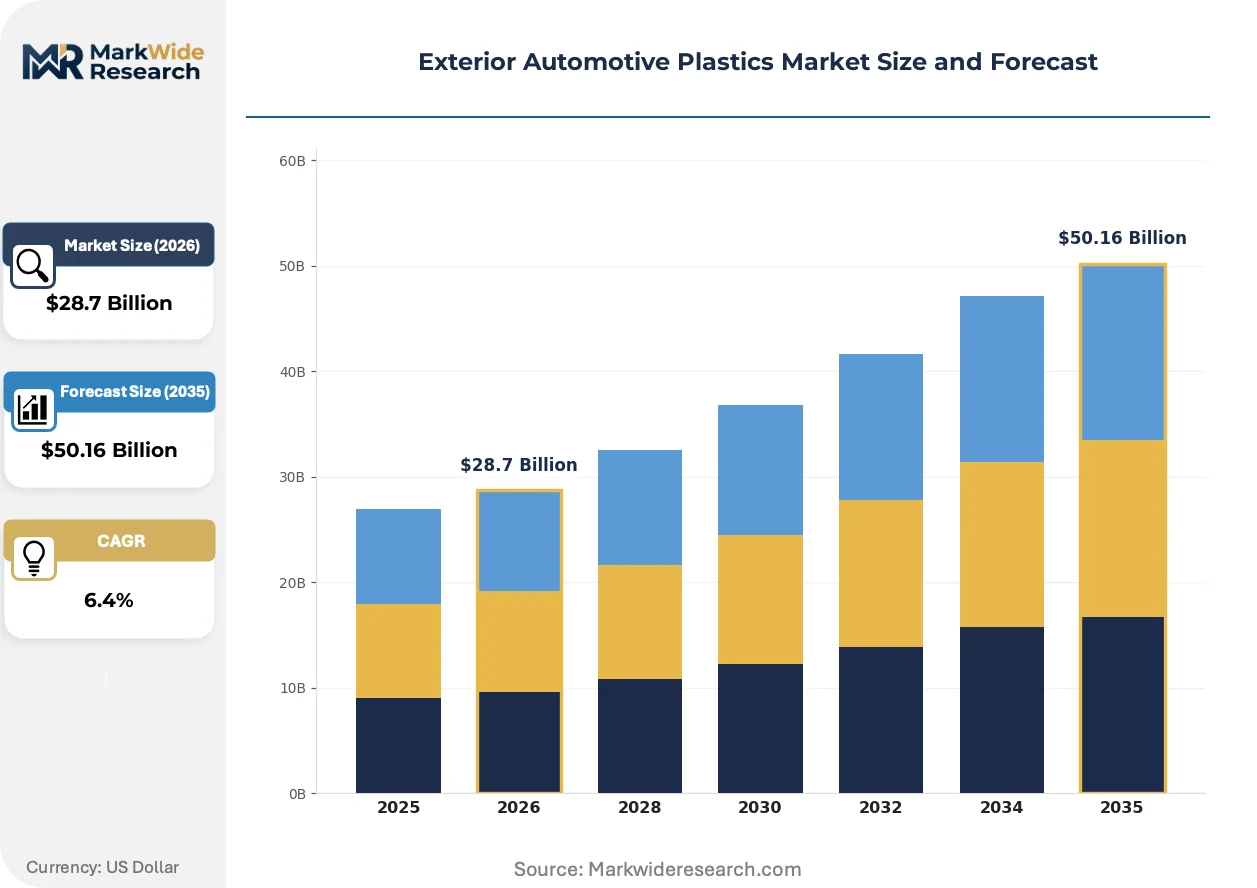
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $50.16 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polyurethane, Acrylonitrile Butadiene Styrene, Polycarbonate, Polyethylene Terephthalate, Polyvinyl Chloride Application: Bumpers, Door Panels, Mirror Housings, Grilles, Roof Racks, Wheel Covers Technology: Injection Molding, Blow Molding, Thermoforming, Extrusion, Compression Molding, Rotational Molding End User Industry: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Plastic Omnium, Saudi Basic Industries Corporation, BASF SE, Dow Inc., DuPont de Nemours, Covestro AG, Celanese Corporation, LyondellBasell Industries, Magna International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Exterior Automotive Plastics Market Strategic Shifts & Innovations
Material-to-digital integration is compressing development cycles for exterior polymer systems, with virtual validation replacing physical prototype iterations. Three convergent developments are restructuring competitive positioning.
Long-fiber thermoplastic (LFT) direct compounding is modularizing how structural exterior components are manufactured. Tier-1 suppliers including Magna and Plastic Omnium are adopting in-line extrusion-compression systems for underbody shields and seatback panels. This process consolidation eliminates pellet inventory and enables real-time fiber length optimization, collapsing logistics costs for geographically distributed assembly plants.
REACH authorization requirements for persistent organic pollutants are tightening specifications for flame-retardant additives in EV battery proximity zones. ECHA's 2023 restriction proposals on halogenated compounds are forcing migrations to phosphorus-nitrogen systems in wheel arch liners and underbody covers. German OEMs through the VDA are coordinating pre-approval testing pools to share substance safety data and accelerate alternative certifications.
Automotive styling studios are consolidating supplier relationships around full-module integrators capable of delivering painted, assembled bumper systems rather than discrete components. Tier-1 procurement patterns now favor compounders with captive painting capacity and Class-A surface expertise over raw material specialists. This preference shift concentrates specification authority in North American and European supply corridors where integrated manufacturing assets cluster.
Exterior Automotive Plastics Market Segmentation
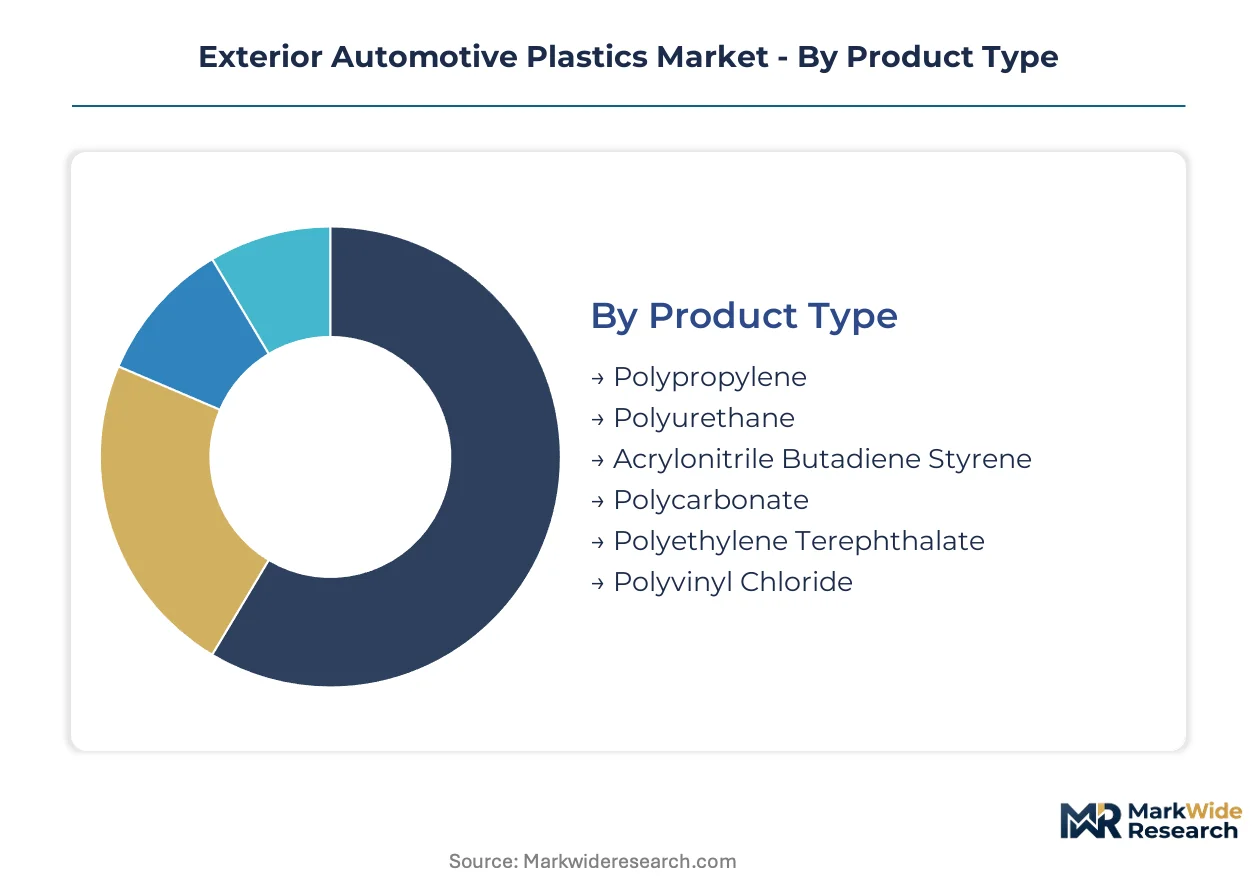
Material specification and processing technology choices in exterior automotive plastics cascade through tooling investment, cycle economics, and regulatory compliance. Segmentation clarity enables suppliers to align compounding assets with OEM platform roadmaps and emerging lightweighting mandates.
Product Type:
Polymer selection pivots on thermal stability, impact resistance, and surface finish requirements specific to each exterior component class.
- Polypropylene:High-flow grades with talc or glass reinforcement dominate bumper fascias and fender liners due to low density and paint adhesion. German OEMs specify this resin for battery-electric front modules where mass reduction offsets pack weight.
- Polyurethane:Energy-absorbing bumper cores and structural foam substrates rely on rigid PU systems for pedestrian safety compliance. REACH F-Gas restrictions on blowing agents are forcing reformulation toward water-blown alternatives in European production.
- Acrylonitrile Butadiene Styrene:Grille assemblies and decorative trim exploit ABS for chrome-plated finishes and dimensional stability.
- Polycarbonate:Optical-grade PC penetrates headlamp lenses and transparent roof panels where UV resistance and clarity command specification.
- Polyethylene Terephthalate:PET compounds serve wheel covers and aerodynamic underbody shields with cost-positioned performance.
- Polyvinyl Chloride:Flexible PVC formulations retain niche presence in side body cladding and protective molding strips.
Polypropylene leads on scale; polycarbonate gains share fastest through lighting and glazing penetration.
Application:
Component function dictates material grade, surface class, and assembly integration complexity across vehicle architectures.
- Bumpers:Multi-material assemblies combining PP fascia, PU core, and steel beam represent the highest-value exterior polymer application. BEV platforms are extending bumper depth for aerodynamic efficiency and sensor integration.
- Door Panels:Injection-molded PP with in-mold film inserts deliver Class-A finish without post-painting. Stellantis and Volkswagen are consolidating door module suppliers to reduce assembly plant complexity.
- Mirror Housings:PC-ABS blends and painted PP compete for side-view camera enclosures where thermal management and signal transparency matter.
- Grilles:Active shutter systems in EVs require thermally stable polymers that maintain dimensional tolerance across -40°C to 120°C operating ranges.
- Roof Racks:Glass-filled nylon and reinforced PP serve load-bearing crossbar attachments with UV-stabilized weathering performance.
- Wheel Covers:Aero-optimized full-wheel discs in BEVs use recycled-content PP to meet emerging EU recycled material mandates.
Bumpers concentrate revenue; wheel covers expand most quickly through aero-driven BEV specification.
Technology:
Process selection locks in capital intensity, cycle time, and geometric capability for each component category.
- Injection Molding:High-pressure clamping with hot-runner systems enables thin-wall bumper fascias and complex grille geometries at sub-60-second cycles. Magna and Plastic Omnium operate 4,000-ton presses across European corridors.
- Blow Molding:Fuel tank and fluid reservoir production exploits extrusion blow molding for hollow-section strength-to-weight ratios.
- Thermoforming:Vacuum and pressure forming serve low-volume roof and hood panels where tooling cost must stay below injection mold thresholds.
- Extrusion:Profile extrusion generates sealing systems and decorative strips with continuous length efficiency.
- Compression Molding:Sheet molding compound and bulk molding compound processes produce structural Class-A panels for low-volume sports vehicles.
- Rotational Molding:Hollow wheel covers and tank assemblies leverage rotomolding for stress-free wall thickness distribution.
Injection molding dominates throughput; compression molding holds margin in specialized low-volume segments.
End User Industry:
Customer type determines specification authority, contract structure, and technical service intensity.
- OEMs:Volkswagen, Stellantis, and Hyundai-Kia retain direct material approval authority for visible exterior components. Their platform engineering teams specify resin grades, color standards, and recycled content thresholds.
- Tier-1 Suppliers:Plastic Omnium, Magna, and Yanfeng purchase compounds against OEM specifications and manage painting, assembly, and sequencing to vehicle plants.
- Aftermarket Providers:Independent distributors serve collision repair and customization markets with color-matched components requiring CE marking for EU road legality.
- Vehicle Assemblers:Contract manufacturers and specialty EV startups procure pre-painted module assemblies rather than discrete resin volumes.
Tier-1 suppliers intermediate the largest compound volumes; vehicle assemblers represent the steepest expansion trajectory among emerging EV entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered thermoplastic automotive body panels through Volkswagen's early adoption of polymer bumpers in the 1980s, establishing the technical foundation that now spreads across battery-electric platforms worldwide.
Germany
Volkswagen, BMW, and Mercedes-Benz specify lightweight polypropylene front modules for their dedicated BEV architectures to offset battery mass. KBA administers type-approval standards that mandate pedestrian safety compliance in bumper systems. The Stuttgart-Munich corridor hosts BASF SE and Covestro AG research centers where sustainable polymer grades undergo OEM qualification testing.
United States
Ford and General Motors expand thermoplastic composite hood and liftgate programs across F-150 Lightning and Silverado EV lineups. NHTSA crashworthiness protocols shape energy-absorbing bumper core specifications. Detroit-Warren manufacturing clusters concentrate injection molding capacity for high-volume truck platforms.
China
BYD and NIO integrate polymer-intensive exterior modules into cell-to-pack platform designs to maximize range efficiency. MIIT new energy vehicle mandates accelerate lightweight material substitution in closure panels. Yangtze River Delta industrial zones host compounders supplying Shanghai-based EV assemblers with certified recycled-content grades.
Japan
Toyota and Honda specify polycarbonate glazing and lighting enclosures for their next-generation electric crossovers. METI carbon neutrality roadmaps pressure suppliers to develop bio-based polymer alternatives. Nagoya-centered automotive supplier networks coordinate just-in-time compound delivery to assembly plants.
South Korea
Hyundai-Kia deploy polymer structural skins across E-GMP platform variants including Ioniq 5 and EV6. MFDS chemical safety assessments align with REACH-equivalent substance restrictions for export compliance. Busan-Ulsan petrochemical corridors supply high-flow polypropylene compounds to Gwangju and Asan vehicle plants.
Exterior Automotive Plastics Market Key Industry Players
Premium-margin players sit above commodity-margin players across formulation complexity and OEM qualification depth, with compounders commanding specification authority for Class-A visible components while resin merchants compete on volume throughput. The vendor base organizes into three strategic archetypes: integrated petrochemical giants with captive compounding assets, specialized polymer compounders with OEM-approved color labs, and full-module integrators managing painting and assembly. Dominant competitive moves include backward integration into mechanical recycling streams and strategic partnerships with BEV platform engineering teams.
Among European-based material science conglomerates, BASF SE and Covestro AG exemplify the integrated research archetype, anchoring competitive positioning through certified sustainable grades and specialized optical polymers respectively. LyondellBasell Industries occupies the manufacturing scale tier with dedicated compounding corridors serving high-volume bumper programs.
| Leading Market Players |
|---|
| Plastic Omnium |
| Saudi Basic Industries Corporation |
| BASF SE |
| Dow Inc. |
| DuPont de Nemours |
| Covestro AG |
| Celanese Corporation |
| LyondellBasell Industries |
| Magna International |
| Others |
Cost & Logistics Intelligence
Certified sustainable grade premiums versus commodity polypropylene pricing creates a bifurcation that propagates through both compounder margins and raw material sourcing strategies. REACH compliance costs and recycled content thresholds in Germany force specification upgrades that reshape procurement patterns across European automotive corridors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs exterior automotive plastics, with OEM qualification status and recycled content certification as the primary price differentiation drivers. Cost compression in commodity polypropylene compounds is intensifying because naphtha-cracking economics transmit volatility directly from refinery utilization swings. Tier-1 suppliers with captive painting capacity show the least price sensitivity, while aftermarket distributors serving collision repair markets face acute margin pressure.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for bumper and fascia programs, with compounders operating dedicated assets across Germany, China, and South Korea. Raw material flows draw from propylene monomer streams, glass fiber reinforcements, and specialty additive packages. Single-source vulnerability concentrates around talc mining operations in specific European deposits. Distribution runs through just-in-time sequencing hubs positioned adjacent to vehicle assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Exterior automotive plastics function as a stable compounder, with battery-electric platform proliferation providing durable volume expansion across multiple OEM portfolios.
For Market Incumbents: Cement specification authority by deepening backward integration into mechanical recycling streams and securing captive supply of post-industrial polypropylene feedstocks. Defend against emerging Asian compounders by accelerating REACH-compliant sustainable grade certifications ahead of EU Green Deal enforcement timelines. For New Entrants and Emerging Players: The mid-tier pricing gap between BASF-certified sustainable grades and commodity imports offers entry traction for regional European compounders with qualified color-matching capabilities. Target aftermarket collision repair distributors in Germany and France with pre-painted module assemblies that bypass OEM direct-approval barriers. Pursue white-label partnerships with Tier-1 integrators lacking captive compounding assets. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale compounders lack the capital intensity for large-tonnage injection mold partnerships with BEV platform engineering teams. Five-to-ten-year viability favors specialists with integrated mechanical recycling and Class-A surface expertise over pure resin merchants. Watch for inflection when EU end-of-life vehicle directives mandate specific recycled content thresholds in exterior applications.| Strategic Initiative | Industry Significance |
|---|---|
| Mechanical Recycling Integration | Secures post-industrial feedstock streams for EU Green Deal compliance. |
| Long-term Supply Agreement | Locks in polypropylene volumes with Volkswagen and Stellantis BEV platforms. |
| Joint Venture | Combines Covestro optical polymer expertise with Tier-1 painting capacity. |
| Capacity Expansion | Adds compounding lines in Busan-Ulsan corridor to serve Hyundai-Kia E-GMP demand. |
| Green Manufacturing Transition | Replaces halogenated flame retardants with phosphorus-nitrogen systems for REACH alignment. |
Research Approach
Coverage spans Germany, United States, China, Japan, and South Korea, with primary inputs from each automotive production cluster. The analysis combines interviews with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and technical R&D directors at compounders, validated against secondary sources including vehicle production databases, IHS Markit registration data, SEC filings from listed material suppliers, and customs trade records. Bottom-up volume modeling and top-down market sizing triangulate to consistent outputs.
Granularity-level modeling operates at the intersection of polymer grade, vehicle propulsion architecture, and regional production hub. Segmentation dimensions include material type, application component, processing technology, and end-user industry tier. CAGRs derive from regression analysis of historical content-per-vehicle trends and OEM platform rollout schedules across the projection horizon. Specific inputs include battery-electric vehicle production forecasts and EU regulatory compliance timeline assumptions.
Caveats apply where propylene feedstock volatility or REACH substance restriction expansions could materially shift the outlook for compounder margin structures. Forecasts reflect assumptions about BEV platform adoption rates and recycled content mandate enforcement. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Liftgate Market
Automotive Interior & Exterior
Automotive Dashboard Market
Automotive Interior & Exterior
Car Door Latch Market
Automotive Interior & Exterior
Automotive Plastic Interior Trims Market
Automotive Interior & Exterior
Automotive Automatic Liftgate Market
Automotive Interior & Exterior
Automotive Air Purifier Market
Automotive Interior & Exterior
Glazing for Automotive Market
Automotive Interior & Exterior
Glove Box Market
Automotive Interior & Exterior
Glass for Electric Vehicle Glass Roof Market
Automotive Interior & Exterior
Automotive Exterior LED Lighting Market
Automotive Interior & Exterior
Decorative Car Accessories Market
Automotive Interior & Exterior
Automotive Drawer Slides Market
Automotive Interior & Exterior
Blind Spot Mirror Market
Automotive Interior & Exterior
Global Automotive Tinted Window Pane Market
Automotive Interior & Exterior
Argentina Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
France Automotive Adaptive Lighting System Market