
 Europe Automotive Upholstery Market | 2026-2036
Europe Automotive Upholstery Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive Upholstery Market Foresight
European seating component manufacturing is restructuring around stricter carbon-accounting requirements for interior materials. Adient PLC leverages its integrated foam-to-fabric operations across multiple EU assembly corridors. Faurecia sustains competitive pressure through dedicated hydrogen-powered vehicle interior programs. Lear Corporation anchors its regional position with just-in-sequence delivery networks serving German premium OEMs.
Automotive upholstery encompasses the layered material systems—typically comprising substrate fabrics, foam cushioning, and surface coverings such as leather, fabric, vinyl, or Alcantara—that form vehicle seats, headliners, door panels, and interior trim, engineered to meet fire-resistance standards and ergonomic durability cycles. Leather commands the highest value per square meter among material categories, though Alcantara gains specification share in performance-oriented SUV and sedan variants. OEM direct sourcing dominates the end-user channel structure, while aftermarket providers occupy fragmented regional niches concentrated in Southern European restoration markets.
REACH regulation and the EU Green Deal shape material compliance pathways, with ECHA substance restrictions progressively limiting chrome-tanning chemistry and certain phthalate plasticizers in vinyl formulations. CE marking requirements under the EU's Construction Products Regulation, alongside EMA automotive-specific guidance on interior emissions, constrain supplier qualification timelines. Stakeholders must monitor evolving bio-based certification standards and battery-electric vehicle thermal-management demands that alter foam density and breathability specifications.
Market Dynamics
REACH chemical restrictions and the EU Green Deal are forcing material substitution across European automotive upholstery supply chains, compressing procurement timelines for petroleum-based vinyls while accelerating bio-based polyurethane qualification programs.
Growth Catalysts
- Bio-based polyurethane specification:Premium electric vehicle seating programs in Germany and France are expanding procurement of sustainable synthetic leather alternatives. OEM sustainability mandates drive material innovation cycles.
- REACH regulatory pressure:ECHA substance restrictions progressively limit chrome-tanning chemistry and certain phthalate plasticizers. Compliance deadlines compress supplier transition windows.
- Bavarian cluster concentration:Germany's automotive upholstery specification activity remains the densest in Europe. Tier-1 supplier engineering centers co-locate with OEM headquarters.
Market Restraints
- Petrochemical input volatility:Crude oil price fluctuations directly impact polyurethane foam and synthetic leather cost structures. Margin compression limits R&D reinvestment capacity.
- Chrome-tanning chemistry phase-out:ECHA restrictions on hexavalent chromium eliminate established leather processing pathways. Alternative tanning technologies require capital-intensive retooling.
- Alcantara supply concentration:Single-source dependency for premium suede alternatives in performance vehicle segments creates procurement vulnerability.
Strategic Opportunities
- French hydrogen vehicle interior programs:Faurecia's dedicated hydrogen-powered vehicle initiatives create new upholstery thermal-management specifications. Foam density and breathability requirements diverge from conventional powertrains.
- EMA automotive interior emissions guidance:Stricter cabin air quality standards advantage suppliers with pre-certified low-VOC material portfolios. First-movers capture specification lock-in.
- Southern European restoration aftermarket:Fragmented regional niches in Italy and Spain remain underpenetrated by organized suppliers. Classic vehicle upholstery represents service revenue expansion.
Industry Challenges
- Bio-based certification complexity:Evolving EU sustainability verification standards delay supplier qualification timelines. Multiple competing certification frameworks create compliance fragmentation.
- Battery-electric thermal management adaptation:Foam density and breathability specifications require re-engineering for EV cabin heating profiles. Legacy combustion-vehicle material portfolios face technical obsolescence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive Upholstery Market |
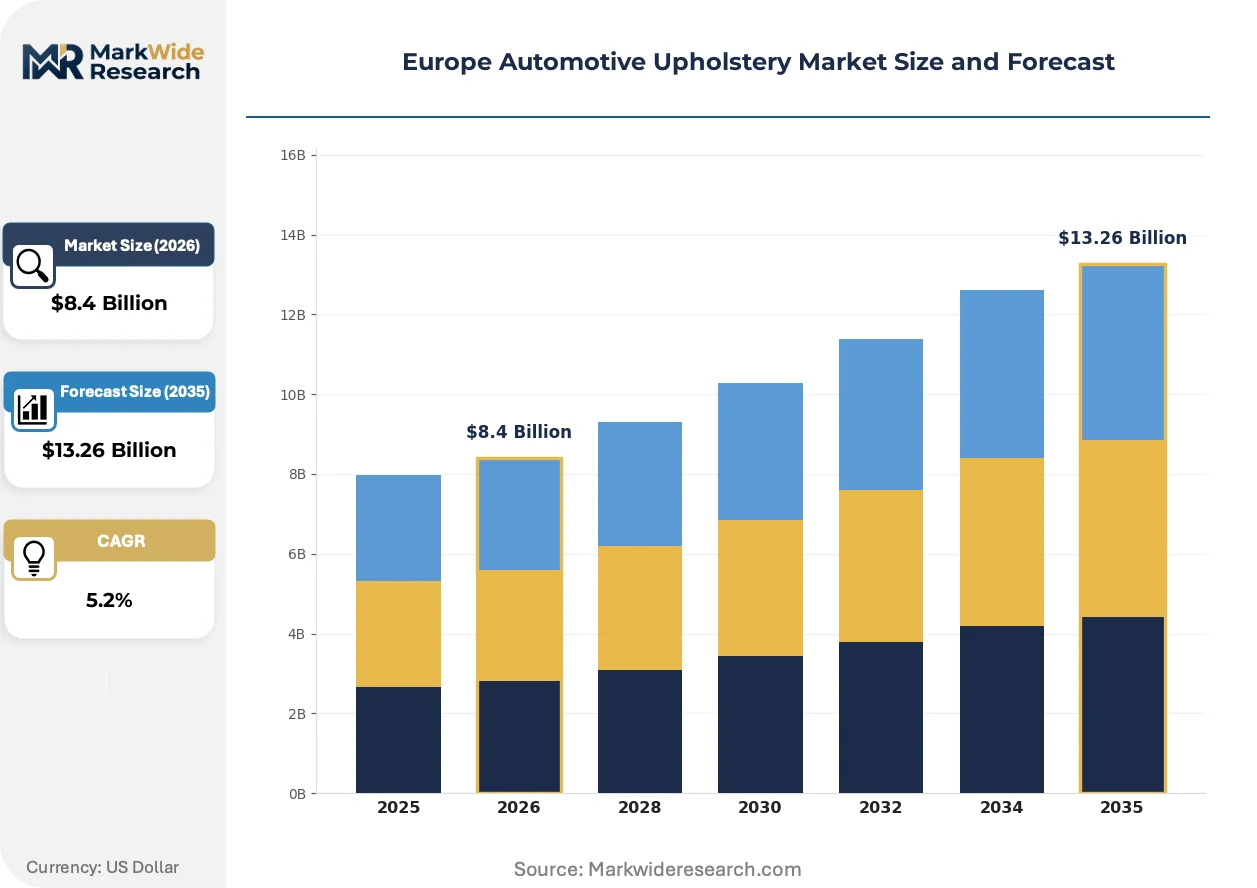
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.26 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Leather, Fabric, Vinyl, Alcantara Vehicle Type: SUVs, Sedans, Hatchbacks, Trucks End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Dealerships Design Style: Sporty, Luxury, Vintage, Modern |
| Companies Covered | Adient PLC, Grupo Antolin, Faurecia, Lear Corporation, Forvia SE, Toyota Boshoku Corporation, Woodbridge Foam Corporation, BASF SE, Freudenberg SE, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive Upholstery Market Shifts & Advancements
Material science convergence with regulatory compliance is reshaping European automotive upholstery development priorities, with sustainability certification and thermal performance emerging as dual specification gatekeepers.
Plant-derived polyurethane foam formulations are expanding into premium electric vehicle seating programs across German and French OEM lineups. Tier-1 suppliers accelerate bio-based content qualification to meet 2025-2030 sustainability targets. The technology is expanding into headliner and door panel applications previously dominated by petroleum-based substrates.
REACH authorization requirements for chrome-tanning agents are compressing leather supply chain configurations across Italian and Spanish processing centers. Tanneries face capital decisions on vegetable-tanning equipment conversion versus synthetic leather pivot. Premium German OEMs are responding with accelerated Alcantara and microfiber specification for performance variants.
Direct OEM sourcing consolidation is displacing multi-tier distributor networks for interior trim components. Just-in-sequence delivery requirements from German premium manufacturers compress supplier geographic radius. Bavarian and Baden-Württemberg production corridors exhibit the most pronounced channel restructuring.
Europe Automotive Upholstery Market Segmentation
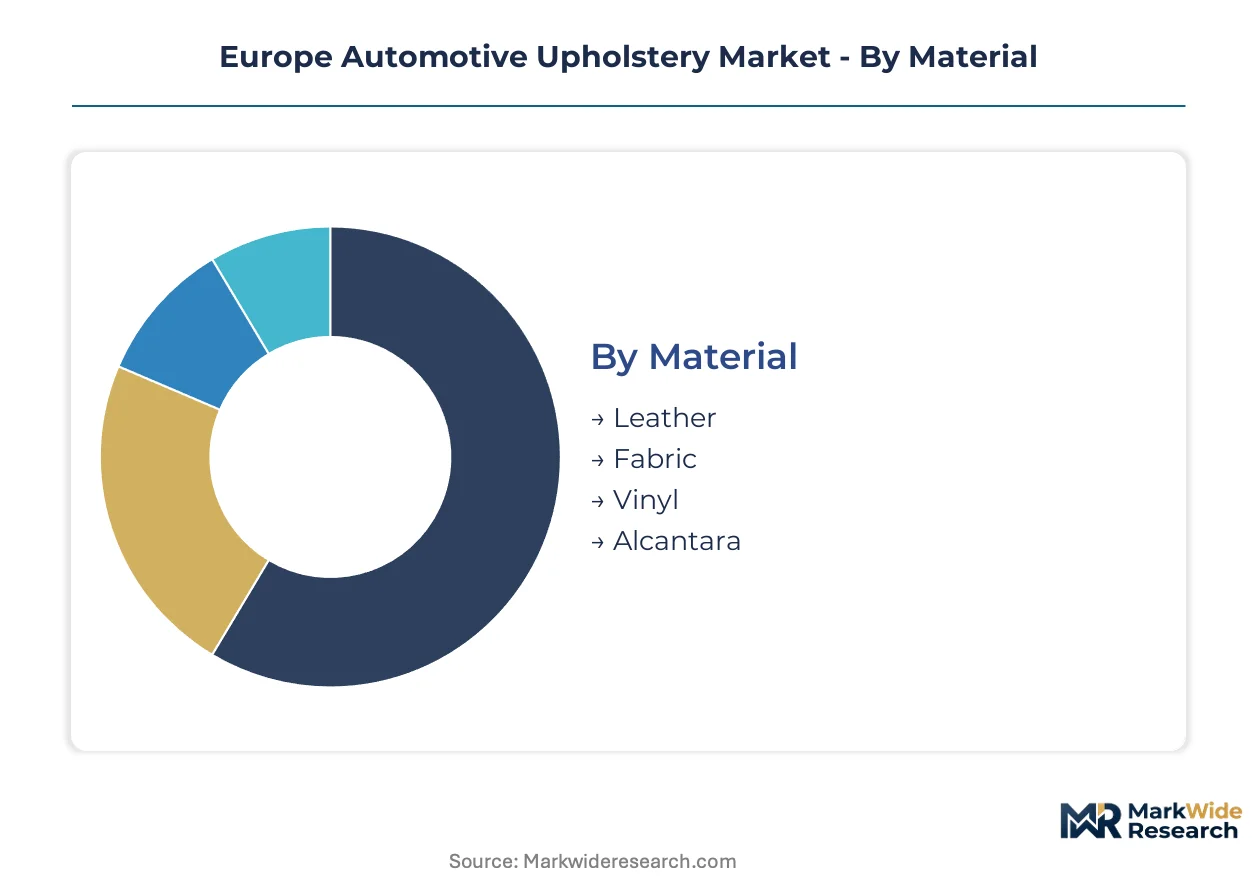
Material specification pathways across European automotive upholstery diverge sharply based on regulatory compliance timelines and OEM sustainability mandates. Segmentation clarity enables suppliers to align R&D investments with qualification windows and thermal-management requirements emerging from electric vehicle platform shifts.
Material:
Supply concentration for surface coverings tilts toward synthetic alternatives as REACH deadlines compress chrome-tanning viability and bio-based polyurethane qualification accelerates.
- Leather:Chrome-tanned hides face ECHA authorization restrictions on hexavalent chromium chemistry. Bavarian premium OEMs are pivoting specification toward vegetable-tanned alternatives or synthetic substitutes, compressing traditional Italian and Spanish tannery margins.
- Alcantara:Single-source supply dependency for this premium microfiber suede creates procurement vulnerability in performance vehicle programs. German OEMs specify Alcantara for SUV and sedan sport variants where tactile differentiation commands price premiums.
- Fabric:Woven textile substrates serve economy and mid-range vehicle segments with lower per-unit material costs.
- Vinyl:Petroleum-based formulations face substitution pressure from bio-based polyurethanes under EU Green Deal procurement guidelines.
Leather absorbs the bulk of installed capacity; Alcantara is expanding most quickly.
Vehicle Type:
Application-driven volume distribution centers on platforms with the highest interior surface area and specification complexity.
- SUVs:Expanded cabin volumes multiply seating rows and door panel coverage, driving aggregate material consumption per vehicle. French and German electric SUV programs specify sustainable synthetic leather across multiple interior touchpoints.
- Sedans:Traditional three-box configurations maintain consistent upholstery specification patterns with emphasis on front-seat ergonomic density.
- Hatchbacks:Compact European segments prioritize cost-optimized fabric and vinyl combinations.
- Trucks:Commercial vehicle durability cycles favor heavy-duty vinyl and reinforced fabric constructions.
SUVs command the greatest material intensity per unit; electric SUV variants are climbing the fastest.
End User:
Customer-type segmentation reveals channel consolidation pressures reshaping supplier relationship structures.
- OEMs:Direct sourcing mandates from German premium manufacturers compress Tier-2 supplier access. Just-in-sequence delivery requirements favor geographically proximate production corridors in Bavaria and Baden-Württemberg.
- Tier-1 Suppliers:Integrated foam-to-fabric operations capture specification influence through design-in capabilities.
- Aftermarket Providers:Fragmented Southern European restoration markets in Italy and Spain remain underpenetrated by organized supply chains.
- Dealerships:Accessory and upgrade upholstery options serve premium personalization demand.
OEMs absorb the bulk of installed capacity; Tier-1 suppliers are gaining share fastest.
Design Style:
Margin-tier differentiation stratifies across aesthetic positioning and material cost structures.
- Luxury:Full-grain leather and Alcantara combinations dominate German flagship sedan and SUV specifications. REACH-compliant tanning chemistry and bio-based certification requirements extend supplier qualification timelines.
- Modern:Minimalist aesthetic programs favor technical textiles and microfiber surfaces with reduced seam complexity.
- Sporty:Performance-oriented bolstered seating requires high-friction surface materials and enhanced foam density specifications.
- Vintage:Classic vehicle restoration demand concentrates in Italian and Spanish aftermarket channels.
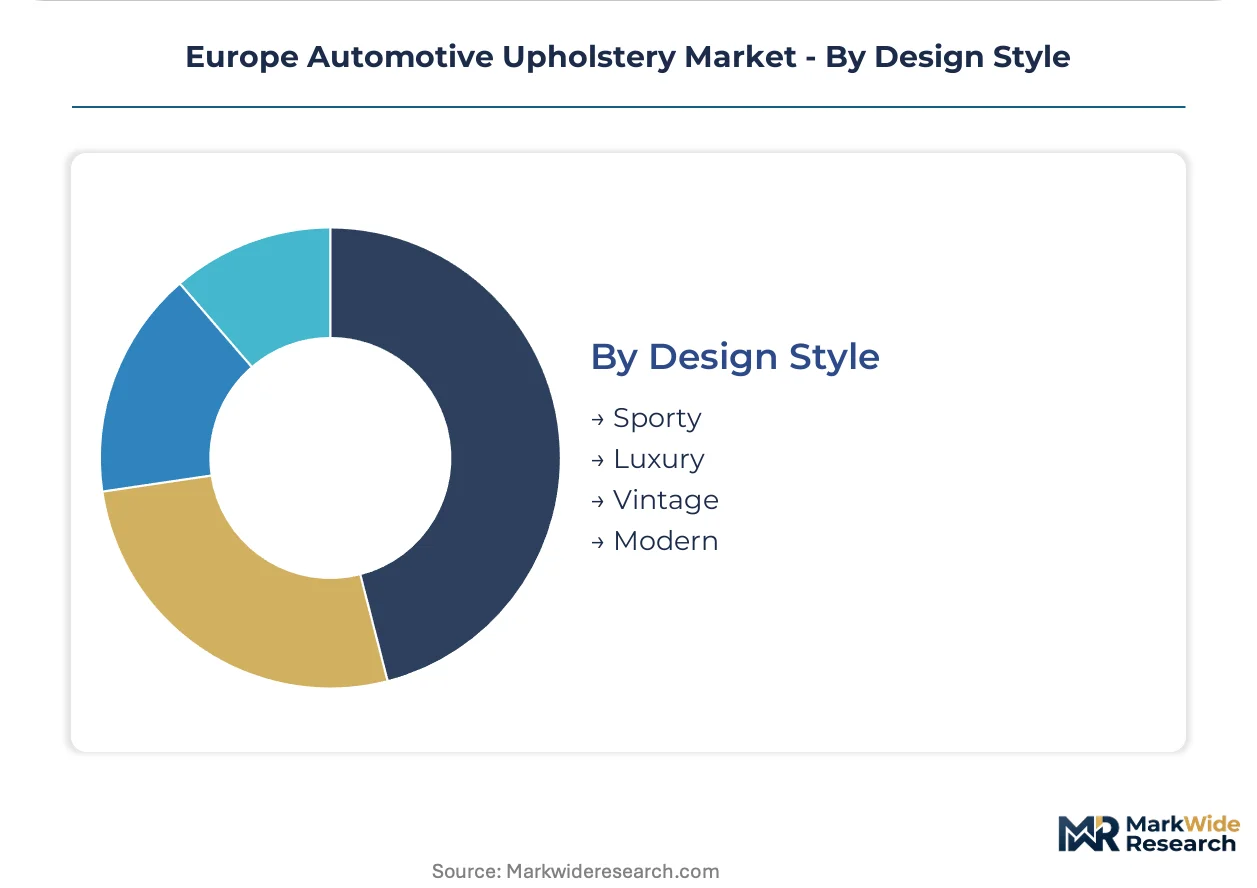
Luxury absorbs the bulk of installed capacity; Modern is gaining specification share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock corridors in Northwest Europe anchor upholstery material supply, with polyurethane precursor production concentrated around Antwerp-Rotterdam-Rhine-Ruhr industrial zones. REACH compliance deadlines and EU Green Deal procurement mandates are redrawing supplier qualification maps across the continent.
Germany
Premium electric vehicle seating programs from BMW and Mercedes-Benz are accelerating bio-based synthetic leather procurement. ECHA substance restrictions on hexavalent chromium are compressing chrome-tanning timelines. Bavaria's automotive cluster around Munich and Ingolstadt hosts the densest concentration of OEM specification engineering centers in Europe.
France
Faurecia's hydrogen-powered vehicle interior programs are creating divergent thermal-management specifications for foam density and breathability. The EU Green Deal drives state-backed procurement incentives for sustainable material alternatives. The Auvergne-Rhône-Alpes region around Lyon sustains specialized textile finishing capabilities for technical upholstery substrates.
Italy
Leather processing centers in Tuscany and Veneto face capital decisions on vegetable-tanning retooling versus synthetic pivot. ECHA authorization requirements for chrome-tanning agents are eliminating established processing pathways. Milan-Turin industrial corridors maintain heritage craft capabilities alongside emerging bio-based material pilot lines.
Spain
Aftermarket restoration demand for classic vehicle upholstery concentrates in Catalonia and Madrid regional markets. CE marking requirements under EU Construction Products Regulation constrain supplier qualification timelines. Basque Country automotive suppliers are diversifying into low-VOC interior emission certification programs.
United Kingdom
Luxury OEM specification activity from Jaguar Land Rover programs sustains premium leather and Alcantara demand. EMA automotive interior emissions guidance advantages suppliers with pre-certified material portfolios. Midlands manufacturing corridors exhibit restructuring around just-in-sequence delivery requirements from German premium OEMs.
Europe Automotive Upholstery Market Competitive Landscape
Global majors compete with regional champions across integrated foam-to-fabric capabilities and just-in-sequence delivery networks. Market structure tilts toward consolidated Tier-1 supplier influence, with direct OEM sourcing mandates compressing multi-tier distributor access. Three archetypes dominate: integrated seating system specialists, chemical material suppliers with downstream upholstery partnerships, and dedicated surface covering manufacturers. Competitive moves center on backward integration into foam production and geographic co-location with Bavarian OEM engineering centers.
Within the integrated seating systems tier, Adient PLC and Lear Corporation exemplify archetypes with captive supply chain control over foam-to-fabric operations. Faurecia occupies a position bridging hydrogen vehicle thermal-management specialization with traditional upholstery specification influence. Among chemical material suppliers, BASF SE anchors the polyurethane precursor segment that feeds downstream synthetic leather formulations. Toyota Boshoku Corporation represents the Asia-Europe cross-regional specialist archetype with manufacturing presence spanning multiple EU assembly corridors.
| Leading Market Players |
|---|
| Adient PLC |
| Grupo Antolin |
| Faurecia |
| Lear Corporation |
| Forvia SE |
| Toyota Boshoku Corporation |
| Woodbridge Foam Corporation |
| BASF SE |
| Freudenberg SE |
| Others |
Supply & Pricing Matrix
German premium OEM procurement concentration anchors contract-based long-term offtake pricing across bio-based polyurethane and REACH-compliant leather alternatives. Bavarian specification engineering centers leverage just-in-sequence delivery requirements to compress supplier margins while locking in multi-year material commitments.
Pricing Analysis
Warranty and service bundling remain unbundled in standard upholstery supply agreements, with after-sales quality guarantees negotiated separately from per-unit material costs. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and foam density specifications. Pricing pressure stems from petrochemical input volatility compressing synthetic leather margins. Tier-1 suppliers exhibit lowest price sensitivity due to captive specification influence; aftermarket providers face highest sensitivity to material cost fluctuations.
Supply Chain Analysis
Single-source vulnerability sits with Alcantara's Italian manufacturing base for premium microfiber suede specifications. Polyurethane precursor production concentrates in Germany, Belgium, and the Netherlands around Antwerp-Rotterdam-Rhine-Ruhr industrial corridors. Raw material dependencies include MDI isocyanates, polyols, and chrome-tanned hides facing ECHA phase-out deadlines. Supply chain risk centers on REACH authorization compressing leather processing alternatives. Distribution runs through direct OEM sourcing channels displacing multi-tier distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is intensifying as REACH compliance deadlines eliminate sub-scale tanneries and foam processors lacking capital for bio-based retooling. ECHA substance restrictions function as a forced-exit mechanism for weaker players.
For Market Incumbents: Deploy backward integration into polyurethane precursor production to secure margin control over bio-based formulations. Adient PLC and Lear Corporation exemplify this lever through captive foam-to-fabric operations. Incumbents must accelerate low-VOC certification investment ahead of EMA automotive interior emissions guidance tightening. Channel control through geographic co-location with Bavarian OEM engineering centers defends against emerging hydrogen vehicle thermal-management specialists. For New Entrants and Emerging Players: Enter via Southern European aftermarket restoration channels in Italy and Spain, where organized supply chains remain underpenetrated. Classic vehicle upholstery services represent the most penetrable white-space target. Bio-based material pilot lines serving French hydrogen vehicle interior programs offer a second entry vector. Go-to-market positioning should emphasize ECHA pre-certification to compress OEM qualification timelines. For Investors and Strategic Acquirers: The window for entry favors mid-cap specialists with integrated foam-to-fabric capabilities and established REACH-compliant material portfolios. Long-term viability hinges on exposure to electric SUV platform ramps rather than legacy combustion-vehicle programs. Acquisition targets should demonstrate backward integration into polyurethane production or exclusive Alcantara distribution rights. The signal to watch is EMA guidance finalization on cabin air quality standards, which would trigger specification lock-in for pre-certified suppliers. Deviation in bio-based certification standard harmonization would shift the outlook materially.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyurethane Precursor Production | Captive MDI supply secures margin control for BASF SE and downstream synthetic leather formulators. |
| Low-VOC Certification Investment | Pre-certified portfolios capture specification lock-in under EMA automotive interior emissions guidance. |
| Hydrogen Vehicle Thermal-Management Program Development | Faurecia's initiative creates divergent foam density requirements distinct from conventional powertrains. |
| Geographic Co-location with Bavarian OEM Engineering Centers | Just-in-sequence delivery requirements from BMW and Mercedes-Benz compress supplier radius. |
| Vegetable-Tanning Equipment Conversion | Italian and Spanish tanneries face capital decisions as ECHA hexavalent chromium restrictions eliminate chrome-tanning pathways. |
Research Methodology
Independent corroboration across Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and ECHA regulatory affairs specialists underwrites the qualitative findings. Primary interviews with foam formulation chemists and leather processing technical directors combined with secondary validation from vehicle production databases, REACH authorization registries, and IHS Markit registration data. Customs records tracking polyurethane precursor trade flows and SEC filings from listed seating system suppliers provided demand-side triangulation. Bottom-up material consumption estimates and top-down OEM procurement budget analysis were reconciled.
Rate-of-change decomposition across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions structured the analytical framework. CAGRs were derived from segment-level material intensity coefficients applied to platform production schedules. Electric SUV thermal-management specifications and bio-based polyurethane qualification timelines served as industry-specific forecast inputs throughout the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA authorization acceleration or petrochemical price spike scenarios. Forecasts reflect documented assumptions on REACH compliance deadlines and OEM sustainability procurement mandates. Deviation in EU bio-based certification standard harmonization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Zero Gravity Seat Market
Automotive Interior & Exterior
Automotive Flock Market
Automotive Interior & Exterior
Automotive Smart Faceplate Market
Automotive Interior & Exterior
Automotive Drawer Slides Market
Automotive Interior & Exterior
Automotive Auto Dimming Mirror Market
Automotive Interior & Exterior
Automotive Door Seal Market
Automotive Interior & Exterior
Automotive Steering Wheel Covers Market
Automotive Interior & Exterior
Global Automotive Interiors Market
Automotive Interior & Exterior
Automotive Active Grille Shutter (AGS) Market
Automotive Interior & Exterior
Automotive Chromium Finishing Market
Automotive Interior & Exterior
Automotive Head Up Display (HUD) Market
Automotive Interior & Exterior
Global Automotive Anti Vibration Mounting Market
Automotive Interior & Exterior
China Automotive Sunroof Market
Automotive Interior & Exterior
Train Seat Materials Market
Automotive Interior & Exterior
Africa and Middle East Automotive Sunroof Market
Automotive Interior & Exterior
Automotive in-Vehicle Air Purifier Market