
 United States Agricultural Biologicals Market | 2026-2036
United States Agricultural Biologicals Market Size, Share, and Industry Trends Forecast 2026-2036
United States Agricultural Biologicals Market Insights
Subscription-based agronomic advisory bundled with biological inputs is decoupling product sales from standalone commodity transactions. Corteva Agriscience leverages its Pioneer seed distribution network to anchor biological adjacencies at the point of planting. Bayer AG sustains R&D intensity through its Crop Science division's microbial platform investments. Novonesis Group differentiates through enzymatic fermentation capabilities that occupy a distinct tier in active-ingredient manufacturing.
United States agricultural biologicals comprise living organisms, derived metabolites, and biochemical compounds formulated for crop protection, soil amendment, or plant physiological enhancement, typically requiring fermentation or extraction processes with defined colony-forming-unit thresholds and shelf-stability specifications. Their primary commercial purpose is to reduce synthetic chemical residues while maintaining yield parity through modes of action such as antibiosis, induced systemic resistance, or rhizosphere colonization. Microbial products lead volume throughput due to established manufacturing infrastructure and EPA registration precedents, while bioherbicides represent the fastest-expanding margin pool as glyphosate resistance pressures intensify across Midwest soybean and cotton acreage. Biopesticides command premium positioning in organic farming and export-oriented specialty crop channels where residue tolerances tighten.
The EPA's biopesticide division and USDA's National Organic Program jointly determine registration pathways and label claims that shape market access timelines and formulation standards for domestic manufacturers. California's Department of Pesticide Regulation imposes additional state-level data requirements that filter entrants and elevate compliance costs for products targeting the nation's largest agricultural economy. Stakeholders must monitor evolving EPA guidance on plant-incorporated protectants and RNA-interference biologicals, as these frameworks will determine which technology platforms secure expedited market entry versus multi-year review cycles.
Market Dynamics
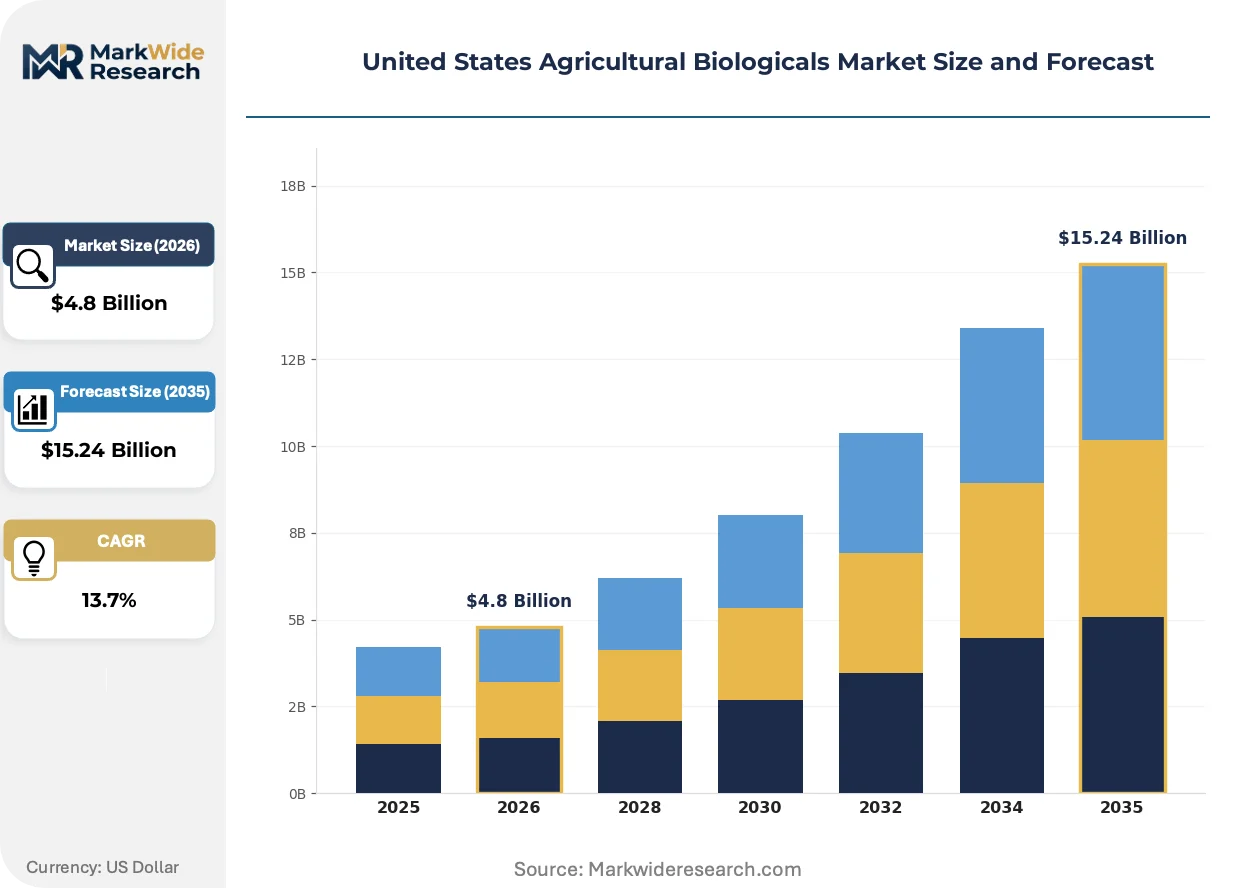
The United States agricultural biologicals market is restructuring around accelerated EPA biopesticide registration timelines under FIFRA Section 3, compressing multi-year review cycles and redirecting R&D investment toward microbial platform development.
Growth Catalysts
- EPA Registration Streamlining:The agency's biopesticide division has reduced average review timelines, enabling faster commercialization of microbial active ingredients and attracting venture capital to fermentation-based manufacturing.
- Glyphosate Resistance Pressure:Weed management failures across Midwest soybean and cotton acreage are forcing growers to stack bioherbicides with conventional chemistries, expanding addressable hectares for biological solutions.
- California Regulatory Stringency:State-level restrictions on synthetic fungicides under DPR oversight push Central Valley specialty crop producers toward microbial biofungicides and biostimulant soil amendments.
Market Restraints
- Manufacturing Concentration Risk:Fermentation capacity for high-titer microbial strains concentrates among contract manufacturers in the Great Lakes region, creating single-source vulnerabilities for emerging biological startups.
- Shelf-Stability Limitations:Colony-forming-unit degradation during storage and transport restricts distribution radius and complicates inventory management for live microbial products.
- Performance Variability:Efficacy inconsistency across soil types and weather conditions forces growers to maintain synthetic chemical backup programs, diluting biological adoption economics.
Strategic Opportunities
- Texas High Plains Cotton:Underpenetrated acreage in the Southern Plains presents expansion potential for nematode-targeting biologicals as bollworm resistance intensifies.
- RNA-Interference Biologicals:Novel mode-of-action platforms awaiting EPA guidance on plant-incorporated protectants could unlock premium positioning in resistance management programs.
- Subscription Agronomic Services:Bundled biological-input-plus-advisory models decouple revenue from commodity pricing, locking in multi-season grower relationships through Pioneer and independent retail networks.
Industry Challenges
- Fermentation Specialist Scarcity:Industrial microbiology and downstream processing expertise remains concentrated among legacy pharmaceutical and enzyme manufacturers, constraining biological scale-up capacity.
- Label Claim Complexity:Dual EPA-USDA organic certification requirements create documentation burdens that extend commercialization timelines and elevate compliance costs for multi-state distribution.
- Legacy System Integration:Biological tank-mix compatibility with existing spray equipment and synthetic chemical programs requires extensive field validation, slowing grower adoption cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Agricultural Biologicals Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microbial Products, Bioherbicides, Biopesticides, Biofungicides End Use Industry: Crop Protection, Soil Health, Plant Growth, Pest Management Distribution Channel: Retail, Wholesale, Online, Direct Sales Application: Agronomy, Horticulture, Turf Management, Organic Farming |
| Companies Covered | Corteva Agriscience, Bayer AG, Novonesis Group, Valent BioSciences LLC, BASF SE, Syngenta Group, FMC Corporation, UPL, BioWorks Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Agricultural Biologicals Market Trends and Innovations
Biological formulation science is converging with precision application technologies, reshaping how active ingredients reach target pest or plant physiological pathways. This convergence is compressing the performance gap between biological and synthetic chemistries.
RNA-interference biologicals are integrating with conventional spray programs as a resistance-breaking mechanism. Specialty crop producers in Florida citrus and California tree nuts are piloting foliar-applied dsRNA formulations against Asian citrus psyllid and navel orangeworm. This integration is enabling biological products to occupy previously synthetic-exclusive windows in integrated pest management calendars.
The EPA's evolving guidance on plant-incorporated protectants is clarifying regulatory boundaries for genetically modified biological delivery systems. Seed treatment applications incorporating microbial endophytes now face streamlined data requirements, accelerating commercialization timelines. Corn Belt row-crop operators are responding by expanding biological seed treatment adoption in soybean and corn rotations.
Buyer concentration among agricultural retailers is reshaping distribution economics for biological inputs. Multi-state cooperatives and regional agronomy chains are consolidating procurement authority, demanding performance guarantees and rebate structures that mirror synthetic chemical programs. This shift is most visible in the Midwest, where three input distributors control access to roughly half of corn and soybean planted acreage.
United States Agricultural Biologicals Market Segmentation
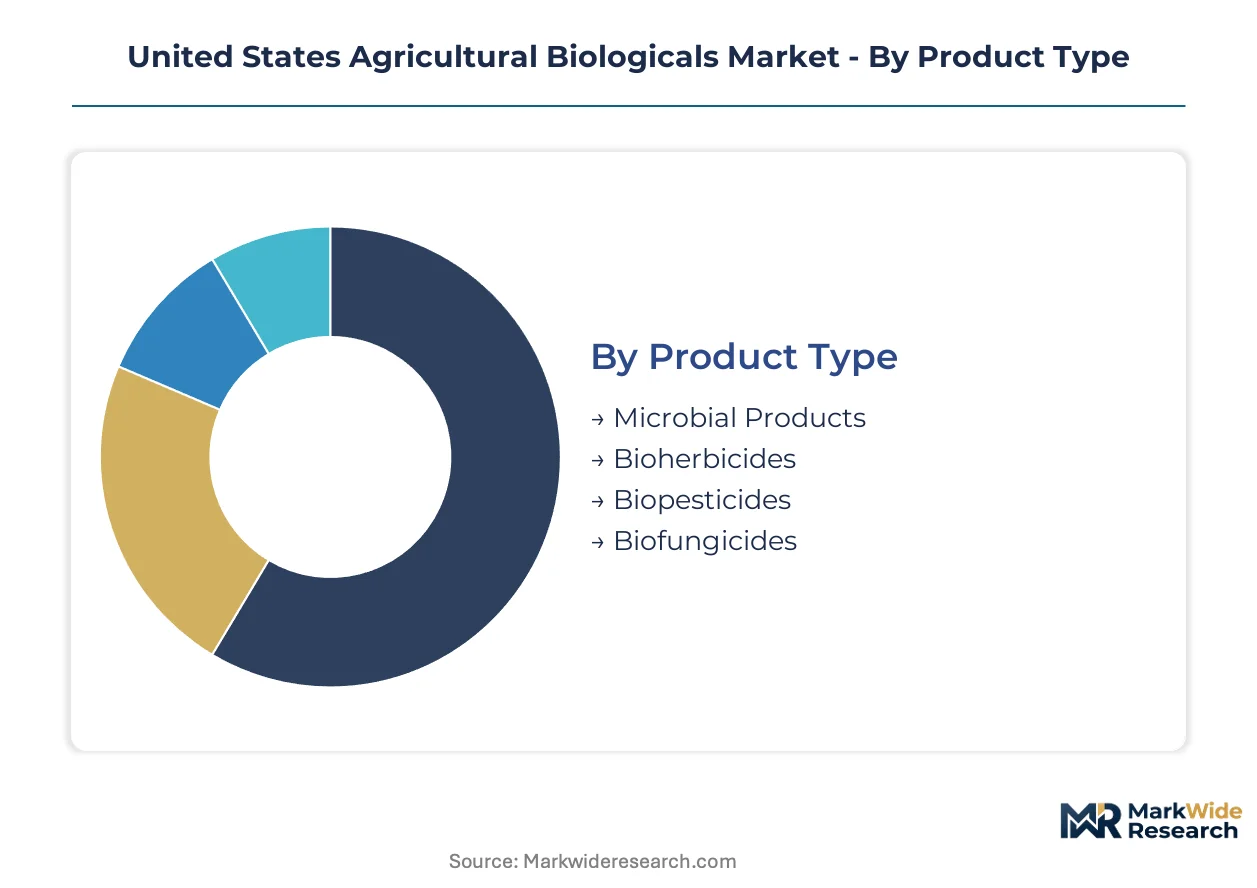
Segmentation in the United States agricultural biologicals market reveals distinct procurement patterns across product categories and application contexts. Buyers prioritize EPA registration status, formulation stability, and tank-mix compatibility when selecting biological inputs for their operations.
Product Type:
Cost tier determines adoption sequencing, with established microbial platforms commanding lower risk premiums than novel biochemical entrants.
- Microbial Products:Living organisms including bacteria, fungi, and viruses formulated with defined colony-forming-unit specifications for consistent field performance. Corn Belt row-crop operators in Iowa and Illinois deploy these for rhizosphere colonization and induced systemic resistance, constrained by shelf-stability limitations during summer storage.
- Bioherbicides:Microbial metabolites and plant-derived compounds targeting weed physiology through novel modes of action. Demand concentrates in Midwest soybean acreage where glyphosate-resistant Palmer amaranth pressures force growers to stack biological adjuvants with synthetic chemistries.
- Biopesticides:Targeted arthropod control agents derived from fermentation or botanical extraction processes.
- Biofungicides:Microbial antagonists and biochemical suppressors of soilborne and foliar pathogens.
Volume sits with Microbial Products; growth tilts toward Bioherbicides.
End Use Industry:
Application context shapes performance expectations and rebate structures across buyer segments.
- Crop Protection:Biological inputs deployed as primary or rotational pest management tools within integrated programs. California Central Valley specialty crop producers lead expenditure here, driven by DPR restrictions on synthetic fungicides in export-oriented stone fruit and nut operations.
- Soil Health:Biostimulant and microbial inoculant treatments targeting nutrient cycling and rhizosphere biology. Adoption accelerates in the Great Plains wheat belt where regenerative agriculture contracts from food manufacturers create guaranteed offtake for carbon-sequestering practices.
- Plant Growth:Physiological enhancement products including biostimulants for abiotic stress tolerance.
- Pest Management:Targeted biological control within broader insect resistance management frameworks.
Revenue concentrates in Crop Protection; Soil Health climbs the fastest as carbon market linkages mature.
Distribution Channel:
Customer scale and technical support requirements fragment procurement pathways across the value chain.
- Retail:Independent agricultural retailers and cooperatives providing localized agronomic advice alongside product fulfillment. The Midwest's consolidated input distribution networks—controlling access to roughly half of corn and soybean acreage—favor this channel for biological seed treatments.
- Wholesale:Volume procurement by multi-state agronomy chains and regional cooperatives demanding performance guarantees mirroring synthetic chemical programs.
- Online:Direct-to-grower platforms with limited technical support, capturing price-sensitive smaller operations.
- Direct Sales:Manufacturer field representatives serving large integrated producers with customized application protocols.
Transaction volume flows through Retail; Direct Sales gains share fastest as subscription advisory models proliferate.
Application:
Certification requirements and residue tolerances create divergent pricing power across use cases.
- Agronomy:Row-crop biological programs in corn, soybean, and wheat rotations where yield parity with synthetic chemistries determines adoption. Texas High Plains cotton expansion presents underpenetrated acreage for nematode-targeting biologicals as bollworm resistance intensifies.
- Horticulture:High-value fruit and vegetable production with stringent export residue limits. Florida citrus growers pilot RNA-interference formulations against Asian citrus psyllid, integrating biologicals into previously synthetic-exclusive spray windows.
- Turf Management:Golf course and municipal grounds maintenance with aesthetic performance thresholds.
- Organic Farming:USDA National Organic Program certified operations where biological inputs constitute the sole permitted pest management category.
Agronomy dominates hectare coverage; Horticulture commands the steepest expansion trajectory as specialty crop export channels tighten residue standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fresno anchors United States agricultural biologicals demand through California's Central Valley specialty crop concentration, where export-oriented stone fruit and nut producers face the nation's strictest residue limits. EPA registration timelines and state-level DPR restrictions create divergent market access conditions across major production belts.
California
Central Valley growers deploy microbial biofungicides against soilborne pathogens in almond and pistachio orchards. The Department of Pesticide Regulation's enhanced data requirements filter product entrants and elevate compliance costs for multi-state manufacturers. Fresno-based formulation facilities service coastal strawberry districts where fumigant restrictions intensify biological soil treatment adoption.
Midwest Corn Belt
Iowa and Illinois row-crop operators integrate biological seed treatments into corn-soybean rotations as EPA streamlines microbial active ingredient reviews. The USDA's National Organic Program certification requirements shape procurement for transitioning acreage. Chicago-area distribution networks control access to roughly half of regional planted hectares through consolidated retail channels.
Texas High Plains
Cotton producers in Lubbock and surrounding counties pilot nematode-targeting biologicals as bollworm resistance strains proliferate. State agricultural extension services validate tank-mix compatibility with existing spray programs. Local cooperatives aggregate procurement authority for biological adjuvants stacked with synthetic chemistries.
Florida
Citrus growers in Polk and Hendry counties test RNA-interference formulations against Asian citrus psyllid under experimental use permits. The state's specialized pest management districts coordinate area-wide biological release programs. Immokalee-based research stations generate region-specific efficacy data for subtropical application protocols.
Pacific Northwest
Washington apple and cherry producers adopt biostimulant programs to meet export market phytosanitary standards. State-level organic certification incentives accelerate soil health input spending in Yakima Valley tree fruit districts. Seattle-area venture capital flows toward precision fermentation startups serving regional specialty crop channels.
United States Agricultural Biologicals Market Competitive Landscape
Capital-heavy fermentation producers compete with asset-light formulation specialists for shelf space in consolidated retail networks. The vendor base clusters around three tiers: integrated agrochemical conglomerates with seed distribution anchoring, dedicated microbial platform developers with captive manufacturing, and regional specialists serving organic certification channels. Dominant competitive moves include backward integration into strain development capabilities and subscription-based advisory bundling that locks in multi-season grower relationships.
Within the integrated conglomerate tier, Corteva Agriscience and Bayer AG occupy positions defined by Pioneer seed network access and Crop Science division R&D intensity respectively. Novonesis Group exemplifies the specialized fermentation archetype through enzymatic manufacturing capabilities that supply active ingredients to downstream formulators. These three entities represent distinct strategic postures: distribution-anchored biological adjacencies, research-intensive microbial platform development, and upstream active ingredient supply concentration.
| Leading Market Players |
|---|
| Corteva Agriscience |
| Bayer AG |
| Novonesis Group |
| Valent BioSciences LLC |
| BASF SE |
| Syngenta Group |
| FMC Corporation |
| UPL |
| BioWorks Inc. |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up fermentation specialists anchor supply-side concentration across the Great Lakes manufacturing belt, translating captive strain-development capabilities into pricing discipline that resists commodity erosion. Their ownership structure rewards throughput optimization over margin sacrifice, compressing price competition for microbial active ingredients while elevating compliance-cost barriers for undercapitalized formulators.
Pricing Analysis
Yield-guarantee contracts serve as the dominant value-based pricing anchor, tying biological input costs to demonstrable harvest outcomes. Three-tier pricing structure across premium, standard, and economy levels separates EPA-registered microbial platforms with multi-season field data from experimental entrants and generic fermentation byproducts. Cost compression in the standard tier is intensifying because consolidated Midwest retailers demand rebate parity with synthetic chemical programs. Smaller organic-transitioning operations exhibit highest price sensitivity, while export-oriented California specialty crop producers accept premium positioning for residue-compliant formulations.
Supply Chain Analysis
Domestic-content preferences embedded in USDA procurement guidelines and California DPR registration incentives reshape sourcing toward US-based fermentation capacity. Active ingredient manufacturing concentrates in the United States, Brazil, and select European Union facilities with established EPA equivalency determinations. Downstream formulation draws from proprietary microbial strains, agricultural substrate feedstocks, and specialized stabilizing carriers. Single-source vulnerability concentrates among contract fermentation providers serving multiple formulators from shared bioreactor networks. Distribution runs through consolidated agricultural retail cooperatives that aggregate procurement authority across multi-state footprints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as EPA registration cost inflation and shelf-stability R&D requirements force sub-scale formulators toward strategic exit. Weaker players lacking captive fermentation assets face margin compression that accelerates acquisition-driven industry restructuring.
For Market Incumbents: Cement distribution lock-in through subscription-based agronomic advisory bundles that decouple revenue from spot commodity pricing. Prioritize backward integration into strain-development capabilities to reduce dependency on Great Lakes contract manufacturers. The threat of RNA-interference platform entrants with novel mode-of-action claims demands accelerated microbial patent estate expansion. For New Entrants and Emerging Players: EPA biopesticide registration streamlining under FIFRA Section 3 opens a window for Texas High Plains cotton acreage, where nematode-targeting biologicals remain underpenetrated. Target specialty crop channels in Florida citrus with experimental-use-permit positioning ahead of full commercial registration. Pursue direct sales relationships with large integrated producers seeking customized application protocols outside consolidated retail networks. For Investors and Strategic Acquirers: First commercial RNA-interference biological approvals under EPA plant-incorporated protectant guidance is the leading indicator that mode-of-action diversification will reshape competitive tiers. Five-to-ten-year viability favors acquisition targets with enzymatic fermentation capabilities and established organic certification channels. Monitor California DPR enforcement actions against synthetic fungicide residues as the signal for biological substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strain Development | Captive microbial libraries reduce dependency on Great Lakes contract fermentation capacity. |
| Subscription Advisory Bundling | Pioneer seed network anchoring locks in multi-season grower relationships beyond transactional sales. |
| California DPR Registration Investment | State-level compliance certification unlocks access to Central Valley specialty crop premium channels. |
| RNA-Interference Platform Development | Novel mode-of-action positioning anticipates EPA guidance on plant-incorporated protectants. |
| Organic Certification Channel Expansion | USDA National Organic Program alignment captures residue-sensitive export-oriented producer demand. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving fermentation plant managers, EPA regulatory affairs specialists, agricultural cooperative procurement leads, and specialty crop agronomists. EPA biopesticide registration databases, USDA National Organic Program certification lists, California DPR product registration records, and SEC 10-K disclosures from publicly traded agrochemical conglomerates supplied quantitative benchmarks. Bottom-up strain-development capacity assessments triangulated against top-down agricultural input expenditure models.
Segmentation granularity applied product-type distinctions at the active-ingredient level, distribution-channel modeling at the customer-scale tier, and application-context differentiation across residue-tolerance thresholds. End-use industry forecasts incorporated carbon-market linkage maturation for soil health inputs and glyphosate resistance pressure indices for bioherbicide adoption curves. CAGRs derived from weighted scenario analysis across regulatory timeline assumptions and manufacturing capacity expansion schedules. Mode-of-action innovation pipelines and EPA guidance evolution served as primary forecast sensitivity inputs.
The model assumes a particular technology adoption path; alternative pathways for RNA-interference biologicals would alter the outlook if EPA registration timelines extend beyond microbial precedent. Forecasts reflect assumptions regarding EPA biopesticide division staffing continuity, California DPR enforcement intensity, and fermentation substrate cost stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Hydroponics Market
Bio-Agriculture
Seed Biostimulants Market
Bio-Agriculture
Europe Plant-Based Biologics Market
Bio-Agriculture
Africa Biological Organic Fertilizers Market
Bio-Agriculture
Latin America Biopesticide Market
Bio-Agriculture
Marine Biotechnology Market
Bio-Agriculture
Global Feed Phytobiotics Market
Bio-Agriculture
North America Biological Organic Fertilizer Market
Bio-Agriculture
North America Bioherbicides Market
Bio-Agriculture
Bovine High-Mountain Disease Market
Bio-Agriculture
Europe Agricultural Biologicals Market
Bio-Agriculture
Plant Based Biosurfactants Market
Bio-Agriculture
Europe Feed Probiotics Market
Bio-Agriculture
Bio-Insecticide Market
Bio-Agriculture
Canada Biofertilizers Market
Bio-Agriculture
Australia Biopesticides Market