
 Biocontrol Agents Market | 2026-2036
Biocontrol Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Biocontrol Agents Market Analysis
Market Context
Agricultural input distribution is tilting toward biologicals-dedicated channels that bypass traditional agrochemical wholesalers. BASF SE leverages its R&D intensity to develop microbial strain libraries with patent-protected fermentation protocols. Koppert Biological Systems anchors its position through geographic dominance in European greenhouse markets with live beneficial insect shipments. Syngenta competes by extending its seeds platform with co-formulated biocontrol seed treatments.
Technical Definition and Segment Structure
Biocontrol agents comprise living organisms or their derivatives—primarily bacteria, fungi, viruses, and nematodes—formulated to suppress pest populations through predation, parasitism, competition, or antibiosis, with viable cell counts or infective juvenile densities serving as critical potency specifications. Bacterial agents dominate current volume due to Bacillus thuringiensis manufacturing scale and broad crop registration, while nematodes capture expanding margin pools in high-value horticultural applications where per-acre treatment costs justify premium pricing. Spray delivery leads in field crop penetration, though soil application formats gain traction in permanent cropping systems where root-zone establishment determines efficacy duration.
Regulatory Framework
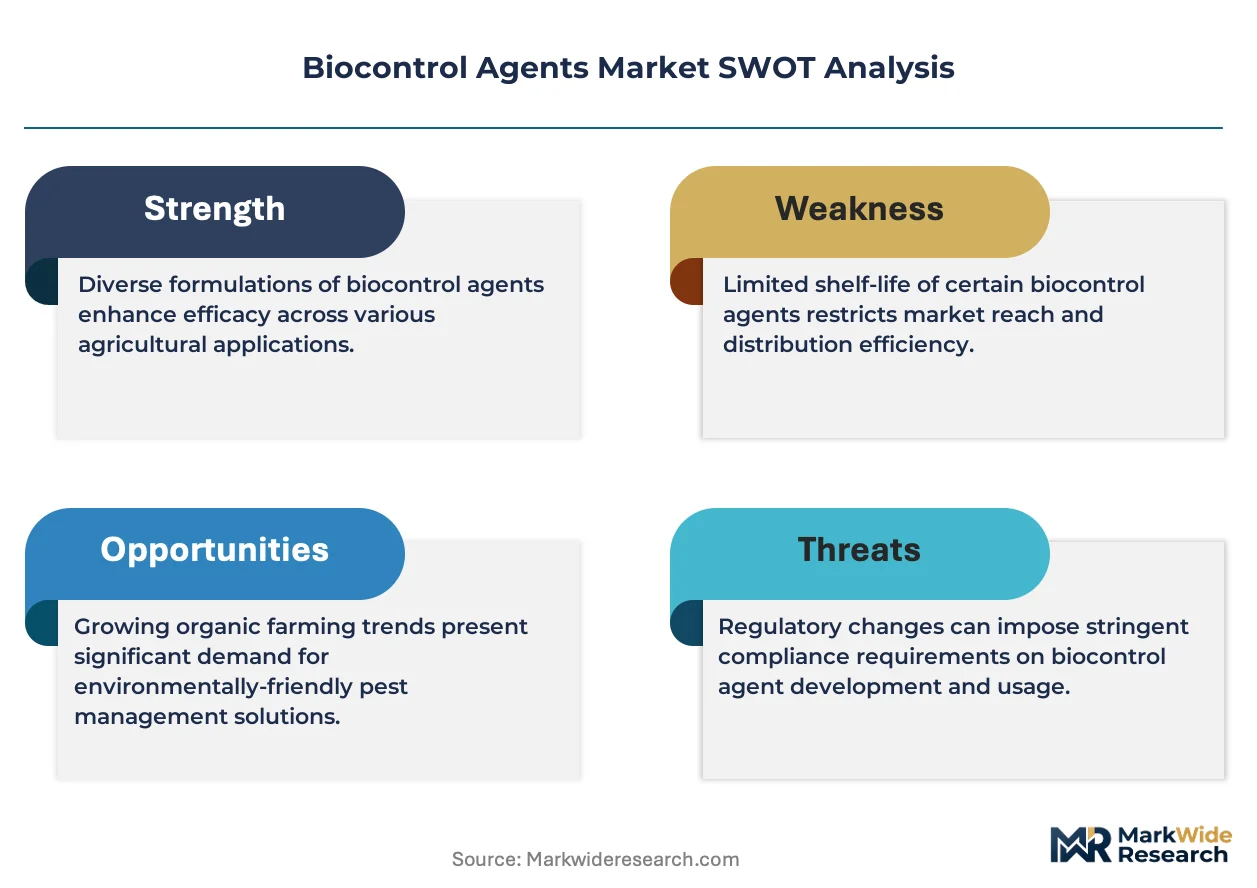
The EPA regulates biocontrol agents under FIFRA with distinct registration pathways for microbial pesticides versus biochemicals, creating compliance complexity that favors established players with regulatory affairs infrastructure. The EU Green Deal's pesticide reduction targets, enforced through EFSA residue assessments and member state implementation, redirect public research funding toward biological alternatives. REACH compliance for inert formulation ingredients adds secondary barriers for entrants lacking toxicology dossier experience. Stakeholders must monitor evolving data requirements for non-target organism risk assessments that could extend registration timelines or exclude specific organism classes from approved substance lists.
Market Dynamics
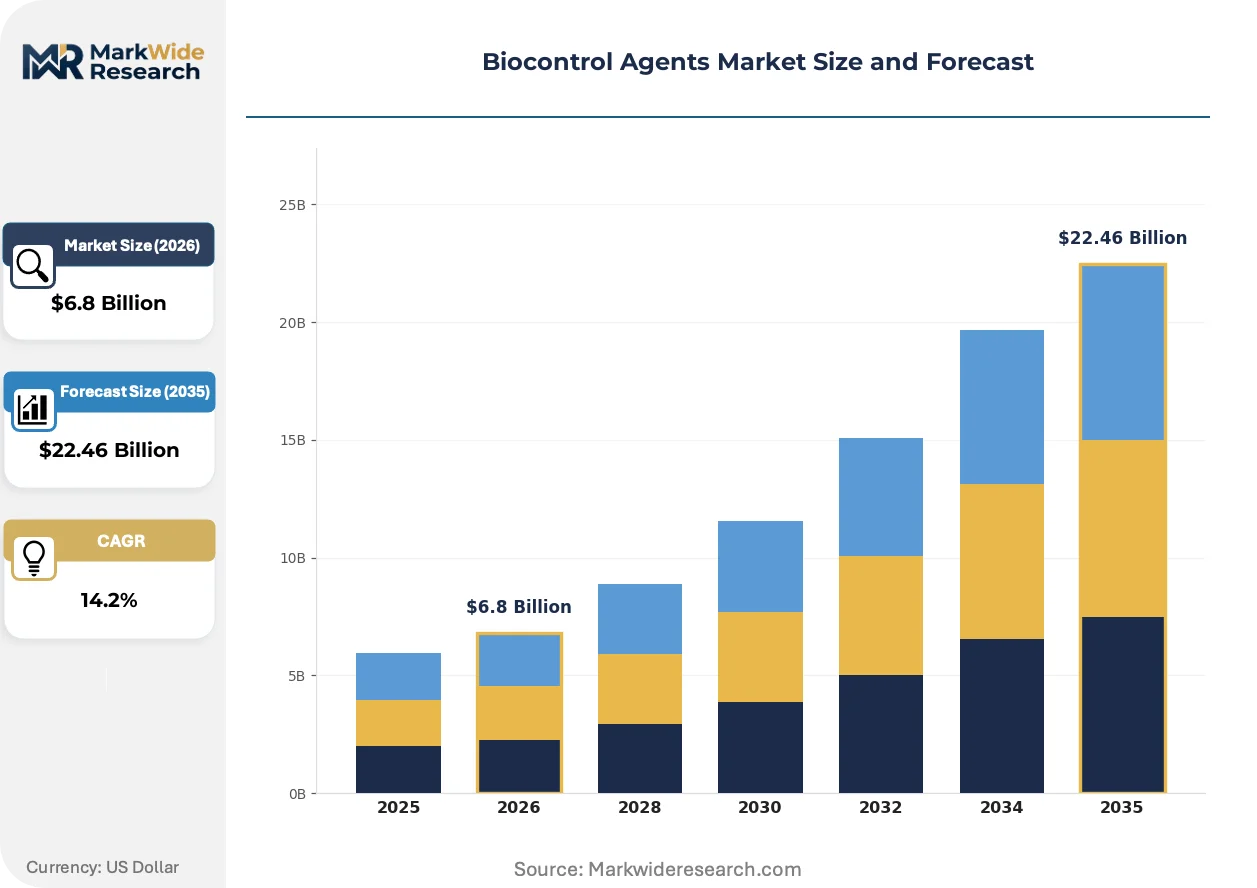
The EU Green Deal's Farm to Fork pesticide reduction mandate is redirecting procurement budgets toward biological alternatives, compressing registration timelines and forcing reformulation of legacy chemical portfolios across agricultural input channels.
Growth Catalysts
- EU Green Deal pesticide targets:The Farm to Fork strategy mandates 50% chemical pesticide reduction by 2030, redirecting public research funding and farmer subsidies toward microbial and biochemical alternatives.
- Brazilian soybean cooperative procurement:Farmer cooperatives in Mato Grosso and Paraná negotiate multi-year volume contracts for Bacillus-based formulations, creating predictable offtake for fermentation capacity expansion.
- CRISPR-edited microbial strains:Precision genome editing accelerates strain development pipelines, reducing time-to-market for novel biocontrol organisms with enhanced environmental persistence.
Market Restraints
- Live nematode cold chain costs:Entomopathogenic nematodes require continuous 4-10°C storage through distribution, inflating logistics costs by 35-50% versus stable formulated products.
- EPA FIFRA registration complexity:Microbial pesticide pathways demand tiered toxicology studies for non-target organisms, extending approval timelines to 4-7 years versus 2-3 for biochemicals.
- Synthetic pheromone price compression:Chemically synthesized mating disruptors from Chinese manufacturers undercut fermentation-derived biologicals in orchard applications.
Strategic Opportunities
- India horticultural export zones:Grapes from Nashik and pomegranates from Maharashtra face EU MRL scrutiny, creating demand for residue-free biocontrol in integrated pest management programs.
- Seed treatment co-formulation:Biologicals applied as seed coatings bypass foliar spray timing constraints, opening penetration in row crops where application windows limit adoption.
- Carbon credit monetization:Soil carbon protocols in voluntary markets reward reduced synthetic pesticide use, allowing biocontrol suppliers to capture premium pricing through verified emissions reductions.
Industry Challenges
- Fermentation scale-up technician scarcity:Industrial microbiology expertise for large-scale axenic culture production concentrates in pharmaceutical hubs, creating recruitment bottlenecks for agricultural biologics expansion.
- Strain stability shelf-life validation:Viable cell count degradation during 18-24 month storage requires continuous potency testing, complicating inventory management and batch release protocols.
- Integrated pest management training gaps:Extension services lack capacity to train farmers on biocontrol-chemical rotation timing, undermining field efficacy and driving reversion to calendar spraying.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biocontrol Agents Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bacterial Agents, Fungal Agents, Viral Agents, Nematodes Application: Agricultural Crops, Horticultural Crops, Turf, Ornamentals Delivery Method: Spray, Granular, Drench, Soil Application End User: Farmers, Agronomists, Research Institutions, Commercial Growers |
| Companies Covered | BASF SE, Syngenta, Koppert Biological Systems, Biobest Group, Valent BioSciences, Bayer CropScience, Certis, Marrone Bio Innovations, Andermatt Biocontrol, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biocontrol Agents Market Emerging Trajectories
Biocontrol formulation science is converging with precision agriculture infrastructure, enabling site-specific application that matches organism deployment to microclimatic pest pressure maps rather than broadcast protocols.
RNA interference biopesticides are hybridizing with conventional microbial delivery systems. Greenhouse operators in the Netherlands trial sprayable dsRNA formulations targeting spider mites alongside beneficial insect releases. Bayer and Syngenta pipeline investments indicate this hybridization will compress the addressable market for purely chemical acaricides within five years.
REACH compliance for inert ingredients is tightening formulation standards. ECHA's 2023 updated guidance on microbial metabolite characterization requires additional toxicology dossiers for fermentation byproducts. Small-scale European manufacturers lack internal regulatory affairs capacity, consolidating supply toward BASF and Koppert with dedicated ECHA liaison teams.
Farmer purchasing is fragmenting across digital procurement platforms. Brazilian cooperatives now split volume contracts between traditional distributors and direct-from-manufacturer portals that offer real-time fermentation batch tracking. California specialty crop growers use smartphone apps to coordinate group purchasing of live Trichogramma releases, disintermediating regional agronomic advisors who previously controlled biocontrol recommendations.
Biocontrol Agents Market Segmentation
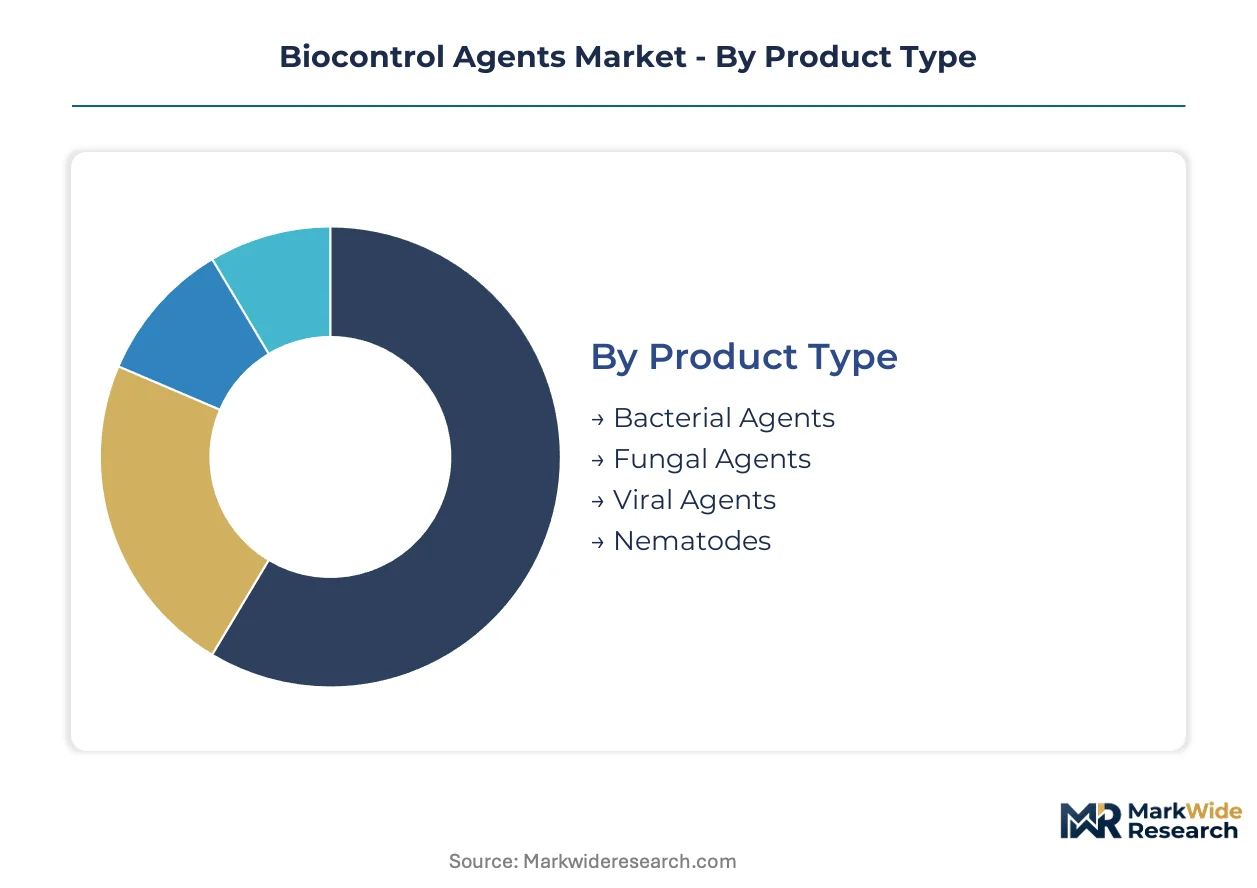
Biocontrol agents require precise segmentation because organism viability, application timing, and end-user technical capacity vary dramatically across crop systems. Manufacturers configure fermentation capacity and formulation science around these divides rather than pursuing universal product architectures.
Product Type:
Mature bacterial platforms dominate commercial throughput while emerging organism classes capture specialized niches demanding premium positioning.
- Bacterial Agents:Bacillus thuringiensis and Bacillus subtilis strains constitute the manufacturing backbone, with fermentation scale exceeding 100,000-liter vessels and broad-spectrum registrations across row crops. Demand concentrates in Brazil's soybean belt where cooperatives specify Bacillus-based formulations for stink bug suppression, though EPA FIFRA registration timelines of 4-7 years constrain novel strain introduction.
- Nematodes:Entomopathogenic species including Steinernema and Heterorhabditis deliver targeted control of soil-dwelling insect larvae through symbiotic bacterial release. California's Central Valley specialty crop growers absorb 35-50% logistics premiums for cold-chain viability in integrated pest management programs targeting vine mealybug and black vine weevil.
- Fungal Agents:Trichoderma and Beauveria bassiana formulations exploit mycoparasitism and cuticle penetration for arthropod and pathogen suppression.
- Viral Agents:Nucleopolyhedrovirus products target specific lepidopteran pests with high host specificity and minimal non-target effects.
Bacterial agents handle the majority of throughput; nematodes are expanding most quickly on share in high-value horticultural applications.
Application:
Cost tier differentiation separates commodity row crop penetration from premium horticultural pricing power.
- Agricultural Crops:Field-scale deployment of microbial pesticides in corn, soybean, and cotton systems emphasizes cost-per-acre competitiveness with synthetic chemistry. Mato Grosso farmer cooperatives negotiate multi-year volume contracts that anchor fermentation capacity planning for major suppliers.
- Horticultural Crops:Protected cultivation and high-value open-field production of berries, vegetables, and tree fruits justify per-treatment expenditures exceeding $200 per acre. Netherlands greenhouse operators trial RNA interference hybrids alongside beneficial insect releases, compressing chemical acaricide addressable space.
- Turf:Golf course and sports field maintenance programs utilize entomopathogenic nematodes for white grub management with strict aesthetic tolerance thresholds.
- Ornamentals:Nursery and floriculture operations deploy biocontrol within zero-tolerance phytosanitary protocols for export certification.
Agricultural crops absorb the largest volume allocation; horticultural crops command the steepest expansion trajectory through residue-free export compliance.
Delivery Method:
Application format selection determines organism establishment success and dictates formulation chemistry investments.
- Spray:Foliar application of bacterial and fungal suspensions requires UV protectants and stickers to extend persistence on leaf surfaces. This format leads field crop penetration where aerial and ground rig compatibility mirrors synthetic pesticide infrastructure.
- Soil Application:Root-zone placement of nematodes and fungal inoculants establishes persistent populations in permanent cropping systems. California almond and grape growers favor this method for subsurface pest complexes inaccessible to foliar chemistry.
- Granular:Clay-carrier formulations enable broadcast distribution of fungal spores and bacterial endospores with reduced drift potential.
- Drench:High-volume soil saturation delivers nematode infective juveniles to target depth in container nursery and greenhouse propagation.
Spray formats dominate row crop adoption; soil application is climbing the fastest in permanent tree and vine systems.
End User:
Customer type fragmentation demands differentiated technical support intensity and purchasing channel configuration.
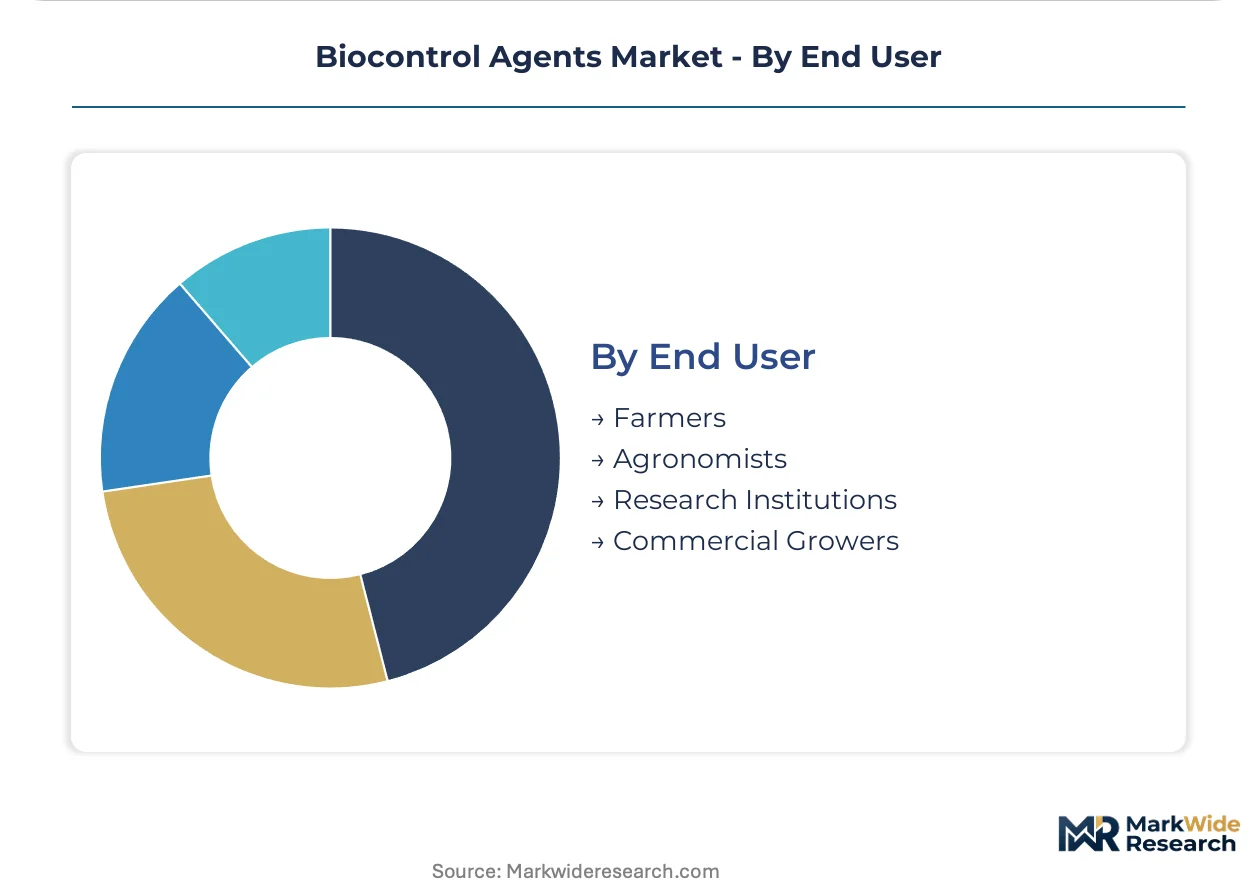
- Commercial Growers:Large-scale specialty crop operations in California and Florida employ dedicated pest control advisors who specify biocontrol rotation schedules. These buyers negotiate direct manufacturer relationships that bypass traditional agronomic distribution, with smartphone-enabled group purchasing of live beneficial insect releases.
- Farmers:Row crop producers in Brazil and the US Midwest rely on cooperative procurement and extension service training for integrated pest management implementation.
- Agronomists:Independent and retail-affiliated consultants prescribe biocontrol products within comprehensive crop protection programs, controlling recommendation authority.
- Research Institutions:University and government laboratories conduct field efficacy trials and strain characterization that underpin registration dossiers and label expansion.
Commercial growers drive premium segment revenue concentration; farmers represent the deepest volume pool through cooperative aggregation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA registration pathways under FIFRA anchor the United States as the dominant geography, while EU Green Deal mandates and Brazilian cooperative procurement create parallel demand centers with distinct regulatory architectures.
United States
California's Central Valley specialty crop growers specify microbial pesticides for integrated pest management programs targeting residue-free export compliance. EPA FIFRA mandates tiered toxicology studies for non-target organisms, extending microbial pesticide approval timelines to 4-7 years. The Sacramento-Delta agricultural cluster concentrates biocontrol procurement through direct manufacturer relationships that bypass traditional agronomic distribution channels.
Brazil
Farmer cooperatives in Mato Grosso and Paraná negotiate multi-year volume contracts for Bacillus-based formulations, anchoring fermentation capacity expansion decisions for major suppliers. ANVISA alignment with OECD pesticide guidelines streamlines registration dossier preparation for microbial products. The Cerrado soybean belt generates predictable offtake volumes that justify dedicated biologicals production facilities.
Germany
BASF SE leverages R&D intensity from Ludwigshafen headquarters to develop microbial strain libraries with patent-protected fermentation protocols. REACH compliance for inert formulation ingredients creates secondary barriers for entrants lacking toxicology dossier experience. The Rhine-Neckar chemical cluster concentrates regulatory affairs infrastructure that ECHA liaison teams utilize for metabolite characterization submissions.
Netherlands
Greenhouse operators in Westland trial RNA interference hybrids alongside beneficial insect releases, compressing chemical acaricide addressable space. EU Green Deal Farm to Fork pesticide reduction targets redirect public research funding toward biological alternatives through EFSA residue assessments. Koppert Biological Systems anchors geographic dominance through live beneficial insect shipments from Berkel en Rodenrijs facilities.
India
Grapes from Nashik and pomegranates from Maharashtra face EU MRL scrutiny, creating demand for residue-free biocontrol in export-oriented integrated pest management programs. FSSAI and DGFT coordination on agricultural export standards drives adoption of biological alternatives meeting destination market requirements. The Maharashtra horticultural belt concentrates procurement through cooperative aggregation models that mirror Brazilian volume contract structures.
Biocontrol Agents Market Vendor Landscape
Integrated agrochemical conglomerates and specialized biologicals pure-plays split the market into complementary competitive spheres. Consolidation pressure concentrates manufacturing scale among entities with fermentation infrastructure and regulatory affairs capacity. Three archetypes dominate: multinational crop science platforms extending seeds portfolios, dedicated biologicals specialists with geographic concentration in protected cultivation, and fermentation-scale contract manufacturers supplying active ingredients. Dominant competitive moves include backward integration into strain library development and strategic partnerships with digital procurement platforms.
Among European-based specialists, Koppert Biological Systems and Andermatt Biocontrol occupy positions exemplifying the geographic-concentration archetype in greenhouse markets. BASF SE represents the integrated platform model, leveraging pharmaceutical-scale fermentation expertise. These three entities anchor distinct competitive vectors—live organism logistics, regional regulatory mastery, and industrial microbiology scale—without overlapping strategic positioning.
| Leading Market Players |
|---|
| BASF SE |
| Syngenta |
| Koppert Biological Systems |
| Biobest Group |
| Valent BioSciences |
| Bayer CropScience |
| Certis |
| Marrone Bio Innovations |
| Andermatt Biocontrol |
| Others |
Supply Flow & Price Mechanics
Fermentation capacity concentration in Germany, Brazil, and the Netherlands directly determines where margin pools accumulate downstream, with axenic culture production expertise anchoring premium capture at the bacterial strain formulation tier while cold-chain logistics costs erode returns for live nematode distributors.
Pricing Analysis
Geographic price spreads of 40-60% separate EU greenhouse markets from Brazilian row crop procurement, with Netherlands specialty growers absorbing per-acre treatment costs exceeding $200 while Mato Grosso cooperatives negotiate multi-year volume contracts below $50 per hectare. Three-tier pricing structure across premium, standard, and economy levels reflects strain purity grades and registration breadth, with EPA FIFRA-compliant formulations commanding 25-35% markups over emerging market equivalents. Cost compression in standard-tier bacterial products is intensifying because Chinese manufacturers are scaling Bacillus thuringiensis fermentation capacity. Farmer cooperatives in Brazil exhibit highest price sensitivity, while California export-oriented specialty crop growers demonstrate least sensitivity due to residue-free certification requirements.
Supply Chain Analysis
Upstream feedstock dependence on molasses-based fermentation media, pharmaceutical-grade nitrogen sources, and proprietary cryoprotectant formulations concentrates input cost volatility at the active ingredient production stage. Manufacturing gravity centers on Germany for precision fermentation equipment, Brazil for soybean belt proximity, and India for cost-competitive contract fermentation services. Single-source vulnerability runs through cold-chain logistics providers for live organism distribution, with 4-10°C continuous storage requirements limiting qualified carrier networks. Distribution runs through biologicals-dedicated channels that bypass traditional agrochemical wholesalers, with direct manufacturer portals capturing 15-20% volume share in Brazilian cooperative procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation across organism classes, application formats, and regulatory jurisdictions creates multiple entry points for specialized players, with EU Green Deal pesticide reduction mandates fragmenting demand into residue-free certification niches that favor biologicals over synthetic chemistry.
For Market Incumbents: Insulate fermentation capacity advantages through backward integration into strain library development and captive supply of cryoprotectant formulations, while securing EPA FIFRA registration dossier capacity as a defensive moat against Chinese manufacturers expanding Bacillus production. Priority levers include patent-protected fermentation protocols and dedicated regulatory affairs infrastructure that extends approval timeline advantages. For New Entrants and Emerging Players: Mid-tier horticultural export zones in Maharashtra and Nashik represent the most penetrable entry point, with EU MRL compliance requirements creating demand for residue-free biocontrol alternatives among grape and pomegranate growers lacking incumbent supplier relationships. RNA interference biopesticide hybrids targeting spider mites in protected cultivation offer a differentiated go-to-market angle that sidesteps established microbial pesticide competition. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across fermentation-scale manufacturing as 100,000-liter vessel deployment and continuous culture automation replace batch processing, favoring acquisition targets with existing axenic culture infrastructure over greenfield capacity builds. Watch for ANVISA-OECD alignment completion in Brazil as an inflection signal indicating streamlined registration pathways that could accelerate market consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Library Acquisition | Patent-protected microbial collections from Ludwigshafen and Wageningen clusters accelerate novel biocontrol pipeline development. |
| Cold Chain Infrastructure Partnership | Qualified 4-10°C logistics networks reduce live nematode degradation losses for California Central Valley distribution. |
| Seed Treatment Co-Formulation | Bayer and Syngenta pipeline investments indicate biological seed coatings will bypass foliar spray timing constraints in row crops. |
| Regulatory Affairs Capacity Buildout | Dedicated EPA FIFRA and ECHA liaison teams compress approval timelines for microbial pesticide and metabolite characterization submissions. |
| Digital Procurement Platform Integration | Real-time fermentation batch tracking through direct manufacturer portals disintermediates traditional agronomic distribution in Brazilian cooperatives. |
Methodological Framework
Operator-level perspectives from fermentation facility managers, integrated pest management advisors at California specialty crop operations, Brazilian cooperative procurement officers, and ECHA regulatory affairs specialists anchored the qualitative base. Secondary validation drew from EPA FIFRA registration databases, EFSA residue assessment protocols, ANVISA alignment documentation with OECD guidelines, and trade flow records for Bacillus thuringiensis active ingredient shipments. Bottom-up strain-level production estimates and top-down agricultural input channel revenue analysis were triangulated to constrain forecast variance.
Scenario-bracketing around EU Green Deal implementation pace, Brazilian cooperative contract renewal cycles, and CRISPR-edited strain development timelines bounded the projection horizon. Segmentation dimensions modeled include organism class, application format, crop system value tier, and regional regulatory cluster complexity. CAGRs were derived from fitted growth curves anchored to volume contract visibility in Mato Grosso and export certification demand trajectories in Maharashtra horticultural zones.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity prices, biofuel policy shifts affecting molasses feedstock costs, or refrigeration energy price spikes would shift the trajectory. Cross-checking against customs records for fermentation equipment imports and cold-chain logistics carrier capacity utilization is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Artificial Insemination Market
Bio-Agriculture
Biopesticides Market
Bio-Agriculture
Biofibre Market
Bio-Agriculture
US Biochar Market
Bio-Agriculture
United States Biostimulants Market
Bio-Agriculture
Biofertilizers Market
Bio-Agriculture
Europe Biological Organic Fertilizer Market
Bio-Agriculture
Rhizobium-Based Biofertilizer Market
Bio-Agriculture
Hydroponics Market
Bio-Agriculture
Bio-Based Succinic Acid Market
Bio-Agriculture
Global Citrus Bioflavonoids Market
Bio-Agriculture
Latin America Biostimulants Market
Bio-Agriculture
Agriculture Biologicals Testing Market
Bio-Agriculture
India Agricultural Biologicals Market
Bio-Agriculture
Africa Biofertilizer Market
Bio-Agriculture
South America Biological Organic Fertilizers Market