
 Agriculture Biologicals Testing Market | 2026-2036
Agriculture Biologicals Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Agriculture Biologicals Testing Market Analysis
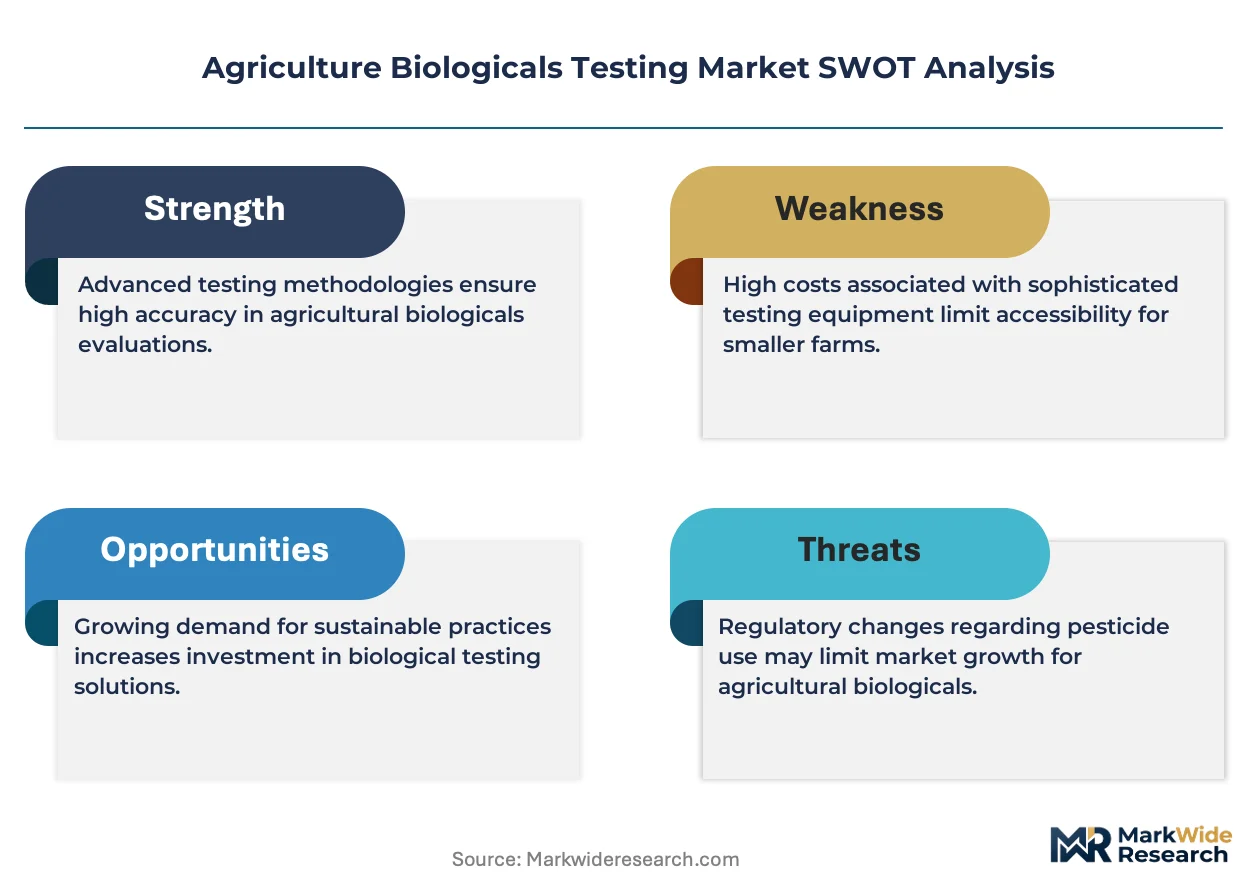
Specialty crop producers are reorganizing procurement priorities around biological input verification, shifting budget share from conventional agrochemical residue testing toward efficacy and safety validation of biopesticides and biostimulants. Eurofins Scientific leverages its global laboratory network to anchor field trial capabilities across multiple growing zones. SGS SA competes through specialized microbial assay protocols that accelerate registration timelines for biofertilizer developers. Bureau Veritas differentiates by integrating soil health benchmarking with product performance claims, giving agronomists dual-use datasets.
Agriculture biologicals testing encompasses analytical and field-based verification of living organisms, botanical extracts, and microbial formulations used to enhance crop productivity or protect against pests, with protocols measuring colony-forming unit counts, metabolite stability, and target-species specificity under variable climatic conditions. Biopesticide testing occupies the largest share of current service revenue, reflecting registration complexity and extended field trial requirements in major jurisdictions. Biostimulant analysis represents the fastest-expanding segment as novel seaweed and protein hydrolysate formulations proliferate and regulators demand standardized efficacy proof. Soil health application testing sits at a more mature phase, with established microbial community profiling methods limiting margin expansion compared to emerging performance testing for yield enhancement claims.
The EPA governs biopesticide registration through FIFRA, while the EU's Plant Protection Products Regulation imposes tiered data requirements on biological active substances, and Brazil's national agricultural regulator mandates localized field efficacy studies for tropical crop systems. These frameworks shape demand by determining which testing packages developers must purchase before market authorization. Stakeholders must monitor divergence between OECD harmonized guidelines and country-specific microbial safety thresholds, as this gap dictates whether single-study submissions suffice or redundant multi-site trials become necessary.
Market Dynamics
The EU's Farm-to-Fork strategy is compressing allowable chemical residue thresholds, forcing specialty crop exporters to revalidate entire input portfolios through biological alternatives before 2030 deadlines.
Growth Catalysts
- EU Plant Protection Products Regulation:Tiered data requirements on biological active substances mandate expanded efficacy dossiers, creating sustained demand for field trial services across member states.
- Biopesticide registration protocols:Brazil's ANVISA mandates localized tropical efficacy studies for soybean and cotton systems, concentrating validation spend in the Cerrado and Mato Grosso regions.
- Seaweed extract formulations:Novel biostimulant chemistries proliferate in specialty vegetable production, requiring metabolite stability profiling that extends laboratory contract durations.
Market Restraints
- Field trial cost structure:Multi-site climatic replication for microbial biopesticides demands 18-24 month validation cycles, compressing developer cash flows before revenue realization.
- Reference strain concentration:Authenticated microbial cultures for assay standardization concentrate in European and North American culture collections, creating import dependency for Asian and Latin American laboratories.
- OECD guideline divergence:Country-specific microbial safety thresholds in major jurisdictions force redundant study submissions, inflating registration budgets without harmonized mutual recognition.
Strategic Opportunities
- Indian biostimulant formalization:FSSAI and state agricultural departments institute mandatory efficacy labeling for protein hydrolysate products, opening standardized testing protocols for domestic and export-bound manufacturers.
- Soil health benchmarking integration:Microbial community profiling services combine with carbon credit verification platforms, creating dual-revenue analytical packages for regenerative agriculture adopters.
- Drone-deployed microbial inoculants:Precision application hardware convergence with live-cell formulation stability testing opens field validation services for aerial distribution systems in broad-acre row crops.
Industry Challenges
- Taxonomic expertise scarcity:Accurate strain-level identification of novel biocontrol organisms requires phylogenetic sequencing capabilities that outpace university training pipeline output.
- Climate chamber capex intensity:Controlled-environment simulation of tropical humidity and ultraviolet exposure patterns demands infrastructure investment that mid-sized laboratories struggle to amortize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agriculture Biologicals Testing Market |
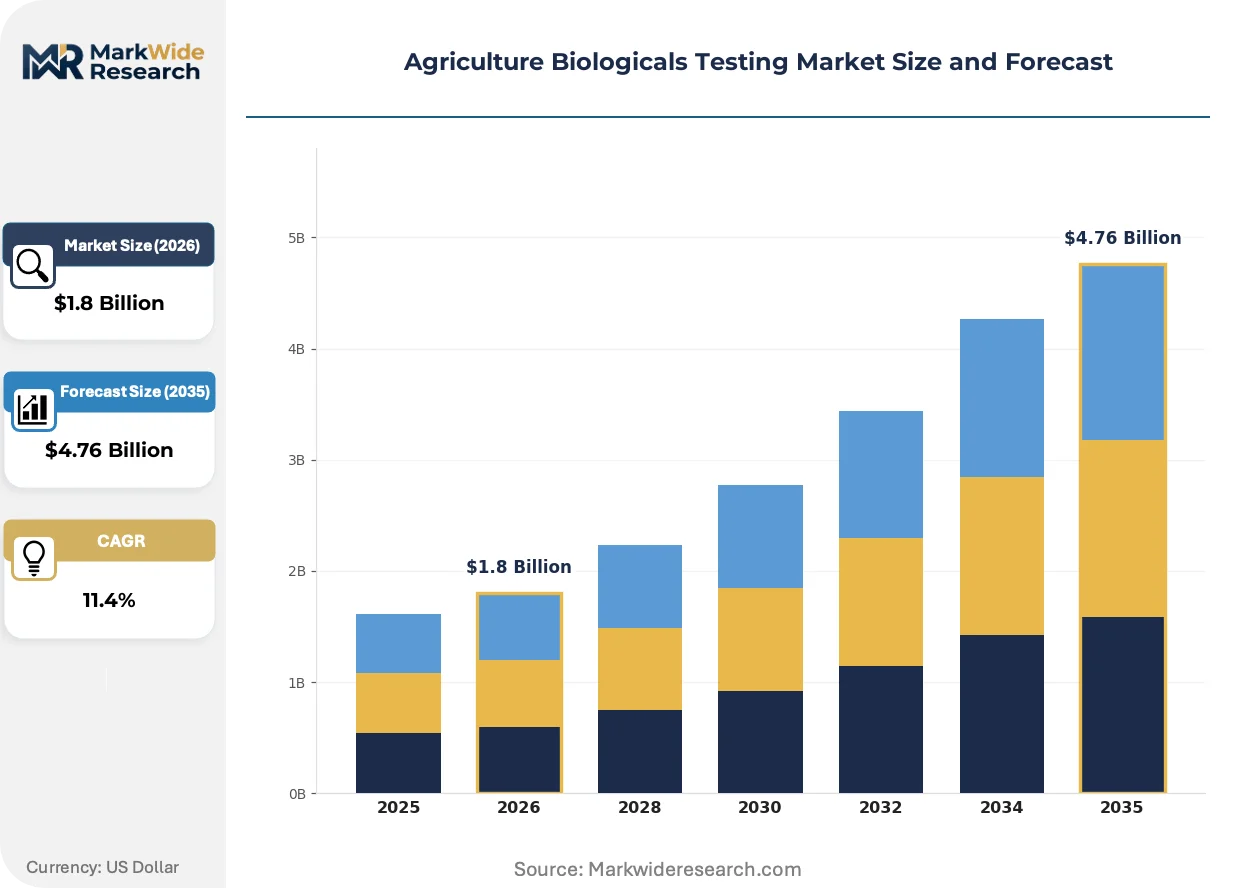
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bioherbicides, Biopesticides, Biofertilizers, Biostimulants Application: Crop Protection, Soil Health, Yield Enhancement, Pest Management End User: Farmers, Agricultural Research Institutions, Crop Producers, Fertilizer Companies Testing Method: Field Trials, Lab Analysis, Microbial Assays, Performance Testing |
| Companies Covered | Eurofins Scientific, SGS SA, Intertek Group plc, Bureau Veritas, ALS Limited, Staphyt, SynTech Research Group, Apal Agricultural Laboratory, RJ Hill Laboratories Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agriculture Biologicals Testing Market Emerging Trajectories
Biological input verification is migrating from static analytical snapshots toward continuous field performance monitoring, reshaping how testing contracts are structured and priced.
CRISPR-based microbial strain tracking is supplanting traditional colony morphology identification in biocontrol product quality assurance. Large-scale biopesticide manufacturers in Brazil and the United States adopt gene-edited marker systems to verify batch consistency across multi-year field trials. This molecular approach compresses contamination detection timelines from weeks to days, enabling faster corrective action during critical crop growth windows.
REACH regulatory evolution in Europe imposes new substance identity requirements on botanical extract impurities, forcing reformulation of established nematicide and fungicide products. Manufacturers must resubmit full toxicological dossiers for co-formulants previously considered inert, redirecting R&D budgets toward analytical characterization. Biostimulant developers with seaweed and plant extract portfolios face the steepest compliance cost escalation.
Certification-driven procurement now dominates specialty crop exporter buying committees, displacing price-first supplier selection. Organic and residue-free program enrollment in avocado, grape, and berry value chains requires documented biological input chains of custody. Chilean and Peruvian agricultural exporters lead this behavioral shift, bundling testing costs into forward supply agreements with European retail consolidators.
Agriculture Biologicals Testing Market Segmentation
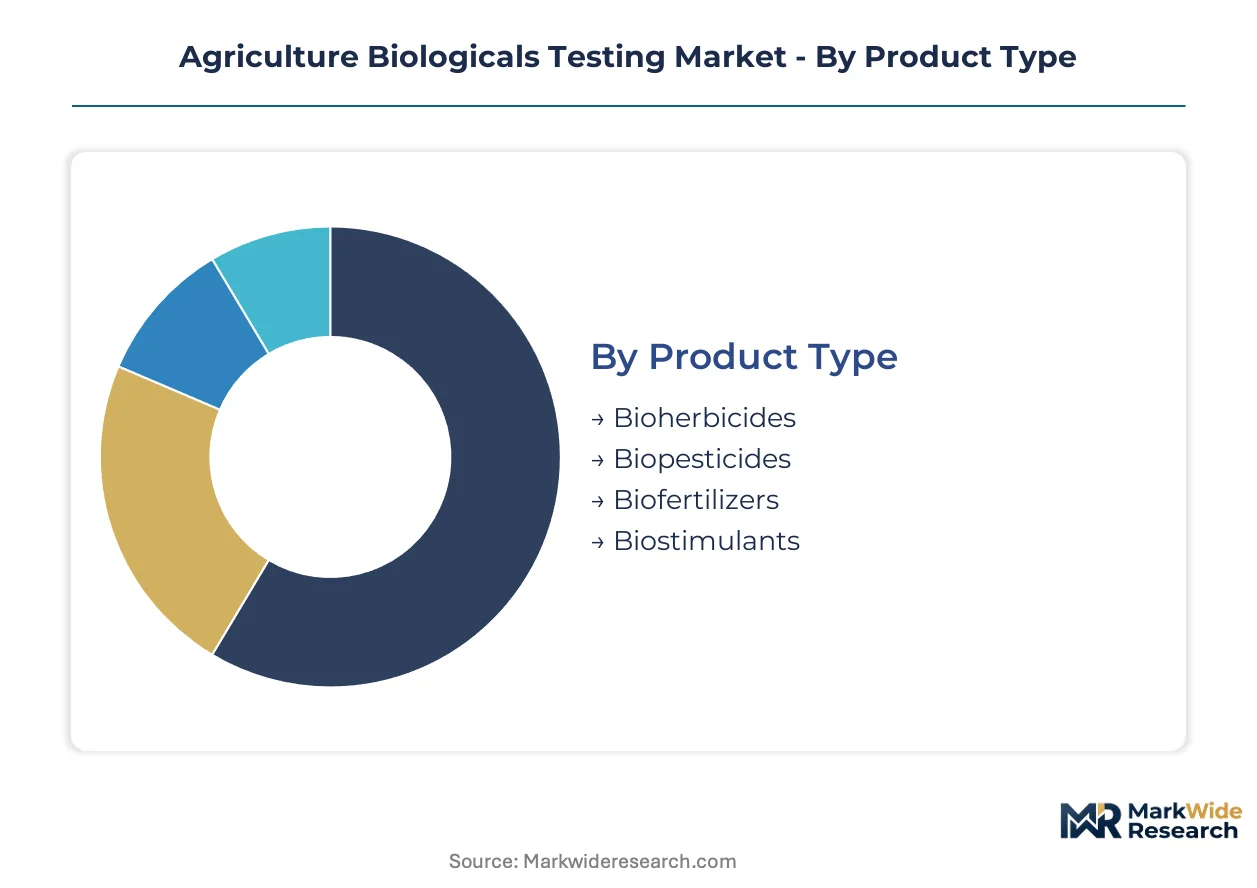
Testing service providers calibrate pricing and capacity deployment around product chemistry complexity and regulatory dossier requirements. Segmentation reveals where laboratory investments generate sustainable returns versus commoditized analytical work.
Product Type:
Margins concentrate in biostimulant and biopesticide validation where metabolite profiling and multi-year field trials extend contract durations.
- Biopesticides:These formulations contain living organisms or botanical derivatives targeting specific pest species, requiring tiered toxicological dossiers under EPA FIFRA and EU Plant Protection Products Regulation. Brazil's ANVISA mandates localized tropical efficacy studies for soybean and cotton systems, concentrating validation spend in the Cerrado region.
- Biostimulants:Seaweed extracts, protein hydrolysates, and microbial inoculants fall under evolving regulatory frameworks that demand standardized efficacy proof for yield enhancement claims. India's FSSAI formalization of mandatory efficacy labeling is opening standardized testing protocols for domestic manufacturers.
- Biofertilizers:Nitrogen-fixing and phosphate-solubilizing microbial formulations require colony-forming unit count verification and carrier material stability assessment.
- Bioherbicides:Botanical and fungal-derived weed control products face narrower commercial adoption due to host-specificity limitations and slower kill speeds.
Biopesticides hold installed capacity. Biostimulants is rotating up the share rankings.
Application:
Service revenue aligns with regulatory pressure intensity, with crop protection commanding premium pricing due to registration complexity.
- Crop Protection:Biopesticide and bioherbicide efficacy validation against target pests and diseases requires multi-site field trials under variable climatic conditions. EU Farm-to-Fork strategy compression of chemical residue thresholds is forcing specialty crop exporters to revalidate entire input portfolios through biological alternatives.
- Soil Health:Microbial community profiling and carbon sequestration verification support regenerative agriculture transitions, though established methods limit margin expansion compared to emerging performance testing.
- Yield Enhancement:Biostimulant performance claims require metabolite stability profiling and controlled-environment growth response trials.
- Pest Management:Integrated pest management program support combines scouting data with biological intervention efficacy tracking.
Crop protection dominates contract values. Soil health is climbing the fastest as carbon credit verification converges with agronomic testing.
End User:
Procurement sophistication varies sharply, with research institutions driving method innovation while fertilizer companies prioritize throughput and cost efficiency.
- Agricultural Research Institutions:Universities and government experiment stations commission novel assay development and reference strain characterization, anchoring technical capability advancement.
- Fertilizer Companies:Incumbents expanding into biological portfolios require high-volume quality control testing for manufacturing consistency.
- Crop Producers:Specialty vegetable and fruit exporters in Chile and Peru are bundling testing costs into forward supply agreements with European retail consolidators.
- Farmers:Direct procurement remains limited to large-scale operations with internal agronomy teams capable of interpreting complex datasets.
Agricultural research institutions anchor method development pipelines. Crop producers are gaining procurement sophistication fastest.
Testing Method:
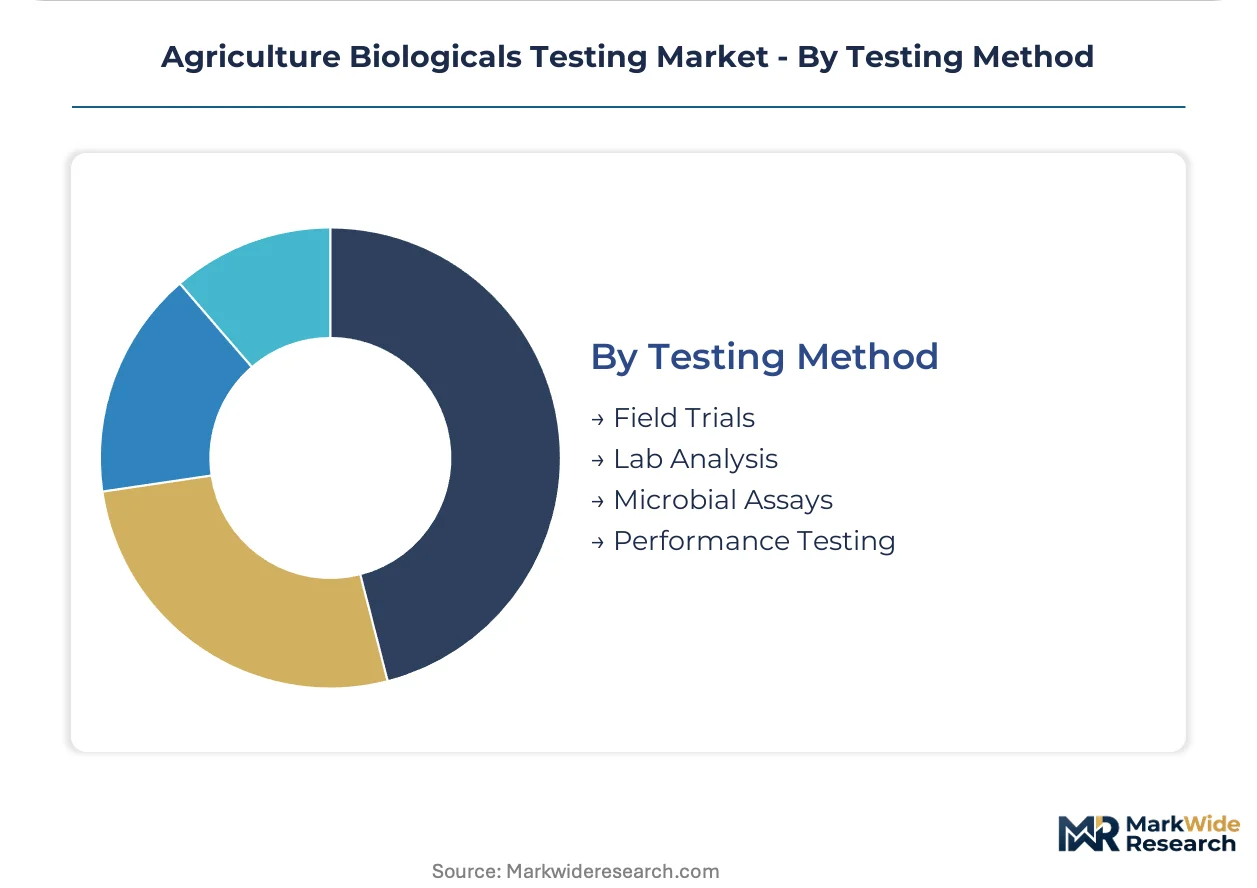
Capital intensity stratifies competitive positioning, with field trial infrastructure creating regional moats that laboratory-only competitors cannot replicate.
- Field Trials:Multi-site climatic replication for microbial biopesticides demands 18-24 month validation cycles across distinct agro-ecological zones. ANVISA requirements for Brazilian tropical crop systems concentrate this capacity in the Cerrado and Mato Grosso regions.
- Lab Analysis:Chromatographic and spectroscopic characterization of botanical extract purity and metabolite concentration supports formulation standardization.
- Microbial Assays:Colony-forming unit enumeration and contamination detection protocols verify batch viability for live-cell products.
- Performance Testing:Controlled-environment growth response trials and stress tolerance assessment validate biostimulant efficacy claims under standardized conditions.
Field trials command premium pricing. Lab analysis is rotating toward automation and higher throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian soybean exporters to the European Union drive demand for residue-free certification protocols, while Indian biostimulant manufacturers seek compliance pathways for protein hydrolysate shipments to Middle Eastern markets.
United States
EPA biopesticide registrations under FIFRA concentrate validation demand in California's Central Valley and Iowa's corn belt. The agency's tiered data requirements for microbial active substances sustain multi-year field trial contracts across diverse agro-ecological zones. St. Louis anchors commercial seed treatment testing capacity, where major agricultural input companies validate live-cell inoculant stability.
Brazil
ANVISA mandates localized tropical efficacy studies for soybean and cotton biopesticides, funneling contract spend toward Cerrado and Mato Grosso field stations. The national agricultural regulator's microbial safety thresholds diverge from OECD guidelines, forcing redundant study submissions for export-bound products. Campinas clusters specialized microbial assay laboratories serving domestic formulation developers.
Germany
EU Plant Protection Products Regulation tiered dossier requirements sustain premium pricing for efficacy validation services across member states. ECHA's evolving substance identity rules for botanical extract impurities redirect manufacturer R&D budgets toward analytical characterization. Cologne anchors Eurofins Scientific's European field trial coordination hub for multi-site climatic replication studies.
India
FSSAI mandatory efficacy labeling for protein hydrolysate biostimulants opens standardized testing protocols for domestic and export manufacturers. State agricultural departments in Maharashtra and Gujarat formalize microbial biofertilizer quality control mandates. Hyderabad clusters contract research organizations developing tropical field trial methodologies for South Asian crop systems.
Australia
APVMA registration requirements for biological crop protection products sustain demand for efficacy validation across wheat belt and horticultural regions. The national regulator's data protection provisions incentivize local field trial generation rather than reliance on foreign studies. Melbourne anchors ALS Limited's Asia-Pacific analytical services hub for botanical extract metabolite profiling.
Agriculture Biologicals Testing Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and geographic coverage dimensions. The vendor base stratifies between global laboratory networks with field trial infrastructure and regional specialists with microbial assay expertise. Three archetypes dominate: integrated testing conglomerates with multi-continent presence, crop protection-focused contract research organizations, and agricultural commodity inspection houses diversifying into biological inputs. Competitive moves concentrate on M&A to acquire tropical field trial capabilities and strategic partnerships with drone application hardware providers.
Within the integrated testing tier, Eurofins Scientific and SGS SA exemplify capital-heavy positioning through extensive laboratory networks and field station footprints. Bureau Veritas occupies a position bridging agricultural inspection heritage with biological input verification demand. Staphyt and SynTech Research Group represent the specialized contract research archetype, anchoring crop protection-focused validation services without diversified industrial testing portfolios. These company patterns illustrate how competitive positioning separates scale-driven conglomerates from technical specialists in a market where regulatory complexity rewards geographic and capability breadth.
| Leading Market Players |
|---|
| Eurofins Scientific |
| SGS SA |
| Intertek Group plc |
| Bureau Veritas |
| ALS Limited |
| Staphyt |
| SynTech Research Group |
| Apal Agricultural Laboratory |
| RJ Hill Laboratories Limited |
| Others |
Supply Flow & Price Mechanics
Eighteen-to-twenty-four-month field trial cycles for microbial biopesticides concentrate pricing power with laboratories possessing tropical climate chamber infrastructure, while Asian and Latin American competitors face import dependency on authenticated reference strains from European and North American culture collections. This lead-time asymmetry stratifies contract values across geographies and reinforces tiered service positioning.
Pricing Analysis
Current-generation CRISPR-based microbial strain tracking commands premium contract rates against prior-generation colony morphology identification, while next-generation drone-deployed inoculant validation services remain nascent. Three-tier pricing structure across premium, standard, and economy levels separates multi-site field trial packages from single-location laboratory assays and basic microbial enumeration services. Cost compression in standard-tier chromatographic profiling is intensifying because automation investments raise throughput without proportional analyst headcount expansion. Fertilizer companies expanding into biological portfolios exhibit highest price sensitivity due to volume procurement requirements, while specialty crop exporters in Chile and Peru demonstrate lowest sensitivity when bundling testing costs into forward supply agreements with European retail consolidators.
Supply Chain Analysis
Germany and the United States anchor high-value analytical instrumentation manufacturing and reference strain authentication services, while Brazil and India concentrate tropical field trial execution and domestic microbial assay capacity. Testing service supply chains draw from precision chromatography equipment, climate simulation chambers, and authenticated microbial culture collections as critical inputs. Single-source vulnerability concentrates in European and North American culture collections, creating import bottlenecks for laboratories in Asia and Latin America seeking assay standardization materials. Distribution runs through direct contractual relationships between testing conglomerates and agricultural input manufacturers, with regional specialists serving domestic formulation developers through shorter sales cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Agriculture biologicals testing demand cycles recover through regulatory deadline compression, as EU Farm-to-Fork strategy chemical residue thresholds and Indian FSSAI mandatory efficacy labeling timelines force revalidation spend across exporter portfolios.
For Market Incumbents: Consolidate tropical field trial infrastructure through targeted capacity additions in Brazil's Cerrado and Mato Grosso regions, where ANVISA mandates concentrate soybean and cotton biopesticide validation demand. Acquire specialized microbial assay capabilities in Campinas and Hyderabad to preempt domestic competitor scale-up. Certification investment in OECD guideline harmonization advocacy reduces redundant study submission costs for multinational clients. For New Entrants and Emerging Players: Differentiate on drone-deployed microbial inoculant field validation services, where precision application hardware convergence with live-cell formulation stability testing remains underdeveloped. Target Indian protein hydrolysate biostimulant manufacturers facing FSSAI mandatory efficacy labeling requirements as the most penetrable client segment. Pursue partnership-based go-to-market positioning with aerial application equipment providers rather than capital-intensive independent infrastructure buildout. For Investors and Strategic Acquirers: Carve-out targets emerge from agricultural commodity inspection houses diversifying into biological inputs, where biological verification capabilities lag traditional chemical residue testing expertise. Long-term viability over a five-to-ten-year window hinges on regulatory divergence between OECD harmonized guidelines and country-specific microbial safety thresholds persisting rather than converging. Watch for ECHA substance identity rule evolution on botanical extract impurities as the signal indicating reformulation-driven analytical characterization demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Tropical Field Trial Capacity Expansion | ANVISA mandates for Brazilian soybean systems concentrate validation spend in Cerrado and Mato Grosso regions. |
| CRISPR-Based Strain Tracking Adoption | Gene-edited marker systems compress contamination detection timelines from weeks to days for biopesticide manufacturers. |
| Soil Health Benchmarking Integration | Microbial community profiling convergence with carbon credit verification creates dual-revenue analytical packages. |
| Drone Application Hardware Partnership | Precision aerial distribution systems demand live-cell formulation stability testing for broad-acre row crops. |
| Indian Biostimulant Protocol Development | FSSAI mandatory efficacy labeling opens standardized testing pathways for protein hydrolysate manufacturers. |
Methodological Framework
Cross-validation between regulatory filing analysis and field trial contract documentation anchors the qualitative findings in this study. Primary interviews with biopesticide registration managers, agricultural research institution procurement officers, biostimulant formulation developers, and regulatory affairs specialists at testing conglomerates combined with secondary validation against EPA FIFRA registration databases, EU Plant Protection Products Regulation submission records, ANVISA tropical efficacy study requirements, and OECD harmonized guideline documentation. Bottom-up service provider capacity modeling and top-down agricultural input manufacturer R&D spend allocation triangulate market sizing across the projection horizon.
Sensitivity analysis on regulatory timeline assumptions shapes the analytical framework approach throughout the forecast period. Segmentation dimensions modeled include product type chemistry complexity, application regulatory pressure intensity, end user procurement sophistication, and testing method capital intensity. CAGRs derive from regression analysis against historical validation contract durations and projected registration pipeline volumes. Industry-specific forecast inputs incorporate ANVISA tropical study mandate expansion rates and EU Farm-to-Fork strategy implementation pacing.
Material uncertainties — regulatory guideline harmonization progress, reference strain import policy shifts, climate chamber infrastructure investment cycles — sit outside the modeled envelope. Forecasts reflect assumptions about sustained divergence between OECD standards and country-specific microbial safety thresholds. Recalibration cycles align with material shifts in ECHA substance identity rule evolution and FSSAI labeling mandate enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Asia-Pacific Agricultural Biologicals Market
Bio-Agriculture
Middle East and Africa Biopesticides Market
Bio-Agriculture
Bio-Insecticide Market
Bio-Agriculture
Europe Bioethanol Market
Bio-Agriculture
Canada Biofertilizers Market
Bio-Agriculture
South America Biological Organic Fertilizers Market
Bio-Agriculture
Europe Biological Organic Fertilizer Market
Bio-Agriculture
Africa Biological Organic Fertilizers Market
Bio-Agriculture
Agricultural Biologicals Market
Bio-Agriculture
Biocontrol Agents Market
Bio-Agriculture
Bio-Based Succinic Acid Market
Bio-Agriculture
Rhizobium-Based Biofertilizer Market
Bio-Agriculture
China Biofertilizer Market
Bio-Agriculture
Bio Rational Fungicides Market
Bio-Agriculture
Hydroponics Nutrients Market
Bio-Agriculture
Brazil Biofertilizers Market